
 Fruit Brandy Market | 2026-2036
Fruit Brandy Market Size, Share, and Industry Trends Forecast 2026-2036
Fruit Brandy Market Foresight
Buyer concentration among craft cocktail bars and boutique hospitality groups is realigning procurement patterns toward small-batch, provenance-verified fruit brandies. Beam Suntory Inc. leverages its Japanese distribution infrastructure to sustain premium positioning in Asian markets. Diageo anchors volume through controlled-atmosphere aging programs that standardize flavor profiles across batches. E. & J. Gallo Winery competes via backward integration into California stone fruit orchards, securing varietal consistency for its brandy programs.
Fruit brandy denotes a distilled spirit produced exclusively from fermented fruit mash, with alcohol content typically ranging from 40% to 60% ABV and no added flavoring beyond the source fruit's natural esters. Copper pot stills remain the dominant production apparatus for premium expressions, preserving volatile aromatic compounds that column distillation strips away. Apple brandy and pear brandy occupy the largest volume positions, reflecting established orcharding infrastructure in Normandy and the Pacific Northwest. Cherry brandy represents the fastest-expanding category, driven by mixology adoption and its structural use in classic cocktail formulations where color intensity and almond-like pit aromatics add complexity.
The U.S. Alcohol and Tobacco Tax and Trade Bureau enforces standard of identity rules that restrict "brandy" labeling to grape-based spirits, forcing fruit distillers into alternative classification categories that complicate consumer education. The EU's EFSA and national regulators such as France's ANSM coordinate geographic indication enforcement that protects Calvados and Poire Williams appellations from dilution by non-compliant imports. Stakeholders must monitor evolving TTB labeling petitions and EU Spirits Regulation amendments that could either harmonize fruit spirit classifications or deepen transatlantic regulatory divergence.
Market Dynamics
The EU's revised Spirits Regulation tightens geographic indication enforcement, forcing non-authentic producers to reclassify or exit while authentic distilleries in protected appellations capture pricing power and shelf space.
Growth Catalysts
- Premium mixology adoption:Independent bars and hotel chains in Germany's Baden-Württemberg region anchor demand for small-batch Obstbrand expressions. Copper pot stills preserve volatile aromatics that column distillation strips away.
- EFSA coordination on geographic indications:France's ANSM enforces Calvados and Poire Williams protections, preventing dilution by non-compliant imports and tightening supply authenticity.
- Cherry brandy formulation demand:Classic cocktail programs leverage almond-like pit aromatics and color intensity, expanding structural use in bartending applications.
Market Restraints
- Input cost volatility:Stone fruit orchard yields in California and Normandy fluctuate with climate stress, compressing margin predictability for distillers without backward integration into orcharding.
- Regulatory friction:The US TTB restricts "brandy" labeling to grape-based spirits, forcing fruit distillers into alternative classifications that complicate consumer education and retail placement.
- Supply concentration risk:Copper pot still fabrication concentrates among specialized European metalworkers, creating equipment procurement bottlenecks for new market entrants.
Strategic Opportunities
- Asian distribution infrastructure:Japanese and South Korean hospitality markets show underpenetrated demand for provenance-verified European fruit brandies, with controlled-atmosphere aging programs enabling consistent export quality.
- Regulatory harmonization petitions:Active TTB labeling petitions could reclassify fruit spirits under unified standards, reducing compliance fragmentation for cross-border producers.
- Direct-to-consumer channels:Boutique distillery tasting rooms and subscription models bypass traditional three-tier distribution, capturing margin and building brand equity.
Industry Challenges
- Master distiller talent scarcity:Copper pot still operation requires multi-year apprenticeship pipelines that German and Austrian craft programs struggle to populate.
- Batch-to-batch consistency:Natural fruit ester variation demands rigorous chromatographic monitoring, extending quality control timelines and raising laboratory capex requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fruit Brandy Market |
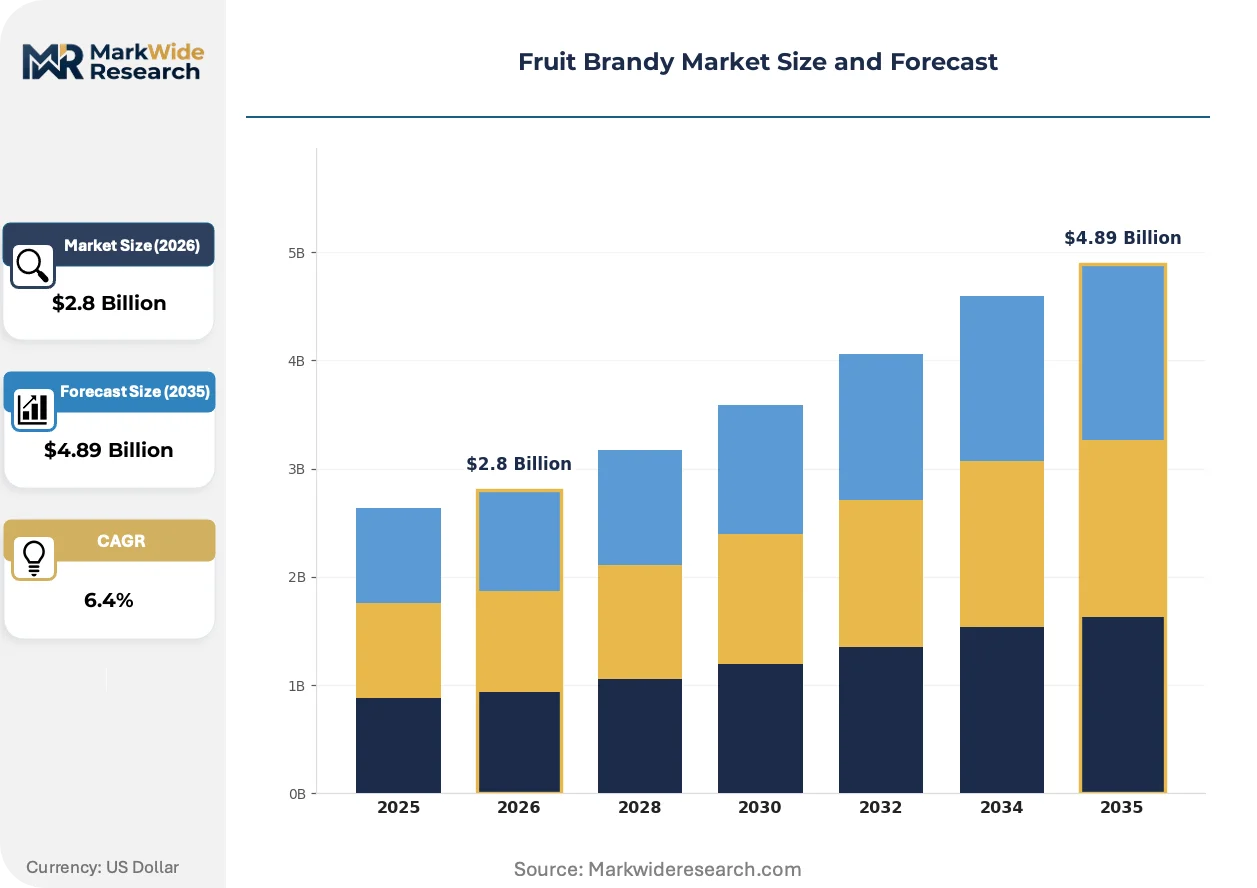
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Apple Brandy, Pear Brandy, Cherry Brandy, Apricot Brandy, Plum Brandy, Peach Brandy Application: Mixology, Culinary Use, Medicinal Tinctures, Gift Packaging, Celebratory Events, Personal Consumption Packaging Type: Glass Bottles, Tins, Wooden Boxes, Miniature Bottles, Bulk Containers, Decorative Flasks End User: Hospitality, Specialty Retailers, Private Collectors, Bartenders, Event Organizers, Connoisseurs |
| Companies Covered | F.E. TRIMBACH, Distilleries et Domaines de Provence, Great Lakes Distillery, Lucas Bols, Beam Suntory Inc., Diageo, E. & J. Gallo Winery, Alliance Global Group Inc., F. Korbel & Bros., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fruit Brandy Market Shifts & Advancements
Controlled-atmosphere aging and chromatographic quality monitoring are compressing batch variation while regulatory enforcement and channel fragmentation reshape competitive positioning.
Chromatographic ester profiling is expanding into standard quality assurance protocols. Premium distilleries in France and Germany adopt gas chromatography-mass spectrometry to map volatile compound signatures across fermentation batches. This technology is expanding into mid-tier producers seeking appellation compliance without sensory panel dependency, compressing the quality assurance cost curve.
REACH chemical safety protocols and EU Spirits Regulation amendments tighten additive disclosure and oak sourcing documentation. French regulators now require chain-of-custody certification for barrel staves used in Calvados aging. Small producers in Normandy respond by consolidating cooperage relationships and digitizing inventory tracking to satisfy audit requirements.
Boutique hospitality procurement teams now specify provenance documentation and single-orchard sourcing in RFPs, displacing commodity fruit spirit purchasing. Independent cocktail bars in Berlin and Copenhagen negotiate directly with Baden-Württemberg distilleries, shortening supply chains and capturing exclusive cask allocations. This concentration is most visible in Scandinavian markets where alcohol retail monopolies privilege certified geographic indication products in their purchasing algorithms.
Fruit Brandy Market Segmentation
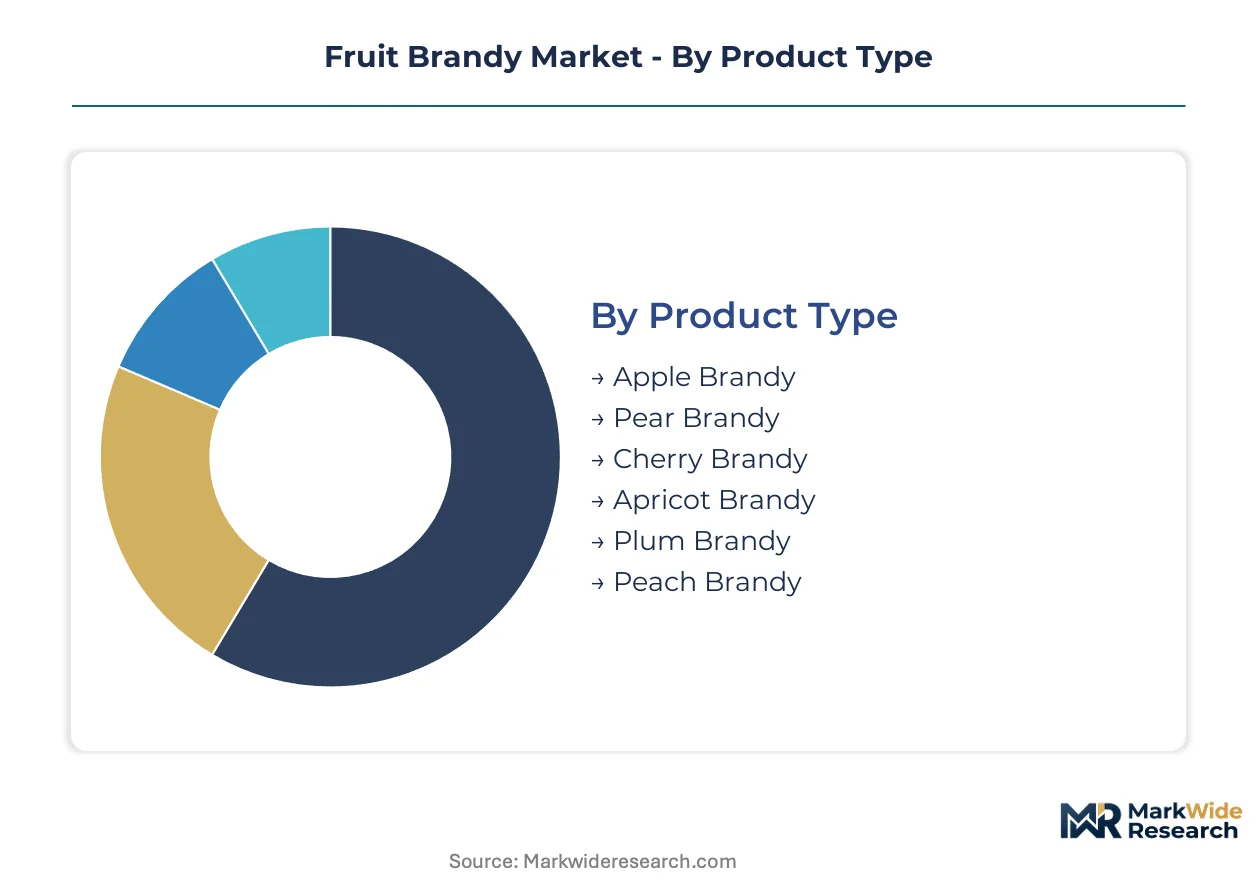
Fruit brandy segmentation reveals how procurement patterns diverge across use cases and buyer sophistication. Distillers calibrate production specifications, aging protocols, and packaging investments to match distinct channel requirements and price tolerance thresholds.
Product Type:
Replacement cycles vary by fruit base, with orchard-dependent categories showing longer inventory turnover than those sourcing from diversified supply regions.
- Apple Brandy:Distilled from fermented cider apple mash, typically aged in oak with 40-50% ABV. Normandy's Calvados distilleries and Oregon's Willamette Valley producers anchor volume, constrained by multi-year orchard maturation timelines and EFSA geographic indication enforcement.
- Cherry Brandy:Fermented from sour or sweet cherry mash, often incorporating pit maceration for almond-like aromatics. Bartenders in Berlin and Copenhagen drive structural demand for cocktail applications where color intensity and aromatic complexity command premium positioning.
- Pear Brandy:Clear spirit from Williams or Bartlett pear fermentation, requiring precise fermentation temperature control. Poire Williams appellation protection limits supply authenticity to designated French and Swiss zones.
- Apricot Brandy:Stone fruit distillate with pronounced floral ester profile. Austrian Burgenland and Hungarian Kecskemét orchards supply dominant volume positions.
- Plum Brandy:Slivovitz-style expressions dominate Eastern European supply, with Serbian and Croatian distilleries maintaining traditional pot still methods.
- Peach Brandy:Delicate aromatic profile demands rapid post-distillation handling. California Central Valley and South Carolina peach belt concentrate limited commercial production.
Volume placements concentrate in Apple Brandy; the faster expansion belongs to Cherry Brandy.
Application:
Cost tier differentiation separates commodity bulk purchasers from premium channel buyers willing to absorb provenance verification premiums.
- Mixology:Craft cocktail programs specify single-orchard sourcing and chromatographic quality documentation. Independent bars in Germany's Baden-Württemberg region negotiate direct allocations, bypassing traditional wholesale tiers.
- Culinary Use:Flambé applications and sauce reductions demand consistent alcohol content and neutral flavor profiles. Restaurant procurement teams prioritize volume pricing over provenance certification.
- Medicinal Tinctures:Traditional European apothecary formulations require specific ester profiles. ANSM and EFSA additive disclosure rules constrain production flexibility.
- Gift Packaging:Premium presentation drives cooperage-grade wooden box and decorative flask demand. Seasonal purchasing concentrates in Q4 calendar periods.
- Celebratory Events:Wedding and corporate gifting segments favor miniature bottle formats with customized labeling.
- Personal Consumption:Connoisseur collectors drive aged expression demand, with cellar-worthy vintages appreciating in secondary markets.
Mixology commands the highest per-liter margins; Medicinal Tinctures face the steepest regulatory compliance cost escalation.
Packaging Type:
Customer type stratification shapes format selection, with hospitality buyers prioritizing operational efficiency and collectors emphasizing display aesthetics.
- Glass Bottles:Standard 750ml and 375ml formats dominate retail and on-premise distribution. REACH chemical safety protocols and EU Spirits Regulation amendments tighten additive disclosure for closure materials.
- Wooden Boxes:Premium gift and collector segments require chain-of-custody certification for oak sourcing. French regulators mandate documentation for barrel staves used in Calvados aging.
- Miniature Bottles:Airline and hotel minibar procurement favors 50ml formats with tamper-evident seals.
- Tins:Lightweight shipping and corrosion resistance suit export markets with extended distribution timelines.
- Bulk Containers:Food service and culinary manufacturing buyers purchase 5-20 liter stainless steel totes for high-volume applications.
- Decorative Flasks:Limited edition releases incorporate etched glass and precious metal accents for ultra-premium positioning.
Glass Bottles absorb the largest unit volume; Wooden Boxes capture the steepest expansion trajectory in absolute dollar terms.
End User:
Supply concentration among specialized metalworkers for copper pot still fabrication creates equipment procurement bottlenecks that constrain new entrant expansion across all buyer categories.
- Hospitality:Hotel chains and independent bars specify provenance documentation in RFPs. Scandinavian alcohol retail monopolies privilege certified geographic indication products in purchasing algorithms.
- Specialty Retailers:Boutique spirits shops curate regional portfolios, negotiating exclusive cask allocations directly with Baden-Württemberg and Normandy distilleries.
- Private Collectors:Cellar investment demand concentrates on vintage-dated expressions with documented orchard sourcing and controlled-atmosphere aging protocols.
- Bartenders:Individual practitioner purchasing through direct-to-consumer channels bypasses three-tier distribution, capturing margin and building brand equity.
- Event Organizers:Corporate and wedding planners favor customizable miniature formats with private labeling capabilities.
- Connoisseurs:Sensory-focused buyers prioritize single-varietal expressions with gas chromatography-mass spectrometry quality verification.
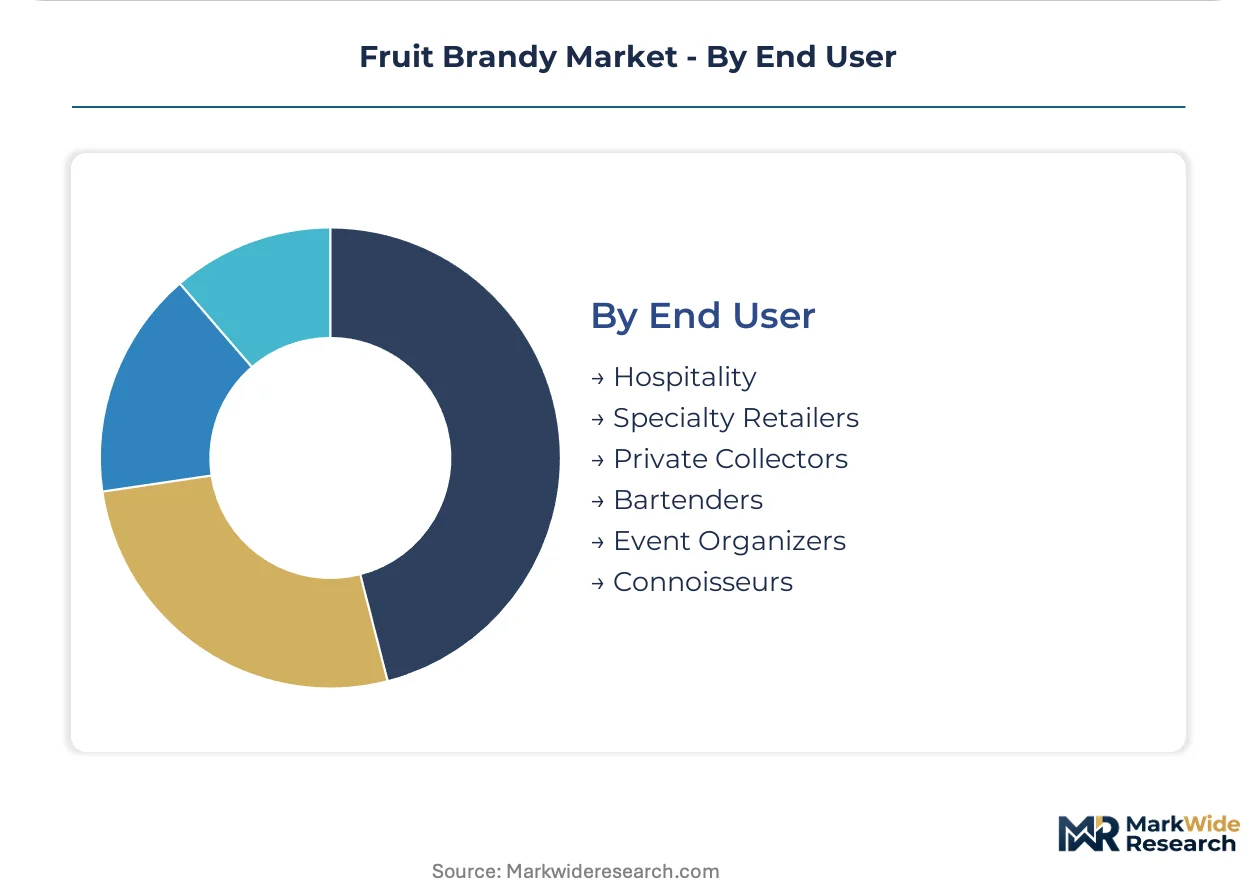
Hospitality maintains the broadest volume base; Private Collectors generate the fastest margin expansion through allocation scarcity premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Orchard belts in Normandy, Baden-Württemberg, and the Pacific Northwest anchor raw material supply for premium fruit brandy production. Climate stress on stone fruit yields concentrates distilling activity in established growing regions with irrigation infrastructure and multi-decade tree maturity. Regulatory enforcement of geographic indications shapes competitive access across consuming markets.
Germany
Baden-Württemberg and Bavaria distilleries anchor European Obstbrand supply, with copper pot still fabrication concentrated among specialized Swabian metalworkers. The country's Federal Ministry of Food and Agriculture enforces EU Spirits Regulation compliance for geographic indication products. Stuttgart-area craft programs struggle to populate master distiller apprenticeship pipelines.
France
Normandy's Calvados distilleries and Alsace's Poire Williams producers command premium positioning through appellation protection. ANSM and EFSA coordinate geographic indication enforcement that prevents dilution by non-compliant imports. Rouen and Caen industrial clusters concentrate aging warehouse infrastructure along the Seine valley.
United States
Oregon's Willamette Valley and California Central Valley stone fruit orchards supply apple and peach brandy feedstock. The TTB restricts "brandy" labeling to grape-based spirits, forcing fruit distillers into alternative classification categories. Portland-area craft distilleries negotiate directly with independent bars for cask allocations.
Austria
Burgenland apricot orchards supply dominant European volume for Marillenbrand production. The country's national food safety authority enforces additive disclosure rules aligned with EFSA protocols. Vienna-area hospitality procurement teams specify single-orchard sourcing in supplier RFPs.
Japan
Tokyo and Osaka hospitality markets show underpenetrated demand for provenance-verified European fruit brandies. METI import regulations govern spirits distribution through licensed wholesale channels. Beam Suntory leverages domestic infrastructure to sustain premium positioning for imported expressions.
Fruit Brandy Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue direct-to-consumer channels and geographic indication certification. The market structure fragments across orchard-integrated distilleries, contract distillers, and import-focused distributors. Three archetypes dominate: heritage appellation houses with controlled-atmosphere aging programs, craft distilleries with single-orchard sourcing, and diversified spirits conglomerates with Asian distribution infrastructure. Competitive moves concentrate on backward integration into orcharding and regulatory harmonization petitions.
Among diversified spirits conglomerates, Beam Suntory Inc. and Diageo occupy positions defined by distribution scale and aging technology investment. E. & J. Gallo Winery represents the orchard-integrated archetype through its California stone fruit supply control. Heritage specialists such as F.E. TRIMBACH exemplify appellation-protected positioning in Alsace. These groupings illustrate how competitive advantage accrues to players with captive feedstock supply or regulatory navigation capabilities rather than manufacturing scale alone.
| Leading Market Players |
|---|
| F.E. TRIMBACH |
| Distilleries et Domaines de Provence |
| Great Lakes Distillery |
| Lucas Bols |
| Beam Suntory Inc. |
| Diageo |
| E. & J. Gallo Winery |
| Alliance Global Group Inc. |
| F. Korbel & Bros. |
| Others |
Supply & Pricing Matrix
California stone fruit futures and Normandy cider apple spot markets cascade through three-tier pricing structures across premium, standard, and economy levels, with copper pot still scarcity and EFSA geographic indication enforcement compressing margin predictability for non-integrated distillers while orchard-anchored producers capture appellation premiums.
Pricing Analysis
After-sales service bundling separates premium expressions with chromatographic quality documentation from unbundled commodity tiers lacking provenance verification. Certification grade under EU Spirits Regulation and volume scale drive price differentiation, with small-batch Calvados and Poire Williams commanding substantial premiums over non-appellation alternatives. Cost compression in standard tiers intensifies because climate stress on orchard yields raises input volatility. Culinary manufacturing buyers exhibit highest price sensitivity, while private collectors and boutique hospitality groups absorb premium positioning with minimal elasticity.
Supply Chain Analysis
Regional distribution centers along the Seine valley and Stuttgart industrial corridor coordinate hub-and-spoke patterns for aged inventory release. Supply concentrates in France, Germany, and the United States, with raw material dependencies on cider apple orchards, Williams pear cultivation, and copper pot still fabrication from specialized Swabian metalworkers. Single-source vulnerability in master distiller talent pipelines constrains capacity expansion. Distribution runs through three-tier wholesale channels in regulated markets and direct-to-consumer tasting rooms in deregulated zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a vertical-integration race where backward integration into orcharding and controlled-atmosphere aging infrastructure determines who captures appellation premiums versus who faces margin compression from input volatility.
For Market Incumbents: Deepen captive supply of stone fruit orchards in California and Normandy to insulate against climate-driven yield fluctuations. Expand controlled-atmosphere aging warehouse capacity along established river valley corridors. Consolidate cooperage relationships to satisfy REACH chain-of-custody documentation requirements. Regulatory harmonization petitions present offensive leverage against competitors dependent on fragmented compliance structures.
For New Entrants and Emerging Players: Direct-to-consumer subscription channels and boutique tasting room models bypass three-tier distribution capture in saturated wholesale markets. Target underpenetrated Japanese and South Korean hospitality procurement teams seeking provenance-verified European expressions. Negotiate exclusive cask allocations with Baden-Württemberg distilleries lacking Asian export infrastructure. Chromatographic quality verification investments differentiate against commodity importers.
For Investors and Strategic Acquirers: Distressed-cycle entries favor orchard-integrated mid-cap specialists in Austrian Burgenland and Hungarian Kecskemét regions facing succession gaps in family-owned operations. Long-term viability hinges on geographic indication certification moats and direct hospitality channel relationships rather than manufacturing scale. Monitor TTB labeling petition outcomes as inflection indicators for regulatory arbitrage opportunities.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Orcharding | Captive stone fruit supply secures varietal consistency against climate volatility in Normandy and California. |
| Geographic Indication Certification | EFSA-protected Calvados and Poire Williams appellations prevent dilution by non-compliant imports. |
| Direct-to-Consumer Channel Launch | Boutique tasting rooms bypass three-tier distribution margin capture in Scandinavian monopoly markets. |
| Controlled-Atmosphere Aging Investment | Standardized flavor profiles enable consistent export quality to underpenetrated Japanese hospitality. |
| Chromatographic Quality Verification | Gas chromatography-mass spectrometry protocols satisfy ANSM additive disclosure without sensory panel dependency. |
Research Methodology
Trade association filings, customs export records, and EFSA regulatory databases formed the secondary backbone, cross-referenced against primary interviews with master distillers, hospitality procurement managers, and copper still fabrication specialists. Bottom-up and top-down triangulation validated volume estimates across orchard-integrated distilleries, contract producers, and import-focused distributors.
Bottom-up modeling tracked fruit base categories, application channels, and packaging formats across the projection horizon. CAGRs derived from weighted average of historical volume trajectories and forward-looking capacity announcements. Forecast inputs incorporated climate stress indices for stone fruit yields and master distiller apprenticeship pipeline data from German craft programs.
The model holds under stable EU Spirits Regulation enforcement and TTB classification continuity; deviation in geographic indication recognition or labeling harmonization would shift competitive access patterns. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Global Craft Vodka Market
Alcoholic Beverages
Global Liquor Bottles Market
Alcoholic Beverages
Middle East and Africa Kegs Market
Alcoholic Beverages
Nitro Cocktails Market
Alcoholic Beverages
US Wine Market
Alcoholic Beverages
Middle East and Africa Beer Market
Alcoholic Beverages
Global Malt Market
Alcoholic Beverages
Cigar and Cigarillos Market
Alcoholic Beverages
France Alcohol E-Commerce Market
Alcoholic Beverages
E-Commerce Liquor Market
Alcoholic Beverages
Craft Rum Market
Alcoholic Beverages
Europe Tequila Market
Alcoholic Beverages
Gluten-Free Beer Market
Alcoholic Beverages
Home Brew Boiler Market
Alcoholic Beverages
Cannabis Beverages Market
Alcoholic Beverages
Canada Alcohol E-Commerce Market