
 Craft Spirits Market | 2026-2036
Craft Spirits Market Size, Share, and Industry Trends Forecast 2026-2036
Craft Spirits Market Analysis
Buyer concentration among premium hospitality groups is hardening as independent bars consolidate into multi-unit operators with centralized procurement. Bacardi Limited leverages its Caribbean rum heritage to compete in craft-influenced aged spirits. Brown-Forman Corporation anchors its position through sustained investment in small-batch whiskey infrastructure. William Grant & Sons differentiates via family-owned distilling credibility that resonates with authenticity-seeking accounts.
Craft spirits denote alcoholic beverages produced in limited quantities by independently owned distilleries, typically employing traditional methods, local or heritage grains, and pot still distillation with batch sizes under defined regulatory thresholds. These products serve commercial and consumer markets seeking differentiated flavor profiles, provenance narratives, and production transparency absent from mass-market alternatives. Whiskey commands the deepest margin pools as barrel aging creates scarcity value and collector tiers. Gin experiences rapid portfolio expansion as botanical experimentation attracts metropolitan bartenders and home enthusiasts. Vodka competes on purity signaling and regional water sourcing rather than age-based prestige.
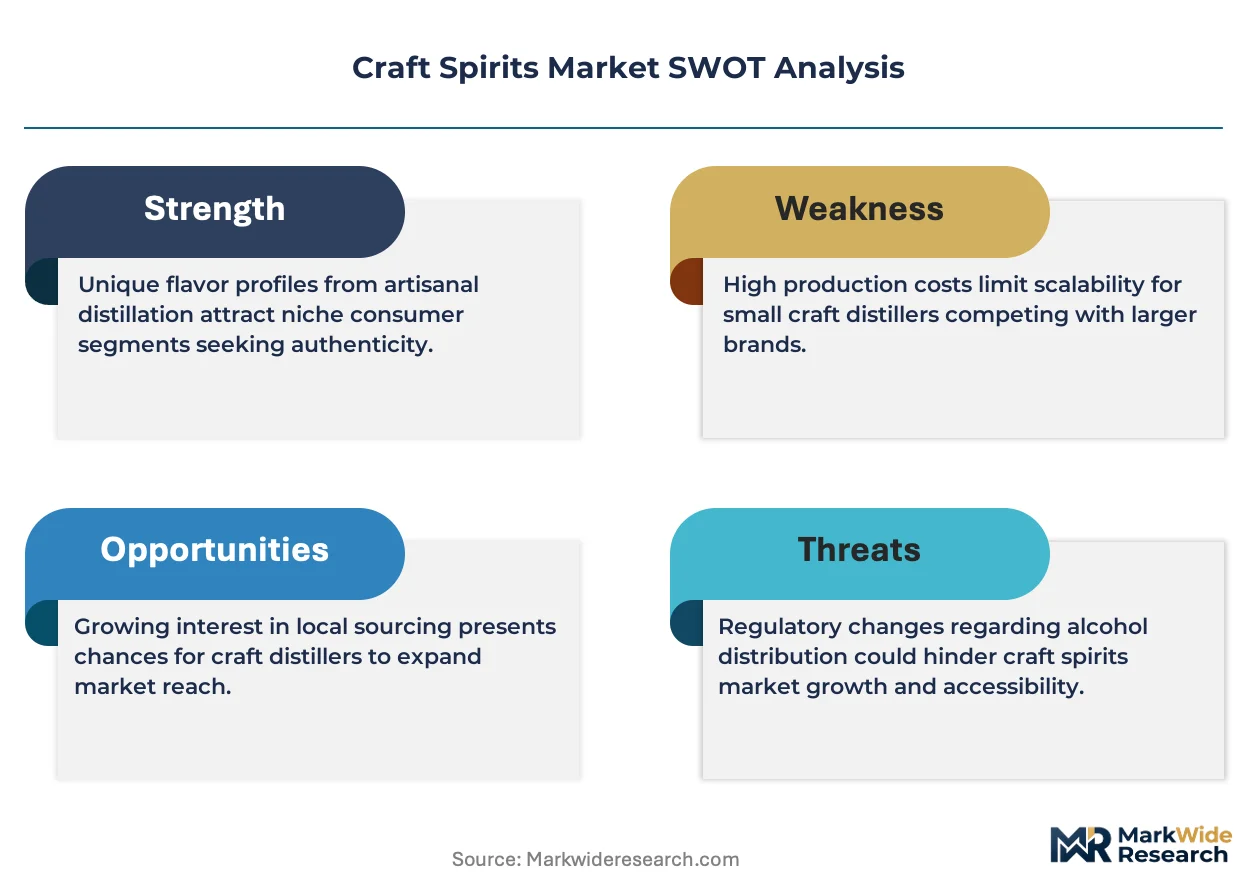
The Alcohol and Tobacco Tax and Trade Bureau governs label approval, formula disclosure, and bonded warehouse rules for United States producers, while the EU Spirits Regulation mandates geographic indications, minimum aging requirements, and additive restrictions across member states. The Food Standards Agency in the United Kingdom enforces allergen labeling and alcohol content verification that shapes export compliance costs. Stakeholders must monitor evolving excise tax structures and locality-based production thresholds that determine craft eligibility and pricing flexibility across jurisdictions.
Market Dynamics
Premium hospitality consolidation is compressing procurement timelines and demanding proof of provenance documentation that smaller distilleries struggle to assemble at scale.
Growth Catalysts
- EU Spirits Regulation geographic indications:Protected status for regional production methods enables pricing premiums for authenticated heritage processes in member states.
- Metropolitan bartender networks:Influential mixologists in London, New York, and Sydney function as de facto gatekeepers, accelerating adoption of experimental botanical formulations through cocktail menu placement.
- Pot still micro-distillation:Batch-scale equipment manufacturers have reduced capital barriers, permitting garage-scale entry with output volumes under TTB small producer thresholds.
Market Restraints
- Oak barrel supply concentration:American white oak cooperage capacity concentrates in Missouri and Kentucky, creating eighteen-month order backlogs for new entrants.
- TTB formula disclosure requirements:Proprietary botanical blends must submit ingredient lists for federal approval, exposing trade secrets to competitor surveillance through public databases.
- Excise tax burden:Federal and state alcohol taxes in the United States absorb thirty to fifty percent of wholesale price at distillery gate, compressing margin for volume-limited producers.
Strategic Opportunities
- Australian craft gin underpenetration:Sydney and Melbourne metropolitan markets show concentration gaps for native botanical expressions using Tasmanian pepperberry and lemon myrtle.
- Direct-to-consumer subscription channels:Tasting club models bypass three-tier distribution constraints in permissive jurisdictions, capturing full retail margin.
- IRA clean energy manufacturing credits:Distillery equipment retrofits for biomass or solar thermal heating qualify for federal tax offsets, reducing operational carbon intensity for sustainability-marketed brands.
Industry Challenges
- Master distiller talent scarcity:Formal fermentation science programs produce fewer graduates than distillery openings require, forcing poaching from established Scottish and Irish operations.
- Warehouse bond compliance complexity:TTB bonded premises regulations mandate physical security and record-keeping systems that demand specialized legal counsel for first-time applicants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Craft Spirits Market |
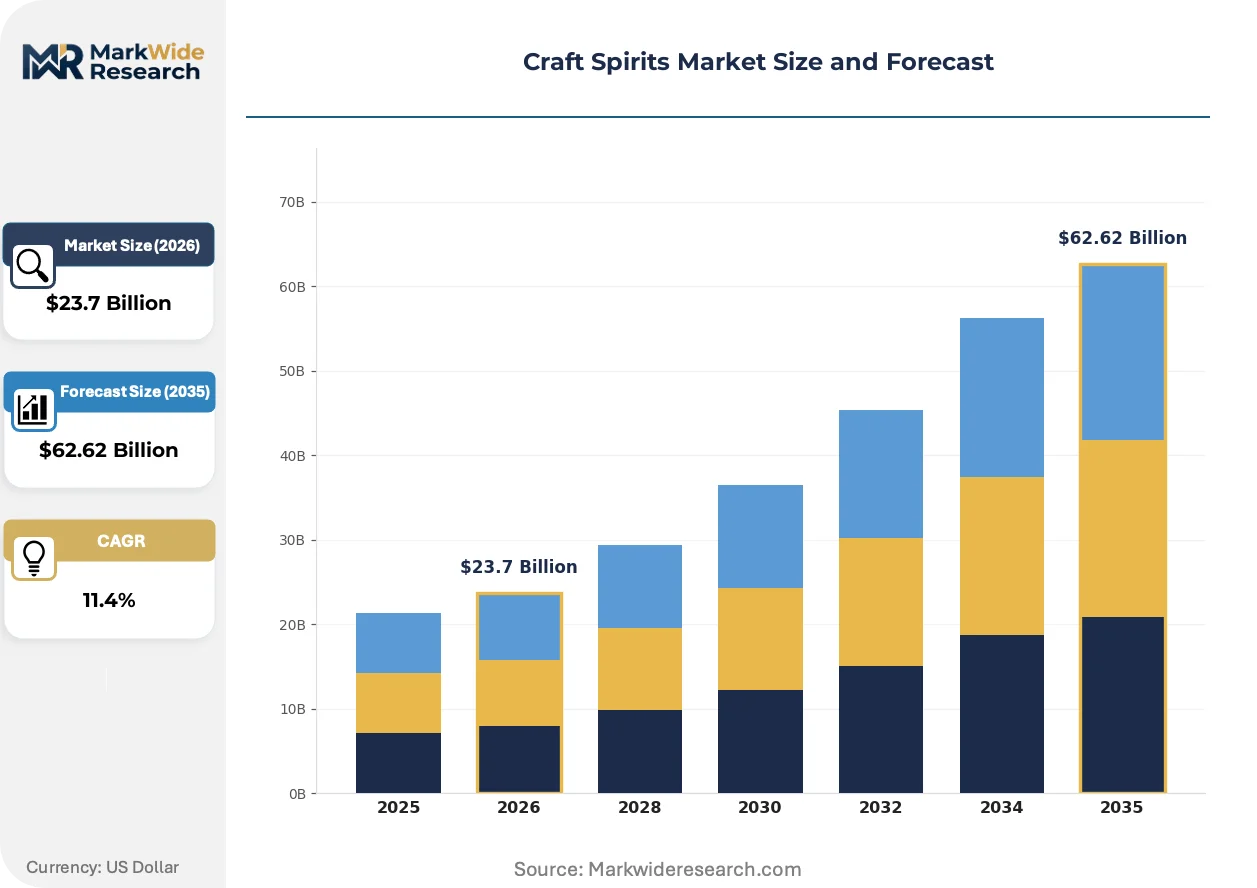
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $62.62 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whiskey, Gin, Vodka, Rum Packaging Type: Bottles, Cans, Kegs, Tetra Packs Service Type: Tastings, Tours, Events, Online Sales End User: Bars, Restaurants, Retailers, Home Consumers |
| Companies Covered | Bacardi Limited, Brown-Forman Corporation, William Grant & Sons, Sazerac Company, Beam Suntory, Diageo Plc, Rémy Cointreau, Heaven Hill Brands, Pernod Ricard, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Craft Spirits Market Emerging Trajectories
Production transparency tools and accelerated maturation technologies are compressing the traditional time-to-market advantage held by legacy aged spirit inventories.
Non-destructive spectroscopic analysis is decentralizing quality verification. Handheld devices now permit real-time ethanol congeners measurement without laboratory submission. Small-batch distillers in Colorado and Tasmania deploy these units for batch release decisions. The technology is decentralizing quality assurance from centralized labs to production floors, shortening release cycles from weeks to hours.
EU Spirits Regulation additive disclosure mandates tighten ingredient transparency. The framework requires allergen labeling and prohibits certain flavoring substances in products claiming traditional production status. Botanical-forward gin producers in the Netherlands and Spain reformulate recipes to maintain geographic indication eligibility, shifting competitive advantage toward clean-label formulations.
Buyer concentration among multi-unit hospitality groups alters contract structures. Premium cocktail bar chains now demand exclusive bottling runs and co-branded expressions in exchange for menu placement. Independent distillers in Kentucky and Islay negotiate multi-year supply agreements with London-based bar groups, trading margin for volume certainty and brand visibility in influential accounts.
Craft Spirits Market Segmentation
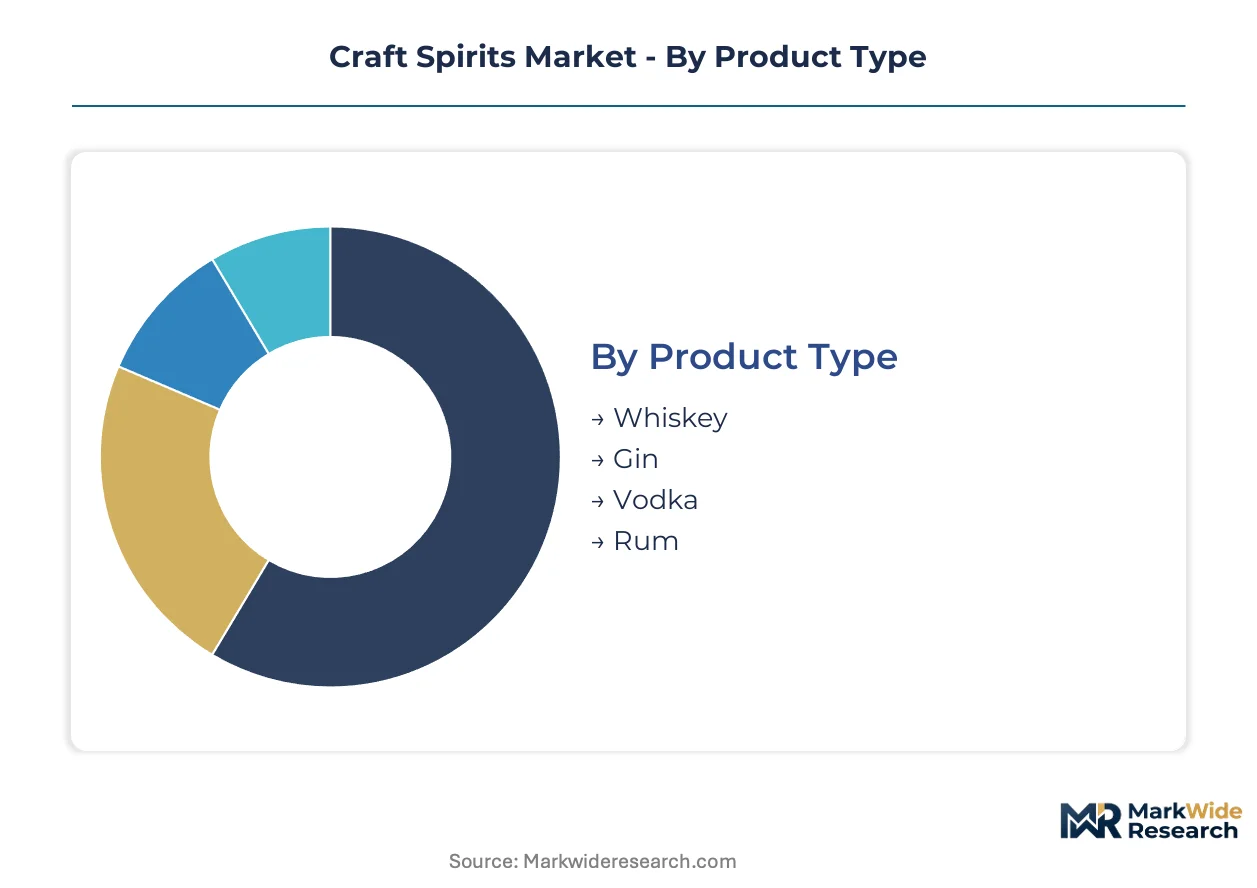
Craft spirits producers navigate a fragmented demand landscape where customization requirements differ sharply across buyer types. Distillers must align production scale and distribution formats to distinct channel economics and consumption occasions.
Product Type:
Customization intensity varies from barrel-driven scarcity plays to formula-flexible clear spirits that accommodate rapid portfolio rotation.
- Whiskey:Barrel-aged grain spirits matured in charred oak casks develop congener complexity over multi-year cycles. Demand concentrates in United States metropolitan markets and Scottish export channels where collector tiers and allocated releases command sustained premiums. Aging infrastructure requirements create steep barriers that favor established distilleries with bonded warehouse capacity.
- Gin:Neutral grain spirit redistilled with juniper and botanicals permits rapid recipe iteration without maturation delays. London, New York, and Sydney bartender networks drive formulation trends through menu placement decisions. Botanical experimentation cycles measure in weeks rather than years, enabling seasonal and limited expressions.
- Vodka:Multiple-distilled neutral spirit competes on purity signaling and regional water provenance narratives.
- Rum:Cane or molasses-based distillate spans unaged agricole expressions to extended tropical maturation programs.
Leading the category by volume: Whiskey. Growing fastest: Gin.
Packaging Type:
Format selection tracks channel access rules and consumption occasion portability requirements across on-premise and off-premise segments.
- Bottles:Glass containers in 750ml standard and 375ml specialty formats dominate retail shelf presence and back-bar display. United States three-tier distribution mandates and EU Spirits Regulation labeling standards shape bottle specification compliance costs. Premium positioning relies on weight, closure quality, and label substrate differentiation.
- Cans:Aluminum single-serve formats enable outdoor and transit consumption where glass restrictions apply. Australian and United Kingdom ready-to-drink cocktail segments show concentration for canned craft spirits. Portability advantages compete against perceived quality trade-offs in aged spirit categories.
- Kegs:Stainless steel returnable vessels serve high-volume on-premise accounts with draft cocktail programs.
- Tetra Packs:Aseptic carton formats reduce shipping weight for bulk export and airline duty-free channels.
Dominant by value: Bottles. Expanding most quickly: Cans.
Service Type:
Revenue model diversification separates production-focused distilleries from experience-driven hospitality operators with integrated visitor economics.
- Tastings:Structured sampling sessions convert visitor traffic to direct purchase and club membership enrollment. Kentucky Bourbon Trail and Scottish distillery routes demonstrate concentration where tourism infrastructure supports repeat visitation. Regulatory tasting room licensing varies by United States state and EU member jurisdiction.
- Tours:Production facility access builds brand narrative authenticity and justifies premium pricing in retail channels. Australian Tasmanian whisky trail and Islay malt circuit show geographic concentration for destination tourism models. Tour capacity limits constrain revenue scaling for smaller operations.
- Events:Pop-up activations and festival sponsorships extend reach beyond fixed facility catchment areas.
- Online Sales:Direct-to-consumer shipping bypasses wholesale markups where interstate and international regulations permit.
Highest margin contribution: Tastings. Steepest expansion trajectory: Online Sales.
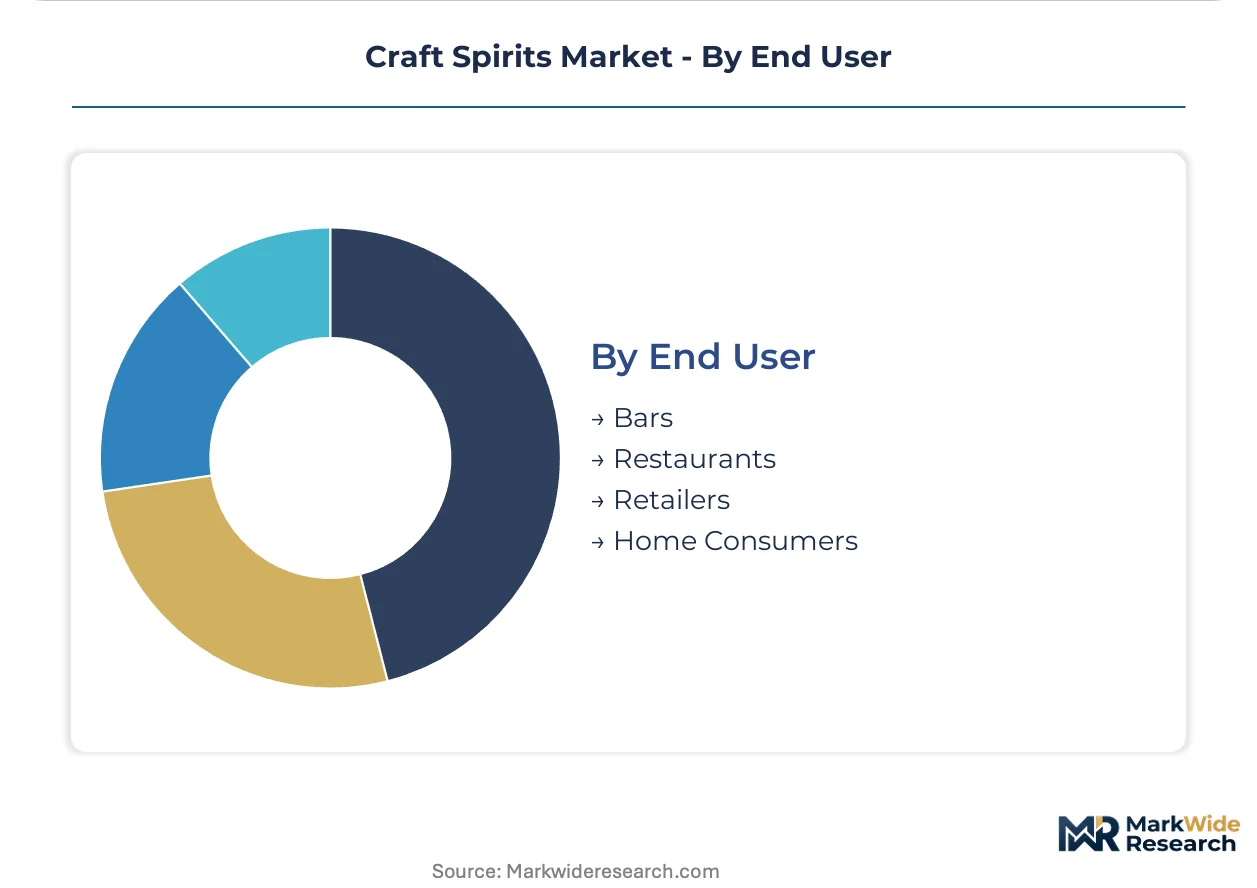
End User:
Procurement concentration and technical specification requirements diverge sharply between institutional buyers and individual consumers.
- Bars:On-premise accounts demand proof of provenance documentation, consistent supply security, and co-branding flexibility for menu placement. London, New York, and Sydney cocktail bar groups exercise gatekeeper influence through centralized purchasing and exclusive bottling negotiations. Well-program accounts function as brand building platforms with outsized visibility.
- Restaurants:Food-pairing compatibility and by-the-glass program economics shape spirit selection criteria. Sommelier and beverage director networks in Paris, San Francisco, and Melbourne concentrate demand for terroir-linked expressions. List placement duration affects inventory planning and vintage or batch continuity requirements.
- Retailers:Shelf space allocation and promotional calendar coordination determine distribution access.
- Home Consumers:Direct purchase and subscription club models capture full retail margin where permitted.
Concentrating fastest: Bars. Volume foundation: Home Consumers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
American white oak forests in Missouri and Kentucky anchor the barrel supply chains that constrain maturation capacity for aged spirits worldwide. Regional demand clusters concentrate in metropolitan cocktail bar networks across three continents. Regulatory fragmentation across the United States, European Union, and Australia shapes compliance architectures for export-oriented distilleries.
United States
Metropolitan bartender networks in New York, Chicago, and Los Angeles drive formulation trends through centralized procurement decisions. The Alcohol and Tobacco Tax and Trade Bureau enforces bonded warehouse regulations and formula disclosure requirements that shape production economics. Kentucky's Bourbon Trail and Tennessee's whiskey corridor concentrate visitor-driven direct-to-consumer revenue models.
United Kingdom
London cocktail bar groups exercise gatekeeper influence through exclusive bottling negotiations and co-branded expressions. The Food Standards Agency mandates allergen labeling and alcohol content verification that adds export compliance layers for incoming producers. Scottish Islay and Speyside clusters maintain heritage credibility through geographic indication protections under EU Spirits Regulation continuity frameworks.
Australia
Sydney and Melbourne metropolitan markets show concentration gaps for native botanical gin expressions using Tasmanian pepperberry and lemon myrtle. The Australian Taxation Office administers excise tax structures that determine craft eligibility thresholds for small-scale distillers. Tasmania's whisky trail and Victoria's gin corridor anchor tourism-integrated production models with integrated tasting room licensing.
Germany
Bavarian and Baden-Württemberg craft distilleries leverage fruit brandy heritage to compete in premium schnapps and gin segments. EU Spirits Regulation geographic indication frameworks enable pricing premiums for authenticated regional production methods. Berlin's mixology lounge concentration drives adoption of experimental botanical formulations through menu placement decisions.
Japan
Tokyo and Osaka hospitality networks concentrate demand for terroir-linked whiskey and gin expressions with provenance documentation. The Ministry of Economy, Trade and Industry oversees standards alignment for export-oriented producers targeting European and North American markets. Hokkaido's grain supply and Kyushu's shochu heritage anchor raw material and technical credibility for craft spirit diversification.
Craft Spirits Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue authenticity-signaling and small-batch credibility plays. The market structures around heritage conglomerates with bonded warehouse capacity, mid-scale regional specialists with tasting room integration, and garage-scale entrants with direct-to-consumer subscription models. Two dominant competitive moves define current positioning: portfolio diversification into craft-influenced aged expressions, and backward integration into cooperage and grain supply to secure barrel allocation and provenance documentation.
Within the heritage conglomerate tier, Bacardi Limited, Brown-Forman Corporation, and William Grant & Sons occupy positions that exemplify contrasting strategic anchors. Bacardi represents Caribbean rum heritage leveraged into craft-influenced aged spirits credibility. Brown-Forman exemplifies sustained infrastructure investment in small-batch whiskey capacity. William Grant & Sons anchors family-owned distilling authenticity that resonates with provenance-seeking hospitality accounts. These three entities collectively illustrate how scale incumbents deploy heritage assets against craft entrant positioning.
| Leading Market Players |
|---|
| Bacardi Limited |
| Brown-Forman Corporation |
| William Grant & Sons |
| Sazerac Company |
| Beam Suntory |
| Diageo Plc |
| Rémy Cointreau |
| Heaven Hill Brands |
| Pernod Ricard |
| Others |
Supply Flow & Price Mechanics
EU Spirits Regulation geographic indication compliance gates both qualified barrel supply and premium-tier pricing access for craft distillers seeking authenticated heritage status in member states. Producers lacking protected designation documentation face exclusion from hospitality procurement networks that demand provenance verification, compressing margin capture to standard-tier clear spirits categories.
Pricing Analysis
Volume versus margin splits sharply across product categories, with barrel-aged whiskey commanding sustained premiums through scarcity signaling while gin operates on rapid portfolio rotation economics. Three-tier pricing structure across premium allocated releases, standard distribution tiers, and economy private-label segments tracks aging infrastructure ownership and botanical formulation complexity. Pricing pressure stems from American white oak cooperage backlogs extending eighteen months, forcing new entrants toward unaged expressions or premium pricing that tests buyer elasticity. Multi-unit hospitality groups exercise least price sensitivity through exclusive bottling negotiations, while independent retailers and home consumers demonstrate highest elasticity to tariff-passed cost increases.
Supply Chain Analysis
TTB formula disclosure requirements and bonded warehouse certification gate entry for producers seeking federal label approval and tax-advantaged maturation storage. American white oak forests in Missouri and Kentucky, Scottish cooperage operations in Speyside, and French Limousin oak sources anchor global barrel supply for aged spirit categories. Raw material dependencies center on heritage grain varieties, juniper berry sourcing from Mediterranean suppliers, and proprietary yeast cultures maintained through generational propagation. Single-source vulnerability concentrates in Missouri-based cooperage capacity where weather-related harvest disruption or kiln fire events could constrain global maturation throughput. Distribution runs through three-tier wholesale networks in the United States, bonded warehouse release systems in the United Kingdom, and direct-to-consumer tasting room channels where state licensing permits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Craft spirits consolidation accelerates as excise tax burdens and bonded warehouse compliance costs force sub-scale distilleries toward distressed sale or operational closure. Market incumbents with bonded capacity and heritage documentation capture share through selective acquisition of distressed botanical formulation IP.
For Market Incumbents: Extend bonded warehouse capacity in Kentucky and Tennessee to secure barrel allocation priority during cooperage supply crunches. Acquire distressed Australian and Scottish craft distilleries with established geographic indication credentials to backfill portfolio gaps in authenticated heritage expressions. Master distiller talent poaching from Islay and Speyside operations remains the priority lever against formulation quality erosion.
For New Entrants and Emerging Players: Metropolitan bartender networks in Sydney and Melbourne present the most penetrable channel for native botanical gin expressions using Tasmanian pepperberry and lemon myrtle. Direct-to-consumer subscription models bypass three-tier distribution constraints in permissive United States states, capturing full retail margin through tasting club enrollment. Co-branded exclusive bottling negotiations with London cocktail bar groups deliver brand visibility without wholesale margin compression.
For Investors and Strategic Acquirers: IRA clean energy manufacturing credit utilization rates are the leading indicator that operational carbon intensity reduction is shifting from marketing narrative to cost structure advantage. Five-to-ten year viability favors distilleries with integrated tasting room tourism economics and captive grain supply contracts that insulate against input cost volatility. Acquisition target archetype: mid-scale regional specialists with bonded warehouse capacity and underutilized botanical formulation R&D pipelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cooperage | Captive American white oak supply secures barrel allocation priority during eighteen-month order backlogs. |
| Geographic Indication Certification | EU Spirits Regulation protected status enables pricing premiums in authenticated heritage process categories. |
| Direct-to-Consumer Channel Launch | Tasting club models bypass three-tier distribution constraints in permissive United States jurisdictions. |
| Native Botanical Portfolio Expansion | Tasmanian pepperberry and lemon myrtle formulations address underpenetration in Sydney metropolitan markets. |
| Clean Energy Equipment Retrofit | IRA biomass and solar thermal credits reduce operational carbon intensity for sustainability-marketed brands. |
Methodological Framework
Document review covered TTB formula disclosure databases, EU Spirits Regulation geographic indication registries, and bonded warehouse licensing records, complemented by interviews with master distillers, hospitality procurement directors, and cooperage operations managers. Secondary validation drew from distillery excise tax filings, three-tier distribution shipment data, and tourism board visitor statistics across Kentucky, Scotland, and Tasmania. Bottom-up triangulation aggregated individual distillery capacity and output estimates against top-down category volume assessments from trade association disclosures.
Cross-referencing historical production trends against panel input from distillery expansion planners and equipment manufacturers shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, packaging format, service revenue model, and end-user channel, with additional granularity on metropolitan market concentration patterns. CAGRs were derived through trend extrapolation adjusted for regulatory threshold changes and excise tax policy scenarios. Forecast inputs incorporated barrel aging cycle durations, botanical harvest seasonality, and tasting room licensing approval timelines.
Caveats apply where TTB formula disclosure requirement modifications, EU Spirits Regulation additive restriction expansions, or state-level direct-to-consumer shipping permission changes could materially shift the outlook. Forecasts reflect assumptions regarding cooperage capacity expansion rates and master distiller labor market elasticity. A model refresh is warranted upon material change in federal excise tax structures or bonded warehouse security mandate revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Beer Keg System Market
Alcoholic Beverages
Oak Barrel Alternatives Market
Alcoholic Beverages
Wine Filtering Machine Market
Alcoholic Beverages
Organic Beer Market
Alcoholic Beverages
Liquor Flavored Ice Cream Market
Alcoholic Beverages
Port Wine Market
Alcoholic Beverages
US Frozen Cocktail Popsicles Market
Alcoholic Beverages
Wine Bags Market
Alcoholic Beverages
Alcohol Enzymes Market
Alcoholic Beverages
Moonshine Market
Alcoholic Beverages
Coffee Beer Market
Alcoholic Beverages
Beer Cans Market
Alcoholic Beverages
Malaysia Alcohol E-Commerce Market
Alcoholic Beverages
Alcopop Market
Alcoholic Beverages
Wine Chocolate Market
Alcoholic Beverages
Stout Market