
 Industrial Alcohol Market | 2026-2036
Industrial Alcohol Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Alcohol Market Intelligence
Expertise in advanced fermentation and bioprocess engineering is rotating from traditional commodity production towards high-purity and specialty alcohol grades. Cargill leverages its vast agricultural supply chain to maintain scale in commodity ethanol production. In contrast, MGP Ingredients Inc. specializes in premium distilled spirits and specialty wheat proteins, differentiating on quality. Raízen Energia anchors Brazil's bioethanol sector through its massive sugarcane processing capacity.
Industrial alcohol encompasses grades of ethanol, methanol, and isopropanol not intended for human consumption, typically produced via fermentation of biomass or synthetic chemical processes. These products, often with a purity exceeding 95%, serve primarily as chemical intermediates, solvents, or fuel components. Ethyl alcohol derived from corn or sugarcane remains the dominant product type by volume, largely due to its use as a fuel additive. The solvent application segment is mature, but demand for isopropyl alcohol as an antiseptic shows consistent strength in pharmaceutical and personal care markets.
Market access and product specifications are governed by a complex web of regulations, including the US EPA's Renewable Fuel Standard and the EU's REACH framework for chemical safety. In India, the Bureau of Indian Standards (BIS) sets quality parameters for various industrial alcohol grades, impacting both domestic production and imports. Stakeholders must navigate feedstock price volatility and the strategic choice between investing in bio-based fermentation capacity versus synthetic production pathways.
Market Dynamics
The push for decarbonization and circular economy principles is the central force shaping the market. This pressure compels a structural shift from fossil-based synthetic production towards renewable, bio-based fermentation pathways, influencing everything from feedstock sourcing to capital investment.
Growth Catalysts
- Biofuel Mandates:Policies like Brazil's national program create vast, stable demand for fuel-grade ethanol, anchoring global production.
- Pharmaceutical Applications:Demand for high-purity ethanol as a solvent and antiseptic provides a consistent, high-margin revenue stream for producers.
- Process Technology:Advances in fermentation improve yields from feedstocks like corn, boosting the cost-competitiveness of bio-based alcohol.
Market Restraints
- Feedstock Volatility:Production costs are tied to agricultural commodity prices like corn, exposing producers to significant margin pressure from price swings.
- Capital Intensity:Building new biorefineries requires substantial upfront investment, creating high barriers to entry and slowing capacity expansion.
- Substitution Risk:In solvent applications, alcohols face competition from other chemicals, with choices influenced by price and regulations like the EU's REACH.
Strategic Opportunities
- Sustainable Aviation Fuel:The alcohol-to-jet pathway presents a major new demand vector, converting ethanol into a component for decarbonizing aviation.
- Bio-based Chemicals:Ethanol serves as a platform chemical for producing materials like bio-ethylene, offering a renewable alternative to petroleum-based feedstocks.
- Blending Mandate Expansion:Many countries in Asia and Africa have underutilized biofuel blending potential, representing untapped markets for fuel-grade ethanol.
Industry Challenges
- Regulatory Divergence:Producers navigate a patchwork of national regulations for denaturing and purity, such as those from India's BIS, increasing compliance costs.
- Water Management:The water-intensive nature of fermentation and distillation presents operational challenges in water-stressed agricultural regions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Alcohol Market |
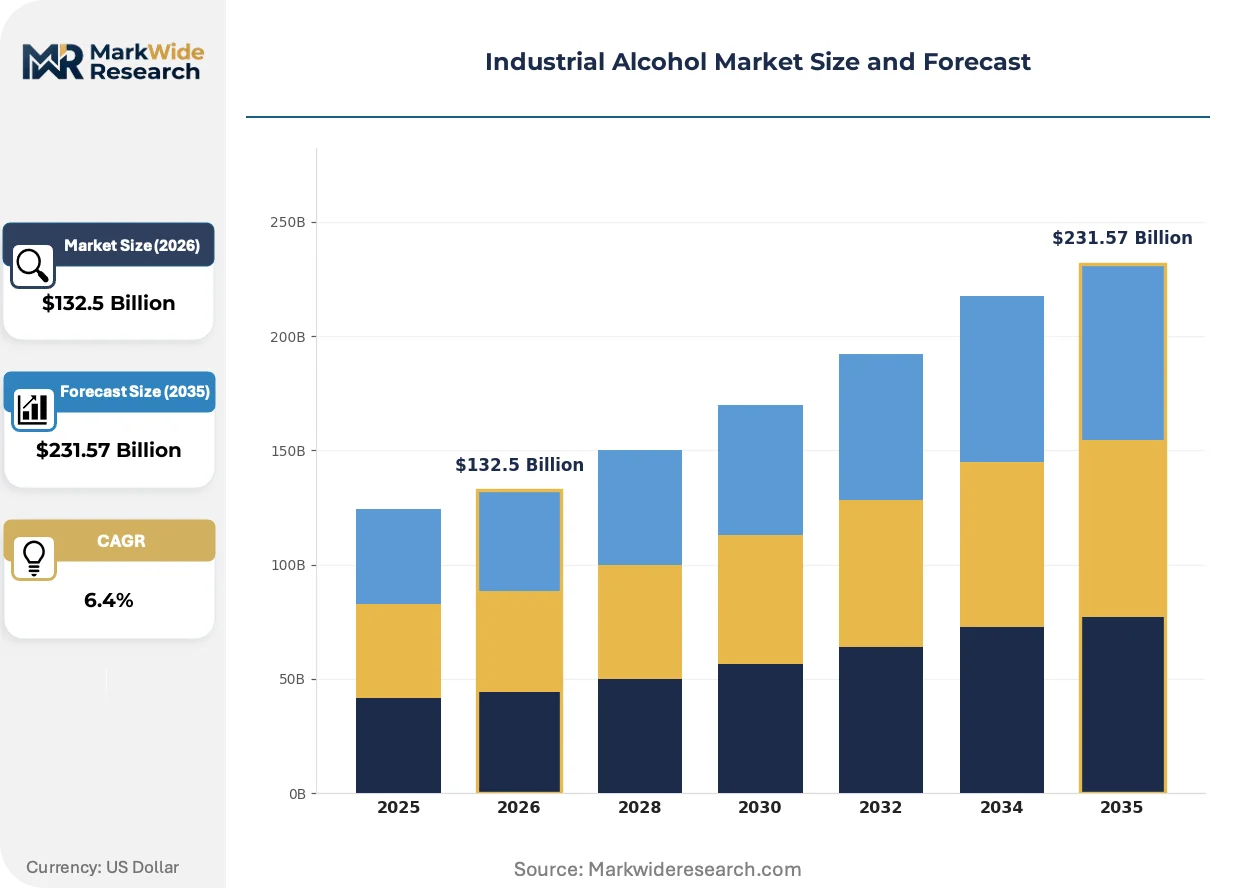
| Market Size in 2026 | $132.5 Billion |
| Market Size in 2035 | $231.57 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
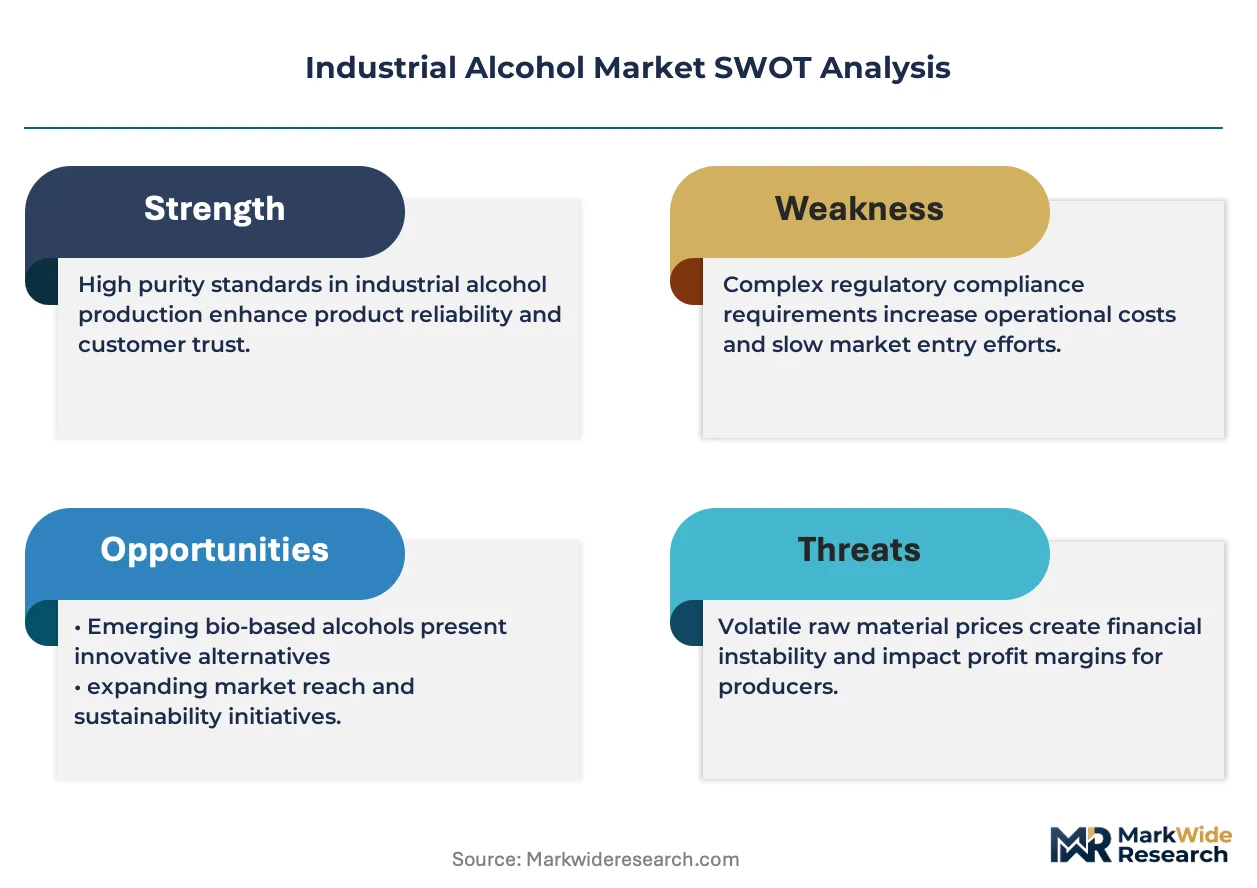
| Segmentation | Product Type: Ethyl Alcohol, Methyl Alcohol, Isopropyl Alcohol, Butanol, Amyl Alcohol Application: Solvent, Antiseptic, Fuel Additive, Chemical Intermediate, Personal Care Manufacturing Stage: Fermentation, Synthetic, Distillation, Purification, Blending End User Industry: Pharmaceuticals, Paints & Coatings, Cosmetics, Food Processing, Textile Treatment |
| Companies Covered | Cargill, Cristalco SAS, Green Plains Inc., MGP Ingredients Inc., Grain Millers Inc., The Andersons Inc., Birla Sugar, Raízen Energia, Greenfield Global Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Alcohol Market Strategic Shifts & Innovations
Sustainability mandates and demand for higher performance specifications are simultaneously reshaping the market. This dynamic drives innovation in bio-based production and the development of specialty grades for demanding applications.
Cellulosic ethanol technology utilizes enzymatic hydrolysis to process non-food biomass like corn stover into fermentable sugars. Biofuel producers and chemical companies are adopting this process to diversify feedstocks beyond food crops. This second-generation method is displacing the exclusive reliance on crop-based inputs, addressing food-versus-fuel concerns.
The European Union’s updated Renewable Energy Directive (RED III) raises targets for renewables in transport, including sub-targets for advanced biofuels. This legislation incentivizes investment in capacity for fuels from non-food feedstocks, like cellulosic ethanol. European fuel suppliers are most affected, now required to source and blend more advanced alcohols.
A significant shift involves the preference for industrial alcohols with verifiable sustainability credentials, such as ISCC or Bonsucro certifications. This trend disrupts procurement of uncertified commodity alcohol, favoring suppliers who provide full supply chain traceability. This is most pronounced in Europe's personal care sector, where brand reputation is tied to ESG performance.
Industrial Alcohol Market Segmentation
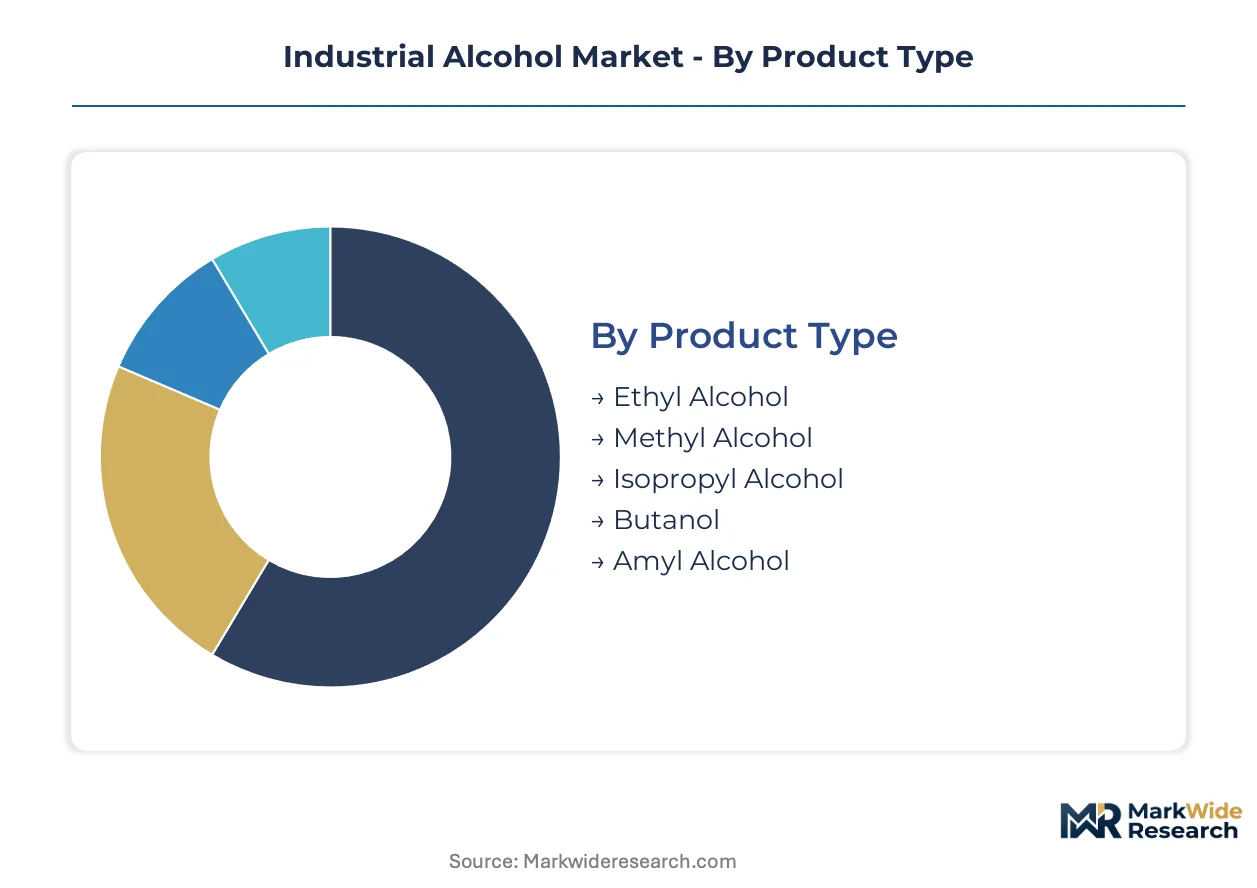
The industrial alcohol market segments reflect a complex interplay between chemical properties, production methods, and diverse end-user requirements. Understanding these distinctions is critical for producers to navigate regulatory landscapes and for consumers to ensure product suitability for their specific applications.
Product Type:
Regulatory bodies often differentiate industrial alcohol grades by their chemical composition and intended use, influencing production standards and market access.
- Ethyl Alcohol:This organic compound, primarily produced via fermentation of biomass or synthetic hydration of ethylene, serves as a versatile solvent, chemical intermediate, and fuel additive. Demand concentrates in Brazil and the United States for fuel blending, alongside pharmaceutical applications requiring high purity.
- Isopropyl Alcohol:A clear, colorless solvent and antiseptic, commonly produced from propylene, it is valued for its rapid evaporation and low toxicity compared to other alcohols. Demand is consistent in pharmaceutical and personal care markets for sanitizers and disinfectants, and in electronics for cleaning.
- Methyl Alcohol:As the simplest alcohol, methanol is a crucial chemical feedstock for formaldehyde and acetic acid production, also used as a solvent and fuel.
- Butanol:This higher alcohol finds application as a solvent in coatings and as a potential biofuel, offering a lower vapor pressure than ethanol.
- Amyl Alcohol:Used as a solvent in lacquers and as a frothing agent in mineral processing, amyl alcohol consists of several isomeric forms.
Ethyl Alcohol handles the majority of throughput; Isopropyl Alcohol is the fastest mover on share.
Application:
Application needs dictate purity levels and regulatory compliance for industrial alcohols, influencing their market value and distribution channels.
- Fuel Additive:Ethanol blended with gasoline enhances octane and reduces emissions, driven by national biofuel mandates and environmental policies. This application creates vast, stable demand in countries like Brazil and the United States.
- Antiseptic:High-purity ethyl or isopropyl alcohol sterilizes surfaces and skin, effectively killing microorganisms in medical and personal care settings. The pharmaceutical and healthcare sectors maintain consistent demand for these critical hygiene products.
- Solvent:Industrial alcohols dissolve other substances across diverse industries, from pharmaceuticals to paints and coatings, representing a mature but essential application segment.
- Chemical Intermediate:Alcohols serve as fundamental building blocks for synthesizing a wide array of other chemicals, including esters, ethers, and plastics, supporting the broader chemical industry.
- Personal Care:Alcohols function as carriers, preservatives, or active ingredients in cosmetics, perfumes, and toiletries, contributing to product stability and efficacy.
Market demand for industrial alcohol applications remains heavily influenced by feedstock availability and evolving environmental regulations.
Manufacturing Stage:
Production pathways for industrial alcohols are evolving, driven by sustainability targets and feedstock availability shifts.
- Fermentation:This biotechnological process converts biomass, such as corn, sugarcane, or cellulosic materials, into alcohol using microorganisms like yeast. This pathway is expanding due to the push for decarbonization and renewable resources.
- Synthetic:Chemical synthesis routes produce alcohols from fossil-based feedstocks, including natural gas or petroleum derivatives, offering cost-competitiveness in regions with abundant resources. Traditional industrial uses often rely on this method.
- Distillation:A purification technique that separates alcohol from water and other impurities based on differences in boiling points, essential for achieving desired purity levels.
- Purification:Advanced processes remove trace contaminants to meet stringent specifications for high-purity grades, critical for pharmaceutical and electronics applications.
- Blending:The process of combining different alcohol grades or adding denaturants to render industrial alcohol unfit for human consumption, tailoring products for specific end-uses and regulatory requirements.
Fermentation capacity is expanding globally, while synthetic production faces increasing pressure from environmental policies.
End User Industry:
Diverse end-user industries require specific industrial alcohol grades, tailored for their unique process and product requirements.
- Pharmaceuticals:This sector demands high-purity ethyl alcohol for use as an antiseptic, solvent for drug synthesis, and excipient in various formulations. Stringent quality controls govern alcohol procurement for drug manufacturing and healthcare.
- Paints & Coatings:Alcohols function as primary solvents for resins, binders, and pigments, influencing the viscosity, drying time, and overall performance of surface coatings. The construction and automotive industries are major consumers.
- Cosmetics:Industrial alcohols serve as solvents, preservatives, and carriers for active ingredients in a wide range of personal care products, including perfumes, lotions, and hairsprays.
- Food Processing:Alcohols are utilized as extraction solvents for flavorings, as carriers for food additives, and as sanitizing agents in food production facilities.
- Textile Treatment:In the textile industry, alcohols act as solvents or processing aids in dyeing, printing, and finishing operations, impacting fabric properties and appearance.
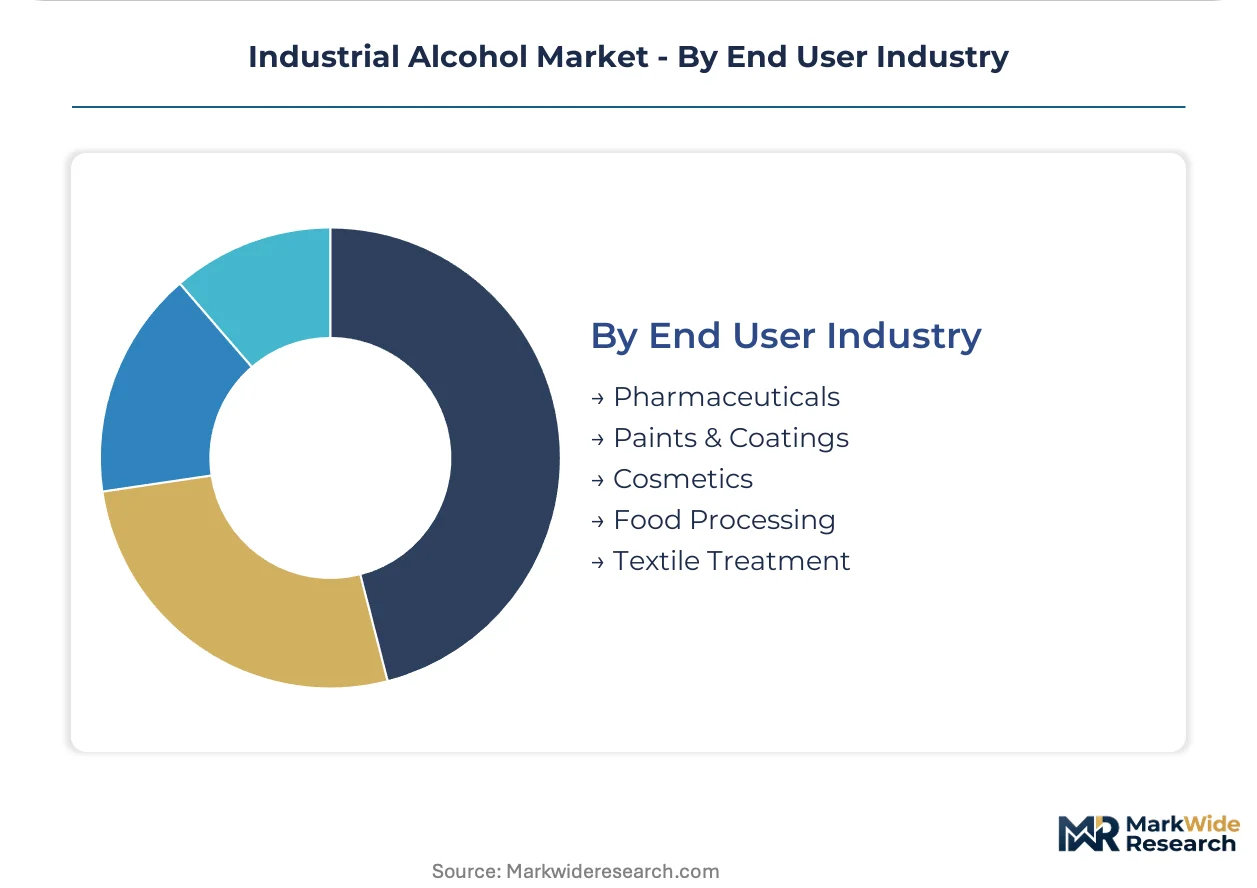
The pharmaceutical sector drives demand for premium, high-purity alcohols, while industrial applications like paints and coatings consume significant volumes of commodity grades.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US EPA's Renewable Fuel Standard significantly influences industrial alcohol demand across key global markets. This regulation, alongside other national and regional policies, drives production and consumption patterns for fuel-grade ethanol and high-purity industrial alcohols worldwide. Diverse regulatory frameworks and feedstock availability shape regional market dynamics.
Brazil
Demand for fuel-grade ethanol anchors Brazil's industrial alcohol market, driven by its well-established flex-fuel vehicle fleet. The country's national biofuel policies mandate high blending ratios, ensuring stable consumption. São Paulo state, with its extensive sugarcane processing infrastructure, remains the epicenter for bioethanol production.
United States
The United States sees strong demand for ethyl alcohol in fuel blending and high-purity applications for pharmaceuticals. The US EPA's Renewable Fuel Standard provides a consistent market for corn-based ethanol. Production facilities across the Midwest states, particularly Iowa and Illinois, concentrate ethanol manufacturing capacity.
Germany
Germany's industrial alcohol market emphasizes bio-based solvents and high-purity grades, influenced by European environmental directives. The EU's REACH framework and Renewable Energy Directive (RED III) push for sustainable chemical feedstocks. The Rhine-Ruhr region, a major chemical manufacturing hub, drives demand for specialty alcohols.
India
India exhibits consistent demand for industrial alcohol across diverse applications, including pharmaceuticals and chemical intermediates. The Bureau of Indian Standards (BIS) sets critical quality parameters for various alcohol grades, impacting domestic production and imports. Maharashtra state, with its robust chemical and pharmaceutical industries, represents a significant consumption center.
Industrial Alcohol Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier within the industrial alcohol market. This tiered structure reflects the capital-intensive nature of large-scale production versus the specialized requirements for high-purity grades. Strategic archetypes include large-scale commodity producers, niche specialty alcohol manufacturers, and bio-based innovators. Capacity expansion and portfolio diversification represent dominant competitive moves among these players.
At the scale-driven end, Cargill exemplifies large-scale commodity ethanol production, leveraging its vast agricultural supply chain for feedstock. Raízen Energia, based in Brazil, anchors the bioethanol sector through its massive sugarcane processing capacity. MGP Ingredients Inc. occupies a position within the specialty alcohol segment, differentiating on premium quality for distilled spirits and high-purity applications.
| Leading Market Players |
|---|
| Cargill |
| Cristalco SAS |
| Green Plains Inc. |
| MGP Ingredients Inc. |
| Grain Millers Inc. |
| The Andersons Inc. |
| Birla Sugar |
| Raízen Energia |
| Greenfield Global Inc. |
Cost & Logistics Intelligence
Massive fermentation capacity utilization dictates supply concentration and influences price floors for commodity industrial alcohols. This concentration of production significantly impacts global pricing power and market access for various grades.
Pricing Analysis
Geographic price spreads for industrial alcohol reflect regional feedstock costs and regulatory frameworks. The market operates on a hybrid model, combining commodity spot pricing for bulk ethanol with contract-based long-term offtake agreements for high-purity grades. Price differentiation stems from quality grade, such as pharmaceutical purity versus fuel-grade, and specific certifications like ISCC or Bonsucro. Pricing pressure stems from agricultural commodity price volatility, particularly for corn and sugarcane. Pharmaceutical buyers exhibit the least price sensitivity for high-purity ethyl alcohol, while paints and coatings manufacturers are highly sensitive to commodity alcohol costs.
Supply Chain Analysis
Strategic stockpiling of agricultural feedstocks mitigates supply disruptions in industrial alcohol production. The supply chain concentrates significantly in Brazil for sugarcane-based ethanol and the United States for corn-based ethanol, with Germany leading in specialty bio-based solvents. Raw material dependencies include corn, sugarcane, and propylene for isopropyl alcohol production. Feedstock price volatility represents a primary structural risk to the supply chain. Distribution runs through bulk transport for commodity grades and specialized logistics for high-purity, denatured, or certified products.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The industrial alcohol market is poised for a cyclical recovery, driven by renewed industrial activity and consistent demand from pharmaceutical applications. This demand underpins market stability and growth projections.
For Market Incumbents: Consolidate existing fermentation capacity in key agricultural regions to optimize cost structures against feedstock price volatility. Invest in advanced bioprocess engineering to improve yields and diversify into cellulosic ethanol production, mitigating "food-versus-fuel" concerns. Secure long-term supply agreements with pharmaceutical and personal care clients, leveraging certification investments to counter substitution risk from synthetic alternatives. Expand R&D into alcohol-to-jet pathways to capture future demand vectors.
For New Entrants and Emerging Players: Differentiate on sustainability credentials and high-purity specifications to capture demand in Europe's personal care sector. Target the underpenetrated bio-based chemical intermediate segment by offering renewable alternatives to petroleum-based feedstocks. Focus on developing cellulosic ethanol technology to access non-food biomass, reducing reliance on traditional crop inputs. A go-to-market angle emphasizing ISCC or Bonsucro certifications will unlock premium market access.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among producers specializing in high-purity alcohols for pharmaceutical and personal care markets. Long-term viability favors companies with established bio-based fermentation capacity and advanced bioprocess engineering expertise. Acquisition targets should include firms with proprietary cellulosic ethanol technology or strong market access in emerging biofuel blending regions like Asia and Africa. A signal to watch is the expansion of alcohol-to-jet pathway investments by major energy companies.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion for Bio-based Ethanol | This increases supply of renewable fuel and chemical feedstock, addressing decarbonization goals. |
| Green Manufacturing Process Transition | This reduces environmental footprint and aligns with circular economy principles, enhancing brand reputation. |
| Long-term Supply Agreements with Pharma | This secures stable revenue streams for high-purity alcohol producers, insulating against price swings. |
| Joint Venture for Alcohol-to-Jet Development | This unlocks new demand for ethanol in sustainable aviation fuel, diversifying product portfolios. |
| Portfolio Diversification into Bio-based Chemicals | This leverages existing ethanol production for higher-value chemical intermediates, expanding market reach. |
Research Approach
A standing panel of biorefinery plant managers, pharmaceutical procurement leads, chemical intermediate R&D directors, and biofuel policy analysts provided ongoing calibration for market data. This primary research was rigorously validated through secondary sources, including EPA Renewable Fuel Standard reports, EU REACH documents, BIS standards, and agricultural commodity market data. The analysis integrated both bottom-up aggregation and top-down market sizing approaches for comprehensive coverage.
Forecast outputs underwent rigorous consistency checks against external industry benchmarks and governmental energy projections. The analytical framework modeled market dynamics across the analysis window, segmenting by product type, application, manufacturing stage, end-user industry, and purity grade. Compound annual growth rates were derived from historical trends, projected feedstock availability, and anticipated regulatory impacts. Biofuel blending mandates and agricultural commodity price forecasts served as critical industry-specific forecast inputs.
The analysis sits within stated boundaries; outcomes outside significant shifts in national biofuel mandates or feedstock supply would require recalibration. Forecasts reflect a comprehensive set of assumptions regarding technological advancements and regulatory evolution. Revision becomes warranted when regulatory changes or technological breakthroughs cross predefined thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Digital Shaker Market
Alcoholic Beverages
Beer Bottling Kit Market
Alcoholic Beverages
Cannabis-Based Alcoholic Beverages Market
Alcoholic Beverages
Cannabis Drinks Market
Alcoholic Beverages
Specialty Beer Market
Alcoholic Beverages
Brewing Supplies Market
Alcoholic Beverages
Hard Kombucha Market
Alcoholic Beverages
Mini Brew Fermenter Market
Alcoholic Beverages
Global Malted Barley Market
Alcoholic Beverages
Alcoholic Drinks Market
Alcoholic Beverages
Tequila Market
Alcoholic Beverages
Craft Rum Market
Alcoholic Beverages
Beer Cans Market
Alcoholic Beverages
Global Liquor Confectionery Market
Alcoholic Beverages
Germany Tequila Market
Alcoholic Beverages
Gluten-Free Beer Market