
 Scandinavia Car Rental Market | 2026-2036
Scandinavia Car Rental Market Size, Share, and Industry Trends Forecast 2026-2036
Scandinavia Car Rental Market Intelligence
Corporate fleet outsourcing is collapsing into short-term flexible contracts as the dominant buyer archetype across Nordic markets. Avis Budget Group anchors its position through centralized fleet management systems serving multinational accounts. Europcar Sweden differentiates via premium EV allocations targeting Oslo and Copenhagen business corridors. Green Motion specializes in zero-emission vehicle lines that align with municipal procurement rules.
Scandinavia car rental denotes the short-term and long-term commercial provision of passenger vehicles across Denmark, Norway, and Sweden, encompassing daily hires through multi-year operational leases with specified mileage thresholds and maintenance inclusions. The sector functions as a mobility substitute for capital-constrained businesses and tourists requiring temporary vehicle access without ownership obligations. Daily and weekly rental formats dominate transaction volumes, while long-term leasing captures the deepest margin pools from corporate clients seeking predictable fleet expenditures. SUV and sedan vehicle types lead Nordic preferences due to terrain demands and executive transport norms, with van segments serving last-mile logistics contractors through dedicated commercial channels.
Swedish Transport Agency regulations, Norwegian Public Roads Administration zero-emission procurement directives, and Danish Business Authority leasing disclosure standards collectively constrain fleet composition and contract transparency across all three markets. The EU Green Deal's transport decarbonization targets filter into national tender requirements, forcing operators to electrify offerings or forfeit public-sector contracts. Stakeholders must monitor battery supply commitments and charging infrastructure rollouts as determinants of competitive viability in forthcoming procurement cycles.
Market Dynamics
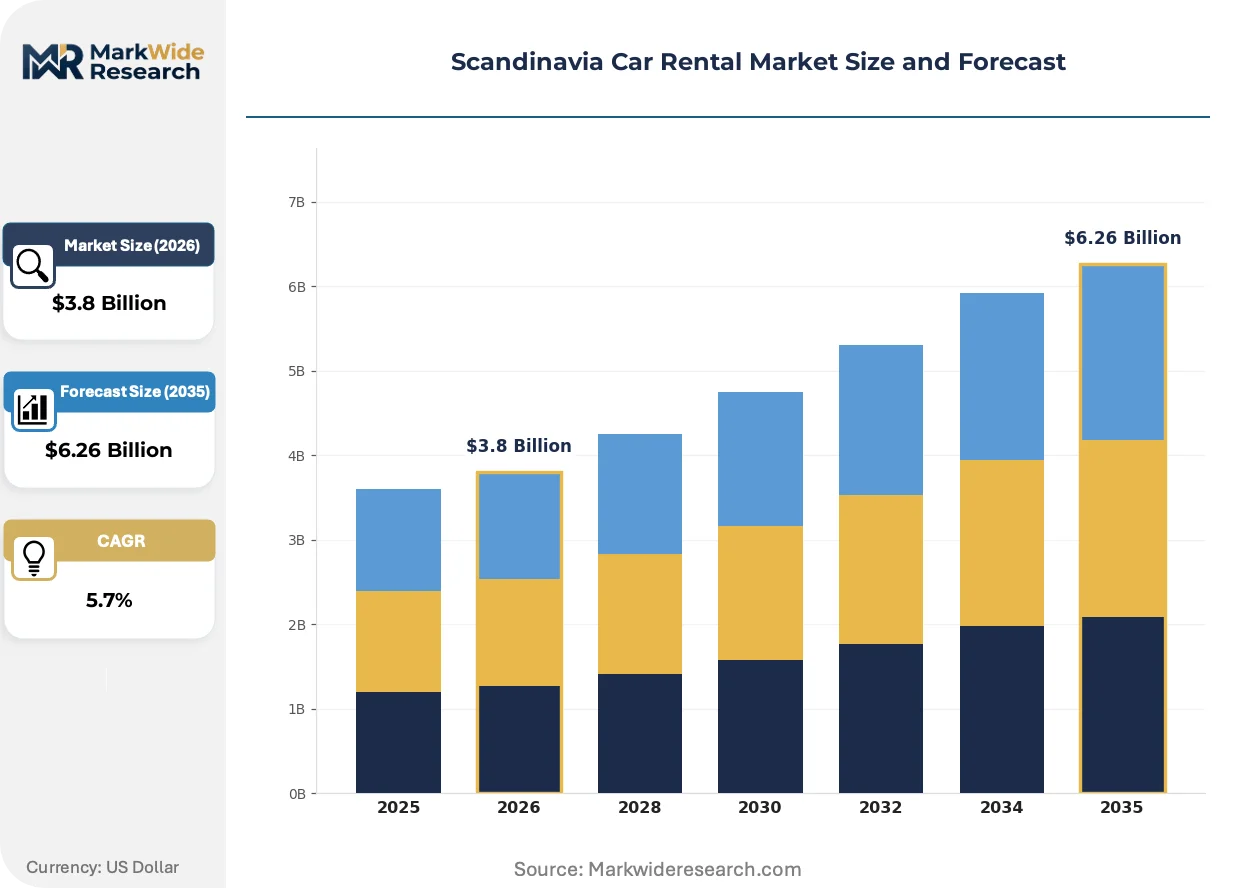
Norway's zero-emission vehicle mandate is compressing fleet procurement timelines across all three Nordic markets, forcing rental operators to restructure supplier relationships and charging infrastructure commitments ahead of regulatory deadlines.
Growth Catalysts
- EU Green Deal transport targets:National tender requirements in Denmark and Sweden now mandate minimum EV quotas for public-sector contracts, expanding addressable market for electrified fleet providers.
- Oslo-Copenhagen business corridor density:Corporate headquarters concentration generates sustained demand for premium flexible mobility solutions with predictable billing structures.
- Battery-as-a-service models:Decoupling battery ownership from vehicle acquisition lowers upfront capital barriers for mid-size rental operators expanding zero-emission lines.
Market Restraints
- Lithium supply concentration:Battery cell sourcing dependencies on Asian manufacturers create fleet procurement bottlenecks and price volatility exposure.
- Norwegian Public Roads Administration certification delays:Extended type-approval timelines for new EV models compress fleet refresh windows during peak demand seasons.
- Urban congestion charging zones:Stockholm and Gothenburg road pricing schemes erode margin on short-term urban rentals.
Strategic Opportunities
- Danish island tourism circuits:Bornholm and Ærø routes remain underserved by EV-specific rental infrastructure despite concentrated visitor flows.
- Swedish Transport Agency pooled mobility pilots:Municipal car-sharing integration programs offer fleet utilization premiums for participating operators.
- Telematics-embedded insurance convergence:Real-time driving data streams enable usage-based coverage products that reduce fleet risk capital requirements.
Industry Challenges
- High-voltage technician scarcity:Certified EV maintenance specialists command wage premiums that strain operational cost structures outside major urban clusters.
- Legacy reservation system integration:Proprietary fleet management platforms require expensive API redevelopment to synchronize with emerging charging network payment protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Scandinavia Car Rental Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Daily Rental, Weekly Rental, Monthly Rental, Long-term Leasing Vehicle Type: SUV, Sedan, Hatchback, Van Customer Type: Corporate Clients, Tourists, Locals, Government Agencies Booking Channel: Online Platforms, Travel Agencies, Phone Reservations, In-person |
| Companies Covered | Avis Budget Group, Mabi Rent, Hertz Sweden, Alamo Rent A Car, Green Motion, Europcar Sweden, Enterprise Rent-A-Car, National Car Rental, Sixt Sweden, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Scandinavia Car Rental Market Strategic Shifts & Innovations
Connected vehicle architectures are redefining how rental operators monetize fleet assets beyond per-day pricing, embedding telematics-derived services into core contract structures.
Vehicle-to-grid (V2G) bidirectional charging hardware is miniaturizing from industrial-scale installations to passenger-compatible units. Municipal fleet operators in Oslo and Copenhagen are piloting grid-balancing revenue streams during vehicle idle periods. This technology is miniaturizing the economic threshold for rental operators to participate in energy markets, compressing payback periods for EV capital investments.
Swedish Transport Agency regulations now mandate real-time emissions reporting for all commercial fleets above fifty vehicles. Operators must deploy onboard diagnostics with automated data transmission to national monitoring systems. Long-term leasing divisions face the steepest compliance costs as multi-year contracts span pre- and post-mandate fleet compositions.
Corporate travel managers are consolidating preferred supplier agreements around carbon-accounting transparency requirements. Traditional daily-rate bidding is yielding to total-cost-of-mobility contracts that internalize charging, parking, and emissions offset expenses. This pattern concentrates procurement power among Nordic enterprise accounts with dedicated sustainability procurement functions.
Scandinavia Car Rental Market Segmentation
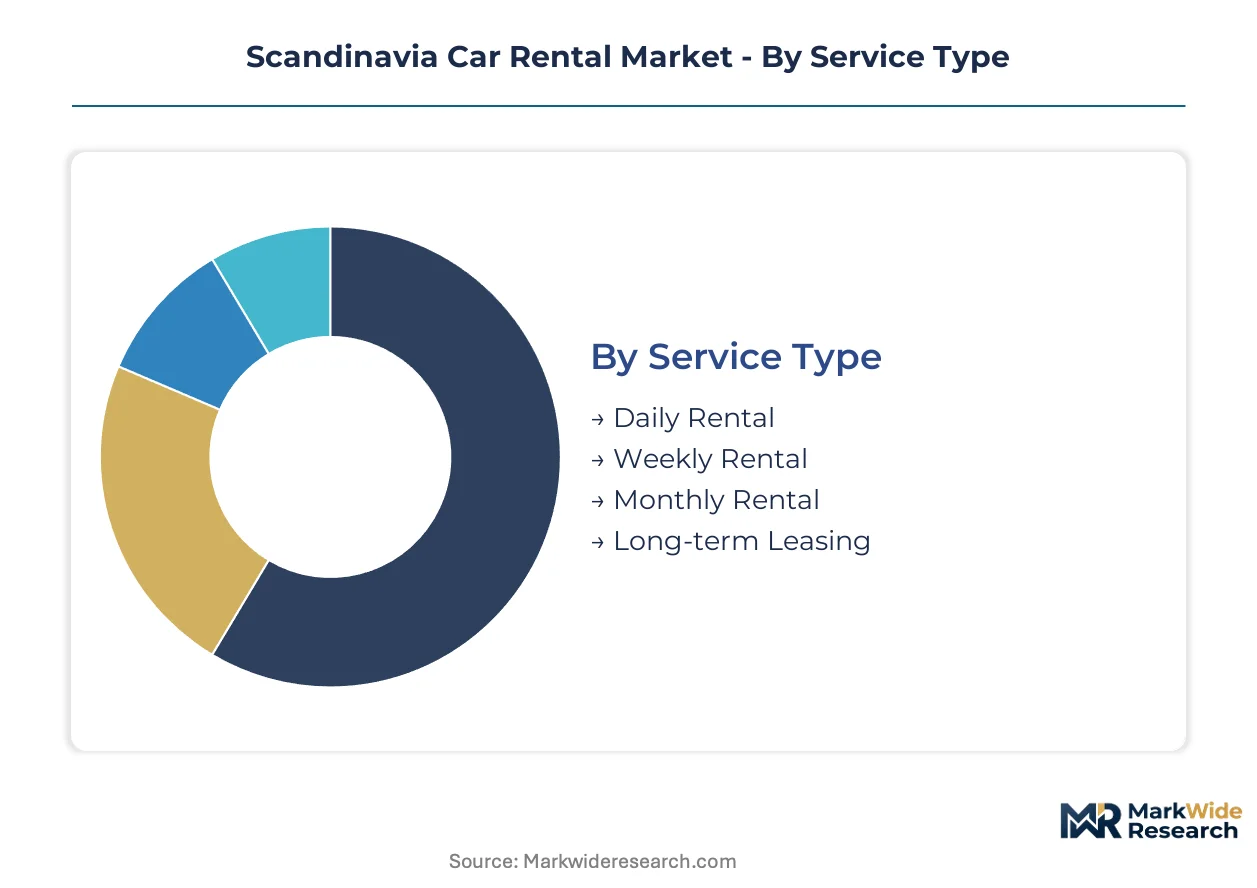
Scandinavia's car rental segmentation reflects divergent regulatory pressures across Denmark, Norway, and Sweden. Norwegian zero-emission mandates compress service timelines while Swedish Transport Agency pooled mobility pilots reshape customer access patterns.
Service Type:
Swedish Transport Agency regulations mandate emissions reporting thresholds that vary by contract duration, creating compliance cost differentials across service tiers.
- Daily Rental:Transaction-dense format capturing tourist arrivals at Copenhagen Airport and Oslo Gardermoen. Stockholm congestion charging zones erode per-unit margins despite high turnover velocity.
- Weekly Rental:Preferred format for Bornholm and Ærø island tourism circuits where visitors seek flexible vehicle access without long-term obligations. Danish Business Authority leasing disclosure standards apply less stringently to sub-seven-day contracts.
- Monthly Rental:Bridge format serving project-based corporate mobility needs in Gothenburg's industrial corridors.
- Long-term Leasing:Multi-year operational leases with specified mileage thresholds dominate enterprise procurement in Oslo-Copenhagen business corridors.
Established volume favors Daily Rental; emerging adoption favors Long-term Leasing.
Vehicle Type:
Procurement costs stratify sharply between internal combustion and electrified platforms under Norway's zero-emission vehicle mandate.
- SUV:Terrain-optimized platforms commanding premium positioning across Nordic rural routes. Norwegian Public Roads Administration certification delays for new EV SUV models compress fleet refresh windows during peak summer demand seasons.
- Sedan:Executive transport norm for corporate accounts in Stockholm and Copenhagen headquarters districts. EU Green Deal transport targets accelerate electrified sedan allocations in public-sector tender responses.
- Hatchback:Compact urban format aligning with Gothenburg and Oslo congestion zone access patterns.
- Van:Last-mile logistics contractors in Danish commercial channels drive dedicated fleet configurations with telematics-embedded insurance convergence.
Margin concentration sits with Sedan; steepest expansion trajectory belongs to electrified SUV lines.
Customer Type:
Carbon-accounting transparency requirements now govern procurement consolidation patterns across buyer archetypes.
- Corporate Clients:Enterprise accounts with dedicated sustainability procurement functions negotiate total-cost-of-mobility contracts internalizing charging, parking, and emissions offset expenses. Battery-as-a-service models lower upfront capital barriers for mid-size operators serving this segment.
- Tourists:Seasonal demand concentrates in Swedish urban corridors, particularly Stockholm and Gothenburg, with EV-specific infrastructure gaps on Danish island circuits creating service voids.
- Locals:Swedish Transport Agency pooled mobility pilots offer fleet utilization premiums for operators integrating with municipal car-sharing programs.
- Government Agencies:Public-sector contracts now mandate minimum EV quotas under national tender requirements in Denmark and Sweden, expanding addressable market for electrified fleet providers.
Revenue depth favors Corporate Clients; policy tailwinds favor Government Agencies.
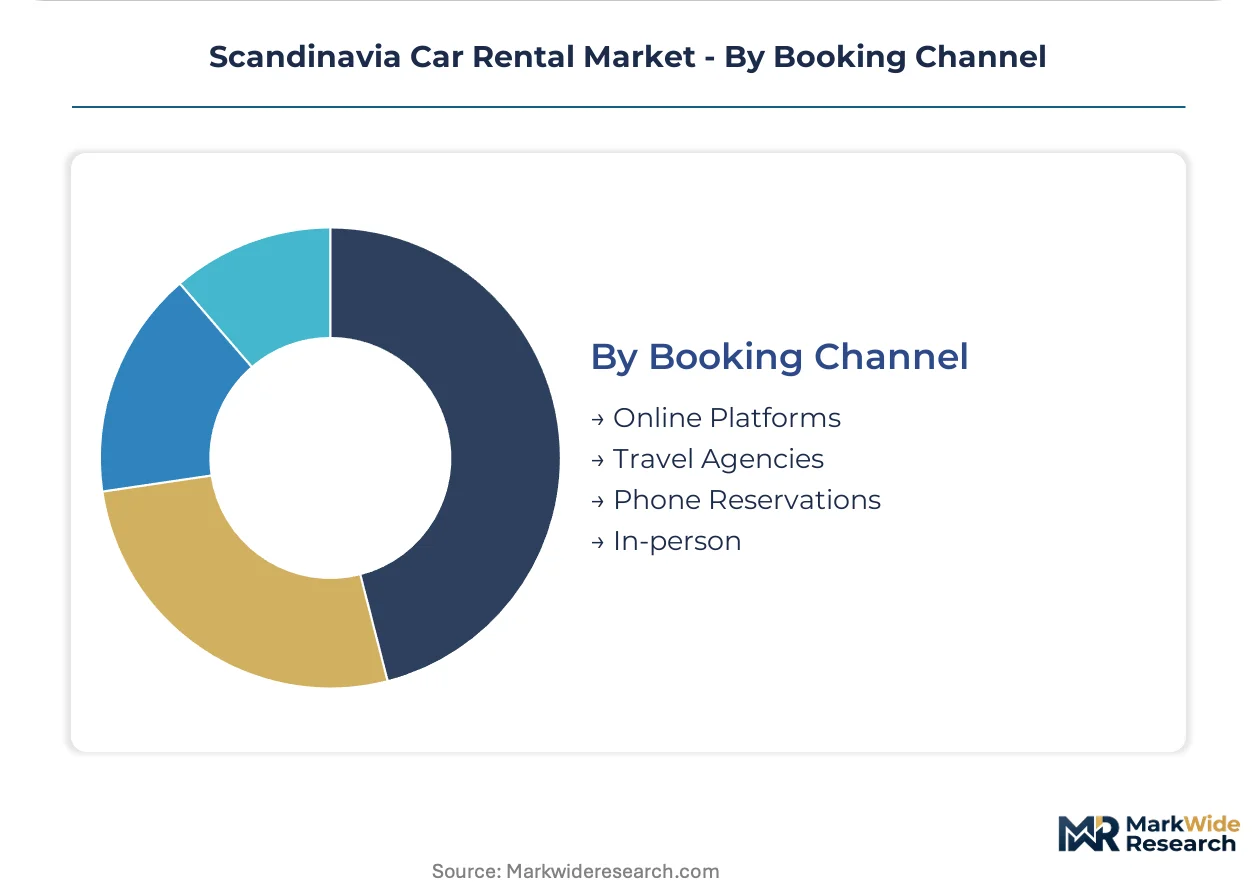
Booking Channel:
Legacy reservation system integration costs stratify channel economics across operator scale tiers.
- Online Platforms:Dominant transaction path requiring expensive API redevelopment to synchronize with emerging charging network payment protocols. Corporate travel managers consolidate preferred supplier agreements through centralized platform access.
- Travel Agencies:Intermediary channel serving international tourist inflows at Copenhagen and Oslo gateway airports.
- Phone Reservations:Declining format retained for government contract compliance and accessibility mandates.
- In-person:Airport counter presence sustains premium positioning for business corridor rentals despite operational overhead.
Transaction volume concentrates in Online Platforms; margin preservation favors In-person service tiers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fleet procurement decisions cluster around three national regulatory regimes. Each Nordic market imposes distinct electrification timelines and municipal access rules that reshape operator economics.
Norway
Zero-emission vehicle mandates compress fleet refresh cycles for rental operators serving Oslo Gardermoen and Bergen corridors. The Norwegian Public Roads Administration enforces strict type-approval timelines that delay new EV SUV deployments during peak summer demand. Stavanger's offshore services sector generates sustained corporate leasing volume for extended-stay project personnel.
Sweden
Stockholm congestion charging zones erode per-unit margins on short-term urban rentals despite high transaction velocity. Swedish Transport Agency pooled mobility pilots offer fleet utilization premiums for operators integrating with municipal car-sharing programs. Gothenburg's industrial corridors anchor monthly rental demand from project-based corporate mobility needs.
Denmark
Bornholm and Ærø island tourism circuits remain underserved by EV-specific rental infrastructure despite concentrated visitor flows. Danish Business Authority leasing disclosure standards apply less stringently to sub-seven-day contracts, favoring weekly rental formats. Copenhagen Airport anchors transaction-dense daily rental volume for international tourist arrivals.
Scandinavia Car Rental Market Key Industry Players
Concentration sits with multinational fleet operators possessing centralized management systems and established airport counter networks. The vendor base spans three tiers: global brands with Nordic subsidiaries, regional specialists targeting premium EV segments, and local operators serving island tourism circuits. Strategic moves center on electrified fleet procurement acceleration and API redevelopment for charging network payment synchronization.
Among global-brand operators, Avis Budget Group and Enterprise Rent-A-Car anchor the corporate leasing segment through multinational account servicing infrastructure. Green Motion occupies a specialist position aligned with municipal zero-emission procurement rules. Regional players including Europcar Sweden and Sixt Sweden exemplify premium-tier positioning targeting Oslo-Copenhagen business corridor density.
| Leading Market Players |
|---|
| Avis Budget Group |
| Mabi Rent |
| Hertz Sweden |
| Alamo Rent A Car |
| Green Motion |
| Europcar Sweden |
| Enterprise Rent-A-Car |
| National Car Rental |
| Sixt Sweden |
| Others |
Cost & Logistics Intelligence
Long-term leasing contracts with embedded charging and maintenance provisions lock in both fleet procurement access and predictable unit economics for Nordic operators navigating Norway's zero-emission vehicle mandate. These structures insulate corporate clients from battery price volatility while binding rental providers to fixed-cost recovery schedules across multi-year tenures.
Pricing Analysis
Norwegian Public Roads Administration zero-emission procurement directives dictate the pricing tier structure across Scandinavian rental markets. Three-tier pricing stratifies across premium EV allocations, standard hybrid fleets, and residual internal-combustion economy lines. Price differentiation rests on certification grade under EU Green Deal transport targets and geographic delivery cost to Oslo-Copenhagen business corridors. Cost compression in economy tiers is intensifying because lithium supply concentration strains procurement budgets. Tourist segments at Copenhagen Airport and Oslo Gardermoen exhibit highest price sensitivity; corporate accounts with sustainability procurement functions show lowest sensitivity due to total-cost-of-mobility accounting.
Supply Chain Analysis
Port congestion at Rotterdam and container availability on Asia-Europe trade lanes compress inbound logistics windows for EV fleet deliveries to Nordic markets. Geographic supply concentration centers on China, South Korea, and Germany for battery cells, power electronics, and chassis platforms respectively. Raw material dependencies span lithium carbonate, cobalt sulfate, and rare-earth permanent magnets. Single-source vulnerability in battery cell sourcing creates fleet procurement bottlenecks during peak summer refresh cycles. Distribution runs through centralized fleet management hubs in Stockholm, Oslo, and Copenhagen with last-mile satellite depots serving airport and municipal car-sharing nodes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
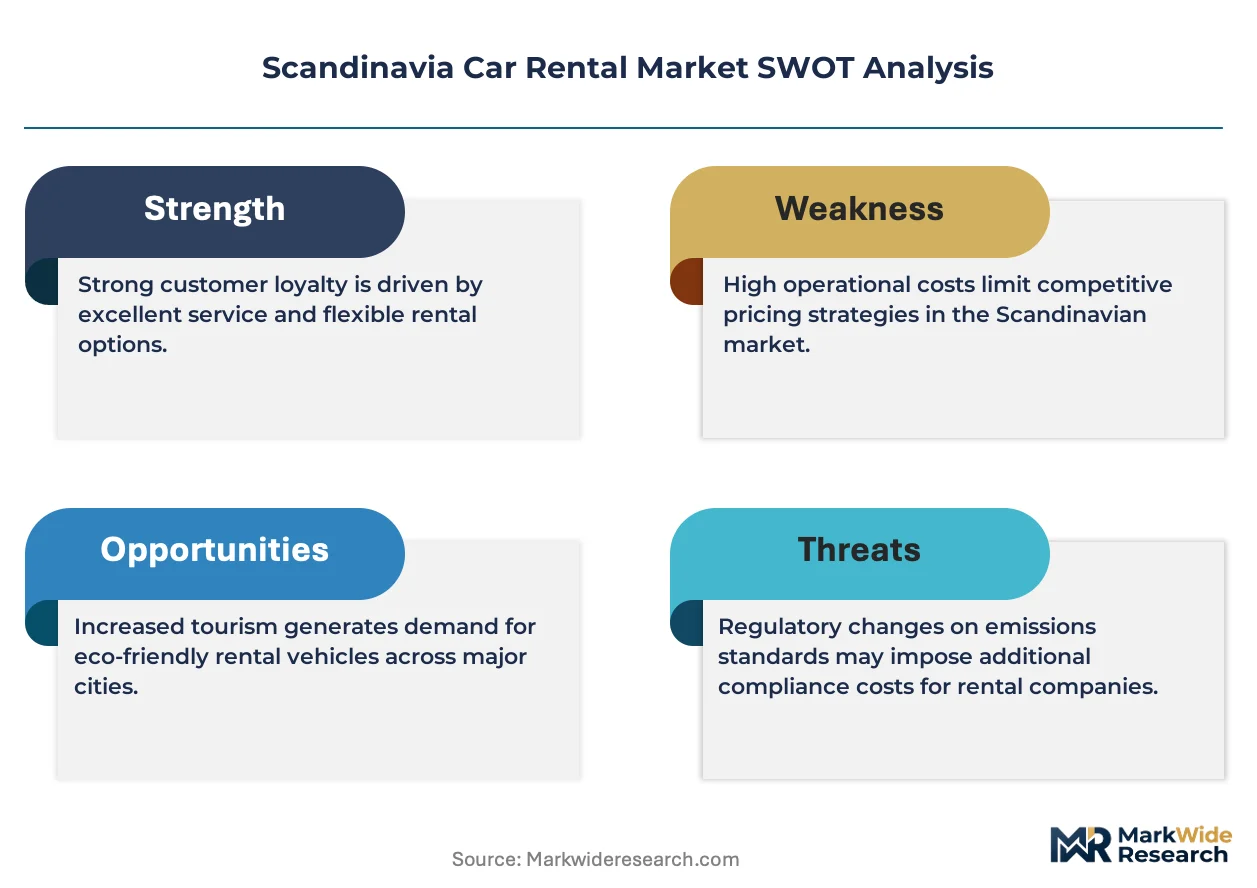
Scandinavia's car rental market presents a defensive-moat structure anchored in regulatory entrenchment. Norway's zero-emission vehicle mandate and Swedish Transport Agency emissions reporting requirements create compliance barriers that favor incumbent operators with established certification infrastructure and centralized fleet management systems.
For Market Incumbents: Secure charging infrastructure partnerships ahead of Norwegian Public Roads Administration certification deadlines to compress fleet refresh timelines. Anchor corporate leasing divisions with battery-as-a-service models that lower upfront capital barriers and lock in multi-year total-cost-of-mobility contracts. Vertical integration into telematics-embedded insurance products reduces fleet risk capital requirements against emerging mobility-substitute threats from pooled municipal programs. For New Entrants and Emerging Players: Differentiate on zero-emission vehicle specialization targeting Danish island tourism circuits where EV-specific rental infrastructure remains underserved despite concentrated visitor flows on Bornholm and Ærø routes. Penetrate the weekly rental format where Danish Business Authority leasing disclosure standards apply less stringently than long-term contracts. Deploy direct-to-island ferry port distribution to bypass incumbent airport counter dominance. For Investors and Strategic Acquirers: Capital is best deployed toward mid-size operators with established municipal car-sharing integrations and pending Swedish Transport Agency pooled mobility pilot certifications. Long-term viability hinges on fleet electrification completion before regulatory deadlines harden into procurement disqualifiers. Monitor battery supply commitment announcements from Asian manufacturers as the inflection signal for competitive viability in forthcoming tender cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Charging Infrastructure Partnership | Oslo and Copenhagen municipal grid-balancing pilots create ancillary revenue streams during vehicle idle periods. |
| Battery-as-a-Service Model | Decoupled battery ownership lowers upfront capital barriers for mid-size operators expanding zero-emission lines. |
| Telematics-Embedded Insurance | Real-time driving data streams enable usage-based coverage products reducing fleet risk capital requirements. |
| Municipal Car-Sharing Integration | Swedish Transport Agency pooled mobility pilots offer fleet utilization premiums for participating operators. |
| Zero-Emission Fleet Procurement | EU Green Deal transport targets mandate minimum EV quotas for public-sector contracts in Denmark and Sweden. |
Research Approach
A spread of perspectives from fleet procurement directors at multinational rental operators, charging infrastructure developers, corporate travel managers with sustainability mandates, and regulatory affairs leads at national transport agencies converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation against Norwegian Public Roads Administration type-approval databases, Swedish Transport Agency emissions reporting filings, Danish Business Authority leasing disclosure records, and EU Green Deal tender requirement documents. Bottom-up fleet composition analysis and top-down market sizing triangulated volume estimates.
Segmentation dimensions modeled include service type across daily through long-term leasing tiers, vehicle propulsion architecture spanning internal combustion to battery-electric platforms, customer archetype from corporate accounts to island tourists, and booking channel concentration between online platforms and in-person airport counters. CAGRs were derived from regression analysis of historical fleet procurement patterns projected across the analysis window. Industry-specific forecast inputs incorporated battery supply commitment announcements and charging infrastructure rollout schedules.
Forecasts assume regulatory continuity in Norwegian zero-emission mandates, Swedish Transport Agency reporting thresholds, and Danish Business Authority disclosure standards; material policy shifts would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation Services
Corporate Employee Transportation Service Market
Transportation Services
Third Party Logistics Services Market
Transportation Services
United Kingdom Car Rental Market
Transportation Services
United Arab Emirates Car Rental Market
Transportation Services
Bulk Transportation Services Market
Transportation Services
MUV Rental Market
Transportation Services
Vehicle Management System Market
Transportation Services
Fleet Management Consulting Service Market
Transportation Services
Australia Taxi Market
Transportation Services
Ride-Hailing Service Market
Transportation Services
United States White Glove Delivery Service Market
Transportation Services
On Street Vehicle Parking Meter Market
Transportation Services
Truck Rental Market
Transportation Services
ASEAN Car Rental Market
Transportation Services
Truck Sharing Market
Transportation Services
Full-Service Carrier Market