
 United Kingdom Car Rental Market | 2026-2036
United Kingdom Car Rental Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Car Rental Market Analytics
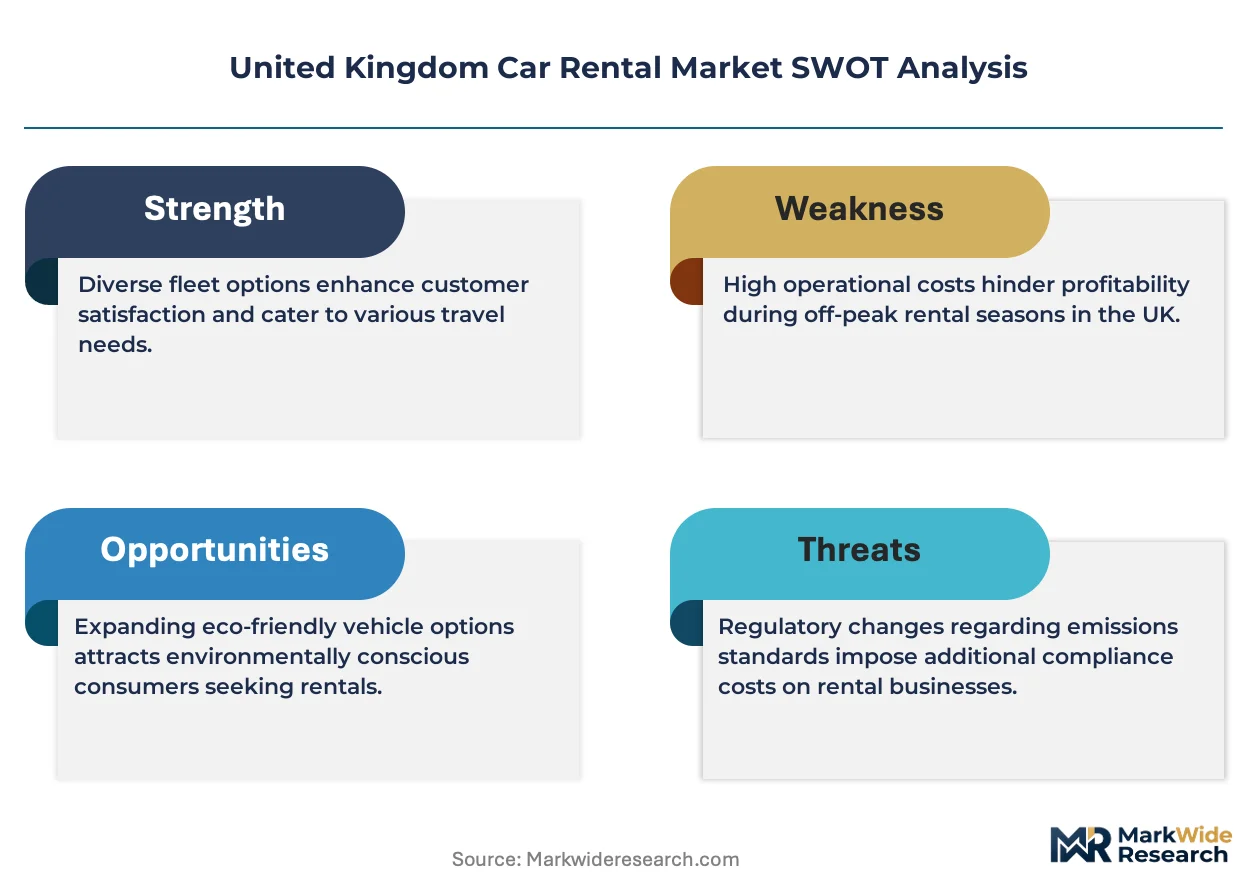
Corporate mobility procurement is pivoting from fixed-term leases toward subscription and short-term rental hybrids. Enterprise Rent-A-Car UK leverages its airport branch density to capture inbound business travellers at Heathrow and Gatwick. Europcar Mobility Group anchors its position through urban car-sharing partnerships with Transport for London. SIXT SE differentiates via premium electric vehicle availability in central London zones.
United Kingdom car rental denotes the commercial provision of temporary vehicle access against time-based fees, encompassing fleet ownership, maintenance scheduling, insurance bundling, and digital reservation platforms. Operators manage asset depreciation curves, utilization rates typically targeting seventy-plus percent, and residual value forecasting to sustain unit economics. Leisure customers dominate transaction volume through online and mobile app booking channels, while long-term rental structures capture higher per-contract value from SME fleet outsourcing. Luxury vehicle types command premium daily rates but carry steeper capital intensity and narrower demand windows.
The Driver and Vehicle Licensing Agency enforces operator licensing standards that shape fleet composition and driver eligibility criteria across England, Scotland, Wales, and Northern Ireland. The Office of Rail and Road monitors competition in transport-adjacent markets, influencing rental pricing transparency at rail-interchange locations. Stakeholders must weigh ICE fleet liquidation timelines against electric vehicle charging infrastructure gaps when configuring regional depot networks.
Market Dynamics
The UK's zero-emission vehicle mandate and 2030 internal combustion engine phase-out deadline are compressing diesel fleet residual values while forcing operators to accelerate electric vehicle procurement timelines ahead of charging infrastructure readiness.
Growth Catalysts
- Rail-air intermodality:Dense pickup nodes around Heathrow, Gatwick, and Birmingham New Street station concentrate inbound business traveller demand.
- ZEV mandate:The UK's legally binding zero-emission vehicle sales requirement pulls fleet operators toward battery electric vehicle contracts.
- SME fleet outsourcing:Small and medium enterprises across England's West Midlands are substituting owned vehicles for flexible rental structures.
Market Restraints
- Charging infrastructure gaps:Rapid depot electrification requirements outpace grid connection approvals in Greater Manchester and West Midlands conurbations.
- Diesel residual value collapse:The 2030 ICE phase-out deadline accelerates depreciation curves on existing fleet assets.
- Insurance cost volatility:Young driver surcharges and electric vehicle repair complexity inflate per-rental coverage expenses.
Strategic Opportunities
- Subscription hybrid models:Corporate procurement teams in London's Square Mile are piloting month-to-month vehicle access replacing fixed-term leases.
- Transport for London partnerships:Urban car-sharing integrations with municipal mobility platforms open dedicated parking bay allocations.
- Scottish expansion:Underpenetrated Edinburgh and Glasgow airport corridors present fleet density growth potential.
Industry Challenges
- Telematics integration complexity:Legacy reservation platforms require costly API overhauls to unify electric vehicle state-of-charge monitoring with customer-facing apps.
- Technician skill shortages:High-voltage battery diagnostics and repair capabilities lag fleet electrification timelines across England's regional depot networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Car Rental Market |
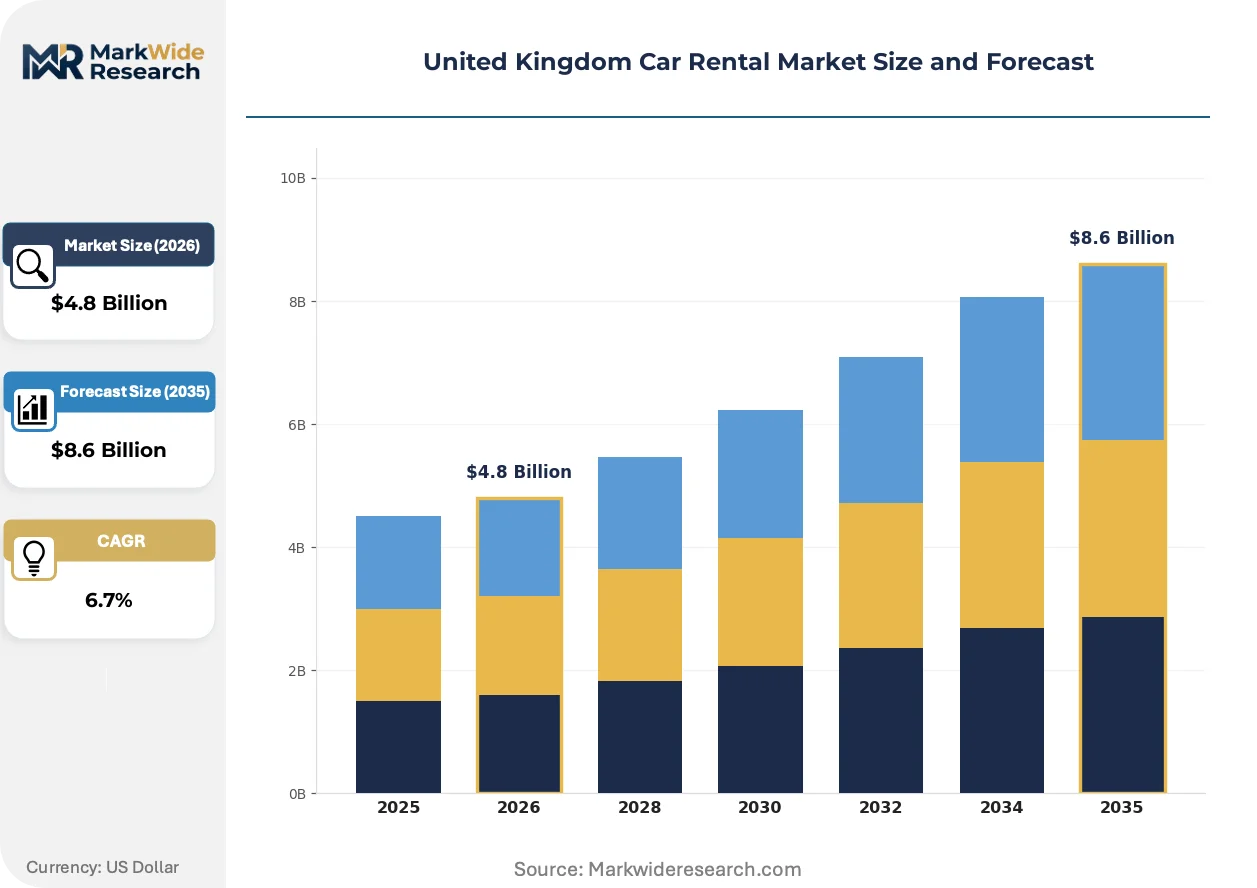
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Customer Type: Leisure, Business, Government, Educational Vehicle Type: Sedan, SUV, Hatchback, Luxury Rental Duration: Short-term, Long-term, Weekly, Monthly Booking Channel: Online, Mobile App, Travel Agency, Walk-in |
| Companies Covered | Lex Autolease, Enterprise Rent-A-Car UK, ZIGUP, Europcar Mobility Group, The Hertz Corporation, Arval, Avis UK, SIXT SE, Northgate, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Car Rental Market Evolving Landscape
Digital fleet management platforms and connected vehicle telemetry are compressing operational decision cycles while regulatory pressure forces asset reconfiguration at unprecedented speed.
Telematics-enabled predictive maintenance is overtaking scheduled service intervals in fleet operations. Large rental operators deploy real-time diagnostic feeds to preempt component failures before customer pickup. This capability is compressing vehicle downtime and extending utilization rates toward eighty percent targets.
The UK's ZEV mandate imposes escalating zero-emission sales quotas on fleet operators each calendar year. Rental companies must liquidate diesel inventory while securing battery electric vehicle supply from constrained manufacturer allocation pools. Urban depots in Greater London face the steepest compliance compression given congestion charge zone access requirements.
Corporate travel managers are consolidating vendor relationships around bundled mobility-as-a-service contracts. Traditional daily rental transactions lose share to integrated subscriptions covering vehicles, insurance, and maintenance in single monthly fees. This pattern concentrates in London's financial services sector where procurement teams prioritize budget predictability over per-trip flexibility.
United Kingdom Car Rental Market Segmentation
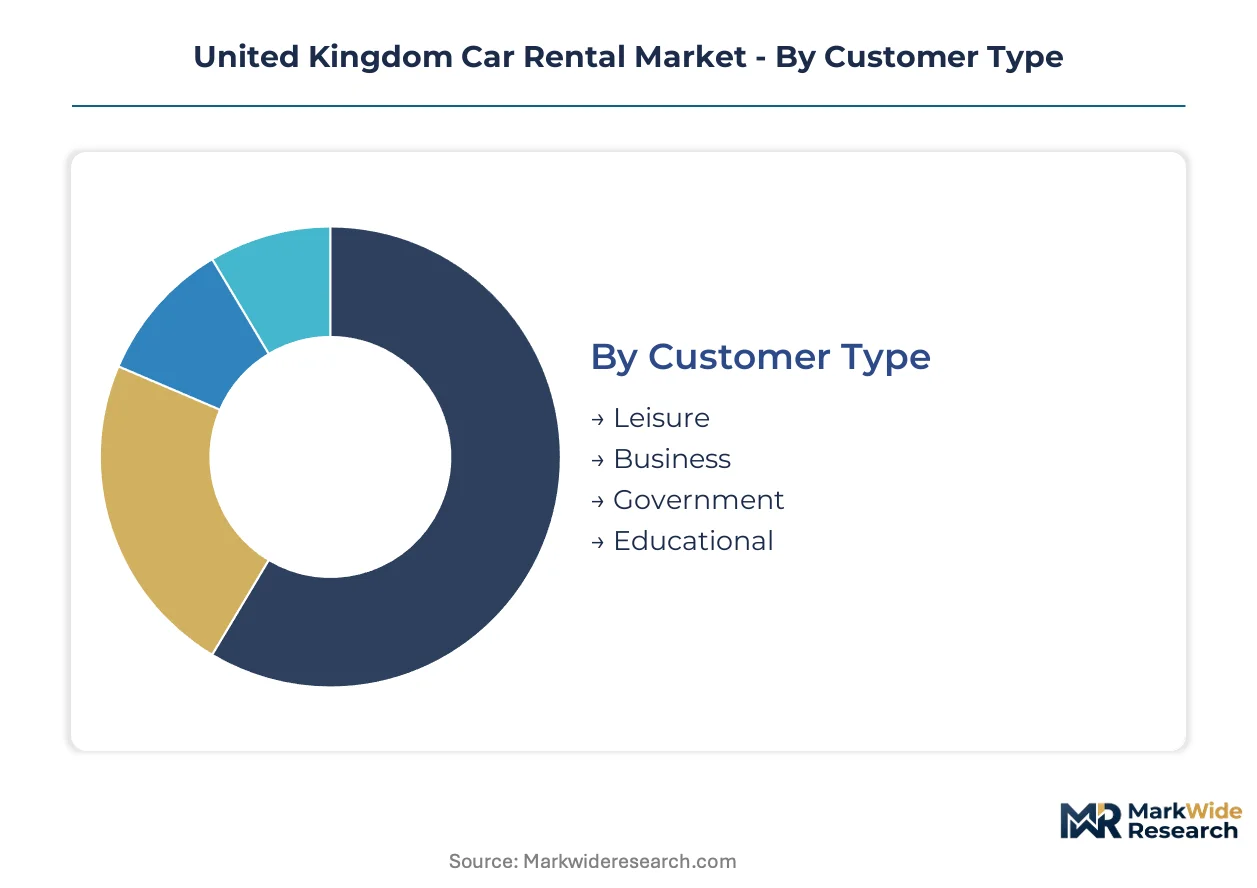
Fleet composition and contract structures vary sharply across customer profiles in the United Kingdom car rental market. Operators configure depreciation schedules, insurance bundles, and charging infrastructure investments differently for each segment cluster.
Customer Type:
Capital intensity escalates from leisure through government segments, with business and educational contracts demanding specialized fleet management platforms and negotiated rate frameworks.
- Leisure:Individual travelers booking through digital channels drive transaction volume but generate lower per-rental margins. Demand concentrates in Greater London and Edinburgh airport corridors during peak tourism windows, with operators managing seasonal utilization swings through dynamic pricing algorithms.
- Business:Corporate travel managers negotiate master service agreements covering airport transfers, intercity rail connections, and extended urban assignments. The West Midlands manufacturing belt and London's Square Mile generate concentrated contract value, with procurement teams prioritizing carbon reporting compliance under the UK's ZEV mandate.
- Government:Central and local authority contracts require certified supplier status and audited sustainability disclosures. Fleet allocations span civil service pool vehicles and emergency service rapid-response units.
- Educational:University and college procurement offices source student mobility packages and research fieldwork transport. Seasonal concentration aligns with academic calendars.
Leisure absorbs the bulk of installed capacity; business is expanding most quickly.
Vehicle Type:
Unit economics diverge dramatically across body styles, with luxury and electric SUV segments carrying steepest acquisition costs but commanding premium rate structures.
- Sedan:Standard four-door configurations dominate corporate fleet rotations and government pool vehicle specifications. ICE sedan residual values face accelerated compression ahead of the 2030 phase-out deadline.
- SUV:Crossover and full-size utility vehicles capture family leisure demand and executive transport contracts. Battery electric SUV availability remains constrained by manufacturer allocation pools, creating wait-list dynamics at Heathrow and Gatwick depots.
- Hatchback:Compact urban runabouts anchor city-center car-sharing integrations with Transport for London. Lower capital requirements support rapid fleet turnover and subscription model experimentation.
- Luxury:Premium marques serve inbound business travelers and high-net-worth leisure segments. Narrow demand windows and elevated insurance surcharges compress utilization targets.
Sedan retains the largest installed base; SUV is climbing the fastest.
Rental Duration:
Contract length directly determines working capital intensity, with monthly structures tying up assets longest but generating predictable revenue streams.
- Short-term:Daily and weekend rentals maximize asset turnover but require dense depot networks and rapid vehicle preparation cycles. Airport locations in Manchester and Birmingham capture inbound volume.
- Long-term:Multi-month contracts support SME fleet outsourcing and temporary workforce mobility. Scotland's underpenetrated Edinburgh-Glasgow corridor presents expansion terrain.
- Weekly:Seven-day packages bridge leisure and business use cases, with pricing calibrated against rail season ticket economics.
- Monthly:Subscription-structured monthly access replaces fixed-term leases for corporate procurement teams prioritizing budget predictability over ownership.
Short-term dominates transaction volume; monthly is gaining share fastest.
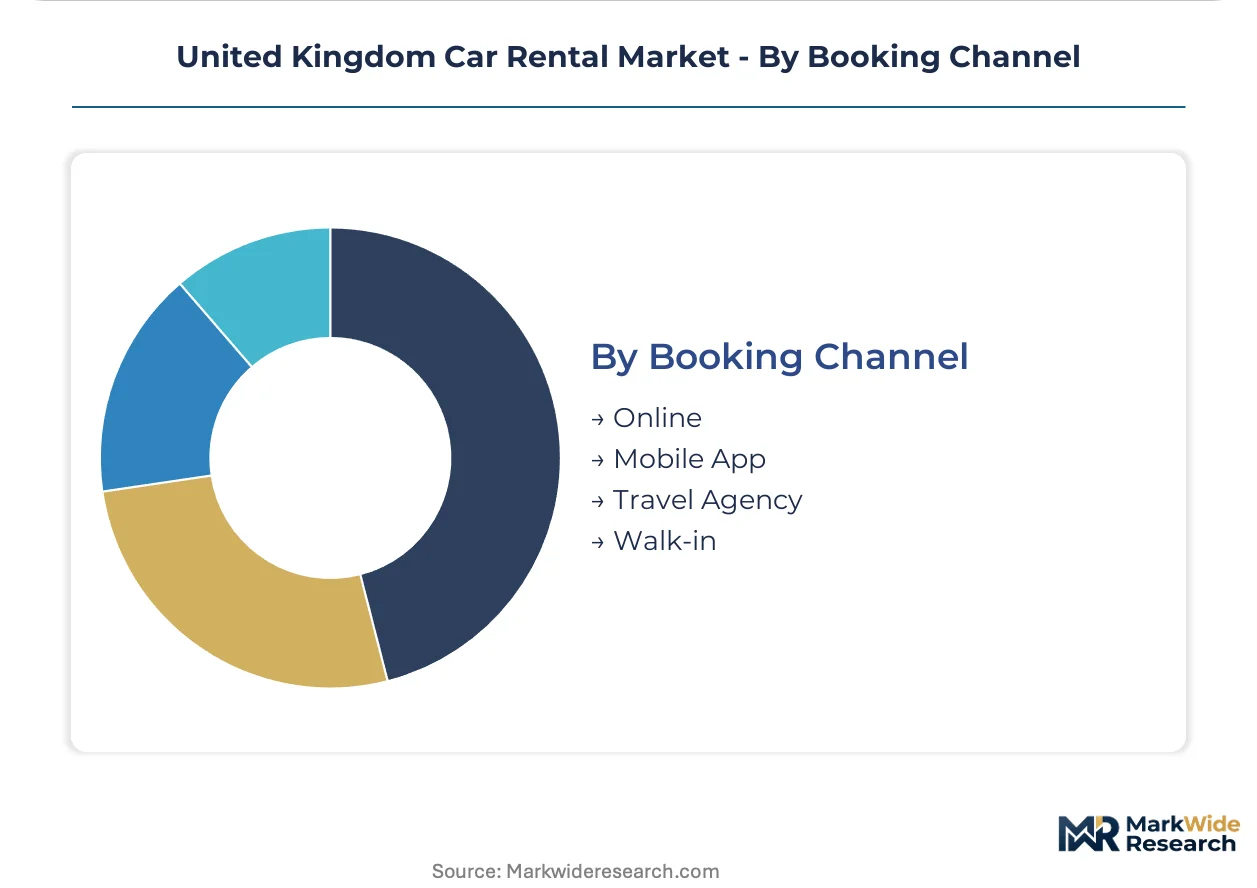
Booking Channel:
Digital infrastructure investment requirements scale from walk-in through mobile app channels, with platform development costs concentrated in online and app segments.
- Online:Web-based reservation engines integrate comparison tools and loyalty program management. Corporate travel management systems feed directly into operator booking APIs.
- Mobile App:Smartphone-native platforms support contactless pickup, real-time vehicle state-of-charge display, and subscription management. Young driver segments show highest app adoption rates.
- Travel Agency:Consolidated bookings through business travel management companies and tour operators generate block allocations with negotiated cancellation terms.
- Walk-in:Counter transactions persist at rail-interchange locations and emergency replacement scenarios, requiring staffed presence despite lower conversion efficiency.
Online captures the majority of reservation volume; mobile app shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise Zones in England's West Midlands and Greater Manchester accelerate fleet operator concentration through business rate relief and simplified planning permissions for depot electrification.
Greater London
Heathrow and Gatwick airports generate dense pickup node demand from inbound business travelers. Transport for London's congestion charge zone and Ultra Low Emission Zone regulations force rapid battery electric vehicle fleet turnover. Fleet operators concentrate depot investments in Park Royal and Croydon industrial estates to access charging infrastructure grants.
West Midlands
Birmingham New Street station anchors rail-air intermodality corridors linking Manchester and London. The region's automotive manufacturing heritage supports technician training pipelines for high-voltage battery diagnostics. Coventry and Solihull host expanding SME fleet outsourcing contracts as manufacturers substitute owned vehicles for flexible rental structures.
North England
Manchester Airport and Leeds Bradford corridors present underpenetrated growth terrain for long-term rental expansion. Grid connection approval delays in Greater Manchester conurbations constrain rapid depot electrification timelines. Liverpool's port logistics cluster generates commercial vehicle demand from freight forwarding operators.
Scotland
Edinburgh and Glasgow airport corridors remain underpenetrated relative to England's density benchmarks. The Scottish Government's zero-emission vehicle funding schemes accelerate public sector fleet transitions. Aberdeen's energy sector corporate travel budgets sustain premium vehicle demand despite North Sea transition headwinds.
Wales
Cardiff and Swansea urban agglomerations concentrate leisure rental demand during peak tourism windows. Welsh Government procurement frameworks require certified supplier status for civil service vehicle pools. The M4 corridor connects Bristol-South Wales logistics demand with England's depot networks.
United Kingdom Car Rental Market Competitive Landscape
Top-tier vendors anchor airport and urban center positions, while mid-tier specialists occupy regional SME outsourcing niches. The market structure consolidates around three to four national operators with dense branch networks, supplemented by fleet leasing incumbents pivoting into short-term rental. Strategic archetypes include airport-dominant volume players, urban car-sharing platform integrators, and premium electric vehicle differentiators. Competitive moves concentrate on charging infrastructure partnerships and subscription model pilots replacing fixed-term corporate leases.
Within the premium-tier vector, SIXT SE occupies a position exemplifying electric vehicle availability strategies in central London zones. Enterprise Rent-A-Car UK and Europcar Mobility Group represent contrasting archetypes: the former anchors airport branch density at Heathrow and Gatwick, while the latter exemplifies municipal mobility platform integrations with Transport for London partnerships. These three operators illustrate how geographic specialization and regulatory compliance shape competitive positioning under the UK's ZEV mandate.
| Leading Market Players |
|---|
| Lex Autolease |
| Enterprise Rent-A-Car UK |
| ZIGUP |
| Europcar Mobility Group |
| The Hertz Corporation |
| Arval |
| Avis UK |
| SIXT SE |
| Northgate |
| Others |
Value Network & Pricing Analysis
Residual value indices for diesel fleet assets cascade through UK rental pricing tiers, compressing daily rates on ICE inventory while elevating battery electric vehicle premiums. Fleet operators pass accelerated depreciation curves into short-term rental structures, with subscription models absorbing residual risk through fixed monthly fees.
Pricing Analysis
Short lead-time bookings at Heathrow and Gatwick terminals command rate premiums against spot inventory liquidated through mobile app channels. Three-tier pricing structure across premium electric, standard hybrid, and economy ICE levels segments corporate procurement from leisure price sensitivity. Pricing pressure stems from diesel residual value collapse ahead of the 2030 phase-out deadline. SME fleet outsourcing contracts show highest price sensitivity; luxury inbound segments absorb premium electric vehicle surcharges without volume erosion.
Supply Chain Analysis
Technician availability constraints across England's West Midlands and Greater Manchester conurbations throttle depot electrification timelines. Vehicle supply concentrates in Germany, South Korea, and Japan through OEM allocation pools constrained by battery electric vehicle production capacity. Lithium-ion battery cells, semiconductor components, and high-voltage charging hardware anchor fleet procurement dependencies. Single-source vulnerability runs through Tesla and BYD allocation queues for UK-market electric SUVs. Distribution runs through airport branch networks and urban car-sharing platform integrations with Transport for London.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UK car rental market sits in a propulsion-technology transition phase, with battery electric vehicle infrastructure displacing diesel fleet economics. Legacy ICE assets face accelerated obsolescence curves while charging network density determines competitive positioning.
For Market Incumbents: Anticipate residual value compression on diesel inventory by accelerating subscription model pilots that transfer depreciation risk to corporate customers. Secure charging infrastructure partnerships in Greater London congestion charge zones to defend market position against electric-native entrants. Prioritize technician certification investments in high-voltage battery diagnostics across West Midlands depot networks. For New Entrants and Emerging Players: Mobile app-native reservation platforms offer the lowest customer acquisition cost route into underpenetrated Scotland corridors around Edinburgh and Glasgow airports. Target SME fleet outsourcing contracts in Birmingham manufacturing belt where incumbent service gaps persist. Deploy car-sharing integrations with municipal mobility platforms as primary go-to-market wedge. For Investors and Strategic Acquirers: Distressed-cycle entries favor fleet-leasing incumbents with captive maintenance capabilities in England's regional industrial estates. Long-term viability hinges on electric vehicle transition execution speed rather than current ICE fleet scale. Monitor Transport for London parking bay allocation announcements as inflection signal for urban market access.| Strategic Initiative | Industry Significance |
|---|---|
| Charging Infrastructure Partnership | Secures dedicated depot electrification capacity ahead of grid connection queues in Greater Manchester. |
| Subscription Model Pilot | Transfers residual value risk to corporate procurement teams through fixed monthly mobility fees. |
| Technician Certification Program | Builds high-voltage battery diagnostic capability ahead of fleet electrification timelines. |
| Transport for London Integration | Opens dedicated parking bay allocations through municipal mobility platform partnerships. |
| Scottish Airport Expansion | Captures underpenetrated Edinburgh-Glasgow corridor demand with lower competitive density. |
Research Methodology
Multi-period observation of fleet utilization rates, residual value curves, and charging infrastructure deployment anchored the trend analysis, supplemented by interviews with rental fleet managers, corporate travel procurement officers, Transport for London mobility planners, and automotive OEM allocation specialists. Secondary validation drew from Driver and Vehicle Licensing Agency licensing records, Office of Rail and Road transport market monitoring, vehicle registration databases, and customs trade flow data. Bottom-up depot-level capacity modeling triangulated against top-down market size estimates.
Segment-weighting across customer type, vehicle propulsion architecture, rental duration structure, and booking channel distribution shaped volume and value projections across the analysis window. CAGRs derived from regression analysis against macroeconomic drivers and regulatory compliance timelines. Electric vehicle adoption curves and charging infrastructure build-out schedules served as primary forecast sensitivity inputs.
The model holds under stable ZEV mandate enforcement and grid connection approval timelines; deviation in ICE phase-out acceleration or lithium supply constraints would shift fleet composition assumptions. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation Services
Malaysia Car Rental Market
Transportation Services
Third Party Logistics Services Market
Transportation Services
Multispace Parking Meter Market
Transportation Services
Europe Vehicle Rental Market
Transportation Services
Philippines Car Rental Market
Transportation Services
Truck Sharing Market
Transportation Services
MUV Rental Market
Transportation Services
Germany Car Rental Market
Transportation Services
Two Wheeler Rental Market
Transportation Services
Ride-Hailing Service Market
Transportation Services
Sanitation Vehicle Market
Transportation Services
Global Moto Taxi Service Market
Transportation Services
Truck Rental Market
Transportation Services
Full-Service Carrier Market
Transportation Services
Poland Car Rental Market
Transportation Services
Latin America Tourism Vehicle Rental Market