
 Fleet Management Consulting Service Market | 2026-2036
Fleet Management Consulting Service Market Size, Share, and Industry Trends Forecast 2026-2036
Fleet Management Consulting Service Market Insights
Modular service bundling is expanding across the fleet consulting landscape, as buyers demand flexible combinations of telematics integration, compliance advisory, and driver safety programs rather than monolithic engagements. Samsara leverages its IoT platform ecosystem to anchor technology implementation consulting for enterprise logistics clients. Geotab competes through open-architecture data analytics that sustain long-term retainer relationships with mixed-fleet operators. Verizon Connect dominates North American channel control, extending its consulting footprint through dealer and OEM partnerships.
Fleet management consulting services encompass advisory engagements that optimize vehicle acquisition, maintenance scheduling, regulatory compliance, and total cost of ownership through data-driven operational frameworks; these services typically integrate telematics feeds, fuel analytics, and driver behavior scoring to reduce per-mile expenditure and liability exposure. Operational consulting leads engagement volume among service types, as fleet managers prioritize route optimization and asset utilization over strategic restructuring. Technology implementation represents the fastest-growing segment, driven by telematics migration and electrification readiness assessments. Compliance advisory commands premium pricing, particularly for clients navigating multi-jurisdictional hours-of-service and emissions rules.
The US DOT, EPA, and FMCSA collectively shape demand through emissions mandates, electronic logging device enforcement, and safety scoring systems that compel outsourced regulatory expertise. The EU Green Deal and its Fit for 55 package extend this pressure across European fleet operators, forcing carbon accounting and alternative-fuel transition planning into consulting scopes. Stakeholders must monitor the divergence between federal and state-level zero-emission vehicle deadlines, as fragmented compliance timelines will determine which advisory practices capture multi-year outsourcing contracts.
Market Dynamics
Electrification readiness assessments are compressing traditional consulting engagement timelines as fleet operators face accelerated zero-emission vehicle mandates from the EPA and EU Green Deal simultaneously.
Growth Catalysts
- EPA Phase 3 Standards:Heavy-duty fleet operators in the United States require specialized advisory to model total cost of ownership for electric transition pathways and charging infrastructure deployment.
- Last-mile logistics densification:E-commerce fulfillment networks in Germany are driving demand for route optimization consulting that integrates real-time telematics with dynamic delivery scheduling.
- Telematics platform convergence:Unified data lakes combining fuel analytics, driver behavior scoring, and predictive maintenance alerts are expanding retainer-based advisory relationships.
Market Restraints
- Specialized talent scarcity:The shallow pool of consultants possessing dual expertise in automotive engineering and data science limits service expansion velocity.
- Input cost volatility:Fluctuations in lithium and semiconductor pricing distort electric vehicle total cost of ownership models that underpin electrification consulting engagements.
- Regulatory fragmentation:Divergent state-level zero-emission vehicle deadlines across California, New York, and Texas create compliance complexity that extends project timelines.
Strategic Opportunities
- India commercial fleet modernization:The country's logistics sector underutilizes predictive maintenance advisory, creating white space for telematics-integrated consulting bundles.
- CSRD-aligned carbon accounting:European sustainability reporting mandates are pulling fleet emissions verification and offset strategy into recurring advisory scopes.
- AI-augmented route optimization:Machine learning convergence with legacy telematics platforms enables premium pricing for dynamic dispatch consulting services.
Industry Challenges
- Legacy system integration friction:Fleet operators running mixed-age vehicle pools struggle to normalize data feeds from incompatible OEM telematics into unified analytics frameworks.
- Certification timeline compression:Accelerated EU Green Deal compliance deadlines strain consultant capacity to deliver validated electrification roadmaps within contracted windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fleet Management Consulting Service Market |
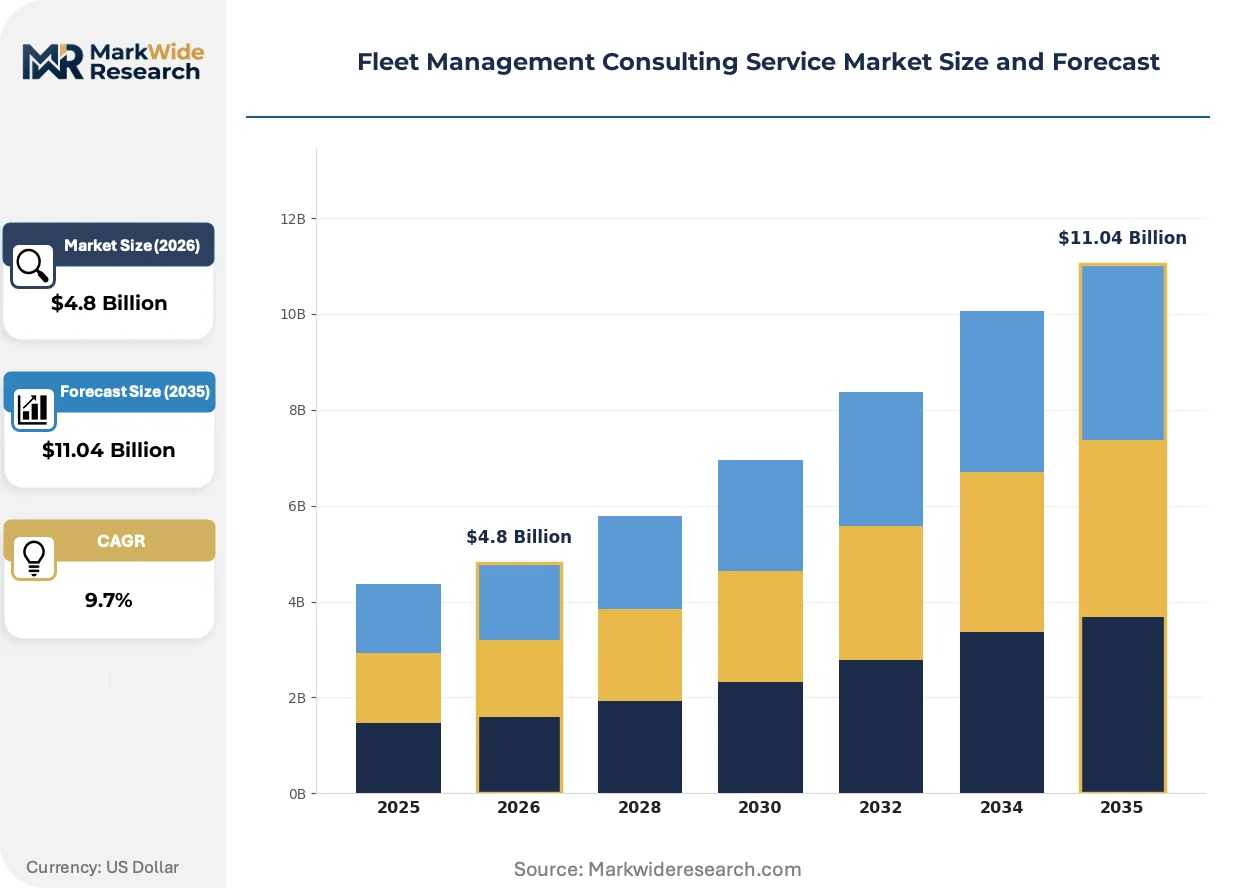
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Operational Consulting, Strategy Development, Technology Implementation, Compliance Advisory Client Type: Commercial Fleets, Government Agencies, Non-Profit Organizations, Logistics Providers Delivery Model: On-site Consulting, Remote Advisory, Workshops, Training Sessions Engagement Type: Project-Based, Retainer, Ad-Hoc Support, Outsourced Services |
| Companies Covered | Verizon Connect, Lytx, Samsara, Teletrac Navman, Omnitracs, Geotab, Fleetio, Azuga, Motive, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fleet Management Consulting Service Market Trends and Innovations
Battery-electric powertrain advisory is displacing diesel-centric consulting methodologies across enterprise fleet engagements. This shift is restructuring service bundling, talent recruitment, and technology partnership strategies simultaneously.
Telematics-integrated electrification planning is electrifying traditional fleet consulting workflows. Advanced battery degradation modeling and charging infrastructure siting algorithms now anchor technology implementation engagements. Logistics operators with mixed heavy-duty and medium-duty portfolios are adopting these tools at the fastest pace. The structural consequence is compressing project timelines from twelve-month strategic roadmaps to six-month operational deployment sprints.
The EU Green Deal's Fit for 55 package is mandating carbon intensity disclosures for commercial transport operators above fifty vehicle thresholds. This regulation forces alternative-fuel transition planning into standard consulting scopes rather than premium add-ons. German and Dutch fleet operators face the earliest compliance deadlines and are outsourcing entire sustainability functions to specialized advisory practices.
Subscription-based advisory retainers are displacing project-based engagements in the mid-market segment. Fleet operators with two hundred to one thousand vehicles prefer fixed monthly fees covering ongoing route optimization, regulatory monitoring, and driver safety program management. This procurement evolution is most visible among third-party logistics providers in the United States seeking predictable operating expenditure structures.
Fleet Management Consulting Service Market Segmentation
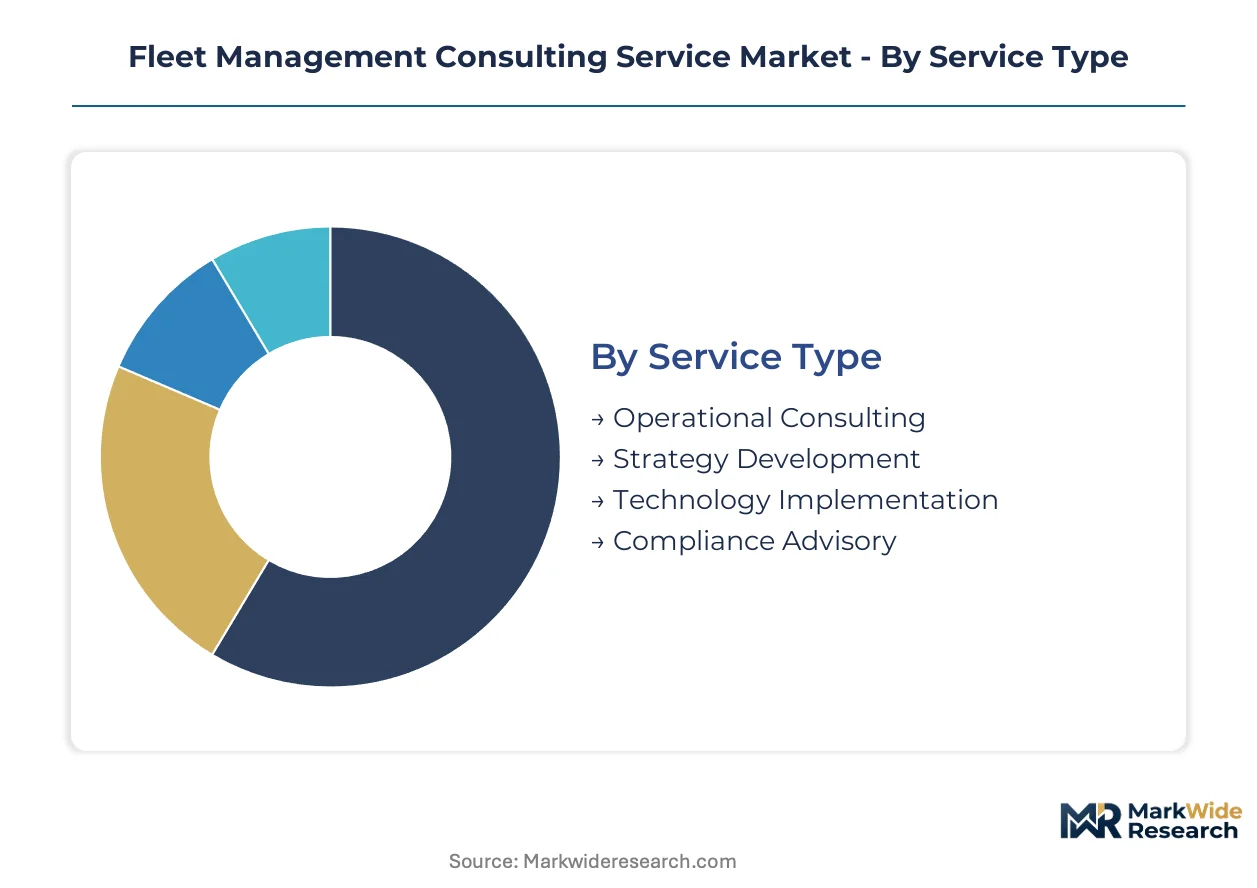
Fleet management consulting services fragment across service modalities, client categories, and contractual structures. These distinctions determine pricing architecture, talent deployment, and technology integration requirements for advisory practices.
Service Type:
Advisory practices structure their upgrade cycles around vehicle replacement timelines and regulatory milestone dates. Service packaging aligns with fleet turnover schedules rather than calendar quarters.
- Operational Consulting:Route optimization, asset utilization analysis, and maintenance scheduling frameworks dominate engagement volume. Logistics providers in Germany deploy these services to compress last-mile delivery costs under EU Green Deal pressure.
- Technology Implementation:Telematics platform migration, charging infrastructure siting, and predictive maintenance system deployment anchor the steepest expansion trajectory. Fleet operators accelerating electrification roadmaps require compressed six-month deployment sprints rather than traditional twelve-month strategic engagements.
- Strategy Development:Long-range fleet composition planning and total cost of ownership modeling for multi-year capital cycles.
- Compliance Advisory:Multi-jurisdictional hours-of-service, emissions standards, and safety scoring system navigation commanding premium pricing.
Volume placements concentrate in Operational Consulting; the faster expansion belongs to Technology Implementation.
Client Type:
Cost tier differentiation separates enterprise-scale engagements from mid-market retainers. Procurement sophistication and compliance exposure drive service bundling decisions.
- Commercial Fleets:Manufacturing, utilities, and service sector operators with captive vehicle pools. These clients prioritize total cost of ownership reduction through predictive maintenance and fuel analytics integration.
- Logistics Providers:Third-party and fourth-party logistics operators managing heterogeneous vehicle assets across multiple shipper contracts. German e-commerce fulfillment networks drive densification consulting demand.
- Government Agencies:Municipal, state, and federal fleets subject to public procurement rules and accelerated zero-emission mandates.
- Non-Profit Organizations:Human services and community transport operators with limited capital access and grant-dependent funding cycles.
Revenue concentration sits with Logistics Providers; margin expansion favors Commercial Fleets with multi-year retainer relationships.
Delivery Model:
Application context determines physical presence requirements. High-stakes technology deployments demand on-site validation; routine monitoring shifts to remote delivery.
- On-site Consulting:Physical presence for fleet audits, driver training, and infrastructure assessments. Electrification readiness evaluations require charging site surveys and grid interconnection analysis.
- Remote Advisory:Cloud-based analytics review, regulatory update dissemination, and virtual troubleshooting. Telematics data lakes enable continuous monitoring without travel overhead.
- Workshops:Cohort-based training for fleet managers on compliance changes or technology platform transitions.
- Training Sessions:Driver safety certification and behavior modification programs delivered through blended learning formats.
Remote Advisory captures the highest volume growth; On-site Consulting retains pricing premiums for complex electrification deployments.
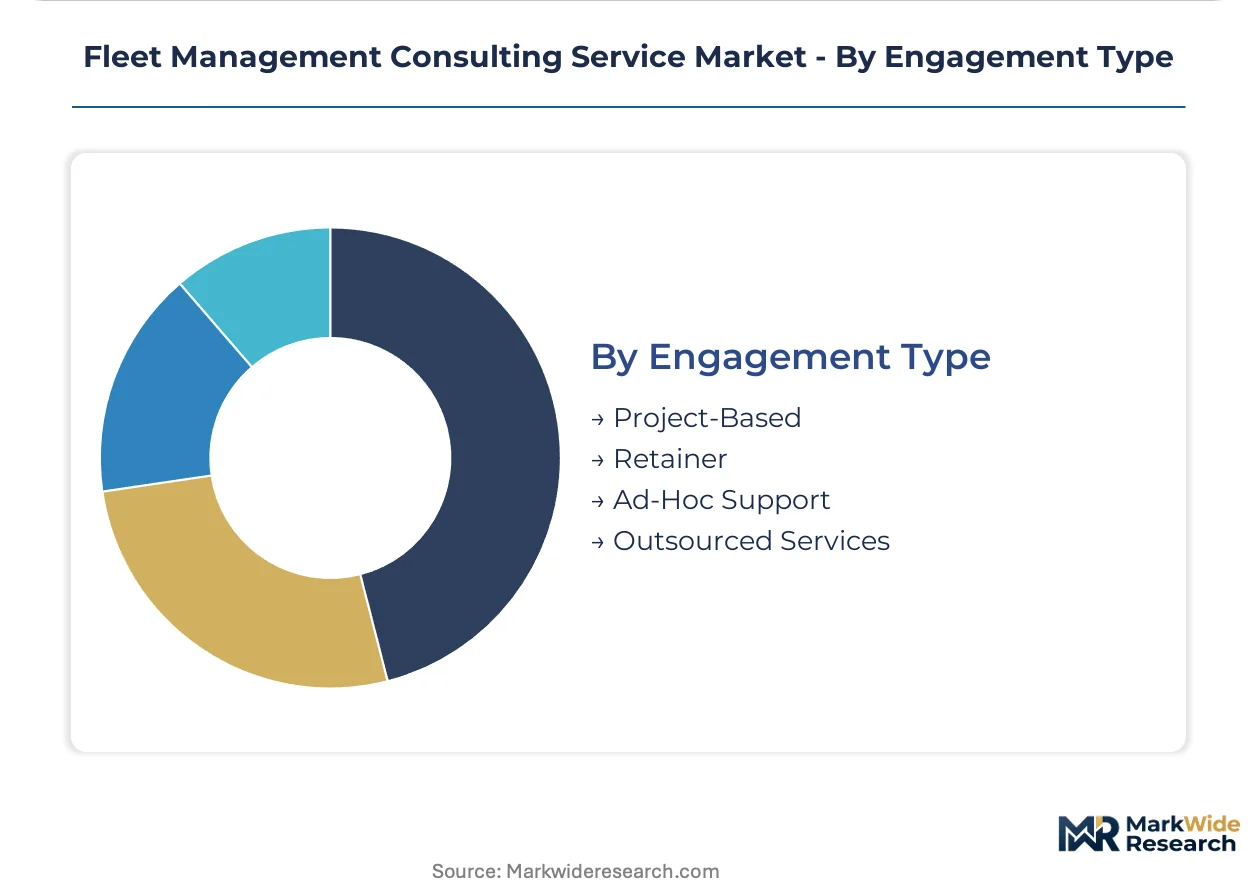
Engagement Type:
Customer maturity and capital availability shape contract structure selection. Predictable operational expenditure preferences displace capital-intensive project commitments.
- Project-Based:Discrete engagements with defined deliverables and termination dates. Strategy roadmaps and technology implementations typically follow this structure.
- Retainer:Fixed monthly fees covering ongoing route optimization, regulatory monitoring, and driver safety program management. US third-party logistics providers with two hundred to one thousand vehicles prefer this procurement model.
- Ad-Hoc Support:Incident-driven consulting for regulatory violations, accident investigations, or emergency route restructuring.
- Outsourced Services:Comprehensive fleet function delegation including procurement, maintenance management, and compliance administration.
Retainer arrangements are displacing Project-Based contracts in the mid-market segment; Outsourced Services remain concentrated among government and large enterprise accounts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consulting service consumption concentrates in mature fleet markets with stringent regulatory frameworks, while advisory talent production clusters near automotive engineering centers and telematics development hubs. The United States generates the largest absolute revenue for fleet consulting, though Germany and the Netherlands exhibit higher per-fleet spending intensity on compliance advisory.
United States
Heavy-duty fleet operators drive demand for electrification readiness assessments under EPA Phase 3 greenhouse gas standards. The FMCSA enforces electronic logging device compliance that compels outsourced regulatory expertise. California's Central Valley logistics corridor anchors technology implementation consulting for mixed-fleet operators migrating to unified telematics platforms.
Germany
Commercial fleets with above-fifty-vehicle thresholds outsource entire sustainability functions to meet EU Green Deal Fit for 55 deadlines. The KBA administers type-approval processes that delay electric vehicle certification timelines. The Rhine-Ruhr industrial belt concentrates last-mile densification consulting for e-commerce fulfillment networks.
Netherlands
Third-party logistics providers with two hundred to one thousand vehicles prefer subscription-based advisory retainers for predictable operating expenditure structures. The national environmental agency enforces zero-emission zones in Amsterdam and Rotterdam that accelerate charging infrastructure siting demand. The Randstad megalopolis hosts specialized advisory practices serving Benelux cross-border fleet operations.
India
Commercial fleet modernization lags in predictive maintenance advisory, creating white space for telematics-integrated consulting bundles. The Ministry of Road Transport and Highways mandates vehicle scrappage policies that force fleet composition restructuring. Maharashtra's Mumbai-Pune logistics corridor attracts initial technology implementation engagements from global advisory practices.
United Kingdom
Post-Brexit regulatory divergence from EU standards compels multi-jurisdictional compliance advisory for cross-border operators. The Driver and Vehicle Standards Agency enforces safety scoring systems that sustain retainer relationships with fleet consultancies. The Midlands manufacturing belt sustains operational consulting demand from captive commercial fleets in automotive supply chains.
Fleet Management Consulting Service Market Competitive Landscape
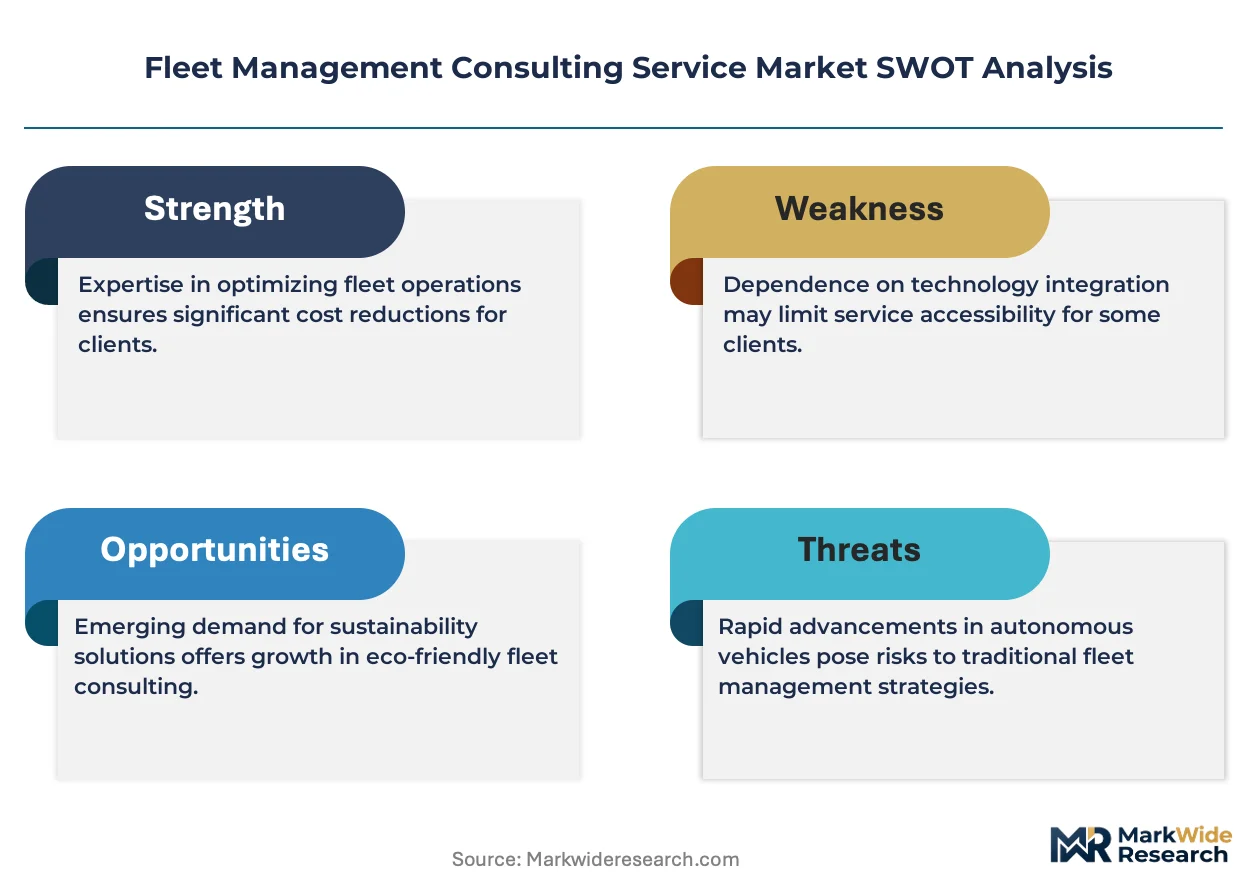
Diversified conglomerates compete with focused pure-play specialists across the fleet consulting landscape, creating a tiered structure where scale-driven platform vendors anchor enterprise relationships and boutique advisors capture premium compliance engagements. The vendor base separates into three strategic archetypes: telematics-native platform extenders, independent data analytics specialists, and regulatory-focused boutique practices. Consolidation pressure operates through strategic partnerships between hardware OEMs and software consultancies, while geographic expansion into underpenetrated Asian markets represents the dominant competitive move.
Among telematics-native platform extenders, Samsara and Geotab exemplify the archetype of IoT-anchored consulting growth, with Verizon Connect occupying a position that represents channel-control dominance through dealer and OEM partnerships. These three entities anchor the competitive landscape by demonstrating how platform ecosystems sustain long-term advisory retainers versus discrete project engagements.
| Leading Market Players |
|---|
| Verizon Connect |
| Lytx |
| Samsara |
| Teletrac Navman |
| Omnitracs |
| Geotab |
| Fleetio |
| Azuga |
| Motive |
| Others |
Pricing and Supply Chain Analysis
EPA Phase 3 greenhouse gas standards gate both qualified advisory talent and premium-tier pricing access, as fleet operators demand electrification readiness assessments that only dual-qualified automotive engineering and data science consultants can deliver. This regulatory filter compresses supply-side capacity while elevating retainer fees for compliance-intensive engagements.
Pricing Analysis
Margin tightening in mid-market retainers reflects the shift from project-based to subscription advisory models among US third-party logistics providers with two hundred to one thousand vehicles. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification depth and telematics integration complexity. Cost-down pressure on operational consulting accelerates because fleet managers prioritize route optimization over strategic restructuring. Government agencies exhibit lowest price sensitivity due to mandated compliance deadlines; non-profit organizations face acute budget constraints.
Supply Chain Analysis
Workforce availability constraints in Germany, the Netherlands, and the United States limit advisory practice expansion velocity. Talent production draws from automotive engineering centers near Stuttgart, Eindhoven, and Detroit, with telematics development hubs in San Francisco and Toronto feeding specialized data science capacity. Supply chain risk centers on single-source vulnerability for battery-electric powertrain advisory expertise. Distribution runs through direct enterprise sales teams, OEM partnerships, and dealer channel networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fleet management consulting sits in a technology-transition phase where battery-electric powertrain advisory displaces diesel-centric methodologies. This substitution restructures service bundling, talent recruitment, and technology partnership strategies simultaneously.
For Market Incumbents: Acquire specialized electrification advisory practices to close capability gaps before EPA Phase 3 and EU Green Deal deadlines compress engagement timelines. Backward integration into charging infrastructure siting algorithms defends margin position against telematics-native platform extenders. Channel control through OEM partnerships remains critical for North American market access. For New Entrants and Emerging Players: Small commercial fleets in India with underutilized predictive maintenance advisory represent the most penetrable white space. Telematics-integrated consulting bundles anchored to vehicle scrappage policy compliance create immediate value propositions. Direct sales to Maharashtra's Mumbai-Pune logistics corridor bypasses entrenched competitor relationships. For Investors and Strategic Acquirers: Accelerated EU Green Deal compliance deadline announcements are the leading indicator that specialized boutique practices will command acquisition premiums. Long-term viability over five-to-ten years hinges on carbon accounting capability depth. Watch for CSRD-aligned sustainability reporting mandate expansions as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Acquisition of Specialist Firm | Electrification advisory boutiques in Germany capture premium pricing under Fit for 55 deadlines. |
| Platform Integration | Telematics data lake convergence sustains long-term retainer relationships with mixed-fleet operators. |
| Geographic Expansion | India's commercial fleet modernization creates white space for predictive maintenance consulting bundles. |
| Strategic Partnership | OEM and dealer channel alliances extend consulting footprint across North American logistics corridors. |
| Product Launch | AI-augmented route optimization tools enable premium pricing for dynamic dispatch advisory services. |
Research Methodology
Multi-period observation of telematics platform migration rates, electrification roadmap adoption curves, and compliance advisory pricing anchored the trend analysis, supplemented by interviews with fleet operations directors, sustainability officers at logistics providers, telematics platform engineers, and regulatory affairs specialists at commercial fleets. Secondary validation drew from EPA enforcement data, EU Green Deal implementation timelines, FMCSA safety scoring system updates, and KBA type-approval processing statistics. Bottom-up service provider revenue aggregation and top-down fleet expenditure modeling enabled triangulation.
Input-output matrix framing structured the forecast framework across service type, client category, delivery model, and engagement structure dimensions throughout the projection horizon. CAGRs were derived from segmented growth rate reconciliation against macro fleet investment cycles. Industry-specific inputs included zero-emission vehicle mandate acceleration curves and telematics platform replacement timelines.
Revisions become necessary when EPA Phase 3 implementation delays, EU Green Deal deadline extensions, or lithium price volatility shocks materialize beyond modeled ranges. Forecasts reflect documented assumptions on regulatory enforcement intensity and fleet capital availability. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation Services
On Street Vehicle Parking Meter Market
Transportation Services
Asia-Pacific Rickshaw Ride Hailing Service Market
Transportation Services
Bike and Scooter Rental Market
Transportation Services
Australia Taxi Market
Transportation Services
India Two-Wheelers Rental Market
Transportation Services
Europe Vehicle Rental Market
Transportation Services
Thailand Car Rental Market
Transportation Services
Latin America Tourism Vehicle Rental Market
Transportation Services
Vacuum Truck Rentals Market
Transportation Services
Indonesia Car Rental Market
Transportation Services
Water Truck Rental Market
Transportation Services
Two Wheeler Rental Market
Transportation Services
Full-Service Carrier Market
Transportation Services
United States Vehicle Rental Market
Transportation Services
Global Garbage Truck Market
Transportation Services
Ride-Hailing Service Market