
 Ride-Hailing Service Market | 2026-2036
Ride-Hailing Service Market Size, Share, and Industry Trends Forecast 2026-2036
Ride-Hailing Service Market Intelligence
The gap between premium chauffeur services and everyday commuter rides is expanding as fleet operators stratify vehicle classes and driver certification tiers to capture divergent willingness-to-pay. Uber Technologies Inc. leverages its global network density to sustain pricing power in dense metropolitan corridors. Lyft Inc. anchors its position through healthcare and airline partnerships that generate predictable trip volumes. Didi Global Inc. dominates its domestic market through in-house mapping and autonomous vehicle R&D pipelines.
Ride-hailing services constitute digitally intermediated transportation networks that match passenger trip requests with available drivers through algorithmic dispatch systems operating on sub-minute response windows. The primary commercial purpose centers on monetizing underutilized vehicle capacity while substituting for personal car ownership and traditional taxi dispatch methods. Pooling services capture the highest trip frequency among price-sensitive commuters, while Luxury segments concentrate margin pools through elevated per-ride yields and lower driver churn. AI Dispatch technology is reshaping fleet efficiency as platforms reduce empty cruising hours and cut passenger wait times through predictive demand clustering.
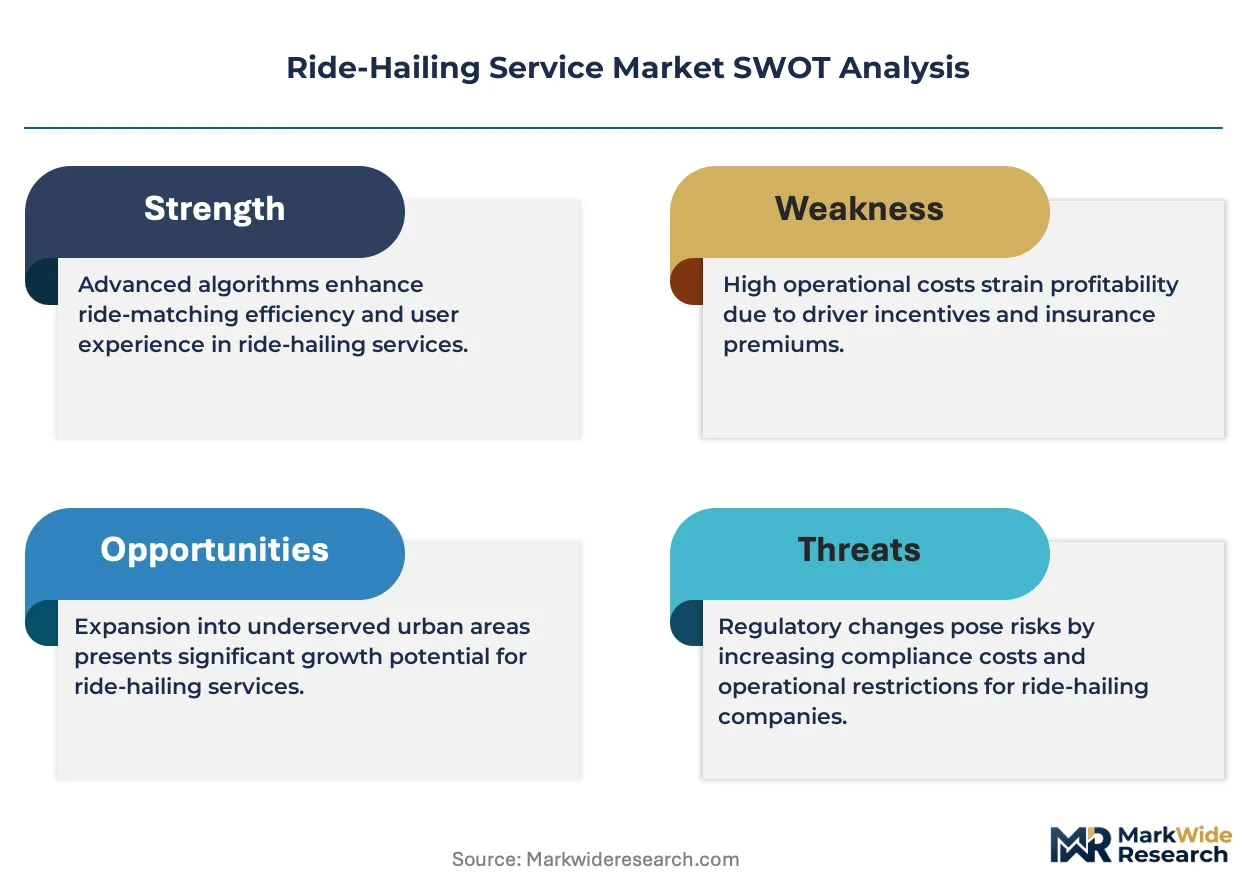
Regulatory scrutiny from the EU's Platform Work Directive, the US Department of Labor's independent contractor tests, and India's Motor Vehicle Aggregator Guidelines is forcing operational recalibration across driver classification, insurance mandates, and fare transparency standards. The US Department of Transportation and state-level public utility commissions shape market access through background check protocols, vehicle inspection regimes, and surge pricing disclosure rules. Stakeholders must monitor how jurisdictional fragmentation in driver employment status creates compliance cost asymmetries that favor platforms with legal resources to navigate multi-regime operations.
Market Dynamics
The EU's Platform Work Directive is forcing platforms to reclassify drivers as employees across member states, compressing margins and accelerating automation investments to offset labor cost inflation.
Growth Catalysts
- Urban Congestion Pricing:Cities like London and Singapore impose vehicle entry fees that push commuters toward shared mobility. Platforms capture this modal shift through subscription commuter passes.
- Healthcare Partnerships:Non-emergency medical transportation contracts with hospital networks generate recurring trip volumes. Insurers reimburse these rides as cost-effective alternatives to ambulance dispatch.
- AI Dispatch Optimization:Predictive demand clustering reduces empty cruising hours. Fleet utilization rates improve as algorithms pre-position vehicles before surge events.
Market Restraints
- Driver Supply Volatility:Fuel price spikes and vehicle maintenance costs erode net earnings. Part-time driver churn accelerates during cost-of-living pressures.
- Insurance Mandate Escalation:Commercial ride-hail coverage requirements in California and New York exceed personal auto premiums by multiples. Small fleet operators exit as compliance costs rise.
- Substitution by Micromobility:E-scooter and bike-share networks capture trips under three kilometers. Urban trip frequency shifts toward these lower-cost alternatives.
Strategic Opportunities
- Autonomous Vehicle Convergence:Robotaxi pilots in Phoenix and San Francisco demonstrate path to driverless unit economics. Regulatory sandbox approvals in Arizona accelerate testing scale.
- Corporate Mobility Budgets:Enterprise travel managers consolidate ground transportation spend under platform contracts. Predictable B2B revenue streams reduce demand volatility.
- India's Motor Vehicle Aggregator Guidelines:Centralized federal framework replaces fragmented state rules. National permit harmonization enables cross-state fleet operations.
Industry Challenges
- Employment Classification Litigation:Multi-jurisdictional legal exposure from driver lawsuits drains capital. Platforms face simultaneous UK employment tribunal actions and US Department of Labor audits.
- Legacy Dispatch System Integration:Traditional taxi cooperatives resist API interoperability. Municipal franchise agreements lock platforms out of airport and transit hub access.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ride-Hailing Service Market |
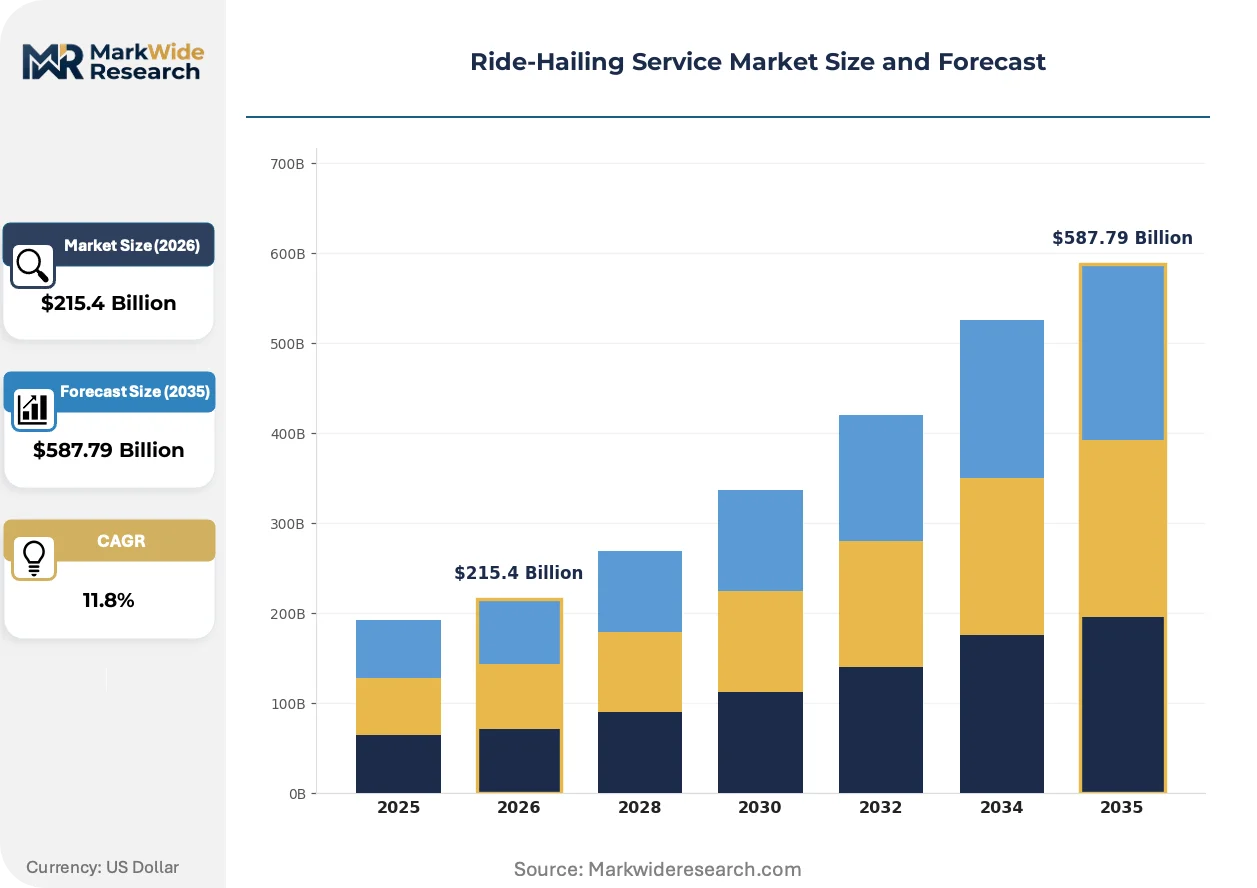
| Market Size in 2026 | $215.4 Billion |
| Market Size in 2035 | $587.79 Billion |
| CAGR (2026 – 2036) | 11.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Private Ride, Pooling, Luxury, Corporate Technology: Mobile App, GPS Tracking, Payment Integration, AI Dispatch End User: Commuters, Tourists, Corporates, Students Pricing Model: Dynamic Pricing, Flat Rate, Subscription, Per-Mile |
| Companies Covered | Uber Technologies Inc., Lyft Inc., Grab Holdings Inc., Bolt Technology OÜ, Didi Global Inc., Ola Electric Mobility Pvt Ltd, Gett, BlaBlaCar, Via Transportation Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ride-Hailing Service Market Strategic Shifts & Innovations
Algorithmic matching and predictive routing are compressing response windows below ninety seconds while regulatory pressure on driver status accelerates capital deployment toward autonomous alternatives.
Autonomous vehicle fleets are automating the most predictable trip corridors. Waymo operates driverless services in Phoenix and San Francisco with expanding geographic coverage. The technology is automating highway and suburban routes first, preserving human drivers for complex urban cores and airport pickups where navigation uncertainty remains elevated.
The EU's Platform Work Directive reclassifies gig workers as employees with minimum wage guarantees and social protections. Platforms face margin compression across Germany, France, and Spain as implementation timelines converge through 2026. Large operators respond by consolidating market share to absorb fixed labor costs while smaller regional apps exit or seek acquisition.
Subscription mobility passes displace per-ride purchasing for frequent commuters. Urban professionals in London and New York lock in monthly caps that guarantee price predictability. Corporate travel managers negotiate enterprise rates that bundle ride-hail with rental car and public transit access, consolidating ground transportation procurement under single-platform contracts.
Ride-Hailing Service Market Segmentation
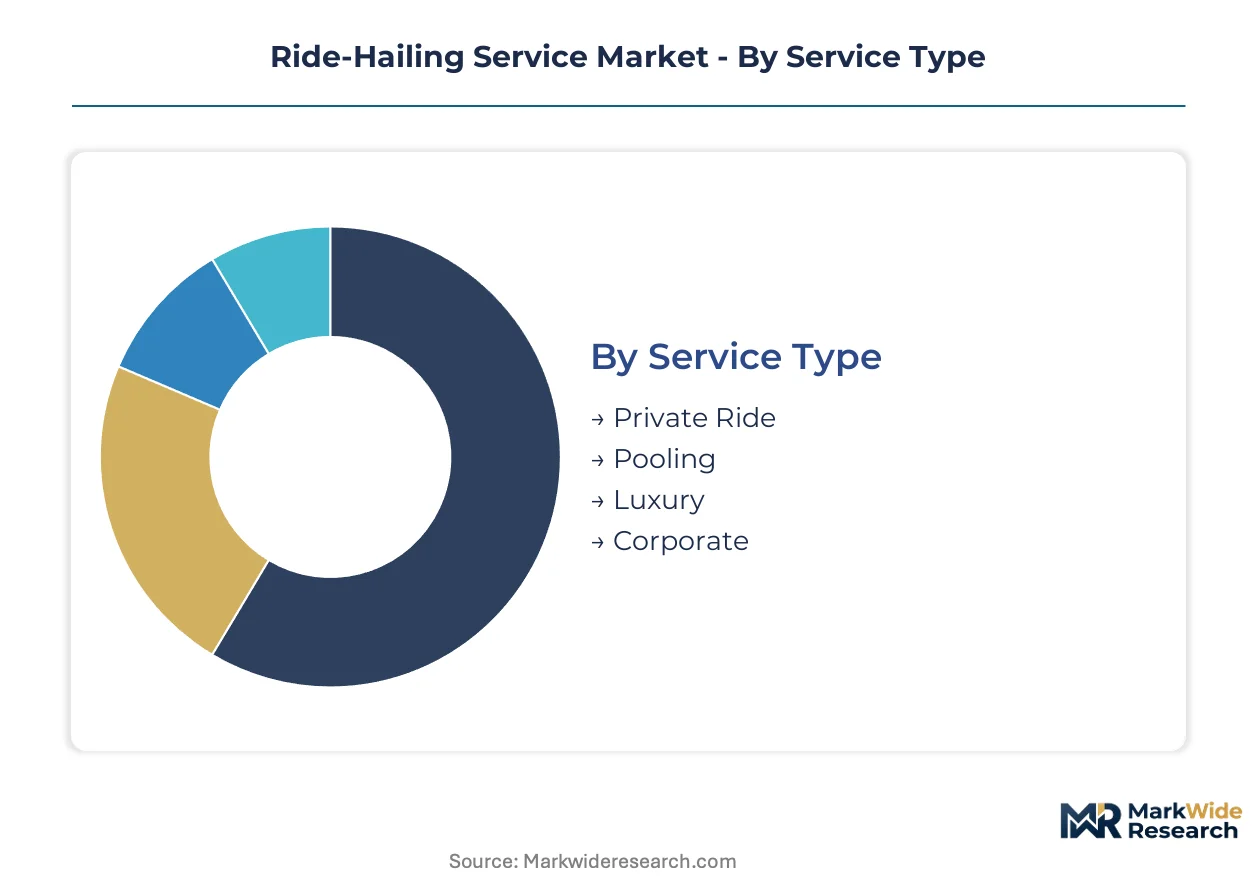
Segmentation in ride-hailing services determines which platforms capture commuter loyalty versus corporate contracts. Service tiers, dispatch technologies, and pricing architectures create distinct margin pools that operators must defend through targeted fleet composition and partnership strategies.
Service Type:
Certification burdens stratify sharply across service tiers, with Luxury segments requiring commercial chauffeur licenses and enhanced vehicle inspection protocols that Pooling services bypass entirely.
- Private Ride:Single-occupancy vehicle dispatch with dedicated driver assignment generates the highest per-trip revenue. Demand concentrates among time-sensitive professionals in dense metropolitan corridors where convenience premiums outweigh cost sensitivity.
- Pooling:Algorithmic co-rider matching reduces per-passenger fares through shared route optimization. This segment captures price-sensitive commuters in high-congestion cities where parking costs and fuel expenses make personal vehicle ownership prohibitive.
- Luxury:Premium vehicle classes with certified professional drivers command elevated fares through service consistency guarantees.
- Corporate:B2B contract structures with centralized billing and expense management integration serve enterprise travel programs.
Leading the category by volume: Pooling. Growing fastest: Corporate.
Technology:
Technology layers determine operational cost structures, with AI Dispatch platforms investing heavily in proprietary algorithm development while Payment Integration providers navigate fragmented financial regulations.
- Mobile App:Consumer-facing booking interfaces with real-time vehicle tracking and fare estimation constitute the primary demand generation channel. Smartphone penetration rates in emerging markets directly correlate with platform adoption velocity.
- AI Dispatch:Predictive demand clustering and route optimization algorithms reduce empty cruising hours while compressing passenger wait times. This technology layer attracts the largest capital deployment as platforms automate toward driverless economics.
- GPS Tracking:Location services enabling real-time vehicle positioning and estimated arrival calculations.
- Payment Integration:Digital wallet connectivity and automated fare settlement systems.
Dominant by deployment scale: Mobile App. Steepest expansion trajectory: AI Dispatch.
End User:
User categories reflect trip frequency patterns, with Commuters generating predictable daily demand while Tourists concentrate in seasonal peaks around transportation hubs and hospitality districts.
- Commuters:Recurring daily travel patterns between residential and employment centers create the most predictable revenue base. Subscription pricing models lock in this segment through monthly caps that reduce fare volatility exposure.
- Corporates:Enterprise travel managers consolidate ground transportation spend under platform contracts with centralized billing and policy compliance tools. This segment delivers the lowest customer acquisition costs through B2B relationship structures.
- Tourists:Intermittent demand concentrated around airports, hotels, and attractions with higher price tolerance.
- Students:Campus-centric demand with elevated price sensitivity and preference for shared mobility options.
Highest trip frequency: Commuters. Fastest account growth: Corporates.
Pricing Model:
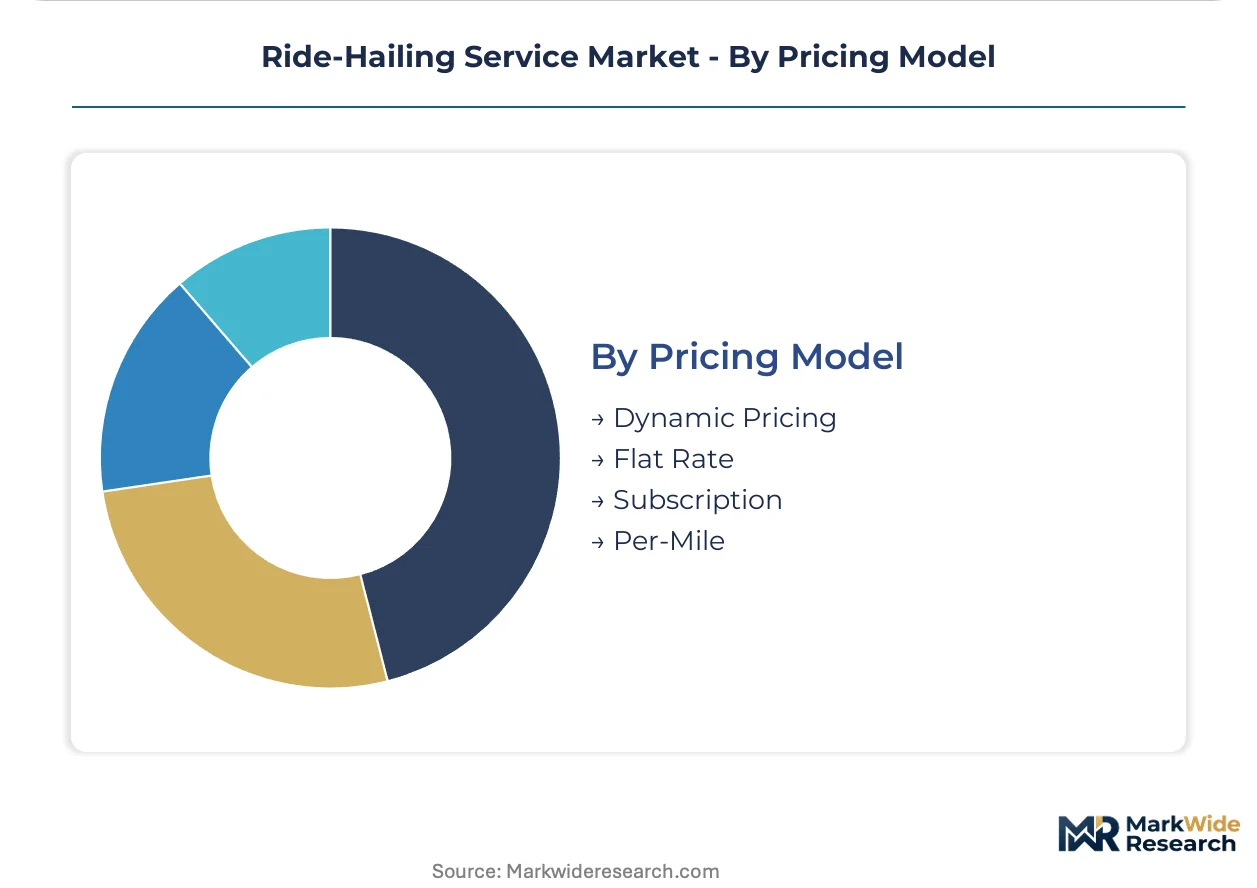
Pricing architectures segment users by risk tolerance, with Dynamic Pricing platforms capturing demand during supply-constrained periods while Subscription models reduce churn through predictability guarantees.
- Dynamic Pricing:Algorithmic fare adjustment responding to real-time supply-demand imbalances maximizes revenue per available vehicle hour. This model concentrates margin capture during peak periods but risks user defection to alternatives during extreme surge events.
- Subscription:Monthly fixed-fee structures with ride quantity caps or discounted per-trip rates generate predictable recurring revenue. Urban professionals in high-cost markets lock in these arrangements to budget transportation expenses.
- Flat Rate:Fixed fares for predefined routes common in airport and intercity corridor services.
- Per-Mile:Distance-based metering aligned with traditional taxi regulatory frameworks.
Widest adoption: Dynamic Pricing. Gaining share fastest: Subscription.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bengaluru and Mumbai generate the densest ride-hailing trip volumes among emerging-market megacities, with smartphone penetration and urban congestion deepening platform dependence across India.
United States
Corporate travel budgets shifting from fleet ownership to on-demand mobility sustain B2B contract growth in Dallas-Fort Worth and Chicago. The Department of Labor's independent contractor tests force operational recalibration on driver classification. Phoenix anchors robotaxi pilot expansion as Waymo scales driverless service coverage.
India
Urban congestion and smartphone penetration deepen platform reliance in Bengaluru and Mumbai among price-sensitive commuters. The Motor Vehicle Aggregator Guidelines replace fragmented state rules with centralized federal oversight. National permit harmonization enables cross-state fleet operations from Delhi-NCR to Hyderabad.
United Kingdom
London's congestion pricing pushes commuters toward shared mobility through subscription passes. The EU Platform Work Directive drives driver reclassification pressure despite post-Brexit regulatory divergence. The capital's black cab cooperatives resist API interoperability at Heathrow and City Airport.
Germany
Enterprise travel managers consolidate ground transportation spend under platform contracts in Berlin and Munich. The Platform Work Directive mandates minimum wage guarantees and social protections for reclassified drivers. The KBA enforces commercial vehicle inspection protocols that stratify service tiers.
Brazil
São Paulo's informal transit gaps and parking scarcity drive adoption among middle-class commuters seeking alternatives to personal vehicle ownership. ANVISA coordinates with municipal regulators on driver background check standards. The city's favela peripheries remain underserved due to safety-related dispatch algorithm exclusions.
Ride-Hailing Service Market Key Industry Players
Capital-heavy fleet operators compete with asset-light platform intermediaries for margin capture in dense metropolitan corridors. The vendor base clusters around three strategic tiers: global network density players, regional specialists with local regulatory fluency, and autonomous vehicle developers seeking driverless unit economics. Consolidation accelerates as labor cost inflation from employment reclassification forces smaller regional apps toward acquisition or exit. Vertical integration into mapping and payment infrastructure separates scaled operators from pure dispatch intermediaries.
Among Silicon Valley-anchored technology platforms, Uber Technologies Inc. and Lyft Inc. occupy positions exemplifying network-density and partnership-anchored archetypes respectively. Didi Global Inc. represents the vertically integrated domestic champion model with in-house R&D pipelines. Bolt Technology OÜ and Grab Holdings Inc. exemplify regional specialists that built regulatory fluency across European and Southeast Asian markets before global expansion.
| Leading Market Players |
|---|
| Uber Technologies Inc. |
| Lyft Inc. |
| Grab Holdings Inc. |
| Bolt Technology OÜ |
| Didi Global Inc. |
| Ola Electric Mobility Pvt Ltd |
| Gett |
| BlaBlaCar |
| Via Transportation Inc. |
| Others |
Cost & Logistics Intelligence
Driver labor costs cascade through service tiers as platforms absorb EU Platform Work Directive mandates, compressing margins in Pooling segments while Luxury tiers pass elevated wage floors to corporate accounts through contract renegotiation. Fuel price volatility and commercial insurance premiums in California and New York further stratify pricing power across fleet operators with captive vehicle supply versus asset-light intermediaries.
Pricing Analysis
Yield-per-available-driver-hour anchors platform pricing architecture, with AI Dispatch optimization compressing empty cruising time to sustain fare competitiveness. Three-tier pricing structure across premium, standard, and economy levels separates certified chauffeur services from commuter Pooling and non-emergency medical transport contracts. Cost compression in Pooling segments is intensifying because driver reclassification mandates in Germany, France, and Spain inflate fixed labor obligations. Corporate travel managers demonstrate lowest price sensitivity through enterprise subscription contracts, while student and tourist segments defect to micromobility alternatives during surge events.
Supply Chain Analysis
Direct-to-fleet channels handle hyperscale vehicle procurement for global network density players, while regional specialists rely on third-party driver-owned vehicle marketplaces. Vehicle manufacturing concentrates in China, Japan, and Germany for electric fleet transitions, with semiconductor components for autonomous systems drawing from Taiwan and South Korea. Lithium-ion battery cell supply rests on South Korean and Chinese cathode production, creating single-source vulnerability for robotaxi pilot expansion. Distribution runs through municipal permit regimes that gate airport and transit hub access, fragmenting last-mile driver supply across jurisdictional boundaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race where mapping data and autonomous vehicle R&D pipelines determine who captures driverless unit economics before employment reclassification erodes gig-model margins.
For Market Incumbents: Deepen proprietary AI Dispatch algorithm development to reduce driver count per trip volume, insulating against EU Platform Work Directive labor cost inflation. Consolidate market share in Germany and France through acquisition of distressed regional apps unable to absorb fixed employment obligations. Secure regulatory sandbox approvals in Arizona and California to accelerate robotaxi deployment timelines ahead of smaller competitors. For New Entrants and Emerging Players: Hospital network partnerships offer the most penetrable white-space target, with non-emergency medical transportation contracts generating recurring revenue insulated from consumer price sensitivity. India's Motor Vehicle Aggregator Guidelines enable cross-state fleet operations from Delhi-NCR to Hyderabad under harmonized federal permits. Target enterprise travel managers with bundled ground transportation procurement platforms that integrate ride-hail with rental car and public transit access. For Investors and Strategic Acquirers: Autonomous vehicle regulatory sandbox approvals in Phoenix and San Francisco are the leading indicator that driverless unit economics will concentrate returns among first-mover platforms with captive mapping infrastructure. Long-term viability across the projection horizon hinges on backward integration into vehicle manufacturing and battery supply chains rather than pure dispatch software plays. Watch for EU member state implementation timelines converging through 2026 as the inflection signal for consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Autonomous Vehicle Fleet Deployment | Waymo's Phoenix and San Francisco operations demonstrate path to driverless economics. |
| Healthcare Partnership Expansion | Hospital network contracts in Dallas-Fort Worth generate recurring non-emergency medical trip volumes. |
| Corporate Mobility Contract Consolidation | Enterprise travel managers in Chicago bundle ground transportation spend under single-platform agreements. |
| AI Dispatch Algorithm Investment | Predictive demand clustering in Bengaluru and Mumbai reduces empty cruising hours below legacy benchmarks. |
| Regulatory Sandbox Engagement | Arizona approvals accelerate robotaxi testing scale ahead of EU employment reclassification mandates. |
Research Approach
Independent corroboration across platform operations executives, fleet procurement managers, and municipal transportation regulators underwrites the qualitative findings on driver supply dynamics and permit fragmentation. Primary interviews with healthcare partnership directors and corporate travel managers validated B2B contract structures, while secondary sources included SEC filings, EU Platform Work Directive implementation documents, and India's Motor Vehicle Aggregator Guidelines. Bottom-up trip volume modeling across Bengaluru, Mumbai, and São Paulo triangulated against top-down market sizing from smartphone penetration and urban congestion metrics.
Rate-of-change decomposition across the analysis window isolated driver reclassification impacts from autonomous vehicle adoption curves and micromobility substitution effects. Segmentation dimensions modeled encompass service tier, dispatch technology maturity, end-user trip frequency patterns, and pricing architecture risk tolerance. CAGRs derived from logistic diffusion curves for autonomous fleet penetration, cross-referenced with regulatory timeline assumptions for EU member state implementation. Forecast inputs incorporated fuel price volatility scenarios and commercial insurance mandate escalation in California and New York.
Several conditions sit outside the modeled scope, including unilateral national regulator reversals on driver employment status, breakthrough battery chemistry displacing lithium-ion cell supply chains, and pandemic-scale demand shocks altering urban commuting patterns permanently. Forecasts reflect assumptions on regulatory implementation pacing and autonomous vehicle safety validation timelines. Periodic stress-testing of base assumptions is recommended against driver litigation outcomes in UK employment tribunals and US Department of Labor audit findings.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation Services
Scandinavia Car Rental Market
Transportation Services
Latin America Tourism Vehicle Rental Market
Transportation Services
Indonesia Car Rental Market
Transportation Services
Drayage Services Market
Transportation Services
Canada White Glove Delivery Service Market
Transportation Services
Russia Car Rental Market
Transportation Services
Egypt Ride Hailing Service Market
Transportation Services
Germany Car Rental Market
Transportation Services
China Vehicle Rental Market
Transportation Services
Equipment Relocation Service Market
Transportation Services
Enclosed Car Transportation Service Market
Transportation Services
Truck Rental Market
Transportation Services
Car Rental Service Market
Transportation Services
Fleet Management Consulting Service Market
Transportation Services
Spain Car Rental Market
Transportation Services
Vehicle Management System Market