
 On Street Vehicle Parking Meter Market | 2026-2036
On Street Vehicle Parking Meter Market Size, Share, and Industry Trends Forecast 2026-2036
On Street Vehicle Parking Meter Market Analytics
Municipal procurement channels are tilting toward integrated parking management platforms that bundle hardware, software, and payment processing. Flowbird leverages its European manufacturing footprint to sustain long-term service contracts with transit authorities. IPS Group, Inc. anchors its position through in-house production of solar-powered single-space meters with embedded cellular connectivity. Duncan Solutions competes primarily on brand strength across Midwestern US city contracts.
On street vehicle parking meters are electromechanical or fully digital devices installed at curbside locations to enforce time-limited parking, typically accepting coins, cards, or mobile payments and communicating occupancy data via RF or cellular networks to central management systems. Their primary commercial purpose is revenue collection for municipal governments while optimizing traffic flow and curb space utilization. Smart and multi-space product types command the deepest margin pools as cities prioritize centralized remote management over legacy single-space installations. Mobile payment and RFID technology segments are expanding fastest where meter vendors bundle consumer-facing apps with backend enforcement integration.
The US Federal Highway Administration coordinates with municipal DOTs on curb management guidelines, while the EU Green Deal and national smart city directives in Germany and France shape procurement specifications for low-energy, connected infrastructure. Parking BOXX Inc. and CivicSmart, Inc. navigate this landscape through modular hardware designs that accommodate both cash acceptance and fully digital configurations. Stakeholders must monitor how open payment standards and interoperability mandates across North American and European jurisdictions reshape vendor qualification criteria.
Market Dynamics
Municipal procurement officers now mandate open payment architectures and API-accessible data streams, forcing meter vendors to abandon proprietary closed systems. This interoperability imperative compresses margins for hardware-only suppliers while rewarding platform-integrated competitors.
Growth Catalysts
- EU Green Deal procurement mandates:German and French city councils now require solar-powered, low-energy connected infrastructure in all new parking meter tenders.
- Contactless payment card networks:Visa and Mastercard certification programs for transit and parking applications eliminate cash-handling costs for municipal operators.
- Curb management digitization:Los Angeles, Chicago, and Melbourne transportation departments deploy dynamic pricing algorithms to optimize space turnover and revenue yield.
Market Restraints
- Lithium-ion battery supply concentration:Solar-powered meter manufacturers depend on Chinese cell suppliers, exposing procurement timelines to export licensing delays.
- Cellular module certification costs:FCC and carrier-specific testing for NB-IoT and LTE-M connectivity adds six-figure validation expenses per hardware SKU.
- Legacy single-space meter installed base:Thousands of functional electromechanical units in smaller US municipalities delay capital refresh cycles.
Strategic Opportunities
- Dynamic curb pricing integration:Convergence of parking meter data with ride-hailing and delivery fleet APIs creates monetizable demand forecasting services.
- Australian smart city corridors:Sydney and Melbourne council tenders prioritize multi-space meters with embedded air quality sensors and digital wayfinding displays.
- Software-as-a-service enforcement platforms:Cloud-based citation management and license plate recognition integration replace on-premise server installations.
Industry Challenges
- RF engineer talent scarcity:Cellular antenna design and mesh network optimization skills command premium compensation in hardware development teams.
- Retrofit integration complexity:New digital meters must interface with decades-old municipal payment back-ends and enforcement databases.
- ISO 27001 cybersecurity certification:Financial data protection standards for payment processing extend compliance timelines by eight to twelve months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | On Street Vehicle Parking Meter Market |
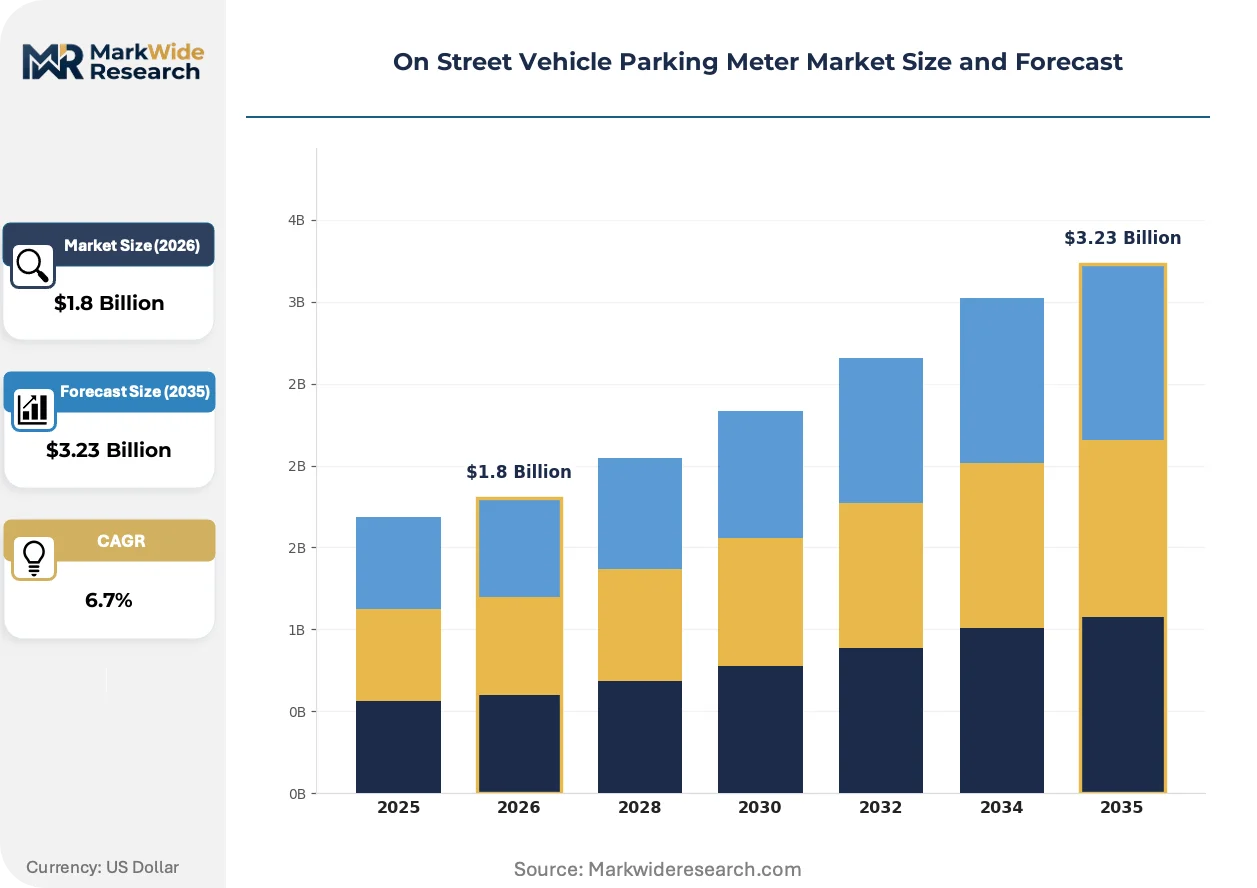
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Space, Multi Space, Digital, Smart Technology: RFID, Solar-Powered, Mobile Payment, Cash Acceptance End User: Parks, Urban Centers, Airports, Shopping Malls Deployment: On-Street, Off-Street, Temporary, Permanent |
| Companies Covered | Flowbird, Duncan Solutions, IPS Group, Inc., J.J. MacKay Canada Limited, Ventek International, METRIC Group Ltd, IEM SA, Parking BOXX Inc., CivicSmart, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
On Street Vehicle Parking Meter Market Evolving Landscape
Hardware commoditization is pushing vendor differentiation toward software layers and data services. Meter manufacturers now compete on API sophistication and enforcement integration depth rather than physical durability alone.
Embedded cellular connectivity with NB-IoT and LTE-M protocols is digitizing how parking occupancy data reaches central management platforms. Municipal DOTs in Germany and the United States now specify always-on connectivity as a baseline requirement. This shift is digitizing revenue reconciliation processes and enabling real-time enforcement dispatch.
The EU Green Deal and national smart city directives in France shape procurement specifications for low-energy, solar-compatible infrastructure. Meter vendors must now document carbon footprint across manufacturing and end-of-life recycling. German transit authorities lead enforcement of these standards, disqualifying non-compliant bidders from federal co-funding programs.
Buyer preference is consolidating around integrated parking management platforms that bundle hardware, payment processing, and enforcement software. Standalone meter sales are losing share to long-term service contracts with guaranteed uptime and revenue-sharing terms. This pattern is most visible in United States municipal RFPs, where total cost of ownership evaluations favor platform vendors over component suppliers.
On Street Vehicle Parking Meter Market Segmentation
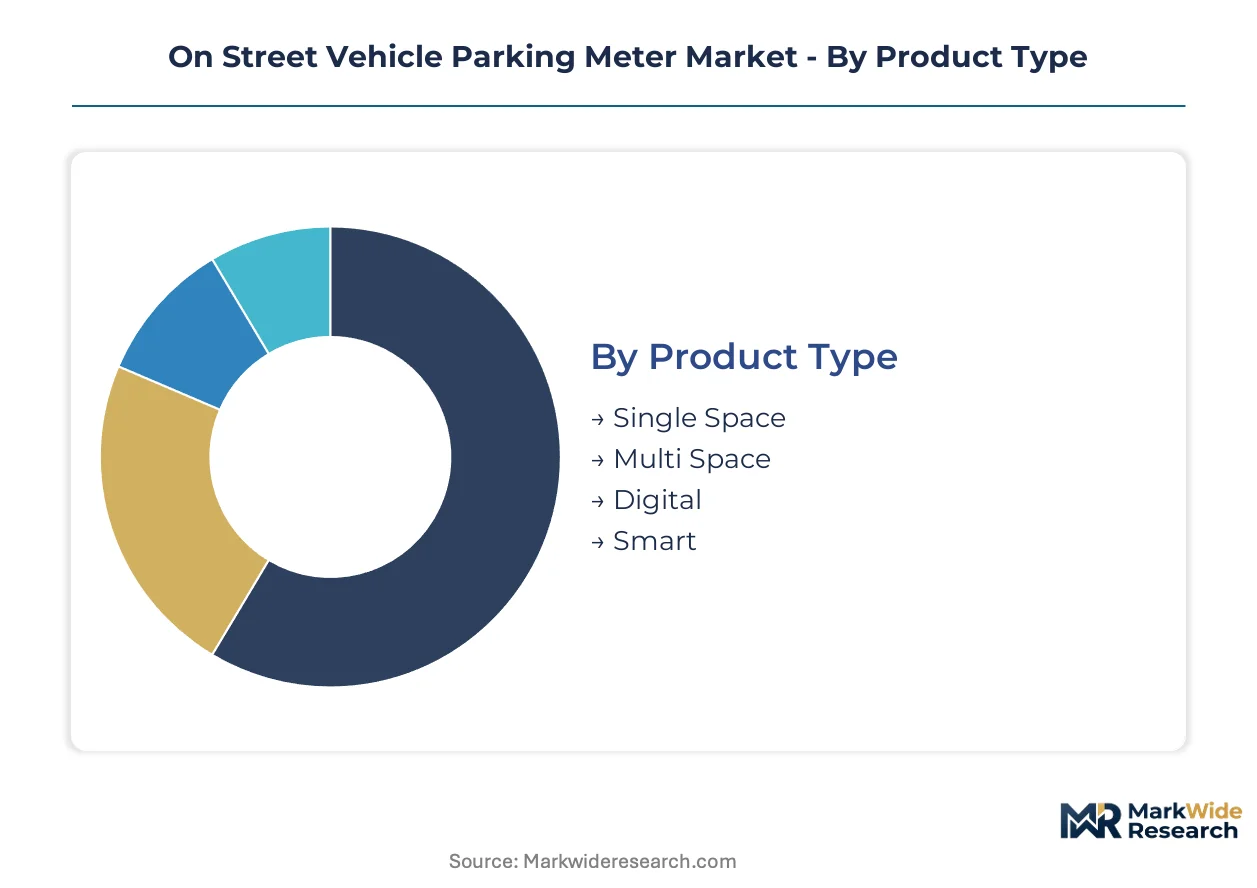
Segmentation in parking meter procurement reveals how municipal buyers prioritize connectivity, energy autonomy, and enforcement integration. Product architecture and payment modality choices cascade into decade-long service contracts and vendor lock-in effects.
Product Type:
Mature single-space electromechanical units coexist with emerging smart platforms that bundle sensors, connectivity, and dynamic pricing engines.
- Single Space:Electromechanical or basic digital meters serving individual parking bays. Demand concentrates in smaller US municipalities with constrained capital budgets and functional legacy infrastructure.
- Multi Space:Centralized pay stations managing multiple bays through zone-based enforcement. German and Australian city councils prioritize these for high-turnover commercial corridors where space optimization drives revenue yield.
- Digital:Screen-based meters with card and mobile payment acceptance but limited connectivity. These occupy the mid-tier procurement tier where cities seek cashless operation without full smart city integration.
- Smart:Fully connected platforms with embedded sensors, real-time occupancy data, and API-accessible management dashboards. Los Angeles and Melbourne transportation departments specify these for dynamic pricing pilots and curb management digitization.
Multi Space handles the majority of throughput in dense urban cores; Smart is expanding most quickly as federal co-funding programs prioritize connected infrastructure.
Technology:
Cost tier differentiation separates premium solar-cellular configurations from economy cash-only deployments.
- RFID:Contactless credential authentication for permit holders and fleet vehicles. Airports and university campuses in Germany deploy these for frictionless access control integrated with enforcement systems.
- Solar-Powered:Photovoltaic cell arrays eliminating grid dependency and trenching costs. EU Green Deal procurement mandates in France and Germany now require solar compatibility as a baseline qualification.
- Mobile Payment:Smartphone app integration with license plate recognition and digital receipting. Urban centers across the United States favor this modality for reduced cash handling and real-time revenue reconciliation.
- Cash Acceptance:Coin and bill validators retaining utility for unbanked populations and tourist districts. Shopping malls and smaller municipal contracts specify hybrid configurations preserving cash alongside digital options.
Mobile Payment commands the deepest municipal investment cycles; Solar-Powered is climbing the fastest on share as energy autonomy becomes a procurement mandate.
End User:
Application context dictates meter specifications from weatherproofing to payment modality and enforcement integration depth.
- Parks:Seasonal or event-driven deployments requiring temporary infrastructure and low-maintenance durability. These favor solar-powered units with vandal-resistant housings and simplified payment interfaces.
- Urban Centers:High-density commercial and residential corridors with 24/7 enforcement demands. Dynamic pricing algorithms and real-time occupancy data concentrate procurement specifications here.
- Airports:High-turnover short-term parking with integrated flight data and pre-booking platforms. RFID and mobile payment dominate where travelers expect frictionless credential-based access.
- Shopping Malls:Private or mixed-use curb management with customer validation programs and loyalty integration. These deployments prioritize multi-space meters with retail system API connectivity.
Urban Centers absorb the highest absolute unit volumes; Airports is gaining share fastest as privatized terminal operators upgrade legacy infrastructure.
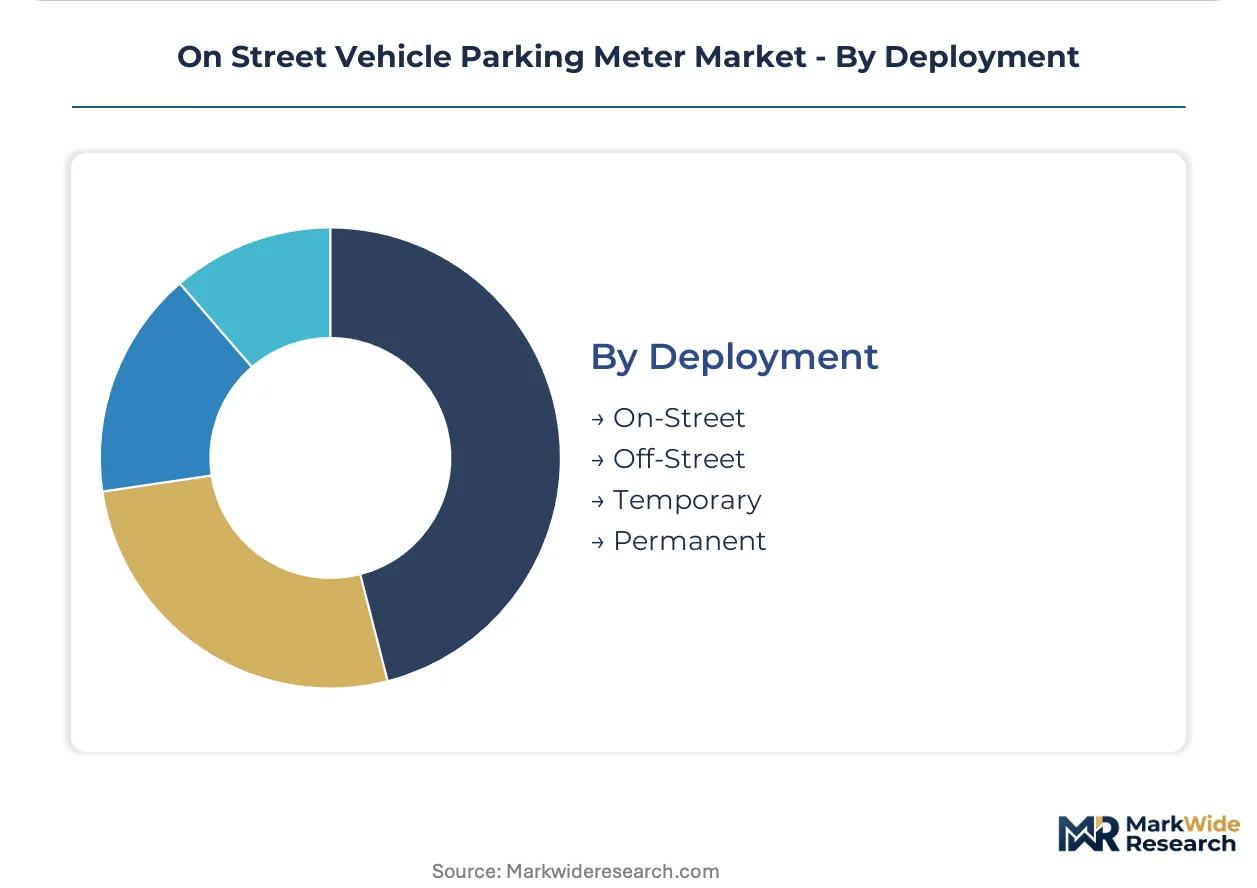
Deployment:
Customer type stratification separates permanent municipal infrastructure from temporary event-based and private off-street installations.
- On-Street:Curbside public right-of-way installations governed by municipal DOTs and traffic engineering departments. FCC-certified cellular modules and ISO 27001 payment compliance dominate technical specifications.
- Off-Street:Surface lots and garage entries under private or quasi-public management. These favor multi-space pay stations with barrier arm integration and monthly permit credentialing.
- Temporary:Festival, construction, and event deployments with rapid-install bases and cellular-only connectivity. Australian smart city pilots deploy these for adaptive curb management during major events.
- Permanent:Fixed infrastructure with ten-to-fifteen-year service life expectations and guaranteed uptime contracts. German transit authorities specify these with documented carbon footprint and end-of-life recycling protocols.
On-Street represents the installed base anchor; Temporary is the steepest expansion trajectory as cities pilot dynamic curb allocation for special events.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German municipal buyers extract steeper service-level guarantees than their US counterparts, while Australian transit authorities accelerate procurement timelines for solar-connected infrastructure. This pricing-power asymmetry reshapes vendor qualification criteria across three distinct regulatory environments.
United States
FCC-certified cellular modules and ISO 27001 payment compliance dominate technical specifications for curbside installations. The Federal Highway Administration coordinates curb management guidelines with municipal DOTs in Los Angeles and Chicago. These cities deploy dynamic pricing algorithms to optimize space turnover and revenue yield through real-time enforcement integration.
Germany
KBA and federal transit authorities enforce EU Green Deal procurement mandates requiring solar-powered, low-energy connected infrastructure. National smart city directives disqualify non-compliant bidders from federal co-funding programs. Berlin and Munich transportation departments specify multi-space meters with documented carbon footprint and end-of-life recycling protocols.
Australia
Sydney and Melbourne council tenders prioritize multi-space meters with embedded air quality sensors and digital wayfinding displays. TGA-aligned procurement standards emphasize temporary deployment flexibility for adaptive curb management during major events. Victorian smart city corridors pilot rapid-install cellular-only units for festival and construction applications.
France
ANSM and CNIL data protection frameworks intersect with EU Green Deal low-energy specifications for parking infrastructure. National directives shape procurement standards requiring solar compatibility as baseline qualification. Paris and Lyon metropolitan authorities bundle hardware, software, and payment processing through integrated platform contracts.
United Kingdom
CE marking and post-Brexit product safety alignment create dual certification burdens for meter vendors. London boroughs and Manchester transportation departments favor modular hardware designs accommodating both cash acceptance and fully digital configurations. UK municipal RFPs increasingly specify API-accessible data streams and open payment architectures.
On Street Vehicle Parking Meter Market Competitive Landscape
Platform-integrated specialists and hardware-centric component suppliers split the market along service-contract versus equipment-sale lines. The vendor base concentrates around long-term municipal relationships rather than transactional procurement. Three archetypes dominate: European manufacturing footprint holders sustaining transit authority contracts, in-house solar-cellular producers anchoring single-space deployments, and modular designers navigating interoperability mandates. Competitive moves center on backward integration into payment processing and geographic expansion through federal co-funding program qualification.
Within the European manufacturing tier, Flowbird and METRIC Group Ltd occupy positions shaped by sustained service relationships with transit authorities. IPS Group, Inc. and Duncan Solutions exemplify the North American hardware-specialist archetype, with the former representing in-house production capabilities and the latter anchoring regional contract concentration. CivicSmart, Inc. and Parking BOXX Inc. sit within the modular-design camp, their configurations accommodating both legacy cash systems and fully digital specifications across divergent municipal procurement environments.
| Leading Market Players |
|---|
| Flowbird |
| Duncan Solutions |
| IPS Group, Inc. |
| J.J. MacKay Canada Limited |
| Ventek International |
| METRIC Group Ltd |
| IEM SA |
| Parking BOXX Inc. |
| CivicSmart, Inc. |
| Others |
Value Network & Pricing Analysis
Shanghai-to-Long Beach freight corridors transmit cost volatility from Chinese lithium-ion cell suppliers directly into meter housing landed costs, compressing margins for solar-powered configurations while amplifying price spreads between standard and configured-to-order units across North American municipal procurement.
Pricing Analysis
The customization-premium spread separates standard cellular-enabled single-space meters from configured-to-order multi-space platforms with embedded air quality sensors and API-accessible enforcement dashboards. Pricing stratifies across premium smart city integration tiers, standard digital payment configurations, and economy cash-acceptance units, with ISO 27001 cybersecurity certification and FCC module validation acting as tier separators. Cost compression in the standard tier intensifies as Chinese battery suppliers extend lead times, while price erosion runs through legacy electromechanical replacements. Small US municipalities with functional installed bases exhibit the highest price sensitivity; German transit authorities with federal co-funding access show the least.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk calculations for solar-powered meter manufacturers dependent on photovoltaic cell arrays and lithium-ion battery packs. Component sourcing draws from China for cellular modules and energy storage systems, Germany for precision electromechanical assemblies, and Mexico for stamped metal housings. Raw material dependencies center on lithium carbonate, polycarbonate resins, and RF-grade copper. Single-source vulnerability concentrates in NB-IoT chipset supply. Distribution runs through municipal procurement channels governed by DOT specification committees and federal co-funding program administrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
RF engineer scarcity for cellular antenna design and mesh network optimization constrains vendor expansion velocity, making captive technical talent the decisive competitive asset across hardware development teams and platform integration roadmaps.
For Market Incumbents: Pre-empt emerging modular-design competitors by securing exclusive service contracts with German transit authorities before EU Green Deal co-funding windows close. Backward integration into payment processing software reduces API-accessibility mandates that commoditize hardware margins. Lock in multi-year lithium-ion supply agreements with South Korean cell producers to neutralize Chinese export licensing volatility. For New Entrants and Emerging Players: Australian temporary deployment corridors for festival and construction adaptive curb management represent the most penetrable entry point, with Victorian smart city pilots actively seeking rapid-install cellular-only units. Mid-tier US municipalities with aging electromechanical bases offer white-space conversion potential where incumbent platform vendors have not yet established enforcement integration. Lead with software-as-a-service enforcement platforms that displace on-premise server installations. For Investors and Strategic Acquirers: Platform-integrated specialists with embedded payment processing and municipal DOT relationship depth command premium positioning across the analysis window. Monitor open payment standard adoption velocity across North American jurisdictions as the inflection signal for vendor qualification barrier shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Payment Processing Integration | Backward integration into Visa and Mastercard certification programs eliminates third-party revenue sharing with municipal operators. |
| Solar Manufacturing Scale-Up | In-house photovoltaic cell assembly secures EU Green Deal compliance timelines for German federal co-funding eligibility. |
| API Platform Expansion | Dynamic curb pricing convergence with ride-haling fleet data creates monetizable demand forecasting services for DOT clients. |
| Cybersecurity Certification Investment | ISO 27001 compliance acceleration opens procurement channels in US municipalities with financial data protection mandates. |
| Temporary Deployment Pilot Programs | Festival and construction corridor trials in Australian smart city zones validate rapid-install product architectures for global rollout. |
Research Methodology
Initial hypotheses were tested against primary input from municipal fleet managers, urban transportation department procurement officers, parking meter hardware engineers, and enforcement software integration specialists, and refined through secondary validation against FCC certification databases, EU Green Deal procurement guidelines, municipal RFP archives, and cellular carrier module approval records. Bottom-up unit deployment tracking across US, German, and Australian city corridors was cross-referenced with top-down vendor revenue triangulation.
Demand-supply-balance framing anchored the analytical approach, with municipal procurement pipeline visibility weighted against manufacturing capacity utilization across Chinese battery cell suppliers and German electromechanical component producers. Segmentation dimensions modeled included product architecture tiers, payment modality configurations, deployment permanence categories, and regional regulatory cluster alignment. CAGRs were derived from installed base refresh cycle analysis and federal co-funding program allocation trajectories. Forecast inputs incorporated lithium-ion supply lead time volatility and open payment standard adoption curves.
Macroeconomic conditions sit as an overlay; deviation in municipal capital expenditure cycles and trans-Pacific freight rate indices would shift the trajectory. Forecasts reflect documented assumptions regarding EU Green Deal enforcement continuity and cellular carrier certification timeline stability. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation Services
Waste Collection Vehicle Market
Transportation Services
Vacuum Truck Rentals Market
Transportation Services
Multispace Parking Meter Market
Transportation Services
Truck Rental Market
Transportation Services
Water Truck Rental Market
Transportation Services
Enclosed Car Transportation Service Market
Transportation Services
Asia-Pacific Rickshaw Ride Hailing Service Market
Transportation Services
Vehicle Management System Market
Transportation Services
Aerial Lift Rental Services Market
Transportation Services
Airline Passenger Service System Market
Transportation Services
Ride-Hailing Service Market
Transportation Services
Refrigerated Truck Rental Market
Transportation Services
Fleet Management Consulting Service Market
Transportation Services
Bird Carriers Market
Transportation Services
Brazil Vehicle Rental Market
Transportation Services
United States Car Rental Market