
 Truck Sharing Market | 2026-2036
Truck Sharing Market Size, Share, and Industry Trends Forecast 2026-2036
Truck Sharing Market Analytics
Commercial driver availability is collapsing across North America and Western Europe, forcing fleet operators to seek asset-light alternatives that preserve capacity without permanent headcount. AB Volvo leverages its connected fleet infrastructure to sustain uptime guarantees for shared heavy-duty units. Daimler AG anchors European urban logistics through its captive van-sharing subsidiaries. Robert Bosch GmbH competes on telematics integration, embedding predictive maintenance into shared truck pools.
Truck sharing denotes the short-term allocation of commercial vehicle capacity through digital platforms that match idle trucks with verified users, typically incorporating real-time GPS tracking, automated damage assessment via onboard cameras, and dynamic per-mile or per-hour pricing. The model eliminates capital lockup for small freight operators while maximizing utilization rates on depreciating assets. Fleet-based services dominate transaction volume owing to standardized maintenance protocols and insured liability frameworks, whereas peer-to-peer networks capture margin in light-duty and last-mile segments where owner-operators seek supplemental income. Mobile apps and payment integration constitute the technology backbone, though GPS tracking and fleet management modules generate the data streams that enable risk-based pricing and route optimization.
The US Department of Transportation enforces hours-of-service rules that indirectly expand demand for shared trucks by capping individual driver utilization. The EU Green Deal and F-Gas Regulation constrain diesel fleet expansion, pushing shared operators toward electric vehicle procurement. Germany's KBA and France's national transport regulator impose safety inspection frequencies that favor professional fleet-based models over informal peer-to-peer arrangements. Stakeholders must weigh regulatory compliance costs against platform scalability when selecting between asset-heavy and asset-light operating structures.
Market Dynamics
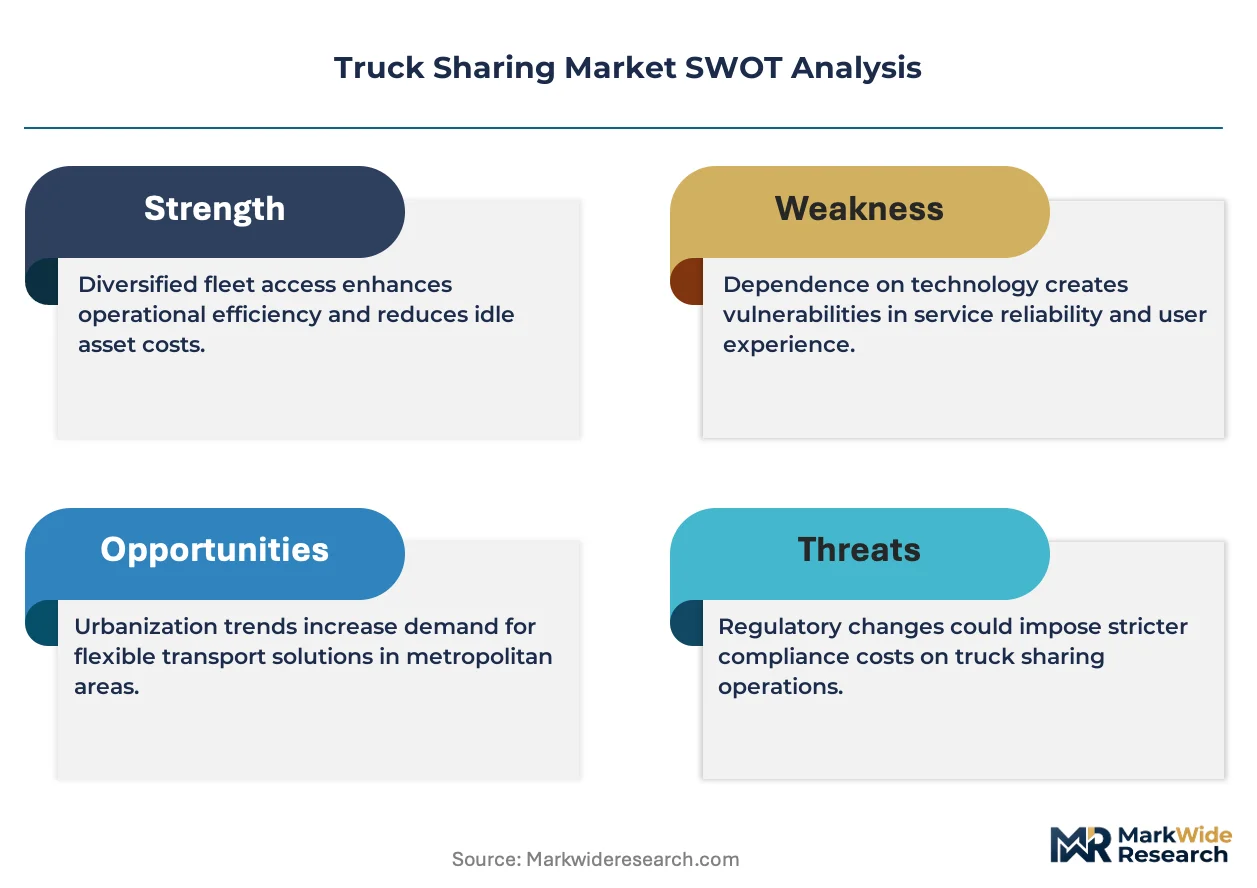
Commercial driver shortages across North America and Western Europe are forcing fleet operators toward asset-light capacity models that preserve utilization without permanent headcount commitments.
Growth Catalysts
- E-commerce fulfillment networks:Last-mile delivery operators in Germany's Rhine-Ruhr corridor are expanding shared truck adoption to manage peak-season volume spikes without capital lockup.
- EU Green Deal emissions standards:The F-Gas Regulation and diesel fleet constraints are pushing shared operators toward electric vehicle procurement, accelerating platform-based fleet turnover.
- Telematics integration:Predictive maintenance algorithms embedded in shared truck pools are reducing downtime guarantees and expanding insured liability coverage for verified users.
Market Restraints
- Insurance cost volatility:Commercial auto liability premiums for shared heavy-duty units fluctuate with claims frequency in urban logistics corridors, compressing per-mile margins.
- Regulatory inspection friction:Germany's KBA and France's national transport regulator impose safety inspection frequencies that favor professional fleet-based models over informal peer-to-peer arrangements.
- Asset depreciation exposure:Platform operators bear residual value risk on electric vehicle fleets as battery technology cycles shorten and resale markets remain thin.
Strategic Opportunities
- Underpenetrated urban corridors:Secondary logistics hubs in Poland and Czechia lack shared truck infrastructure, creating first-mover advantages for platform operators with EU-wide compliance frameworks.
- Refrigerated cargo specialization:Temperature-controlled pharmaceuticals and fresh food logistics represent high-margin segments where shared cold-chain units command premium per-hour pricing.
- Carbon credit monetization:The EU Emissions Trading System allows shared electric fleet operators to generate tradable allowances, offsetting platform acquisition costs.
Industry Challenges
- Commercial driver certification pipelines:Hours-of-service enforcement by the US Department of Transportation and EU equivalents cap individual utilization, forcing platforms to maintain larger verified driver pools.
- Legacy fleet management integration:Established freight operators face technical debt when migrating dispatch and maintenance systems to API-based shared platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Truck Sharing Market |
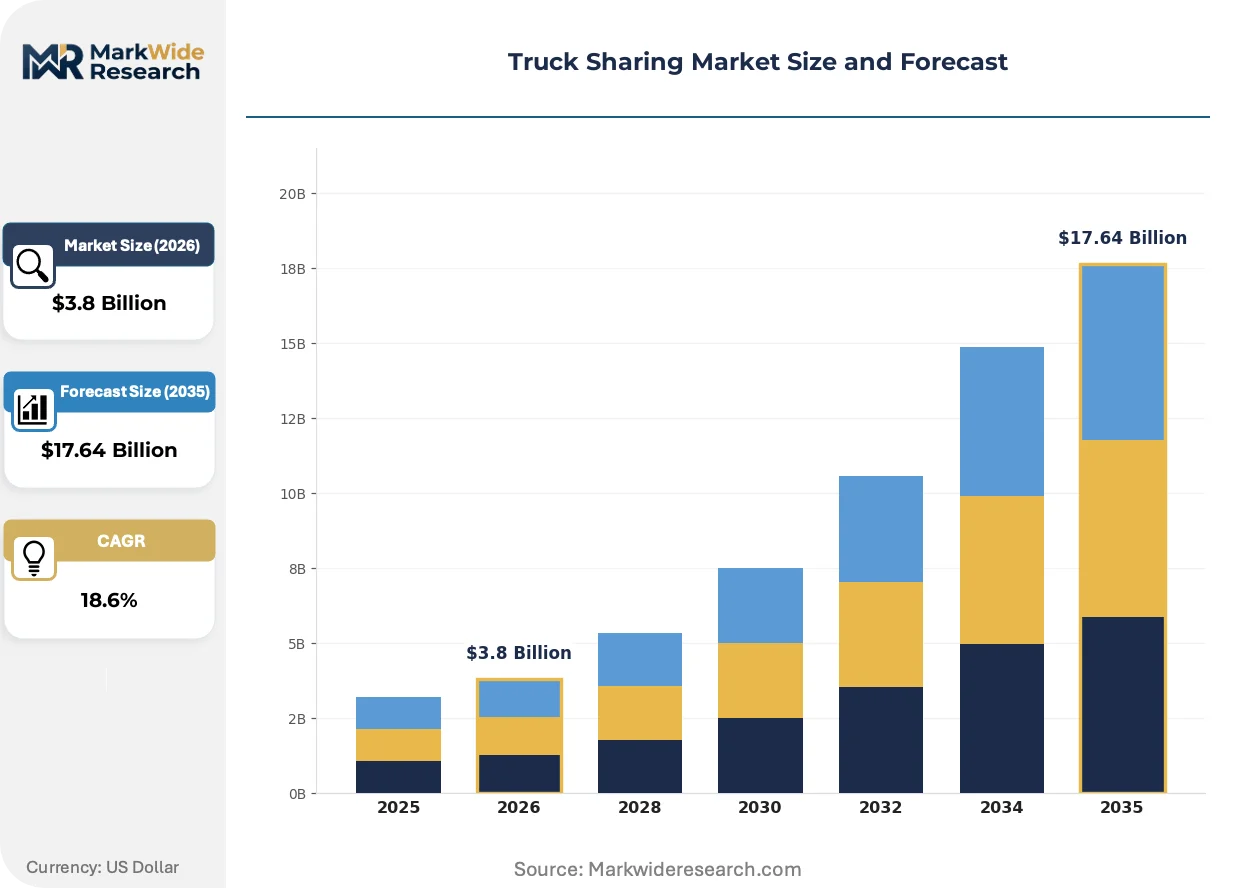
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.64 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Peer-to-Peer, Fleet-Based, On-Demand, Long-Term Rental Vehicle Type: Light-Duty Trucks, Heavy-Duty Trucks, Cargo Vans, Pickup Trucks Customer Type: Businesses, Individual Consumers, Delivery Services, Moving Companies Technology: Mobile Apps, GPS Tracking, Payment Integration, Fleet Management |
| Companies Covered | AB Volvo, Daimler AG, Waymo LL, Continental AG, Robert Bosch GmbH, Aptiv, EMBARK, Intel Corporation, Qualcomm Technologies Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Truck Sharing Market Evolving Landscape
Digital matching platforms are compressing transaction friction while embedded hardware generates the data streams enabling dynamic risk-based pricing and route optimization.
Telematics hardware is decomposing traditional fleet ownership structures by embedding real-time GPS tracking, automated damage assessment via onboard cameras, and predictive maintenance alerts into shared vehicle pools. Small freight operators and last-mile delivery services are adopting these connected units fastest, drawn by per-mile pricing that eliminates capital commitment. The technology is decomposing asset-heavy business models by transferring residual risk to platform operators while maximizing utilization on depreciating commercial vehicles.
The EU Green Deal's emissions standards are mandating diesel fleet phase-outs and accelerating electric vehicle procurement timelines for shared operators. Industrial consequence includes compressed payback periods for charging infrastructure investments and stricter uptime guarantees for battery-electric units. Urban logistics segments in Germany, France, and the Netherlands face the steepest compliance curves, with fleet-based services responding through standardized maintenance protocols and captive charging networks.
Small freight operators are unbundling capacity procurement from asset ownership, preferring short-term allocation through verified digital platforms over traditional lease structures. This behavioral shift disrupts equipment finance channels and captive leasing subsidiaries that historically dominated commercial vehicle distribution. The pattern concentrates in e-commerce fulfillment and food service logistics, where demand seasonality makes fixed-cost fleet ownership economically irrational.
Truck Sharing Market Segmentation
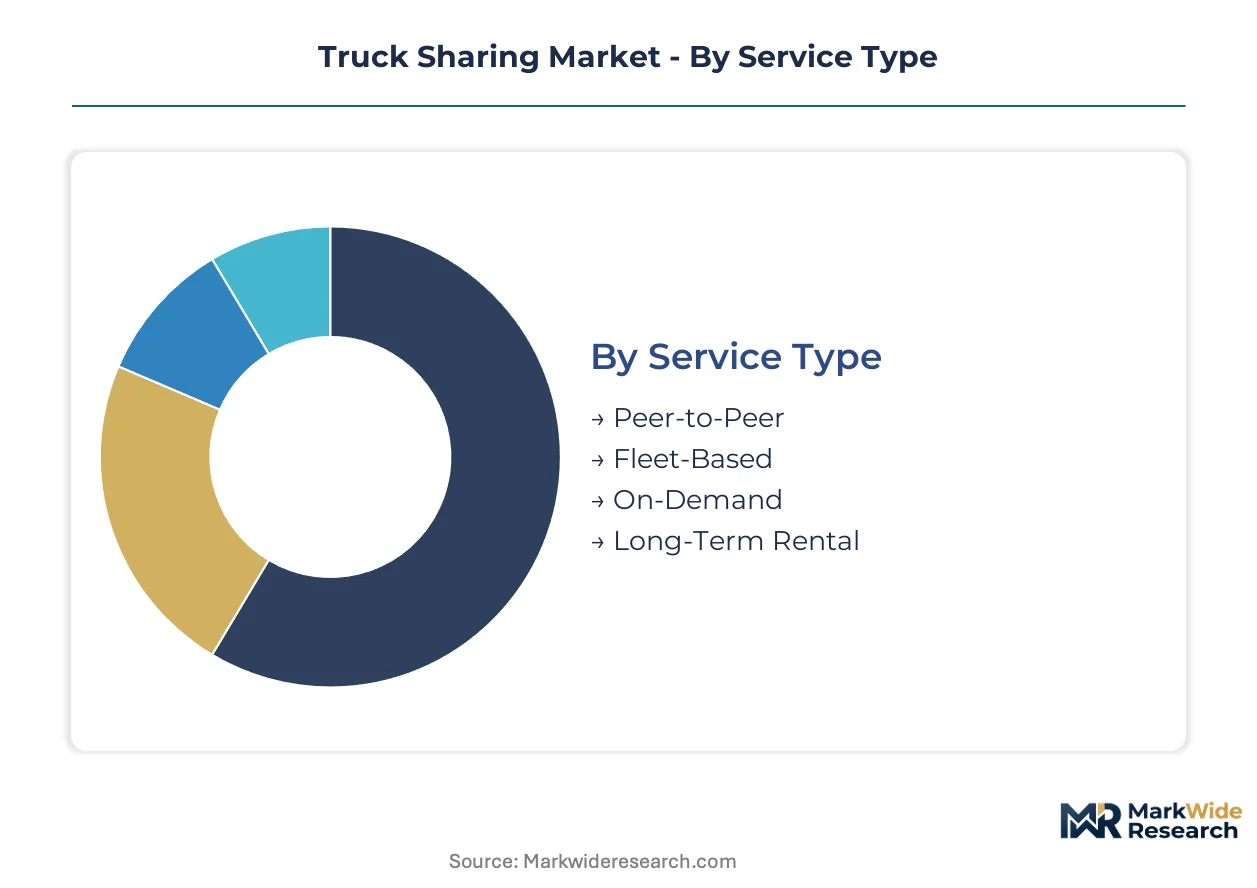
Truck sharing platforms configure service tiers around asset ownership structure, vehicle specification, and customer risk profiles. Segmentation determines pricing mechanics, insurance frameworks, and geographic deployment priorities for operators balancing utilization against regulatory compliance.
Service Type:
Fleet-based models capture premium margin pools through standardized maintenance protocols and insured liability frameworks, while peer-to-peer networks extract yield from asset-light owner-operators.
- Fleet-Based:Professional operators maintain captive vehicle pools with uniform inspection schedules and centralized telematics. Rhine-Ruhr logistics corridors in Germany concentrate demand from e-commerce fulfillment networks managing peak-season volume spikes without capital lockup.
- Peer-to-Peer:Digital platforms match idle privately-owned trucks with verified users, embedding automated damage assessment via onboard cameras. Light-duty and last-mile segments in France attract owner-operators seeking supplemental income, though France's national transport regulator imposes inspection frequencies that compress margins against informal arrangements.
- On-Demand:Immediate allocation through mobile interfaces serves urgent freight movements with dynamic per-mile pricing.
- Long-Term Rental:Extended capacity commitments preserve utilization for seasonal operators avoiding permanent fleet expansion.
Fleet-Based holds installed capacity. Peer-to-Peer is rotating up the share rankings.
Vehicle Type:
Heavy-duty units concentrate revenue per transaction, while light-duty vehicles dominate transaction frequency in urban last-mile corridors.
- Heavy-Duty Trucks:Shared Class 8 tractors and straight trucks integrate predictive maintenance algorithms to sustain uptime guarantees. AB Volvo leverages connected fleet infrastructure to anchor European long-haul segments where EU Green Deal emissions standards accelerate electric procurement timelines.
- Cargo Vans:Compact urban delivery units command premium per-hour pricing in temperature-controlled pharmaceutical logistics. Daimler AG anchors European urban logistics through captive van-sharing subsidiaries responding to diesel phase-out mandates.
- Light-Duty Trucks:Medium commercial vehicles bridge last-mile and regional distribution with flexible payload configurations.
- Pickup Trucks:Consumer-facing and small contractor segments favor short-term rental for intermittent hauling needs.
Heavy-Duty Trucks anchors platform revenue concentration. Cargo Vans is climbing the fastest as urban electrification mandates tighten.
Customer Type:
Business accounts generate recurring revenue streams with lower acquisition costs, while delivery services exhibit steepest volume expansion.
- Delivery Services:Last-mile operators unbundle capacity procurement from asset ownership, preferring short-term allocation through verified digital platforms. E-commerce fulfillment networks in Germany's Rhine-Ruhr corridor expand shared truck adoption to manage demand seasonality without fixed-cost fleet ownership.
- Businesses:Small freight operators adopt connected units drawn by per-mile pricing that eliminates capital commitment. The US Department of Transportation enforces hours-of-service rules that indirectly expand demand by capping individual driver utilization.
- Moving Companies:Residential relocation services require intermittent heavy-duty access with damage liability coverage.
- Individual Consumers:sporadic personal hauling generates low-margin transactions with high customer acquisition expenditure.
Businesses holds contracted revenue base. Delivery Services is gaining share fastest as e-commerce penetration deepens.
Technology:
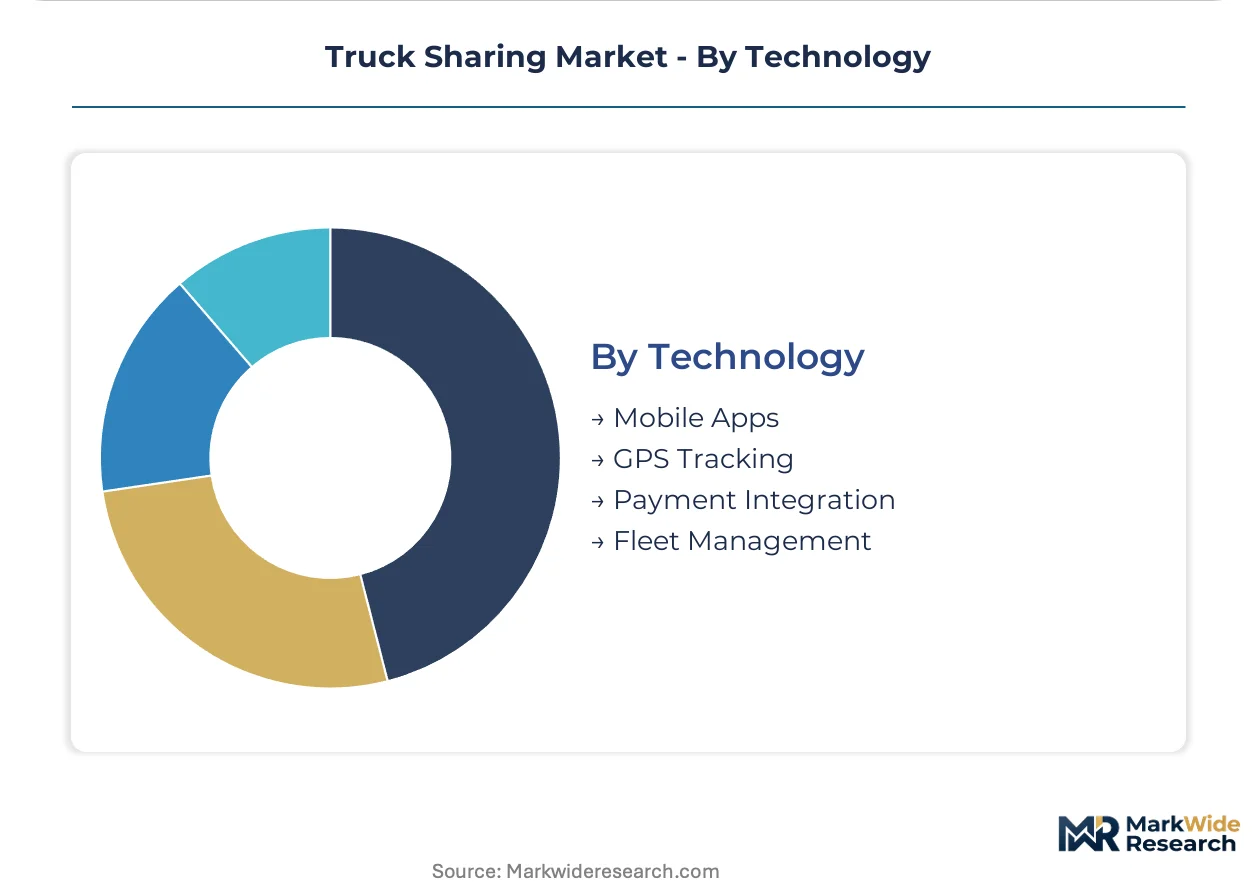
GPS tracking and fleet management modules generate data streams enabling risk-based pricing, while payment integration constitutes baseline infrastructure.
- Fleet Management:Centralized dispatch, maintenance scheduling, and compliance tracking systems decompose traditional ownership structures. Robert Bosch GmbH competes on telematics integration, embedding predictive maintenance into shared truck pools to reduce downtime guarantees.
- GPS Tracking:Real-time location data enables dynamic route optimization and automated geofencing for insurance verification. Urban logistics segments across the Netherlands deploy these capabilities to satisfy EU Green Deal monitoring requirements.
- Mobile Apps:Consumer and business interfaces compress transaction friction through digital verification and instant booking confirmation.
- Payment Integration:Automated billing systems support per-mile, per-hour, and flat-rate pricing structures with embedded insurance premiums.
Fleet Management holds platform differentiation. GPS Tracking is rotating up the share rankings as telematics hardware costs decline.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Germany's Rhine-Ruhr corridor while margins compress in France's peer-to-peer segments. The EU Green Deal's emissions standards reshape fleet composition requirements across Western European logistics networks. Demand clusters in Germany, France, the United Kingdom, the Netherlands, and Poland.
Germany
E-commerce fulfillment networks and last-mile delivery operators drive shared truck adoption in the Rhine-Ruhr logistics corridor. KBA safety inspection frequencies favor professional fleet-based models over informal arrangements. Platform operators in North Rhine-Westphalia manage peak-season volume spikes without capital lockup.
France
Owner-operators in light-duty segments seek supplemental income through digital matching platforms. The national transport regulator imposes inspection frequencies that compress margins against informal peer-to-peer arrangements. Urban logistics corridors around Paris concentrate refrigerated cargo specialization for pharmaceutical and fresh food logistics.
United Kingdom
Small freight operators unbundle capacity procurement from asset ownership, preferring short-term allocation through verified digital platforms. Hours-of-service enforcement caps individual driver utilization, expanding demand for shared trucks. London's urban logistics networks face steep compliance curves for diesel phase-out mandates.
Netherlands
Urban logistics segments deploy GPS tracking capabilities to satisfy EU Green Deal monitoring requirements. The F-Gas Regulation and diesel fleet constraints push shared operators toward electric vehicle procurement. Amsterdam and Rotterdam logistics hubs accelerate platform-based fleet turnover with captive charging networks.
Poland
Secondary logistics hubs lack shared truck infrastructure, creating first-mover advantages for platform operators with EU-wide compliance frameworks. The EU Emissions Trading System allows shared electric fleet operators to generate tradable allowances. Warsaw and Krakow corridors attract investment in refrigerated cargo specialization for temperature-controlled pharmaceuticals.
Truck Sharing Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the truck sharing ecosystem. The market structure consolidates around established automotive manufacturers with connected fleet infrastructure, technology suppliers with telematics integration capabilities, and specialized platform operators with digital matching expertise. Three strategic archetypes dominate: captive fleet operators leveraging OEM service networks, independent technology integrators embedding predictive maintenance algorithms, and asset-light platform specialists compressing transaction friction. Competitive moves center on telematics hardware partnerships and charging infrastructure investments for electric fleet transitions.
Among European-based automotive manufacturers, AB Volvo, Daimler AG, and Robert Bosch GmbH occupy distinct positions within the competitive hierarchy. AB Volvo represents the captive fleet operator archetype with connected heavy-duty infrastructure. Daimler AG exemplifies urban logistics specialization through van-sharing subsidiaries responding to emissions mandates. Robert Bosch GmbH anchors the technology integrator tier, embedding predictive maintenance capabilities into shared vehicle pools. These three entities collectively illustrate how OEM-affiliated players compete against independent platform operators for control of utilization optimization and uptime guarantee frameworks.
| Leading Market Players |
|---|
| AB Volvo |
| Daimler AG |
| Waymo LL |
| Continental AG |
| Robert Bosch GmbH |
| Aptiv |
| EMBARK |
| Intel Corporation |
| Qualcomm Technologies Inc. |
| Others |
Value Network & Pricing Analysis
Electric vehicle battery procurement displacing diesel powertrain sourcing simultaneously redistributes supplier geography toward East Asian cell manufacturers and compresses per-mile pricing premiums that fleet operators once commanded for environmental compliance.
Pricing Analysis
Germany's Rhine-Ruhr corridor commands premium per-hour rates against Poland's emerging logistics hubs where platform density remains thin. Fleet-based services deploy three-tier pricing structure across premium uptime guarantees, standard maintenance-included rates, and economy peer-to-peer matching. Cost compression in light-duty segments intensifies because owner-operators flood digital platforms with surplus capacity. Small freight operators exhibit highest price sensitivity, while pharmaceutical cold-chain logistics buyers absorb premium pricing for temperature-verified units.
Supply Chain Analysis
Inventory cycles for electric commercial vehicles stretch 8-14 weeks longer than legacy diesel equivalents due to battery cell allocation queues. Manufacturing concentrates in Germany, China, and South Korea where OEM-affiliated platforms secure priority chassis allocation. Lithium-ion cells, power electronics, and telematics hardware anchor component dependencies. Single-source vulnerability sits with semiconductor suppliers for fleet management modules. Distribution runs through captive OEM service networks and independent platform operator hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The truck sharing market rewards operators who control connected fleet infrastructure, yet qualified telematics engineers and predictive maintenance algorithm developers remain concentrated among established automotive suppliers.
For Market Incumbents: Shield uptime guarantee frameworks by deepening captive charging infrastructure investments in urban logistics corridors where EU Green Deal compliance curves steepen. Consolidate maintenance technician pools through backward integration into vocational training partnerships, neutralizing the driver certification pipeline collapse that threatens fleet utilization rates. For New Entrants and Emerging Players: Anchor in Poland's secondary logistics corridors where platform infrastructure remains underdeveloped and EU-wide compliance frameworks create first-mover advantages. Target refrigerated cargo specialization for temperature-controlled pharmaceuticals, commanding premium per-hour pricing with lower customer acquisition expenditure than saturated last-mile segments. For Investors and Strategic Acquirers: Capital is best deployed toward technology integrators with embedded predictive maintenance capabilities rather than asset-heavy fleet operators exposed to electric vehicle residual value risk. Long-term viability hinges on control of telematics data streams that enable dynamic risk-based pricing. Watch charging infrastructure utilization rates as the inflection indicator for platform scalability.| Strategic Initiative | Industry Significance |
|---|---|
| Telematics Hardware Partnership | Robert Bosch GmbH embeds predictive maintenance algorithms that reduce downtime guarantees for shared heavy-duty pools. |
| Charging Infrastructure Investment | Daimler AG's captive networks in Amsterdam and Rotterdam accelerate electric van-sharing adoption under F-Gas Regulation timelines. |
| EU Compliance Framework Expansion | Platform operators with KBA-aligned inspection protocols capture share from informal peer-to-peer arrangements in Germany. |
| Cold-Chain Fleet Specialization | Temperature-controlled units in France's pharmaceutical corridors command premium pricing with insured liability coverage. |
| Carbon Credit Monetization | Shared electric fleet operators in the Netherlands generate tradable EU Emissions Trading System allowances offsetting acquisition costs. |
Research Methodology
The analysis maps fleet-based services, peer-to-peer networks, and on-demand allocation platforms, each validated through fleet operations directors, telematics product managers, commercial insurance underwriters, and last-mile logistics procurement leads. Primary interviews combined with secondary sources including EU transport regulator filings, KBA inspection compliance databases, OEM connected fleet disclosures, and customs trade data for commercial vehicle imports. Bottom-up transaction volume estimates triangulated against top-down addressable fleet capacity calculations.
Consistency checks validated volume and value outputs against external benchmarks across the projection horizon. The analytical framework modeled service type, vehicle specification, customer risk profile, and regional regulatory cluster as core segmentation dimensions. CAGRs derived from logistic curve adoption patterns fitted to e-commerce fulfillment penetration rates and electric vehicle procurement timelines. Forecast inputs incorporated hours-of-service enforcement stringency indices and battery technology cost decline curves.
Material uncertainties — abrupt regulatory relaxation of diesel phase-out mandates, accelerated autonomous vehicle deployment, or lithium supply disruptions — sit outside the modeled envelope. Forecasts reflect documented assumptions about platform operator retention economics and charging infrastructure buildout pacing. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation Services
India Car Rental Market
Transportation Services
United States Vehicle Rental Market
Transportation Services
Equipment Relocation Service Market
Transportation Services
United States Car Rental Market
Transportation Services
Vietnam Car Rental Market
Transportation Services
Waste Collection Vehicle Market
Transportation Services
Europe Light Commercial Vehicle Rental Market
Transportation Services
Enclosed Car Transportation Service Market
Transportation Services
Latin America Tourism Vehicle Rental Market
Transportation Services
United States White Glove Delivery Service Market
Transportation Services
Brazil Vehicle Rental Market
Transportation Services
Asia Pacific Tourism Vehicle Rental Market
Transportation Services
Europe Vehicle Rental Market
Transportation Services
Car Rental Service Market
Transportation Services
United Kingdom Car Rental Market
Transportation Services
Ship Management Software Market