
 Full-Service Carrier Market | 2026-2036
Full-Service Carrier Market Size, Share, and Industry Trends Forecast 2026-2036
Full-Service Carrier Market Analysis
A capital-intensity divergence between legacy network carriers and mid-tier flag carriers is reorganizing competitive hierarchies across long-haul aviation. Emirates leverages its Dubai hub position to sustain ultra-long-haul capacity deployment across six continents. American Airlines anchors its transatlantic joint venture with British Airways through premium cabin reinvestment at Dallas-Fort Worth and Charlotte. Lufthansa differentiates via its multi-hub German-Austrian-Swiss network architecture.
A full-service carrier operates scheduled passenger and cargo aviation with integrated premium amenities, hub-and-spoke network design, and interline or codeshare partnerships across multiple aircraft classes. These carriers typically deploy wide-body aircraft with 250-550 seat configurations for sectors exceeding 3,000 nautical miles, offering differentiated cabin products including lie-flat business seats and first-class suites for corporate and high-yield leisure segments. International flights generate the highest revenue per available seat kilometer due to premium cabin density on transoceanic routes, while charter services capture concentrated margin pools from government contracts and sports team movements. Wide-body aircraft dominate capital allocation for Asia-Europe and Asia-North America trunk routes where passenger load factors justify twin-aisle operating economics.
The Federal Aviation Administration enforces airworthiness directives and pilot duty-time regulations that shape crew costs and aircraft utilization rates for US-based carriers. The European Union Aviation Safety Agency mandates emissions monitoring under its ReFuelEU Aviation initiative, while ICAO's CORSIA framework imposes carbon offset obligations on international operations. China's Civil Aviation Administration implements slot coordination and route authority protocols that constrain network expansion for foreign entrants. Stakeholders must monitor sustainable aviation fuel certificate markets and bilateral air service negotiations as these mechanisms increasingly determine route profitability and fleet renewal timing.
Market Dynamics
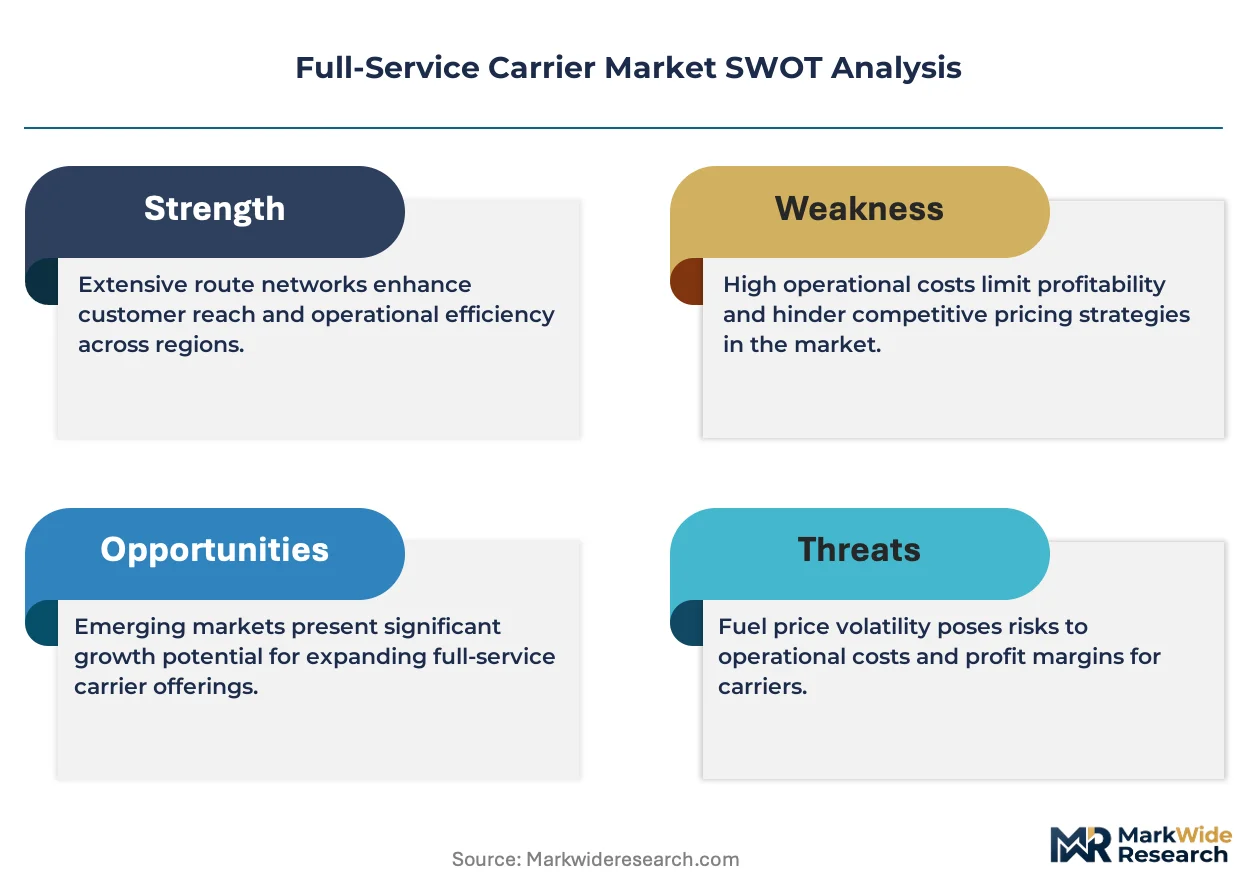
ICAO's CORSIA framework and the EU Green Deal are forcing fleet renewal cycles and sustainable aviation fuel procurement commitments across long-haul networks, compressing operating margins while mandating billions in capital redeployment toward lower-emission aircraft.
Growth Catalysts
- Corporate travel normalization:Multinational corporations in technology and financial services are restoring premium cabin budgets for transatlantic and intra-Asian routes, restoring yield premiums that collapsed during remote-work adoption.
- ReFuelEU Aviation mandate:The European Union's binding sustainable aviation fuel quotas create guaranteed offtake agreements for carriers with early SAF supply contracts, locking in fuel cost predictability against volatile jet kerosene markets.
- Hub concentration in the United Arab Emirates:Dubai's geographic positioning between Europe and Asia-Pacific enables sixth-freedom traffic capture that aggregates thin origin-destination pairs into viable wide-body economics.
Market Restraints
- Wide-body aircraft supply concentration:Boeing and Airbus duopoly control over twin-aisle production creates delivery slot scarcity, forcing carriers to accept 2028-2031 delivery windows for next-generation aircraft.
- Jet fuel price volatility:Crude oil derivative exposure remains unhedged beyond 18-24 months for most flag carriers, amplifying quarterly earnings variance against fixed-yield corporate contracts.
- Pilot training pipeline constraints:FAA and EASA flight-hour requirements for wide-body type ratings extend crew qualification timelines to 18-24 months, capping fleet expansion velocity regardless of aircraft availability.
Strategic Opportunities
- India's underserved long-haul connectivity:Indira Gandhi International Airport slot expansion and bilateral liberalization with the European Union create first-mover advantages for carriers establishing Delhi-Europe nonstop services before local hub carriers scale.
- Premium leisure segment unbundling:High-net-worth individual travelers in the United States and China are accepting a la carte first-class pricing for space and privacy, decoupling premium yield from traditional corporate travel contracts.
- SAF certificate trading markets:Book-and-claim mechanisms for sustainable aviation fuel attributes allow carriers with limited physical SAF access to meet CORSIA obligations through financial instruments, reducing compliance capital intensity.
Industry Challenges
- Maintenance technician scarcity:FAA-certificated airframe and powerplant mechanic shortages at major US maintenance bases are extending C-check intervals and reducing aircraft utilization rates below optimal 13-14 daily hours.
- Legacy revenue management system integration:Sabre and Amadeus passenger service system migrations to cloud-native architectures require 24-36 month implementation timelines, delaying dynamic pricing capabilities during demand recovery.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Full-Service Carrier Market |
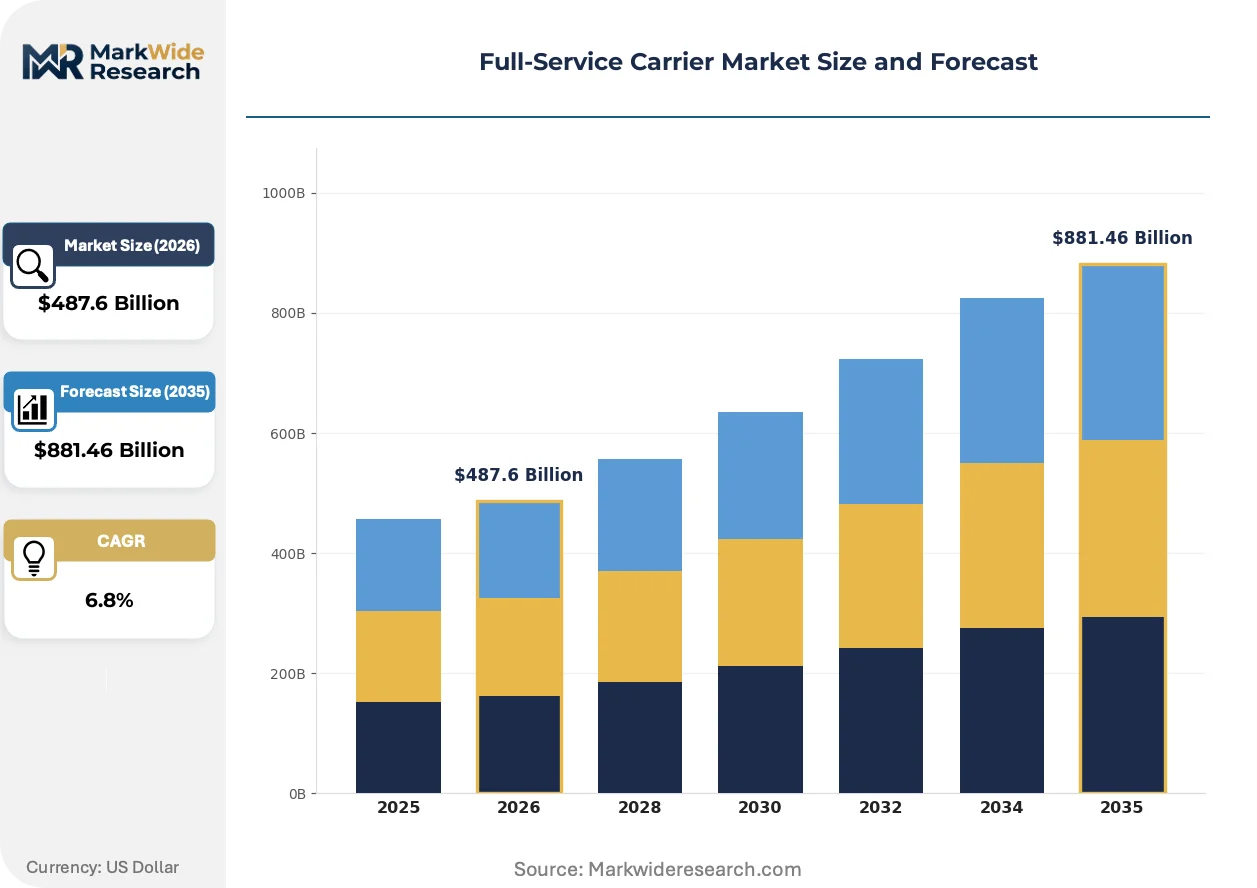
| Market Size in 2026 | $487.6 Billion |
| Market Size in 2035 | $881.46 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: International Flights, Domestic Flights, Charter Services, Codeshare Agreements Customer Type: Business Travelers, Leisure Travelers, VIP Clients, Group Bookings Aircraft Type: Narrow-Body Aircraft, Wide-Body Aircraft, Regional Jets, Cargo Aircraft Distribution Channel: Online Travel Agencies, Direct Booking, Corporate Contracts, Travel Management Companies |
| Companies Covered | China Southern Airlines, Air China, American Airlines, Emirates, Lufthansa, Delta Air Lines, China Eastern Airlines, Air France, United Airlines, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Full-Service Carrier Market Emerging Trajectories
Next-generation propulsion architectures and digital distribution platforms are compressing the traditional ten-year aircraft replacement cycle while fragmentating passenger acquisition channels away from legacy global distribution systems.
Geared turbofan engine technology is miniaturizing fuel consumption per available seat kilometer through higher bypass ratios and advanced ceramic matrix composites. Emirates and Lufthansa are accelerating adoption of Pratt & Whitney GTF and Rolls-Royce UltraFan powerplants for 2026-2028 deliveries. This propulsion shift is miniaturizing the operating cost gap between newest-generation and previous-generation wide-bodies, forcing accelerated retirement of ten-year-old aircraft.
The EU Green Deal's ReFuelEU Aviation initiative mandates escalating SAF blending quotas from 2025 through 2050, with non-compliance penalties tied to carbon market prices. Carriers with early Neste or World Energy supply agreements are securing ten-year offtake contracts at fixed premiums to conventional jet fuel. Long-haul European network carriers face the steepest compliance ramps and are consolidating procurement through airline consortium structures.
Corporate travel managers are unbundling traditional annual volume commitments in favor of spot-market premium cabin purchasing through direct airline NDC channels. This procurement fragmentation is compressing yield management response windows from quarterly to weekly cycles. United States-based technology sector travelers are leading this shift, prioritizing flexibility over negotiated corporate discounts.
Full-Service Carrier Market Segmentation
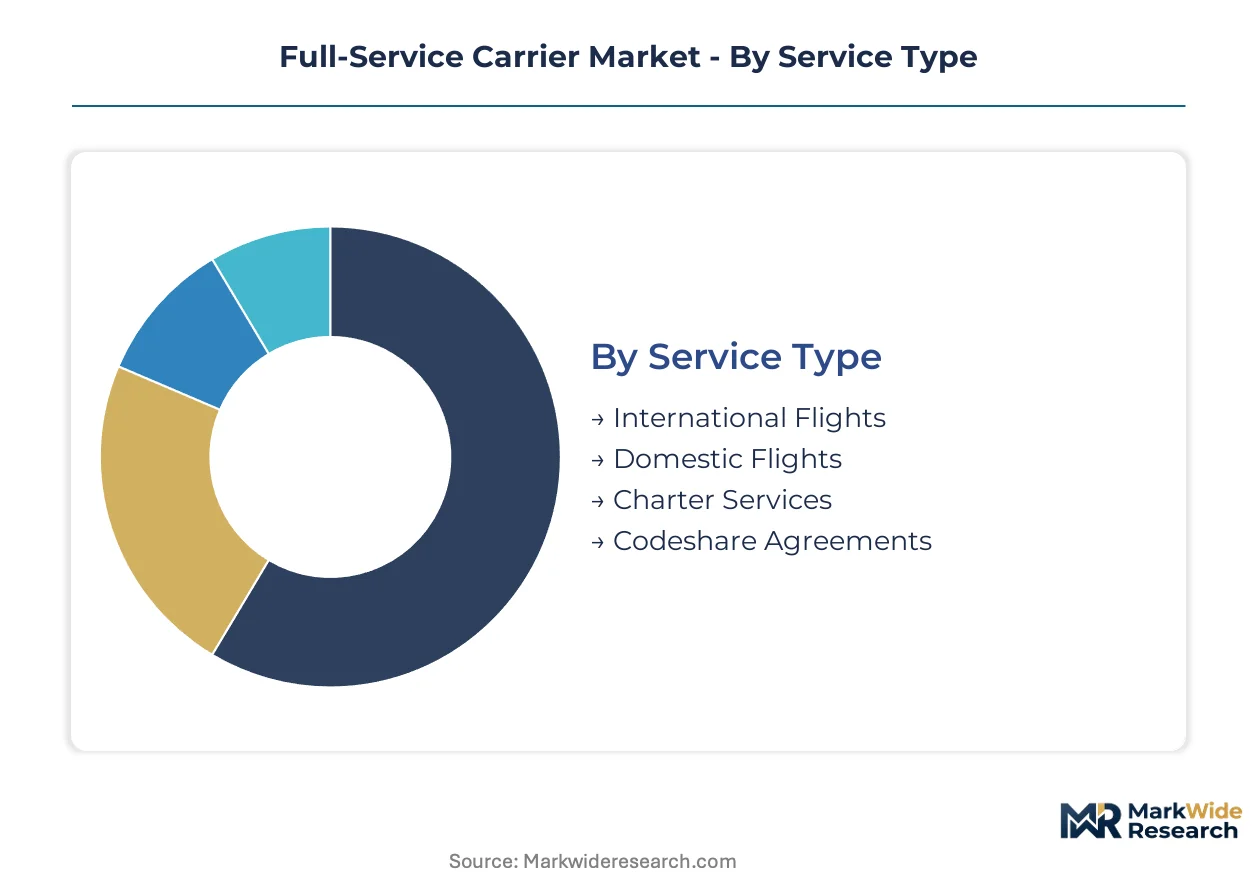
Full-service carriers segment their operations across four critical dimensions that determine capital deployment, crew specialization, and revenue management complexity. Each segmentation axis channels distinct margin profiles through different operational and commercial infrastructures.
Service Type:
International flights flow through interline partnerships and alliance networks, while domestic services concentrate within single-carrier point-to-point systems. Charter and codeshare segments operate through specialized sales channels with divergent yield management protocols.
- International Flights:Long-haul sectors exceeding 3,000 nautical miles deploy wide-body aircraft with lie-flat business seats and first-class suites. Demand concentrates on transatlantic and Asia-North America trunk routes where corporate travel budgets have normalized post-remote-work adoption, driving premium cabin yield recovery.
- Domestic Flights:Hub-and-spoke feeder operations within single countries utilize narrow-body fleets with standardized three-class configurations. Expansion concentrates in the United States, China, and India where trunk route density justifies dedicated crew bases and maintenance infrastructure.
- Charter Services:Non-scheduled operations capture government contracts and sports team movements through dedicated sales teams.
- Codeshare Agreements:Interline partnerships extend network reach without capital deployment through alliance frameworks.
International flights dominate installed base capital allocation. Charter services are where expansion concentrates for margin diversification.
Customer Type:
Yield management systems differentiate pricing architecture across traveler profiles with divergent flexibility requirements and ancillary spending propensity. Corporate contracts anchor forward booking curves while leisure segments fill residual capacity.
- Business Travelers:Corporate account travelers purchasing premium cabins through negotiated annual contracts or spot-market NDC channels. Demand concentrates among United States technology and financial services firms restoring transatlantic travel budgets, compressing yield response windows to weekly cycles.
- Leisure Travelers:Price-sensitive passengers booking economy cabins through online travel agencies with high cancellation flexibility. Expansion concentrates in China's outbound tourism recovery and India's emerging middle-class long-haul demand.
- VIP Clients:High-net-worth individuals purchasing first-class suites and a la carte privacy amenities.
- Group Bookings:Consolidated leisure or corporate blocks managed through specialized sales desks.
Business travelers dominate premium cabin revenue. Leisure segments are climbing the fastest in absolute passenger volume.
Aircraft Type:
Fleet composition determines crew certification requirements, maintenance intervals, and route economics across network architectures. Capital allocation prioritizes wide-body renewal cycles under tightening emissions compliance thresholds.
- Wide-Body Aircraft:Twin-aisle configurations with 250-550 seats dominate Asia-Europe and Asia-North America trunk routes where passenger load factors justify operating economics. Demand concentrates at Emirates, Lufthansa, and American Airlines as these carriers accelerate Pratt & Whitney GTF and Rolls-Royce UltraFan adoption.
- Narrow-Body Aircraft:Single-aisle fleets serve domestic and short-haul international sectors with standardized turnaround protocols. Expansion concentrates in India and Southeast Asia where airport infrastructure constraints favor smaller gauge aircraft.
- Regional Jets:Sub-100-seat aircraft feed hub operations from secondary cities.
- Cargo Aircraft:Dedicated freighter and passenger-to-freighter converted hulls serve e-commerce and pharmaceutical logistics.
Wide-body aircraft dominate capital expenditure. Narrow-body fleets are gaining share fastest in emerging market expansion.
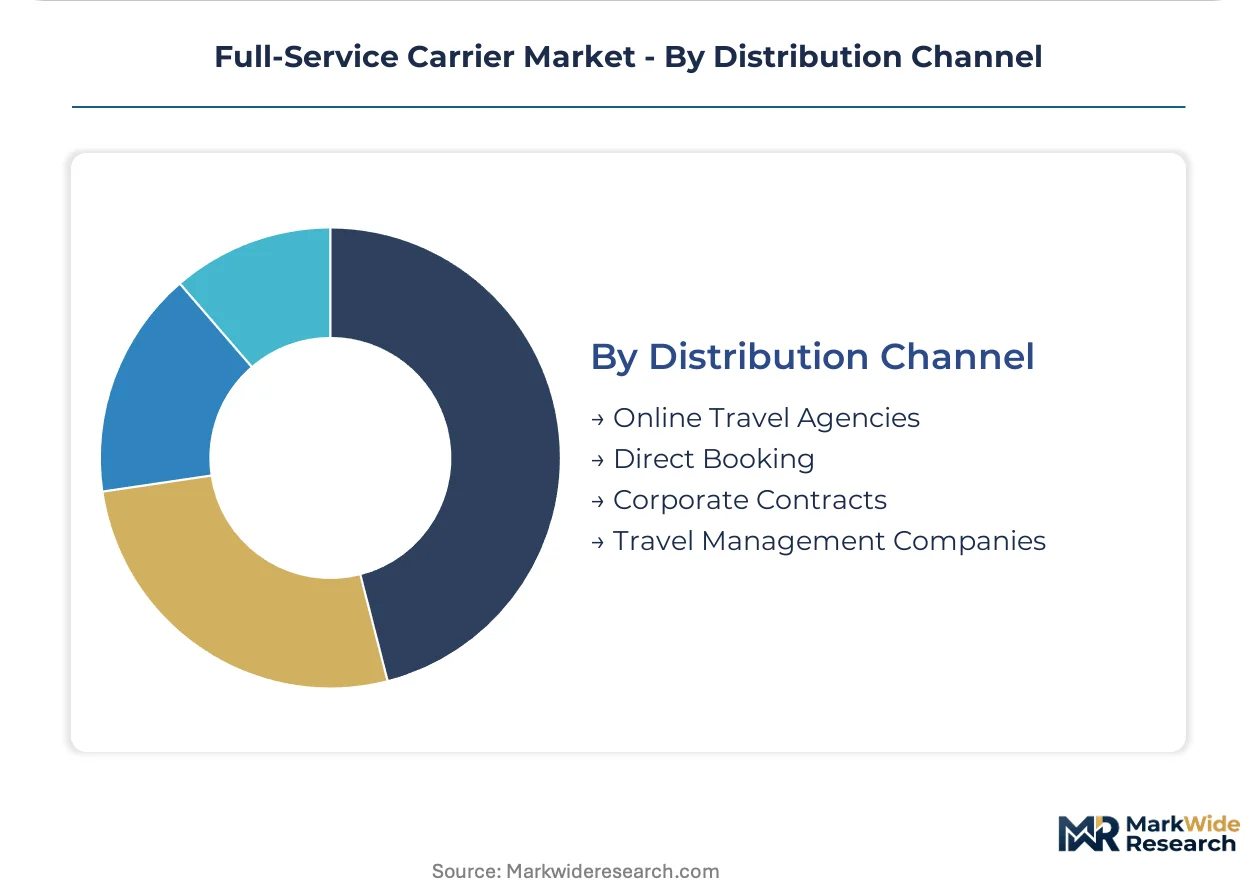
Distribution Channel:
Passenger acquisition fragments away from legacy global distribution systems toward direct digital channels and specialized corporate procurement platforms. Each channel carries distinct commission structures and data ownership terms.
- Direct Booking:Airline-owned websites and mobile applications capturing passenger data for loyalty program enrollment and ancillary upsell. Demand concentrates among United States-based technology sector travelers prioritizing flexibility over negotiated corporate discounts.
- Online Travel Agencies:Third-party platforms aggregating fare comparison with standardized cancellation policies. Expansion concentrates in China's Ctrip and India's MakeMyTrip as these markets recover outbound tourism.
- Corporate Contracts:Negotiated annual volume agreements with multinational travel managers.
- Travel Management Companies:B2B intermediaries managing enterprise travel policy compliance and expense integration.
Direct booking dominates customer lifetime value capture. Online travel agencies are where volume expansion concentrates in emerging markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across geographies: corporate travelers in the United States and United Arab Emirates absorb premium cabin price increases with minimal volume loss, while price-sensitive leisure segments in India and Southeast Asia compress yields on competitive trunk routes.
United States
Technology and financial services corporations in the United States are normalizing transatlantic premium cabin budgets. The FAA enforces pilot duty-time regulations that constrain crew utilization rates. Dallas-Fort Worth and Charlotte anchor American Airlines' joint venture capacity with British Airways.
China
Outbound tourism recovery and middle-class long-haul expansion drive passenger volume. China's Civil Aviation Administration implements slot coordination protocols that constrain foreign carrier network expansion. Beijing and Shanghai Pudong concentrate international wide-body operations for Air China and China Eastern.
Germany
Corporate travel demand through Frankfurt and Munich sustains premium cabin yields on Asia-Europe trunk routes. The EU Green Deal's ReFuelEU Aviation mandate imposes binding sustainable aviation fuel quotas from 2025. Lufthansa's multi-hub German-Austrian-Swiss network architecture differentiates connectivity options.
United Arab Emirates
Dubai's sixth-freedom traffic capture aggregates thin origin-destination pairs into viable wide-body economics across six continents. The General Civil Aviation Authority aligns with ICAO CORSIA carbon offset obligations for international operations. Emirates leverages its hub position for ultra-long-haul capacity deployment.
India
Indira Gandhi International Airport slot expansion and EU bilateral liberalization create first-mover opportunities for Delhi-Europe nonstop services. The Directorate General of Civil Aviation governs route authority and safety compliance. Mumbai and Bangalore secondary city demand feeds emerging long-haul connectivity.
Full-Service Carrier Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in full-service carrier hierarchy. Legacy network carriers with multi-hub architectures compete against geographically concentrated flag carriers for corporate contract share. Two archetypes dominate: Gulf-based sixth-freedom superconnectors and alliance-anchored transatlantic joint venture operators. Competitive moves center on premium cabin reinvestment and sustainable aviation fuel procurement consortium formation.
Among Asia-Pacific state-owned flag carriers, China Southern Airlines and Air China occupy positions within the government-backed network expansion archetype, while Emirates exemplifies the hub-centric superconnector model. American Airlines anchors the transatlantic joint venture tier through oneworld alliance integration. These three represent distinct strategic postures: state-supported domestic market defense, geographic arbitrage through hub positioning, and alliance-anchored corporate contract capture.
| Leading Market Players |
|---|
| China Southern Airlines |
| Air China |
| American Airlines |
| Emirates |
| Lufthansa |
| Delta Air Lines |
| China Eastern Airlines |
| Air France |
| United Airlines |
| Others |
Supply Flow & Price Mechanics
Sustainable aviation fuel substitution for conventional jet kerosene is redrawing procurement geography toward Neste's Singapore and Rotterdam production hubs while inflating fuel cost premiums that compress operating margins across long-haul networks.
Pricing Analysis
Ancillary revenue streams from premium cabin upgrades and loyalty program co-branded credit cards now drive lifetime passenger value beyond base fare capture. Three-tier pricing structure across first, business, and economy cabins segments yield management with corporate contract discounts anchoring the business tier. Pricing pressure stems from unhedged jet fuel exposure amplifying quarterly earnings variance against fixed-yield corporate agreements. Leisure travelers booking through online travel agencies exhibit highest price sensitivity, while VIP clients purchasing first-class suites demonstrate minimal elasticity.
Supply Chain Analysis
Port congestion at Seattle-Tacoma and Charleston is extending engine delivery timelines for Pratt & Whitney GTF powerplants bound for final assembly lines. Wide-body aircraft manufacturing concentrates in the United States, France, and Germany, while avionics and landing gear subsystems source from Japan and the United Kingdom. Supply chains draw from titanium forgings, composite fuselage sections, and semiconductor flight-control chips as critical inputs. Single-source vulnerability around Rolls-Royce UltraFan engine certification timelines threatens 2026-2028 delivery commitments. Distribution runs through lessor intermediaries and direct airline procurement desks with escalating sale-leaseback prevalence.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Full-service carrier economics are approaching a platform inflection where NDC-enabled direct distribution and SAF certificate trading interoperability will separate integrated operators from fragmented competitors.
For Market Incumbents: Shield premium cabin yield through joint venture capacity discipline on transatlantic routes against Gulf carrier sixth-freedom expansion. Deepen backward integration into sustainable aviation fuel procurement consortiums to lock in ReFuelEU Aviation compliance ahead of 2025 mandate ramps. Consolidate maintenance technician training pipelines through proprietary academies to address FAA-certificated mechanic scarcity.
For New Entrants and Emerging Players: Anchor in India's underserved Delhi-Europe nonstop connectivity before bilateral liberalization attracts established hub carriers. Target premium leisure segments with a la carte first-class pricing decoupled from corporate contract dependency. Deploy direct NDC channel acquisition to bypass legacy global distribution system commission structures.
For Investors and Strategic Acquirers: The market sits at a fleet renewal phase that favors carriers with secured 2026-2028 wide-body delivery slots and early SAF supply agreements. Long-term viability across the projection horizon rests on emissions compliance positioning rather than scale alone. Monitor ICAO CORSIA carbon offset price discovery as the inflection signal for margin compression velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Premium Cabin Reinvestment | Lie-flat business seats and first-class suites capture recovering corporate travel budgets at American Airlines and Lufthansa. |
| SAF Procurement Consortium | Airline grouping structures aggregate offtake volumes to secure ten-year Neste supply contracts at fixed premiums. |
| NDC Channel Migration | Direct digital distribution bypasses Sabre and Amadeus commissions while capturing passenger data for loyalty enrollment. |
| Multi-Hub Network Architecture | Lufthansa's German-Austrian-Swiss connectivity differentiation spreads demand across Frankfurt, Munich, Zurich, and Vienna. |
| Sixth-Freedom Hub Expansion | Emirates leverages Dubai's Europe-Asia geographic arbitrage to aggregate thin origin-destination pairs into viable wide-body economics. |
Methodological Framework
Cross-validation between IATA operational statistics and airline association financial disclosures anchors the qualitative findings on yield recovery patterns. Primary interviews with network planning executives, fleet procurement directors, corporate travel managers, and maintenance operations chiefs combined with secondary validation from FAA airworthiness directives, EASA ReFuelEU Aviation regulatory texts, ICAO CORSIA implementation documents, and bilateral air service agreement databases. Bottom-up route-level revenue modeling and top-down industry aggregate triangulation ensure segmentation coherence.
Sensitivity analysis around jet fuel price trajectories and sustainable aviation fuel availability scenarios informs the analytical framework across the modeling period. Segmentation dimensions include service type, customer profile, aircraft gauge, and distribution channel alongside regulatory compliance tier. CAGRs derive from installed base fleet replacement cycles and passenger load factor assumptions calibrated to corporate travel normalization velocity. Forecast inputs incorporate pilot training pipeline constraints and wide-body delivery slot scarcity.
Material uncertainties — geopolitical disruption of SAF supply chains, abrupt CORSIA carbon price spikes, and bilateral air service agreement renegotiations — sit outside the modeled envelope. Forecasts reflect documented assumptions about emissions compliance trajectory and premium cabin demand elasticity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation Services
Multispace Parking Meter Market
Transportation Services
Two Wheeler Rental Market
Transportation Services
Car Rental Market
Transportation Services
India Car Rental Market
Transportation Services
ASEAN Car Rental Market
Transportation Services
Indonesia Car Rental Market
Transportation Services
ASEAN Taxi Market
Transportation Services
Russia Car Rental Market
Transportation Services
Brazil Vehicle Rental Market
Transportation Services
Latin America Tourism Vehicle Rental Market
Transportation Services
Waste Collection Vehicle Market
Transportation Services
Refrigerated Truck Rental Market
Transportation Services
Corporate Employee Transportation Service Market
Transportation Services
United States White Glove Delivery Service Market
Transportation Services
Airport Handling Service Market
Transportation Services
Bulk Transportation Services Market