
 Truck Rental Market | 2026-2036
Truck Rental Market Size, Share, and Industry Trends Forecast 2026-2036
Truck Rental Market Analysis
Telematics integration is fragmenting traditional fleet management into real-time, data-driven asset deployment. U-Haul leverages its self-service network to sustain density advantages in urban relocation corridors. Penske Truck Leasing anchors commercial accounts through dedicated maintenance infrastructure and route optimization tools.
Truck rental denotes the short-term or long-term commercial provision of cargo vehicles ranging from light-duty vans to heavy tractors, typically specified by gross vehicle weight rating, payload capacity, and engine emissions class, serving industrial freight movement, household relocation, and project-based logistics. Light trucks dominate transaction volume due to last-mile delivery proliferation, while heavy trucks command premium rate structures tied to long-haul freight contracts. Logistics companies represent the fastest-expanding end-user category as e-commerce fulfillment networks outsource surge capacity rather than owning dormant assets.
The EPA enforces Tier 4 emissions standards that compel rental fleets to accelerate diesel engine replacements or adopt alternative powertrains, directly elevating capital recovery requirements per unit. The Federal Motor Carrier Safety Administration imposes hours-of-service and electronic logging device mandates that shape how rental providers structure driver-inclusive offerings versus bare chassis leases. Stakeholders must monitor regulatory compliance cost trajectories against utilization rate thresholds to calibrate fleet mix decisions.
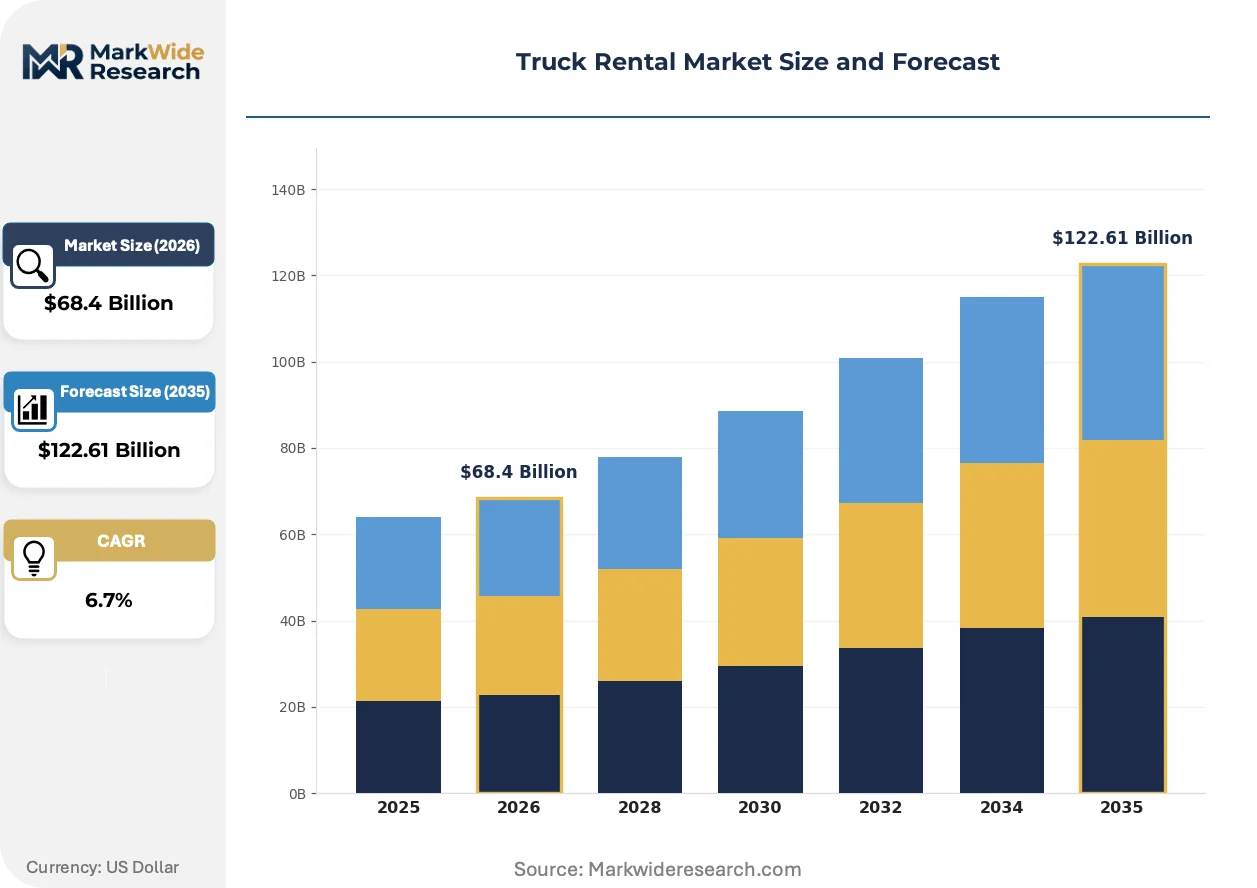
Market Dynamics
Telematics-enabled fleet optimization is compressing rental utilization cycles while EPA Tier 4 compliance costs are restructuring capital deployment across diesel-heavy portfolios.
Growth Catalysts
- Last-mile logistics surge:E-commerce fulfillment networks in the United States Sun Belt are outsourcing surge capacity rather than owning dormant assets, expanding transaction density in urban freight corridors.
- Electronic Logging Device mandates:FMCSA hours-of-service enforcement is compelling commercial fleets toward rental models that bundle driver-inclusive offerings versus bare chassis leases.
- Alternative powertrain pilots:Battery-electric and hydrogen fuel cell demonstrations are qualifying for state-level zero-emission incentives in California and New York, accelerating fleet diversification trials.
Market Restraints
- Emissions compliance capital intensity:Tier 4 diesel retrofits and alternative powertrain premiums are elevating per-unit recovery thresholds, squeezing returns on low-utilization assets.
- Semiconductor supply concentration:Telematics control module shortages originating from East Asian foundries are extending vehicle delivery timelines and inflating electronic component costs.
- Driver qualification scarcity:Commercial driver's license pipeline constraints are limiting expansion of driver-inclusive rental offerings regardless of chassis availability.
Strategic Opportunities
- Mexico manufacturing corridor penetration:Nearshoring-driven freight volumes along the Monterrey-Laredo axis are creating unmet demand for cross-border medium-duty rental capacity.
- Carbon accounting integration:EU CSRD scope 3 disclosure requirements are pushing multinational logistics firms toward rental partners with verified emissions tracking infrastructure.
- Autonomous yard tractor convergence:Lidar and computer vision technologies are hybridizing with traditional diesel chassis for terminal automation pilots at major port complexes.
Industry Challenges
- Telematics platform integration:Legacy fleet management systems require costly API overhauls to ingest real-time diagnostic feeds from mixed-vendor rental pools.
- Technician certification lag:High-voltage battery and fuel cell maintenance credentials are outpacing vocational training program output, constraining service network expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Truck Rental Market |
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $122.61 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Light Trucks, Heavy Trucks, Medium Trucks, Pickup Trucks End User: Individuals, Construction Firms, Event Organizers, Logistics Companies Rental Duration: Short-Term, Long-Term, Daily, Weekly Distribution Channel: Online Platforms, Traditional Rentals, Direct Sales, Corporate Accounts |
| Companies Covered | Budget Truck Rental, Hertz, U-Haul, National Car Rental, Avis Budget Group, Penske Truck Leasing, Enterprise Holdings, Alamo Rent A Car, Ryder System, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Truck Rental Market Emerging Trajectories
Data-driven asset deployment is fragmenting traditional fleet ownership models while regulatory pressure accelerates powertrain diversification and procurement patterns favor flexible capacity over fixed investment.
Digital twin simulation is hybridizing with physical fleet operations, enabling rental providers to model utilization scenarios before capital commitment. Third-party logistics firms are adopting these tools fastest, compressing their vehicle specification cycles from annual to quarterly reviews. The structural consequence is collapsing residual value predictability for conventional diesel assets.
EPA enforcement of Tier 4 Final standards is compelling rental fleets to accelerate engine replacement schedules or absorb alternative powertrain premiums. California's Advanced Clean Trucks rule is extending these obligations to medium-duty segments earlier than federal timelines. Heavy-haul providers serving port drayage corridors are responding with battery-electric terminal tractor pilots.
Subscription-based capacity contracts are displacing traditional term leases among project logistics operators, unbundling maintenance and insurance into variable cost structures. Equipment lessors are consolidating these offerings through platform marketplaces rather than direct sales forces. This shift is most visible in Texas and Florida construction corridors where project duration uncertainty is highest.
Truck Rental Market Segmentation
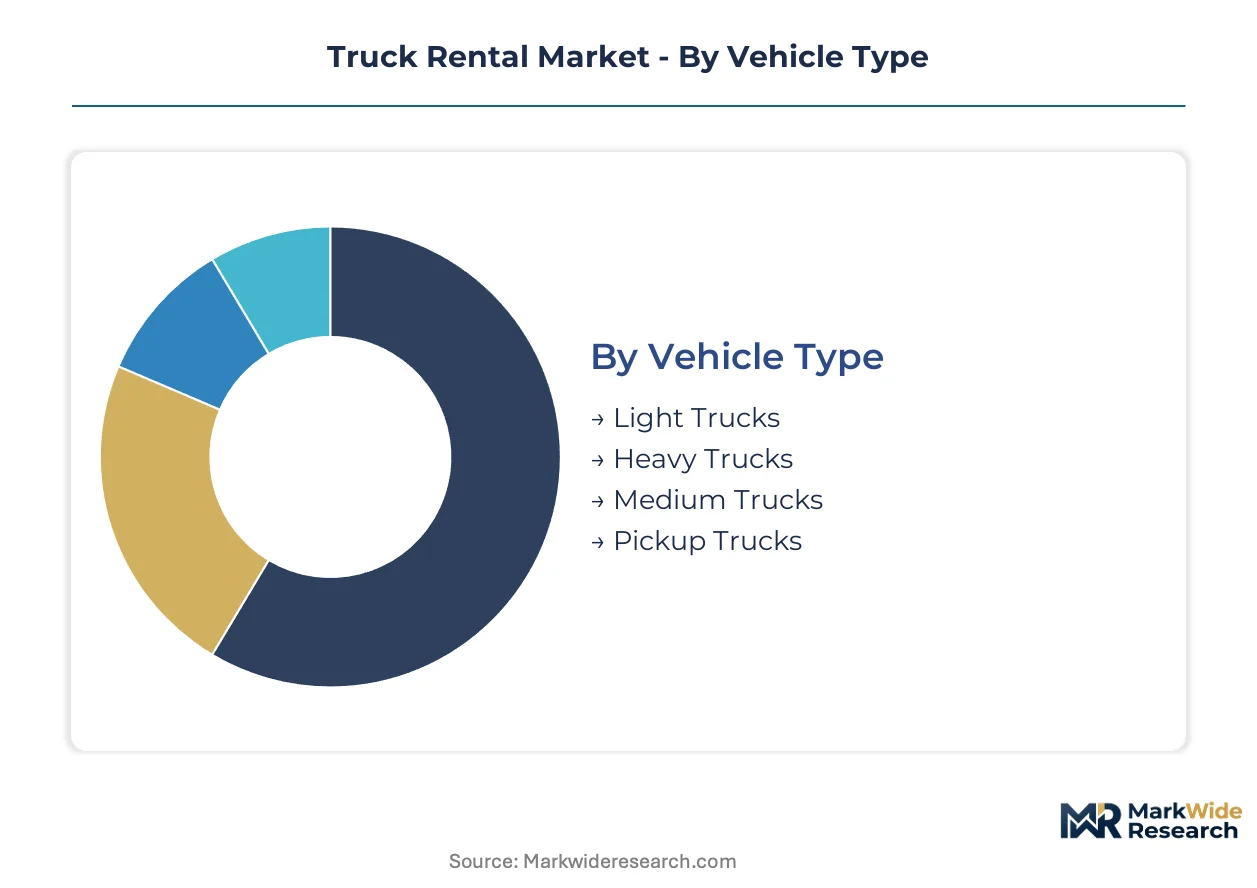
Truck rental segmentation reflects divergent asset utilization economics across payload classes and customer operational models. Fleet providers calibrate depreciation schedules, maintenance protocols, and telematics investments differently for each category, creating distinct competitive arenas within the broader market.
Vehicle Type:
Use-case spectrum spans last-mile parcel delivery through interstate freight corridors, with gross vehicle weight rating determining regulatory compliance burdens and capital recovery timelines.
- Light Trucks:Class 1-2 vehicles with payload capacities below 6,350 pounds dominate transaction volume. E-commerce fulfillment networks in the United States Sun Belt urban corridors outsource surge capacity rather than owning dormant assets, compressing rental cycles.
- Heavy Trucks:Class 7-8 tractors with diesel powertrains exceeding 26,000 pounds GVWR command premium rate structures. Long-haul freight contracts along the Monterrey-Laredo manufacturing corridor drive utilization intensity despite elevated EPA Tier 4 compliance costs.
- Medium Trucks:Class 3-6 box trucks and straight trucks serve regional distribution loops with moderate payload requirements.
- Pickup Trucks:Light-duty consumer and commercial utility vehicles address household relocation and small contractor needs.
The dominant share belongs to Light Trucks, while Heavy Trucks is closing the gap fastest.
End User:
Customer type determines contract structure complexity, with commercial accounts demanding integrated telematics and maintenance bundling versus transactional individual rentals.
- Logistics Companies:Third-party fulfillment operators and freight brokers represent the steepest expansion trajectory. These firms substitute fixed fleet ownership with variable capacity contracts to match e-commerce demand volatility, particularly across Texas and Florida distribution hubs.
- Construction Firms:Project-based contractors require seasonal equipment access without residual value risk. Subscription-based capacity contracts are displacing traditional term leases in these segments, unbundling maintenance and insurance into variable cost structures.
- Individuals:Household relocation and DIY transport needs drive short-term rental density.
- Event Organizers:Temporary logistics coordination for exhibitions and entertainment productions generates sporadic demand spikes.
Logistics Companies command the largest revenue pool, though Construction Firms are gaining share fastest through flexible contracting adoption.
Rental Duration:
Contract length directly shapes fleet turnover economics and residual value exposure for rental providers.
- Long-Term:Multi-month and annual leases anchor commercial fleet replacement strategies. Corporate accounts leverage these structures to defer capital expenditure while accessing EPA-compliant powertrains without ownership risk.
- Short-Term:Hourly and daily rentals maximize asset velocity through high-turnover consumer channels. Digital platform integration enables real-time availability matching against demand surges.
- Daily:Single-day contracts concentrate in household relocation and small business logistics.
- Weekly:Intermediate duration serves project contractors with defined but brief equipment needs.
Long-Term contracts generate the most predictable revenue streams, yet Short-Term is expanding most quickly through platform marketplace consolidation.
Distribution Channel:
Channel selection determines customer acquisition cost structures and service bundling capabilities.
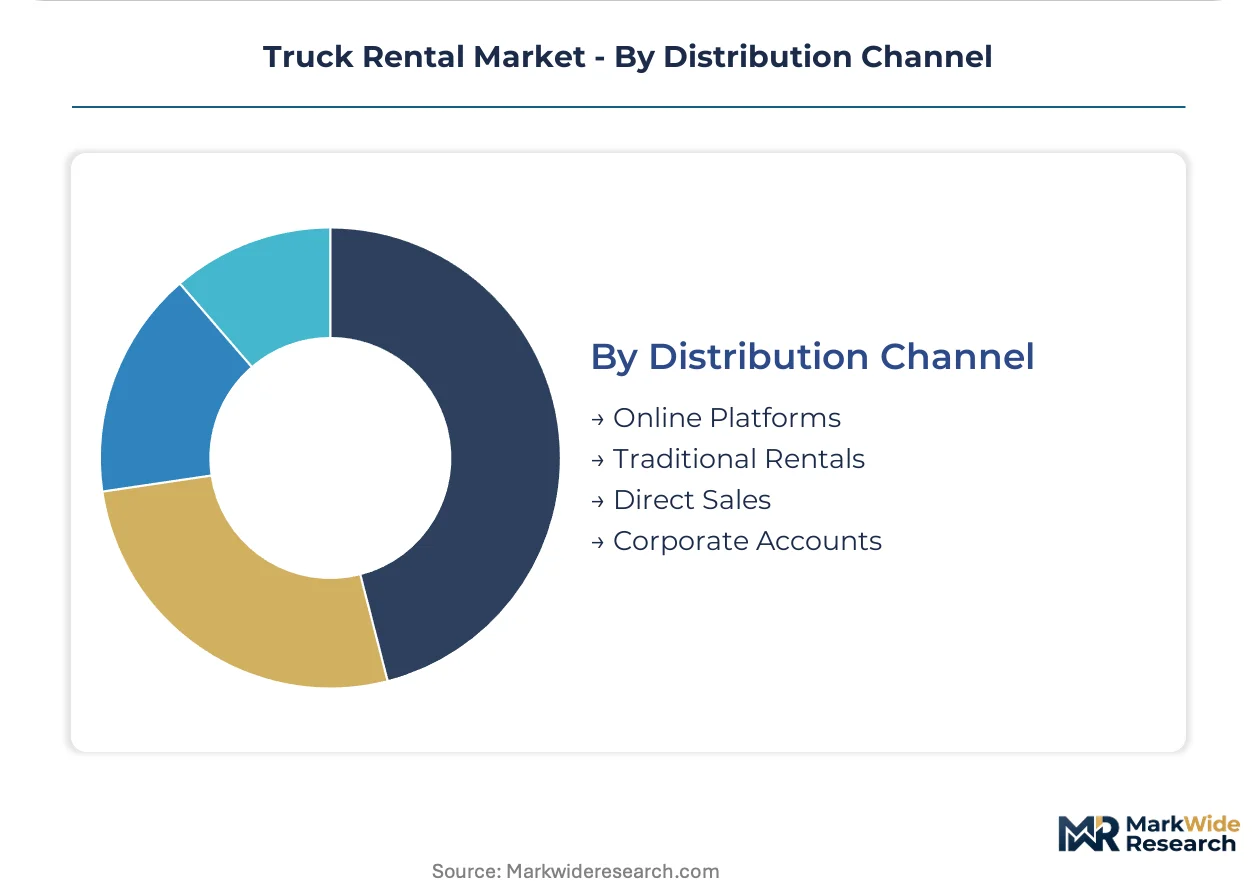
- Online Platforms:Digital marketplaces aggregate fragmented supply and enable price-transparent comparison. Equipment lessors are consolidating subscription offerings through these channels rather than direct sales forces, particularly visible in Texas and Florida construction corridors.
- Corporate Accounts:Dedicated B2B relationships embed route optimization tools and maintenance infrastructure. Penske Truck Leasing anchors this segment through integrated fleet management services.
- Traditional Rentals:Physical branch networks sustain density advantages in urban relocation corridors through self-service models.
- Direct Sales:Manufacturer-captive rental arms and specialized lessors bypass intermediary platforms.
Corporate Accounts retain the deepest revenue concentration, while Online Platforms are climbing the fastest through marketplace aggregation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Logistics companies and construction contractors dominate truck rental procurement across North American, European, and Asia-Pacific corridors. Fleet outsourcing intensity varies sharply by regulatory environment and industrial density. Mexico's nearshoring corridors and Germany's logistics hubs anchor contrasting demand archetypes.
United States
E-commerce fulfillment networks in Texas and Florida distribution hubs outsource surge capacity through variable contracts rather than owning dormant assets. EPA Tier 4 emissions standards and FMCSA electronic logging device mandates reshape fleet composition requirements. The Sun Belt urban freight corridors concentrate transaction density as last-mile delivery proliferation accelerates rental cycle compression.
Germany
Industrial freight brokers and automotive suppliers drive medium-duty rental demand across the Rhine-Ruhr and Bavarian manufacturing belts. EU CSRD scope 3 disclosure requirements push logistics firms toward rental partners with verified emissions tracking infrastructure. The Port of Hamburg anchors heavy-haul electrification pilots as battery-electric terminal tractors enter commercial deployment.
Mexico
Nearshoring-driven manufacturing relocation from Asia generates cross-border freight volumes along the Monterrey-Laredo axis. Mexican federal transport regulations and state-level environmental programs shape fleet modernization timelines. Nuevo León's industrial parks concentrate medium-duty rental demand as automotive and electronics manufacturers expand regional distribution networks.
Canada
Oil sands project logistics and prairie agricultural distribution sustain seasonal heavy-truck rental cycles. Transport Canada commercial vehicle safety regulations and provincial carbon pricing schemes influence fleet replacement decisions. Alberta's energy corridor and Ontario's Golden Horseshoe manufacturing belt represent divergent demand concentrations.
United Kingdom
Post-Brexit customs clearance complexity and construction sector volatility expand short-term rental adoption. UK DVSA operator licensing requirements and London's ultra-low emission zone penalties accelerate alternative powertrain trials. The Midlands logistics triangle and Greater Manchester distribution hubs concentrate fleet outsourcing activity.
Truck Rental Market Vendor Landscape
Channel-controlling players compete with product-specialist players across fragmented national markets. The vendor base organizes around three strategic archetypes: network-density operators sustaining urban relocation corridors, integrated fleet managers embedding telematics and maintenance bundling, and platform aggregators consolidating subscription capacity contracts. Competitive moves concentrate on telematics platform integration and alternative powertrain fleet diversification.
Within the network-density archetype, U-Haul leverages self-service infrastructure advantages. Penske Truck Leasing anchors the integrated fleet management tier through dedicated maintenance networks. Ryder System occupies a position bridging commercial account services and supply chain solutions. These three exemplify divergent capital deployment strategies across the same regulatory and demand environment.
| Leading Market Players |
|---|
| Budget Truck Rental |
| Hertz |
| U-Haul |
| National Car Rental |
| Avis Budget Group |
| Penske Truck Leasing |
| Enterprise Holdings |
| Alamo Rent A Car |
| Ryder System |
| Others |
Supply Flow & Price Mechanics
Detroit's chassis manufacturing cluster concentrates diesel powertrain capacity, amplifying pricing leverage for Tier 4-compliant heavy truck lessors serving cross-border freight corridors. Fleet providers pass through EPA-mandated engine premiums via indexed fuel surcharge mechanisms, while telematics bundling creates rate separation between bare chassis and driver-inclusive offerings.
Pricing Analysis
Cost-plus contracts indexed to diesel futures and EPA compliance cost schedules dominate commercial fleet agreements. Three-tier pricing structure across premium, standard, and economy levels separates telematics-enabled integrated offerings from bare chassis rentals and aged fleet clearance units. Pricing pressure stems from alternative powertrain capital premiums compressing returns on low-utilization assets. Logistics companies exhibit lowest price sensitivity due to operational cost pass-through mechanisms, while construction contractors demand maximum flexibility through unbundled variable structures.
Supply Chain Analysis
Export control restrictions on advanced telematics control modules and lidar sensor arrays constrain fleet modernization timelines for North American lessors. Manufacturing concentrates in Mexico for chassis assembly, Germany for precision diesel components, and South Korea for battery-electric powertrain modules. Critical dependencies include semiconductor foundry output, high-grade steel coil, and EPA-certified aftertreatment systems. Single-source vulnerability in East Asian chip fabrication creates delivery uncertainty. Distribution runs through corporate account direct relationships, platform marketplace aggregation, and self-service branch networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Truck rental economics are shifting toward platform-mediated capacity markets as telematics interoperability enables real-time asset pooling across competing fleet operators.
For Market Incumbents: Entrench density advantages in Sun Belt urban corridors through accelerated telematics platform integration, defending against platform aggregators unbundling maintenance and insurance into variable subscription structures. Prioritize backward integration into high-voltage battery service networks to capture alternative powertrain maintenance margins before technician certification scarcity constrains expansion. For New Entrants and Emerging Players: Establish a beachhead in Mexico's Monterrey-Laredo nearshoring corridor where cross-border medium-duty capacity shortages outmatch incumbent fleet positioning. Target construction logistics operators in Texas and Florida with subscription-based capacity contracts that absorb project duration uncertainty through unbundled cost structures. Deploy digital-native platform interfaces to bypass legacy branch infrastructure requirements. For Investors and Strategic Acquirers: Long-term, this sits as a fleet-as-a-service infrastructure play because logistics outsourcing intensity is displacing fixed asset ownership across e-commerce fulfillment networks. Acquisition targets should display verified emissions tracking infrastructure aligned with EU CSRD scope 3 disclosure requirements. Monitor state-level zero-emission incentive program expansion as the signal indicating alternative powertrain fleet value inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Telematics Platform Integration | Enables real-time asset deployment across mixed-vendor rental pools for logistics clients. |
| Alternative Powertrain Fleet Diversification | Qualifies California and New York operators for state zero-emission incentive programs. |
| Cross-Border Capacity Expansion | Captures nearshoring-driven freight volumes along the Monterrey-Laredo manufacturing corridor. |
| Subscription Contract Unbundling | Absorbs construction sector project duration uncertainty through variable cost structures. |
| Technician Certification Investment | Secures high-voltage battery and fuel cell maintenance capabilities before training pipeline constraints. |
Methodological Framework
Cross-validation between fleet operator interviews and regulatory filing analysis anchors the qualitative findings in this study. Primary fieldwork engaged fleet procurement directors, telematics platform engineers, EPA compliance officers, and third-party logistics contract managers across North American corridors. Secondary sources included FMCSA enforcement data, EPA emissions certification databases, state-level incentive program filings, and customs trade records for cross-border chassis movements. Bottom-up rental transaction modeling and top-down fleet capacity estimates were reconciled through iterative triangulation.
Calibration against historical utilization rate trajectories and powertrain replacement cycles shaped the analytical framework across the projection horizon. Segmentation dimensions encompassed vehicle class by GVWR, end-user operational model, contract duration structure, and distribution channel type. CAGRs were derived from regression analysis of fleet outsourcing intensity against e-commerce fulfillment network expansion. Industry-specific inputs included EPA Tier 4 compliance cost schedules and electronic logging device mandate implementation timelines.
Stress conditions across diesel price volatility, semiconductor delivery timelines, and commercial driver license pipeline constraints were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and alternative powertrain cost reduction curves. Material shifts in EPA emissions standard acceleration or federal hours-of-service rule modifications would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation Services
MUV Rental Market
Transportation Services
Drayage Services Market
Transportation Services
Europe Vehicle Rental Market
Transportation Services
North America International Express Service Market
Transportation Services
India Two-Wheelers Rental Market
Transportation Services
Online Bus Ticketing Service Market
Transportation Services
ASEAN Car Rental Market
Transportation Services
Latin America Tourism Vehicle Rental Market
Transportation Services
Sanitation Vehicle Market
Transportation Services
Bulk Transportation Services Market
Transportation Services
Europe Refrigerated Truck Rental Market
Transportation Services
Taxi and Ride-Hailing Services Market
Transportation Services
Germany Car Rental Market
Transportation Services
Middle East Car Rental Market
Transportation Services
Peer-To-Peer (P2P) Car-Sharing Market
Transportation Services
Australia Taxi Market