
 Bulk Transportation Services Market | 2026-2036
Bulk Transportation Services Market Size, Share, and Industry Trends Forecast 2026-2036
Bulk Transportation Services Market Insights
The gap between premium and commodity tiers in bulk transportation is recalibrating around fuel efficiency and digital cargo tracking. Maersk Line leverages its integrated logistics platform to command premium rates on controlled-temperature dry bulk shipments. Oldendorff Carriers anchors its position through massive scale in the Capesize segment, moving iron ore from Brazil to East Asian ports. Golden Ocean Group Limited specializes in modern, fuel-efficient vessels that meet tightening environmental standards.
Bulk transportation services encompass the large-scale movement of unpackaged commodities—minerals, grains, liquids, and break bulk cargo—using specialized vessels, railcars, tanker trucks, and conveyor systems designed for volumes exceeding 10,000 metric tons per shipment. The primary purpose centers on connecting extraction and production sites with processing facilities, power plants, and manufacturing centers through continuous, cost-optimized flow. Ocean freight dominates value generation due to the intercontinental distances of mineral and energy trade, while liquid bulk commands margin premiums from chemical and petroleum shippers requiring double-hull tankers and vapor recovery systems. Rail freight sustains competitive positioning in continental corridors where pipeline alternatives remain absent, particularly for grain and coal movements across North American and Eurasian networks.
The International Maritime Organization enforces carbon intensity indicators that compel fleet renewal or engine modification for continued market access. The US Coast Guard and EPA jointly regulate ballast water treatment and vessel emissions in American waters, raising compliance costs for operators serving Gulf Coast petrochemical terminals. Stakeholders must monitor the divergence between regulatory compliance investments and the pricing power needed to recover them across contract structures.
Market Dynamics
The International Maritime Organization's carbon intensity regulations are forcing a bifurcation between compliant modern fleets and aging tonnage facing accelerated retirement, compressing effective vessel supply while reshaping contract pricing power toward fuel-efficient operators.
Growth Catalysts
- IMO CII Compliance Deadlines:The International Maritime Organization's carbon intensity indicator mandates are accelerating fleet renewal investments, creating pull for newbuild Capesize and VLOC vessels with dual-fuel engine configurations.
- Australian Iron Ore Export Expansion:Mining operations in Western Australia's Pilbara region are scaling port throughput capacity, generating sustained demand for dedicated ocean freight contracts on the Australia-China corridor.
- Digital Cargo Tracking Platforms:Real-time bulk cargo monitoring systems using IoT sensors and blockchain verification are reducing demurrage disputes and enabling premium pricing for transparency-guaranteed shipments.
Market Restraints
- Steel Price Volatility:Fluctuations in global steel prices directly impact newbuild vessel costs, constraining fleet expansion timelines for mid-size operators dependent on external financing.
- Shipyard Concentration Risk:Over 70% of bulk carrier construction concentrates in Chinese and South Korean shipyards, creating supply bottlenecks and extended delivery schedules during order surges.
- Limited Alternative Fuel Infrastructure:Ammonia and methanol bunkering networks remain underdeveloped across major bulk ports, trapping operators in transitional fuel strategies with uncertain regulatory acceptance.
Strategic Opportunities
- Green Corridor Development:The Australia-Japan iron ore shipping route is emerging as a testbed for zero-emission bulk transport, with port authorities in Port Hedland and Port of Kobe coordinating ammonia bunkering infrastructure investments.
- Integrated Logistics Bundling:End-to-end bulk supply chain management combining ocean freight with last-mile rail and conveyor systems is capturing margin from mining companies seeking single-contractor accountability.
- EU Emissions Trading System Inclusion:Maritime's phased entry into the EU ETS from 2024 is creating compliance service demand for emissions verification, carbon offset procurement, and voyage optimization consulting.
Industry Challenges
- Maritime Decarbonization Skill Shortage:The transition to dual-fuel and alternative propulsion systems has outpaced training pipeline capacity, creating acute shortages of certified marine engineers and vessel superintendents.
- Ballast Water Treatment Retrofit Backlogs:US Coast Guard and EPA compliance deadlines for ballast water management systems have overwhelmed installation yard capacity, forcing operational downtime for scheduled upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bulk Transportation Services Market |
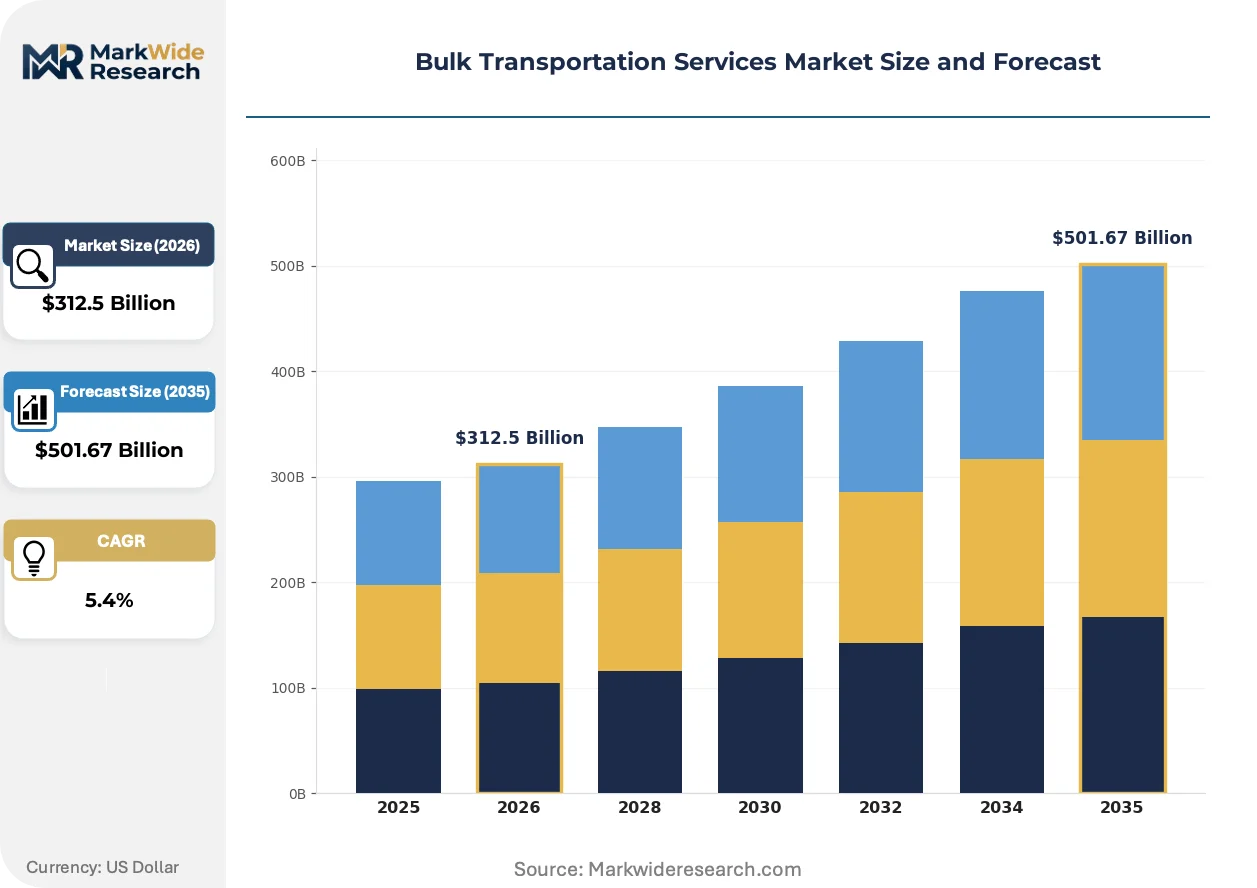
| Market Size in 2026 | $312.5 Billion |
| Market Size in 2035 | $501.67 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Road Freight, Rail Freight, Air Freight, Ocean Freight Mode: Liquid, Dry Bulk, Containerized, Break Bulk Industry Vertical: Agriculture, Construction, Manufacturing, Mining Customer Type: Businesses, Government, Non-Profits, Individuals |
| Companies Covered | Maersk Line, COSCO Shipping, Star Bulk Carriers Corp., Pacific Basin Shipping Limited, Hapag-Lloyd, Oldendorff Carriers, Golden Ocean Group Limited, American Commercial Barge Line, Genco Shipping and Trading, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bulk Transportation Services Market Trends and Innovations
Digitalization and alternative fuel pathways are converging to redefine operational economics in bulk transportation, compressing the competitive advantage window for traditional fuel-heavy fleets while elevating data-rich service models.
Wind-assisted propulsion technology is modularizing bulk carrier design architectures. Flettner rotor and rigid sail systems from manufacturers like Norsepower and Anemoi Marine are being retrofitted onto existing Capesize vessels by operators seeking fuel consumption reductions of 5-20% without engine replacement. Mining majors including BHP and Rio Tinto are inserting wind-ready specifications into newbuild tenders, accelerating adoption timelines from pilot to fleet standard within five-year procurement cycles.
The European Union's Fit for 55 regulatory package is extending emissions trading to maritime transport on a phased basis. This policy expansion imposes direct carbon cost liabilities on bulk carriers calling at EU ports, forcing operators to either absorb compliance costs or embed carbon pricing into freight contracts. Brazilian iron ore exporters to European steel mills are most exposed, with charter parties increasingly splitting EU Allowance obligations between shipowners and cargo interests.
Steel mills and power generators are consolidating procurement through long-term offtake agreements that bundle freight with commodity supply. Chinese state-owned enterprises now favor ten to fifteen-year COA structures over spot market exposure, transferring volume risk to vessel operators in exchange for rate stability. This contractual compression is most pronounced in coking coal movements from Queensland to Jingtang and Caofeidian ports, where integrated miners like Glencore and BHP have aligned shipping terms with metallurgical coal supply commitments.
Bulk Transportation Services Market Segmentation
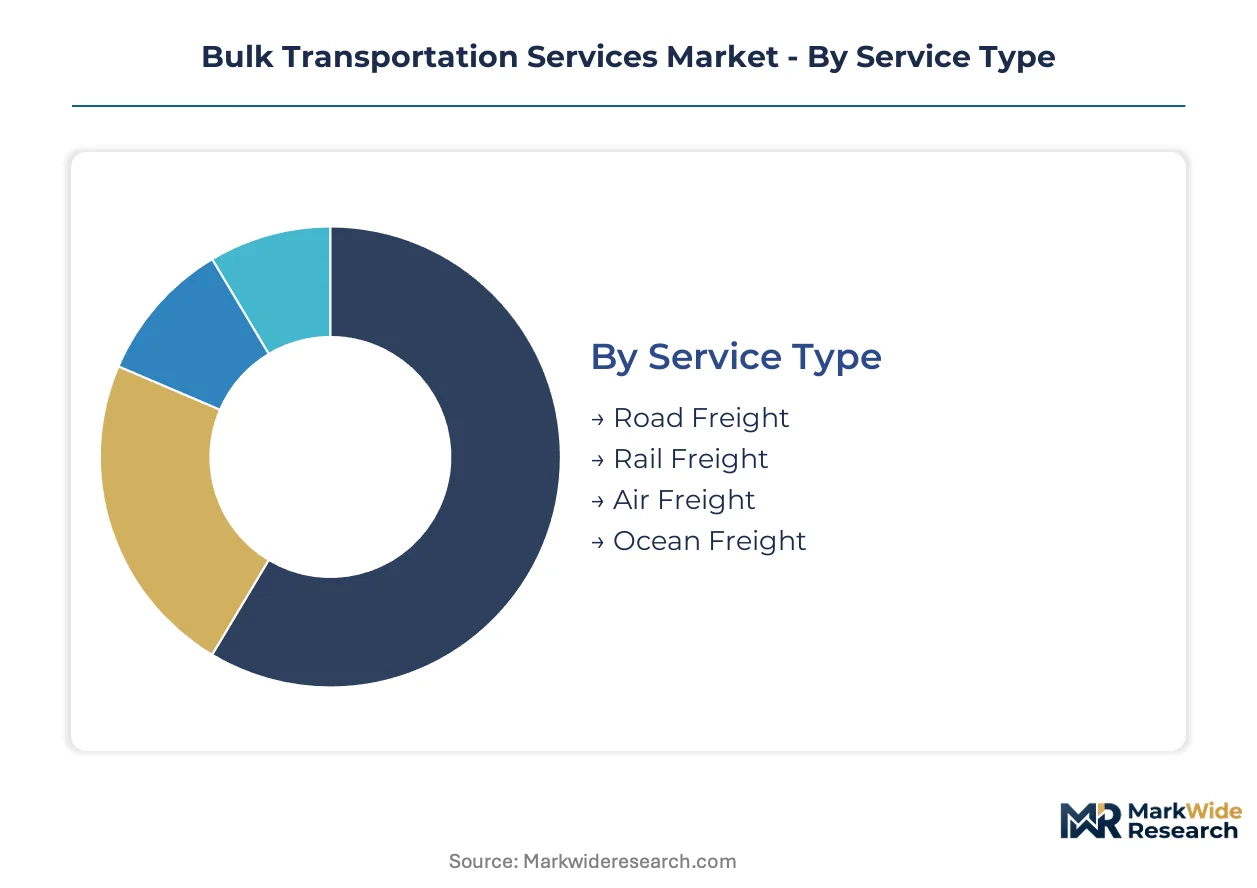
Segmentation in bulk transportation services reveals how capital intensity and regulatory pressure distribute differently across operational modes. Understanding these divisions exposes where fleet renewal investments concentrate and which service tiers command sustainable margin.
Service Type:
Replacement cycles vary dramatically across surface and air modalities, with environmental compliance acting as the forcing mechanism for upgrade decisions.
- Road Freight:Tanker trucks and specialized trailers for liquid and dry commodities operate on 7-10 year replacement schedules. Australian mining corridors and Brazilian agricultural belts are driving demand for Euro VI-compliant tractor units with telematics integration.
- Rail Freight:Hopper cars and tank wagons move grains, coal, and chemicals across continental networks. North American Class I railroads are retiring legacy coal hoppers while expanding covered grain car fleets to serve export terminals on the US Gulf Coast.
- Air Freight:Charter cargo operations for time-critical bulk shipments including perishables and high-value minerals. Limited to niche applications where velocity outweighs unit cost constraints.
- Ocean Freight:Capesize and VLOC vessels dominate intercontinental mineral trade. IMO carbon intensity regulations are compressing effective supply as older tonnage faces accelerated retirement.
Ocean Freight sits at the top of the volume ranking, with Rail Freight climbing the fastest as mining companies seek lower-carbon alternatives to trucking.
Mode:
Physical state of cargo dictates vessel and vehicle specifications, with liquid and dry bulk representing divergent capital deployment strategies.
- Liquid:Double-hull tankers and chemical carriers with vapor recovery systems. Demand concentrates from petrochemical shippers moving refined products from US Gulf Coast terminals to European and Asian ports.
- Dry Bulk:Unpackaged commodities including iron ore, coal, and grains moved in open-hold vessels. Chinese steel mills and power generators anchor procurement through long-term contracts from Australian and Brazilian export terminals.
- Containerized:Standardized box movements for processed commodities and intermediate goods. Offers modal flexibility but sacrifices loading efficiency for bulk commodities.
- Break Bulk:Individual heavy or oversized cargo pieces requiring specialized handling. Project cargo for construction and energy infrastructure dominates this segment.
Dry Bulk generates the highest absolute tonnage, with Liquid capturing the steepest margin expansion from chemical and petroleum shippers.
Industry Vertical:
End-use concentration determines route density and contract duration, with extraction industries favoring decade-long offtake structures.
- Mining:Iron ore, coal, and bauxite movements from extraction sites to processing facilities and export terminals. Pilbara region in Western Australia and Carajás in Brazil anchor global volume.
- Agriculture:Grain and oilseed flows from production belts to export elevators and domestic processors. US Midwest-to-Gulf corridors and Ukrainian Black Sea routes remain critical.
- Construction:Cement, aggregates, and steel movements supporting infrastructure development. Urbanization in Southeast Asian markets drives regional demand.
- Manufacturing:Raw material inputs and finished goods distribution for industrial production. Just-in-time requirements favor multimodal solutions.
Mining commands the longest contract durations, with Agriculture expanding most quickly as food security concerns reshape government procurement priorities.
Customer Type:
Procurement sophistication varies sharply between institutional buyers and fragmented private demand, with volume scale determining pricing leverage.
- Businesses:Mining majors, commodity traders, and industrial manufacturers with dedicated logistics functions. BHP and Rio Tinto negotiate multi-year COAs with embedded fuel adjustment clauses.
- Government:Strategic reserve movements, military logistics, and public infrastructure materials. Energy security mandates drive state-controlled procurement in China and India.
- Non-Profits:Humanitarian food aid and emergency relief cargo. World Food Programme contracts represent concentrated but irregular demand.
- Individuals:Minimal direct participation due to scale requirements; limited to specialty agricultural shipments and small-scale construction materials.
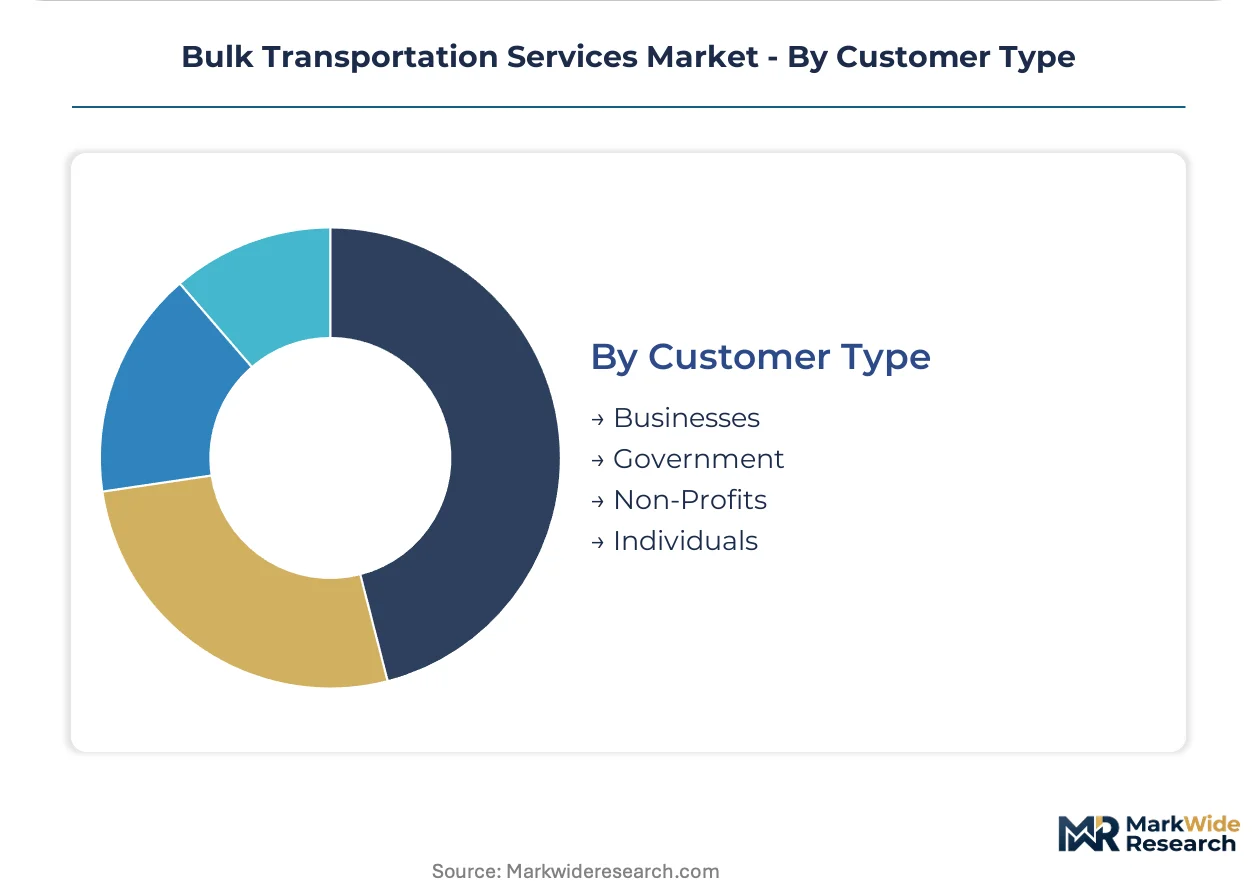
Businesses account for the dominant revenue share, with Government procurement gaining share fastest through strategic mineral stockpiling programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Marine engineering talent pools in Hamburg, Singapore, and Shanghai anchor the operational command centers for bulk fleet management. These concentrations of certified vessel superintendents and dual-fuel engine specialists determine where regulatory compliance investments translate into competitive positioning.
China
Shanghai Port Authority processes the world's largest dry bulk throughput volumes, connecting Australian iron ore with steel mills along the Yangtze River. The Ministry of Ecology and Environment enforces domestic emission control area standards that exceed IMO baselines for vessels calling at Chinese ports. Qingdao and Tianjin anchor the northern import corridor where state-owned steel enterprises negotiate decade-long contract of affreightment structures.
Australia
Pilbara mining operations in Western Australia generate sustained demand for Capesize and VLOC vessel deployments on the Australia-China route. The Australian Maritime Safety Authority implements stringent ballast water management protocols aligned with but exceeding international standards. Port Hedland maintains the world's largest bulk export terminal capacity, with planned ammonia bunkering infrastructure supporting green corridor development to Japan.
Brazil
Carajás iron ore complex and Itaqui port terminals sustain long-haul Atlantic voyages to East Asian steel mills. The National Waterway Transportation Agency regulates inland waterway connections between mining regions and coastal export facilities. São Paulo-based commodity trading houses coordinate integrated logistics contracts bundling ocean freight with terminal handling services.
Japan
Kobe and Chiba steel mill complexes anchor import demand for Australian and Brazilian metallurgical coal and iron ore. The Ministry of Economy, Trade and Industry sponsors green corridor pilot programs testing ammonia-fueled bulk carriers on established trade lanes. Nagoya port authorities coordinate with Australian counterparts on zero-emission shipping infrastructure investments.
Germany
Hamburg and Bremen harbor clusters concentrate maritime insurance, classification society headquarters, and fleet management operations for European bulk operators. The Federal Maritime and Hydrographic Agency enforces EU Emissions Trading System compliance for vessels calling at German ports. Rostock terminal operators are expanding grain handling capacity to serve Black Sea alternative routing demand.
Bulk Transportation Services Market Competitive Landscape
Top-tier vendors anchor integrated logistics platforms commanding premium contract structures, while mid-scale operators compete on vessel efficiency and route specialization. The market structure reflects consolidation pressure from fuel compliance costs and digital investment requirements. Three archetypes dominate: diversified container-bulk hybrids, pure-play dry bulk specialists, and integrated mining-house fleets. Competitive moves center on fleet renewal acceleration and strategic port terminal partnerships securing dedicated berth access.
Among diversified container-bulk hybrids, Maersk Line exemplifies platform-based service bundling, while COSCO Shipping represents state-backed scale deployment. Within pure-play dry bulk specialists, Golden Ocean Group Limited and Oldendorff Carriers occupy positions defined by fleet age profiles and fuel efficiency specifications. These named entities serve as anchors for understanding how capital structure and regulatory compliance timelines differentiate competitive positioning across the industry.
| Leading Market Players |
|---|
| Maersk Line |
| COSCO Shipping |
| Star Bulk Carriers Corp. |
| Pacific Basin Shipping Limited |
| Hapag-Lloyd |
| Oldendorff Carriers |
| Golden Ocean Group Limited |
| American Commercial Barge Line |
| Genco Shipping and Trading |
| Others |
Pricing and Supply Chain Analysis
Chinese steel mill procurement consolidation into decade-long contract of affreightment structures is compressing spot market liquidity and forcing vessel operators to absorb fuel price volatility through fixed-rate commitments. This buyer-side consolidation elevates pricing power for integrated logistics platforms while squeezing standalone freight providers.
Pricing Analysis
Bundled ocean-rail-terminal contracts command premium positioning against unbundled spot freight. Three-tier pricing structure across premium, standard, and economy levels stratifies around fuel efficiency certification and digital cargo tracking inclusion. Pricing pressure stems from EU ETS carbon cost absorption requirements for European-bound cargoes. Commodity traders exhibit highest price sensitivity; mining majors with captive shipping demand show lowest.
Supply Chain Analysis
Single-source vulnerability sits with Chinese and South Korean shipyards controlling over seventy percent of newbuild bulk carrier construction. Steel plate and marine engine production draws from concentrated East Asian supplier networks. Tariff exposure on steel inputs threatens vessel delivery timelines. Distribution runs through dedicated long-term offtake contracts rather than spot market allocation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story where environmental compliance specifications now dominate procurement scoring. Mining majors are prioritizing fuel-efficient fleet access over rate minimization.
For Market Incumbents: Acquire ammonia-ready vessel slots and dual-fuel engine certifications to preempt green corridor requirements. Defensive positioning demands backward integration into port terminal partnerships at Port Hedland and Itaqui to secure dedicated berth access against emerging integrated logistics competitors. For New Entrants and Emerging Players: Digital freight matching platforms offer the most penetrable entry vector for mid-size commodity traders seeking alternatives to incumbent COA structures. Target Australian domestic grain corridors where legacy rail contracts face renewal windows. Lead with IoT-enabled cargo monitoring as differentiated service bundling. For Investors and Strategic Acquirers: Asymmetric upside sits with pure-play dry bulk operators holding modern Capesize fleets under five years of age. Five-to-ten year viability hinges on IMO CII compliance trajectory rather than cyclical rate recovery. Monitor ammonia bunkering infrastructure commitment announcements at Port of Kobe and Rotterdam as inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Fleet Renewal Acceleration | Dual-fuel Capesize orders from Oldendorff and Golden Ocean secure IMO CII compliance advantages. |
| Green Corridor Partnership | Port Hedland-Kobe ammonia infrastructure coordination tests zero-emission bulk transport economics. |
| Integrated Logistics Bundling | End-to-end contracts combining ocean freight with last-mile rail capture margin from mining procurement consolidation. |
| Digital Cargo Platform Deployment | Blockchain-verified IoT tracking reduces demurrage disputes and enables premium pricing for transparency-guaranteed shipments. |
| EU ETS Compliance Service Expansion | Emissions verification and carbon offset procurement services address maritime's phased entry into European carbon trading. |
Research Methodology
Coverage spans Asia-Pacific, Europe, and Americas bulk trade corridors, with primary inputs from each. Fleet operators, mining procurement executives, shipyard commercial managers, and maritime classification surveyors provided structured interviews. Secondary validation drew from IMO regulatory filings, Lloyd's List vessel data, customs trade statistics, and SEC shipping company disclosures. Bottom-up vessel deployment models triangulated against top-down commodity flow estimates.
Granularity-level modeling operated at service type, cargo mode, and industry vertical dimensions across the projection horizon. Ocean freight, rail freight, and liquid bulk segments were modeled separately with distinct fuel cost and regulatory compliance assumptions. CAGRs derived from vessel supply-demand balance projections and commodity trade flow forecasts. Steel price volatility and shipyard capacity constraints entered as scenario variables.
Regulatory enforcement delays, alternative fuel infrastructure abandonment, and mining production disruptions are the dominant revision risks to modeled outcomes. Forecasts reflect documented assumptions about IMO CII implementation stringency and green corridor adoption timelines. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation Services
Europe Van Rental Market
Transportation Services
ASEAN Car Rental Market
Transportation Services
Global White Glove Service in Delivery Market
Transportation Services
Australia Taxi Market
Transportation Services
Global Moto Taxi Service Market
Transportation Services
United States Vehicle Rental Market
Transportation Services
Vehicle Management System Market
Transportation Services
Refuse Truck Market
Transportation Services
Airline Passenger Service System Market
Transportation Services
Thailand Car Rental Market
Transportation Services
Sanitation Vehicle Market
Transportation Services
Europe Refrigerated Truck Rental Market
Transportation Services
Asia-Pacific Rickshaw Ride Hailing Service Market
Transportation Services
Water Truck Rental Market
Transportation Services
India Two-Wheelers Rental Market
Transportation Services
Car Rental Service Market