
 Car Rental Market | 2026-2036
Car Rental Market Size, Share, and Industry Trends Forecast 2026-2036
Car Rental Market Intelligence
The EU Green Deal is rebalancing fleet procurement criteria across Europe, forcing rental operators to electrify holdings faster than replacement cycles originally planned. Enterprise Holdings leverages its North American maintenance infrastructure to sustain margin density on hybrid transitions. Europcar Mobility Group anchors its European network density against airport-centric competitors. Localiza dominates Latin American coverage through franchise partnerships that extend reach without capital-heavy fleet ownership.
Car rental denotes short- to medium-term vehicle access contracts where operators retain asset ownership, maintain insurance liability, and manage depreciation risk across daily, weekly, or monthly terms. Fleet composition spans internal combustion, hybrid, and battery electric vehicles with odometer thresholds, age caps, and manufacturer service intervals defining unit economics. Self-drive and chauffeur-driven service types capture divergent margin structures, with the former scaling through asset utilization software and the latter commanding premium pricing around executive transport and event logistics. Electric vehicle type segments within fleet portfolios attract differentiated insurance products and charging infrastructure partnerships that alter total cost of ownership calculations versus conventional economy cars and SUVs.
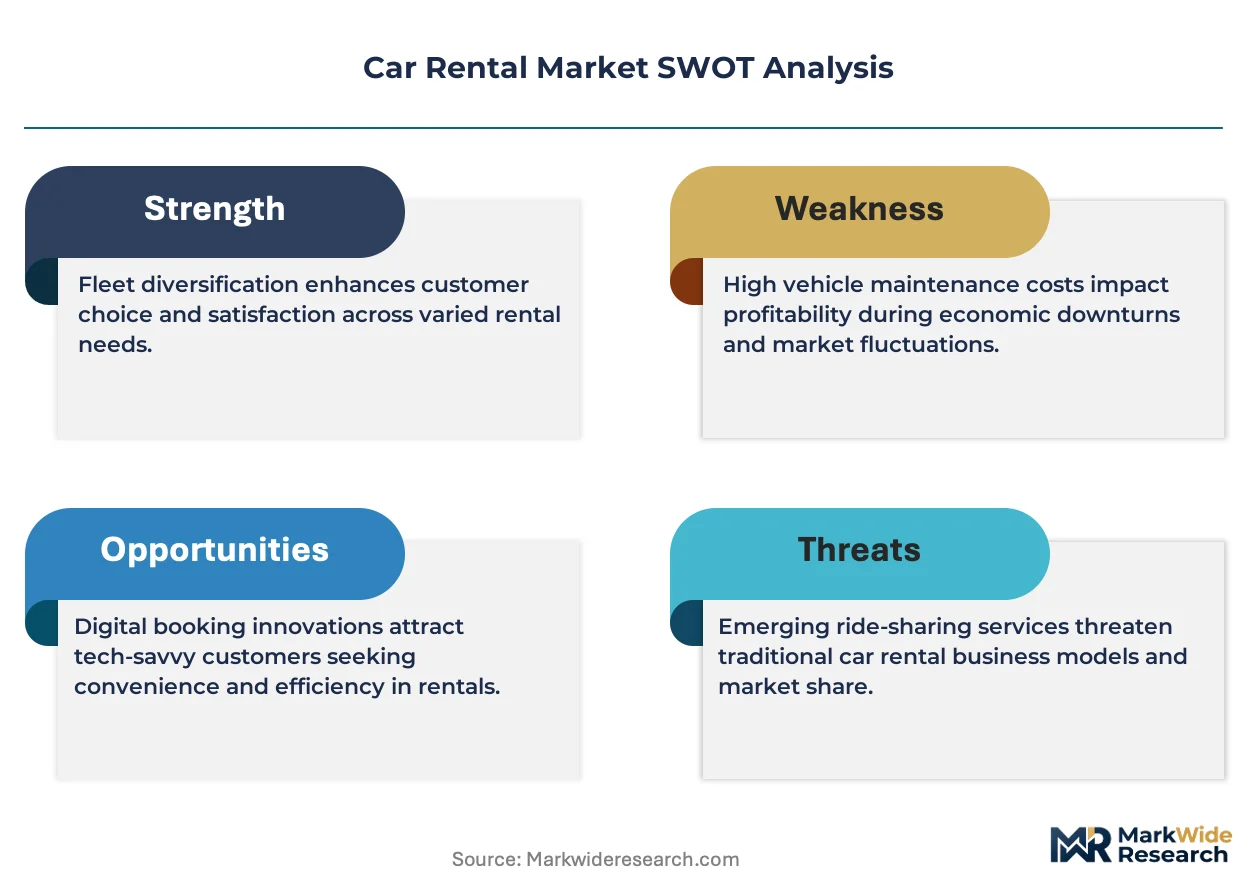
Fleet CO2 regulations under the EU Green Deal, EPA emissions standards for light-duty vehicles, and national zero-emission vehicle mandates in California and New York reshape fleet composition requirements and capital allocation timelines for rental operators. Compliance timelines compress procurement decisions and elevate residual value risk on internal combustion assets. Stakeholders must monitor regulatory phase-out schedules against fleet turnover rates to avoid stranded asset exposure.
Market Dynamics
Fleet electrification timelines are compressing procurement cycles as residual value risk on internal combustion engines forces operators to accelerate battery electric vehicle adoption ahead of traditional replacement schedules.
Growth Catalysts
- EU Green Deal fleet mandates:Corporate leasing contracts must meet Scope 3 emissions targets, redirecting procurement toward electric and hybrid vehicle portfolios.
- Airport hub density:Business travel recovery concentrates demand at major aviation gateways where rental operators capture premium daily rates.
- Telematics integration:Real-time asset utilization software optimizes fleet turnover and reduces idle inventory carrying costs.
Market Restraints
- Lithium-ion battery supply concentration:Cathode material processing dependence on Chinese refiners creates input cost volatility and geopolitical sourcing risk.
- Charging infrastructure gaps:Uneven fast-charging network deployment across secondary cities limits electric vehicle rental range confidence.
- Residual value uncertainty:Accelerated internal combustion phase-out schedules in Germany, France, and the United Kingdom strand depreciation models.
Strategic Opportunities
- Subscription service expansion:Monthly flexible-access contracts attract urban consumers avoiding vehicle ownership in Madrid, Milan, and Amsterdam.
- Corporate mobility budgets:Employers are consolidating travel spend into managed rental programs with sustainability reporting requirements.
- Vehicle-to-grid integration:Bidirectional charging partnerships with utilities transform idle rental fleets into grid stabilization assets.
Industry Challenges
- Technician certification gaps:High-voltage battery maintenance requires specialized training that outpaces vocational program output.
- Legacy reservation system integration:Siloed technology stacks complicate unified fleet visibility across franchise and corporate-owned locations.
- Insurance product lag:Underwriting models for autonomous vehicle features remain undeveloped, delaying deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Car Rental Market |
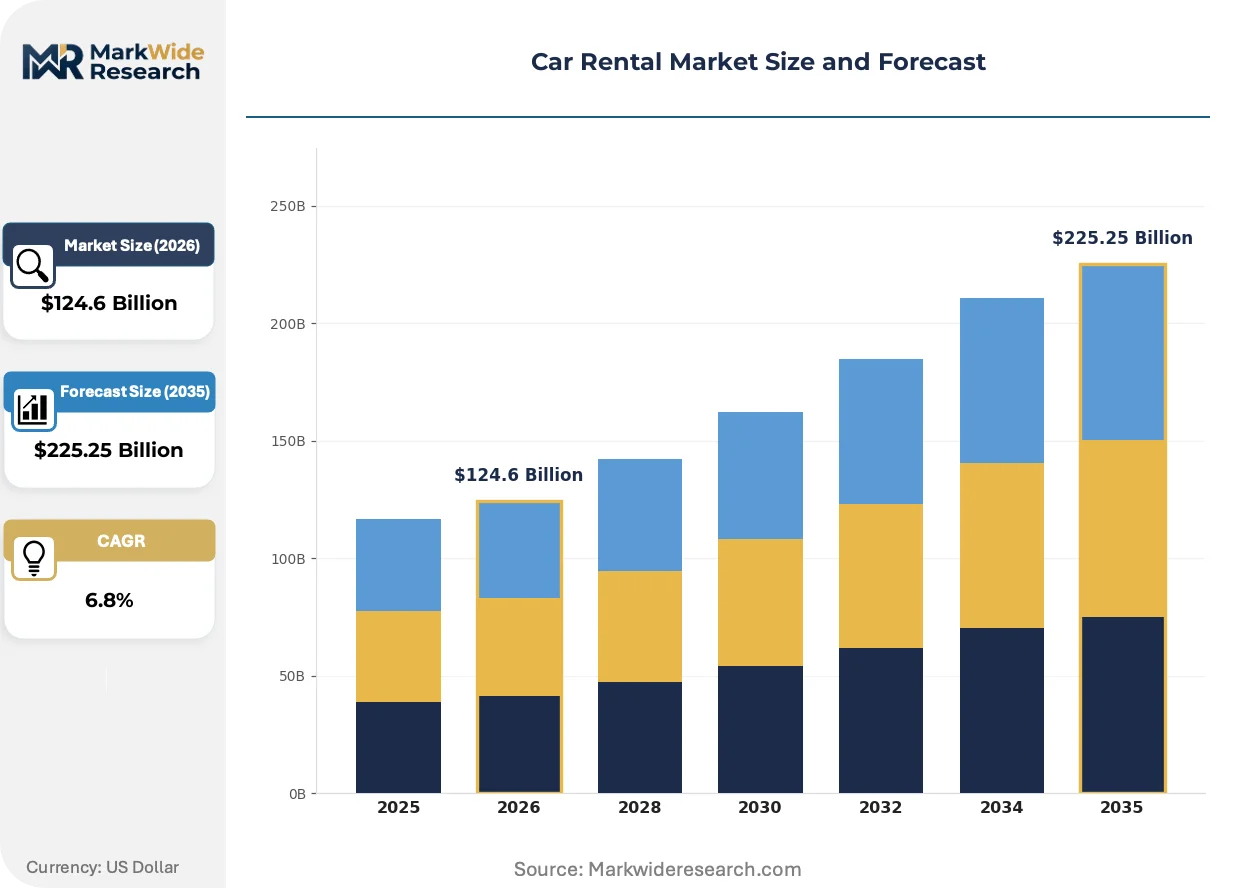
| Market Size in 2026 | $124.6 Billion |
| Market Size in 2035 | $225.25 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Self-Drive, Chauffeur-Driven, Ride-Sharing, Luxury Rentals Vehicle Type: Economy Cars, SUVs, Vans, Electric Vehicles Customer Type: Corporate Clients, Tourists, Locals, Government Agencies Booking Channel: Online Platforms, Travel Agencies, Direct Booking, Phone Reservations |
| Companies Covered | Enterprise Holdings, Avis Budget Group, Hertz Global Holdings, Europcar Mobility Group, Sixt SE, Localiza, Turo, Zoomcar Holdings, National Car Rental, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Car Rental Market Strategic Shifts & Innovations
Digital fleet management platforms are converging with connected vehicle architectures to enable predictive maintenance and dynamic pricing based on real-time utilization data.
Artificial intelligence-driven demand forecasting is automating fleet rebalancing decisions across rental locations. Operators in Germany and the United Kingdom deploy machine learning models to anticipate airport pickup surges and pre-position inventory. This capability compresses customer wait times and reduces deadhead transfer costs.
The EU Green Deal's corporate fleet reporting requirements are mandating granular emissions tracking for leased vehicles. Rental operators must install telematics capable of Scope 3 calculation and audit trails. France and the Netherlands lead enforcement, with KBA in Germany preparing compliance verification protocols.
Business travelers are consolidating ground transportation into employer-managed mobility accounts rather than individual expense reimbursement. This procurement consolidation favors rental operators with direct corporate contracts and sustainability certification. The shift is most pronounced in financial services and professional services verticals across London, Frankfurt, and Paris.
Car Rental Market Segmentation
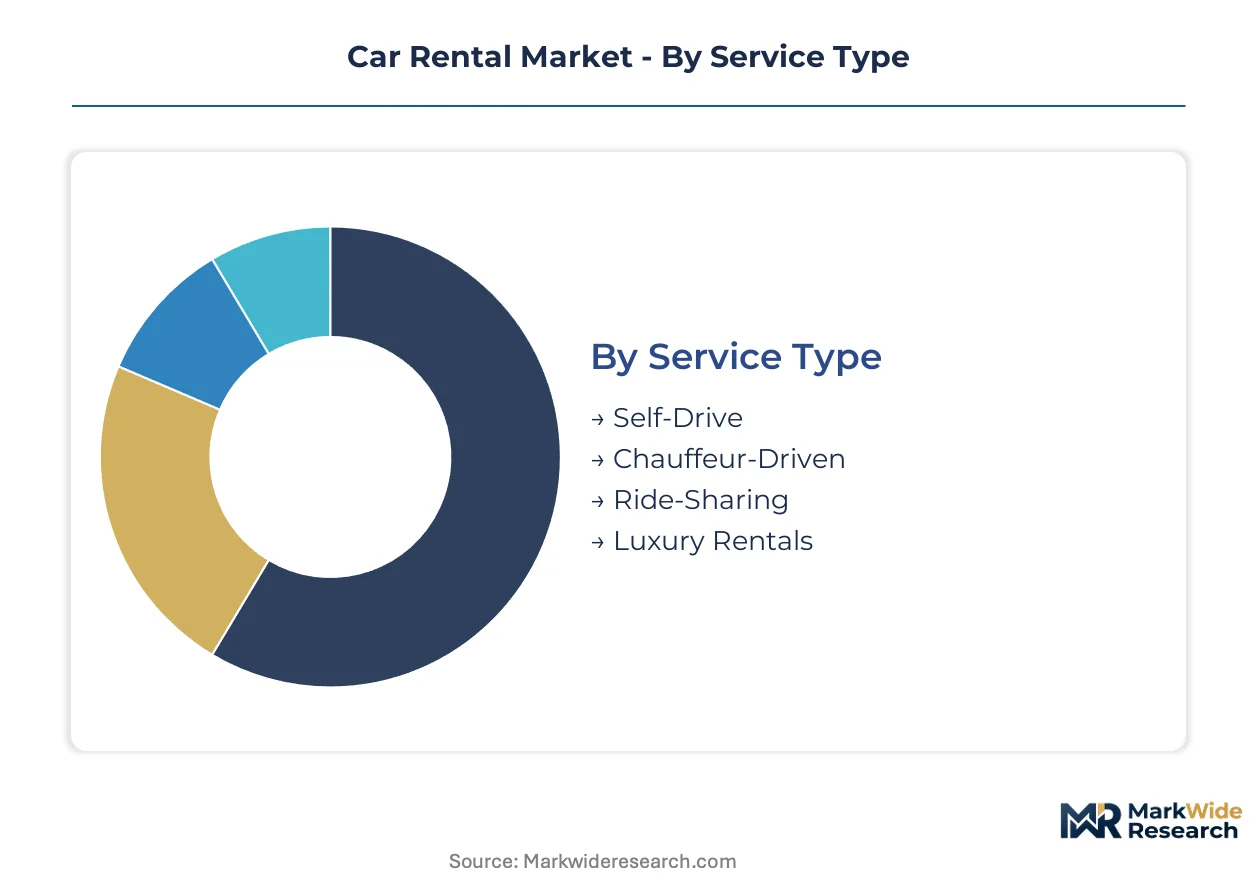
Fleet composition and service configuration determine capital allocation, depreciation schedules, and margin structures across rental operations. Procurement patterns diverge sharply between airport-centric business travel and urban subscription models, forcing operators to segment inventory by utilization profile rather than asset class alone.
Service Type:
Supply concentration in self-drive infrastructure dominates capital deployment, while chauffeur-driven assets command premium positioning through labor-intensive service layers.
- Self-Drive:Asset-heavy model where operators retain full depreciation risk and insurance liability across daily to monthly contract terms. Demand concentrates at Frankfurt, Heathrow, and Charles de Gaulle airports where business travelers absorb premium daily rates during weekday peaks. Telematics integration compresses idle inventory carrying costs.
- Chauffeur-Driven:Labor-anchored service commanding 3-4x pricing multiples over self-drive equivalents through executive transport and event logistics specialization. Madrid and Milan corporate accounts drive sustained demand for airport transfer and roadshow circuits. Driver certification requirements limit supply elasticity.
- Ride-Sharing:Platform-mediated access model disrupting traditional rental with per-trip pricing and no asset ownership transfer.
- Luxury Rentals:Niche segment targeting experiential consumption and special occasion demand with specialized insurance products and concierge onboarding.
Today's leader: Self-Drive. Tomorrow's challenger: Chauffeur-Driven.
Vehicle Type:
Cost tier segmentation separates high-turnover economy inventory from electrified assets carrying residual value uncertainty and charging infrastructure dependencies.
- Economy Cars:High-rotation compact and mid-size sedans forming the volume base of airport and urban fleets. Procurement concentrates through manufacturer fleet programs with standardized service intervals and rapid remarketing pipelines. KBA compliance verification in Germany accelerates ICE phase-out pressure on this segment.
- Electric Vehicles:Battery-powered units attracting differentiated insurance products and utility partnerships for bidirectional charging integration. Corporate leasing contracts in France and the Netherlands mandate Scope 3 reporting that elevates EV procurement priority. Charging infrastructure gaps across secondary cities constrain range confidence.
- SUVs:Family and leisure travel anchor with higher per-day revenue and seasonal demand volatility.
- Vans:Commercial logistics and relocation demand driver with distinct utilization patterns from passenger rental.
Electric Vehicles are gaining share fastest; Economy Cars face compressed replacement cycles.
Customer Type:
Application-based segmentation distinguishes managed corporate procurement with sustainability mandates from discretionary leisure demand with price sensitivity.
- Corporate Clients:Employer-managed mobility accounts consolidating ground transportation spend with ESG reporting requirements. Financial services verticals in London and Frankfurt drive direct contract relationships over aggregator platforms. EU Green Deal fleet mandates redirect procurement toward electrified portfolios.
- Tourists:Leisure travelers booking through online platforms and travel agencies with high price elasticity and seasonal concentration. Amsterdam and Barcelona experience surges during peak travel windows requiring dynamic fleet rebalancing.
- Locals:Urban residents avoiding ownership through monthly subscription contracts.
- Government Agencies:Public sector procurement with formal tender processes and domestic content requirements.
Corporate Clients anchor revenue stability; Locals represent the steepest expansion trajectory.
Booking Channel:
Volume concentration in digital platforms is displacing traditional intermediary relationships and forcing direct-to-consumer capability investment.
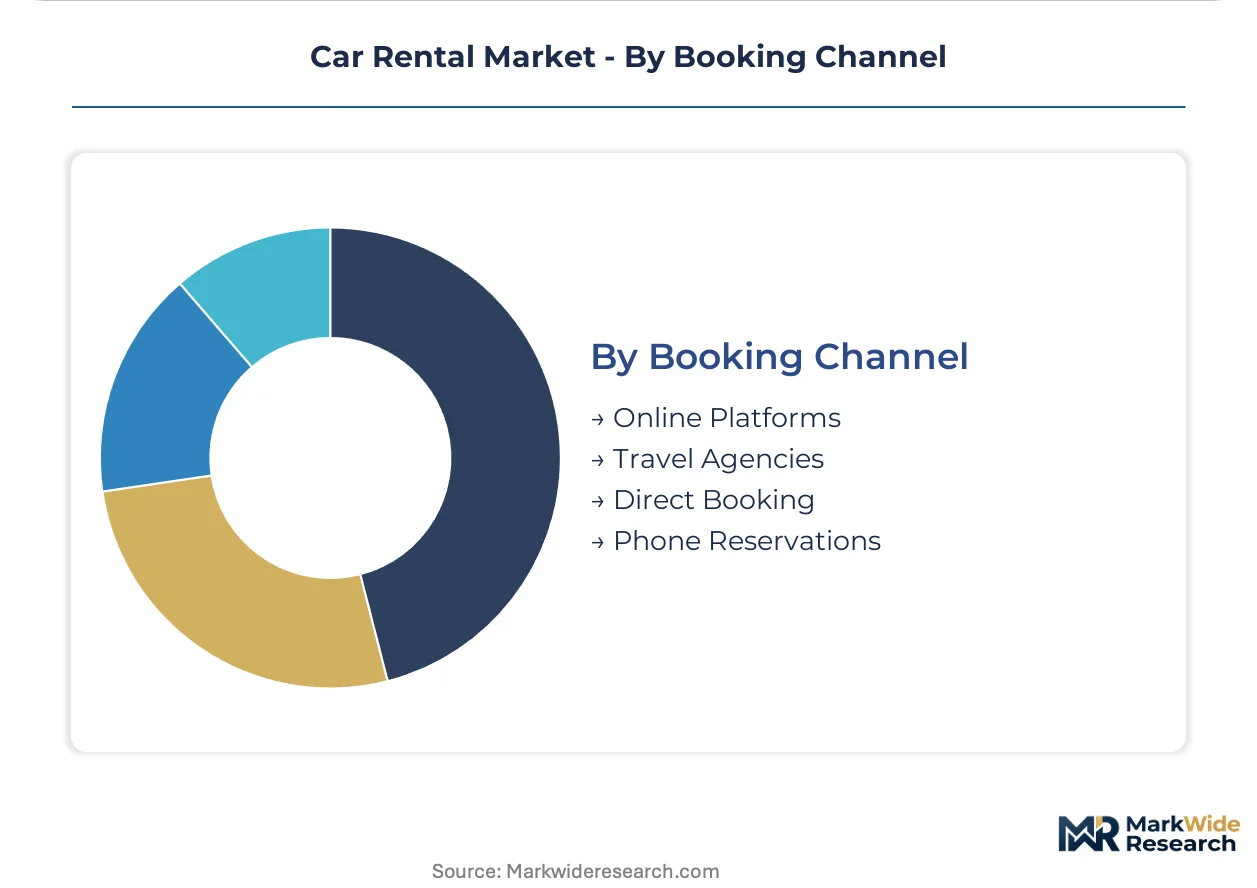
- Online Platforms:Aggregator and operator-owned digital channels capturing majority share of leisure and unmanaged business bookings. Real-time inventory visibility and dynamic pricing algorithms optimize yield across fragmented demand. Mobile-first interfaces dominate customer acquisition in urban European markets.
- Travel Agencies:Traditional intermediary channel retaining relevance for complex multi-leg itineraries and corporate travel management integration.
- Direct Booking:Operator-controlled channels preserving margin through avoided commission structures and loyalty program data capture.
- Phone Reservations:Legacy channel serving demographic segments and complex service requirements outside standard digital workflows.
Online Platforms dominate transaction volume; Direct Booking offers margin defense.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The car rental industry traces its modern operational scale to post-war United States fleet deployments, where airport-centric business models first standardized short-term vehicle access contracts. This template spread through Western Europe during the 1970s and 1980s, then adapted to emerging market conditions across Latin America and Asia-Pacific. Regulatory divergence now shapes competitive positioning across major national markets.
United States
Business travel recovery concentrates demand at Atlanta, Dallas-Fort Worth, and Denver aviation hubs where operators capture premium weekday rates. EPA emissions standards for light-duty vehicles compress fleet turnover timelines. Enterprise Holdings anchors North American network density through maintenance infrastructure that sustains margin density on hybrid transitions.
Germany
Corporate fleet managers expand long-term leasing programs to meet Scope 3 emissions targets under the EU Green Deal. KBA prepares compliance verification protocols that accelerate internal combustion phase-out pressure. Frankfurt and Munich airport clusters experience surging demand for electric vehicle rental subscriptions with telematics-enabled emissions tracking.
France
Employer-managed mobility accounts consolidate ground transportation spend with ESG reporting requirements in financial services verticals. ANSM and CNIL oversight intersects with emissions data privacy in connected fleet telematics. Paris and Lyon drive sustained demand for chauffeur-driven executive transport and roadshow circuits.
United Kingdom
Heathrow and Gatwick capture premium daily rates during weekday business travel peaks with dynamic fleet rebalancing. UK zero-emission vehicle mandates reshape capital allocation timelines for rental operators. London financial services procurement consolidation favors operators with direct corporate contracts and sustainability certification.
Brazil
Franchise partnerships extend market reach without capital-heavy fleet ownership across São Paulo and Rio de Janeiro metropolitan corridors. Localiza dominates Latin American coverage through this asset-light expansion model. Seasonal leisure demand volatility in coastal tourism zones requires flexible inventory positioning.
Car Rental Market Key Industry Players
Premium-margin players sit above commodity-margin players across service tier and fleet electrification readiness. The market structure consolidates around three strategic archetypes: airport-hub operators with maintenance infrastructure density, urban subscription specialists with flexible-access platforms, and franchise-network aggregators with capital-light geographic extension. Dominant competitive moves include fleet electrification acceleration ahead of regulatory phase-outs and telematics integration for predictive asset utilization.
Within the airport-hub operator tier, Enterprise Holdings and Avis Budget Group exemplify North American infrastructure scale. Europcar Mobility Group occupies a position representing European network density against aviation-gateway competitors. Localiza anchors the franchise-network archetype in Latin American coverage extension. Sixt SE sits within the premium-tier vector with German-origin positioning. Hertz Global Holdings represents fleet electrification acceleration through battery electric vehicle procurement ahead of replacement cycles.
| Leading Market Players |
|---|
| Enterprise Holdings |
| Avis Budget Group |
| Hertz Global Holdings |
| Europcar Mobility Group |
| Sixt SE |
| Localiza |
| Turo |
| Zoomcar Holdings |
| National Car Rental |
| Others |
Cost & Logistics Intelligence
EU Green Deal fleet mandates gate qualified supply access and premium-tier pricing power for rental operators, compressing procurement timelines for electrified assets while elevating residual value risk on internal combustion inventory. Corporate clients with Scope 3 reporting requirements absorb pricing premiums for telematics-enabled electric vehicle subscriptions, whereas price-sensitive leisure tourists concentrate demand in standardized economy segments.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments the market by service intensity and asset electrification status. Price differentiation rests on telematics integration depth and charging infrastructure bundling, with chauffeur-driven services commanding multiples over self-drive equivalents. Pricing pressure stems from lithium-ion battery supply volatility feeding into fleet acquisition costs. Leisure tourists exhibit highest price sensitivity; corporate mobility accounts with ESG mandates show lowest.
Supply Chain Analysis
Domestic-content requirements in Brazil and India reshape sourcing patterns for fleet procurement and maintenance infrastructure. Vehicle manufacturing concentrates in Germany, Japan, and China, with cathode material processing anchored in Chinese refineries. Raw material dependencies span lithium carbonate, cobalt sulfate, and high-grade steel alloys. Single-source vulnerability in battery cell supply creates fleet acquisition bottlenecks. Distribution runs through airport-hub operators with direct manufacturer fleet programs and franchise-network intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The car rental market functions as a regulatory compounder where EU Green Deal fleet mandates accelerate capital reallocation toward electrified portfolios and compress depreciation timelines for legacy assets.
For Market Incumbents: Anticipate residual value collapse on internal combustion inventory by accelerating battery electric vehicle procurement ahead of KBA compliance verification timelines. Consolidate maintenance infrastructure density around high-voltage technician certification programs to defend service margins against emerging platform competitors. For New Entrants and Emerging Players: AI-driven demand forecasting platforms offer a technology-first wedge into airport-hub fleet rebalancing services currently served by legacy reservation systems. Target urban subscription markets in Madrid, Milan, and Amsterdam with flexible-access monthly contracts. Pursue direct utility partnerships for vehicle-to-grid integration as a differentiated go-to-market anchor. For Investors and Strategic Acquirers: Valuations sit cheapest among franchise-network aggregators with capital-light geographic extension models and limited electrification exposure. Long-term viability favors operators with telematics-enabled Scope 3 reporting capabilities and direct corporate contract relationships. Monitor EU Green Deal enforcement acceleration across France, Germany, and the Netherlands as the inflection signal for fleet turnover velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Fleet Electrification Acceleration | Battery electric vehicle procurement ahead of regulatory phase-out schedules compresses stranded asset risk. |
| Telematics Platform Integration | Real-time asset utilization software optimizes fleet turnover and enables Scope 3 emissions audit trails. |
| Charging Infrastructure Partnership | Bidirectional charging agreements with utilities transform idle rental fleets into grid stabilization assets. |
| Corporate Mobility Contract Consolidation | Direct relationships with financial services verticals in London and Frankfurt anchor revenue stability. |
| High-Voltage Technician Certification Program | Specialized training pipelines address maintenance capability gaps for electrified fleet portfolios. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with fleet procurement managers, airport operations directors, corporate mobility budget owners, and high-voltage maintenance technicians with secondary validation. Regulatory filings from EPA, KBA, and ANSM anchored compliance timeline assumptions. Trade data from customs authorities, vehicle registration databases, and airport passenger volume statistics supported demand modeling. Bottom-up fleet inventory analysis and top-down market sizing triangulated value estimates.
Comparable historical periods anchored the forecast window across the projection horizon, with segmentation modeling across service type, vehicle propulsion architecture, customer application, and regional regulatory cluster. CAGRs derived from regression analysis against macroeconomic indicators and fleet turnover velocity. Industry-specific inputs incorporated charging infrastructure deployment rates and corporate Scope 3 reporting adoption curves.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to battery supply chain disruptions and EU Green Deal enforcement acceleration. Assumptions reflect documented regulatory phase-out schedules and manufacturer fleet program commitments. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation Services
Sanitation Vehicle Market
Transportation Services
Ride-Hailing Service Market
Transportation Services
Third Party Logistics Services Market
Transportation Services
Europe Light Commercial Vehicle Rental Market
Transportation Services
ASEAN Car Rental Market
Transportation Services
Corporate Employee Transportation Service Market
Transportation Services
Waste Collection Vehicle Market
Transportation Services
Egypt Ride Hailing Service Market
Transportation Services
United States Vehicle Rental Market
Transportation Services
United States White Glove Delivery Service Market
Transportation Services
Full-Service Carrier Market
Transportation Services
Europe Refrigerated Truck Rental Market
Transportation Services
Two Wheeler Rental Market
Transportation Services
Poland Car Rental Market
Transportation Services
India Two-Wheelers Rental Market
Transportation Services
Global Taxi Market