
 ASEAN Car Rental Market | 2026-2036
ASEAN Car Rental Market Size, Share, and Industry Trends Forecast 2026-2036
ASEAN Car Rental Market Outlook
Subscription-based fleet access is hardening into the core revenue model across ASEAN car rental operations. Europcar Mobility Group leverages its airport counter network to anchor corporate accounts across Singapore and Kuala Lumpur. Avis Budget Group sustains weekend leisure volumes through localized digital partnerships with hospitality chains. Bluebird Group dominates Indonesia's chauffeured segment through its integrated taxi-to-rental dispatch infrastructure.
ASEAN car rental denotes the short-term commercial provision of motorized vehicles—typically passenger cars with engine displacements from 1.0L to 3.5L—through daily, weekly, or monthly contracts for transportation without ownership transfer. Fleet operators maintain vehicles to manufacturer service intervals and national inspection standards before redeployment across urban, airport, and resort catchments. Self-drive bookings capture the largest revenue pool among service types as independent travelers prioritize itinerary flexibility across Thailand's island circuits and Vietnam's coastal corridors. Chauffeured services command premium pricing in Indonesia's Jakarta-Bandung corridor where executive road time competes with domestic aviation. SUV vehicle types are gaining structural share as road infrastructure improvements open highland and rural tourism routes previously served only by coach services.
Malaysia's Land Public Transport Agency (APAD) and Thailand's Department of Land Transport enforce commercial vehicle fitness certification that dictates fleet replacement timelines and insurance underwriting across both markets. Indonesia's Ministry of Transportation coordinates with the National Standardization Agency (BSN) on emission testing protocols that filter older diesel units from rental eligibility in Jakarta and Surabaya. Singapore's Land Transport Authority vehicle quota system constrains fleet expansion velocity through certificate-of-entitlement auctions. Stakeholders must weigh regulatory compliance costs against the margin compression from asset-light platform competitors entering without captive fleet burdens.
Market Dynamics
Subscription-based fleet access is hardening into the dominant commercial model across Southeast Asia, compressing traditional daily-rate economics as operators trade transaction volume for predictable recurring revenue and lower customer acquisition costs.
Growth Catalysts
- Thailand's island circuit tourism:Independent travelers prioritize itinerary flexibility across Phuket and Koh Samui, driving self-drive booking volumes through digital platforms that aggregate fragmented local fleet supply.
- Malaysia's APAD vehicle safety standards:Mandatory fitness certification timelines accelerate fleet renewal cycles, creating replacement demand for newer vehicle models with embedded telematics and emission compliance.
- Telematics integration:Real-time vehicle monitoring systems enable usage-based insurance underwriting and predictive maintenance scheduling, reducing downtime and asset depreciation rates for fleet operators.
Market Restraints
- Certificate-of-entitlement auctions in Singapore:Singapore's Land Transport Authority vehicle quota system constrains fleet expansion velocity through limited permit availability, capping market entry for new rental operators.
- Used vehicle import restrictions:Indonesia's Ministry of Transportation emission testing protocols filter older diesel units from rental eligibility in Jakarta and Surabaya, raising fleet acquisition costs for operators dependent on secondary markets.
- Domestic aviation substitution:Executive road time competes with low-cost carrier routes on the Jakarta-Bandung corridor, compressing chauffeured service pricing power during peak business travel periods.
Strategic Opportunities
- Vietnam's coastal corridor development:Road infrastructure improvements connecting Da Nang to Hoi An and Hue open highland tourism routes previously served only by coach services, creating demand for SUV and 4WD fleet expansion.
- Integrated hospitality partnerships:Direct API connections between rental platforms and hotel property management systems enable seamless booking at point of reservation, capturing leisure travelers before competitive search begins.
- Thailand's Department of Land Transport commercial licensing reforms:Streamlined fitness certification processes for rental-specific vehicle categories reduce administrative burden and accelerate fleet deployment timelines for compliant operators.
Industry Challenges
- Telematics technician scarcity:Fleet maintenance operations require specialized diagnostic capabilities for connected vehicle systems, creating wage pressure in Bangkok and Kuala Lumpur labor markets where technical training pipelines remain underdeveloped.
- Multi-platform inventory synchronization:Operators listing assets across aggregator networks, direct channels, and corporate account portals face real-time availability conflicts that erode customer trust and trigger penalty clauses.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | ASEAN Car Rental Market |
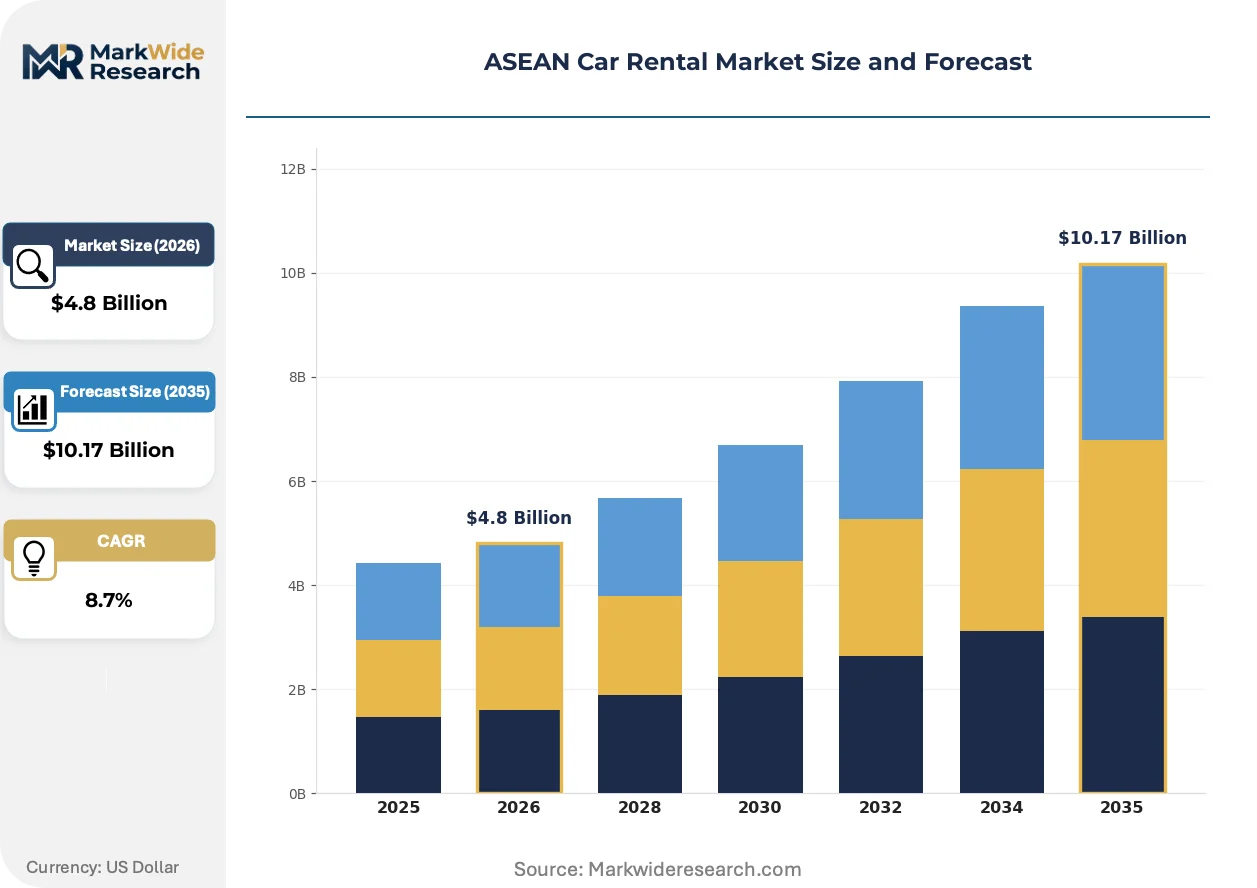
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Self-Drive, Chauffeured, Leisure, Business Vehicle Type: SUV, Sedan, Hatchback, Luxury Rental Duration: Short-Term, Long-Term, Weekend, Monthly Client Type: Tourists, Corporates, Locals, Event Planners |
| Companies Covered | Europcar Mobility Group, INDORENT, Avis Budget Group, Tribecar Pte Ltd, Bluebird Group, Sixt SE, Enterprise Holdings Inc., SOCAR Mobility Malaysia, Hertz Global Holdings, Others |
| Regions Covered | Southeast Asia: Indonesia, Thailand, Vietnam, Philippines, Malaysia, Singapore, Myanmar, Cambodia, Rest of Southeast Asia |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
ASEAN Car Rental Market Strategic Shifts
Digital booking infrastructure is absorbing operational complexity across ASEAN fleet networks, replacing counter-based transactions with mobile-first experiences that reshape customer acquisition economics and asset utilization patterns.
Embedded telematics hardware is absorbing fleet management functions previously handled through manual inspection and paper logbooks. Operators in Thailand and Malaysia are retrofitting existing inventories with GPS-enabled diagnostic modules that transmit odometer readings, fuel levels, and engine fault codes to centralized dispatch platforms. This technology is absorbing traditional vehicle handoff friction, enabling contactless pickup and drop-off workflows that reduce labor costs at airport and hotel locations.
Singapore's Land Transport Authority vehicle quota system is tightening supply-side constraints through certificate-of-entitlement auction mechanics that limit fleet expansion velocity. Commercial operators must bid against private vehicle purchasers for limited permit allocations, raising capital intensity for market entry. The chauffeured segment is responding through extended vehicle lifecycles and premium pricing strategies that amortize permit costs across higher-margin executive bookings.
Corporate travel managers are consolidating vendor relationships through master service agreements that bundle airport transfers, intercity road transport, and short-term self-drive access under single invoicing structures. This procurement consolidation displaces fragmented spot-market booking behaviors that previously dominated ASEAN business travel. The shift is most visible in Singapore and Kuala Lumpur, where multinational regional headquarters centralize mobility spend across Southeast Asian operations.
ASEAN Car Rental Market Segmentation
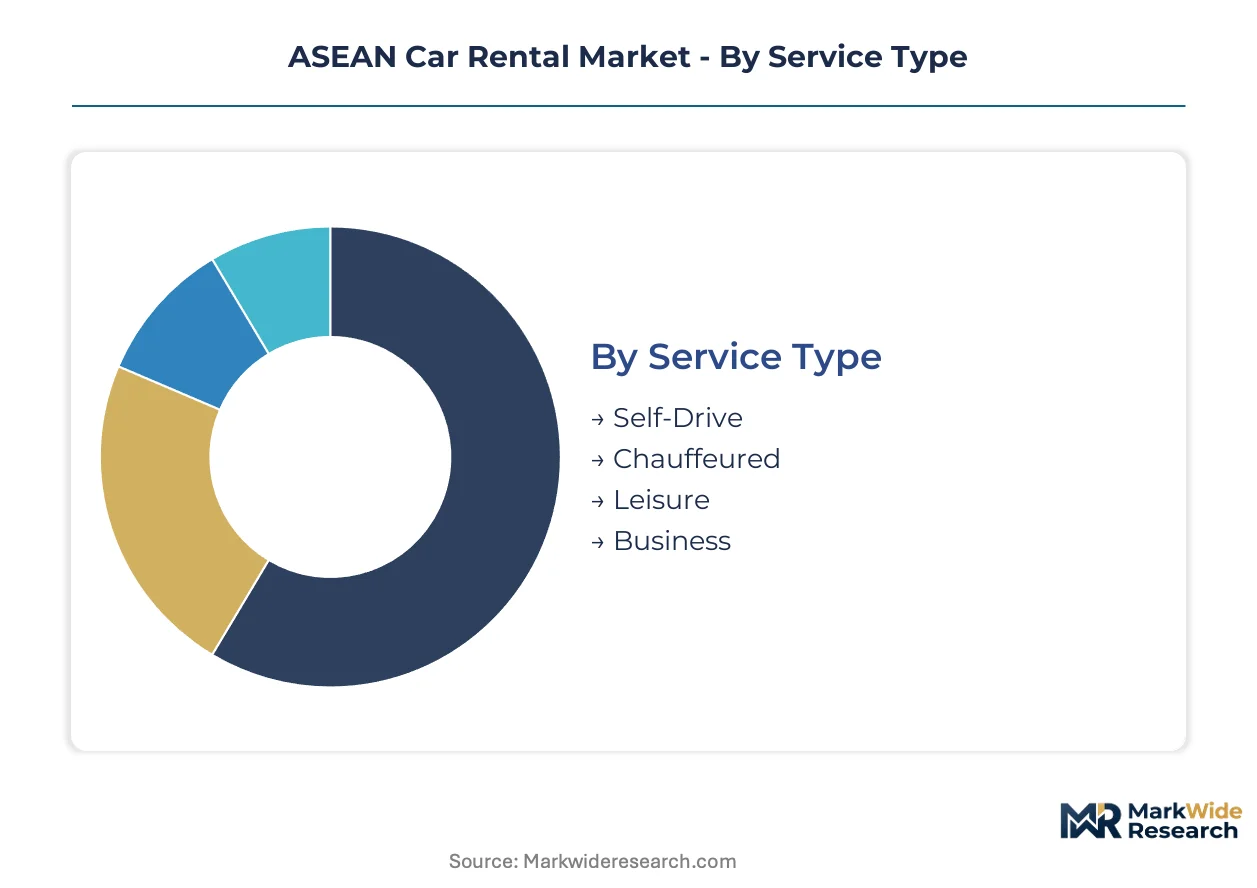
Segmentation in the ASEAN car rental market reveals how mobility needs fragment across travel purpose, vehicle specification, and booking cadence. Operators configure fleet mix and pricing architecture around these divides to optimize asset turns and margin capture.
Service Type:
Travelers select service modes based on itinerary control preferences, local driving confidence, and executive productivity requirements.
- Self-Drive:Independent travelers operate rental vehicles without operator-provided drivers, typically selecting compact to mid-size sedans for island circuits in Phuket and Koh Samui. Thailand's tourism-dependent economy concentrates demand here as digital platforms aggregate fragmented local fleet supply.
- Chauffeured:Executive road transport with professional drivers commands premium pricing in Indonesia's Jakarta-Bandung corridor where business travelers substitute car time for domestic aviation. Fleet operators maintain dedicated driver pools and dispatch infrastructure to service corporate account requirements.
- Leisure:Holiday-focused bookings cluster around resort catchments and coastal corridors, with families prioritizing luggage capacity and air conditioning reliability.
- Business:Corporate travel managers source mobility through master service agreements that bundle airport transfers, intercity transport, and short-term self-drive access under single invoicing structures in Singapore and Kuala Lumpur.
Self-Drive leads volumes today; Chauffeured is gaining share fastest as executive productivity demands intensify.
Vehicle Type:
Fleet composition responds to road infrastructure quality, passenger count requirements, and status signaling needs across ASEAN markets.
- SUV:High-clearance vehicles with four-wheel-drive capability serve expanding highland tourism routes in Vietnam's Da Nang-Hue corridor where road improvements previously served only coach services. Operators report structural share gains as rural accessibility improves.
- Sedan:Three-box passenger cars dominate urban airport transfers and intercity business travel, offering balanced fuel economy and luggage capacity for corporate road transport needs across Malaysia's peninsula.
- Hatchback:Compact two-box configurations with rear cargo access suit solo travelers and couples navigating dense urban cores in Bangkok and Jakarta where parking constraints favor smaller footprints.
- Luxury:Premium marques with enhanced cabin materials and advanced driver assistance systems address C-suite mobility requirements and VIP hospitality arrangements in Singapore's financial district.
Sedan holds the largest installed base; SUV is climbing the fastest as tourism routes diversify beyond coastal zones.
Rental Duration:
Booking cadence determines fleet utilization patterns and revenue predictability for operators balancing spot-market volatility against contracted recurring income.
- Short-Term:Daily and multi-day contracts capture impulse leisure demand and emergency replacement needs, requiring operators to maintain excess fleet capacity at airport and hotel locations.
- Long-Term:Extended contracts spanning multiple months serve expatriate assignments and project-based corporate mobility, reducing customer acquisition costs and improving asset depreciation scheduling.
- Weekend:Friday-to-Sunday bookings concentrate leisure demand spikes that strain fleet availability in Phuket and Bali resort markets.
- Monthly:Thirty-day rolling subscriptions are hardening into the core revenue model as operators trade transaction volume for predictable recurring revenue and lower churn.
Short-Term generates the highest transaction frequency; Monthly is expanding most quickly as subscription economics displace daily-rate volatility.
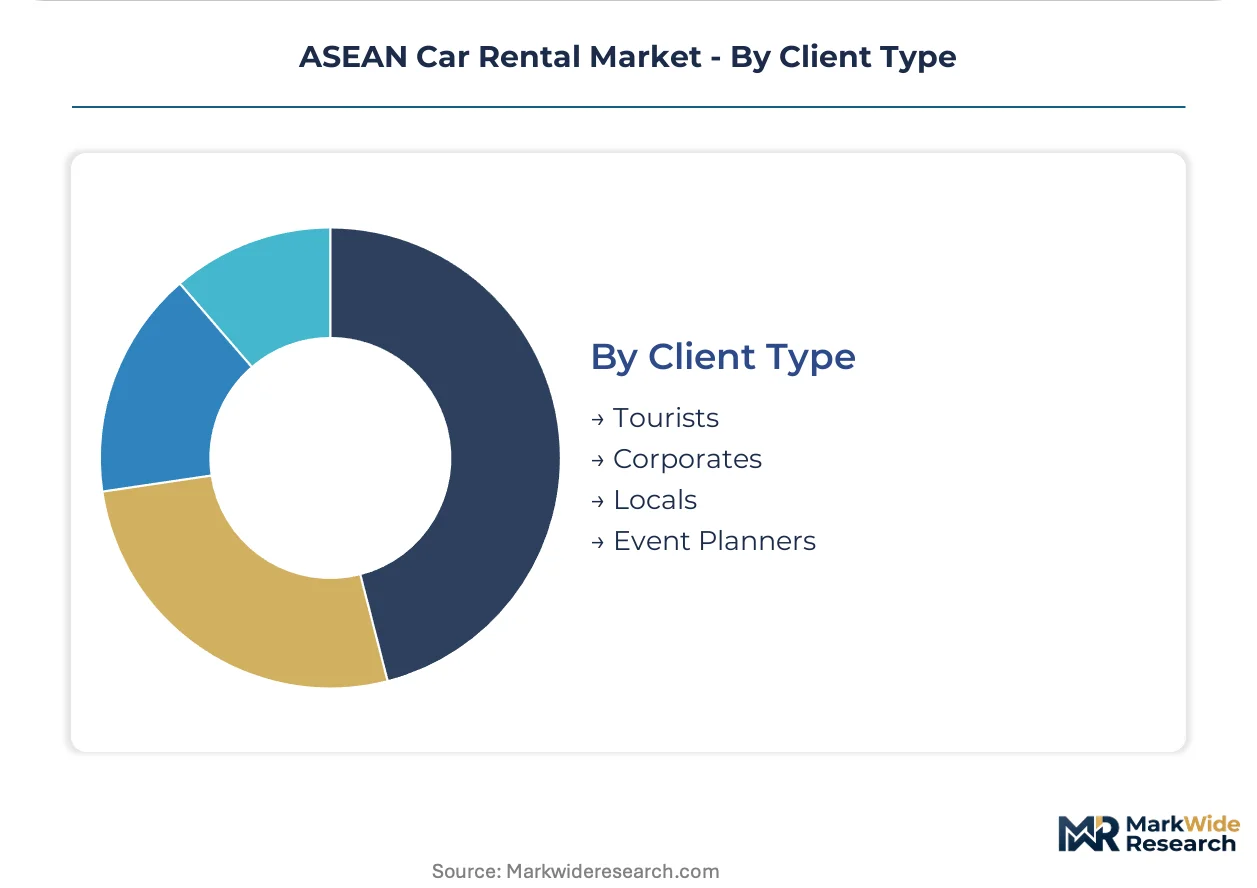
Client Type:
Customer identity shapes booking channels, service expectations, and price sensitivity across the ASEAN rental landscape.
- Tourists:International visitors prioritize digital booking convenience and English-language support, driving platform aggregation of fragmented local fleet supply in Thailand and Vietnam.
- Corporates:Regional headquarters in Singapore and Kuala Lumpur centralize mobility spend across Southeast Asian operations, consolidating vendor relationships through master service agreements.
- Locals:Domestic renters supplement private vehicle ownership during repair periods or family events, exhibiting higher price sensitivity and platform loyalty.
- Event Planners:Wedding, conference, and exhibition coordinators source coordinated vehicle fleets with uniform branding and timing precision.
Tourists anchor revenue concentration today; Corporates are gaining share fastest as procurement centralization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fleet operators exploit regulatory-arbitrage opportunities across Southeast Asia by concentrating asset deployment in jurisdictions with streamlined vehicle certification processes and lower compliance overhead relative to permit-constrained markets.
Thailand
Island-hopping tourism circuits around Phuket and Koh Samui sustain self-drive demand as independent travelers reject fixed-itinerary coach services. The Department of Land Transport enforces commercial vehicle fitness certification that dictates fleet replacement timelines and insurance underwriting. Bangkok's Suvarnabhumi Airport anchors the largest consolidated rental hub where digital platforms aggregate fragmented local fleet supply.
Singapore
Corporate travel managers at multinational regional headquarters centralize mobility spend through master service agreements bundling multiple service types. The Land Transport Authority vehicle quota system constrains fleet expansion velocity through certificate-of-entitlement auctions. Marina Bay and the Central Business District concentrate chauffeured executive transport where extended vehicle lifecycles amortize permit costs.
Malaysia
Intercity business corridors connecting Kuala Lumpur to Penang and Johor Bahru drive sedan-dominant corporate road transport demand. The Land Public Transport Agency (APAD) mandates vehicle safety standards that reshape fleet renewal cycles across the peninsula. Kuala Lumpur International Airport serves as the primary gateway where airport counter networks anchor corporate account relationships.
Indonesia
Executive road transport on the Jakarta-Bandung corridor competes with domestic aviation for business travel wallet share. The Ministry of Transportation coordinates with the National Standardization Agency on emission testing protocols that filter older diesel units from rental eligibility in Jakarta and Surabaya. Bluebird Group's integrated taxi-to-rental dispatch infrastructure dominates the chauffeured segment through captive driver pools.
Vietnam
Road infrastructure improvements connecting Da Nang to Hoi An and Hue open highland tourism routes previously served only by coach services. Provincial transport departments implement commercial licensing requirements that vary across the coastal corridor. Da Nang International Airport emerges as the fastest-growing rental node where SUV fleet expansion captures diversifying tourism demand.
ASEAN Car Rental Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with international mobility groups leveraging airport counter networks against asset-light platform competitors entering without captive fleet burdens. The market structures around three tiers: legacy operators with owned fleet and physical infrastructure, digital-native aggregators with inventory-light models, and integrated transport groups spanning taxi, rental, and chauffeured services. Dominant competitive moves include strategic partnerships with hospitality chains for seamless booking integration and geographic expansion through master service agreements with corporate travel managers.
Within the legacy operator tier, Europcar Mobility Group and Avis Budget Group represent the airport-centric archetype with established counter networks across Singapore and Kuala Lumpur. Bluebird Group occupies a distinct position as an integrated transport specialist leveraging Indonesia's taxi-to-rental dispatch infrastructure. Among digital-native entrants, SOCAR Mobility Malaysia exemplifies the asset-light platform model that compresses customer acquisition costs through mobile-first booking experiences.
| Leading Market Players |
|---|
| Europcar Mobility Group |
| INDORENT |
| Avis Budget Group |
| Tribecar Pte Ltd |
| Bluebird Group |
| Sixt SE |
| Enterprise Holdings Inc. |
| SOCAR Mobility Malaysia |
| Hertz Global Holdings |
| Others |
Value Chain & Pricing Dynamics
Captive fleet ownership across Thailand, Malaysia, and Indonesia anchors pricing power for legacy operators while compressing margins for asset-light entrants lacking vehicle depreciation control. This vertical integration choice determines how certificate-of-entitlement costs in Singapore and APAD compliance timelines in Malaysia translate into rate premiums versus platform-aggregator spot pricing.
Pricing Analysis
Distributor margins at airport counter networks capture the largest share of end-user rates, with Europcar and Avis Budget Group commanding premium positioning through corporate master service agreements. Three-tier pricing structure across premium chauffeured, standard self-drive, and economy hatchback levels separates executive road transport from leisure island circuits. Cost compression in the economy tier intensifies because SOCAR Mobility Malaysia and digital-native aggregators eliminate physical infrastructure overhead. Tourists booking through hospitality API integrations exhibit highest price sensitivity; corporate travel managers in Singapore's Central Business District show least sensitivity due to consolidated procurement budgets.
Supply Chain Analysis
Dual-sourcing requirements for vehicle procurement mandate that fleet operators qualify both Japanese OEMs (Toyota, Honda) and Korean manufacturers (Hyundai, Kia) to mitigate single-source exposure. Geographic supply concentration centers on Thailand for regional vehicle assembly, Japan for hybrid powertrain technology, and South Korea for connected vehicle platforms. Raw material dependencies encompass semiconductors for telematics modules, lithium-ion cells for emerging EV fleets, and steel alloys for SUV frame construction. Tariff exposure on completely built-up imports into Indonesia and Vietnam creates procurement cost volatility. Distribution runs through airport counter networks, hotel concierge partnerships, and direct digital channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ASEAN car rental has entered late-cycle quality phase as corporate procurement centralization and telematics-enabled service tiers displace pure price competition. Demand is shifting toward premium chauffeured specifications where driver training standards and vehicle age limits command rate premiums.
For Market Incumbents: Hedge against asset-light platform erosion by deepening captive fleet control through direct OEM purchasing agreements in Thailand and Malaysia. Accelerate telematics certification investment to differentiate predictive maintenance capabilities from aggregator competitors lacking real-time vehicle monitoring. Channel control through exclusive hospitality API partnerships protects corporate account retention. For New Entrants and Emerging Players: Hospitality technology vendors represent the most accessible channel partner type for white-space penetration, enabling seamless booking integration before competitive search initiation. Target Vietnam's Da Nang-Hue coastal corridor where SUV fleet gaps persist amid infrastructure improvements. Penetrate the monthly subscription segment through mobile-first subscription onboarding that legacy operators have underdeveloped. For Investors and Strategic Acquirers: Roll-up economics work for mid-size regional fleet operators because fragmented local permit regimes and varying national safety certifications prevent rapid organic expansion across ASEAN borders. Five-to-ten year viability hinges on regulatory compliance infrastructure that smaller players cannot replicate. Watch for Indonesia's Ministry of Transportation emission testing protocol enforcement as inflection indicator for fleet replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Telematics Platform Integration | Embedded GPS diagnostic modules enable contactless handoff workflows at Bangkok Suvarnabhumi Airport. |
| Hospitality API Partnership | Direct property management system connections capture leisure travelers before aggregator search begins. |
| Chauffeured Service Expansion | Executive driver pools in Jakarta-Bandung corridor compete with domestic aviation for business wallet share. |
| SUV Fleet Diversification | Four-wheel-drive inventory captures Vietnam highland tourism routes previously served only by coaches. |
| Monthly Subscription Rollout | Predictable recurring revenue models displace volatile daily-rate transaction economics across ASEAN markets. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with fleet operations directors, corporate travel managers, hospitality technology vendors, and APAD compliance officers alongside secondary validation. Secondary sources encompassed Thailand Department of Land Transport fitness certification records, Singapore Land Transport Authority vehicle quota auction data, Indonesia Ministry of Transportation emission testing protocols, and customs trade data on vehicle imports. Bottom-up fleet size modeling and top-down tourism arrival projections were triangulated against corporate mobility spend estimates.
Comparable-period anchoring used historical utilization rates and revenue per available vehicle day across the projection horizon. Segmentation dimensions modeled encompassed service type, vehicle class, rental duration cadence, and client archetype. CAGRs were derived from regression analysis of fleet expansion velocity against regulatory permit constraints. Industry-specific forecast inputs included certificate-of-entitlement auction price trajectories and telematics adoption curves in Bangkok and Kuala Lumpur.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Indonesia's diesel emission enforcement timing and Vietnam infrastructure completion schedules. Deviation in Singapore's vehicle quota auction mechanics would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation Services
Bike Rental Market
Transportation Services
Ship Management Software Market
Transportation Services
Philippines Car Rental Market
Transportation Services
Refuse Truck Market
Transportation Services
Spain Car Rental Market
Transportation Services
India Two-Wheelers Rental Market
Transportation Services
Malaysia Car Rental Market
Transportation Services
Vietnam Taxi Market
Transportation Services
India Car Rental Market
Transportation Services
Third Party Logistics Services Market
Transportation Services
Vietnam Car Rental Market
Transportation Services
ASEAN Taxi Market
Transportation Services
Australia Taxi Market
Transportation Services
Poland Car Rental Market
Transportation Services
Sanitation Vehicle Market
Transportation Services
Europe Refrigerated Truck Rental Market