
 Corporate Employee Transportation Service Market | 2026-2036
Corporate Employee Transportation Service Market Size, Share, and Industry Trends Forecast 2026-2036
Corporate Employee Transportation Service Market Analysis
The US EPA emissions standards for commercial fleets is repositioning the cost-of-entry calculus for operators serving corporate clients. Uber Technologies Inc leverages its driver network density to sustain urban coverage advantages. Lyft Inc anchors its position through healthcare and retail sector partnerships. Transdev Group dominates fixed-route shuttle contracts with large enterprise campuses.
Corporate employee transportation services encompass scheduled shuttle operations, on-demand ride pooling, and dedicated fleet management solutions designed to move workers between residences and workplaces with defined pickup windows, route optimization algorithms, and duty-of-care compliance protocols. These services reduce parking infrastructure burdens, cut individual commuting costs, and support corporate carbon footprint targets through consolidated mobility. Shuttle services and ride hailing capture the dominant revenue share as employers prioritize predictable scheduling alongside flexible overflow capacity. Electric vehicles within the fleet mix represent the fastest-expanding category, driven by Scope 3 emissions accounting and total cost of ownership improvements in battery platforms.
The US Department of Transportation, India's Ministry of Road Transport and Highways, and the EU Green Deal framework collectively shape vehicle safety mandates, driver certification requirements, and emissions benchmarks that determine fleet eligibility for corporate contracts. Operators must navigate divergent national compliance layers when scaling across multinational client footprints. Stakeholders should monitor how real-time carbon reporting obligations alter contract terms and vendor selection criteria.
Market Dynamics
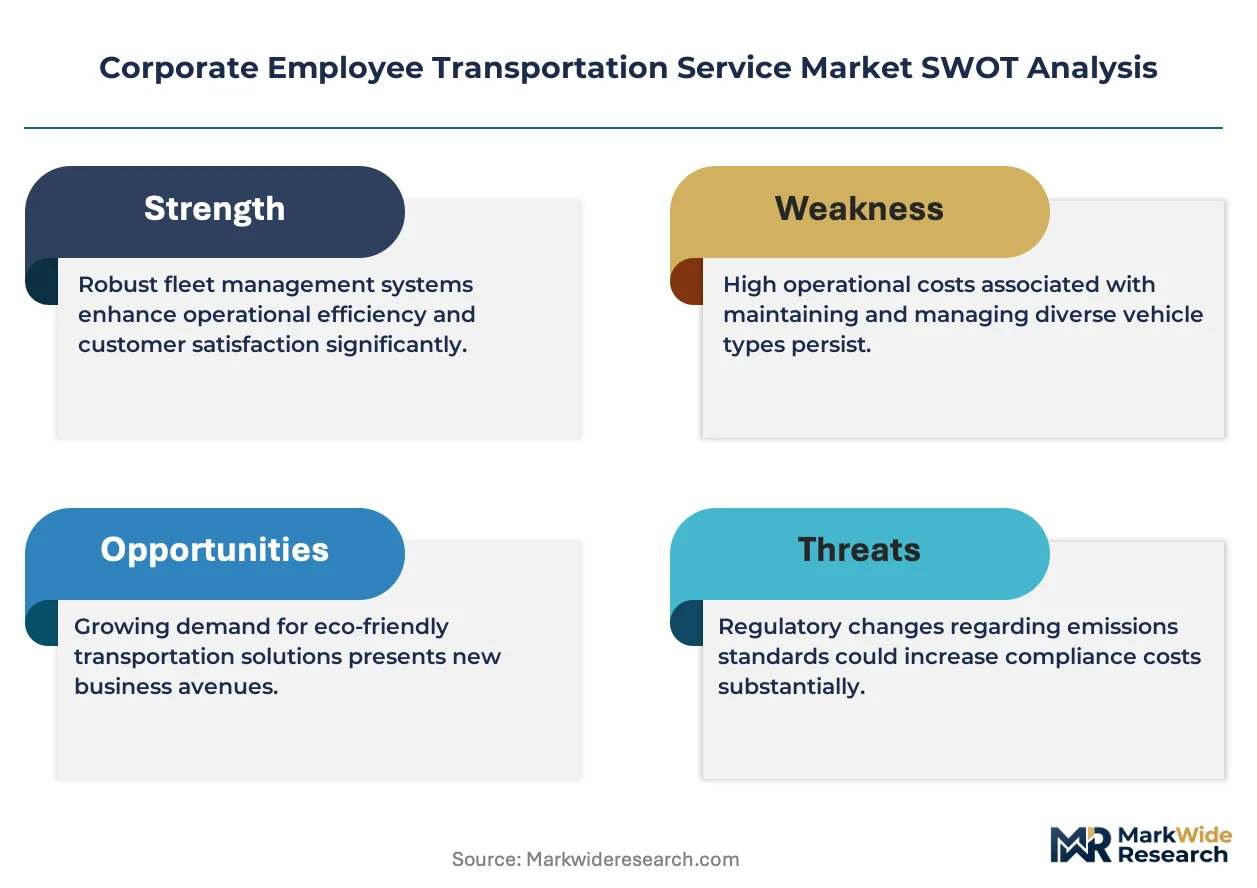
The US EPA emissions standards for commercial fleets is repositioning the cost-of-entry calculus for operators serving corporate clients. Fleet electrification mandates from India's Motor Vehicles Act amendments and state-level EV directives are forcing asset-heavy capital redeployment across multi-national contract portfolios.
Growth Catalysts
- Scope 3 emissions accounting:Corporate sustainability officers now mandate verified carbon reporting for employee commuting categories. This creates procurement preference for shuttle operators with certified electric fleet percentages and real-time telematics dashboards.
- India's PLI scheme for automotive:Domestic battery and EV component manufacturing incentives reduce total cost of ownership for fleet operators. Technology campuses in Bengaluru, Hyderabad, and Pune corridor expand contracted shuttle volumes accordingly.
- Route optimization algorithms:Machine learning platforms reduce empty vehicle kilometers and driver idle time. Large enterprise campuses achieve 15-25% efficiency gains against static routing protocols.
Market Restraints
- Lithium-ion cell supply concentration:Cathode active material processing clusters in specific East Asian jurisdictions create input cost volatility. Fleet electrification timelines extend when battery procurement contracts face force majeure clauses.
- Commercial driver certification bottlenecks:India's Motor Vehicles Act amendments impose enhanced background verification and skill testing protocols. Operator expansion into secondary cities stalls where regional transport office processing queues exceed 90 days.
- Fixed infrastructure substitution:Metro rail corridor extensions and suburban rail electrification projects in dense urban corridors capture commute volumes previously served by corporate shuttles. Employer transportation budgets reallocate toward transit pass subsidies.
Strategic Opportunities
- EU Green Deal framework compliance services:Multinational corporations require Scope 3 verification aligned with CSRD disclosure rules. Fleet operators offering automated carbon accounting integration capture premium contract tiers.
- Healthcare and retail sector verticalization:Shift-based workforce scheduling in hospital networks and distribution centers demands 24-hour shuttle coverage. Specialized operators build recurring revenue through duty-of-care protocols tailored to female employee safety requirements.
- Vehicle-to-grid integration:Bidirectional charging infrastructure allows electric shuttle fleets to provide grid stabilization services during idle periods. Campus operators monetize battery assets beyond transportation function.
Industry Challenges
- Telematics platform interoperability:Corporate clients demand API integration with existing enterprise resource planning and facilities management systems. Shuttle operators face six-to-nine month deployment cycles for custom middleware development.
- Driver retention and wage compression:Gig economy ride-hailing platforms compete for commercial license holders with flexible scheduling. Scheduled shuttle operators absorb 20-30% higher per-kilometer labor costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Corporate Employee Transportation Service Market |
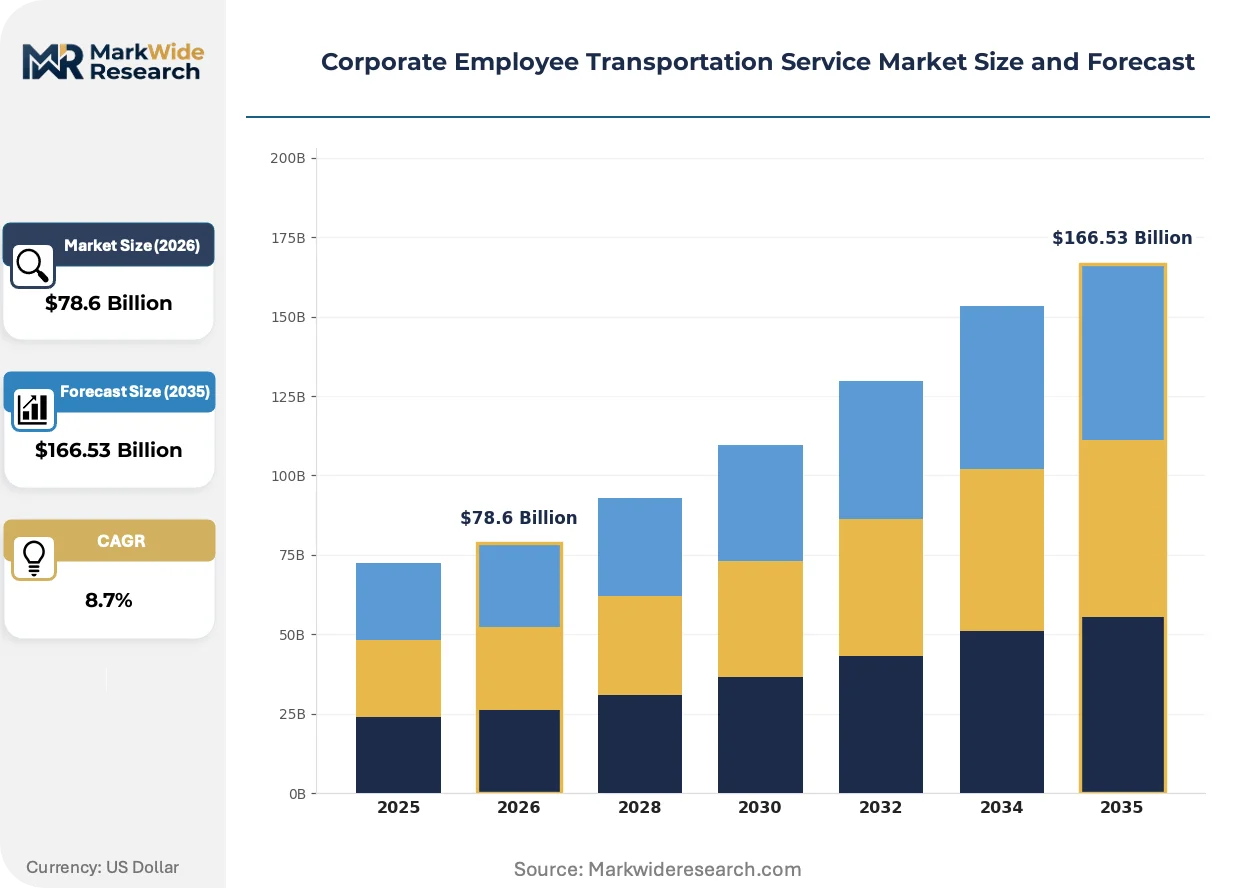
| Market Size in 2026 | $78.6 Billion |
| Market Size in 2035 | $166.53 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Shuttle Services, Carpooling, Ride Hailing, Private Transport Vehicle Type: Buses, Vans, Passenger Cars, Electric Vehicles End User: Large Enterprises, SMEs, Government Agencies, Educational Institutions Technology: GPS Tracking, Mobile Apps, Cloud Solutions, Telematics |
| Companies Covered | Transdev Group, Uber Technologies Inc, Lyft Inc, MoveInSync Technology Solutions Private Limited, FirstGroup plc, Via Transportation Inc, Swvl Holdings Corp, Curb Mobility, Ola Cabs, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Corporate Employee Transportation Service Market Emerging Trajectories
Electrification is absorbing capital allocation across fleet procurement, charging infrastructure, and energy management systems. Three distinct vectors are compressing competitive timelines and reshaping contract structures.
Artificial intelligence dispatch platforms are absorbing manual route planning functions. Large technology campuses in India deploy dynamic pooling algorithms that match real-time ride requests against vehicle capacity and traffic conditions. These systems reduce average wait times from 12 minutes to under 4 minutes, compressing the acceptable service window that defines contract renewals.
The EU Green Deal framework and associated CSRD disclosure requirements are mandating granular carbon accounting for employee mobility categories. Fleet operators must install certified telematics that feed directly into corporate sustainability reporting systems. European multinational headquarters and their Indian subsidiary campuses now exclude vendors lacking ISO 14064-aligned measurement protocols from request-for-proposal shortlists.
Subscription-based mobility budgets are displacing per-ride reimbursement models. Enterprise human resource departments consolidate shuttle, ride-hailing, and transit allowances into single digital wallets. This procurement evolution concentrates volume with platform aggregators capable of multi-modal integration, particularly visible in US technology and financial services headquarters where employee retention competes with commute flexibility as a talent priority.
Corporate Employee Transportation Service Market Segmentation
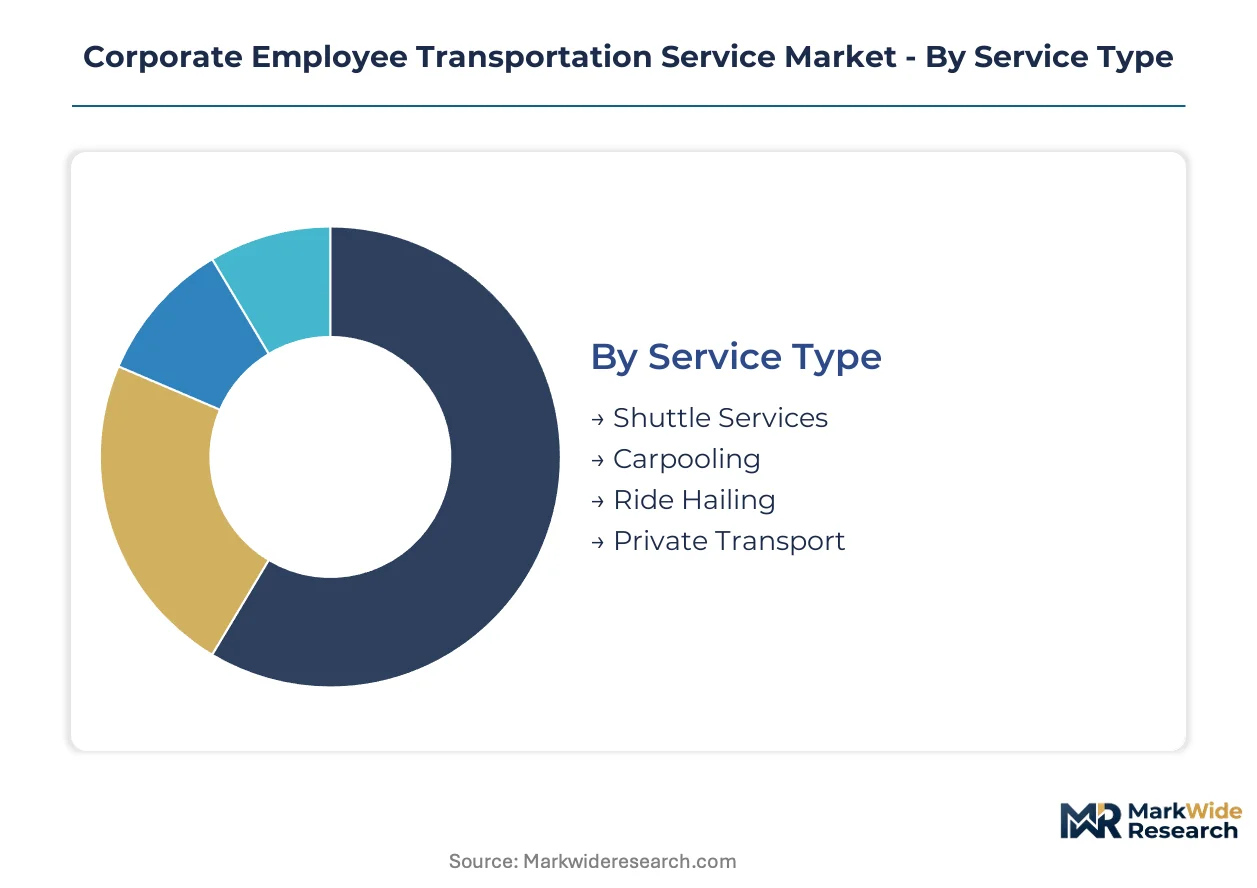
Corporate employee transportation services fragment across service models, asset types, and technology stacks that each carry distinct regulatory burdens and contract economics. Procurement teams evaluate segments against duty-of-care mandates, carbon accounting requirements, and integration complexity with enterprise systems.
Service Type:
Shuttle Services and Ride Hailing require ISO 14064-aligned carbon verification for EU Green Deal compliance, while Carpooling and Private Transport face lighter certification loads but heavier liability exposure under India's Motor Vehicles Act amendments.
- Shuttle Services:Fixed-route operations with scheduled pickup windows and dedicated fleet assets. Large technology campuses in Bengaluru, Hyderabad, and Pune corridor contract these for predictable headcount movement, with Scope 3 emissions accounting now mandating real-time telematics dashboards.
- Ride Hailing:On-demand dispatch through aggregator platforms leveraging driver network density. Urban coverage advantages sustain contract renewals where overflow capacity and flexible scheduling outweigh route optimization gains.
- Carpooling:Peer-to-peer ride matching reducing per-employee commuting costs. SME adoption concentrates where parking infrastructure constraints and limited shuttle density make shared private vehicle use economically viable.
- Private Transport:Dedicated chauffeur services for executive tiers and specialized duty-of-care requirements. Healthcare and retail sector verticalization drives 24-hour coverage contracts with female employee safety protocols.
Shuttle Services sits at the top of the volume ranking, with Ride Hailing climbing the fastest.
Vehicle Type:
Cost tiers separate asset-light operators running Passenger Cars and Vans from capital-intensive fleets deploying Buses and Electric Vehicles with bidirectional charging infrastructure.
- Buses:High-capacity articulated vehicles serving dense enterprise corridors. India's PLI scheme for automotive reduces total cost of ownership for domestic battery procurement, expanding contracted volumes on white-collar campuses.
- Electric Vehicles:Battery-electric platforms with vehicle-to-grid integration capabilities. The US EPA emissions standards reposition cost-of-entry calculus, with lithium-ion cell supply concentration creating input cost volatility that extends fleet electrification timelines.
- Vans:Mid-size capacity vehicles bridging shuttle density gaps. Route optimization algorithms compress empty vehicle kilometers, delivering 15-25% efficiency gains against static routing protocols.
- Passenger Cars:Individual and small-pool configurations for executive transport and overflow demand. Gig economy ride-hailing platforms compete for commercial license holders, forcing 20-30% higher per-kilometer labor costs on scheduled operators.
Buses retain the dominant revenue position, with Electric Vehicles gaining share fastest as Scope 3 accounting hardens procurement criteria.
End User:
Application intensity varies sharply: Large Enterprises consolidate multi-modal mobility budgets, while SMEs, Government Agencies, and Educational Institutions fragment across simpler procurement structures with lighter integration requirements.
- Large Enterprises:Multinational headquarters with CSRD disclosure obligations and automated carbon accounting integration. Subscription-based mobility budgets displace per-ride reimbursement, concentrating volume with platform aggregators capable of multi-modal integration.
- SMEs:Mid-size employers prioritizing cost containment over customization. Telematics platform interoperability demands face six-to-nine month deployment cycles that strain limited IT resources.
- Government Agencies:Public sector procurement with mandated domestic content requirements and enhanced background verification protocols. India's Motor Vehicles Act amendments impose skill testing bottlenecks where regional transport office queues exceed 90 days.
- Educational Institutions:Campus shuttle networks with seasonal demand fluctuation. Fixed infrastructure substitution from metro rail extensions captures commute volumes previously served by contracted services.
Large Enterprises command the steepest contract values, with Educational Institutions expanding most quickly as campus safety mandates harden.
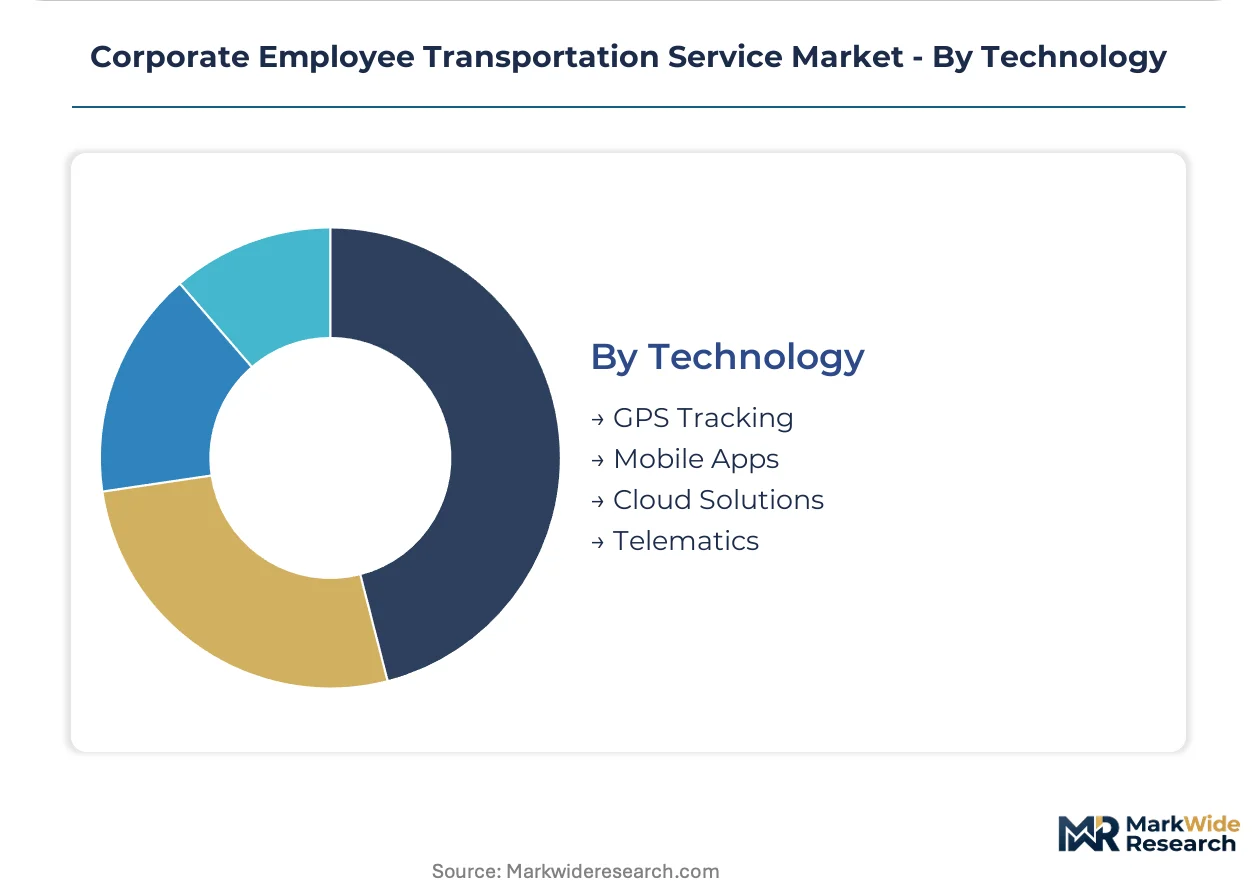
Technology:
Customer type separates enterprise-grade systems requiring API integration with ERP and facilities management platforms from lighter deployments serving smaller operators with standalone functionality.
- GPS Tracking:Real-time location monitoring for route adherence and duty-of-care compliance. Baseline capability across all service tiers with minimal certification burden.
- Telematics:Integrated vehicle diagnostics, driver behavior scoring, and carbon emissions measurement. CSRD-aligned protocols now exclude vendors lacking certified measurement systems from European multinational shortlists.
- Mobile Apps:Employee-facing booking interfaces with dynamic pooling algorithms. Large technology campuses in India reduce average wait times from 12 minutes to under 4 minutes through machine learning dispatch.
- Cloud Solutions:Centralized fleet management with scalability for multi-national contract portfolios. Divergent national compliance layers across the US, India, and EU determine system architecture complexity.
Telematics leads enterprise procurement specifications, with Cloud Solutions expanding most quickly as multinational footprint scaling accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
White-collar technology campuses and carbon accounting mandates concentrate shuttle procurement across five distinct national markets. Each geography presents divergent regulatory compliance layers and fleet electrification timelines that reshape contract economics for multinational operators.
United States
Technology headquarters in Seattle, San Francisco, and Austin anchor demand for subscription-based mobility budgets integrating shuttle, ride-hailing, and transit allowances. The US EPA emissions standards for commercial fleets reposition cost-of-entry calculus for operators serving corporate clients. Large enterprise campuses in Silicon Valley and Manhattan achieve 15-25% efficiency gains through machine learning dispatch platforms.
India
Technology campuses in Bengaluru, Hyderabad, and Pune corridor expand contracted shuttle volumes as domestic manufacturing incentives reduce electric fleet ownership costs. India's Motor Vehicles Act amendments impose enhanced background verification and skill testing protocols that stall operator expansion where regional transport office queues exceed 90 days. The PLI scheme for automotive accelerates battery procurement localization for fleet electrification programs.
Germany
Automotive and industrial headquarters in Munich, Stuttgart, and Wolfsburg mandate ISO 14064-aligned carbon verification for employee mobility categories. The EU Green Deal framework and CSRD disclosure requirements exclude vendors lacking certified telematics measurement protocols from request-for-proposal shortlists. Bidirectional charging infrastructure allows electric shuttle fleets to provide grid stabilization services during idle periods.
United Kingdom
Financial services and professional services clusters in London, Manchester, and Edinburgh consolidate multi-modal mobility budgets into single digital wallets. CSRD-aligned protocols now require automated carbon accounting integration for premium contract tiers. Healthcare and retail sector verticalization drives 24-hour shuttle coverage contracts with duty-of-care protocols tailored to female employee safety requirements.
China
Technology campuses in Beijing, Shanghai, and Shenzhen deploy dynamic pooling algorithms that reduce average wait times from 12 minutes to under 4 minutes. National dual carbon goals and MIIT fleet electrification directives compress competitive timelines for battery-electric platform deployment. Vehicle-to-grid integration capabilities allow campus operators to monetize battery assets beyond transportation function.
Corporate Employee Transportation Service Market Vendor Landscape
The competitive structure tilts toward platform aggregators with multi-modal integration capabilities and asset-heavy shuttle specialists with fixed-route expertise. Consolidation pressures concentrate volume with operators capable of API integration with enterprise resource planning systems. Two strategic archetypes dominate: technology-enabled aggregators leveraging driver network density for urban coverage, and dedicated fleet managers securing long-term campus contracts through duty-of-care compliance. Dominant competitive moves include strategic partnerships with human resource departments for mobility budget consolidation and geographic expansion into secondary cities through acquisition of regional shuttle licenses.
Within the platform-aggregator tier, Uber Technologies Inc and Lyft Inc exemplify network-density positioning for overflow capacity and flexible scheduling. Transdev Group occupies a position as the fixed-route shuttle specialist securing large enterprise campus contracts through predictable scheduling and dedicated fleet assets. MoveInSync Technology Solutions Private Limited represents the India-focused technology platform archetype serving white-collar technology corridors with route optimization algorithms.
| Leading Market Players |
|---|
| Transdev Group |
| Uber Technologies Inc |
| Lyft Inc |
| MoveInSync Technology Solutions Private Limited |
| FirstGroup plc |
| Via Transportation Inc |
| Swvl Holdings Corp |
| Curb Mobility |
| Ola Cabs |
| Others |
Supply Flow & Price Mechanics
Fleet electrification mandates across the US EPA, India's Motor Vehicles Act amendments, and the EU Green Deal framework simultaneously reshape capital deployment patterns and supplier concentration. Battery-electric platform procurement now dictates contract economics, with lithium-ion cell sourcing clusters determining which operators capture premium corporate accounts.
Pricing Analysis
Bundled subscription mobility budgets now dominate enterprise procurement, displacing per-ride reimbursement structures. Price differentiation rests on ISO 14064-aligned carbon verification tiers and real-time telematics integration depth. Cost compression in mid-market shuttle tiers is intensifying because gig economy platforms compete for commercial license holders. SMEs exhibit highest price sensitivity, while large enterprises prioritize duty-of-care compliance over rate negotiation.
Supply Chain Analysis
Single-source vulnerability sits with cathode active material processing concentrated in specific East Asian jurisdictions. Lithium-ion cells, electric drivetrains, and charging infrastructure components draw from China, South Korea, and Japan manufacturing bases. Tariff exposure on battery imports threatens fleet electrification timelines for operators without long-term procurement contracts. Distribution runs through OEM-direct fleet sales and specialized commercial vehicle dealers serving campus operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Corporate Employee Transportation Service Market functions as a stable compounder, with Scope 3 emissions accounting mandating verified carbon reporting that locks in recurring contract renewals. Enterprise sustainability officers now treat employee mobility as a compliance category rather than a discretionary spend.
For Market Incumbents: Deploy API integration capabilities as the primary defensive moat. Transdev Group and fixed-route specialists should deepen ERP connectivity investments to match platform-aggregator interoperability. Threats from ride-hailing network density require certification in ISO 14064-aligned measurement protocols to maintain European multinational shortlist eligibility. Backward integration into charging infrastructure ownership captures vehicle-to-grid revenue streams beyond transportation function. For New Entrants and Emerging Players: Begin with healthcare and retail sector verticalization where 24-hour shift coverage demands remain underserved. Female employee safety protocols and duty-of-care compliance represent the most penetrable service tier. Secondary Indian cities with regional transport office processing bottlenecks offer license acquisition opportunities ahead of incumbent expansion. A go-to-market angle anchored in automated carbon accounting integration captures CSRD-aligned contract premiums. For Investors and Strategic Acquirers: Roll-up economics work for regional shuttle operators with established campus contracts because multinational clients demand geographic coverage breadth that fragments vendor selection. Five-to-ten year viability rests on electrification capex deployment timing and battery asset utilization rates. Acquisition targets should demonstrate contracted revenue visibility with technology campuses in Bengaluru, Hyderabad, or Pune corridor. The signal to watch is lithium-ion cell supply contract renegotiation frequency as a proxy for input cost volatility exposure.| Strategic Initiative | Industry Significance |
|---|---|
| Telematics Platform Integration | API connectivity with ERP systems secures renewal rates with CSRD-mandated enterprises. |
| Bidirectional Charging Infrastructure | Vehicle-to-grid capabilities monetize idle battery assets for campus grid stabilization services. |
| Healthcare Sector Verticalization | 24-hour duty-of-care protocols for female employees build recurring revenue in hospital networks. |
| Secondary City License Acquisition | Regional transport office queue advantages in India create geographic expansion runway. |
| Carbon Accounting Certification | ISO 14064-aligned measurement protocols determine European multinational RFP eligibility. |
Methodological Framework
Coverage spans the United States, India, Germany, United Kingdom, and China, with primary inputs from each market informing demand calibration. The research combines interviews with fleet operations directors, corporate sustainability officers, regional transport office administrators, and campus facilities managers with secondary validation against EPA filings, EU Green Deal implementation documents, India's PLI scheme notifications, and corporate ESG disclosure reports. Bottom-up route density modeling and top-down market sizing triangulate volume estimates.
Granularity-level modeling deploys service type, vehicle type, end user, and technology stack as core segmentation dimensions, with regional regulatory cluster as an overlay variable. CAGRs derive from contracted fleet expansion trajectories across the projection horizon, incorporating India's Motor Vehicles Act amendment implementation pace and EU CSRD disclosure phase-in schedules. Analysis incorporates electric vehicle total cost of ownership curves and driver certification bottleneck duration assumptions.
Caveats apply where lithium-ion cell supply disruptions or metro rail corridor extensions could materially shift the outlook. Forecasts incorporate assumptions around battery platform cost trajectories and carbon accounting mandate enforcement intensity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation Services
Bird Carriers Market
Transportation Services
ASEAN Taxi Market
Transportation Services
India Car Rental Market
Transportation Services
Cross Docking Services Market
Transportation Services
Global Garbage Truck Market
Transportation Services
Indonesia Car Rental Market
Transportation Services
Scandinavia Car Rental Market
Transportation Services
Australia Taxi Market
Transportation Services
Germany Car Rental Market
Transportation Services
Vietnam Car Rental Market
Transportation Services
Vacuum Truck Rentals Market
Transportation Services
Truck Rental Market
Transportation Services
Europe Vehicle Rental Market
Transportation Services
Refuse Truck Market
Transportation Services
Airline Passenger Service System Market
Transportation Services
Airport Handling Service Market