
 United Arab Emirates Car Rental Market | 2026-2036
United Arab Emirates Car Rental Market Size, Share, and Industry Trends Forecast 2026-2036
United Arab Emirates Car Rental Market Analytics
App-based booking platforms is reshaping how fleets reach customers across the Emirates. eZhire Technologies leverages its digital-first model to eliminate traditional counter transactions. Europcar International anchors its position through airport concession dominance and corporate account depth. The Hertz Corporation competes via premium fleet composition and loyalty program integration with hospitality chains.
Car rental denotes the short-term commercial provision of motorized vehicles under contractual terms specifying mileage limits, insurance coverage, and return conditions. Fleet procurement emphasizes fuel efficiency ratings, telematics integration, and rapid turnaround maintenance protocols to maximize asset utilization. Short-term rentals command premium per-day yields during peak tourism windows, while corporate service models generate predictable recurring revenue through multi-year fleet outsourcing agreements. Chauffeur-driven offerings capture high-margin executive transport segments, particularly among business travelers accessing Dubai International Financial Centre and Abu Dhabi Global Market zones.
MOHAP enforces commercial vehicle fitness standards that mandate periodic safety inspections for all rental fleet units. The UAE's federal traffic authority coordinates with emirate-level economic departments to regulate operator licensing and insurance minimums. Stakeholders must monitor evolving autonomous vehicle trial frameworks and carbon neutrality commitments that will redefine fleet composition requirements and capital allocation priorities.
Market Dynamics
MOHAP's commercial vehicle fitness mandates are compressing fleet turnover cycles across the Emirates. Operators now face accelerated capital redeployment timelines as safety inspection protocols tighten.
Growth Catalysts
- Smart Mobility Integration:The UAE's federal smart city frameworks mandate connected vehicle infrastructure. Rental operators deploying telematics-enabled fleets gain preferential access to Dubai's integrated transport corridors.
- Corporate Fleet Outsourcing:Logistics and construction firms in Abu Dhabi's Khalifa Industrial Zone are shedding owned vehicle assets. Multi-year service agreements generate predictable revenue streams for rental providers.
- Chauffeur-Driven Premium Segments:Executive transport demand concentrates around Dubai International Financial Centre and Abu Dhabi Global Market. Business travelers prioritize time efficiency over self-drive flexibility.
Market Restraints
- Fleet Depreciation Velocity:Accelerated MOHAP inspection cycles force shorter asset holding periods. Capital recovery timelines compress against residual value uncertainty.
- Insurance Premium Volatility:UAE federal traffic authority minimum coverage requirements fluctuate with claims experience. Underwriting costs erode margin predictability on short-term rentals.
- Airport Concession Concentration:Dubai International and Zayed International terminal access routes through limited concession holders. New market entrants face structural barriers to high-yield tourist segments.
Strategic Opportunities
- Autonomous Vehicle Trial Frameworks:The UAE's federal transport authority pilots self-driving fleets in designated Dubai zones. Early regulatory alignment positions operators for fleet composition pivots.
- Carbon Neutrality Commitments:Federal emissions targets incentivize electric vehicle procurement. Charging infrastructure density in Abu Dhabi's business districts enables premium positioning.
- Free Zone Corridor Density:Dubai South and Jebel Ali logistics clusters generate concentrated B2B demand. Proximity-based service models reduce customer acquisition costs.
Industry Challenges
- Telematics Integration Complexity:Legacy fleet management systems resist seamless connectivity upgrades. Middleware development demands specialized technical talent scarce in the Emirates.
- Compliance Certification Timelines:MOHAP fitness inspections require documentation translation across Arabic and English protocols. Administrative friction delays vehicle redeployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Arab Emirates Car Rental Market |
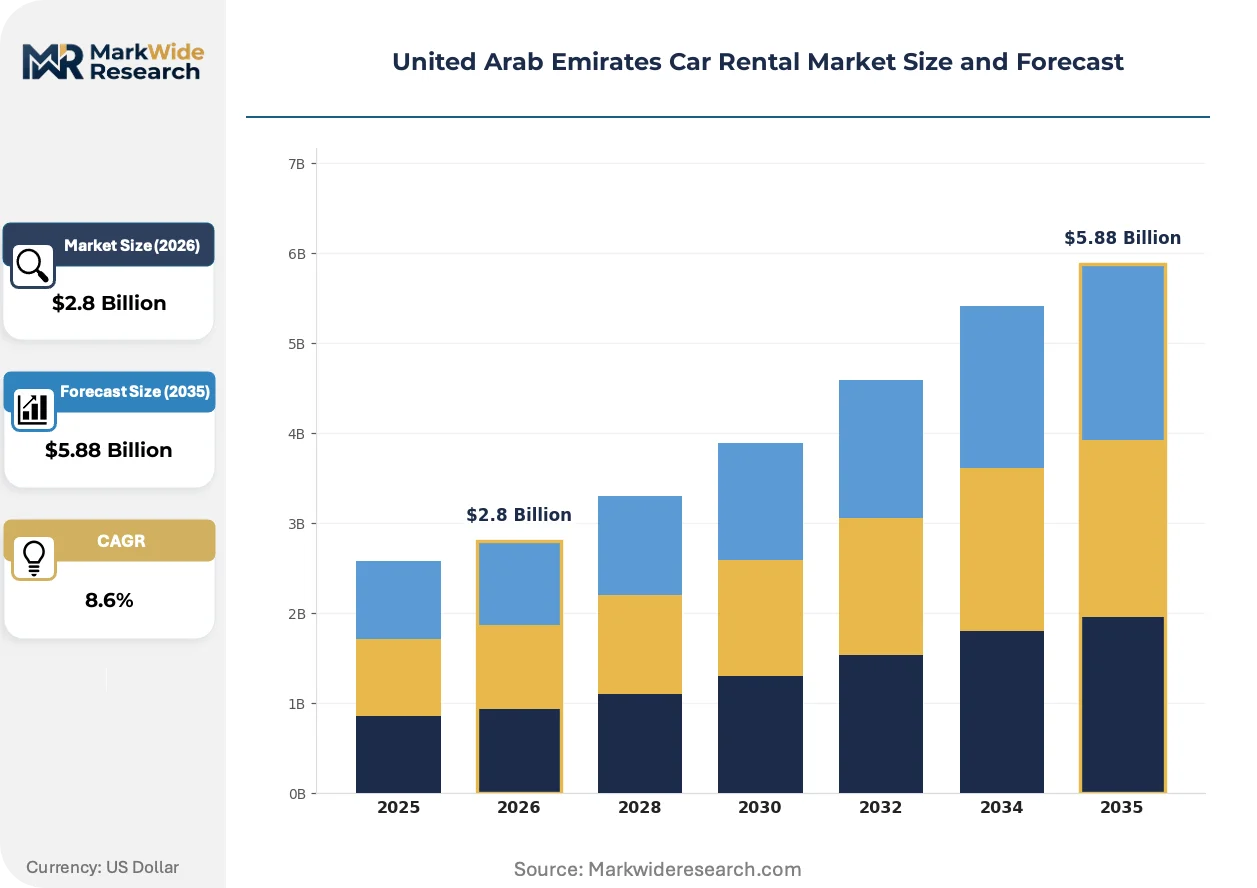
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.88 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: SUV, Sedan, Hatchback, Luxury Rental Duration: Short-term, Long-term, Daily, Weekly Service Model: On-demand, Self-drive, Chauffeur-driven, Corporate Customer Segment: Tourists, Business Travelers, Locals, Expats |
| Companies Covered | The Hertz Corporation, eZhire Technologies, Europcar International, Careem, Thrifty Car Rental, Avis Budget Group, Enterprise Holdings, Massar Solutions, SIXT SE, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Arab Emirates Car Rental Market Evolving Landscape
Digital-native booking architectures are fragmenting traditional counter-based rental economics. Platform intermediation restructures how fleet operators capture customer relationships.
App-based reservation systems is collapsing the distinction between on-demand mobility and scheduled rental. Dubai-based corporate accounts now expect sub-15-minute vehicle deployment. Fleet operators integrating with enterprise expense management platforms capture recurring contract renewals. The technology is collapsing price transparency barriers that once protected incumbent airport concessionaires.
MOHAP's vehicle safety inspection mandates now require real-time telematics data submission. Commercial fleet operators must retrofit existing assets with compliant monitoring hardware. Smaller rental firms lacking technical integration capabilities face operational suspension risks. Dubai-based operators are responding fastest through third-party telematics service partnerships.
Subscription-based mobility packages are displacing traditional daily-rate structures among UAE corporate buyers. Logistics firms in Sharjah's industrial zones now prefer all-inclusive monthly vehicle access over ownership. Fleet providers bundling maintenance, insurance, and replacement vehicles capture multi-year commitments. This shift concentrates most visibly among mid-size construction contractors operating across northern emirates.
United Arab Emirates Car Rental Market Segmentation
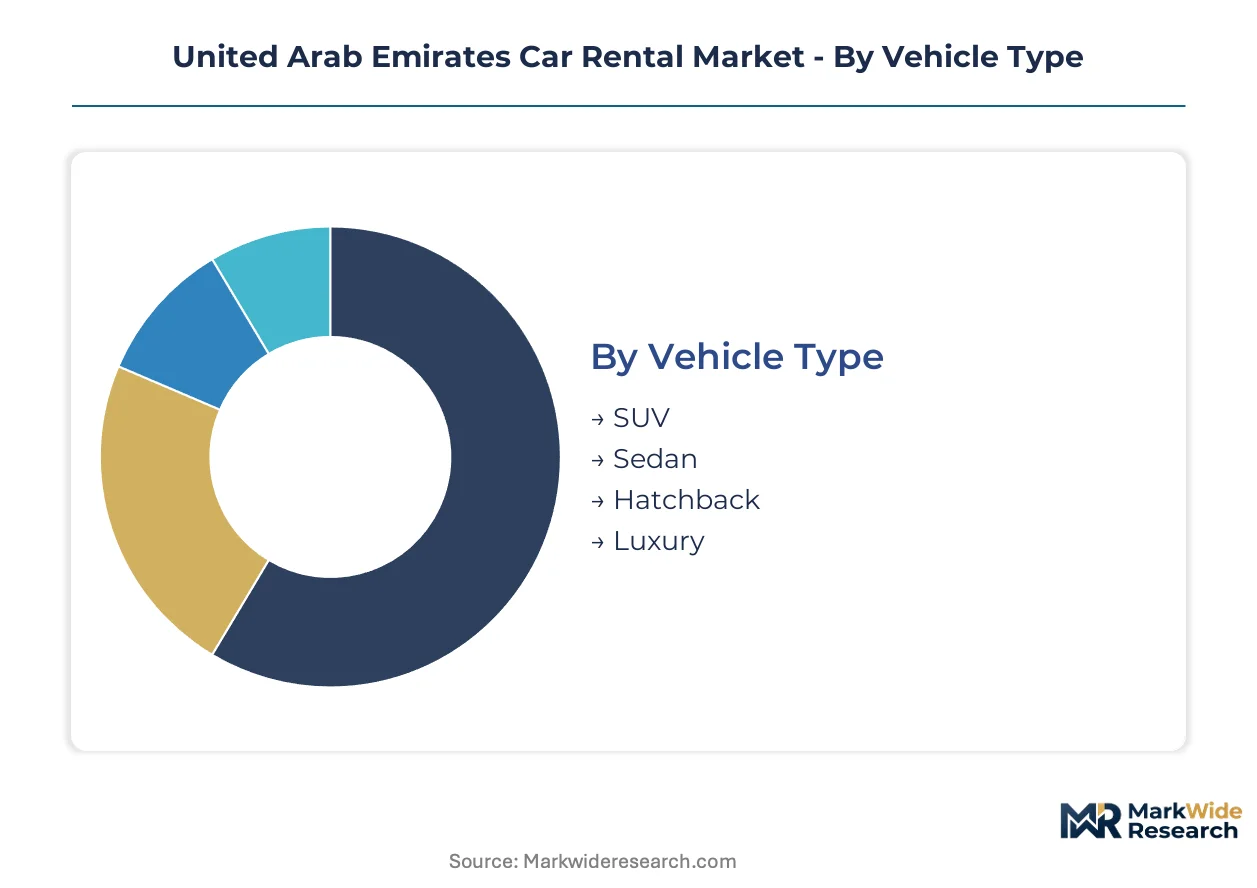
Fleet composition and service architecture in the Emirates rental market diverge sharply across customer use cases. After-sales intensity varies dramatically between corporate multi-year contracts and tourist single-day rentals.
Vehicle Type:
After-sales service intensity peaks with luxury fleet segments requiring specialized maintenance partnerships and rapid replacement protocols.
- SUV:Four-wheel-drive configurations dominate desert tourism circuits and family transport. Demand concentrates in Dubai's hospitality corridors serving inbound visitors seeking off-road accessibility alongside urban utility.
- Sedan:Three-box passenger vehicles with standardized powertrains deliver operational simplicity for high-turnover rental pools. Corporate accounts in Abu Dhabi's business districts favor black sedan fleets for executive ground transport.
- Hatchback:Compact two-box designs optimize parking efficiency in dense urban cores. Budget-conscious expat residents in Sharjah's residential zones drive consistent demand for economy-focused daily rentals.
- Luxury:Premium marques with bespoke interior specifications command elevated daily rates. Chauffeur-driven deployments around Dubai International Financial Centre require manufacturer-certified service centers within 30-minute response radii.
By volume, Sedan leads. By growth pace, Luxury is ahead.
Rental Duration:
Cost tier differentiation separates capital-light daily operations from asset-heavy long-term fleet commitments.
- Short-term:Hourly to multi-day contracts with premium per-unit yields during seasonal peaks. Airport concessionaires at Dubai International capture inbound tourist flows with immediate vehicle deployment.
- Long-term:Monthly to annual agreements transferring maintenance liability to operators. Logistics firms in Jebel Ali Free Zone prefer predictable cost structures over ownership complexity.
- Daily:Single-calendar-day pricing with highest revenue volatility. Weekend demand spikes in Dubai Marina and Downtown districts strain fleet availability.
- Weekly:Seven-day bundled rates targeting extended-stay business visitors. Abu Dhabi Global Market professionals on project assignments generate recurring weekly contract renewals.
Short-term contracts dominate transaction count. Long-term agreements deliver superior margin stability.
Service Model:
Application-specific deployment architectures reshape how operators allocate fleet assets across mobility use cases.
- On-demand:App-triggered vehicle delivery eliminating physical counter interactions. eZhire Technologies pioneered sub-15-minute deployment windows across Dubai's free zone corridors.
- Self-drive:Customer-operated rentals with mileage-capped insurance terms. Young expat professionals in Dubai South favor this model for weekend mobility without ownership burden.
- Chauffeur-driven:Professional driver provision with time-based billing increments. Executive transport demand clusters around Abu Dhabi Global Market and Dubai International Financial Centre entry points.
- Corporate:Multi-year fleet outsourcing with bundled maintenance and replacement guarantees. Construction contractors operating across northern emirates shed owned assets for operational flexibility.
Self-drive generates highest unit volume. Corporate contracts are climbing the fastest.
Customer Segment:
Customer type determines acquisition cost structures and lifetime value trajectories across Emirates rental operations.
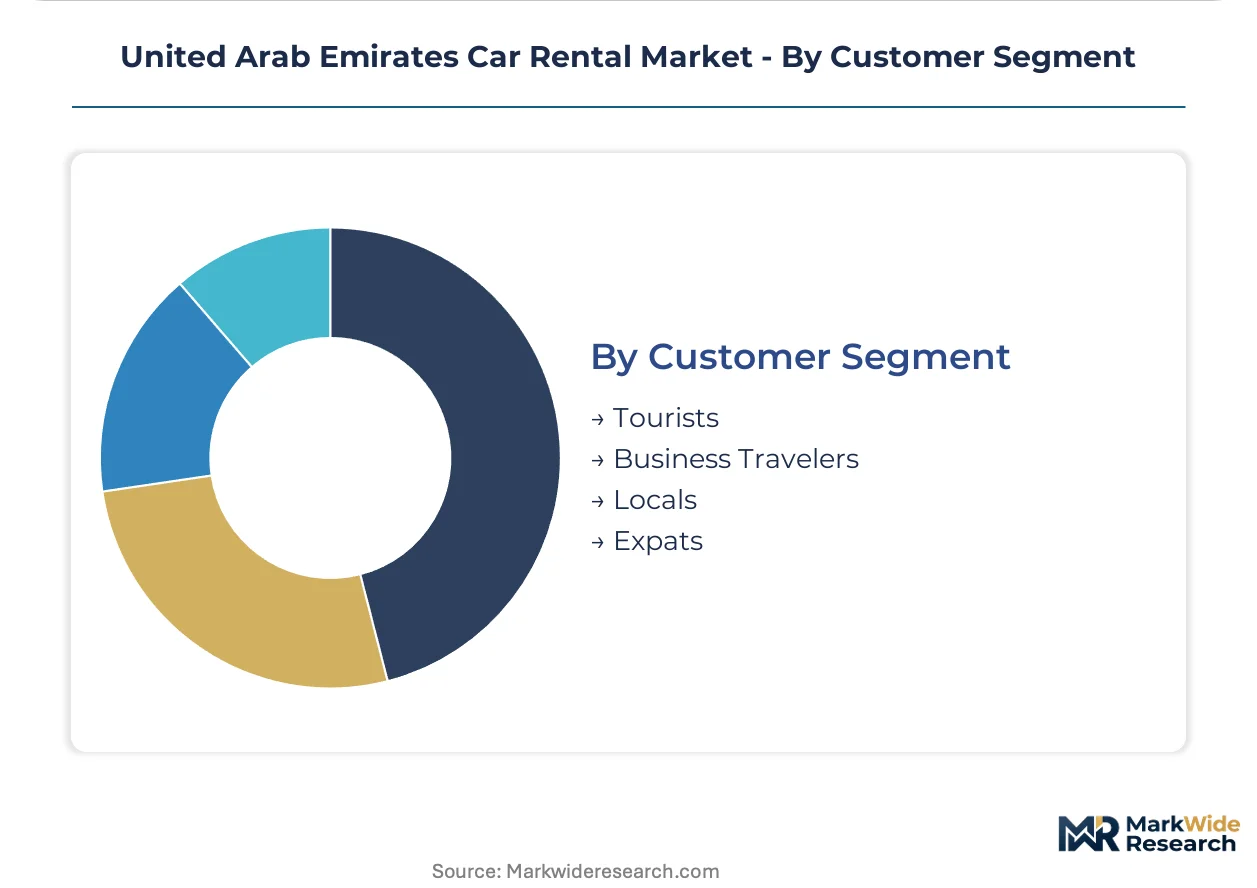
- Tourists:Inbound visitors with price-sensitive booking behavior and peak-season concentration. Dubai International Airport terminal access routes through limited concession holders create supply bottlenecks.
- Business Travelers:Time-priority customers accepting premium rates for reliability and convenience. Dubai International Financial Centre proximity drives chauffeur-driven preference over self-drive flexibility.
- Locals:UAE nationals seeking supplemental mobility for specific occasions. Family-sized SUV demand spikes during Eid and National Day holiday periods.
- Expats:Long-term residents without vehicle ownership requiring sustained rental relationships. Sharjah's industrial zone workforce generates predictable monthly renewal patterns.
Tourists represent largest transaction volume. Business travelers show steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Jebel Ali Port's container throughput capacity anchors the UAE's logistics infrastructure and underwrites fleet demand across the emirates' industrial corridors.
Dubai
Dubai International Airport's passenger volumes drive short-term rental density among inbound tourists. MOHAP's vehicle fitness mandates compress fleet turnover cycles for operators serving the emirate. Dubai South and Jebel Ali Free Zone logistics clusters generate concentrated B2B demand for corporate fleet outsourcing.
Abu Dhabi
Abu Dhabi Global Market's financial sector concentration elevates chauffeur-driven executive transport requirements. The emirate's economic department coordinates with federal traffic authorities on operator licensing protocols. Khalifa Industrial Zone construction and logistics firms are shedding owned vehicle assets for multi-year rental agreements.
Sharjah
Sharjah's industrial zone workforce generates predictable monthly renewal patterns among expat residents without vehicle ownership. The emirate's economic development office enforces commercial vehicle registration standards aligned with federal frameworks. Residential density in Sharjah's urban cores drives consistent demand for economy-focused daily rentals.
Northern Emirates
Ras Al Khaimah and Fujairah tourism development projects are expanding seasonal rental demand for desert-accessible SUV fleets. Federal smart mobility frameworks mandate connected vehicle infrastructure across all seven emirates. Northern emirate construction contractors operating across multiple sites prefer subscription-based mobility packages over asset ownership.
United Arab Emirates Car Rental Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in fleet procurement and maintenance services. The UAE car rental market structures around three distinct player archetypes: airport concessionaires with terminal access rights, digital-native platforms eliminating counter transactions, and corporate fleet outsourcers with multi-year contract expertise. Dominant competitive moves include strategic partnerships with hospitality chains for loyalty program integration and portfolio diversification into chauffeur-driven executive segments.
Among international airport concessionaires, Europcar International and The Hertz Corporation exemplify premium positioning archetypes. eZhire Technologies occupies the digital-native tier with its app-triggered vehicle delivery model. These three anchors represent divergent strategic paths: legacy concession dominance, technology-led disintermediation, and hybrid platform-service integration.
| Leading Market Players |
|---|
| The Hertz Corporation |
| eZhire Technologies |
| Europcar International |
| Careem |
| Thrifty Car Rental |
| Avis Budget Group |
| Enterprise Holdings |
| Massar Solutions |
| SIXT SE |
| Others |
Value Network & Pricing Analysis
MOHAP's commercial vehicle fitness mandates compress fleet turnover cycles and force accelerated capital redeployment timelines. This regulatory chokepoint determines both pricing tier spreads and supply chain shape across Emirates rental operations.
Pricing Analysis
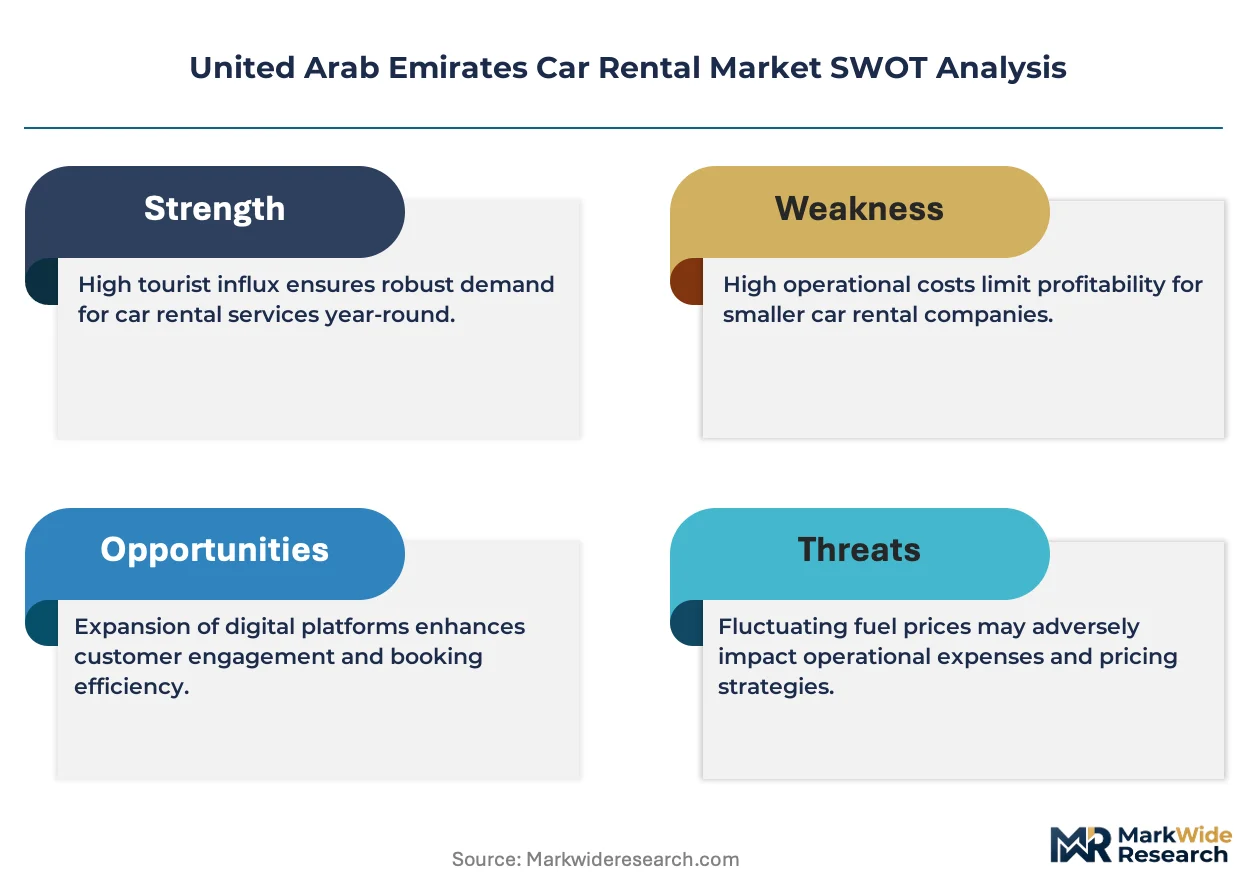
Volume-discount tiering structures separate corporate multi-year contracts from tourist single-day rentals. Three-tier pricing stratifies across premium chauffeur-driven services, standard self-drive sedans, and economy hatchback segments. Price differentiation hinges on after-sales bundling intensity and telematics certification compliance. Cost compression in short-term daily rentals intensifies as airport concessionaires compete for inbound tourist flows. Corporate buyers show lowest price sensitivity due to predictable cost structure preferences.
Supply Chain Analysis
Tariff exposure between Japan and South Korea dominates fleet procurement risk for hybrid and electric vehicle components. Vehicle sourcing draws from Japan, South Korea, and Germany for powertrain assemblies and telematics hardware. Raw material dependencies center on lithium-ion battery cells, semiconductor chips, and aluminum body panels. Single-source vulnerability concentrates in advanced driver-assistance system suppliers. Distribution runs through Dubai's Jebel Ali Port with secondary routing to Abu Dhabi and northern emirate logistics clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UAE car rental market sits at an early-cycle expansion story justified by accelerating corporate fleet outsourcing adoption among logistics and construction firms.
For Market Incumbents: Pre-empt digital-native platform erosion by integrating enterprise expense management systems and securing multi-year corporate contracts. Incumbents should deepen backward integration into telematics service partnerships to offset middleware development talent scarcity. Airport concession dominance remains defensible through hospitality chain loyalty program integration.
For New Entrants and Emerging Players: Build out proximity-based service models targeting Dubai South and Jebel Ali Free Zone logistics corridors where B2B demand concentrates. The most penetrable segment lies in subscription-based mobility packages for mid-size construction contractors across northern emirates. A fleet-light asset partnership model with existing maintenance providers accelerates market entry without capital-heavy vehicle procurement.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors platform-integrated operators with telematics capabilities. Long-term viability over the next decade hinges on regulatory alignment with autonomous vehicle trial frameworks and carbon neutrality commitments. Acquisition targets should demonstrate MOHAP compliance certification speed and charging infrastructure partnerships in Abu Dhabi business districts. The signal to watch is Dubai's federal smart city framework implementation pace as fleet connectivity requirements tighten.
| Strategic Initiative | Industry Significance |
|---|---|
| Telematics Platform Integration | MOHAP's real-time data submission mandates require compliant fleet monitoring hardware deployment. |
| Corporate Fleet Outsourcing Expansion | Khalifa Industrial Zone logistics firms generate predictable multi-year revenue streams. |
| Electric Vehicle Procurement Scaling | Abu Dhabi business district charging density enables premium zero-emission positioning. |
| Chauffeur-Driven Service Tier Launch | Dubai International Financial Centre executive transport commands elevated daily rates. |
| Free Zone Corridor Proximity Model | Dubai South logistics clusters reduce customer acquisition costs through concentrated B2B demand. |
Research Methodology
Desk research of customs vehicle import records, MOHAP regulatory filings, and airport concession agreements preceded structured interviews with fleet operations directors, corporate procurement managers, telematics integration specialists, and hospitality chain mobility coordinators. Primary fieldwork combined with secondary validation through UAE federal traffic authority disclosures and emirate-level economic department statistics. Bottom-up fleet size estimates triangulated against top-down tourism arrival projections.
Assumptions held fixed include MOHAP inspection cycle frequency and federal smart mobility framework implementation scope across the analysis window. Segmentation dimensions modeled encompass vehicle type, rental duration architecture, service model deployment, and customer segment behavior. CAGRs derived from vehicle replacement velocity correlations with corporate outsourcing penetration rates. Industry-specific forecast inputs incorporated Jebel Ali Port container throughput trends and Dubai International Airport passenger volume trajectories.
Practitioners should monitor autonomous vehicle trial zone expansions and carbon neutrality procurement mandates for early signals of fleet composition pivots. Forecasts reflect assumptions about regulatory enforcement consistency and charging infrastructure buildout pace. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation Services
Canada White Glove Delivery Service Market
Transportation Services
Asia Pacific Tourism Vehicle Rental Market
Transportation Services
Latin America Tourism Vehicle Rental Market
Transportation Services
Scandinavia Car Rental Market
Transportation Services
Russia Car Rental Market
Transportation Services
ASEAN Car Rental Market
Transportation Services
Europe Van Rental Market
Transportation Services
Egypt Ride Hailing Service Market
Transportation Services
On Street Vehicle Parking Meter Market
Transportation Services
Scooter Rental Market
Transportation Services
Asia-Pacific Rickshaw Ride Hailing Service Market
Transportation Services
China Vehicle Rental Market
Transportation Services
Driving Vacation Market
Transportation Services
Ride-Hailing Service Market
Transportation Services
Thailand Car Rental Market
Transportation Services
Europe Vehicle Rental Market