
 Europe Road Marking Machine Market | 2026-2036
Europe Road Marking Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Road Marking Machine Market Insights
The EU Green Deal is repositioning procurement criteria across European road authorities toward longer-lasting markings with lower lifecycle carbon footprints. Hofmann GmbH leverages its German manufacturing base to supply heated thermoplastic systems optimized for CE marking compliance. Borum A/S anchors the Nordic region with cold plastic equipment engineered for freeze-thaw resilience. Graco Inc competes through airless spraying technology leadership that extends across Western European contractor fleets.
A road marking machine applies controlled layers of thermoplastic, paint, cold plastic, or preformed markings to asphalt or concrete substrates at calibrated thicknesses between 1.5 mm and 3.0 mm, with glass bead dispersion rates of 300–500 g/m² ensuring retroreflectivity for nighttime visibility. The primary purpose is to create durable traffic control devices that withstand heavy vehicle abrasion and weather extremes. Thermoplastic equipment dominates value pools due to material volume throughput and highway authority preference for five-to-seven-year durability cycles. Cold plastic systems represent the fastest-growing technology segment as contractors seek rapid-cure formulations that minimize lane closure durations on high-traffic corridors.
EMA, ECHA through REACH substance restrictions, and the EU F-Gas Regulation collectively shape material composition standards and equipment emission profiles across member states. CE marking mandates enforce machinery safety and electromagnetic compatibility, creating compliance barriers for non-European suppliers. Stakeholders must monitor evolving CSRD disclosure requirements that will compel road authorities to document embodied carbon in marking material choices.
Market Dynamics
The EU Green Deal is rewriting procurement criteria across European road authorities, forcing a wholesale shift from first-cost bidding to lifecycle durability metrics that favor thermoplastic and cold plastic systems with extended service intervals.
Growth Catalysts
- EU Green Deal durability mandates:Road authorities in Germany and France now specify five-to-seven-year marking lifecycles, concentrating demand on equipment capable of high-volume thermoplastic throughput.
- Nordic climate adaptation:Freeze-thaw resilience requirements in Sweden, Norway, and Finland pull cold plastic formulations with rapid-cure chemistry that minimizes lane closure windows.
- CE marking compliance infrastructure:Machinery safety and electromagnetic compatibility standards create procurement preference for European-manufactured equipment with established certification pathways.
Market Restraints
- Petrochemical feedstock volatility:Thermoplastic binder resins and cold plastic polymers expose contractors to input cost swings that compress bidding margins on fixed-price highway contracts.
- German manufacturing concentration:Heated tank systems and precision extrusion equipment cluster in Baden-Württemberg and Bavaria, creating geographic supply risk for southern European contractors.
- ECHA REACH substance restrictions:Evolving limits on titanium dioxide nanoparticles and solvent-based carrier systems force continuous reformulation of marking materials.
Strategic Opportunities
- Eastern European highway modernization:Poland, Romania, and Bulgaria deploy EU cohesion funds to upgrade trans-European transport corridors, opening demand for mid-tier airless spraying fleets.
- CSRD carbon disclosure requirements:The Corporate Sustainability Reporting Directive compels road authorities to document embodied carbon in marking choices, advantaging low-cure-energy cold plastic systems.
- Telematics-integrated equipment:GPS-guided line marking and real-time bead dispersion monitoring converge to enable precision contracting models with outcome-based payment structures.
Industry Challenges
- Certified equipment technician scarcity:CE marking maintenance and heated thermoplastic system repair require specialized training that outpaces vocational pipeline output in Italy and Spain.
- Legacy fleet integration friction:Contractors operating 10-15 year old solvent-based spray rigs face capital intensity barriers when retrofitting for waterborne or cold plastic compatibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Road Marking Machine Market |
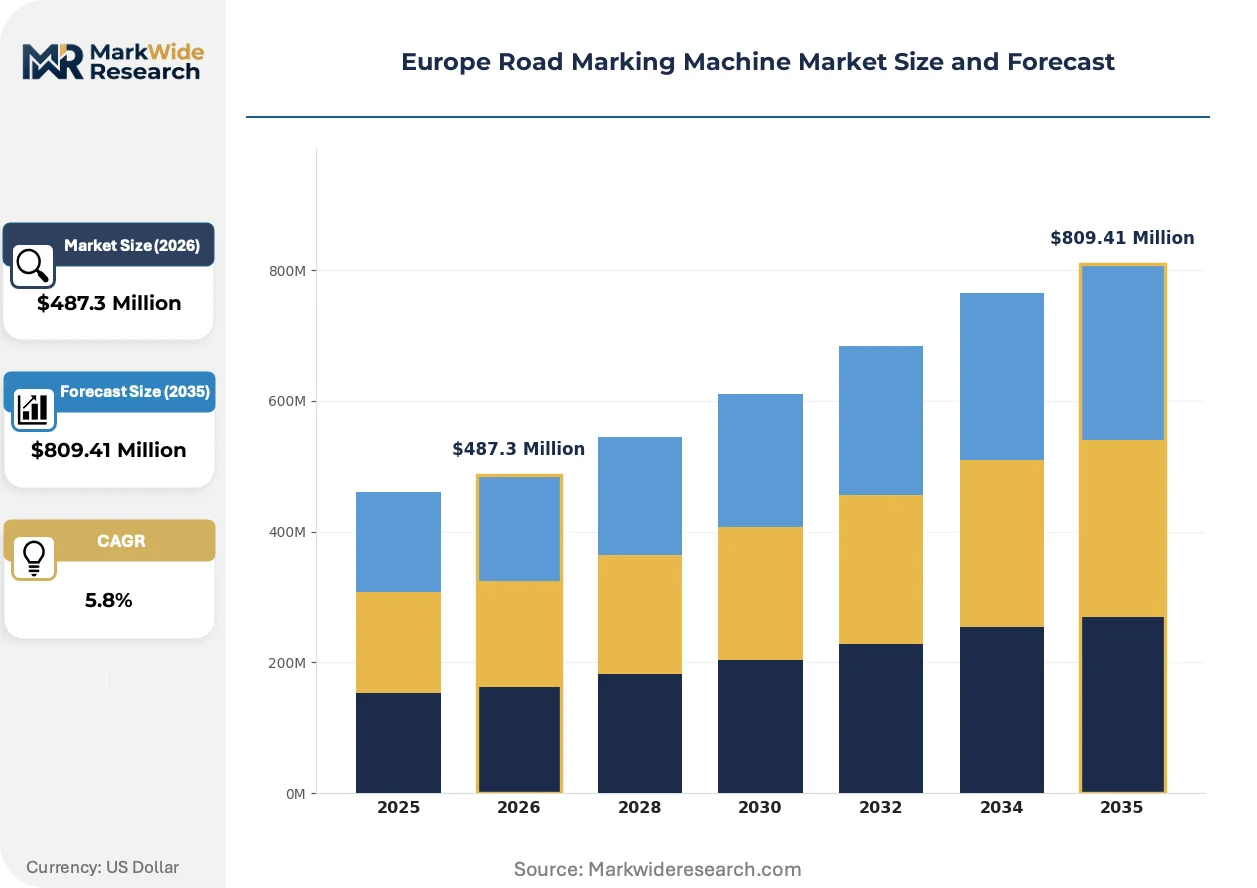
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $809.41 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermoplastic, Paint, Cold Plastic, Preformed Markings End User: Construction Companies, Municipalities, Road Authorities, Contractors Technology: Airless Spraying, Heated Thermoplastic, Roller Application, Stencil Application Application: Highways, Airports, Parking Lots, Residential Streets |
| Companies Covered | Borum A/S, Hofmann GmbH, Graco Inc, RME Road Marking Equipment, SWARCO, Volvo, Wirtgen, STiM Group, Road Marking Equipment of Sweden AB, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Road Marking Machine Market Trends and Innovations
Active regulatory pressure and contractor productivity demands are compressing technology refresh cycles across European road marking fleets, with digital precision and material chemistry advancing in parallel.
Automated glass bead dispersion systems with real-time retroreflectivity feedback are rewriting quality assurance protocols on high-speed highway contracts. German and Austrian contractors deploying these systems report reduced rework rates and compressed acceptance timelines. The technology is enabling fixed-price outcome contracts that transfer performance risk from authorities to equipment operators.
The EU F-Gas Regulation is phasing down hydrofluorocarbon propellants in aerosol marking applications, forcing reformulation toward compressed air or mechanical pump systems. Equipment manufacturers in Denmark and the Netherlands accelerate electric-powered cold plastic sprayers to eliminate propellant dependency entirely. Cold plastic application rates in the Nordic region accelerate as contractors pre-position compliant fleets ahead of 2030 phase-out deadlines.
Performance-based maintenance contracts are displacing unit-price bidding on French and Belgian motorway networks. Contractors now specify their own equipment configurations to meet availability and retroreflectivity guarantees, shifting procurement authority from central authorities to private operators. This inversion concentrates equipment specification power with tier-one contractors operating integrated marking and maintenance divisions.
Europe Road Marking Machine Market Segmentation
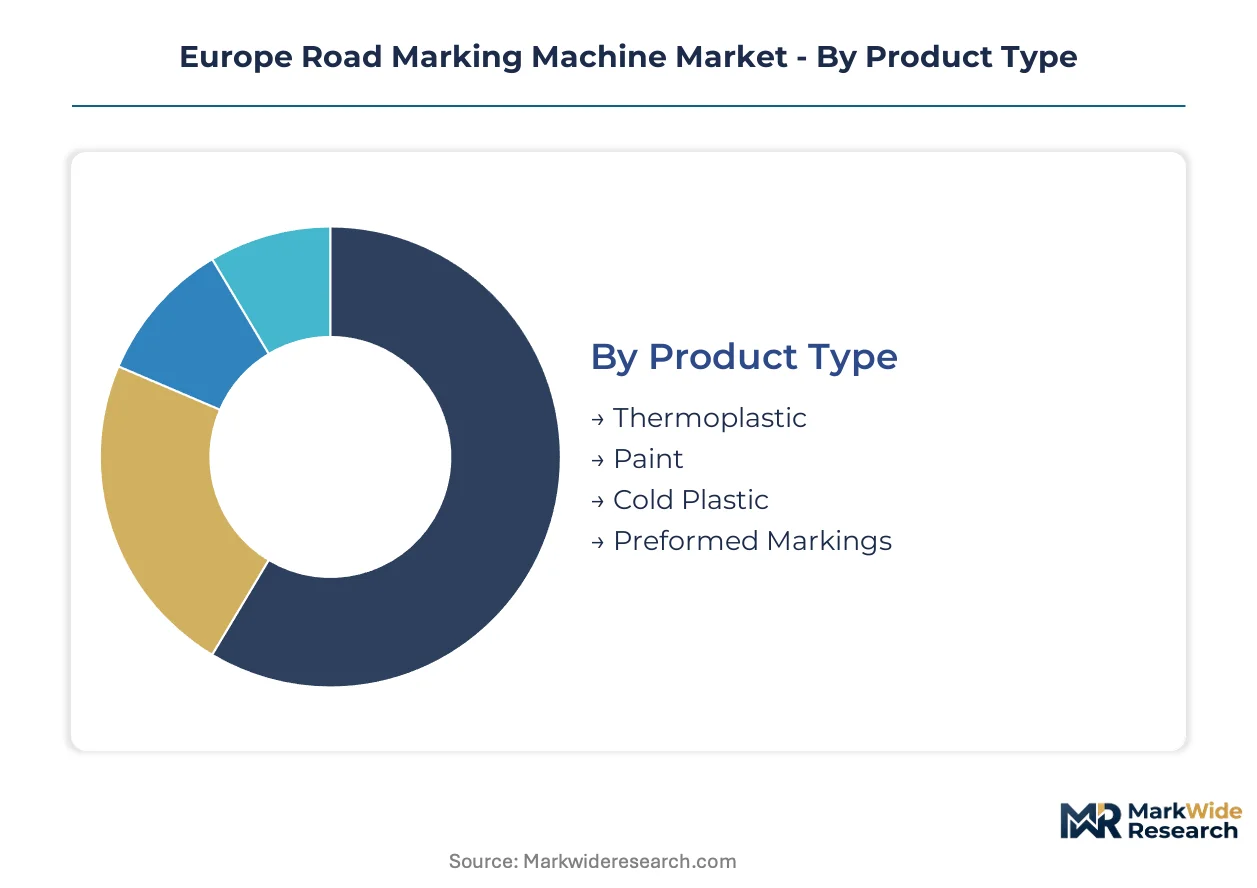
Equipment specification power concentrates with tier-one contractors who configure fleets around material chemistry, application speed, and regulatory compliance. Segmentation reveals how procurement authority has inverted from central road authorities to private operators bearing performance risk on outcome-based contracts.
Product Type:
CE marking mandates and EU Green Deal durability targets create divergent certification burdens across material categories, with thermoplastic systems requiring heated tank compliance and cold plastic formulations navigating ECHA REACH substance restrictions.
- Thermoplastic:Heated extrusion systems apply molten resin-glass bead mixtures at 180-200°C, achieving 2.0-3.0 mm thickness with five-to-seven-year durability cycles. German and French road authorities specify this equipment for trans-European transport corridors under Green Deal procurement criteria. Leading the category by volume: Thermoplastic. Growing fastest: Cold Plastic.
- Cold Plastic:Two-component polyurethane or methyl methacrylate formulations cure chemically without heat, enabling rapid lane reopening on high-traffic Nordic routes. Sweden, Norway, and Finland specify freeze-thaw resilient grades that minimize closure windows during short summer maintenance seasons.
- Paint:Waterborne and solvent-based alkyd systems dominate low-volume residential applications where durability requirements stay below three years. ECHA REACH restrictions on titanium dioxide nanoparticles and solvent carriers force continuous reformulation.
- Preformed Markings:Factory-manufactured tapes and thermoplastic sheets bond to substrates through heat or adhesive activation, serving temporary traffic control and airport taxiway applications requiring precision placement without spray equipment.
Material throughput economics favor thermoplastic for highway authorities, while cold plastic gains share fastest in climate-stressed Nordic zones and high-traffic urban corridors.
End User:
Customer type determines equipment specification authority, with integrated maintenance contractors now dictating fleet configuration where performance-based contracts have displaced unit-price bidding.
- Construction Companies:General infrastructure contractors deploy multi-purpose fleets across road, bridge, and utility projects, prioritizing airless spraying versatility over material-specific optimization. Equipment utilization rates drive procurement decisions.
- Municipalities:City and county road departments in Germany, France, and Benelux operate captive marking divisions with dedicated thermoplastic extrusion systems for annual renewal programs on urban arterial networks.
- Road Authorities:National highway agencies in Poland, Romania, and Bulgaria deploy EU cohesion funds to upgrade corridor marking, creating demand for mid-tier heated tank systems with established CE certification pathways.
- Contractors:Specialized road marking firms in Belgium and the Netherlands now specify equipment configurations to meet retroreflectivity and availability guarantees under inverted procurement authority, bearing full performance risk.
Procurement concentration sits with specialized contractors, while fastest equipment refresh rates occur among integrated maintenance operators.
Technology:
Application method selection tracks material chemistry compatibility, with heated systems locked to thermoplastic and airless architectures accommodating formulation flexibility.
- Airless Spraying:High-pressure piston pumps atomize paint and cold plastic without compressed air, eliminating F-Gas propellant dependency ahead of EU phase-out deadlines. Western European contractor fleets standardize on this architecture for multi-material flexibility.
- Heated Thermoplastic:Diesel-fired or electric tank systems maintain binder temperature through application, requiring electromagnetic compatibility certification under CE marking machinery directives. Baden-Württemberg and Bavaria manufacturing clusters dominate supply.
- Roller Application:Preformed tape and thermoplastic sheet systems use heated rollers or pneumatic pressure for substrate bonding, serving airport and precision placement contracts.
- Stencil Application:Template-guided spray or extrusion systems produce symbols, legends, and complex markings on parking structures and urban intersections.
Technology mix tilts toward heated thermoplastic by installed base value, with airless systems climbing fastest as cold plastic formulations expand.
Application:
Surface type dictates durability specifications and equipment mobility requirements, with highways demanding high-speed application and airports requiring precision tolerances.
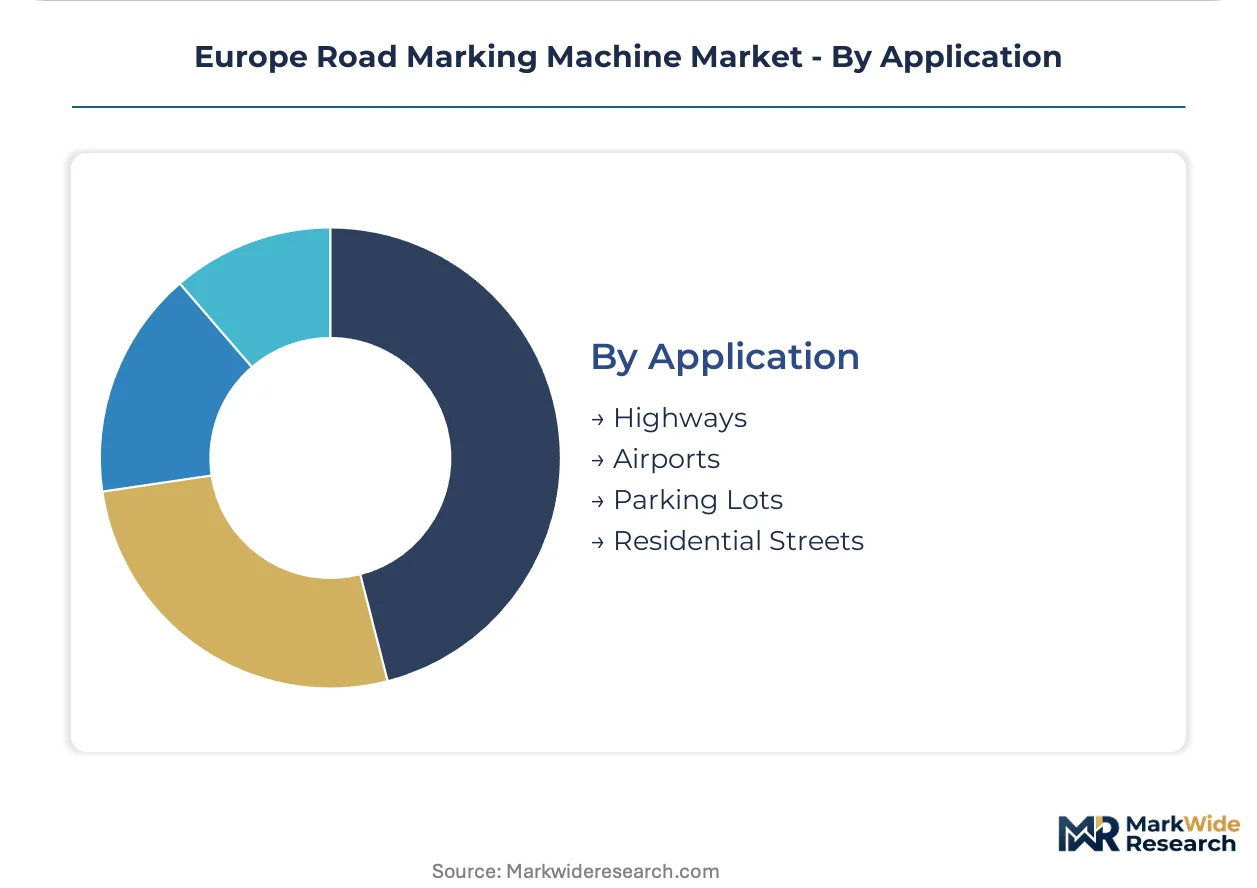
- Highways:Multi-lane motorway networks require continuous extrusion capability at 5-15 km/h application speeds, with automated glass bead dispersion and real-time retroreflectivity monitoring. German Autobahn and French autoroute programs concentrate demand.
- Airports:Runway and taxiway markings demand precision thickness control within 0.5 mm tolerance and specialized color formulations for visibility against asphalt and concrete, requiring dedicated roller and stencil systems.
- Parking Lots:Low-speed, high-maneuverability equipment applies waterborne paint and preformed symbols in confined commercial and residential structures with frequent reconfiguration.
- Residential Streets:Municipal fleets deploy compact airless sprayers for narrow urban corridors where thermoplastic extrusion width exceeds lane geometry.
Highway applications dominate equipment revenue, with airport precision systems commanding premium pricing tiers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Baden-Württemberg and Bavaria manufacturing clusters dominate European road marking equipment supply, anchoring thermoplastic system production for highway authorities across the continent.
Germany
KBA vehicle certification standards and Autobahn renewal programs concentrate demand for heated thermoplastic extrusion systems. The EU Green Deal procurement criteria favor five-to-seven-year durability specifications on federal motorway contracts. Stuttgart and Munich industrial corridors house precision tank manufacturing and electromagnetic compatibility testing facilities serving CE marking compliance.
France
Performance-based maintenance contracts on autoroute networks invert procurement authority toward specialized contractors bearing retroreflectivity guarantees. ANSM and national road directorate regulations enforce machinery safety standards on public works equipment. Lyon and Paris basin contractors deploy automated glass bead dispersion systems under fixed-price outcome agreements.
Sweden
Freeze-thaw resilience requirements on state highway networks pull cold plastic formulations with rapid-cure chemistry. The Swedish Transport Administration specifies extended lifecycle markings to minimize summer maintenance closure windows. Gothenburg and Stockholm corridor contractors pre-position electric-powered sprayers ahead of EU F-Gas Regulation phase-out deadlines.
Poland
EU cohesion fund deployment for trans-European transport corridor upgrades generates demand for mid-tier heated tank systems with established certification pathways. National road authority procurement favors CE-marked equipment for motorway modernization programs. Warsaw and Kraków infrastructure clusters coordinate contractor fleet expansion across Central European highway networks.
Netherlands
Waterborne paint restrictions and carbon disclosure mandates under CSRD compel municipal authorities to document embodied carbon in marking material choices. Rotterdam and Amsterdam metropolitan contractors standardize on airless spraying architectures for multi-material flexibility. Dutch equipment fabricators accelerate electric cold plastic sprayer development to eliminate propellant dependency.
Europe Road Marking Machine Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification depth and material specialization vectors. The vendor base organizes into three tiers: German-engineered thermoplastic specialists, Nordic cold plastic innovators, and Western European multi-material generalists. Consolidation pressure concentrates among mid-scale fabricators lacking in-house CE marking infrastructure. Dominant competitive moves include backward integration into heated tank component manufacturing and technology licensing partnerships for automated bead dispersion systems.
Within the German-engineered tier, Hofmann GmbH and Borum A/S occupy positions reflecting distinct regional specialization archetypes. Hofmann leverages its Baden-Württemberg manufacturing base to anchor thermoplastic system supply for Green Deal-compliant highway authorities. Borum exemplifies Nordic climate adaptation expertise through cold plastic equipment engineered for freeze-thaw resilience. Graco Inc represents Western European multi-material flexibility, competing through airless spraying technology leadership across contractor fleets. These three fabricators illustrate how geographic origin and company structure align with distinct procurement authority centers in the European market.
| Leading Market Players |
|---|
| Borum A/S |
| Hofmann GmbH |
| Graco Inc |
| RME Road Marking Equipment |
| SWARCO |
| Volvo |
| Wirtgen |
| STiM Group |
| Road Marking Equipment of Sweden AB |
| Others |
Pricing and Supply Chain Analysis
EU Green Deal procurement criteria mandating five-to-seven-year durability cycles force contractors toward high-throughput thermoplastic and rapid-cure cold plastic systems, concentrating equipment specification power with manufacturers possessing established CE marking infrastructure and compressing margins for uncertified competitors.
Pricing Analysis
Outcome-based payment structures tied to retroreflectivity guarantees anchor equipment valuation, with pricing stratifying across premium, standard, and economy tiers based on CE certification depth and after-sales service bundling. German-engineered heated tank systems command premiums for electromagnetic compliance and precision extrusion capability. Cost compression in mid-tier airless spraying fleets intensifies as Eastern European contractors bid fixed-price highway contracts with volatile petrochemical input exposure. Municipal road departments show highest price sensitivity on replacement cycles, while integrated maintenance contractors prioritize total cost of ownership over first-cost acquisition.
Supply Chain Analysis
Dual-sourcing requirements from Polish and Romanian road authorities mandate multi-supplier qualification for heated thermoplastic tank components, dispersing procurement across German, Danish, and Dutch fabricators. Manufacturing draws from precision steel forming in Baden-Württemberg, hydraulic systems from Bavaria, and polymer feedstocks from Benelux petrochemical complexes. Single-source vulnerability concentrates in electromagnetic compatibility testing facilities clustered around Stuttgart and Munich. Distribution runs through specialized road construction equipment dealers serving contractor fleets with field service capability.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified equipment technician scarcity across Southern Europe props pricing for manufacturers with captive training infrastructure, creating supply-constrained conditions that favor incumbents with vocational pipeline investments.
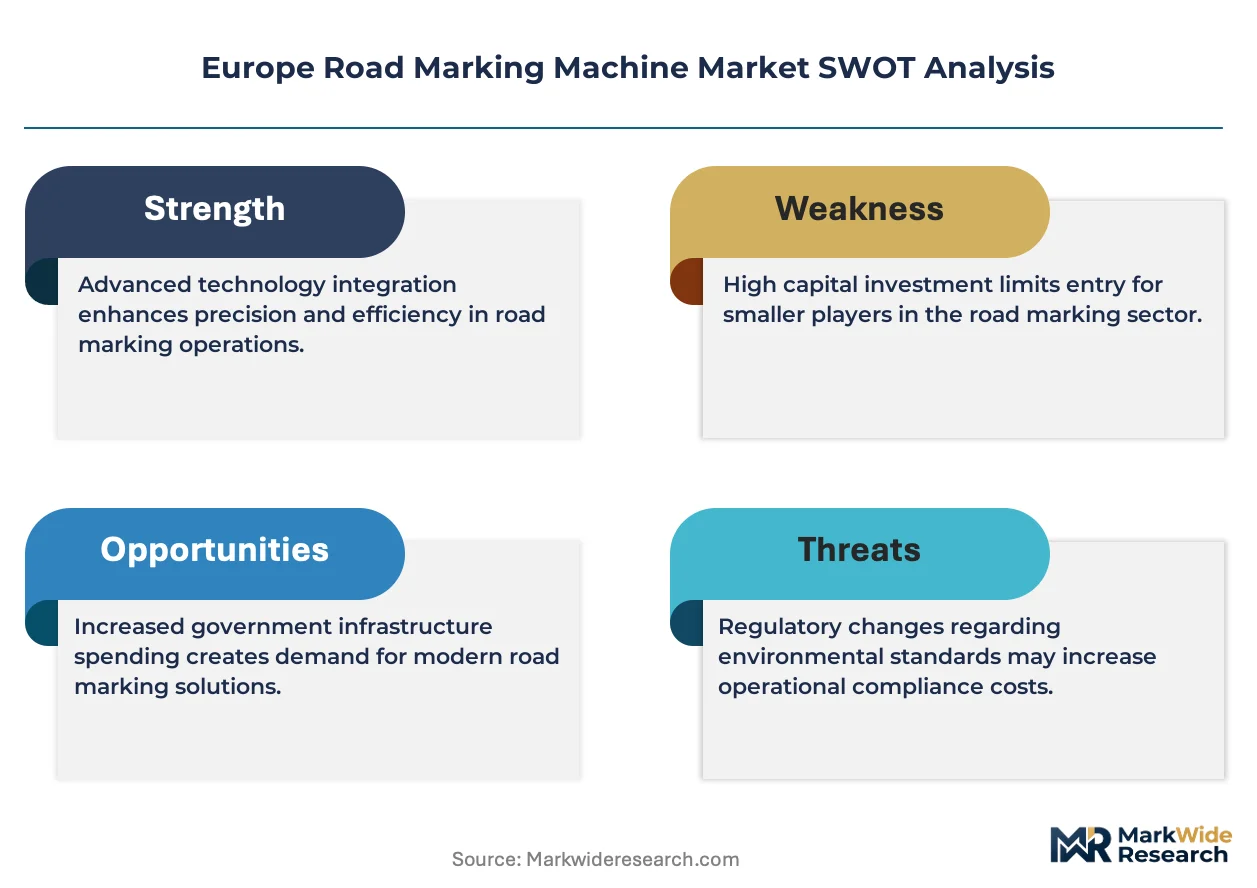
For Market Incumbents: To counter margin erosion from petrochemical feedstock volatility, deepen backward integration into heated tank component manufacturing and expand in-house CE marking compliance infrastructure to accelerate certification timelines for reformulated cold plastic systems. For New Entrants and Emerging Players: Enter via electric-powered cold plastic sprayer development targeting Nordic climate adaptation requirements, leveraging the EU F-Gas Regulation phase-out timeline to displace propellant-dependent legacy fleets in Sweden, Norway, and Finland. For Investors and Strategic Acquirers: The window for entry favors mid-scale fabricators with established electromagnetic compatibility testing pathways; consolidation pressure intensifies among uncertified competitors lacking in-house CE marking infrastructure. Watch for ECHA REACH substance restriction announcements as inflection indicators for material chemistry reformulation cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Heated Tank Components | Captive supply of precision extrusion systems reduces dependency on Baden-Württemberg manufacturing clusters. |
| Electric Cold Plastic Sprayer Development | Elimination of F-Gas propellant dependency aligns equipment portfolios with EU phase-out deadlines. |
| Telematics-Integrated Equipment Launch | GPS-guided line marking enables precision contracting models with outcome-based payment structures. |
| CE Marking Infrastructure Investment | In-house electromagnetic compatibility testing accelerates certification timelines for reformulated systems. |
| Vocational Training Pipeline Expansion | Certified technician programs address scarcity barriers in Italy and Spain while locking contractor loyalty. |
Research Methodology
Document review covered EU regulatory filings, ECHA REACH substance restriction updates, and national road authority procurement specifications, complemented by interviews with equipment procurement managers at German and French municipal road departments, technical directors at Nordic cold plastic formulation specialists, aftermarket service heads at contractor fleets, and plant managers at Baden-Württemberg manufacturing facilities. Secondary validation drew from CE marking machinery directives, EU cohesion fund deployment records, and customs data on thermoplastic binder resin imports. Bottom-up equipment shipment estimates triangulated against top-down highway maintenance expenditure projections.
Historical volume trajectories cross-referenced against panel input from industry participants established baseline growth parameters across the analysis window. Segmentation modeling incorporated product type, material chemistry compatibility, end-user procurement authority, and regional regulatory cluster dimensions. CAGRs derived from fitted trend analysis adjusted for EU Green Deal implementation pacing and ECHA substance restriction timelines. Forecast inputs included cohesion fund allocation patterns for trans-European transport corridors and F-Gas Regulation compliance deadlines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated ECHA REACH restrictions or petrochemical feedstock price spikes. Deviation in EU Green Deal procurement enforcement timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Dust Suppression Fog Cannon Market
Construction Equipment
Tower Crane Market
Construction Equipment
Grout Bags Market
Construction Equipment
Wheeled Excavators Market
Construction Equipment
Asia Pacific Construction Equipment Rental Market
Construction Equipment
Latin America Heavy Construction Equipment Rental Market
Construction Equipment
Australia Mobile Cranes Rental Market
Construction Equipment
GCC Mini Cranes Market
Construction Equipment
Roadheaders Market
Construction Equipment
Construction Site Preparation Equipment Market
Construction Equipment
Garage Equipment Market
Construction Equipment
Middle-East and Africa Anchors and Grouts Market
Construction Equipment
Porter Cable Air Compressor Market
Construction Equipment
Dock Door Market
Construction Equipment
Saudi Arabia Completion Equipment and Services Market
Construction Equipment
Vietnam Crane Market