
 Ratchet Wringer Market | 2026-2036
Ratchet Wringer Market Size, Share, and Industry Trends Forecast 2026-2036
Ratchet Wringer Market Analytics
Specialty tool distribution through industrial supply houses is reshaping how ratchet wringers reach end users in maintenance and cleaning operations. Snap-on leverages its captive dealer network to control premium pricing in automotive service bays. Stanley Black & Decker sustains broad shelf presence across big-box retail and commercial channels. Apex Tool Group anchors its position through private-label partnerships with facility maintenance distributors.
A ratchet wringer employs a ratcheting mechanism to extract liquid from mop heads or cleaning pads through controlled mechanical torque, typically achieving squeeze pressures of 50-150 psi depending on handle geometry and pawl engagement design. The device serves commercial and industrial users who require consistent moisture removal to prevent floor damage and reduce slip hazards. Manual wringers dominate unit volume in household and light commercial settings where capital constraints limit power tool adoption. Electric wringers capture margin concentration in hospital and food processing environments where throughput demands justify premium pricing. Stainless steel construction leads material selection in regulated facilities due to corrosion resistance and compatibility with autoclave sterilization protocols.
OSHA workplace sanitation standards in the United States mandate proper moisture control in commercial cleaning to prevent slip hazards, directly influencing wringer torque specification requirements. REACH substance restrictions in Europe limit certain polymer additives in plastic components, pushing manufacturers toward compliant material formulations. ISO 9001 quality management certification has become a baseline procurement filter for industrial buyers evaluating supplier qualification. Stakeholders must monitor evolving chemical compliance thresholds and electrification cost curves to time product portfolio transitions effectively.
Market Dynamics
OSHA slip-hazard mandates and REACH chemical restrictions are compressing replacement cycles while forcing material upgrades across commercial cleaning supply chains.
Growth Catalysts
- Workplace Sanitation Standards:OSHA moisture-control requirements in the United States specify minimum wringer torque thresholds, compelling facility managers to upgrade aging equipment.
- Stainless Steel Mandates:REACH compliance in Germany restricts polymer additives, accelerating demand for corrosion-resistant wringer construction in food processing plants.
- Hospital Sterilization Protocols:Autoclave-compatible designs are capturing replacement volume in healthcare settings where thermal sterilization is non-negotiable.
Market Restraints
- Steel Price Volatility:Nickel and chromium input costs fluctuate with mining supply disruptions, squeezing margin on premium stainless units.
- Manual Winger Saturation:Light commercial segments show limited upgrade appetite where capital constraints favor repair-over-replace behavior.
- Electrification Cost Barriers:Motor and control system expenses block adoption in budget-constrained municipal and educational facilities.
Strategic Opportunities
- Private-Label Partnerships:Facility maintenance distributors seek exclusive SKUs, creating white-space for compliant stainless-steel variants with customized torque ratings.
- Food Service Hygiene Mandates:FDA-aligned HACCP protocols in the United States are specifying moisture-extraction standards that favor precision-engineered wringers.
- IoT-Enabled Fleet Tracking:Sensor-integrated electric wringers allow usage-based maintenance scheduling, appealing to multi-site cleaning contractors.
Industry Challenges
- Welding Certification Gaps:Stainless fabrication requires ASME-qualified technicians, creating recruitment bottlenecks for manufacturers scaling production.
- ISO 9001 Audit Timelines:Supplier qualification delays stretch 6-12 months, slowing new vendor entry into industrial procurement pipelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ratchet Wringer Market |
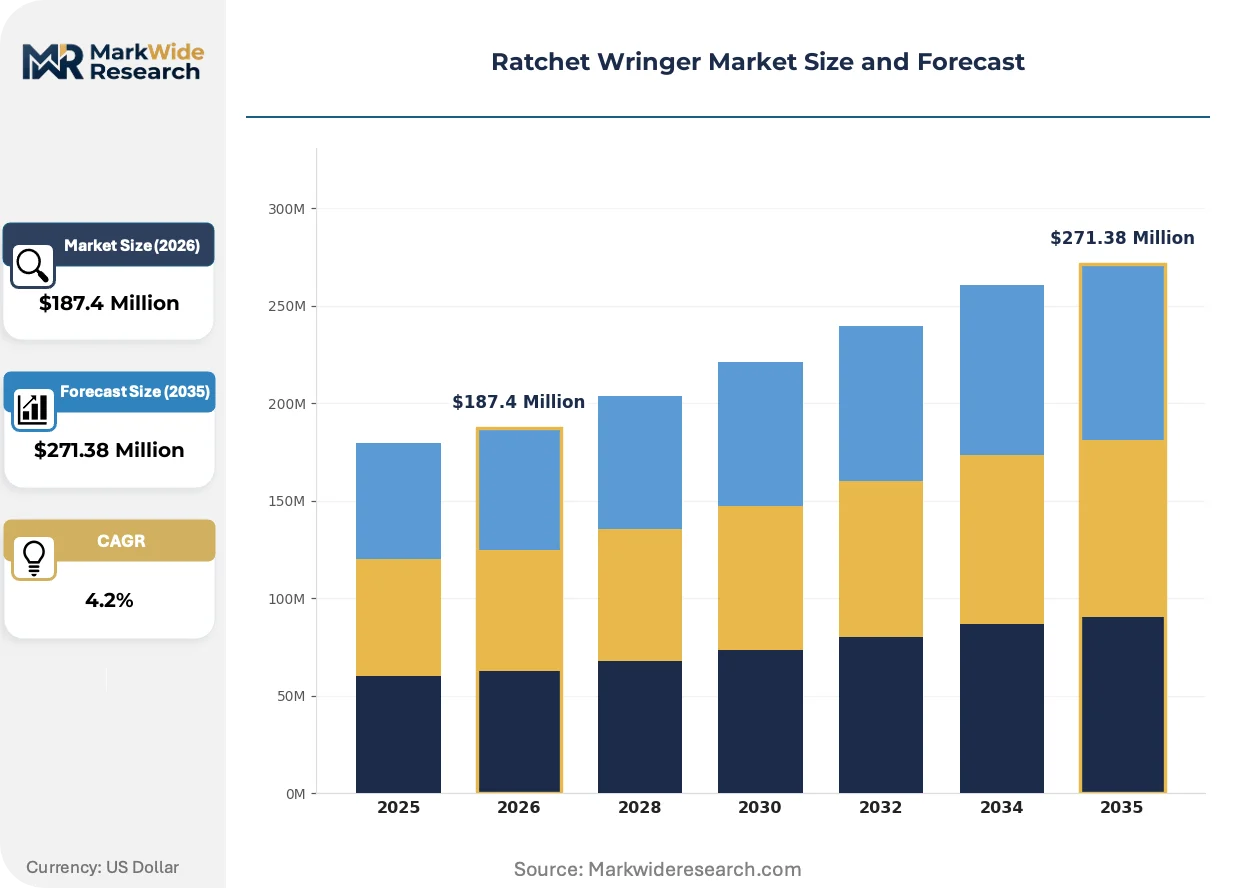
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $271.38 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Wringers, Electric Wringers, Hydraulic Wringers, Pneumatic Wringers End User: Households, Industrial Facilities, Commercial Cleaners, Food Service Material: Stainless Steel, Plastic, Aluminum, Rubber Application: Household Cleaning, Industrial Cleaning, Automotive Maintenance, Floor Care |
| Companies Covered | Snap-on, Stanley Black & Decker, Apex Tool Group, Klein Tools, DeWalt, GearWrench, Proto, Williams, Hazet, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ratchet Wringer Market Evolving Landscape
Mechanical-electrical convergence and compliance-driven material substitution are restructuring product architectures while reshaping how buyers evaluate total cost of ownership.
Brushless DC motor systems paired with planetary gear reduction are hybridizing torque delivery in mid-range electric wringers. Hospital environmental services departments are piloting these units to reduce operator strain during extended shift coverage. The technology is hybridizing price-performance expectations, compressing the gap between premium manual and entry-electric segments.
REACH substance restrictions are eliminating specific phthalate plasticizers from polymer wringer components across European supply chains. Manufacturers reformulating with bio-based alternatives face 18-24 month validation cycles for autoclave durability. Food processing facilities in Germany and France are absorbing price premiums to maintain CE marking compliance.
Consolidated procurement through integrated facility management vendors is displacing decentralized purchasing in multi-site healthcare networks. National service contractors are mandating standardized wringer specifications across their equipment fleets. The United States exhibits the most pronounced concentration, where three cleaning service providers control a significant share of hospital contract volume.
Ratchet Wringer Market Segmentation
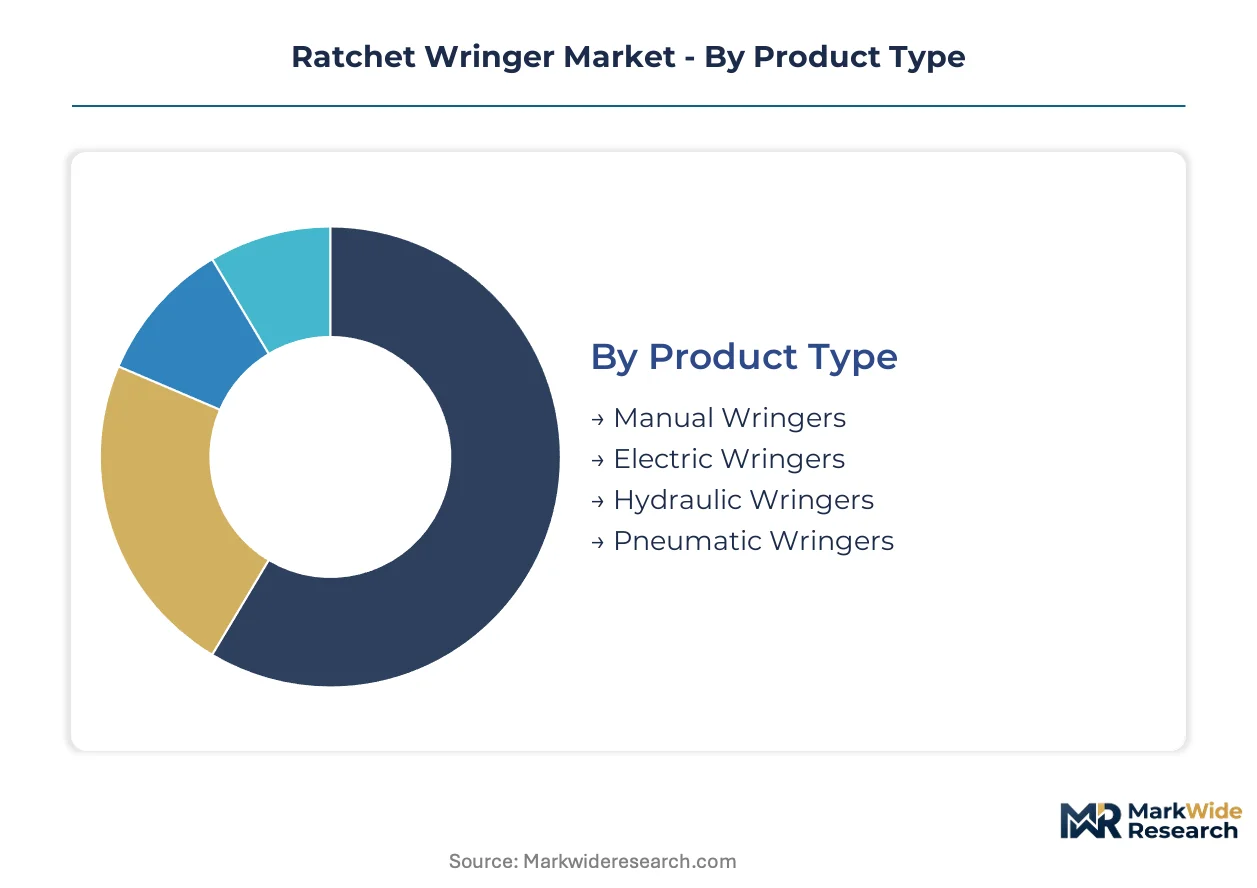
Ratchet wringer procurement patterns diverge sharply across torque requirements, sterilization protocols, and capital constraints. Facility managers segment purchases by autoclave compatibility, OSHA slip-hazard compliance thresholds, and fleet standardization mandates.
Product Type:
Mature mechanical designs dominate unit economics while electrification reshapes performance tiers in regulated environments.
- Manual Wringers:Lever-and-pawl mechanisms deliver 50-150 psi squeeze pressure through variable handle geometry. Demand concentrates in United States municipal school districts and German Mittelstand manufacturing facilities where capital budgets restrict powered equipment procurement. OSHA torque thresholds still mandate replacement of aging units despite repair-over-replace preferences.
- Electric Wringers:Brushless DC motors with planetary gear reduction achieve consistent torque output for hospital environmental services departments. United States healthcare networks pilot these units to reduce repetitive strain injuries during extended shift coverage. Autoclave-compatible stainless housings command premium positioning in FDA-regulated settings.
- Hydraulic Wringers:Fluid-power systems serve heavy-industrial applications in German automotive stamping plants requiring sustained high-pressure extraction.
- Pneumatic Wringers:Compressed-air drive suits food processing facilities in France with existing shop-air infrastructure and explosion-proof requirements.
Manual wringers handle the majority of throughput; electric wringers are expanding most quickly on share.
End User:
Cost tier differentiation separates specification-heavy institutional buyers from price-sensitive residential purchasers.
- Industrial Facilities:German chemical processors and United States metal fabricators specify ASME-welded stainless construction for autoclave sterilization cycles. REACH substance restrictions and OSHA moisture-control mandates compress replacement cycles despite higher unit costs.
- Commercial Cleaners:National service contractors in the United States consolidate procurement through integrated facility management vendors, mandating standardized torque specifications across multi-site fleets. Three providers control significant hospital contract volume.
- Food Service:HACCP-aligned moisture-extraction standards drive precision-engineered wringer adoption in United States restaurant chains.
- Households:Light-duty polymer units serve residential cleaning with minimal regulatory compliance burden.
Industrial facilities absorb the highest per-unit expenditure; commercial cleaners represent the steepest expansion trajectory through fleet standardization.
Material:
Supply concentration in nickel and chromium mining shapes cost structures for corrosion-resistant grades.
- Stainless Steel:Austenitic grades with autoclave durability dominate German food processing and United States hospital procurement. REACH phthalate restrictions accelerate substitution away from polymer alternatives.
- Plastic:Bio-based reformulations face 18-24 month validation cycles for European CE marking compliance.
- Aluminum:Lightweight variants serve mobile cleaning carts in French commercial buildings.
- Rubber:Compression elements in pawl mechanisms require replacement scheduling in high-throughput environments.
Stainless steel commands the premium tier; plastic retains volume leadership in constrained capital environments.
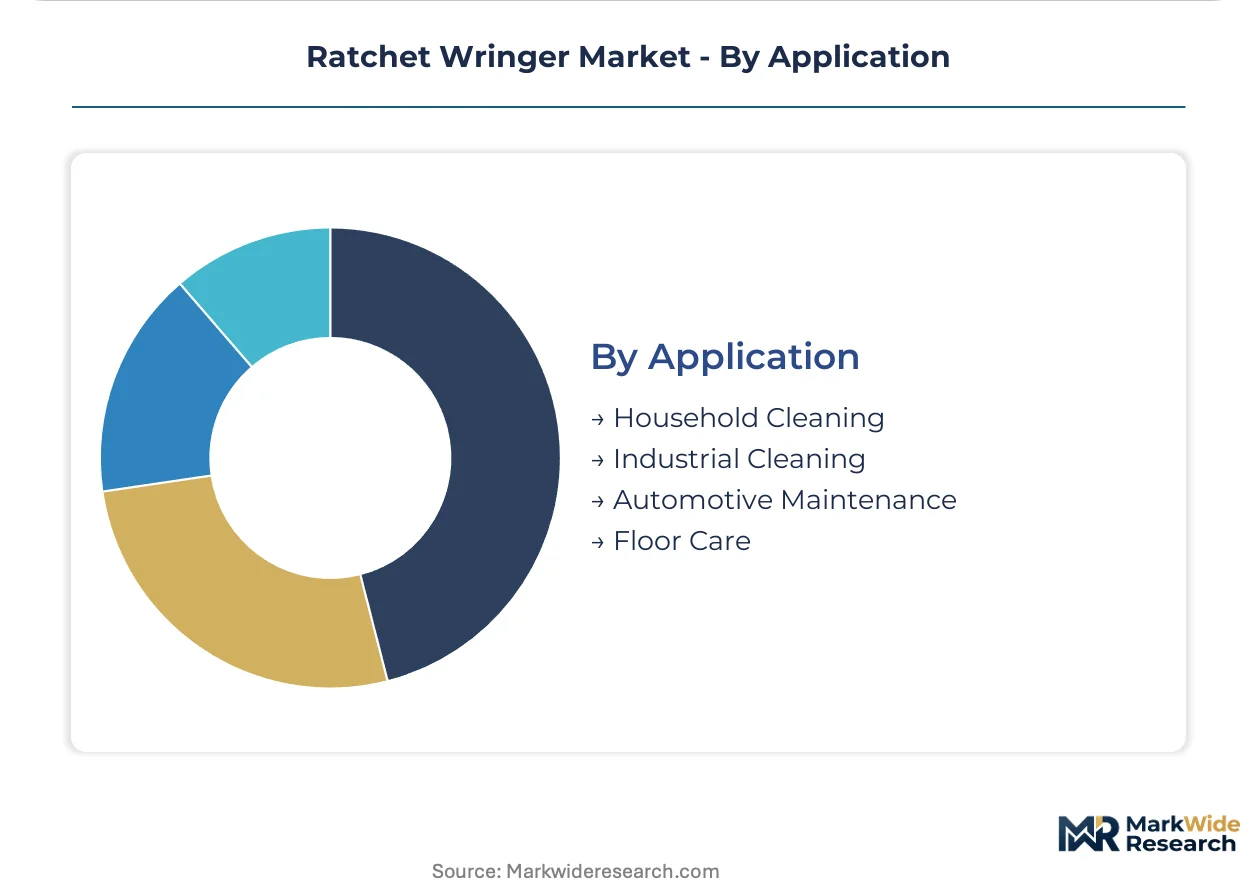
Application:
Geography clusters around regulatory stringency and industrial base density.
- Industrial Cleaning:German automotive and chemical facilities specify torque-calibrated units for contamination control. OSHA and REACH compliance layers add specification complexity.
- Floor Care:Slip-hazard liability drives moisture-extraction precision in United States retail and hospitality chains.
- Household Cleaning:Residential demand concentrates in manual variants with minimal feature differentiation.
- Automotive Maintenance:Service bays in Germany and the United States prioritize durability under solvent exposure.
Industrial cleaning generates the specification density; floor care applications are gaining share fastest through liability-driven upgrade cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg anchors German distribution for stainless steel wringers serving REACH-compliant food processors, while the Port of Los Angeles handles Pacific Rim component imports for OSHA-mandated facility upgrades across the western United States.
United States
OSHA moisture-control mandates and hospital fleet standardization drive replacement cycles in healthcare networks. The FDA aligns with HACCP protocols for food service moisture-extraction standards. Chicago's commercial cleaning corridor concentrates procurement for multi-site facility management contractors.
Germany
REACH substance restrictions on polymer additives accelerate stainless steel adoption in automotive stamping plants. The ECHA enforces phthalate limitations requiring material reformulation. Bavaria's Mittelstand manufacturing belt specifies torque-calibrated units for contamination control.
France
Food processing facilities absorb price premiums for CE-marked autoclave-compatible designs. ANSM oversees hospital sterilization equipment compliance in healthcare settings. The Lyon-Grenoble chemical cluster demands corrosion-resistant construction for solvent-exposed maintenance operations.
United Kingdom
Commercial cleaners consolidate procurement through integrated facility management vendors post-Brexit regulatory divergence. The Health and Safety Executive maintains slip-hazard standards comparable to OSHA thresholds. London's contract cleaning hub mandates standardized specifications across national service fleets.
Japan
Hospital environmental services departments pilot brushless DC motor systems to reduce operator strain during extended shifts. METI promotes workplace sanitation equipment upgrades through industrial standards alignment. Osaka's precision manufacturing district supplies planetary gear reduction components for mid-range electric wringers.
Ratchet Wringer Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in the supply architecture. The vendor base organizes around three strategic archetypes: captive dealer networks controlling premium pricing, broad-channel distributors sustaining retail presence, and private-label partners anchoring facility maintenance procurement. Consolidation pressure concentrates among industrial supply houses seeking exclusive SKU arrangements. Vertical integration into stainless fabrication and backward integration into motor assembly represent the dominant competitive vectors.
Among North American tool conglomerates, Snap-on and Stanley Black & Decker exemplify divergent channel strategies—Snap-on through its captive dealer network and Stanley Black & Decker across big-box retail and commercial channels. Apex Tool Group occupies a position within the private-label partnership tier, anchoring supply relationships with facility maintenance distributors. These three represent the structural poles around which competitive positioning organizes.
| Leading Market Players |
|---|
| Snap-on |
| Stanley Black & Decker |
| Apex Tool Group |
| Klein Tools |
| DeWalt |
| GearWrench |
| Proto |
| Williams |
| Hazet |
| Others |
Value Network & Pricing Analysis
Overcapacity in Chinese stainless steel fabrication is compressing margin realization for mid-tier manual wringer producers while concentrating pricing power among ASME-certified specialty manufacturers serving German food processing and United States hospital procurement channels.
Pricing Analysis
Volume-discount tiering separates ASME-welded stainless units for German automotive and United States healthcare procurement from polymer-based economy variants serving municipal school districts. Price differentiation hinges on ISO 9001 certification status and autoclave durability ratings, with REACH-compliant stainless constructions commanding substantial premiums over phthalate-restricted plastic alternatives. Cost compression in manual wringer segments is intensifying because repair-over-replace behavior in budget-constrained facilities limits upgrade velocity. Municipal and educational buyers exhibit the highest price sensitivity, while hospital environmental services departments prioritize total cost of ownership over unit acquisition cost.
Supply Chain Analysis
Upstream nickel and chromium mining concentrates in Indonesia, South Africa, and the Philippines, with austenitic stainless steel production anchored in China, Germany, and Japan. Component assembly draws from Taiwanese brushless DC motor specialists and Osaka-based planetary gear reduction suppliers. Single-source vulnerability around ASME-qualified welding technicians creates production bottlenecks for manufacturers scaling stainless fabrication. Distribution runs through integrated facility management vendors in the United States and industrial supply houses across Germany, with private-label partnerships capturing growing share in commercial cleaning procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized welding certification scarcity constrains capacity expansion for stainless steel wringer production, creating durable margin pools for manufacturers who have secured qualified technician pipelines.
For Market Incumbents: Build captive ASME technician training pipelines to defend margin pools against emerging private-label competitors. Secure exclusive supply agreements with Indonesian nickel processors to buffer input cost volatility. Deepen backward integration into planetary gear reduction component production to capture value migrating from manual to electric product architectures. For New Entrants and Emerging Players: Build out private-label partnerships with United States integrated facility management vendors seeking exclusive stainless-steel SKUs with customized torque ratings. The most penetrable white-space sits in mid-range electric wringers for hospital networks piloting brushless DC systems to reduce operator strain. A direct-service model bypassing traditional industrial supply houses offers differentiated channel access. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among electric wringer fleet operators offering usage-based maintenance contracts through IoT-enabled equipment tracking. Long-term viability favors manufacturers with demonstrated REACH compliance pathways and established autoclave validation protocols. The signal to watch is consolidation momentum among United States hospital cleaning contractors mandating standardized fleet specifications.| Strategic Initiative | Industry Significance |
|---|---|
| ASME Welding Certification Program | Secures production scalability for stainless steel autoclave-compatible wringer lines serving German food processors. |
| Private-Label Partnership Expansion | Captures procurement consolidation among United States integrated facility management vendors standardizing multi-site fleets. |
| Brushless DC Motor Integration | Addresses OSHA torque mandates while reducing repetitive strain injury liability in hospital environmental services departments. |
| REACH-Compliant Material Reformulation | Maintains CE marking access for European food processing facilities absorbing price premiums for phthalate-free polymer alternatives. |
| IoT-Enabled Fleet Tracking Platform | Enables usage-based maintenance contracting with multi-site commercial cleaning contractors seeking operational visibility. |
Research Methodology
Cross-validation between primary interviews with maintenance directors, plant engineers, OEM procurement teams, and aftermarket service heads anchors the qualitative findings against secondary validation from customs trade data, SEC filings of listed tool manufacturers, OSHA compliance documentation, and REACH substance restriction updates. Bottom-up segment sizing triangulates against top-down market reconstruction across product type, end user, material grade, and application dimensions.
Calibration against historical replacement cycle data and regulatory compliance timeline analysis shapes the projection framework across the analysis window. Segmentation modeling incorporates torque specification tiering, sterilization protocol requirements, and regional regulatory cluster variations. CAGRs derive from elasticity-adjusted demand curves and capital expenditure pattern analysis in hospital and food processing verticals.
Practitioners should monitor nickel price volatility, ASME certification queue lengths, and REACH substance restriction expansion for early signals of forecast revision. Cross-checking against German Mittelstand capital equipment purchasing indices and United States hospital GPO contract award databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Floor Saw Market
Tools
L Allen Wrench Market
Tools
Concrete Saw Market
Tools
Measuring Wheels Market
Tools
Cordless Trim Routers Market
Tools
Scroll Saws Market
Tools
Air Hammer Market
Tools
Industrial Hand Tools Market
Tools
Portable Tools Market
Tools
Reamer Market
Tools
Ripper Market
Tools
Thread Milling Machine Market
Tools
Forging Press Market
Tools
Hand Tools and Woodworking Tools Market
Tools
Chainsaw Market
Tools
Turning Tools Market