
 Stand Tile Saw Market | 2026-2036
Stand Tile Saw Market Size, Share, and Industry Trends Forecast 2026-2036
Stand Tile Saw Market Analysis
China is tilting toward expanded production of wet-cutting tile saws for export markets. Robert Bosch Tool Corporation leverages its cordless power tool ecosystem to anchor battery-operated stand saw development. Husqvarna AB competes through professional-grade wet cutting systems that dominate commercial flooring installations. Makita Corporation extends its brushless motor portfolio into tile cutting equipment, sustaining R&D intensity across Asian and North American distribution channels.
A stand tile saw is a stationary cutting machine mounted on a folding or fixed frame, typically equipped with a diamond-coated blade ranging from 7 to 10 inches and a water reservoir or dust containment system for precision cutting of ceramic, porcelain, or natural stone tiles. The equipment serves contractors and remodelers who require repeatable straight or miter cuts on large-format material. Electric models occupy the largest installed base due to consistent torque output and compatibility with job site power infrastructure, while battery-operated configurations represent the fastest-expanding segment as lithium-ion platforms mature. Wet cutting technology leads in professional settings where silica suppression and blade cooling are mandatory, whereas laser-guided alignment features concentrate margin pools in premium contractor-grade product tiers.
OSHA enforces permissible exposure limits for respirable crystalline silica that push contractors toward wet cutting systems or integrated vacuum extraction. The EPA regulates wastewater discharge from wet saw operations on commercial sites, shaping equipment design toward closed-loop water recycling. ISO 19432 addresses safety requirements for stationary cutting machines, influencing export certification pathways for manufacturers. Stakeholders must monitor evolving silica enforcement patterns and battery platform interoperability standards as determinants of replacement cycle timing and brand loyalty.
Market Dynamics
OSHA's respirable crystalline silica enforcement is compressing dry-cutting equipment replacement cycles and forcing wet-system adoption across residential renovation fleets. Contractors face immediate compliance deadlines that override capital expenditure deferrals.
Growth Catalysts
- Wet-Cutting Mandates:OSHA's permissible exposure limits for respirable crystalline silica push contractors toward integrated water suppression systems. Equipment replacement cycles compress as dry-cutting assets face accelerated obsolescence.
- Battery Platform Convergence:Lithium-ion ecosystems mature across construction tool fleets. Stand saws interoperate with existing cordless infrastructure, reducing total cost of ownership for fleet operators.
- Aging Housing Stock:Suburban corridors across the United States drive kitchen and bathroom remodeling volume. Renovation contractors expand tool fleets to capture repeat project work.
Market Restraints
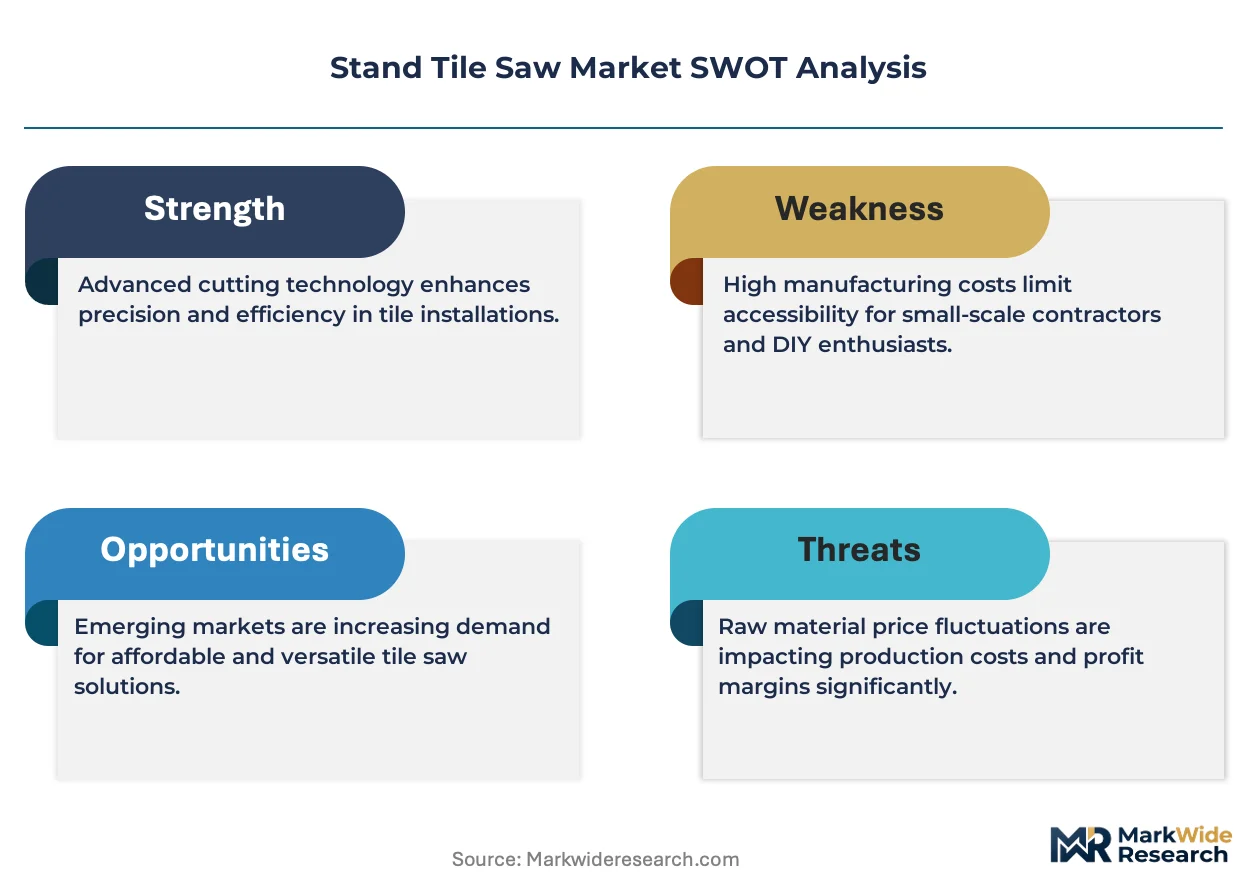
- Diamond Blade Cost Volatility:Synthetic diamond supply concentrates in limited manufacturing geographies. Input cost swings compress margin pools for equipment OEMs and rental fleet operators.
- Water Management Burden:EPA wastewater discharge regulations impose closed-loop system requirements. Equipment weight and complexity increase, limiting portability for residential contractors.
- Manual Cutting Substitution:Score-and-snap tile cutters retain cost advantage for thin ceramic and small-format work. Price-sensitive DIY segments delay powered equipment adoption.
Strategic Opportunities
- Closed-Loop Water Recycling:Advanced filtration systems enable EPA-compliant operation without external discharge. Premium contractor-grade tiers capture margin from compliance-driven specification.
- Battery-Operated Configurations:Cordless platforms penetrate renovation segments where temporary power access is limited. Lithium-ion interoperability with existing tool ecosystems accelerates fleet conversion.
- Laser-Guided Alignment Features:Precision cutting systems command pricing premiums in large-format porcelain applications. Commercial flooring contractors specify accuracy-enhancing features for repeatability.
Industry Challenges
- Silica Compliance Certification:Equipment validation against OSHA exposure limits requires third-party testing. Documentation burdens extend sales cycles and inflate compliance costs.
- Technician Training Gaps:Wet-system operation demands different skill profiles than legacy dry-cutting. Contractor workforce development lags equipment capability advancement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Stand Tile Saw Market |
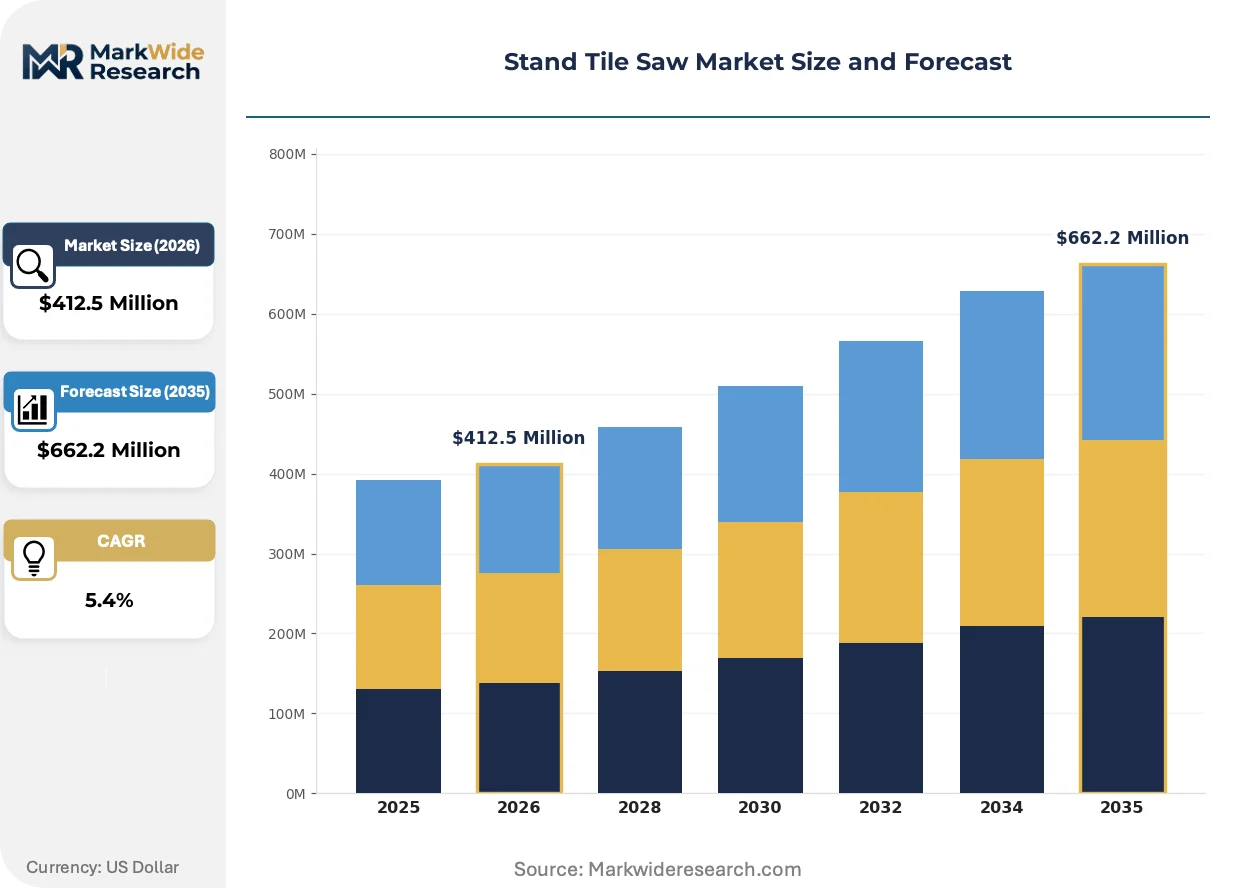
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $662.2 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric, Manual, Pneumatic, Battery-operated End User: Construction, Renovation, DIY Enthusiasts, Tile Shops Application: Residential, Commercial, Industrial, Landscaping Technology: Wet Cutting, Dry Cutting, Laser-guided, Diamond Blade |
| Companies Covered | MK Diamond Products, Inc., Robert Bosch Tool Corporation, Q.E.P. Co., Inc., Husqvarna AB, DEWALT, Makita Corporation, RIDGID, Rubi, Germans Boada SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Stand Tile Saw Market Emerging Trajectories
Equipment architectures are fragmenting across power source and cutting modality dimensions. Manufacturers must now engineer for three simultaneous transitions: cordless electrification, silica compliance, and large-format material handling.
Brushless motor technology is hybridizing with traditional wet-cutting architectures to deliver torque consistency without generator dependency. Commercial flooring contractors adopt these systems for indoor environments where exhaust and noise restrictions apply. The convergence is compressing demand for gasoline-powered alternatives in enclosed commercial sites.
EPA wastewater discharge regulations are forcing closed-loop water system integration into contractor-grade equipment designs. Manufacturers redesign reservoirs and filtration modules to eliminate external discharge points. Commercial flooring segments in the United States absorb cost premiums to maintain job site mobility without regulatory interruption.
Procurement patterns among multi-location renovation contractors are consolidating toward fleet-standardized battery platforms. Equipment purchasing decisions now prioritize interoperability with existing cordless ecosystems over standalone performance specifications. This behavior concentrates in suburban United States markets where contractor scale enables platform commitment.
Stand Tile Saw Market Segmentation
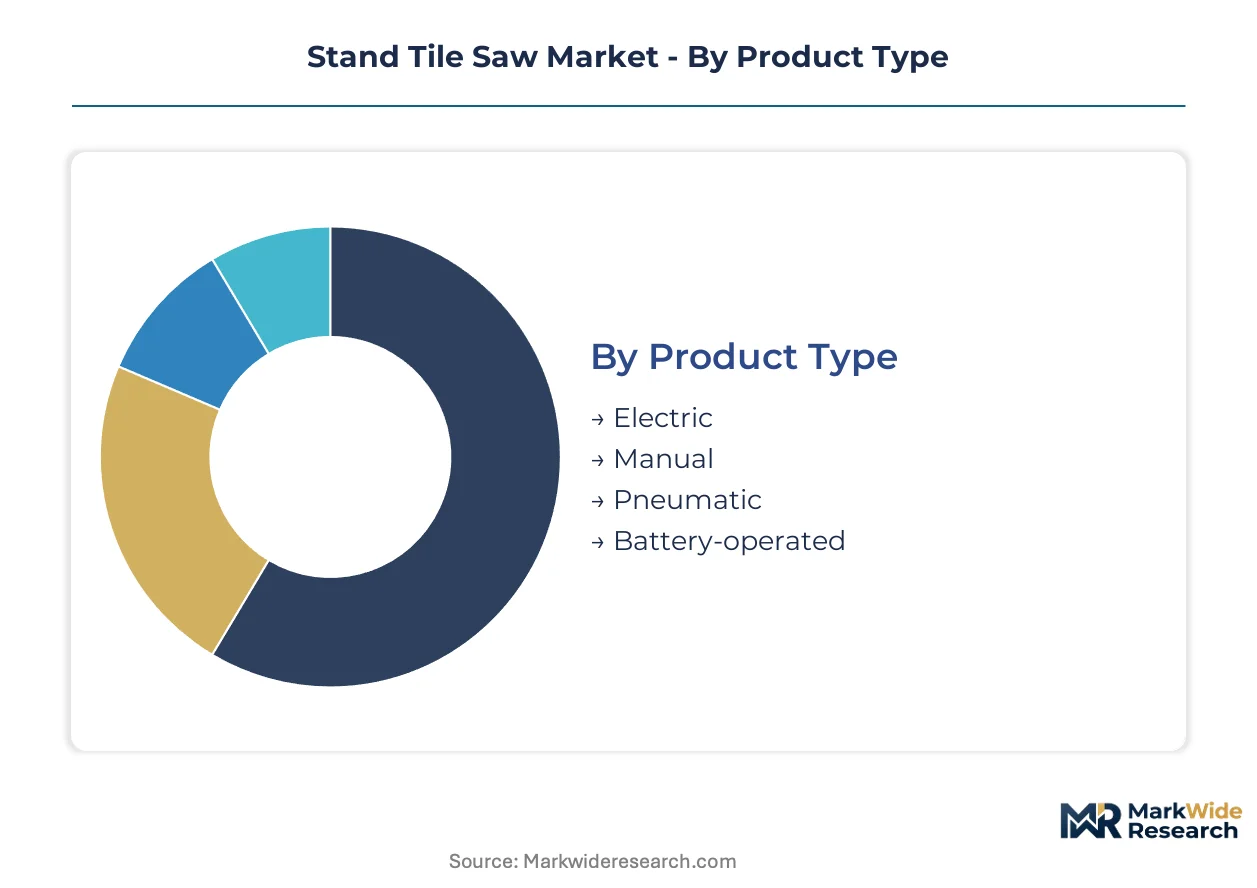
Stand tile saw segmentation reveals divergent equipment requirements across power modalities, silica compliance regimes, and end-user sophistication levels. Contractors prioritize wet-cutting electric systems for OSHA adherence, while cordless platforms reshape fleet procurement patterns among renovation specialists.
Product Type:
Cost tier differentiation separates professional-grade infrastructure from entry-level alternatives in contractor purchasing decisions.
- Electric:Stationary units deliver consistent torque output through direct grid connection. Wet-cutting electric systems dominate commercial flooring installations across suburban United States corridors where silica enforcement is strictest.
- Battery-operated:Lithium-ion platforms leverage interoperability with existing cordless tool ecosystems. Renovation contractors in residential retrofit segments adopt these configurations where temporary power access is unreliable.
- Manual:Score-and-snap mechanisms serve thin ceramic and small-format tile work. DIY enthusiasts and budget-conscious tile shops retain these units for low-volume cutting tasks.
- Pneumatic:Compressed-air systems occupy niche industrial applications. These units concentrate in manufacturing facilities with existing compressed air infrastructure.
Electric holds installed capacity. Battery-operated is rotating up the share rankings.
End User:
Customer type segmentation maps equipment specifications against project scale, compliance burden, and capital deployment capacity.
- Construction:General contractors deploy wet-cutting systems for new-build commercial and multi-family projects. OSHA silica mandates accelerate fleet standardization around water-suppression architectures.
- Renovation:Kitchen and bathroom specialists drive repeat equipment purchases in aging suburban housing corridors. These operators absorb premium pricing for laser-guided precision in large-format porcelain applications.
- DIY Enthusiasts:Homeowners and hobbyists gravitate toward manual cutters and entry-level electric units. Price sensitivity constrains adoption of professional-grade wet systems.
- Tile Shops:Retail and fabrication operations maintain demonstration and light production equipment. These entities balance customer service visibility against capital efficiency.
Construction commands specification authority. Renovation is climbing the fastest as housing stock ages.
Application:
Volume concentration varies across building typologies with distinct material specifications, cutting precision requirements, and regulatory exposure.
- Residential:Single-family and multi-family remodeling generates sustained demand for portable wet-cutting equipment. Kitchen and bathroom retrofits in established suburbs drive contractor fleet expansion.
- Commercial:Office, retail, and hospitality flooring installations require precision cutting of large-format tiles. Laser-guided systems capture specification in these high-visibility projects.
- Industrial:Manufacturing and warehouse facilities demand heavy-duty cutting capacity for thick stone and paver materials. Pneumatic and high-torque electric units serve these applications.
- Landscaping:Outdoor hardscape projects utilize specialized saws for stone pavers and concrete materials. These applications prioritize portability and dust management over precision features.
Residential anchors unit volume. Commercial is gaining share fastest through specification upgrading.
Technology:
Maturity curves separate legacy dry-cutting architectures from compliance-driven wet systems and precision-enhancing guidance technologies.
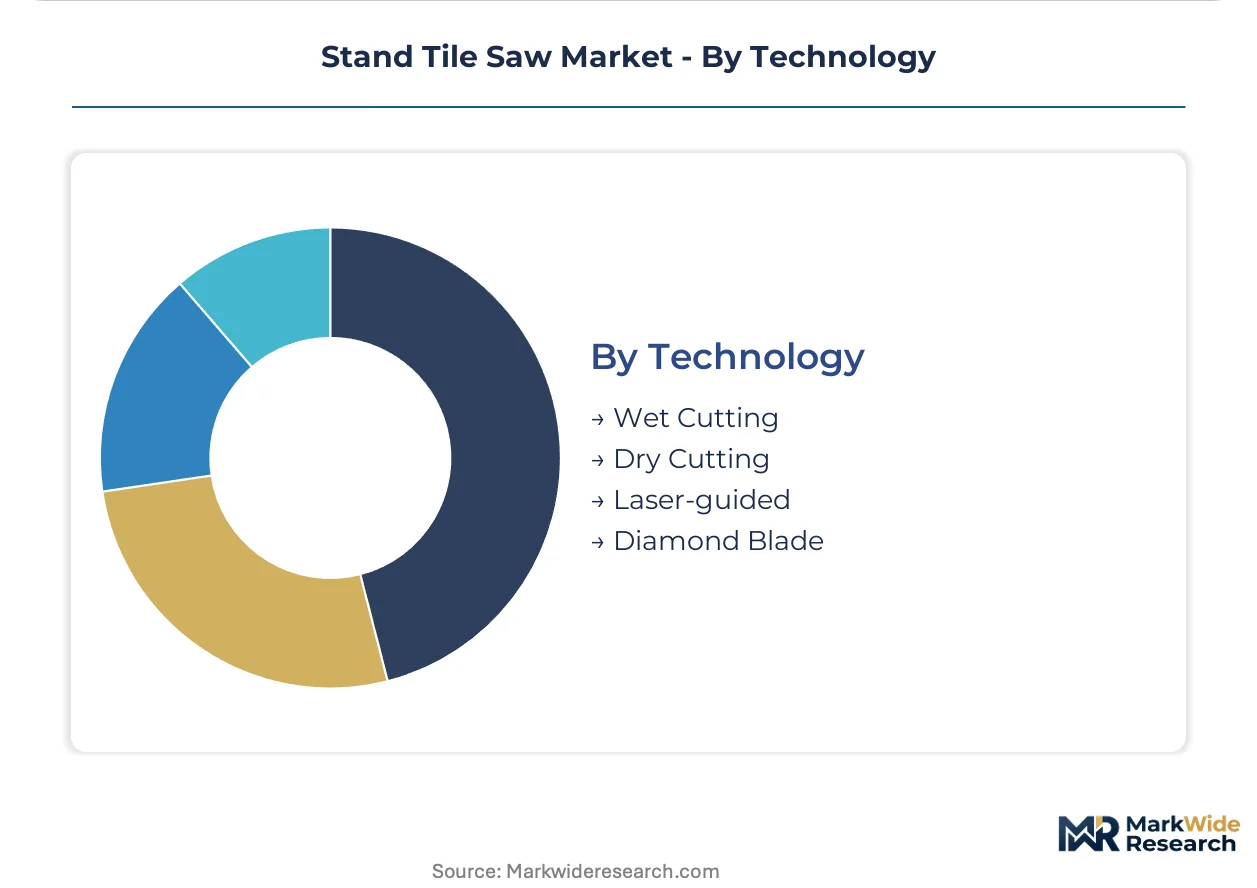
- Wet Cutting:Integrated water suppression systems cool blades and capture respirable silica at the point of generation. OSHA enforcement compresses replacement cycles for dry-cutting assets.
- Dry Cutting:Vacuum-extraction and uncontrolled dust emission systems face regulatory obsolescence. Remaining demand concentrates in outdoor landscaping and jurisdictions with limited silica enforcement.
- Laser-guided:Alignment projection systems enable repeatable straight and miter cuts without manual marking. Commercial flooring contractors specify these features for large-format porcelain repeatability.
- Diamond Blade:Synthetic diamond cutting surfaces deliver durability across ceramic, porcelain, and natural stone materials. Blade cost volatility shapes total cost of ownership calculations for fleet operators.
Wet Cutting holds specification dominance. Laser-guided is rotating up the share rankings through precision premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
OSHA enforcement in the United States compresses equipment replacement cycles and forces wet-system adoption across residential renovation fleets. Contractors face immediate compliance deadlines that override capital expenditure deferrals.
United States
Suburban housing corridors in Texas, Florida, and Arizona drive kitchen and bathroom remodeling volume. EPA wastewater discharge regulations from wet saw operations on commercial sites shape equipment design toward closed-loop water recycling. The Dallas-Fort Worth metroplex anchors contractor fleet expansion among renovation specialists.
China
Export-oriented manufacturers tilt toward expanded production of wet-cutting tile saws for international markets. MIIT industrial standards and GB certification requirements shape export pathways. The Pearl River Delta manufacturing cluster concentrates OEM capacity serving North American and European distribution channels.
Germany
Commercial flooring contractors specify precision cutting systems for large-format porcelain in office and retail installations. REACH chemical regulations and CE marking requirements influence blade material sourcing and equipment safety certification. The Rhine-Ruhr industrial region hosts specialized distributors serving renovation contractors across Central Europe.
Japan
Brushless motor technology penetrates tile cutting equipment through existing cordless power tool ecosystems. METI energy efficiency guidelines and JIS safety standards govern product development cycles. The Chubu region around Nagoya anchors precision manufacturing for motor-drive systems.
India
Infrastructure investment and urban housing stock expansion drive contractor tool fleet growth. BIS certification requirements and state-level building codes shape equipment import and distribution patterns. The Delhi-NCR corridor concentrates renovation contractor activity amid rapid residential development.
Stand Tile Saw Market Vendor Landscape
Power tool conglomerates and specialized cutting equipment manufacturers split the market along battery-platform and wet-system capability vectors. The vendor base concentrates among diversified industrial conglomerates with construction tool portfolios and focused specialists with diamond-cutting heritage. Two strategic archetypes dominate: ecosystem-anchored battery platform operators and precision wet-system specialists. Competitive moves center on lithium-ion interoperability expansion and closed-loop water recycling integration.
Within the ecosystem-anchored tier, Robert Bosch Tool Corporation and Makita Corporation represent battery platform convergence strategies that leverage existing cordless infrastructure. DEWALT occupies a position among professional-grade power tool manufacturers with construction site distribution density. Husqvarna AB exemplifies the wet-system specialist archetype with professional-grade cutting heritage. These three anchors demonstrate how equipment purchasing decisions prioritize interoperability with existing fleet infrastructure over standalone performance specifications.
| Leading Market Players |
|---|
| MK Diamond Products, Inc. |
| Robert Bosch Tool Corporation |
| Q.E.P. Co., Inc. |
| Husqvarna AB |
| DEWALT |
| Makita Corporation |
| RIDGID |
| Rubi |
| Germans Boada SA |
| Others |
Supply Flow & Price Mechanics
Overcapacity in China's Pearl River Delta manufacturing cluster is compressing export pricing for wet-cutting tile saw platforms while simultaneously accelerating supplier consolidation. This utilization dynamic forces OEMs to absorb synthetic diamond blade cost volatility through inventory hedging rather than pass-through pricing, reshaping margin structures across North American distribution channels.
Pricing Analysis
Contractor-grade wet-cutting systems in Texas and Florida command premiums over comparable units in the Midwest due to stricter OSHA silica enforcement timelines. Three-tier pricing structure across premium laser-guided, standard wet-cutting, and economy dry-cutting levels separates specification authority. Cost compression in entry-level electric tiers is intensifying because manual score-and-snap cutters retain DIY segment loyalty. Renovation contractors show least price sensitivity for closed-loop water recycling features, while tile shops and hobbyists resist premium wet-system adoption.
Supply Chain Analysis
Export-control scrutiny on advanced brushless motor technology from Japan and precision filtration components from Germany is fragmenting component sourcing strategies. Manufacturing concentrates in China, Mexico, and the United States for final assembly, while synthetic diamond blanks draw from limited suppliers in Ireland and Russia. Single-source vulnerability in lithium-ion battery cell supply creates fleet standardization risk for cordless platform operators. Distribution runs through construction equipment rental houses and specialized flooring distributors serving commercial contractor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Score-and-snap manual cutters represent a persistent substitution threat that powered equipment manufacturers must neutralize through compliance-driven obsolescence of dry-cutting alternatives.
For Market Incumbents: Entrench battery platform interoperability as the primary switching cost by deepening cordless ecosystem integration across renovation contractor fleets. Accelerate closed-loop water recycling certification to preempt EPA discharge regulation expansion. Defensive patent positioning around laser-guided alignment systems protects premium tier margins from emerging Asian competitors. For New Entrants and Emerging Players: India's Delhi-NCR corridor offers underpenetrated white-space for wet-cutting system adoption amid rapid residential development and infrastructure investment. Battery-operated configurations targeting temporary power-constrained job sites present the most penetrable entry vector. Partnership with established construction equipment rental networks accelerates brand visibility without direct distribution buildout. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across closed-loop filtration technology development, favoring scaled manufacturers with captive R&D resources. Long-term viability hinges on silica compliance certification depth rather than standalone performance specifications. Acquisition targets should demonstrate OSHA validation documentation and established contractor fleet relationships. The signal to monitor is EPA wastewater discharge rule expansion into residential renovation segments.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Platform Interoperability Expansion | Locks renovation contractors into cordless ecosystems spanning multiple tool categories. |
| Closed-Loop Water Recycling Integration | Enables EPA-compliant operation without external discharge infrastructure. |
| Laser-Guided Precision System Development | Captures specification premiums in large-format porcelain commercial flooring. |
| OSHA Silica Compliance Certification Investment | Accelerates dry-cutting equipment replacement cycles through regulatory mandate. |
| Rental Fleet Partnership Expansion | Penetrates price-sensitive contractor segments without direct capital sales burden. |
Methodological Framework
Initial hypotheses were tested against primary input from renovation contractor fleet managers, commercial flooring project supervisors, construction equipment rental house procurement directors, and diamond blade manufacturing engineers and refined through secondary validation. Regulatory filings from OSHA and EPA, customs trade data on power tool imports, equipment distributor inventory records, and patent databases on brushless motor and filtration technologies anchored triangulation. Bottom-up unit shipment estimates from distribution channels converged with top-down construction spending allocation models.
Demand-supply balance dynamics across wet-cutting system adoption curves and battery platform conversion rates structured the analytical framework. Segmentation dimensions modeled include power modality, cutting technology, end-user sophistication tier, and regional regulatory enforcement intensity. CAGRs derived from equipment replacement cycle compression patterns and housing stock age demographics. Silica exposure limit enforcement timelines and lithium-ion platform interoperability standards served as industry-specific forecast inputs across the projection horizon.
Practitioners should monitor EPA wastewater discharge rule expansion and OSHA silica enforcement pattern shifts for early signals of equipment specification change. Forecasts reflect assumptions regarding regulatory compliance deadline adherence and battery platform consolidation trajectories. Material shifts in federal environmental enforcement intensity or lithium-ion supply chain disruption would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Orbital Recip Saw Market
Tools
Automotive Torque Tools Market
Tools
Cutting Pipe and Perforating Pipe Drilling Tools Market
Tools
Cutting Equipment Market
Tools
Rivet Gun Market
Tools
Europe Paint Spray Guns Market
Tools
Engraver Machine Market
Tools
Woodpecker Tools Market
Tools
Lathe Machines Market
Tools
Aluminum Folding Ladders Market
Tools
Industrial Floor Scrubber Market
Tools
China Power Tools and Hand Tools Market
Tools
Pipe Alignment Clamps Market
Tools
Tool Pliers Market
Tools
Mechanical Puller Market
Tools
Hand and Power Tools Market