
 Tool Boxes Market | 2026-2036
Tool Boxes Market Size, Share, and Industry Trends Forecast 2026-2036
Tool Boxes Market Analytics
Asset-light leasing models for mobile workshop fleets is tilting competitive dynamics toward providers with flexible financing infrastructure. Stanley Black & Decker leverages its captive distribution network to sustain recurring revenue from professional trades. Snap-on Incorporated anchors its position through franchise-van routes that control last-mile access to mechanics. Techtronic Industries competes on cordless platform ecosystems that extend storage compatibility across power tool lines.
Tool boxes constitute rigid enclosures engineered from steel, aluminum, or high-impact polymers with load ratings, drawer-slide mechanisms, and weather-sealing specifications designed to protect, organize, and transport hand tools and power equipment across industrial, commercial, and residential settings. Metal fabrication dominates premium segments where gauge thickness and powder-coat durability command price premiums, while plastic resins occupy lightweight portable categories favored by residential DIY users. Rolling tool boxes represent the fastest-expanding product configuration as mobile workforce models proliferate, and wholesale distribution channels capture the largest volume flow despite margin compression from direct-to-contractor digital platforms.
OSHA mandates on loose-tool containment in industrial settings shape product design requirements for latching systems and load security, while EPA guidelines on powder-coat emissions influence metal-finishing plant locations and compliance costs. The EU RoHS framework restricts hazardous substance content in polymer formulations exported to European markets. Stakeholders must monitor evolving trade compliance on steel tariffs and polymer feedstock regulations that could reshape sourcing geography and finished-goods cost structures.
Market Dynamics
Mobile workforce proliferation and fleet electrification are compressing tool storage footprints while expanding demand for weather-sealed, vehicle-integrated systems that protect high-voltage diagnostic equipment.
Growth Catalysts
- OSHA containment mandates:Tightened workplace safety rules on loose-tool hazards in manufacturing plants are forcing upgrades to latching systems and load-secure drawer mechanisms.
- Texas manufacturing corridors:Heavy equipment servicing hubs along the Gulf Coast are driving concentrated procurement of rolling cabinet systems for field maintenance crews.
- Polymer composite advances:High-impact thermoplastics with UV stabilization are displacing steel in portable categories favored by residential contractors.
Market Restraints
- Steel tariff volatility:Section 232 duties on imported cold-rolled steel are elevating input costs for metal fabrication plants in Ohio and Pennsylvania.
- Single-source powder-coat supply:EPA emissions compliance has concentrated specialty finishing capacity among three domestic operators, creating bottleneck risk.
- Polymer feedstock instability:Propylene price swings tied to Gulf Coast petrochemical outages are compressing margins on plastic-resin tool box lines.
Strategic Opportunities
- EU RoHS expansion:Upcoming restrictions on additional hazardous substances in polymer formulations create first-mover advantage for compliant suppliers exporting to European markets.
- Electric vehicle fleet conversion:Commercial trucking electrification is generating demand for insulated storage systems protecting high-voltage testing gear.
- Direct-to-contractor platforms:Digital procurement channels bypassing wholesale distribution are capturing margin previously lost to distributor markups.
Industry Challenges
- Welding certification scarcity:Shortage of AWS-certified aluminum welders is constraining expansion of lightweight premium product lines.
- ISO 9001 audit backlogs:Extended certification timelines are delaying supplier qualification for automotive OEM vendor programs.
- Legacy fleet integration:Retrofitting organized storage into existing commercial vehicle configurations requires custom fabrication capacity that strains production scheduling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tool Boxes Market |
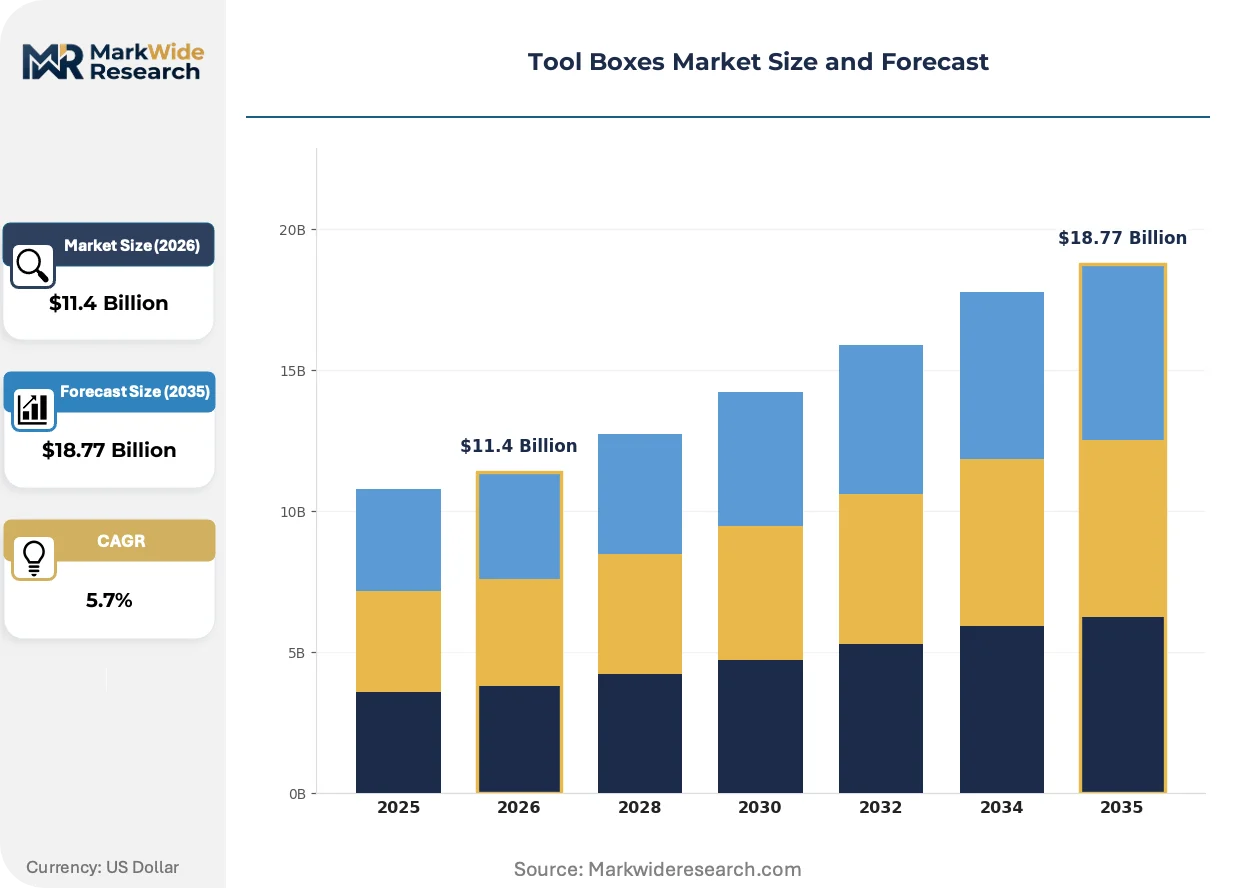
| Market Size in 2026 | $11.4 Billion |
| Market Size in 2035 | $18.77 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Tool Boxes, Tool Chests, Rolling Tool Boxes, Tool Cabinets Material: Metal, Plastic, Wood, Composite Capacity: Small, Medium, Large, Extra Large Distribution Channel: Online Retail, Specialty Stores, Hardware Stores, Wholesale |
| Companies Covered | Stanley Black & Decker, Snap-on Incorporated, Techtronic Industries, Apex Tool Group, Matco Tools, Husky, Craftsman, Bosch, DeWalt, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tool Boxes Market Evolving Landscape
Tool storage systems are converging with connected equipment ecosystems and modular vehicle architectures, compressing traditional product boundaries between hardware, software, and fleet management services.
RFID-enabled inventory tracking is digitizing asset visibility for mobile mechanics managing dispersed tool sets across multiple job sites. Commercial fleet operators in Great Lakes automotive hubs are piloting these systems at scale. The technology is digitizing warranty claim verification and reducing replacement cycle disputes between contractors and equipment lessors.
REACH substance restrictions on chromium(VI) in surface treatments are forcing metal finishers to migrate toward trivalent chrome and zirconium-based pretreatment chemistries. Powder-coat applicators in Germany and Poland are absorbing capital costs for conversion lines. Tool box manufacturers exporting to EU markets are redesigning hinge and latch hardware to eliminate hexavalent chrome passivation layers.
Subscription-based fleet outfitting is displacing capital purchase models among regional trucking operators seeking to preserve balance-sheet flexibility. Leasing providers are bundling tool storage, diagnostic equipment, and maintenance services into single monthly rates. This pattern is most visible in Texas and California corridors where asset-light logistics operators are expanding contracted maintenance capacity.
Tool Boxes Market Segmentation
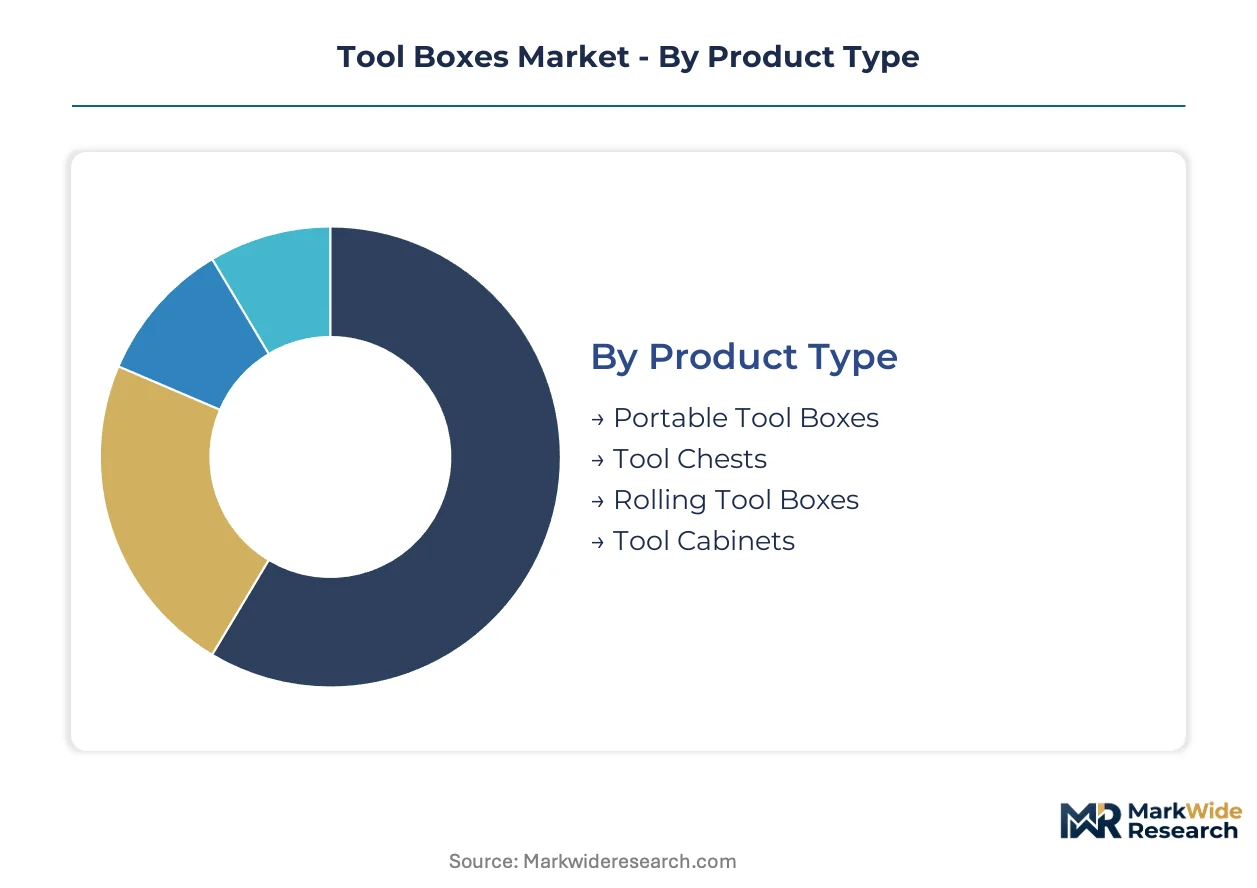
Tool box segmentation reflects divergent user workflows across fixed workshop installations and mobile field operations. Material selection and distribution channel access determine margin capture and customer lifetime value for manufacturers serving industrial, commercial, and residential end-uses.
Product Type:
Mature configurations dominate established workshop infrastructure while emerging formats address fleet mobility requirements.
- Portable Tool Boxes:Hand-carry designs constructed from stamped steel or rotationally molded polymers with integrated tote trays and removable dividers. Residential contractors in Texas Gulf Coast corridors favor these for residential HVAC service calls where vehicle cargo space is constrained.
- Tool Chests:Stationary top-box units with ball-bearing drawer slides rated for 100-200 pound loads, designed for benchtop or cabinet-top mounting in fixed workshop environments. Great Lakes automotive hubs drive concentrated procurement for dealership service departments requiring organized fastener storage.
- Rolling Tool Boxes:Telescoping-handle designs with pneumatic or solid-core casters enabling single-user transport across job sites. Fleet electrification is compressing storage footprints while expanding demand for weather-sealed units protecting diagnostic equipment.
- Tool Cabinets:Floor-standing systems with full-extension drawers and side-locking mechanisms securing high-value power tools in commercial maintenance facilities. OSHA containment mandates on loose-tool hazards are forcing upgrades to latching systems in manufacturing plants.
Rolling tool boxes handles the majority of throughput growth; portable tool boxes is the fastest mover on share among residential contractors.
Material:
Cost tier stratification separates premium metal fabrication from economy polymer alternatives serving distinct customer workflows.
- Metal:Cold-rolled steel and aluminum alloy constructions with powder-coat or zinc-plated finishes, specified for load ratings and impact resistance in industrial settings. Section 232 steel tariff volatility is elevating input costs for Ohio and Pennsylvania fabrication plants serving automotive OEM vendor programs.
- Plastic:High-impact polypropylene and ABS thermoformed shells with UV stabilizers preventing brittleness in outdoor exposure. Propylene price swings tied to Gulf Coast petrochemical outages are compressing margins on resin-based product lines.
- Wood:Hardwood or plywood constructions with brass hardware, traditionally specified for residential garage storage and custom workshop builds where aesthetic integration matters.
- Composite:Hybrid constructions combining fiberglass-reinforced polymer skins with aluminum or steel structural frames, positioned between metal durability and plastic weight advantages.
Metal handles the majority of throughput in industrial segments; composite is expanding most quickly as fleet operators seek weight reduction without sacrificing weather sealing.
Capacity:
Volume-based segmentation aligns with tool inventory scale and vehicle integration constraints across customer types.
- Small:Compact designs under 20 inches in primary dimension, accommodating hand tools and compact power equipment for residential DIY users.
- Medium:Intermediate footprints housing mixed hand and power tool sets, representing the standard specification for commercial service technicians.
- Large:Extended-width units with 10+ drawer configurations, specified for master mechanics and fleet maintenance supervisors managing comprehensive tool inventories.
- Extra Large:Full-cabinet systems exceeding 40 inches in width, typically deployed in fixed workshop installations or specialized mobile workshop vehicles.
Medium capacity handles the majority of throughput; extra large is climbing the fastest as fleet operators consolidate tool storage into fewer vehicle-mounted systems.
Distribution Channel:
Customer type and purchase urgency determine channel selection between immediate availability and cost-optimized procurement cycles.
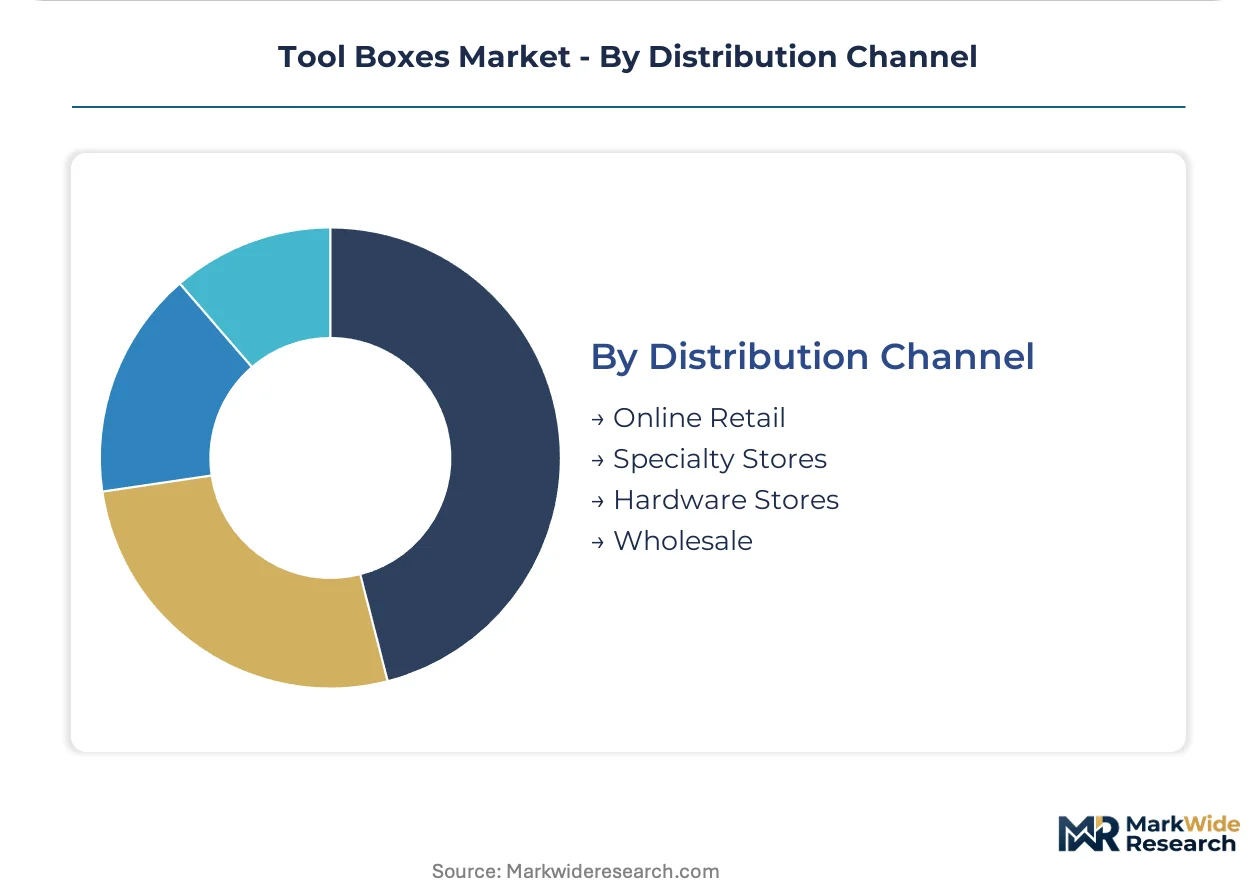
- Online Retail:Digital platforms with direct-to-contractor fulfillment, capturing margin previously lost to distributor markups through price transparency and bulk shipping arrangements.
- Specialty Stores:Professional tool retailers with in-person product demonstration and immediate replacement part availability, serving trades requiring same-day procurement.
- Hardware Stores:General merchandise retailers with localized inventory, capturing residential DIY demand and emergency replacement purchases.
- Wholesale:Volume distributors serving fleet operators and industrial procurement departments with negotiated pricing tiers and scheduled delivery logistics.
Wholesale handles the majority of throughput; online retail is gaining share fastest as digital procurement platforms bypass traditional distributor markups.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in tool boxes track manufacturing density and fleet maintenance demand across concentrated industrial corridors. Trade balances favor production hubs with integrated steel fabrication and polymer compounding capacity serving regional logistics networks.
United States
OSHA workplace safety mandates on loose-tool containment are accelerating replacement cycles in manufacturing plants. The EPA's National Emission Standards for Hazardous Air Pollutants constrain powder-coat finishing capacity, concentrating supply among compliant operators. Texas Gulf Coast heavy equipment corridors drive concentrated procurement of rolling cabinet systems for field maintenance crews.
Germany
REACH substance restrictions on chromium(VI) in surface treatments are forcing metal finishers toward trivalent chrome alternatives. The EU RoHS framework restricts hazardous substance content in polymer formulations exported from German manufacturing bases. Powder-coat applicators in Bavaria and North Rhine-Westphalia are absorbing capital costs for conversion line upgrades.
China
MIIT industrial standards on tool storage safety are tightening compliance requirements for domestic and export-bound production. Dual carbon goals are elevating energy costs for steel fabrication plants in Yangtze River Delta clusters. Zhejiang and Jiangsu province manufacturers are repositioning toward polymer composite lines to reduce carbon-intensive metal finishing.
Japan
METI quality certification requirements shape product specifications for precision tool storage in automotive vendor programs. JIS standards on load ratings and drawer-slide durability command price premiums in professional segments. Chubu region fabrication specialists supply organized storage systems to Nagoya-based automotive OEM maintenance networks.
India
BIS certification mandates on metal gauge thickness and structural integrity are elevating entry barriers for import competition. PLI scheme incentives for domestic manufacturing are attracting capacity expansion in Gujarat and Maharashtra tool fabrication clusters. Pune and Chennai automotive hubs drive procurement of medium-capacity rolling systems for dealership service departments.
Tool Boxes Market Competitive Landscape
On the supply side, the industry is consolidating around three strategic archetypes: diversified industrial conglomerates with captive distribution networks, specialized tool storage manufacturers with franchise-route control, and power tool ecosystem players extending storage compatibility. Competitive dynamics center on M&A activity targeting regional fabrication capacity and strategic partnerships bundling storage with fleet management services.
Within the diversified industrial tier, Stanley Black & Decker and Apex Tool Group occupy positions defined by scale-driven manufacturing and wholesale distribution access. Snap-on Incorporated exemplifies the franchise-route archetype, anchoring last-mile professional access through controlled van-based distribution. Techtronic Industries represents the ecosystem-extension model, competing on cordless platform compatibility that spans storage and power tool lines.
| Leading Market Players |
|---|
| Stanley Black & Decker |
| Snap-on Incorporated |
| Techtronic Industries |
| Apex Tool Group |
| Matco Tools |
| Husky |
| Craftsman |
| Bosch |
| DeWalt |
| Others |
Value Network & Pricing Analysis
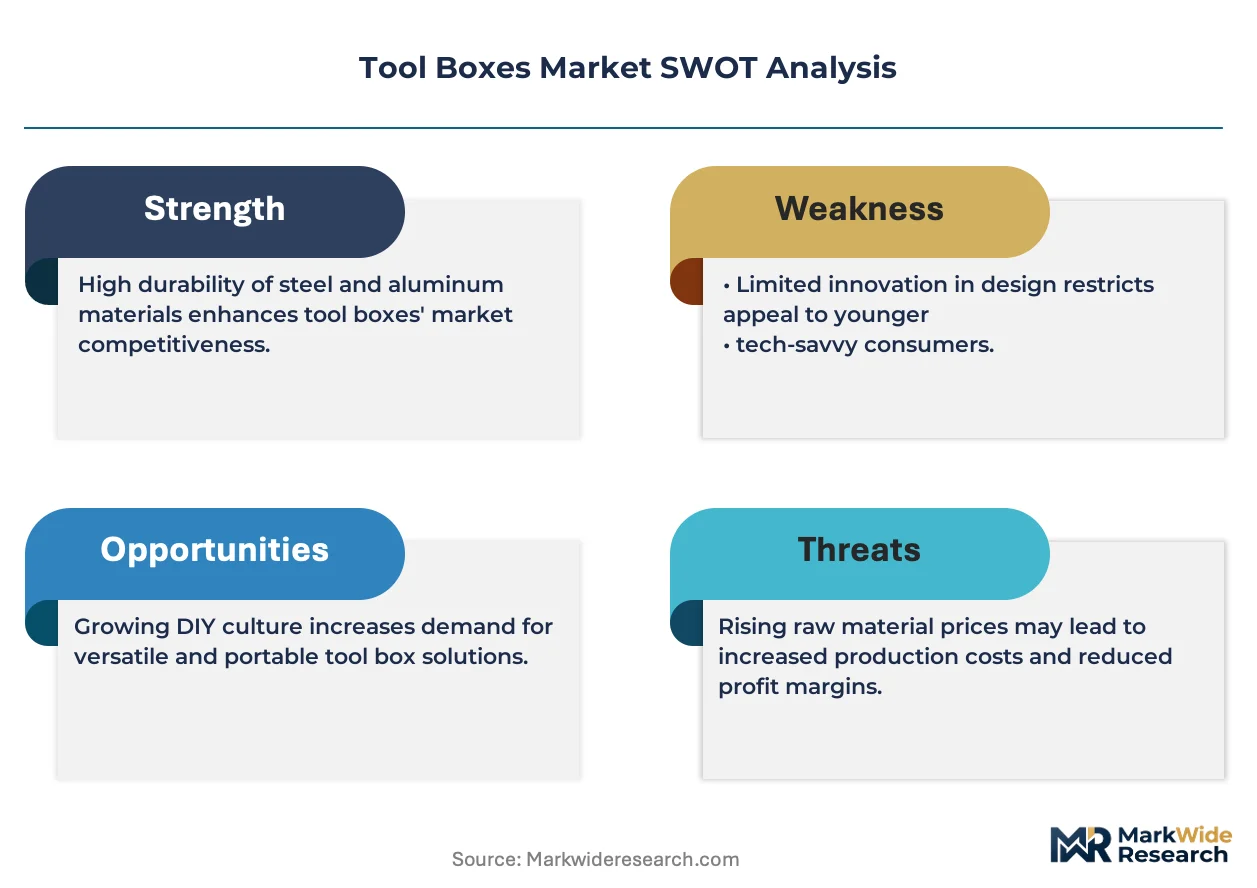
Section 232 tariff exposure on cold-rolled steel imports determines both pricing tier spreads and supply chain shape, compressing margins for Ohio and Pennsylvania fabrication plants while concentrating premium capacity among tariff-exempt domestic mills. This structural cost pressure propagates through three-tier pricing stratification across premium, standard, and economy levels, with polymer composite alternatives capturing displaced demand from steel-dependent product lines.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing stratification across premium, standard, and economy levels, with differentiation resting on ISO 9001 certification grade and powder-coat durability specifications. Cost compression in standard-tier metal fabrication is intensifying because Section 232 duties elevate input costs for cold-rolled steel, while residential contractors exhibit highest price sensitivity and fleet operators demonstrate lowest sensitivity due to bundled service contracts.
Supply Chain Analysis
Contract manufacturing concentration sits with Yangtze River Delta steel fabrication clusters and Zhejiang province polymer compounding facilities, with secondary capacity in Ohio and Pennsylvania for tariff-advantaged domestic supply. Raw material dependencies draw from Gulf Coast petrochemical feedstocks for polypropylene resin, domestic cold-rolled steel from Indiana and Ohio mills, and specialty powder-coat chemistries from concentrated EPA-compliant finishers. Single-source vulnerability in powder-coat finishing capacity creates bottleneck exposure. Distribution runs through wholesale distributors serving fleet operators, with direct-to-contractor digital platforms gaining downstream share.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Tool box manufacturing constitutes a defensive-moat market where regulatory entrenchment through OSHA compliance certification and EPA emissions permitting creates durable barriers against import competition and unqualified entrants.
For Market Incumbents: Build switching-cost moats through captive financing infrastructure for fleet leasing bundles that embed tool storage into long-term service relationships. Add AWS-certified aluminum welding capacity in Texas Gulf Coast corridors to capture lightweight premium segment growth. Defend against polymer composite substitution by deepening powder-coat durability differentiation and expediting REACH-compliant trivalent chrome conversion for EU export qualification. For New Entrants and Emerging Players: Pursue white-space opportunity in insulated high-voltage storage systems for commercial trucking electrification fleets, where incumbent product lines lack thermal protection specifications. Target direct-to-contractor digital procurement channels with modular vehicle-integrated configurations that bypass wholesale distributor markups. Establish go-to-market partnerships with regional fleet lessors seeking asset-light subscription outfitting models. For Investors and Strategic Acquirers: EU RoHS expansion on additional hazardous substance restrictions reshapes the acquisition landscape by elevating compliant polymer formulation capabilities above commodity metal fabrication assets. Long-term viability favors suppliers with integrated REACH certification and captive distribution control over pure manufacturing plays. Monitor EPA National Emission Standards enforcement actions as inflection signal for powder-coat capacity scarcity premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Compounding | Zhejiang manufacturers reduce carbon-intensive metal finishing exposure under MIIT dual carbon goals. |
| REACH-Compliant Surface Treatment Conversion | German powder-coat applicators in Bavaria absorb capital costs for trivalent chrome migration ahead of enforcement. |
| Franchise Route Expansion | Van-based distribution controls last-mile access to Great Lakes automotive hub mechanics. |
| RFID-Enabled Fleet Tracking Integration | Commercial fleet operators in Texas corridors pilot digitized asset visibility for dispersed tool management. |
| Subscription-Based Fleet Outfitting | Regional trucking operators in California corridors preserve balance-sheet flexibility through bundled monthly rates. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs trade data, SEC 10-K filings, and OSHA enforcement records, triangulating input from maintenance directors at commercial fleet operators, plant engineers at Ohio and Pennsylvania fabrication facilities, OEM procurement teams at automotive vendor programs, and aftermarket service heads at wholesale distributors. Bottom-up demand modeling across product type, material grade, capacity tier, and distribution channel converges with top-down trade flow analysis.
Forecast inputs span fleet electrification penetration rates, OSHA compliance audit frequency, and polymer feedstock price volatility across the projection horizon. Segmentation dimensions include product configuration, material construction, capacity classification, and end-use industry vertical. CAGRs derive from regression analysis against historical replacement cycle data and regulatory mandate implementation timelines, with cross-validation against automotive production forecasts and commercial vehicle registration patterns.
Macroeconomic conditions sit as an overlay; deviation in steel tariff rates, propylene pricing, and fleet capital expenditure cycles would shift the trajectory. Quarterly review of EPA enforcement actions, REACH substance restriction proposals, and OSHA citation data is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Manual Cutting Equipment Market
Tools
Gouging Torch Market
Tools
Land Survey Equipment Market
Tools
China Power Tools Market
Tools
Global Swaging Machine Market
Tools
Global Staple Gun Market
Tools
Surface Planer Market
Tools
North America Power Tools Market
Tools
Global Flange Fasteners Market
Tools
Drilling Tools Market
Tools
Machine Tools Market
Tools
Global Tool Holder Adapters Market
Tools
Cordless Power Drill Market
Tools
Stand Tile Saw Market
Tools
Wood-Sanding Machine Market
Tools
Mallets and Sledgehammers Market