
 Cutting Pipe and Perforating Pipe Drilling Tools Market | 2026-2036
Cutting Pipe and Perforating Pipe Drilling Tools Market Size, Share, and Industry Trends Forecast 2026-2036
Cutting Pipe and Perforating Pipe Drilling Tools Market Analysis
Modular tool-string configurations is broadening buyer choice across well-completion programs. Hunting Plc leverages its integrated manufacturing footprint to control supply timelines for shaped-charge perforating systems. Baker Hughes Company anchors its position through R&D intensity in advanced drill-bit metallurgy. Halliburton differentiates via technology leadership in hybrid rotary-linear perforating platforms.
Cutting pipe and perforating pipe drilling tools encompass mechanically or explosively actuated devices engineered to sever, puncture, or enlarge wellbore tubulars, typically fabricated from high-grade steel alloys with tungsten carbide or diamond composite cutting structures, and manufactured through powder metallurgy sintering and precision EDM finishing to achieve downhole pressure ratings exceeding 15,000 psi. These tools enable zonal isolation, production enhancement, and well intervention across hydrocarbon and geothermal extraction. Carbide material segments command premium positioning due to extreme wear resistance in abrasive formations. Hydraulic technology adoption leads growth trajectories as operators pursue higher shot density in unconventional reservoirs. Steel-based cutting tools remain the mature volume category, serving standard well-intervention work where cost efficiency outweighs performance extremes.
API standards, NHTSA transportation regulations for explosive materials, and EPA emissions frameworks collectively shape product certification, logistics constraints, and operational permitting for drilling tool manufacturers. The EPA's hazardous waste classifications affect spent perforating charge disposal protocols, while API RP 19B testing requirements mandate documented performance under simulated downhole conditions. Stakeholders must monitor evolving state-level methane regulations and API specification revisions to anticipate compliance-driven procurement shifts.
Market Dynamics
Extended-reach horizontal drilling in the Permian Basin is compressing well completion timelines and forcing perforating system suppliers to pre-integrate cutting tools with wireline logging packages before they reach the wellsite.
Growth Catalysts
- Hydraulic perforating technology:Operators in unconventional shale basins deploy higher shot-density systems to maximize reservoir contact. API RP 19B testing requirements validate performance under simulated downhole conditions above 15,000 psi.
- EPA hazardous waste frameworks:Stricter disposal protocols for spent perforating charges are accelerating demand for reusable mechanical cutting alternatives in environmentally sensitive drilling jurisdictions.
- Carbide material advancement:Powder metallurgy sintering techniques now produce tungsten carbide cutting structures with extreme wear resistance in abrasive formations.
Market Restraints
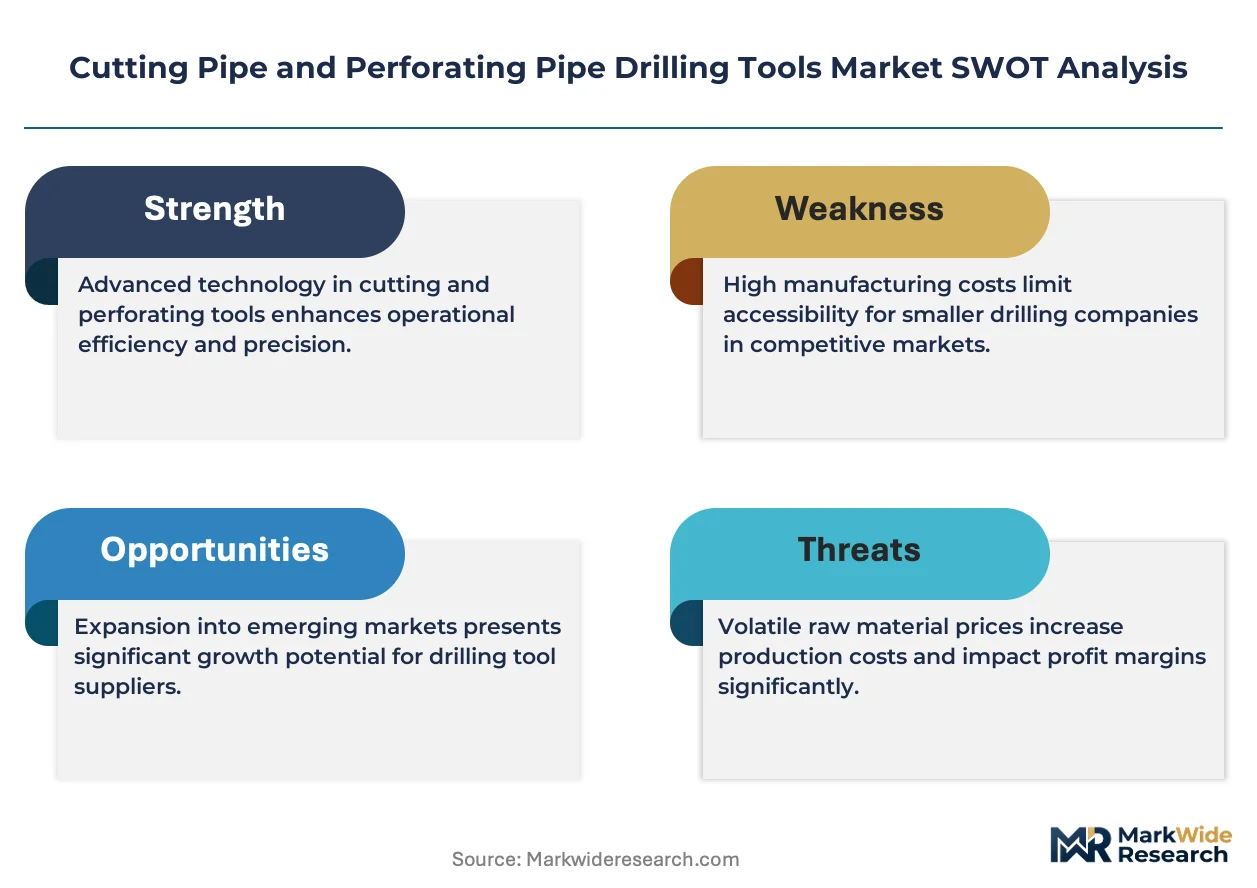
- Steel alloy input volatility:High-grade steel prices fluctuate with scrap metal and alloying element markets, compressing margins for standard well-intervention tool manufacturers.
- Explosive materials logistics:NHTSA transportation regulations for shaped-charge perforating systems create supply chain bottlenecks and extend lead times for integrated tool-string deliveries.
- Geothermal substitution threat:Closed-loop geothermal systems eliminate perforating requirements entirely in certain renewable energy extraction configurations.
Strategic Opportunities
- Geothermal expansion:Enhanced geothermal systems in Nevada and Utah require specialized cutting tools for wellbore enlargement in high-temperature crystalline formations.
- ISO 11960 harmonization:Alignment of international tubular performance standards is reducing certification duplication costs for multi-territory operators.
- Hybrid rotary-linear platforms:Convergence of rotary drilling mechanics with linear perforating actuation is opening new well-intervention service categories.
Industry Challenges
- Powder metallurgy talent scarcity:Precision EDM finishing and carbide sintering expertise concentrates among aging specialists in legacy manufacturing regions.
- API specification revision cycles:Evolving 5CT standards force continuous product recertification, stretching R&D budgets across multiple concurrent compliance tracks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cutting Pipe and Perforating Pipe Drilling Tools Market |
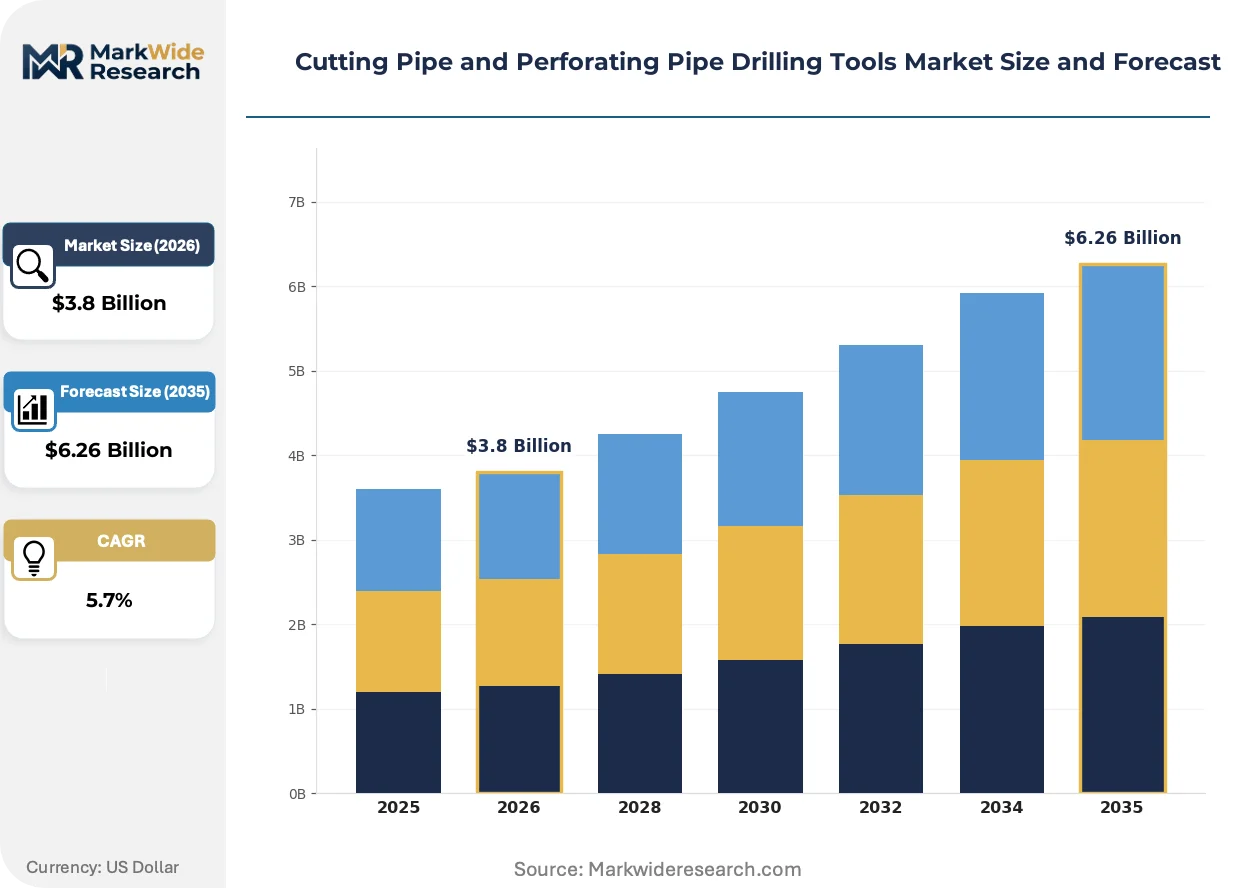
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cutting Tools, Perforating Tools, Drill Bits, Reamers Technology: Rotary, Linear, Hybrid, Hydraulic End User: Oil & Gas, Construction, Mining, Water Supply Material: Steel, Carbide, Diamond, Polymer |
| Companies Covered | Hunting Plc, Baker Hughes Company, Halliburton, ABS Group, Weatherford International Plc, Schlumberger Limited, NOV Inc., Rubicon Oilfield Products Limited, General Electric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cutting Pipe and Perforating Pipe Drilling Tools Market Emerging Trajectories
Diamond composite cutting structures are displacing conventional tungsten carbide in high-pressure perforating applications, while regulatory pressure on explosive materials is accelerating mechanical alternatives.
Electrical discharge machining finishing is integrating with automated powder metallurgy lines to achieve sub-micron tolerance on perforating gun ports. Permian Basin operators now specify these precision-manufactured components for extended-reach laterals where charge alignment determines production rates. The technology is integrating quality control directly into fabrication workflows, compressing inspection timelines from weeks to days.
EPA emissions frameworks are tightening hazardous waste classifications for spent perforating charges, forcing operators to document disposal chain-of-custody. This regulatory pressure is elevating mechanical cutting tools in environmentally sensitive drilling permits. Manufacturers serving the Marcellus Shale region now pre-certify tools against state-level methane regulations to accelerate permitting.
Buyer concentration among supermajor operators is compressing supplier negotiation cycles and unbundling after-sales service from equipment procurement. Independent tool rental firms in the Permian Basin now compete directly with integrated oilfield service companies for maintenance contracts. This channel disintermediation is most visible in Texas and New Mexico, where extended-reach drilling programs demand rapid tool redeployment.
Cutting Pipe and Perforating Pipe Drilling Tools Market Segmentation
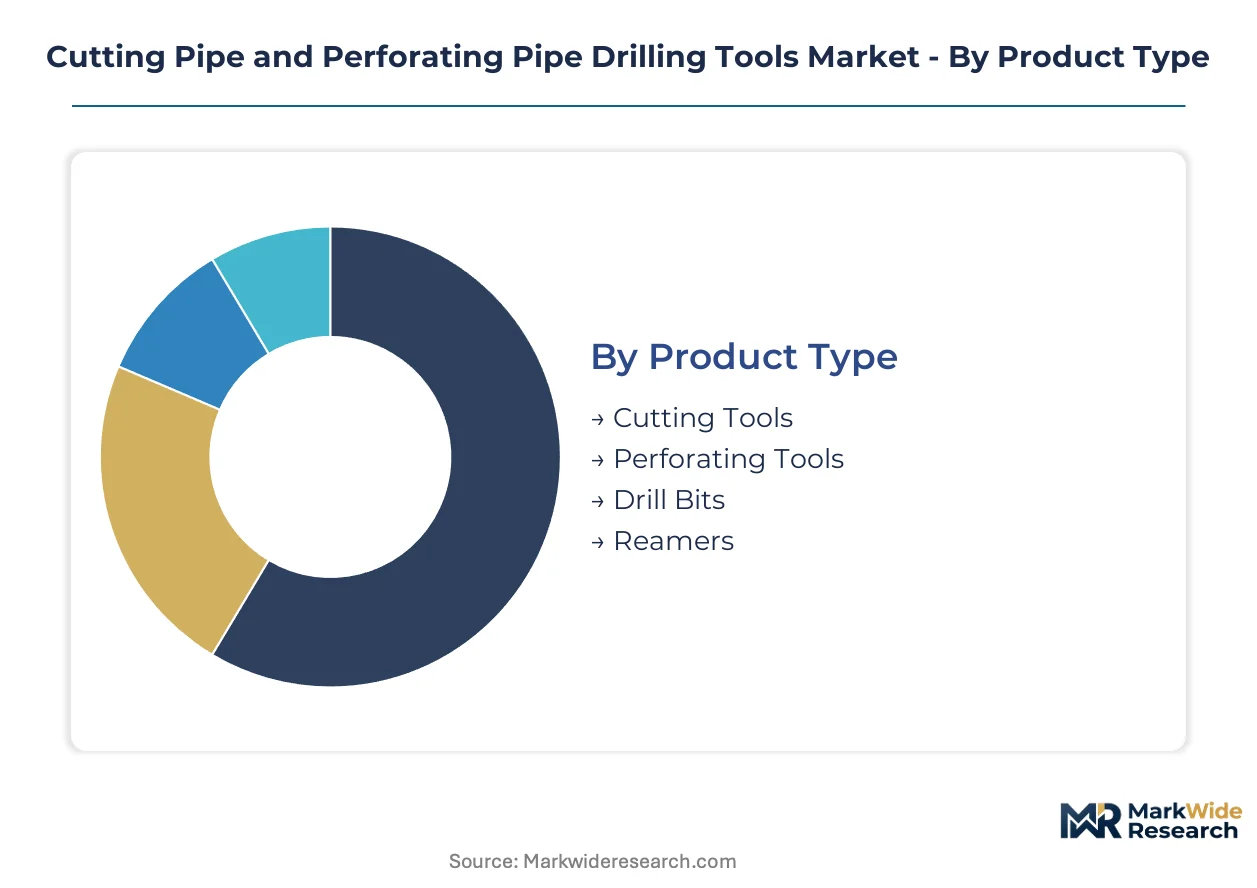
Segmentation in the cutting pipe and perforating pipe drilling tools market reveals how certification requirements, material specifications, and application intensity fragment procurement patterns across operator types. Each dimension carries distinct API validation protocols that shape supplier qualification timelines and contract structures.
Product Type:
API RP 19B testing mandates apply differentially across this category, with explosive-actuated systems requiring documented performance under simulated downhole conditions above 15,000 psi while mechanical alternatives face lighter documentation burdens.
- Perforating Tools:Explosively actuated systems engineered to puncture wellbore tubulars through shaped-charge detonation, typically fabricated from high-grade steel housings with precision-machined charge carriers. Demand concentrates in the Permian Basin of Texas and New Mexico where extended-reach horizontal drilling dominates activity and shot density directly determines production rates.
- Cutting Tools:Mechanically actuated devices designed to sever or enlarge tubulars through rotary or linear force application, often incorporating tungsten carbide or diamond composite cutting structures. Operators in environmentally sensitive drilling jurisdictions are accelerating demand for these reusable alternatives as EPA hazardous waste frameworks tighten disposal protocols for spent explosive charges.
- Drill Bits:Rotary cutting structures at the leading edge of drilling assemblies, manufactured through powder metallurgy sintering to achieve extreme wear resistance in abrasive formations.
- Reamers:Wellbore enlargement tools deployed during drilling or completion phases to smooth ratholes and ensure casing clearance.
Perforating tools sit at the top of the volume ranking, with cutting tools climbing the fastest as regulatory pressure on explosive materials intensifies.
Technology:
Cost tiering separates this category into premium hydraulic systems commanding price multiples over mature rotary platforms, with hybrid configurations occupying an intermediate position as operators balance performance against capital deployment.
- Hydraulic:Fluid-pressure actuation systems enabling higher shot density in unconventional reservoirs, deployed where reservoir contact maximization justifies operational complexity. Permian Basin operators specify these systems for extended-reach laterals where charge alignment precision determines production outcomes.
- Hybrid:Convergence platforms combining rotary drilling mechanics with linear perforating actuation, opening new well-intervention service categories. Halliburton anchors its competitive position through technology leadership in this segment.
- Rotary:Mature mechanical platforms serving standard well-intervention work where cost efficiency outweighs performance extremes.
- Linear:Direct-force actuation systems deployed in specialized cutting applications requiring controlled penetration rates.
Hydraulic technology captures the steepest expansion trajectory, while rotary platforms retain the largest installed base across conventional drilling programs.
End User:
Application intensity varies dramatically across this category, with oil and gas operators demanding pressure ratings exceeding 15,000 psi while construction and water supply segments accept lower specifications at corresponding price points.
- Oil & Gas:Hydrocarbon extraction operators requiring zonal isolation, production enhancement, and well intervention across conventional and unconventional reservoirs. Demand concentrates in extended-reach horizontal drilling programs where API 5CT specifications and ISO 11960 standards tighten product requirements.
- Mining:Mineral extraction operations deploying cutting tools for shaft sinking and raise boring in hard-rock environments.
- Construction:Infrastructure projects utilizing directional drilling for utility installation and foundation work.
- Water Supply:Municipal and agricultural well development programs where cost efficiency dominates procurement criteria.
Oil and gas sits at the top of the volume ranking, with mining climbing the fastest as commodity price recovery drives capital deployment into shaft development.
Material:
Margin structures in this category stratify sharply, with diamond composite cutting structures commanding premium positioning due to extreme wear resistance while steel-based tools compete on price in mature replacement markets.
- Carbide:Tungsten carbide cutting structures produced through powder metallurgy sintering and precision EDM finishing, achieving sub-micron tolerance on perforating gun ports. Powder metallurgy talent scarcity concentrates expertise among aging specialists in legacy manufacturing regions.
- Diamond:Synthetic or natural diamond composite cutting structures displacing conventional tungsten carbide in high-pressure perforating applications.
- Steel:High-grade steel alloys serving standard well-intervention work where cost efficiency outweighs performance extremes, though input volatility from scrap metal and alloying element markets compresses manufacturer margins.
- Polymer:Composite materials deployed in specialized applications requiring corrosion resistance or weight reduction.
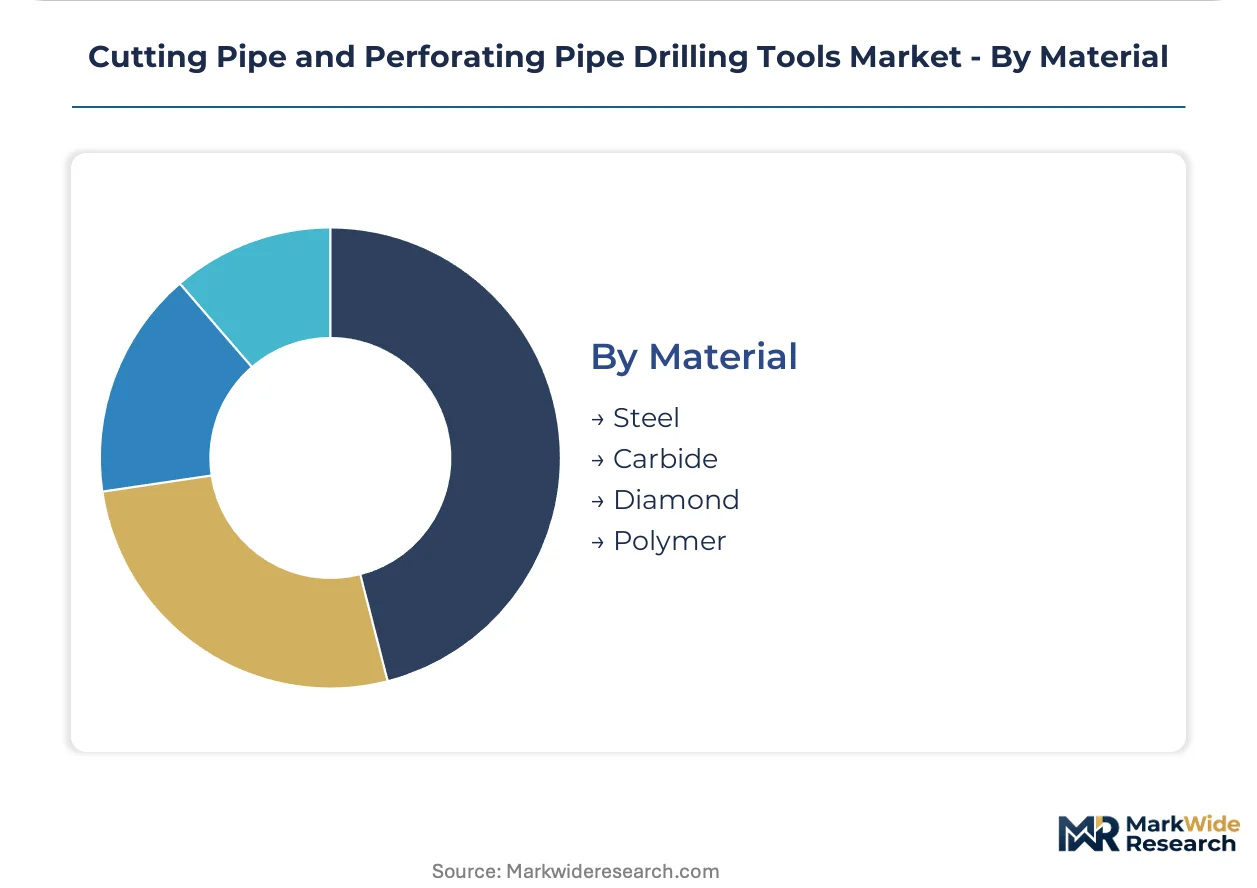
Steel sits at the top of the volume ranking, with carbide gaining share fastest as abrasive formation drilling intensifies in unconventional basins.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The cutting pipe and perforating pipe drilling tools industry traces its commercial scale to the Texas oil boom of the early twentieth century, where shaped-charge perforating technology first enabled controlled wellbore penetration. API standards developed in Houston subsequently diffused to hydrocarbon provinces worldwide, establishing the technical foundation for modern zonal isolation practices.
United States
Permian Basin operators in Texas and New Mexico compress well completion timelines through pre-integrated perforating systems. EPA hazardous waste classifications tighten disposal protocols for spent charges, elevating mechanical cutting alternatives. Houston hosts the densest concentration of perforating gun manufacturers, where EDM finishing capabilities achieve sub-micron tolerance for extended-reach laterals.
Saudi Arabia
Aramco's unconventional gas programs in the Jafurah Basin drive specification for high-pressure perforating systems above 15,000 psi. The national oil company mandates API 5CT compliance across all tubular procurement, accelerating supplier qualification timelines. Dammam's Eastern Province industrial corridor anchors manufacturing partnerships between international service companies and domestic fabrication facilities.
China
Sinopec and PetroChina deploy hydraulic perforating technology in Sichuan's shale gas plays to maximize reservoir contact in complex geological structures. GB standards and MIIT regulations govern domestic tool certification, creating parallel compliance tracks for multinational suppliers. Yangtze River Delta machining clusters specialize in powder metallurgy sintering for tungsten carbide cutting structures.
Canada
Montney Formation operators specify hybrid rotary-linear platforms to navigate extended-reach horizontals in British Columbia's gas-prone fairways. Health Canada and provincial regulators enforce transportation restrictions on explosive materials that extend supply chain lead times. Calgary's oilfield service headquarters coordinate procurement across Alberta's oil sands and unconventional light oil developments.
United Arab Emirates
ADNOC's tight gas concessions in Abu Dhabi require specialized perforating systems for high-temperature carbonate reservoirs. MOHAP and federal environmental frameworks shape hazardous materials handling protocols across onshore and offshore operations. Dubai's Jebel Ali free zone facilitates re-export logistics for perforating tools serving Middle East and North African markets.
Cutting Pipe and Perforating Pipe Drilling Tools Market Vendor Landscape
Premium-margin players sit above commodity-margin players across material-grade and certification-intensity tiers, with diamond-composite and precision-EDM finished tools commanding price multiples over standard steel offerings. The vendor base stratifies into three archetypes: integrated oilfield service conglomerates with captive manufacturing, specialized perforating system houses with powder metallurgy expertise, and regional tool rental firms competing on deployment velocity. Consolidation pressure concentrates among mid-scale fabricators facing API recertification cost burdens, while strategic partnerships between technology licensors and regional distributors accelerate market access in emerging hydrocarbon provinces.
Among integrated service conglomerates, Hunting Plc, Baker Hughes Company, and Halliburton occupy positions spanning the full perforating tool value chain from shaped-charge manufacturing to wireline deployment services. These entities exemplify the premium-tier archetype through backward integration into high-grade steel alloy supply and captive EDM finishing capabilities. Schlumberger Limited and Weatherford International Plc represent alternative structural approaches within the same tier, with organizational configurations emphasizing technology licensing and regional partnership networks respectively. NOV Inc. anchors the drilling equipment specialist segment, while Rubicon Oilfield Products Limited and ABS Group exemplify mid-scale competitors navigating certification cost pressures through focused product line concentration.
| Leading Market Players |
|---|
| Hunting Plc |
| Baker Hughes Company |
| Halliburton |
| ABS Group |
| Weatherford International Plc |
| Schlumberger Limited |
| NOV Inc. |
| Rubicon Oilfield Products Limited |
| General Electric |
| Others |
Supply Flow & Price Mechanics
Private-equity-rolled-up specialists in perforating gun manufacturing anchor supply concentration across Texas industrial corridors, translating captive EDM finishing capacity into pricing discipline on precision-machined charge carriers while compressing margins for non-integrated fabricators dependent on outsourced powder metallurgy.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates API-certified diamond-composite systems from carbide-mid-grade offerings and basic steel interventions. Price differentiation hinges on certification grade and after-sales service bundling. Cost compression in the steel tier intensifies because scrap metal and alloying element volatility squeezes manufacturer margins. Independent tool rental firms in the Permian Basin exhibit highest price sensitivity, while Aramco and ADNOC tolerate premium positioning for high-pressure specifications above 15,000 psi.
Supply Chain Analysis
Direct-to-supermajor channels handle hyperscale buyer demand for pre-integrated perforating systems, while regional rental firms source through distributor networks. Manufacturing gravity centers on the United States, China, and Saudi Arabia. Raw material flows draw from tungsten carbide powder suppliers, high-grade steel alloy producers, and synthetic diamond composite fabricators. Single-source vulnerability concentrates in precision EDM finishing equipment, where aging specialist expertise limits supplier alternatives. Distribution runs through Houston's oilfield service cluster, Dammam's Eastern Province corridor, and Yangtze River Delta machining centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder, with EPA hazardous waste classification tightening for spent perforating charges driving substitution demand toward reusable mechanical alternatives.
For Market Incumbents: Extend backward integration into powder metallurgy sintering to defend margin position against carbide material cost volatility. Consolidate EDM finishing expertise through targeted capability acquisition in legacy manufacturing regions, as talent scarcity threatens production scalability. Pre-certify tool portfolios against evolving API 5CT revisions to compress competitor qualification timelines. For New Entrants and Emerging Players: EPA emissions frameworks in the United States open a window for mechanical cutting tool specialists to capture share in environmentally sensitive drilling permits. Target geothermal expansion in Nevada and Utah as the most penetrable application segment, where high-temperature crystalline formations require specialized wellbore enlargement capabilities. Pursue technology licensing partnerships with established wireline logging providers to bypass capital-intensive manufacturing scale requirements. For Investors and Strategic Acquirers: Integrated oilfield service conglomerates are the most active acquirer in this space, seeking captive manufacturing capacity to control supply timelines. Mid-scale fabricators facing concurrent API recertification cost burdens represent the optimal acquisition target archetype. Monitor state-level methane regulation adoption rates as the signal to watch for compliance-driven procurement inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Powder Metallurgy | Hunting Plc and Baker Hughes anchor competitive positioning through captive tungsten carbide sintering capacity. |
| Hybrid Platform Development | Halliburton's rotary-linear convergence technology opens new well-intervention service categories in extended-reach laterals. |
| EPA Pre-Certification Investment | Marcellus Shale suppliers accelerate permitting timelines by documenting disposal chain-of-custody compliance upfront. |
| Geothermal Capability Expansion | Specialized cutting tools for high-temperature crystalline formations capture Nevada and Utah enhanced geothermal deployment. |
| ISO 11960 Harmonization Alignment | Multi-territory operators reduce certification duplication costs through international tubular standard convergence. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with perforating system engineers, wireline operations managers, powder metallurgy specialists, and EPA regulatory compliance officers with secondary validation against API specification documents, SEC 10-K filings from listed oilfield service companies, and EPA hazardous waste classification updates. Bottom-up demand modeling across operator types and top-down supply verification through customs and trade data provided triangulation.
Segment-weighting applied product type, technology platform, material grade, and end-use intensity dimensions across the projection horizon. CAGRs derived from historical trajectory analysis and forward-looking deployment schedules for unconventional shale basins. Forecast inputs incorporated Permian Basin extended-reach drilling activity levels and API RP 19B testing requirement adoption curves.
Revisions become necessary when EPA emissions framework amendments, API specification revision cycles, or geothermal substitution acceleration materialize outside modeled parameters. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Spray Painting Machine Market
Tools
Hand and Power Tools Market
Tools
Cordless Bandsaw Sander Market
Tools
Pneumatic Marking Machines Market
Tools
Tooling Market
Tools
Leather Cutting Machine Market
Tools
Machine Vise Market
Tools
CNC Leather Cutting Machine Market
Tools
MIG Guns Market
Tools
Adoption of Benelux Power Tools Market
Tools
Automatic Lathe Machines Market
Tools
Pneumatic Tools Market
Tools
Impact Sockets Market
Tools
Industrial Ladder Market
Tools
Digital Laser Levels Market
Tools
Fastening Power Tools Market