
 Concrete Form Oil Market | 2026-2036
Concrete Form Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Concrete Form Oil Market Analysis
Aftermarket form-release servicing is rewriting margin distribution across the concrete form oil value chain. BASF SE leverages its petrochemical backbone to supply synthetic formulations with consistent viscosity profiles. FUCHS Group anchors European demand through specialized industrial lubricant expertise. Sika AG competes by extending its construction chemicals portfolio into premium release agents for complex formwork geometries.
Concrete form oil denotes a surface-treatment fluid applied to formwork substrates to prevent adhesion during concrete curing, typically formulated with mineral base stocks, ester-modified synthetics, or vegetable-derived biodegradable carriers with flash points exceeding 150°C. Mineral oil retains dominant volume share across residential and commercial construction, while biodegradable oil gains traction in infrastructure projects subject to environmental compliance. Synthetic oil commands premium positioning in precast manufacturing where thermal cycling demands chemical stability. Emulsified oil occupies cost-sensitive contractor segments through dilutable concentrate economics.
EPA oversight of volatile organic compound emissions constrains solvent-based formulations in US construction markets. REACH registration requirements in Europe elevate compliance costs for petrochemical-derived mineral oils. India's BIS certification mandates performance testing for construction chemical imports. Stakeholders must monitor regulatory divergence between biodegradable mandates in Western jurisdictions and cost-driven mineral oil persistence in developing construction corridors.
Market Dynamics
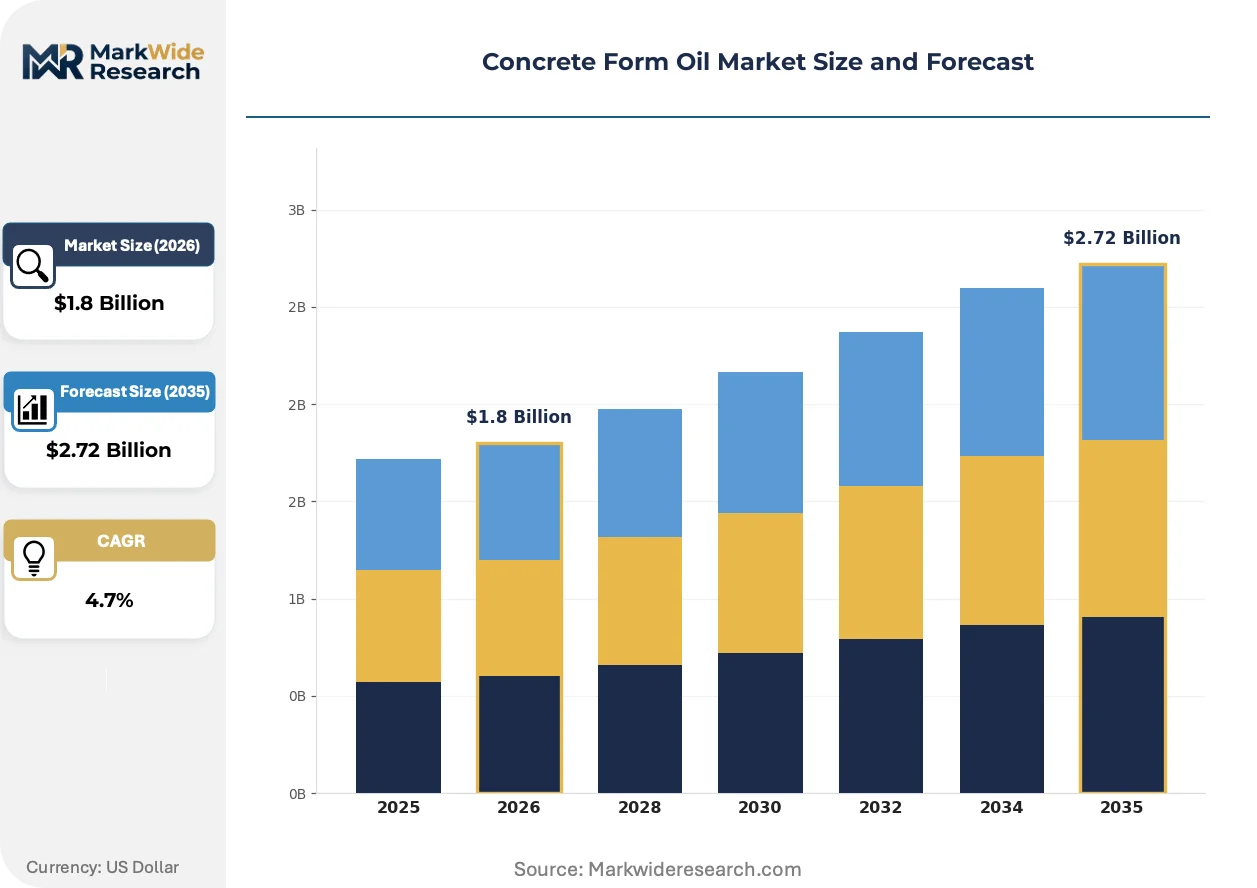
REACH registration requirements in Europe are forcing reformulation across mineral oil supply chains while India's precast corridor and Gulf megaproject clusters pull demand toward synthetic and biodegradable alternatives.
Growth Catalysts
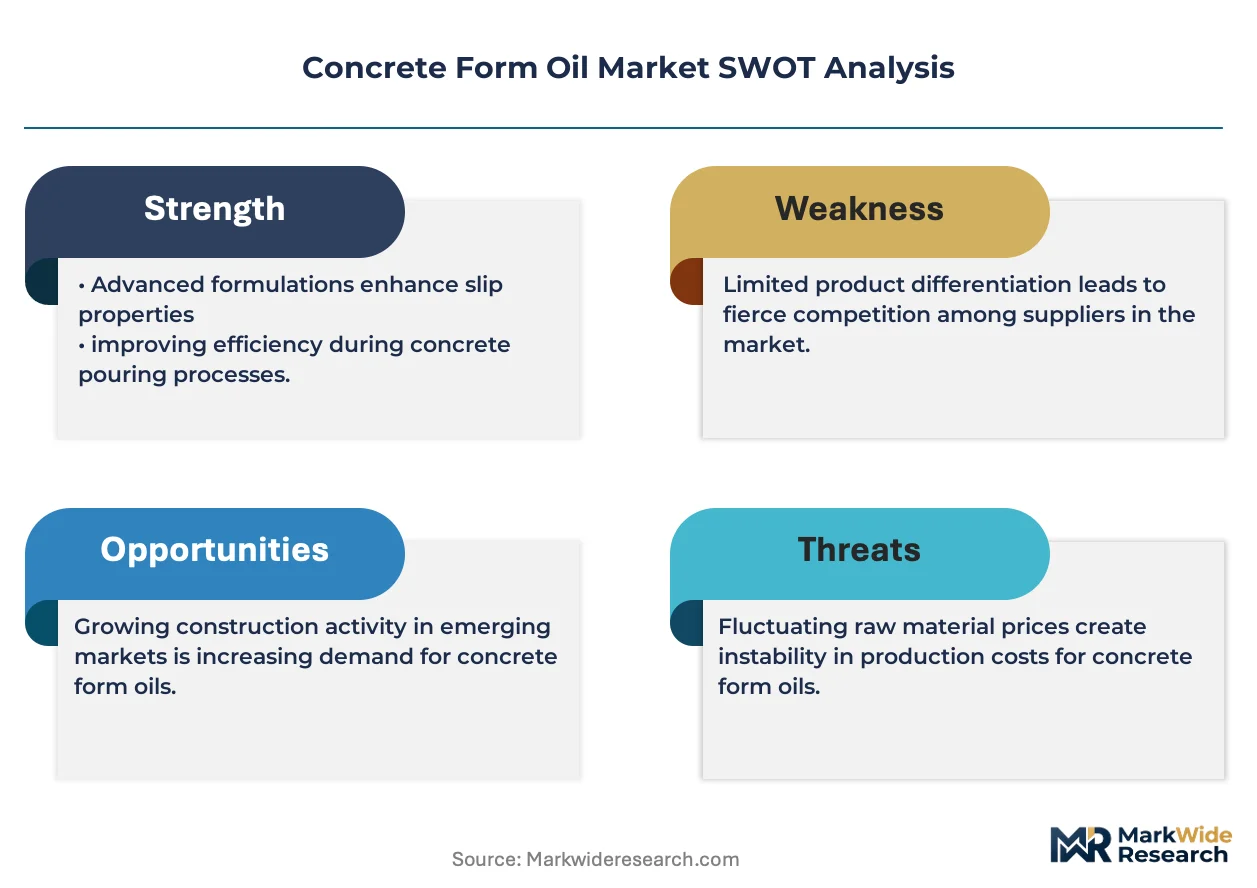
- EU REACH Framework:Petrochemical registration mandates are elevating synthetic ester formulations above commodity mineral oils in European infrastructure tenders.
- India's PLI Scheme:Domestic manufacturing incentives for construction chemicals are accelerating local blending capacity along the Delhi-Mumbai Industrial Corridor.
- Precast Thermal Cycling:Automated curing chambers in Gulf Cooperation Council megaprojects demand form oils with viscosity stability above 180°C flash points.
Market Restraints
- Base Oil Concentration:Group I mineral feedstock supply concentrates in Middle Eastern refining complexes, exposing formulators to geopolitical freight disruptions.
- Biodegradable Cost Premium:Vegetable-derived carriers command 40-60% raw material premiums over mineral stocks, constraining adoption in cost-sensitive contractor segments.
- Solvent Substitution Limits:EPA VOC emission caps have eliminated aromatic solvent extenders without fully viable low-flash alternatives for cold-weather application.
Strategic Opportunities
- Emulsified Concentrate Distribution:Water-dilutable formulations enable bulk tank logistics that bypass packaged goods bottlenecks in remote Brazilian and Indonesian project sites.
- EU Green Deal Procurement Mandates:Public infrastructure tenders above €5 million now require environmental product declarations, creating preferential access for biodegradable-certified suppliers.
- Digital Formwork Monitoring:Integration of release-agent sensors with IoT-enabled formwork systems creates predictive reapplication protocols in German and Japanese precast plants.
Industry Challenges
- Formulation Chemist Scarcity:Expertise in ester-modified synthetic blending remains concentrated among retiring specialists at European industrial lubricant houses.
- BIS Certification Timelines:India's mandatory performance testing for construction chemical imports extends product registration cycles by 8-14 months.
- Legacy Equipment Compatibility:Biodegradable oils with divergent polarity profiles degrade conventional pump seals in aging site equipment across Latin American contractor fleets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Concrete Form Oil Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mineral Oil, Biodegradable Oil, Synthetic Oil, Emulsified Oil Application: Residential Construction, Commercial Construction, Infrastructure Projects, Precast Manufacturing End User: Contractors, Construction Companies, Manufacturers, DIY Enthusiasts Distribution Channel: Online Retail, Direct Sales, Wholesale Distributors, Specialty Stores |
| Companies Covered | Croda International Plc, Henkel AG & Co. KGaA, BASF SE, MAPEI S.p.A., Evonik Industries AG, Sika AG, Dow Chemical, Fosroc, Inc., FUCHS Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Concrete Form Oil Market Emerging Trajectories
Digital release-agent monitoring systems are compressing reapplication cycles while regulatory chemistry mandates and procurement centralization reshape competitive access across project tiers.
Advanced ester-modified synthetics with programmable viscosity curves are virtualizing the traditional mineral-synthetic product boundary. German precast manufacturers now specify single-formulation oils across summer and winter curing protocols. This convergence is virtualizing seasonal SKU proliferation that previously fragmented inventory planning.
China's GB standards for construction chemicals now mandate heavy metal testing and biodegradability screening for imported form oils. Domestic blenders in Shandong and Jiangsu provinces are accelerating SAMR certification for synthetic alternatives. The policy is compressing market access for unregistered mineral oil traders while elevating compliant domestic suppliers in Belt and Road infrastructure packages.
Consolidated procurement by multinational EPC contractors is displacing fragmented site-level purchasing across Southeast Asian infrastructure corridors. Engineering firms like Bechtel and Samsung C&T now mandate certified supplier lists with unified technical datasheets. This concentration is visible most acutely in Vietnam's North-South Expressway segments where single-source form oil contracts cover 200+ kilometer concrete pours.
Concrete Form Oil Market Segmentation
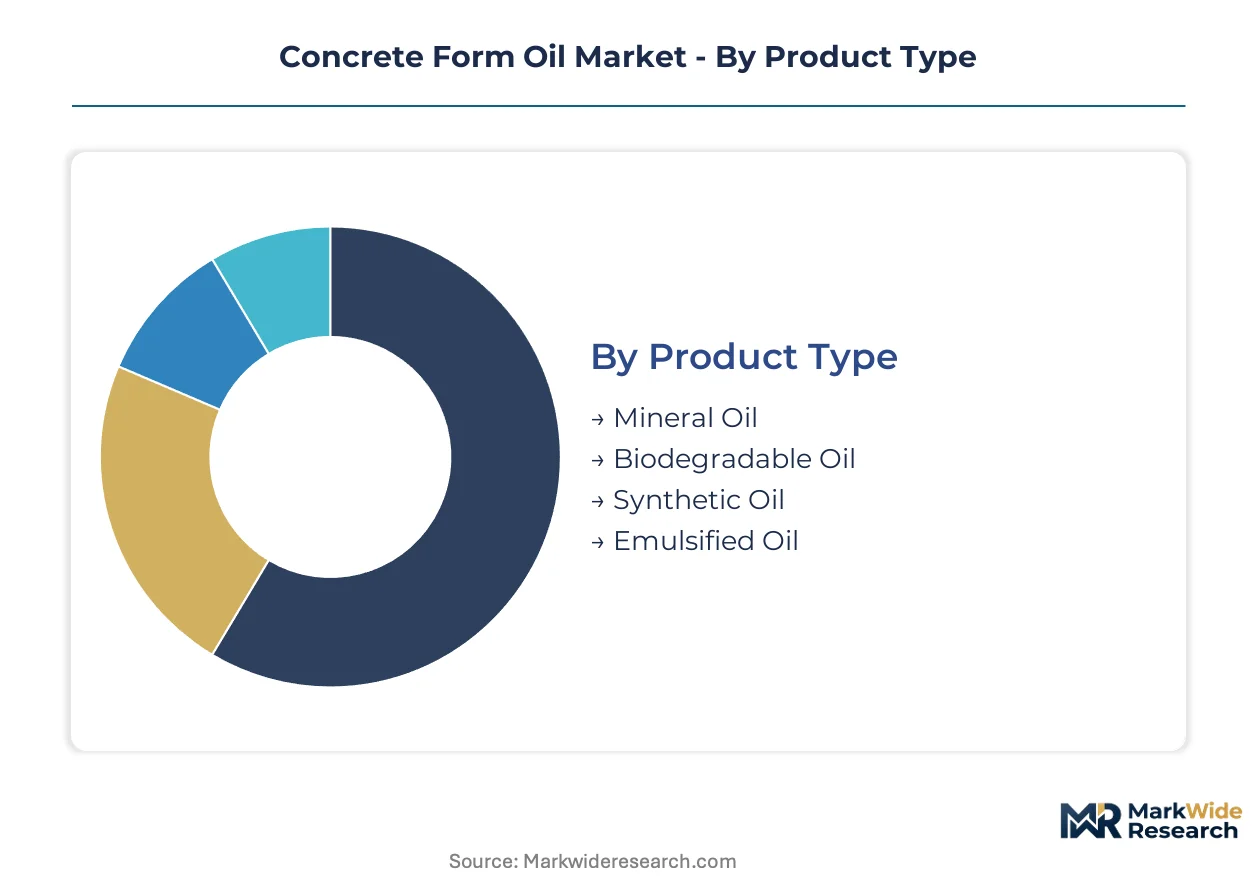
Concrete form oil segmentation reveals divergent margin profiles across product chemistries and procurement channels. Aftermarket servicing intensity varies sharply between bulk infrastructure contracts and spot residential purchases.
Product Type:
After-sales service intensity peaks with synthetic formulations requiring technical support for thermal cycling protocols, while mineral oil transactions complete with minimal follow-on engagement.
- Mineral Oil:Formulated with Group I or Group II petroleum base stocks, these formulations dominate high-volume pours where flash points above 150°C satisfy standard curing requirements. India's precast corridor and Gulf megaproject clusters pull steady demand despite REACH registration pressures in Europe. Contractors favor mineral oil for cost predictability in fixed-bid infrastructure contracts.
- Synthetic Oil:Ester-modified synthetics deliver programmable viscosity stability across automated curing chambers operating above 180°C. German and Japanese precast manufacturers specify these formulations for complex formwork geometries where thermal cycling demands chemical consistency. The segment commands premium positioning through technical specification rather than commodity pricing.
- Biodegradable Oil:Vegetable-derived carriers with ester modifications serve EU Green Deal procurement mandates and China's GB standards for heavy metal compliance.
- Emulsified Oil:Water-dilutable concentrates enable bulk tank logistics across remote Brazilian and Indonesian project sites.
By volume, mineral oil leads. By growth pace, biodegradable oil is expanding most quickly.
Application:
Cost tier separation distinguishes commodity residential pours from specification-driven precast manufacturing where formulation chemistry directly determines surface finish quality.
- Infrastructure Projects:Mega-scale concrete pours across India's Delhi-Mumbai Industrial Corridor and Vietnam's North-South Expressway demand certified supply chains with unified technical datasheets. Engineering firms mandate pre-qualified supplier lists, compressing market access for unregistered traders.
- Precast Manufacturing:Automated curing chambers in Gulf Cooperation Council clusters require form oils with validated viscosity curves across seasonal temperature swings. German manufacturers now specify single-formulation oils replacing seasonal SKU proliferation.
- Residential Construction:Cost-sensitive contractor segments favor emulsified concentrates through wholesale distributor networks.
- Commercial Construction:Mid-tier specifications balance performance requirements against budget constraints in urban high-rise developments.
By volume, infrastructure leads. By margin concentration, precast manufacturing is ahead.
End User:
Customer type determines procurement modality, with consolidated construction companies negotiating frame contracts while fragmented contractors purchase through distributor spot markets.
- Contractors:Fragmented site-level purchasing across Latin American fleets faces equipment compatibility constraints with biodegradable oil polarity profiles. Aging pump seals degrade without seal material upgrades.
- Construction Companies:Multinational EPC contractors like Bechtel and Samsung C&T disaggregate supplier bases through certified vendor lists with mandatory environmental product declarations.
- Manufacturers:Precast producers integrate release-agent sensors with IoT-enabled formwork systems for predictive reapplication protocols.
- DIY Enthusiasts:Small-volume purchasers access formulations through online retail channels with minimal technical support requirements.
By volume, contractors lead. By contract value concentration, construction companies are ahead.
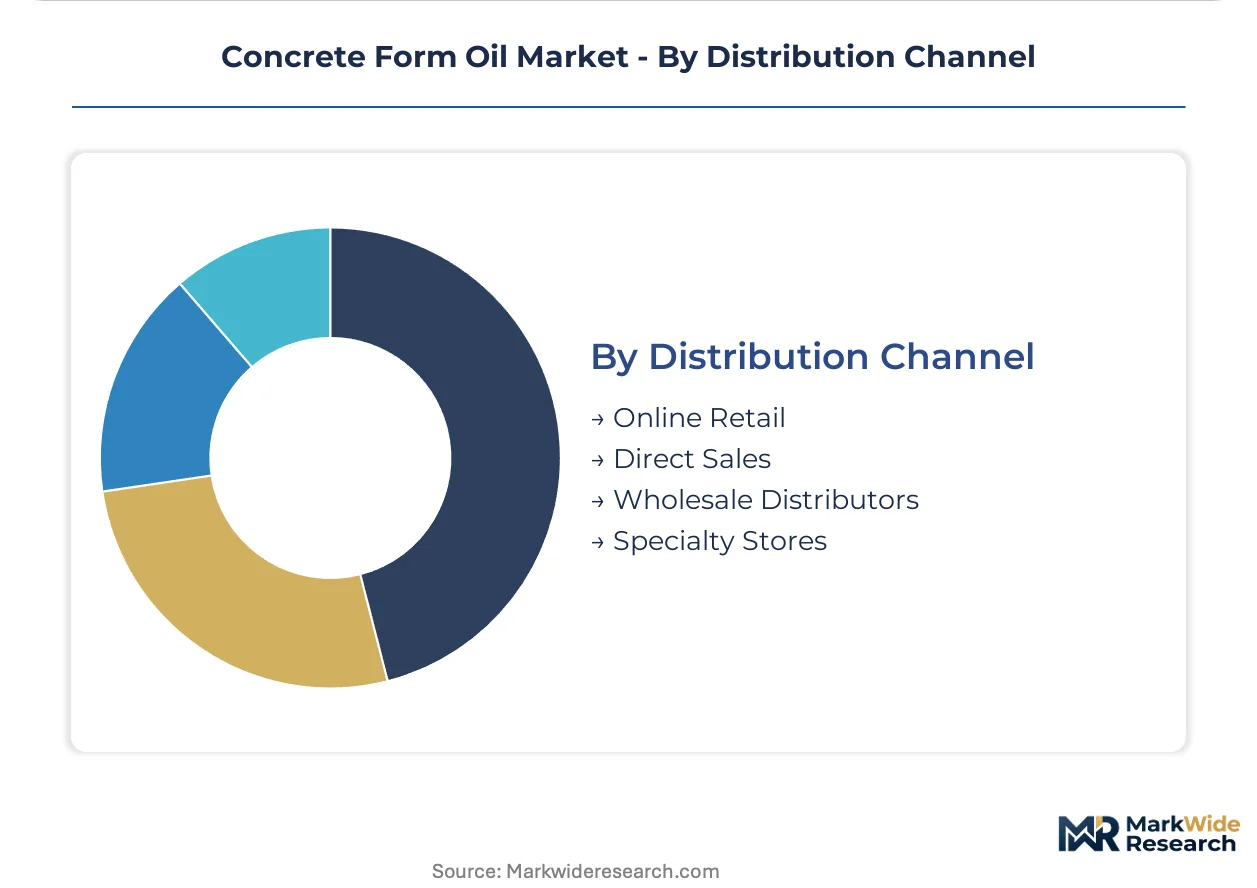
Distribution Channel:
Supply concentration in wholesale distribution reflects the bulk logistics economics of form oil, while digital channels capture peripheral segments.
- Wholesale Distributors:Bulk tank logistics and drum packaging dominate contractor supply across established construction corridors. Middle Eastern refining complex proximity shapes regional distribution hubs.
- Direct Sales:Frame contracts with multinational EPC firms bypass intermediary margins for high-volume infrastructure packages.
- Specialty Stores:Technical consultation services support specification-grade synthetic selection for complex formwork applications.
- Online Retail:Digital channels serve DIY segments and small contractors with standardized mineral oil formulations.
By volume, wholesale distributors lead. By margin expansion, direct sales are ahead.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across construction corridors. India's fragmented contractor base drives mineral oil consumption through spot purchasing, while German precast manufacturers absorb synthetic premiums for thermal cycling compliance.
United States
EPA VOC emission caps eliminated aromatic solvent extenders from cold-weather formulations. Contractors along the Gulf Coast corridor now blend emulsified concentrates for bulk infrastructure pours. Houston-area distributors maintain tank farm capacity serving petrochemical megaprojects.
Germany
REACH registration requirements elevate synthetic ester formulations above commodity mineral oils in federal infrastructure tenders. Bavarian precast plants specify single-formulation oils across seasonal curing protocols. ECHA compliance costs compress market access for unregistered mineral oil traders.
China
GB standards mandate heavy metal testing and biodegradability screening for imported form oils. Shandong and Jiangsu blenders accelerate SAMR certification for synthetic alternatives. Belt and Road infrastructure packages increasingly specify compliant domestic suppliers.
India
PLI scheme incentives accelerate local blending capacity along the Delhi-Mumbai Industrial Corridor. BIS certification extends product registration cycles by 8-14 months for construction chemical imports. Gujarat precast clusters pull demand toward synthetic alternatives despite cost premiums.
United Arab Emirates
Gulf Cooperation Council megaprojects demand form oils with validated viscosity stability above 180°C flash points. Dubai and Abu Dhabi automated curing chambers specify ester-modified synthetics for thermal cycling consistency. Consolidated procurement by multinational EPC firms compresses supplier lists.
Concrete Form Oil Market Vendor Landscape
Petrochemical majors and construction chemical specialists split the market across formulation chemistry lines. Mineral oil supply concentrates among integrated refiners with captive base stock access. Synthetic and biodegradable segments attract industrial lubricant houses and specialty chemical players. Capacity expansion and portfolio diversification represent the dominant competitive moves as firms respond to regulatory chemistry mandates.
Within the petrochemical archetype, BASF SE and Dow Chemical exemplify integrated suppliers leveraging feedstock control. FUCHS Group occupies a position among industrial lubricant specialists extending expertise into construction applications. Sika AG and MAPEI S.p.A. represent construction chemical pure-plays competing through specification-grade formulation portfolios.
| Leading Market Players |
|---|
| Croda International Plc |
| Henkel AG & Co. KGaA |
| BASF SE |
| MAPEI S.p.A. |
| Evonik Industries AG |
| Sika AG |
| Dow Chemical |
| Fosroc, Inc. |
| FUCHS Group |
| Others |
Supply Flow & Price Mechanics
Freight corridors linking Middle Eastern Group I base oil refineries to Indian blending facilities impose cost structures that amplify price differentiation between mineral and synthetic formulations. These logistics economics concentrate supply-side power among integrated petrochemical majors while forcing downstream formulators to absorb volatility or pass through to contractor segments with divergent price elasticity.
Pricing Analysis
After-sales technical servicing and frame contract renewals drive lifetime value capture across synthetic formulation tiers. Three-tier pricing structure across premium ester-modified synthetics, standard mineral oils, and economy emulsified concentrates reflects certification grade and volume scale differentiation. Pricing pressure stems from REACH compliance cost absorption in European markets. Cost-sensitive residential contractors exhibit highest price sensitivity, while Gulf precast manufacturers absorb synthetic premiums for thermal cycling guarantees.
Supply Chain Analysis
Contract manufacturing capacity for ester-modified synthetics concentrates among German industrial lubricant houses and Chinese SAMR-certified blenders in Shandong province. Base stock supply draws from Saudi Arabian and Kuwaiti refining complexes, with vegetable-derived carriers sourcing from Malaysian and Indonesian palm oil plantations. Single-source vulnerability runs through Middle Eastern Group I feedstock concentration. Distribution runs through wholesale tank farm networks serving bulk infrastructure corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated multinational EPC contractors mandating certified supplier lists, fragmenting access for unregistered traders and elevating compliance investments as table stakes for market participation.
For Market Incumbents: Harden specification-grade formulation portfolios against biodegradable mandates by securing EU Green Deal environmental product declarations. Deepen backward integration into Group II base stock refining to offset Middle Eastern supply disruption exposure. Channel control through direct frame contracts with Bechtel-class EPC firms insulates against distributor disintermediation.
For New Entrants and Emerging Players: Establish a beachhead in India's PLI-accelerated domestic blending corridor along the Delhi-Mumbai Industrial Corridor. Target emulsified concentrate distribution for remote Indonesian and Brazilian project sites where bulk tank logistics bypass packaged goods bottlenecks. Go-to-market leverage rests on water-dilutable formulation economics for cost-sensitive contractor segments.
For Investors and Strategic Acquirers: Carve-out targets emerge from petrochemical majors divesting non-core construction chemical divisions amid portfolio rationalization. Long-term viability favors synthetic and biodegradable specialists with SAMR certification and REACH registration asset bases. Monitor BIS certification timeline compression as inflection signal for Indian market access acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| REACH Registration Asset Acquisition | Pre-registered formulation portfolios bypass ECHA compliance timelines for European infrastructure tenders. |
| Backward Integration into Base Stock Refining | Captive Group II supply secures margin control against Middle Eastern feedstock volatility. |
| Emulsified Concentrate Distribution Partnership | Bulk tank logistics alliances penetrate remote Brazilian and Indonesian contractor markets. |
| IoT-Enabled Release-Agent Monitoring Integration | Sensor partnerships with German precast manufacturers create predictive reapplication revenue streams. |
| PLI Scheme Manufacturing Localization | Domestic blending capacity along India's industrial corridor captures government incentive economics. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with precast plant engineers, construction chemical procurement leads at multinational EPC firms, wholesale distribution channel heads, and technical R&D directors at industrial lubricant houses. Secondary validation drew from customs trade data, BIS certification registries, ECHA REACH submission databases, and SEC filings of listed petrochemical majors. Bottom-up volume triangulation across product chemistry tiers and top-down value reconciliation against infrastructure spending pipelines anchored the analytical framework.
Calibration against historical mineral-to-synthetic substitution elasticities and regulatory compliance cost pass-through rates shaped the projection methodology across the analysis window. Segmentation dimensions modeled include product chemistry tier, application intensity infrastructure versus precast versus residential, procurement channel concentration, and regional regulatory cluster alignment. CAGRs were derived from elasticity-adjusted volume forecasts and price trajectory assumptions incorporating REACH registration cost absorption and PLI scheme localization incentives.
Stress conditions across Middle Eastern base oil supply disruption scenarios, BIS certification timeline extensions, and EU Green Deal procurement mandate acceleration were modeled; outcomes outside those bands fall beyond the analytical envelope. Quarterly review of EPC contractor supplier list consolidation patterns and SAMR certification velocity for Chinese domestic blenders is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Pocket Door Market
Building & Construction Materials
Germany Construction Chemicals Market
Building & Construction Materials
Precast Concrete Manufacturing Market
Building & Construction Materials
Global Drywall Textures Market
Building & Construction Materials
Elastomeric Expansion Joint Market
Building & Construction Materials
Air Barrier Market
Building & Construction Materials
Global Steel Sections Market
Building & Construction Materials
Japan Prefab Wood Building Market
Building & Construction Materials
Fiber Cement Rainscreen Panels Market
Building & Construction Materials
US Terracotta Cladding Market
Building & Construction Materials
North America Fabricated Metal Products Market
Building & Construction Materials
India Ready-Mix Concrete Market
Building & Construction Materials
Suspended Ceiling Systems Market
Building & Construction Materials
North America Cross-Laminated Timber Market
Building & Construction Materials
Carbon Textile Reinforced Concrete Market
Building & Construction Materials
United Kingdom Timber Cladding Market