
 Mechanical Puller Market | 2026-2036
Mechanical Puller Market Size, Share, and Industry Trends Forecast 2026-2036
Mechanical Puller Market Analytics
Heavy-duty specification-tier demand is rotating toward hydraulic pullers rated above 50-ton capacity. SKF leverages its bearing-service ecosystem to anchor aftermarket puller sales across European industrial corridors. Enerpac sustains technology leadership in high-force hydraulic tooling through integrated pump-and-puller systems. Timken competes on geographic dominance in North American rail and power-generation maintenance channels.
A mechanical puller is a force-transfer device employing screw, lever, or fluid-pressure mechanisms to extract interference-fit components from shafts or housings without surface damage, typically achieving pull forces from 2 to 100 tons depending on configuration. Steel-bodied hydraulic pullers dominate structural demand due to fatigue resistance under cyclic loading, while aluminum variants serve aerospace and field-service applications where portability governs procurement. Application segmentation shows machinery maintenance commanding the largest installed-base replacement cycle, with automotive aftermarket puller demand accelerating as electric vehicle powertrain redesigns alter bearing and gear service protocols. Composite-material pullers occupy a nascent tier targeting corrosion-critical environments in chemical processing and offshore equipment.
OSHA lockout/tagout standards and the EU Machinery Directive's force-limitation requirements shape product certification pathways for puller manufacturers seeking transatlantic market access. ISO 9001 quality-system registration and CE marking function as baseline gating criteria for distributor acceptance in regulated procurement channels. Stakeholders must monitor evolving EV-specific maintenance tool standards and assess whether pneumatic puller platforms can displace hydraulic systems in clean-room battery assembly environments.
Market Dynamics
Electric vehicle powertrain redesigns are compressing bearing service cycles and forcing puller manufacturers to recalibrate capacity ratings for lighter, higher-RPM drivetrain components. This technological inflection is redistributing demand across specification tiers faster than replacement-cycle norms.
Growth Catalysts
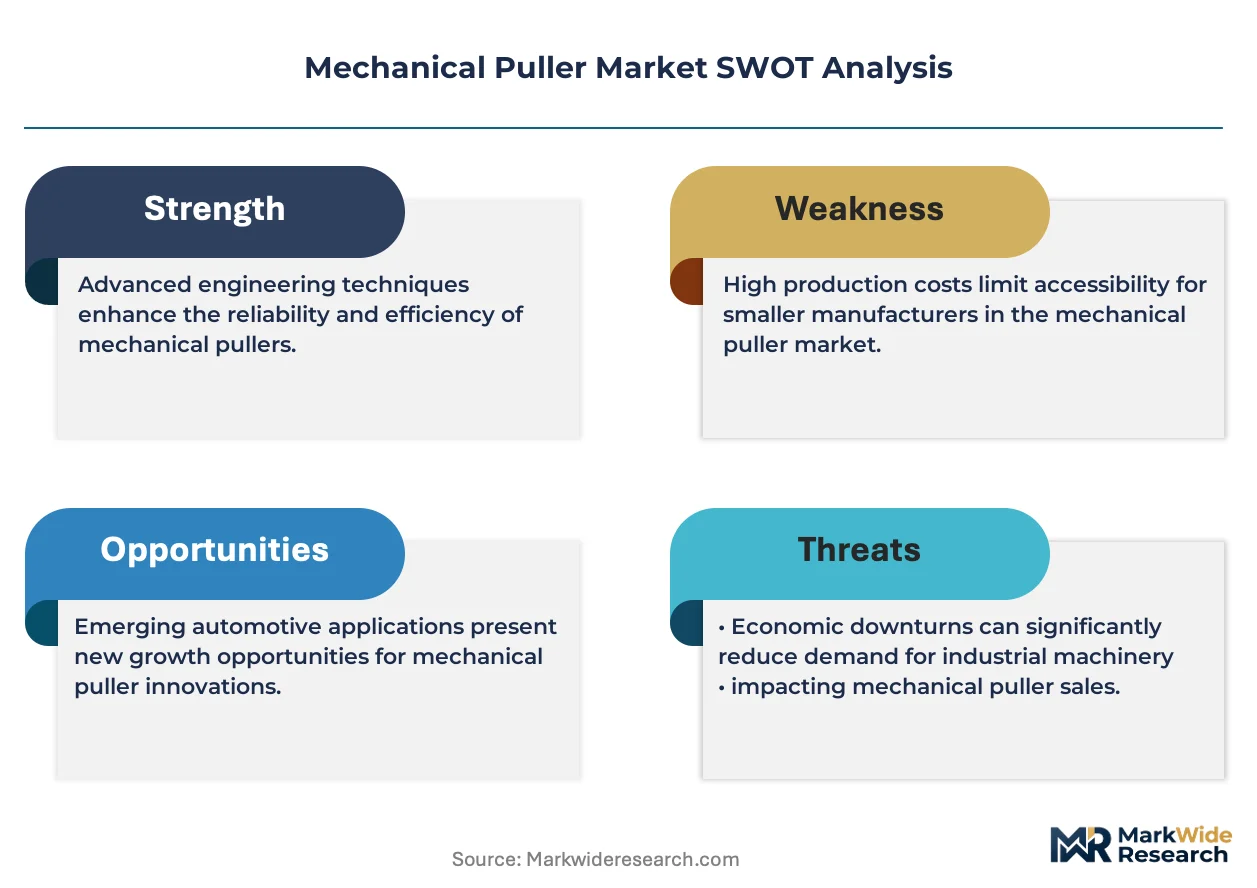
- EU Machinery Directive force-limitation mandates:CE marking requirements for certified load-rated designs are locking non-compliant suppliers out of transatlantic procurement channels, consolidating volume with certified manufacturers.
- China's eastern manufacturing provinces:Automotive aftermarket clusters in Jiangsu and Zhejiang are generating concentrated puller demand as EV production scales and legacy internal combustion engine maintenance transitions.
- Hydraulic puller systems above 50-ton capacity:Heavy machinery maintenance operations in Germany and the United States are expanding procurement of these systems for wind turbine gearbox and rail axle extraction.
Market Restraints
- Specialized alloy input cost volatility:Chromium-molybdenum steel price swings compress margin stability for fatigue-rated hydraulic puller bodies.
- Supply concentration in German pump-and-cylinder manufacturing:Integrated hydraulic system sourcing faces bottleneck risk from limited qualified European component suppliers.
- Pneumatic puller technical limitations:Force inconsistency under variable shop-air pressure prevents displacement of hydraulic systems in precision bearing extraction.
Strategic Opportunities
- India's PLI scheme for automotive component manufacturing:Domestic production incentives are attracting puller distributors to establish localized assembly and calibration facilities.
- Composite-material corrosion resistance:Chemical processing and offshore equipment operators are testing carbon-fiber-reinforced puller bodies for salt-spray environments.
- Convergence of IoT load sensing with hydraulic systems:Real-time force monitoring is enabling predictive maintenance contracts that unbundle hardware from service revenue.
Industry Challenges
- OSHA lockout/tagout certification timelines:Third-party validation delays for new hydraulic puller designs extend product launch cycles by six to nine months.
- Integration complexity with legacy maintenance management software:Field-service teams face workflow friction when connecting smart puller systems to existing enterprise asset management platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mechanical Puller Market |
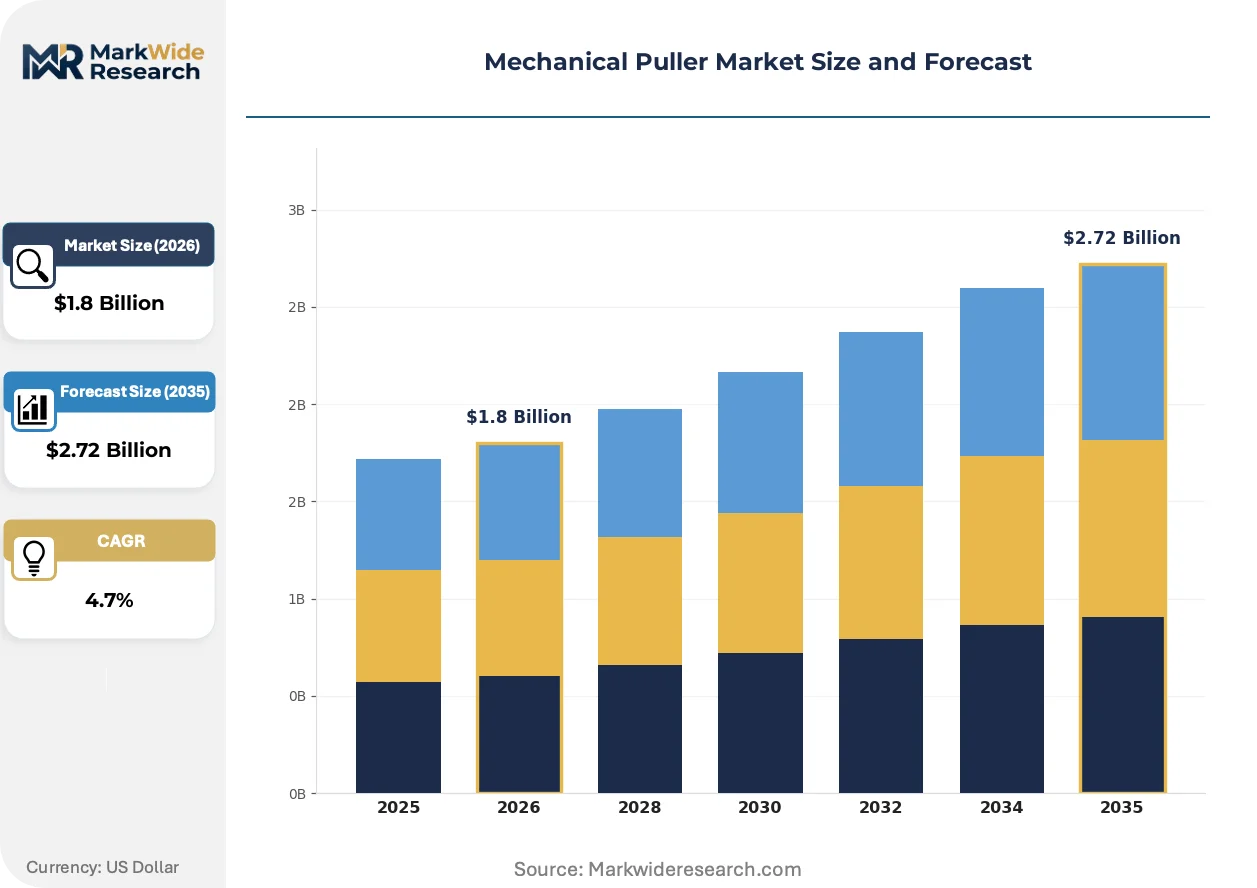
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Manual Pullers, Hydraulic Pullers, Pneumatic Pullers, Electric Pullers Size: Small, Medium, Large, Extra Large Material: Steel, Aluminum, Plastic, Composite Application: Automotive, Machinery Maintenance, Construction, Electrical |
| Companies Covered | SKF, Enerpac, Snap-on Incorporated, Timken, Schaeffler, Stanley Black & Decker, Techtronic Industries, Apex Tool Group, Atlas Copco, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mechanical Puller Market Evolving Landscape
Puller technology is fragmenting across force-generation architectures as end-use requirements diverge between heavy-industrial maintenance and precision field service. This architectural split is forcing manufacturers to place parallel bets on hydraulic, screw-mechanical, and emerging electromechanical platforms.
Smart hydraulic pullers with embedded load cells and Bluetooth telemetry are bifurcating the specification market. Wind turbine maintenance contractors in Denmark and Texas are specifying these systems for remote force verification. The technology is compressing warranty liability for OEMs while enabling usage-based service pricing that separates hardware from calibration revenue.
OSHA's updated lockout/tagout enforcement protocols are mandating redundant mechanical locking on hydraulic puller systems. Industrial maintenance contractors in the United States are retrofitting existing fleets or accelerating replacement cycles. The regulation is most affecting 20-50 ton capacity segments where rental fleets dominate procurement.
Maintenance departments are consolidating vendor relationships around integrated tooling ecosystems rather than standalone puller purchases. Automotive aftermarket chains in China's Pearl River Delta are sourcing from bearing-service platform providers. This bundling behavior is most visible where SKF and Timken have established authorized distributor networks with calibration service attachments.
Mechanical Puller Market Segmentation
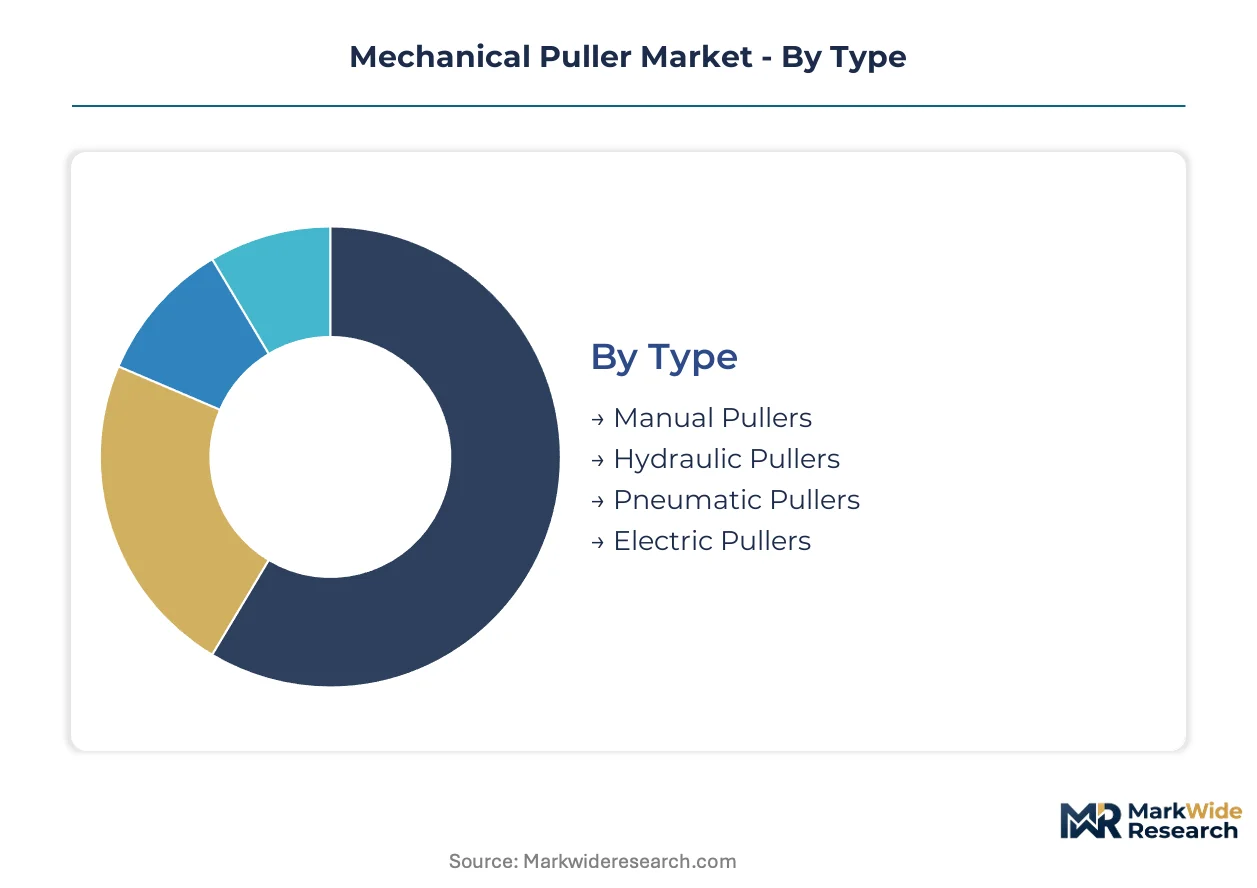
Mechanical puller procurement channels diverge sharply by specification tier. Industrial maintenance contractors source hydraulic systems through authorized distributor networks with calibration service attachments, while automotive aftermarket operators favor portable manual and electric variants through direct e-commerce platforms.
Type:
Channel mix varies dramatically across force-generation architectures. Hydraulic pullers flow primarily through industrial distributors with service bundling, while manual and electric variants concentrate in direct-to-technician online channels.
- Hydraulic Pullers:These systems employ fluid-pressure mechanisms achieving pull forces from 10 to 100 tons through integrated pump-and-cylinder configurations. Demand concentrates in Germany and the United States for wind turbine gearbox and rail axle extraction, driven by EU Machinery Directive force-limitation mandates that lock non-compliant suppliers out of transatlantic procurement channels.
- Manual Pullers:Screw and lever-based force-transfer devices dominate field-service applications where portability governs procurement decisions. China's eastern manufacturing provinces in Jiangsu and Zhejiang generate concentrated demand as EV production scales and legacy internal combustion engine maintenance transitions create dual protocol requirements.
- Pneumatic Pullers:Shop-air-powered systems serve clean-room battery assembly environments where hydraulic fluid contamination risks exclude conventional alternatives.
- Electric Pullers:Battery-powered electromechanical platforms target precision bearing extraction in aerospace maintenance hangars where tethered systems create workflow friction.
Hydraulic pullers dominate installed base. Electric pullers are where expansion concentrates.
Size:
Cost tier stratification separates specification tiers by capital intensity and replacement cycle frequency. Large-capacity systems command premium pricing with decade-long service intervals, while small units operate on consumable-like replacement economics.
- Large:Systems rated above 50-ton capacity feature chromium-molybdenum steel bodies engineered for fatigue resistance under cyclic loading. Heavy machinery maintenance operations in Germany and the United States are expanding procurement for wind turbine gearbox extraction, though specialized alloy input cost volatility compresses margin stability for manufacturers.
- Extra Large:Custom-engineered pullers exceeding 100-ton capacity serve offshore equipment and heavy rail maintenance with project-based procurement through OEM-direct channels.
- Medium:20-50 ton capacity segments face accelerated replacement cycles as OSHA lockout/tagout enforcement protocols mandate redundant mechanical locking, most affecting rental fleet procurement in the United States.
- Small:Portable units below 10-ton capacity target automotive aftermarket bearing service with price-sensitive procurement through e-commerce platforms.
Medium-capacity systems dominate installed base. Large-capacity systems are where expansion concentrates.
Material:
Application environment dictates material selection, with corrosion resistance and weight trade-offs driving specification divergence between industrial maintenance and field-service use cases.
- Steel:Steel-bodied hydraulic pullers dominate structural demand due to fatigue resistance under cyclic loading. Wind turbine maintenance contractors in Denmark and Texas specify these systems for remote force verification with embedded load cell integration.
- Composite:Carbon-fiber-reinforced puller bodies occupy a nascent tier targeting corrosion-critical environments in chemical processing and offshore equipment, where salt-spray resistance governs procurement.
- Aluminum:Lightweight variants serve aerospace and field-service applications where technician portability governs procurement decisions.
- Plastic:Polymer-bodied manual pullers target single-use or low-cycle applications in electrical component extraction where conductive material risks exclude metal alternatives.
Steel dominates installed base. Composite is where expansion concentrates.
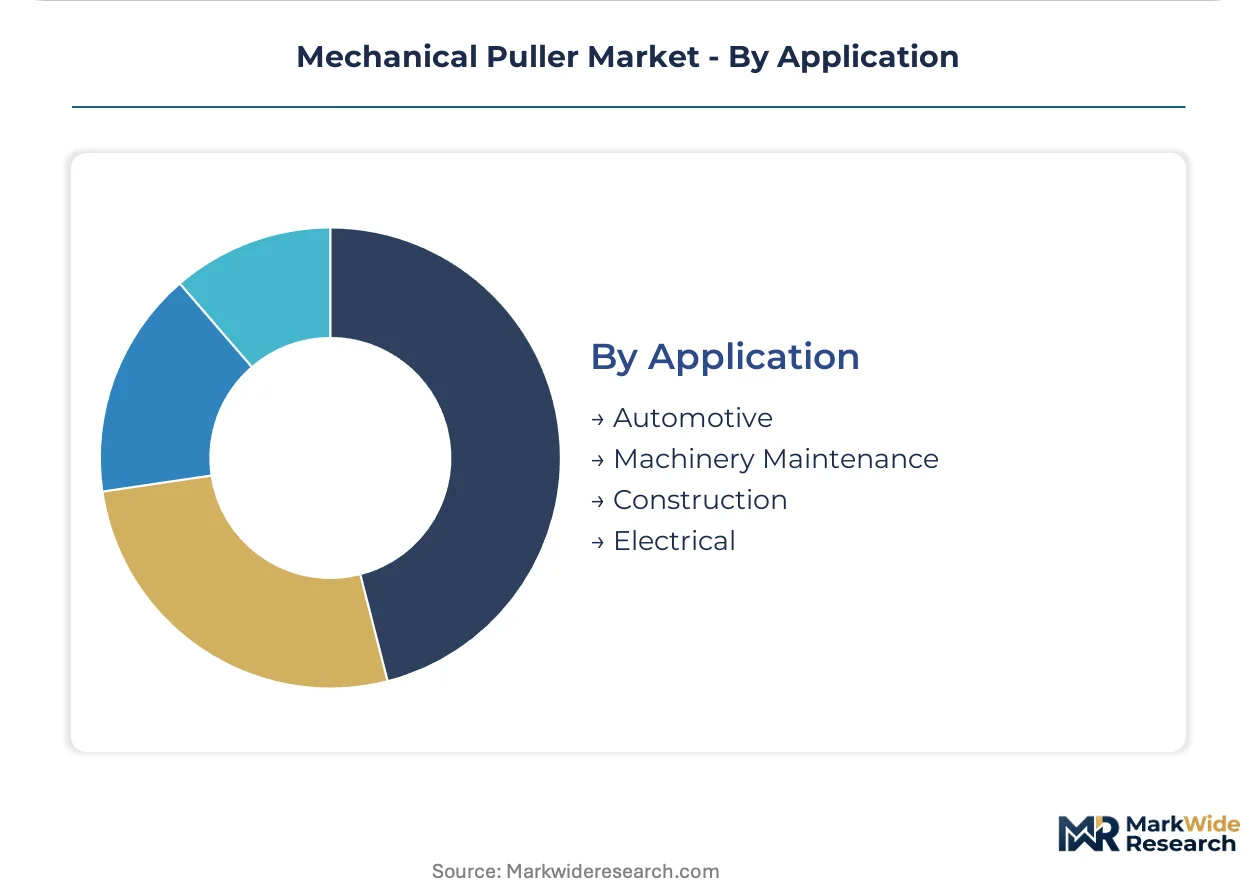
Application:
Customer type segmentation reveals divergent procurement behaviors between integrated maintenance departments and distributed field-service operations.
- Machinery Maintenance:This segment commands the largest installed-base replacement cycle through integrated tooling ecosystems rather than standalone puller purchases. Maintenance departments consolidate vendor relationships around bearing-service platform providers with calibration service attachments.
- Automotive:Aftermarket puller demand accelerates as electric vehicle powertrain redesigns alter bearing and gear service protocols. Automotive aftermarket chains in China's Pearl River Delta source from authorized distributor networks.
- Construction:Heavy equipment fleet maintenance generates periodic demand for large-capacity hydraulic systems through rental channel procurement.
- Electrical:Transformer and motor maintenance applications specify insulated or non-conductive puller variants for live-work safety compliance.
Machinery maintenance dominates installed base. Automotive is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German hydraulic component exports supply maintenance contractors across Denmark and Texas wind corridors, while Chinese manufacturing clusters feed automotive aftermarket demand through direct e-commerce channels.
United States
Rail axle extraction and wind turbine gearbox maintenance drive procurement of 50-ton-plus hydraulic systems. OSHA lockout/tagout enforcement mandates redundant mechanical locking, accelerating replacement cycles in 20-50 ton rental fleets. Houston and Dallas maintenance hubs specify smart pullers with embedded load cells for remote force verification.
Germany
Heavy machinery maintenance operations anchor European demand for fatigue-rated hydraulic pullers. EU Machinery Directive force-limitation requirements lock non-compliant suppliers out of transatlantic procurement channels. Stuttgart and Munich industrial corridors concentrate SKF-authorized distributor networks with calibration service attachments.
China
EV powertrain redesigns compress bearing service cycles and alter gear extraction protocols. Jiangsu and Zhejiang automotive aftermarket clusters generate concentrated demand as legacy internal combustion engine maintenance transitions. Shanghai and Guangzhou Pearl River Delta chains source through bearing-service platform providers.
India
Domestic automotive component manufacturing incentives attract puller distributors to establish localized assembly facilities. PLI scheme subsidies reduce import dependency for hydraulic system sourcing. Maharashtra and Gujarat industrial zones host emerging calibration and certification infrastructure.
Denmark
Offshore wind turbine maintenance contractors specify steel-bodied hydraulic pullers with Bluetooth telemetry for salt-spray environments. National renewable energy targets expand gearbox service contract volumes. Copenhagen and Esbjerg marine logistics hubs coordinate North Sea extraction operations.
Mechanical Puller Market Competitive Landscape
Listed leaders compete with private specialists across certification-tier positioning, creating a tiered structure where scale-driven manufacturers anchor premium segments and regional fabricators capture price-sensitive aftermarket volume. The vendor base separates into three strategic archetypes: integrated bearing-service platforms, high-force hydraulic tooling specialists, and diversified industrial tool conglomerates. Dominant competitive moves include backward integration into pump-and-cylinder manufacturing and geographic expansion through authorized distributor network establishment.
Within the integrated platform tier, SKF leverages its bearing-service ecosystem to anchor aftermarket puller sales, while Enerpac exemplifies high-force hydraulic tooling leadership through system integration capabilities. Timken occupies a position in North American rail and power-generation maintenance channels. Among diversified industrial tool conglomerates, Stanley Black & Decker and Apex Tool Group represent scale-driven portfolio breadth across manual, electric, and hydraulic force-generation architectures.
| Leading Market Players |
|---|
| SKF |
| Enerpac |
| Snap-on Incorporated |
| Timken |
| Schaeffler |
| Stanley Black & Decker |
| Techtronic Industries |
| Apex Tool Group |
| Atlas Copco |
| Others |
Value Network & Pricing Analysis
Long-term offtake contracts between German pump manufacturers and industrial maintenance contractors lock in chromium-molybdenum steel supply access while anchoring price visibility across 50-ton-plus hydraulic puller tiers. This contract structure insulates certified suppliers from spot-market alloy volatility while locking non-compliant competitors out of transatlantic procurement channels under EU Machinery Directive mandates.
Pricing Analysis
Technology-generation pricing gaps separate legacy screw-mechanical platforms from integrated hydraulic systems and emerging electromechanical alternatives. Three-tier pricing structure across premium certified, standard industrial, and economy portable levels reflects CE marking status and fatigue-rating certification. Pricing pressure stems from chromium-molybdenum steel cost swings compressing margin stability for fatigue-rated hydraulic puller bodies. Automotive aftermarket technicians demonstrate highest price sensitivity through e-commerce procurement of sub-10-ton manual units, while wind turbine maintenance contractors show lowest sensitivity due to project-based budgeting and warranty liability considerations.
Supply Chain Analysis
Inventory lead times for integrated pump-and-cylinder systems extend from German component manufacturers through qualified European suppliers, creating bottleneck exposure in hydraulic puller assembly. Manufacturing concentrates in Germany, China, and the United States, with German exports supplying Denmark and Texas wind corridors. Supply chains draw from chromium-molybdenum steel mills, precision pump foundries, and load-cell sensor manufacturers. Single-source vulnerability in German pump-and-cylinder manufacturing threatens system availability. Distribution runs through authorized industrial distributor networks with calibration service attachments for hydraulic tiers, while direct e-commerce channels serve portable manual and electric variants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating around integrated tooling ecosystems as automotive aftermarket chains and wind turbine maintenance contractors consolidate vendor relationships. This consolidation shifts negotiation leverage toward bearing-service platform providers with calibration service attachments.
For Market Incumbents: Compound certification advantage by accelerating CE marking and OSHA lockout/tagout compliance investments before third-party validation timelines extend product launch cycles. Deepen backward integration into pump-and-cylinder manufacturing to reduce German component supplier concentration risk. Defend against pneumatic puller substitution in clean-room battery assembly by embedding IoT load sensing for predictive maintenance contracts that unbundle hardware from recurring calibration revenue. For New Entrants and Emerging Players: Anchor in India's PLI scheme automotive component manufacturing zones to capture domestic production incentives and reduce import dependency for hydraulic system sourcing. Target composite-material corrosion-resistant puller bodies for chemical processing and offshore equipment salt-spray environments as the most penetrable white-space segment. Pursue carbon-fiber-reinforced platform development through partnership with Denmark and Texas wind turbine maintenance contractors seeking Bluetooth telemetry integration. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated bearing-service platform providers with calibration service attachments across European and North American industrial corridors. Long-term viability over the projection horizon favors acquirers of certified load-rated design portfolios with established distributor networks. Signal to monitor: EV powertrain redesign pace compressing bearing service cycles and forcing capacity rating recalibrations for lighter, higher-RPM drivetrain components.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pump Manufacturing | Captive supply of precision cylinders reduces German supplier concentration risk for hydraulic system assemblers. |
| CE Marking and OSHA Certification Investment | Compliance with EU Machinery Directive force-limitation mandates locks out non-certified competitors from transatlantic procurement. |
| IoT Load Sensing Platform Development | Real-time force monitoring enables predictive maintenance contracts separating hardware from recurring calibration revenue streams. |
| Composite-Material Puller Body Launch | Carbon-fiber-reinforced platforms target corrosion-critical chemical processing and offshore salt-spray environments. |
| Authorized Distributor Network Expansion | Calibration service attachments in China's Pearl River Delta and German industrial corridors consolidate buyer relationships. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of trade customs data, SEC filings from industrial tool conglomerates, and EU Machinery Directive compliance registries. Maintenance directors at wind turbine operators, plant engineers at automotive aftermarket chains, OEM procurement teams at bearing manufacturers, and aftermarket service heads at hydraulic tooling distributors provided structured input. Secondary validation drew from OSHA enforcement databases, CE marking registries, and chromium-molybdenum steel price indices. Bottom-up puller shipment estimates triangulated against top-down industrial maintenance spending allocations.
Segmentation dimensions modeled span force-generation architecture, capacity rating tier, material composition, and application vertical across the analysis window. Analytical framework projected replacement-cycle timing for machinery maintenance installed bases, EV powertrain redesign impacts on bearing service protocols, and regulatory compliance transition costs. CAGRs derived from weighted average of segment growth trajectories incorporating alloy input cost elasticity and certification adoption curves. Industry-specific inputs included wind turbine gearbox extraction contract volumes and automotive aftermarket cluster expansion rates in China's eastern manufacturing provinces.
Material uncertainties — chromium-molybdenum steel price volatility, third-party OSHA validation timeline extensions, and pneumatic puller technical breakthroughs in force consistency — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding EU Machinery Directive enforcement intensity and EV production scaling trajectories. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Floor Scraper Market
Tools
Pneumatic Tools Market
Tools
Industrial Floor Scrubber Market
Tools
Digital Levels Market
Tools
Ultra Hard Material Cutting Machines Market
Tools
Rivet Gun Market
Tools
Bottle Jack Market
Tools
Mold Racks Market
Tools
Rocket Wrench Market
Tools
Indexable Tool Inserts Market
Tools
End Milling Machine Market
Tools
Cutting Equipment Market
Tools
Diamond Hole Saw Market
Tools
Cutting Tool Inserts Market
Tools
Europe Power Tools Market
Tools
Tool Storage Market