

Orbital Recip Saw Market Size, Share, and Industry Trends Forecast 2026-2036
Orbital Recip Saw Market Insights
China is narrowing its orbital recip saw supply gap through expanded brushless motor manufacturing clusters in Jiangsu and Zhejiang provinces. Milwaukee Tool leverages vertical integration in battery cell sourcing to sustain North American distribution dominance. Bosch competes through precision engineering heritage in vibration reduction systems, while Makita anchors Asia-Pacific channel density with contractor-direct service networks.
An orbital recip saw combines reciprocating blade motion with an elliptical orbital path to accelerate material removal in demolition and rough-cutting tasks. The tool typically operates at 0 to 3,000 strokes per minute with orbital settings that adjust aggressiveness based on material density. Cordless configurations now dominate contractor preference as lithium-ion platforms extend runtime for metal cutting and construction demolition applications. Brushless motor technology captures expanding margin pools by reducing heat generation and extending tool longevity under sustained load conditions. Battery operated systems represent the fastest-growing product category as equipment rental fleets and handyman services prioritize mobility over tethered power.
OSHA vibration exposure limits and EPA battery disposal regulations shape product design requirements for manufacturers serving the United States market. CE marking under the EU Machinery Directive and REACH substance restrictions govern European market access and material composition standards. Stakeholders must monitor regulatory divergence between battery safety certification regimes and decide whether to maintain region-specific product variants or pursue unified global platform architectures.
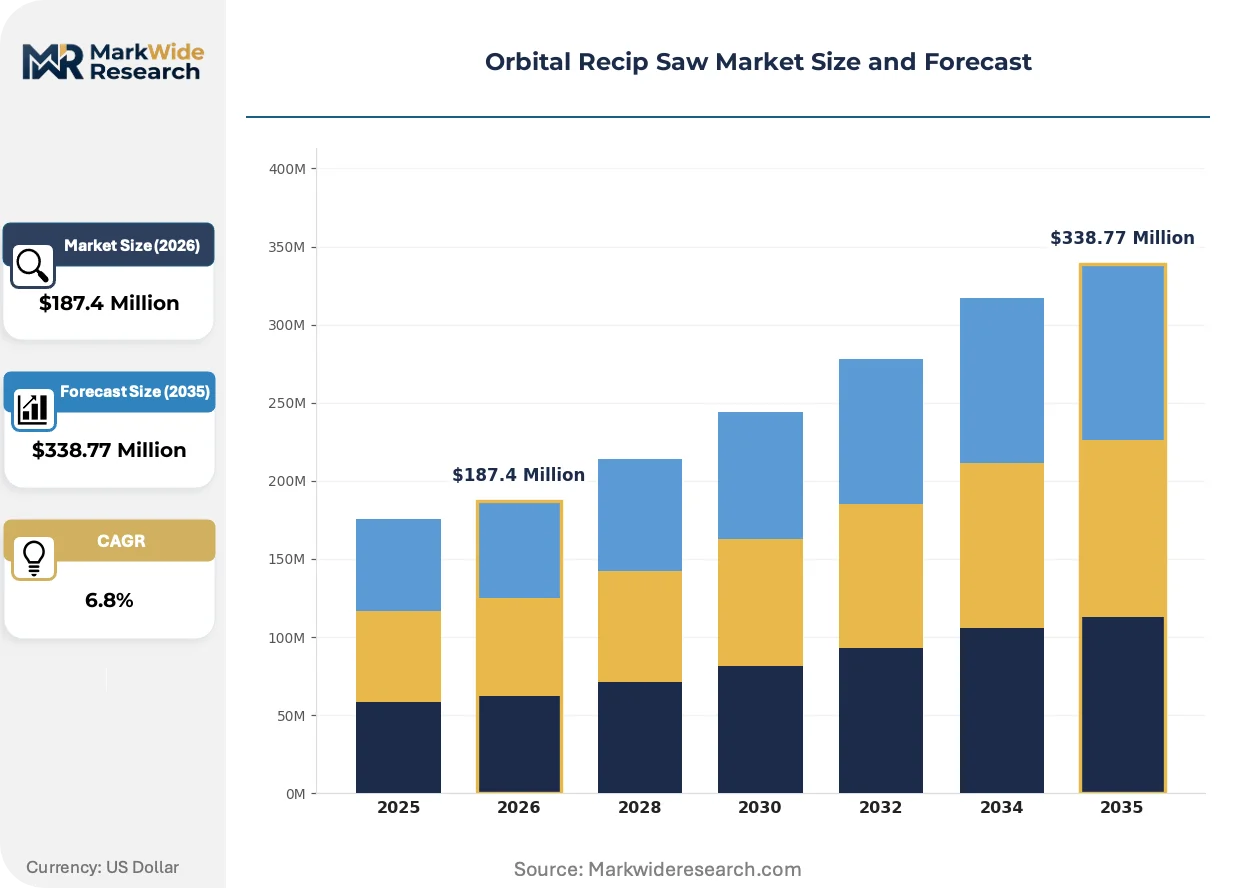
Market Dynamics
Brushless motor electrification is compressing the performance gap between cordless and corded orbital recip saws, forcing manufacturers to reconfigure R&D priorities around battery thermal management and vibration control systems.
Growth Catalysts
- OSHA vibration exposure limits:Manufacturers are engineering enhanced dampening systems to comply with United States workplace safety mandates, creating specification upgrades across contractor-grade product lines.
- Brushless motor technology:Reduced heat generation and extended duty cycles are expanding cordless platform viability for sustained metal cutting in demolition workflows.
- Jiangsu and Zhejiang manufacturing clusters:Expanded brushless motor production capacity in these Chinese provinces is narrowing supply constraints for high-torque drive systems.
Market Restraints
- Lithium-ion cell cost volatility:Raw material price fluctuations for cobalt and nickel concentrate input cost risk in battery pack manufacturing.
- REACH substance restrictions:European material composition standards limit certain polymers and coatings, complicating multi-region product platform strategies.
- Stationary band saw substitution:Metal fabrication shops with fixed infrastructure sometimes prefer dedicated cutting equipment for precision work over portable demolition tools.
Strategic Opportunities
- Equipment rental fleet electrification:North American rental channels are expanding cordless inventory ratios, opening volume contracts for battery platform ecosystems.
- EU Green Deal procurement incentives:Public infrastructure tenders increasingly favor battery-powered equipment, creating specification advantages for cordless configurations in European demolition contracts.
- AI-enabled predictive maintenance:Integration of motor sensors with fleet management software allows rental operators to optimize tool rotation and reduce downtime.
Industry Challenges
- Battery safety certification timelines:Divergent UN 38.3, IEC 62133, and UL 2580 testing requirements across jurisdictions delay product launches.
- Cross-platform battery incompatibility:Proprietary cell formats lock contractors into single-brand ecosystems, complicating fleet standardization decisions for multi-trade general contractors.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Orbital Recip Saw Market Trends and Innovations
Electrification architectures and intelligent tool connectivity are redefining how contractors specify demolition equipment, with performance metrics shifting from raw power output to runtime consistency and fleet integration capabilities.
Smart battery management systems with real-time thermal monitoring and adaptive discharge algorithms are collapsing the runtime penalty that previously constrained cordless tools in heavy-gauge metal cutting. Demolition contractors in the United States are adopting these platforms for steel framing removal and HVAC ductwork dismantling. The technology is collapsing the historical trade-off between portability and sustained cutting performance that structured product category boundaries.
EPA battery disposal regulations under the Resource Conservation and Recovery Act are mandating closed-loop recycling participation for power tool manufacturers serving the United States market. Compliance requires establishing certified collection networks and material recovery partnerships. The regulation most affects high-volume cordless product lines, pushing manufacturers toward modular battery designs that simplify cell replacement and extend pack service life.
Contractor procurement patterns are consolidating around battery platform loyalty rather than tool-by-tool selection, with fleet managers prioritizing interoperable charging infrastructure and shared cell inventories. This behavior is displacing single-tool purchasing at independent hardware distributors. The shift is most visible among United States residential renovation contractors managing mixed-trade crews with overlapping equipment needs.
Orbital Recip Saw Market Segmentation
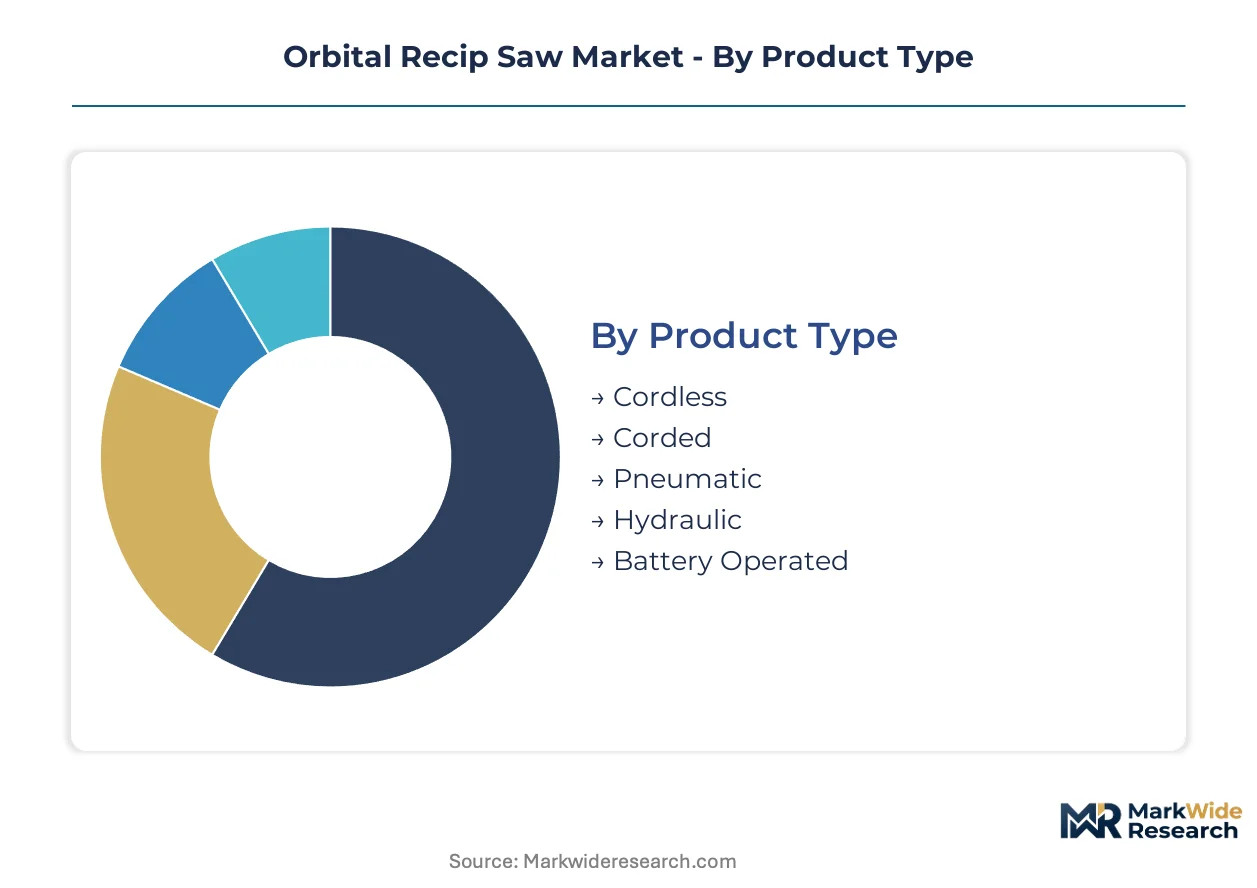
Orbital recip saw procurement patterns diverge sharply across use-case intensity, power source mobility, and operator skill levels. Contractors prioritize runtime consistency and battery platform compatibility, while rental fleets optimize for durability under multi-user abuse. Segmentation reveals where margin pools concentrate versus where volume commoditizes.
Product Type:
Contractor workflows span from light residential trim removal to continuous steel demolition, creating distinct power source requirements across the use-case spectrum.
- Cordless:Lithium-ion platforms with 18V to 54V architectures dominate residential renovation and commercial demolition where tethered power proves impractical. Demand concentrates among United States electrical contractors and HVAC technicians performing overhead ductwork dismantling, with OSHA vibration exposure limits pushing specification upgrades toward brushless motor variants.
- Battery Operated:This designation captures emerging solid-state and high-nickel cell configurations that extend runtime for sustained metal cutting. German construction firms are adopting these systems for steel framing removal under EU Green Deal procurement incentives that favor cordless equipment in public infrastructure tenders.
- Corded:Continuous AC power suits stationary fabrication shops and heavy-gauge metal cutting where runtime certainty outweighs mobility needs.
- Pneumatic:Compressed air systems persist in automotive collision repair and industrial maintenance settings with existing shop air infrastructure.
- Hydraulic:High-torque drive systems serve underwater demolition and explosive atmosphere environments where electrical ignition risks prohibit battery or corded alternatives.
Established volume favors corded systems in fixed fabrication environments; emerging adoption favors battery operated configurations in mobile demolition workflows.
Technology:
Performance differentiation now hinges on thermal management precision and operator fatigue reduction rather than raw stroke rate specifications.
- Brushless Motor:Electronic commutation eliminates brush friction losses, collapsing heat generation under sustained load. Jiangsu and Zhejiang manufacturing clusters in China are expanding production capacity for these high-torque drive systems, narrowing supply constraints for contractor-grade cordless platforms.
- Vibration Reduction:Counterbalance mechanisms and isolated handles address OSHA exposure limits for United States demolition contractors performing extended steel cutting operations.
- Variable Speed Control:Dial-based or trigger-responsive stroke rate adjustment allows material-specific optimization from 0 to 3,000 strokes per minute.
- Electronic Clutch:Torque-limiting disengagement protects gear trains from bind-up damage in nail-embedded wood or frozen fastener scenarios.
- LED Indicator:Battery state-of-charge and fault code displays reduce unexpected downtime in rental fleet rotations.
Brushless motor systems command premium positioning; vibration reduction features are becoming table stakes for contractor-grade specification.
Application:
Material density and cut precision requirements segment demand across rough demolition versus finish-oriented trades.
- Construction Demolition:Aggressive orbital action with extended blades accelerates structural teardown, drywall removal, and embedded fastener cutting. United States residential renovation contractors are consolidating procurement around battery platform ecosystems for mixed-trade crews with overlapping equipment needs.
- Metal Cutting:Thin-wall conduit, steel framing, and HVAC ductwork demand consistent power delivery without thermal shutdown. Smart battery management with real-time thermal monitoring is collapsing the runtime penalty that previously constrained cordless tools in heavy-gauge applications.
- Woodworking:Finish carpenters and trim crews prioritize orbital settings that minimize splintering in delicate material.
- Plumbing:Cast iron pipe cutting and copper tube notching require blade configurations optimized for ferrous and non-ferrous alloys.
- Electrical Installation:Recessed lighting retrofits and panel upgrades demand compact blade profiles for confined space access.
Construction demolition anchors current volume concentration; metal cutting applications are climbing the fastest as battery thermal management improves.
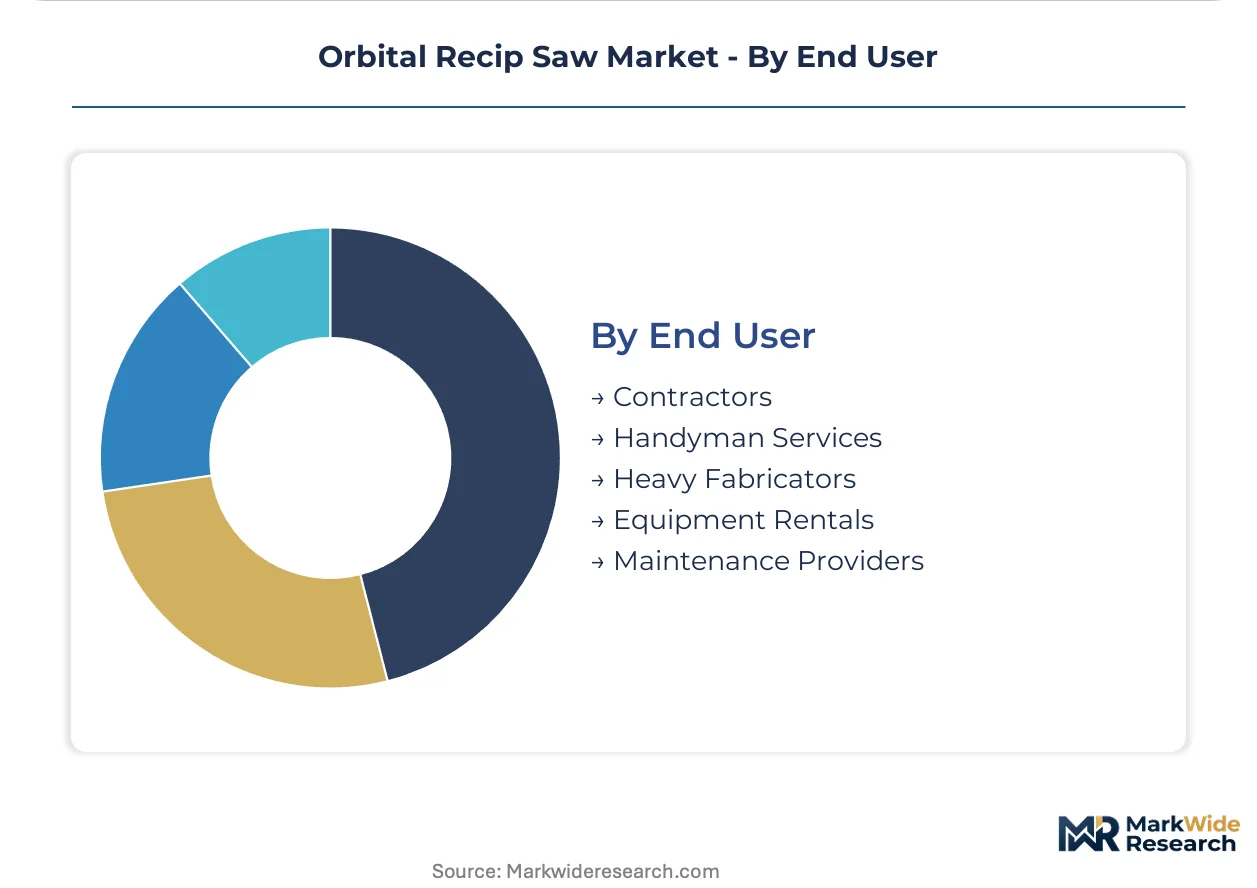
End User:
Purchase authority and utilization intensity create distinct channel and pricing dynamics across customer types.
- Contractors:General and trade-specific builders specify tool-by-tool for owned fleets, with procurement consolidating around battery platform loyalty rather than individual tool selection. Cross-platform battery incompatibility locks these users into single-brand ecosystems, complicating fleet standardization for multi-trade operations.
- Equipment Rentals:North American rental channels are expanding cordless inventory ratios, opening volume contracts for battery platform ecosystems. AI-enabled predictive maintenance through motor sensors allows rental operators to optimize tool rotation and reduce downtime.
- Handyman Services:Solo operators and small crews prioritize single-battery versatility across multiple tool categories.
- Heavy Fabricators:Metal shops with fixed infrastructure sometimes prefer stationary band saws for precision work over portable demolition tools.
- Maintenance Providers:Facility and industrial maintenance departments balance emergency response mobility with capital budget constraints.
Equipment rentals are gaining share fastest through fleet electrification; contractors remain the margin anchor through platform ecosystem lock-in.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Contractors in the United States deploy orbital recip saws primarily for overhead demolition and confined-space metal cutting, while German fabricators emphasize vibration-controlled precision for steel framing removal. Chinese adoption concentrates in high-volume residential teardowns where brushless motor platforms dominate procurement decisions.
United States
Electrical contractors and HVAC technicians drive cordless platform demand for overhead ductwork dismantling and recessed lighting retrofits. OSHA vibration exposure limits mandate enhanced dampening systems on contractor-grade equipment. Equipment rental fleets in Texas and Florida are expanding cordless inventory ratios through volume battery platform contracts.
Germany
Construction firms prioritize brushless motor systems for steel framing removal under EU Green Deal procurement incentives favoring battery-powered equipment. REACH substance restrictions govern polymer and coating compositions for multi-region product platforms. Manufacturing clusters in Baden-Württemberg and North Rhine-Westphalia concentrate precision engineering capabilities for vibration reduction systems.
China
Residential renovation contractors adopt high-torque cordless platforms for aggressive structural teardown and drywall removal workflows. Dual carbon goals under MIIT guidance accelerate battery platform electrification in public infrastructure tenders. Brushless motor manufacturing clusters in Jiangsu and Zhejiang provinces are narrowing supply constraints for contractor-grade drive systems.
Japan
Maintenance providers and facility departments balance emergency response mobility with capital budget constraints in mixed-trade operations. METI industrial standards shape battery safety certification requirements for domestic market access. Tokyo-Osaka corridor distributors emphasize contractor-direct service networks for fleet standardization support.
Australia
Handyman services and solo operators prioritize single-battery versatility across multiple tool categories in residential renovation markets. ISO battery safety standards align with IEC 62133 testing requirements for cordless equipment import compliance. New South Wales and Victoria equipment rental channels are adopting predictive maintenance systems for fleet rotation optimization.
Orbital Recip Saw Market Competitive Landscape
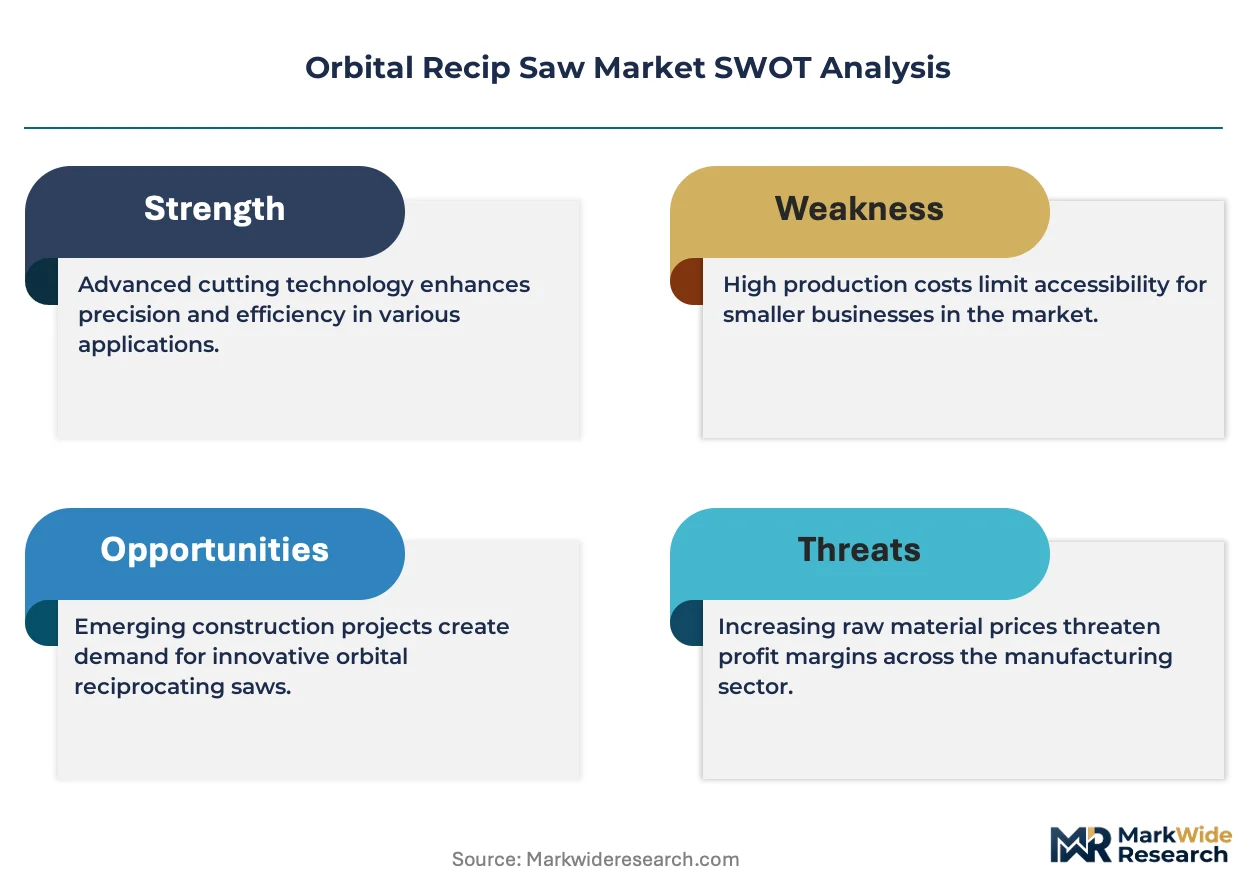
Capability concentration sits with precision engineering specialists; scale advantage sits with battery platform ecosystem architects. The vendor base separates into three functional tiers: premium-tier brushless motor innovators, mid-market battery platform consolidators, and value-tier commodity assemblers. Dominant competitive moves include captive supply chain control over lithium-ion cell sourcing and strategic partnerships with equipment rental channels for fleet electrification contracts.
Within the premium-tier engineering segment, Milwaukee Tool and Bosch exemplify divergent strategic archetypes. Milwaukee Tool anchors North American distribution dominance through backward integration into battery cell sourcing and vertical control over platform ecosystem development. Bosch occupies a position emphasizing precision heritage in vibration reduction and dampening system engineering. Makita represents the Asia-Pacific channel density archetype, with contractor-direct service networks spanning distribution infrastructure across multiple regional markets.
| Leading Market Players |
|---|
| Milwaukee Tool |
| DeWalt |
| Bosch |
| Makita |
| Ryobi |
| Metabo |
| SKIL |
| RIDGID |
| Black+Decker |
| Others |
Pricing and Supply Chain Analysis
Lithium-ion cell cost volatility in cobalt and nickel markets compresses margin pools across battery pack manufacturing tiers, forcing manufacturers to stratify pricing across premium brushless motor systems, mid-market platform consolidators, and value-tier commodity configurations while reshaping sourcing footprints toward captive cell supply and regional assembly hedges.
Pricing Analysis
United States contractor-grade orbital recip saws command 25-40% premiums over equivalent European SKUs due to OSHA-mandated vibration dampening systems and extended warranty bundling. Pricing stratifies across premium, standard, and economy tiers based on brushless motor certification grade and battery platform interoperability depth. Cost compression in the economy tier is intensifying because Chinese Jiangsu and Zhejiang manufacturing clusters are flooding mid-market channels with unbranded brushless motor assemblies. Equipment rental fleets demonstrate lowest price sensitivity due to fleet-scale volume contracts and total-cost-of-ownership modeling, while solo handyman services exhibit acute sensitivity to initial acquisition thresholds.
Supply Chain Analysis
Brushless motor stator laminations and rare-earth magnet assemblies draw from concentrated manufacturing footprints in China, Japan, and Germany, with Jiangsu province alone accounting for substantial global high-torque drive system capacity. Battery cell chemistry feeds from South Korean and Japanese cathode material suppliers tethered to Australian and Chilean lithium carbonate extraction. Single-source vulnerability concentrates in NdFeB permanent magnet supply, where Chinese export license regimes create regulatory chokepoint exposure for non-domestic assemblers. Distribution runs through North American equipment rental channels, German construction supply cooperatives, and Chinese provincial distributor networks serving residential renovation contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is consolidating around battery platform ecosystems, with multi-trade general contractors and equipment rental fleets leveraging fleet-scale procurement to extract interoperability guarantees and extended service terms from manufacturers.
For Market Incumbents: Harden captive supply positions in lithium-ion cell sourcing through backward integration or long-term offtake agreements with South Korean and Japanese cathode suppliers, insulating margin pools from raw material volatility. Accelerate certification investment in UN 38.3 and UL 2580 battery safety testing to compress launch timelines against regulatory divergence threats. Deepen channel control through exclusive fleet electrification contracts with North American rental operators, locking out competitor platform penetration. For New Entrants and Emerging Players: Build out white-space positions in solid-state battery configurations for sustained metal cutting applications, where thermal management performance gaps persist among established cordless platforms. Target Australian handyman services and solo operators through single-battery versatility positioning, exploiting lower brand loyalty and price sensitivity in residential renovation segments. Pursue contractor-direct service network partnerships in Japanese maintenance provider channels, leveraging METI compliance consulting as a differentiated go-to-market anchor. For Investors and Strategic Acquirers: The market sits at a platform consolidation phase that favors battery ecosystem architects with captive cell supply and rental channel density over precision engineering specialists without platform scale. Long-term viability hinges on 5-10 year electrification tailwinds in construction demolition and infrastructure refurbishment across United States, German, and Chinese building stock. Acquisition targets should emphasize brushless motor manufacturing clusters with regional regulatory certification depth. The signal to watch is rental fleet cordless inventory ratio inflection, which indicates platform lock-in velocity and ecosystem switching cost accumulation.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Platform Ecosystem Expansion | Captive cell supply from South Korean partners secures runtime consistency advantages for United States rental fleet contracts. |
| Brushless Motor Manufacturing Scale-Up | Jiangsu and Zhejiang production cluster expansion narrows supply constraints for high-torque drive systems serving Chinese demolition contractors. |
| Regulatory Certification Pre-Positioning | UN 38.3 and UL 2580 testing completion accelerates United States market access ahead of competitor launch timelines. |
| Predictive Maintenance Integration | AI-enabled motor sensor deployment optimizes rental fleet rotation and reduces downtime for North American equipment rental operators. |
| Closed-Loop Recycling Partnership | EPA RCRA-compliant collection networks extend battery pack service life and satisfy United States disposal mandates for cordless product lines. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with demolition contractors, equipment rental fleet managers, brushless motor manufacturing engineers, and power tool distribution channel heads; and secondary validation against customs trade records, OSHA enforcement databases, SEC equipment manufacturer filings, and EU Machinery Directive compliance registries. Bottom-up triangulation across product-level bill-of-materials costing and top-down reconciliation against regional construction expenditure data anchored volume and value estimates.
Forecast inputs considered power source migration patterns, battery energy density improvement trajectories, and regulatory compliance cost evolution across the projection horizon. Segmentation dimensions modeled include product type mobility tier, motor technology sophistication, application material density, and end-user procurement authority. CAGRs were derived from slope-intercept fitting of historical adoption curves against infrastructure refurbishment cycle timing. Industry-specific forecast inputs incorporated lithium-ion cell cost volatility indices and OSHA vibration exposure limit enforcement intensity.
Stress conditions across cobalt-nickel price bands, battery safety certification timeline delays, and rental fleet electrification adoption rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding brushless motor manufacturing capacity expansion and EU Green Deal procurement incentive persistence. Quarterly review of rental channel cordless inventory ratios and Chinese export license regime adjustments is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.