
 Woodcarving Tool Market | 2026-2036
Woodcarving Tool Market Size, Share, and Industry Trends Forecast 2026-2036
Woodcarving Tool Market Analytics
Specialty woodworking retailers is reshaping how premium carving tools reach end users, bypassing generalist hardware chains for dedicated craft channels. Flexcut leverages direct-to-consumer education bundles to sustain brand loyalty among hobbyists. Pfeil Tools anchors European distribution through dedicated craft-school partnerships in Switzerland and Germany. BeaverCraft competes aggressively on price-point accessibility for entry-level knife sets.
Woodcarving tools encompass hand-operated and powered instruments designed to remove, shape, and detail wood substrates through controlled cutting action, typically employing high-carbon or alloy steel edges hardened to 58-62 HRC for edge retention. These instruments serve artistic production, functional furniture component fabrication, and educational craft instruction across amateur and professional settings. Chisels and gouges occupy the mature core of product demand, sustaining stable replacement cycles among professional workshops. Power tools represent the fastest-expanding category as cordless rotary systems penetrate hobbyist segments previously served only by hand tools. Knives command concentrated margin pools in premium artisan-grade offerings where metallurgy and ergonomic handle design differentiate positioning.
EPA guidelines in the United States govern volatile organic compound emissions from factory-applied tool finishes, while REACH in Europe restricts hazardous substances in handle coatings and metal treatments. ISO 9001 certification shapes supplier qualification for institutional procurement channels including schools and government-funded craft programs. Stakeholders must monitor evolving material compliance thresholds that will determine market access for Asian-manufactured imports into Western regulatory jurisdictions.
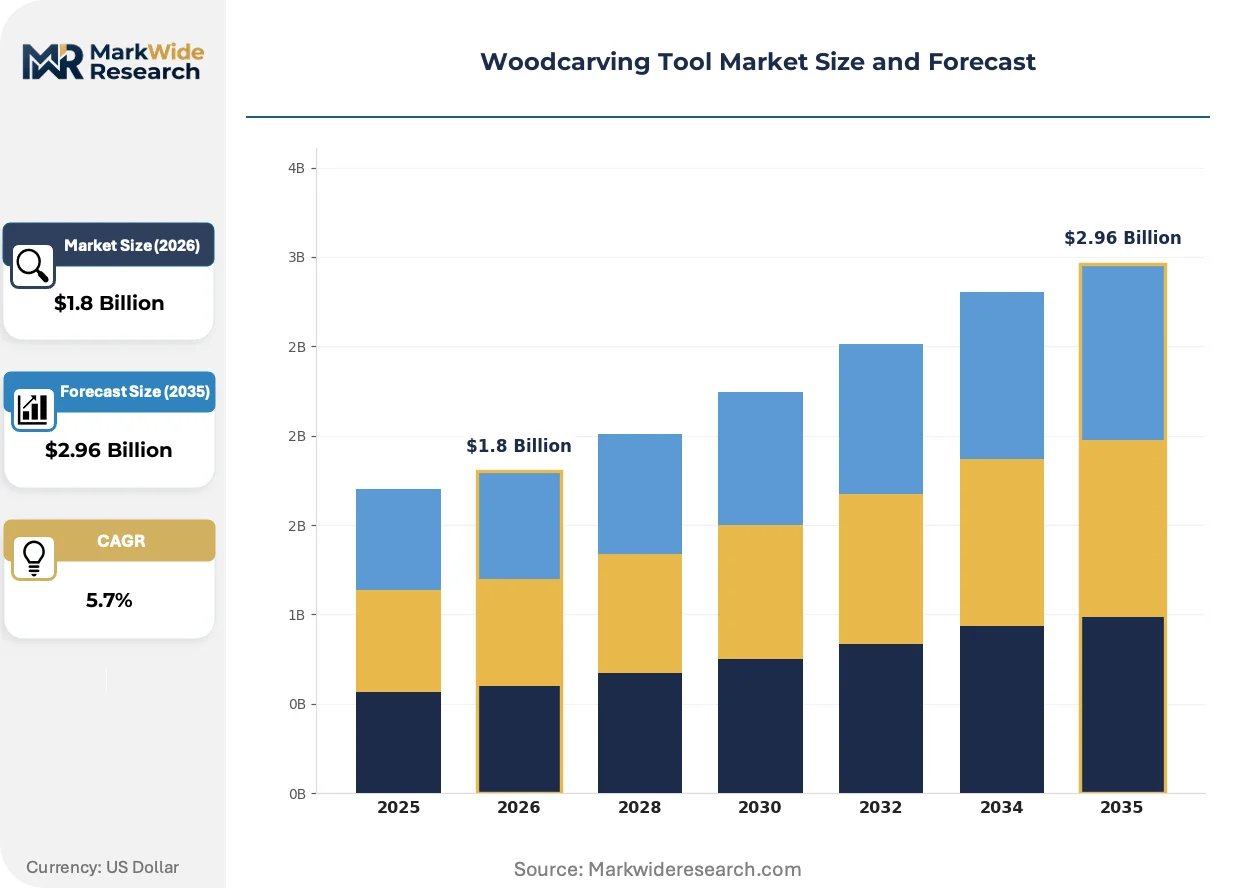
Market Dynamics
REACH compliance in Europe is virtualizing material selection across the woodcarving tool supply chain, forcing manufacturers to abandon solvent-based handle coatings and chromium-plated finishes in favor of bio-based alternatives and powder-coated surfaces.
Growth Catalysts
- REACH substance restrictions:European manufacturers accelerate reformulation of handle coatings and metal treatments to maintain market access, creating pull for compliant material suppliers.
- Social platform hobbyist communities:Amateur carvers on Instagram and YouTube drive tool purchases through viral project tutorials and unboxing content.
- Germany's Black Forest craft schools:Traditional woodworking academies sustain premium hand-tool demand through institutional procurement cycles.
Market Restraints
- High-carbon steel price volatility:Input cost swings for blade alloys compress margin stability for mid-tier manufacturers.
- Asian import concentration:Western markets depend heavily on Chinese and Indian forging capacity for entry-level tool sets.
- Manual skill dependency:Hand-tool proficiency requirements limit addressable market expansion among time-constrained hobbyists.
Strategic Opportunities
- EU Green Deal procurement incentives:Public craft education programs increasingly favor tools with certified sustainable supply chains.
- Cordless rotary system convergence:Battery-powered micro-carving tools open penetration into apartment-dwelling urban hobbyists previously excluded by noise and space constraints.
- Direct-to-consumer education bundles:Brands bypass retail markup by pairing tool kits with streaming tutorial subscriptions.
Industry Challenges
- ISO 9001 certification timelines:Institutional procurement channels demand documented quality systems that smaller forges struggle to implement.
- Master craftsperson recruitment:European and North American manufacturers face acute shortages of trained grinders and heat-treatment specialists.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Woodcarving Tool Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Tool Type: Chisels, Gouges, Knives, Power Tools Material: Wood, Metal, Plastic, Composite Application: Artistic, Decoration, Furniture Making, Educational End User: Professional Carvers, Hobbyists, Schools, Workshops |
| Companies Covered | Flexcut, Pfeil Tools, BeaverCraft, Two Cherries, Henry Taylor, Narex, Helvie, Kirschen, Frosts, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Woodcarving Tool Market Evolving Landscape
Digital fabrication workflows are compressing traditional hand-tool training periods while regulatory pressure on material chemistry accelerates product redesign cycles across premium and mass-market tiers.
Carbide-insert micro-tools are virtualizing the economics of precision detail work. Professional furniture carvers and instrument makers adopt indexable carbide tips for consistent edge geometry without frequent sharpening. This technology is virtualizing the traditional division between hand-forged premium tools and disposable entry-level sets, enabling mid-market brands to offer professional-grade cutting performance at accessible price points.
EPA volatile organic compound guidelines now govern factory-applied finishes on tools sold into the United States, mirroring European REACH restrictions on hazardous substances. Manufacturers serving both jurisdictions consolidate coating formulations to single compliant platforms, raising compliance costs for small-batch artisans while advantaging larger producers with in-house finishing lines. The institutional procurement segment responds fastest, with schools and government-funded programs demanding documented emissions compliance before purchase authorization.
Streaming tutorial subscriptions now bundle with physical tool purchases, displacing traditional retail discovery. Hobbyist buyers in North America and Western Europe encounter carving knife sets through YouTube-sponsored content and Patreon-exclusive project series rather than brick-and-mortar specialty stores. This channel compression most visibly affects Germany and Switzerland, where dedicated craft retailers historically anchored brand loyalty through in-person demonstration and sharpening instruction.
Woodcarving Tool Market Segmentation
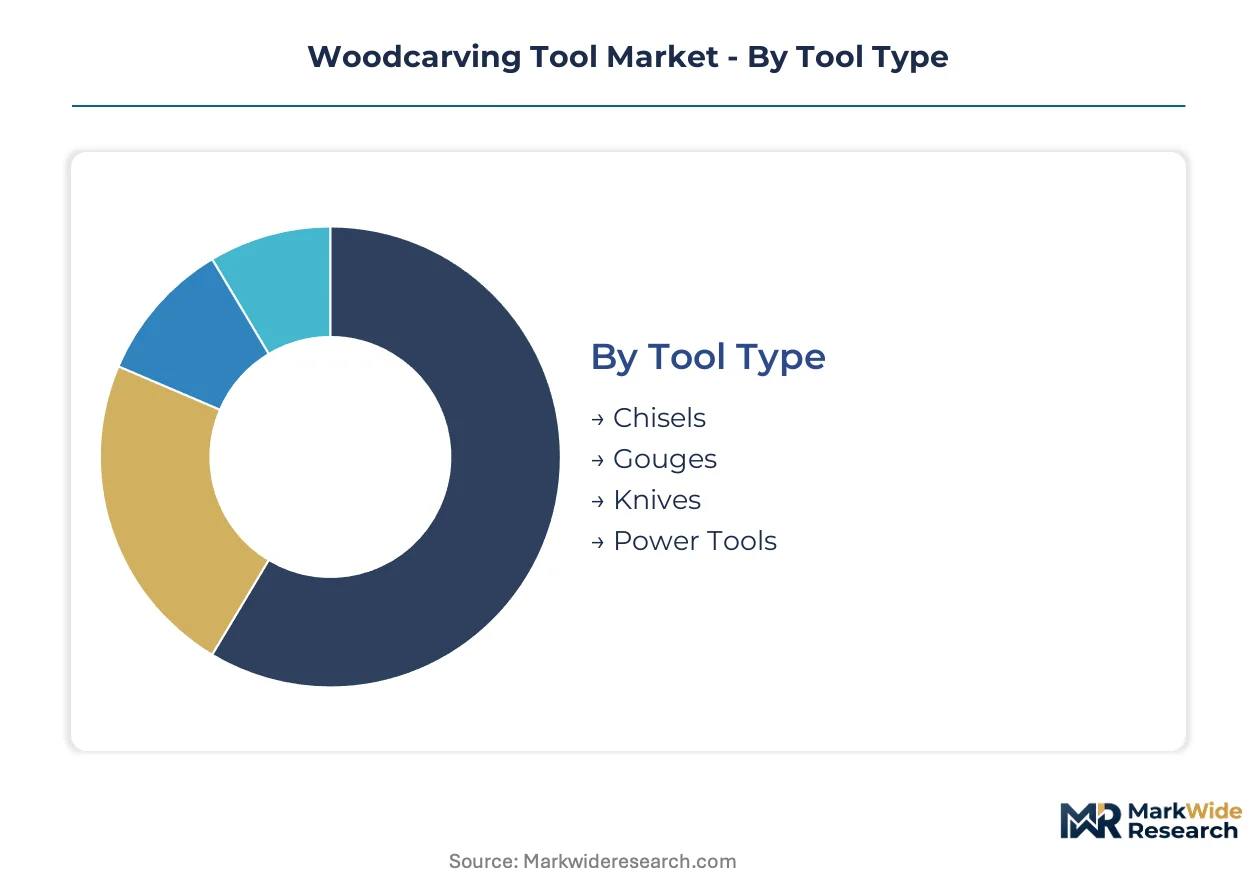
Woodcarving tool manufacturers calibrate warranty terms and sharpening service networks differently across segment boundaries, with professional-grade chisels demanding multi-year maintenance commitments while entry-level knives ship without post-purchase support. This service intensity gradient shapes pricing architecture and channel selection throughout the value chain.
Tool Type:
After-sales obligations diverge sharply across tool categories, with powered instruments requiring authorized repair networks and hand tools leaning on user-serviceable edge geometry.
- Chisels:These straight-edged cutting instruments with beveled blades excel at paring and mortising operations in hardwood substrates. Germany's Black Forest craft schools sustain institutional procurement cycles for premium socket-handle variants with laminated steel construction.
- Gouges:Curved cutting profiles ranging from shallow sweeps to deep U-shapes enable hollow forms and decorative fluting. Professional furniture component fabricators in Switzerland concentrate demand for fishtail and back-bent geometries that access tight internal corners.
- Knives:Compact fixed-blade instruments dominate portable carving and detail work where tool rolls must minimize weight. Flexcut and BeaverCraft compete aggressively on ergonomic handle contours and blade steel formulations for hobbyist segments.
- Power Tools:Cordless rotary systems and micro-grinders penetrate apartment-dwelling urban hobbyists previously excluded by noise constraints. Battery platform compatibility now shapes repurchase decisions more than brand loyalty.
By volume, knives lead. By growth pace, power tools are ahead.
Material:
Cost tier stratification follows raw material selection, with exotic hardwoods and stabilized burls commanding artisan-grade premiums while injection-molded composites anchor mass-market accessibility.
- Wood:Traditional handle materials span beech, ash, and exotic hardwoods selected for shock absorption and dimensional stability. REACH substance restrictions in Europe accelerate migration toward sustainably certified timber sources with documented chain-of-custody documentation.
- Metal:Full-tang steel construction and brass ferrules characterize professional-grade instruments where balance and durability outweigh weight considerations. Pfeil Tools anchors European distribution through metal-handled variants engineered for institutional workshop environments.
- Plastic:Glass-reinforced nylon and ABS polymers enable dishwasher-safe maintenance and chemical resistance for educational settings. Price-point accessibility drives penetration among first-time hobbyists purchasing through direct-to-consumer channels.
- Composite:Stabilized wood-resin hybrids and carbon-fiber reinforced handles merge traditional aesthetics with modern durability specifications. This segment climbs fastest as manufacturers seek differentiation in crowded mid-market tiers.
Wood dominates unit shipments. Composite formulations gain share fastest on performance-per-dollar metrics.
Application:
Customer type determines margin structure, with artistic production tolerating premium pricing for metallurgical refinement while educational procurement demands volume discounts and institutional warranty terms.
- Artistic:Gallery-oriented sculptors and commissioned artisans prioritize edge-holding alloys and ergonomic balance for extended carving sessions. Japan's traditional craft preservation programs sustain demand for specialized profiles unavailable in Western catalogs.
- Decoration:Architectural ornament and holiday craft production favor standardized profiles that accelerate output without custom grinding. China's export-oriented workshops concentrate volume demand for mid-sweep gouges and V-tools.
- Furniture Making:Component fabricators serving high-end residential and hospitality sectors require consistent edge geometry across replacement cycles. ISO 9001 certification shapes supplier qualification for these procurement channels.
- Educational:Public craft programs and private academies mandate safety-rounded corners and bulk packaging configurations. EU Green Deal procurement incentives increasingly favor tools with certified sustainable supply chains.
Furniture making generates the largest revenue pool. Educational applications expand most quickly on public funding restoration.
End User:
Volume concentration varies by user sophistication, with professional workshops consolidating purchases through specialized distributors while hobbyists fragment across direct-to-consumer and marketplace channels.
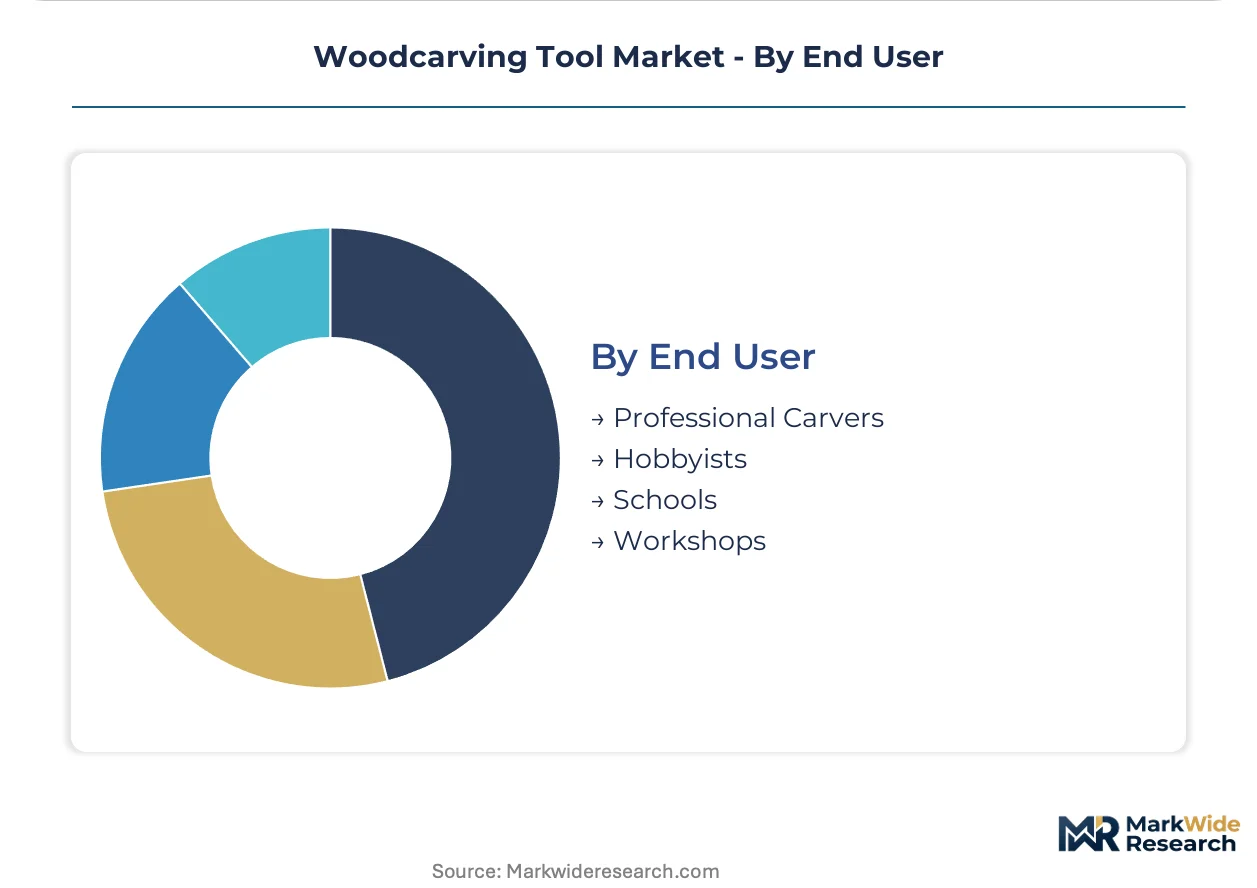
- Professional Carvers:Full-time artisans and restoration specialists maintain extensive tool inventories with dedicated sharpening stations and custom profile grinding capabilities. Master craftsperson recruitment shortages constrain European and North American manufacturer capacity expansion.
- Hobbyists:Amateur practitioners discover tools through Instagram tutorials and YouTube unboxing content rather than brick-and-mortar discovery. Streaming tutorial subscriptions now bundle with physical purchases, displacing traditional retail relationships.
- Schools:Secondary and post-secondary craft programs demand documented emissions compliance and safety certifications before purchase authorization. Institutional procurement cycles sustain predictable replacement demand for chisel and gouge sets.
- Workshops:Community maker spaces and corporate team-building facilities balance durability concerns with theft-resistant communal ownership models. These operators favor brightly colored composite handles that deter misappropriation.
Hobbyists drive unit volume. Schools provide the steadiest demand trajectory through budgetary predictability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg anchors European tool distribution, connecting Black Forest forging clusters to Atlantic shipping lanes while Rhine barges feed component supply chains into Swiss and German manufacturing basins.
United States
EPA volatile organic compound guidelines govern factory-applied finishes on imported tools, forcing coating reformulation for market access. The Appalachian region sustains artisan-grade demand through heritage craft preservation programs and traditional woodworking schools.
Germany
REACH substance restrictions accelerate migration toward bio-based handle coatings and powder-coated metal surfaces. The Black Forest region concentrates premium hand-tool production, where craft schools institutionalize procurement cycles for laminated steel chisels.
Switzerland
Swissmedic-equivalent craft certification standards shape institutional procurement for educational settings. Zurich and Basel anchor distribution networks serving professional furniture component fabricators requiring ISO 9001-documented quality systems.
Japan
METI traditional craft preservation programs sustain demand for specialized blade profiles unavailable in Western catalogs. The Kansai region around Osaka and Kyoto maintains master-apprentice forging traditions for gallery-oriented sculptors.
China
Dual carbon goals under MEE pressure export-oriented workshops toward energy-efficient forging and finishing processes. Yangtze River Delta manufacturing clusters concentrate volume production for mid-sweep gouges and V-tools serving architectural ornament markets.
Woodcarving Tool Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying blade alloys and ergonomic handle substrates to finished-tool assemblers. The vendor base stratifies across three tiers: heritage European forges with craft-school accreditation, Asian volume manufacturers serving price-sensitive entry segments, and direct-to-consumer brands bundling streaming education with physical purchases. Two dominant competitive moves reshape positioning: strategic partnerships between tool makers and tutorial platforms, plus geographic expansion through regional craft-school anchoring.
Among heritage European forges, Pfeil Tools and Henry Taylor exemplify the craft-school partnership archetype, anchoring institutional procurement channels through documented quality systems and dedicated educational service networks. Flexcut occupies a position within the direct-to-consumer education bundle tier, representing the platform convergence strategy where physical tool sales integrate with streaming tutorial subscriptions to bypass traditional retail markups.
| Leading Market Players |
|---|
| Flexcut |
| Pfeil Tools |
| BeaverCraft |
| Two Cherries |
| Henry Taylor |
| Narex |
| Helvie |
| Kirschen |
| Frosts |
| Others |
Value Network & Pricing Analysis
Overcapacity in Yangtze River Delta forging clusters is compressing margin buffers for entry-level tool assemblers while simultaneously enabling aggressive volume-discounting posture among dominant distributors serving Western hobbyist channels.
Pricing Analysis
Volume-discount tiering structures dominate procurement negotiations, with institutional buyers capturing 15-25 point spreads over direct-to-consumer pricing through multi-year replacement contracts. Certification grade and after-sales service bundling drive differentiation between premium laminated-steel chisels and commodity knife sets. Pricing pressure stems from high-carbon steel input volatility and Asian import concentration eroding mid-tier positioning. Hobbyist segments exhibit highest price sensitivity, while professional restoration workshops tolerate premium positioning for documented metallurgical traceability.
Supply Chain Analysis
Contract-manufacturing concentration resides with Yangtze River Delta and Guangdong Province forging clusters, supplemented by dedicated craft-school suppliers in Germany's Black Forest and Solingen regions. Raw material dependencies center on Swedish and Japanese high-carbon steel stock, sustainably certified European hardwoods, and cobalt-alloyed carbide inserts. Single-source vulnerability runs through Chinese heat-treatment capacity for entry-level blade hardening. Distribution runs through Hamburg and Rotterdam port consolidation for European institutional procurement, with direct-to-consumer channels bypassing traditional specialty retail markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sharpening service subscriptions and streaming tutorial bundles are expanding faster than hardware unit economics, transforming tool vendors into recurring-revenue platforms anchored by physical product entry points.
For Market Incumbents: Pre-empt cordless rotary system convergence by securing battery-platform exclusivity agreements before power-tool majors consolidate hobbyist segments. Anchor institutional procurement through ISO 9001 certification acceleration and dedicated craft-school service networks that emerging Asian competitors cannot replicate within certification timelines. For New Entrants and Emerging Players: Apartment-dwelling urban hobbyists in North American and Western European metropolitan cores represent the most penetrable entry point, underserved by noise-constrained hand-tool alternatives and premium power-tool positioning. Entry-level composite-handle knife sets bundled with Patreon-exclusive project tutorials bypass established retail gatekeepers. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among direct-to-consumer brands with streaming education attach rates exceeding 40 percent of physical purchases. Long-term viability favors acquisition targets with captive sharpening service networks and documented sustainable supply chains qualifying for EU Green Deal procurement incentives. Monitor REACH compliance cost escalation as inflection signal for consolidation acceleration among small-batch European forges.| Strategic Initiative | Industry Significance |
|---|---|
| Streaming Tutorial Platform Partnership | Flexcut's education-bundle model demonstrates subscriber retention exceeding traditional retail repurchase cycles. |
| REACH-Compliant Material Reformulation | Bio-based handle coatings and powder-coated surfaces secure European market access against regulatory exclusion. |
| Craft-School Accreditation Program | Pfeil Tools' institutional anchoring in Switzerland and Germany creates multi-year procurement visibility. |
| Cordless Rotary System Development | Battery-powered micro-carving tools penetrate apartment-dwelling segments previously excluded by noise constraints. |
| Sustainable Supply Chain Certification | EU Green Deal procurement incentives increasingly mandate documented chain-of-custody for educational channel access. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with tool manufacturers, craft-school procurement officers, specialty retailer buyers, and sharpening service operators; and secondary validation through customs trade databases, SEC filings of publicly traded parent companies, REACH substance restriction updates, and ISO certification registries. Bottom-up demand modeling across tool type, material, application, and end-user segments was triangulated against top-down macroeconomic indicators and regional craft education funding trajectories.
Forecast inputs considered historical replacement cycles for chisels and gouges, social platform engagement metrics as leading indicators of hobbyist demand, and regulatory compliance cost trajectories across the analysis window. Segmentation dimensions modeled include tool type, handle material certification tier, application intensity, and end-user sophistication. CAGRs were derived from slope analysis of normalized demand curves adjusted for institutional procurement cyclicality and power-tool substitution elasticity.
Practitioners should monitor high-carbon steel price volatility, REACH substance restriction expansion timelines, and social platform algorithm changes affecting tutorial discoverability for early signals of forecast revision. Quarterly review of craft-school enrollment trends, battery-platform compatibility standards, and sustainable timber certification availability is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Brazing Torch Market
Tools
Machine Bench Vices Market
Tools
Industrial Hand Tools Market
Tools
Industrial Cleaning Equipment Market
Tools
Wood-Sanding Machine Market
Tools
Metal Cutting Machine Market
Tools
Circular Saw Blades Market
Tools
Rocket Wrench Market
Tools
Mechanical Springs Market
Tools
Global Tools Storage Products Market
Tools
Floor Pads Market
Tools
Edge Bending Machine Market
Tools
Cordless Long Neck Grinder Market
Tools
Pneumatic Tools Market
Tools
Gear Honing Machines Market
Tools
Mortiser Market