
 Edge Banders Market | 2026-2036
Edge Banders Market Size, Share, and Industry Trends Forecast 2026-2036
Edge Banders Market Foresight
The edge banders market is recalibrating around a widening gap between premium CNC-laser systems and commodity manual units. SCM Group leverages vertical integration in high-frequency glue technology to command premium positioning. Homag Group anchors its competitiveness through modular automation architectures that scale from mid-tier to industrial throughput. Biesse Group differentiates via software-integrated edge processing that reduces changeover times for custom furniture runs.
Edge banders apply decorative and protective strips to exposed panel edges using heated adhesives or laser-activated polymers, with PUR systems achieving zero-joint seams resistant to moisture and thermal cycling. Fully automatic and CNC edge banders lead equipment demand as European and North American manufacturers replace aging hot-melt lines with PUR and laser platforms. By material, MDF and particle board applications dominate volume due to flat-pack furniture production, while plywood edge banding retains margin concentration in marine and architectural specialty segments.
The EU F-Gas Regulation and REACH framework constrain adhesive formulations and volatile compound thresholds, pushing OEMs toward solvent-free PUR and laser-based bonding systems. The US EPA and OSHA impose parallel workplace exposure limits that affect equipment ventilation specifications and factory layout requirements. Stakeholders must monitor how dual carbon mandates in China and the EU Green Deal's embodied carbon rules reshape equipment energy ratings and supplier qualification criteria.
Market Dynamics
The edge banders market is bifurcating around adhesive technology standards, with PUR and laser-activated polymer systems displacing conventional hot-melt configurations as regulatory emission thresholds tighten across manufacturing jurisdictions.
Growth Catalysts
- EU F-Gas Regulation:Adhesive emission caps in Europe are accelerating factory retrofits toward solvent-free bonding equipment. German furniture manufacturers are expanding automated finishing lines to maintain export certification.
- Integrated cabinetry clusters:China's Guangdong province concentrates demand for precision edge-banding equipment serving export-grade flat-pack production.
- Zero-joint seam performance:PUR systems achieve moisture-resistant and thermally stable panel edges that withstand cycling conditions in marine and architectural applications.
Market Restraints
- Capital intensity of laser platforms:CNC-laser edge banders require substantial upfront investment that constrains mid-tier manufacturer upgrade cycles.
- Adhesive formulation concentration:Specialized PUR and laser-activated polymer supply chains concentrate among limited chemical suppliers, creating input vulnerability.
- Technical service infrastructure gaps:Precision alignment and thermal calibration demands exceed available technician density in secondary manufacturing regions.
Strategic Opportunities
- Modular automation architectures:Equipment configurations that scale from mid-tier throughput to industrial volume capture upgrade pathways without full replacement.
- Software-integrated edge processing:Digital workflow integration reduces changeover times for custom furniture runs and short-batch production.
- Architectural specialty segments:Plywood edge banding for marine and high-end interior applications retains margin concentration underserved by commodity equipment.
Industry Challenges
- Skilled technician scarcity:Laser alignment, thermal calibration, and polymer chemistry expertise outpaces vocational training pipeline output.
- Legacy hot-melt integration friction:Existing production lines require substantial reconfiguration to accommodate PUR adhesive delivery systems and ventilation specifications.
- Dual certification timelines:Equipment must simultaneously satisfy EU REACH substance restrictions and US EPA workplace exposure limits, extending approval cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Edge Banders Market |
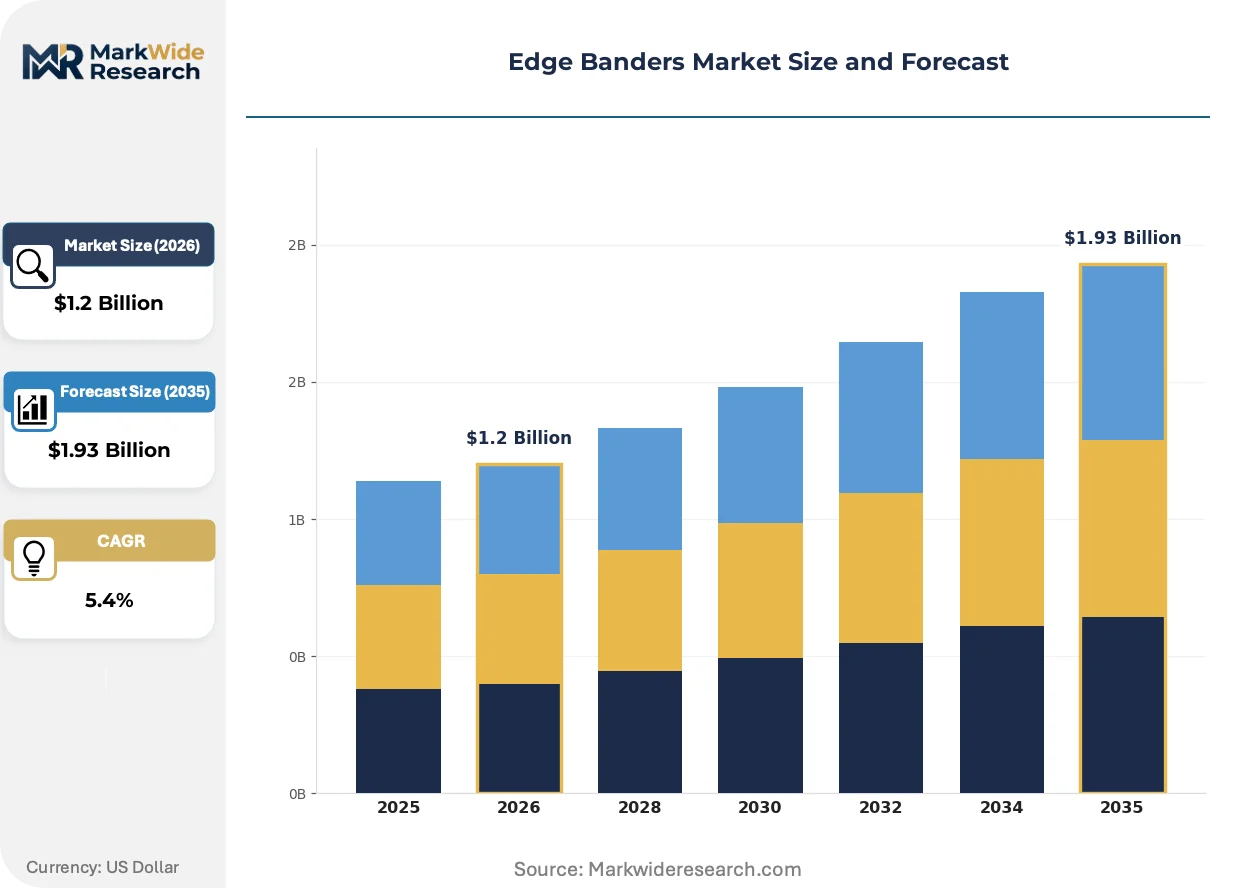
| Market Size in 2026 | $1.2 Billion |
| Market Size in 2035 | $1.93 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Edge Banders, Semi-Automatic Edge Banders, Fully Automatic Edge Banders, CNC Edge Banders Material: Wood, MDF, Plywood, Particle Board End User: Furniture Manufacturers, Cabinet Makers, Construction Companies, DIY Enthusiasts Technology: Hot Melt Technology, PUR Technology, Laser Technology, Cold Glue Technology |
| Companies Covered | SCM Group, Michael Weinig, Homag Group, Biesse Group, Felder Group, Nanxing Machinery, Virutex, Altendorf, CO-MATIC Machinery, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Edge Banders Market Shifts & Advancements
Laser-activated polymer bonding is reshaping equipment specifications as manufacturers seek zero-emission alternatives to solvent-based adhesives. Digital workflow integration and modular system architectures are converging to compress reconfiguration downtime.
Laser-activated polymer edge banding uses focused infrared energy to melt decorative strips directly onto panel substrates without intermediate adhesive layers. High-end furniture producers in Italy and Germany are adopting these systems at accelerating rates to eliminate solvent handling and ventilation infrastructure. This technology is expanding into mid-tier manufacturing segments previously served by hot-melt equipment, compressing the addressable market for conventional adhesive systems.
The EU F-Gas Regulation and REACH framework constrain volatile organic compound thresholds in adhesive formulations. Industrial consequences include mandatory ventilation upgrades and factory layout modifications for manufacturers retaining solvent-based systems. European OEMs are responding by developing solvent-free PUR delivery platforms and laser bonding configurations that preempt enforcement timelines.
Buyer procurement patterns are consolidating around integrated solution providers capable of delivering software-controlled edge processing with predictive maintenance capabilities. Traditional equipment distributors face displacement by direct manufacturer relationships and subscription-based service models. This concentration is most visible in North American contract furniture manufacturing, where procurement teams prioritize single-source accountability for throughput guarantees.
Edge Banders Market Segmentation
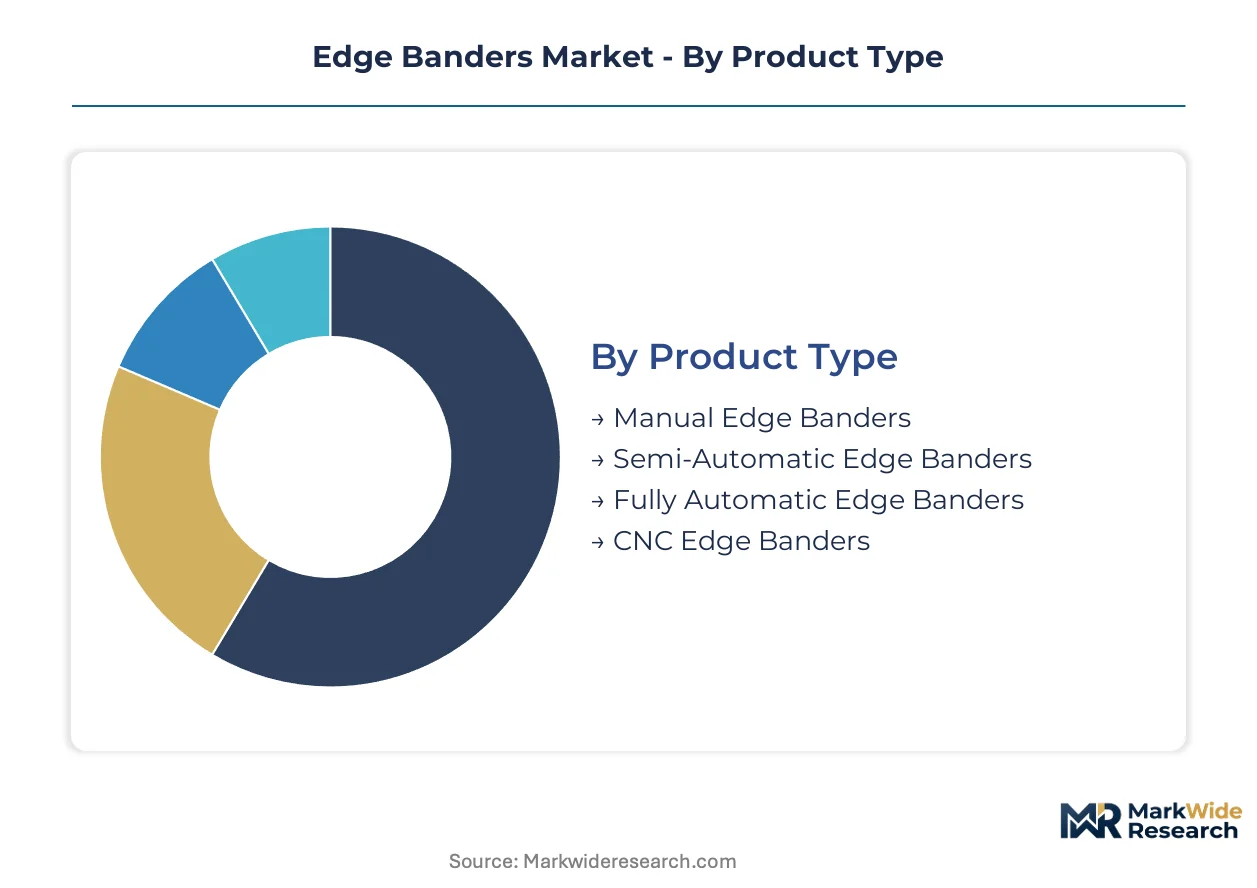
Edge bander procurement patterns diverge sharply across automation tiers and adhesive technologies, with replacement cycles accelerating in Europe and China as emission regulations harden. Equipment specification varies by panel substrate, end-use scale, and integration requirements for factory automation architectures.
Product Type:
Equipment replacement cycles now favor automated platforms as labor costs rise and quality tolerances tighten across export-oriented production.
- Fully Automatic Edge Banders:These systems integrate pre-milling, glue application, edge trimming, and buffing in continuous feed configurations. German furniture manufacturers expanding automated finishing lines under EU F-Gas Regulation timelines are driving concentrated demand for these platforms.
- CNC Edge Banders:Computer-numerical control enables rapid changeover between panel specifications and stores processing parameters for recurring jobs. China's Guangdong province cabinetry clusters source these systems to maintain precision tolerances for flat-pack export production.
- Semi-Automatic Edge Banders:Intermediate platforms requiring operator loading but automating adhesive application and trimming functions serve mid-tier manufacturers in Poland and Vietnam.
- Manual Edge Banders:Portable benchtop units dominate entry-level woodworking shops and vocational training facilities in Indonesia and Mexico.
Volume placements concentrate in Fully Automatic systems; the faster expansion belongs to CNC platforms with software-integrated workflow capabilities.
Material:
Substrate selection dictates adhesive technology requirements and determines equipment specification for thermal cycling resistance.
- MDF:Medium-density fiberboard presents uniform edge porosity that accepts hot-melt and PUR bonding with minimal pre-conditioning. Flat-pack furniture producers in Sweden and Turkey specify MDF-compatible edge banders for high-throughput panel processing.
- Particle Board:Lower-density core structures require controlled glue penetration to prevent edge swelling; moisture-resistant PUR systems are displacing conventional hot-melt in German kitchen cabinet manufacturing.
- Plywood:Marine-grade and architectural applications demand zero-joint seam performance that laser-activated polymer systems deliver for yacht builders in Italy and high-end interior contractors in France.
- Wood:Solid timber edge banding retains artisan furniture segments and restoration workshops where manual or semi-automatic equipment suffices.
MDF commands the largest installed base; plywood applications are climbing the fastest as marine and specialty architectural specifications proliferate.
End User:
Customer scale determines automation investment thresholds and service infrastructure requirements for technical support density.
- Furniture Manufacturers:Industrial-scale producers operating integrated finishing lines require CNC-laser platforms with predictive maintenance integration and throughput guarantees.
- Cabinet Makers:Custom kitchen and built-in specialists favor modular semi-automatic systems that reconfigure between batch sizes without dedicated technicians.
- Construction Companies:On-site millwork contractors prioritize portable edge banding equipment for architectural installation finishing.
- DIY Enthusiasts:Hobbyist woodworkers purchase compact manual units through distributor and direct-to-consumer channels.
Furniture manufacturers account for dominant equipment placements; cabinet makers are gaining share fastest as custom production runs proliferate.
Technology:
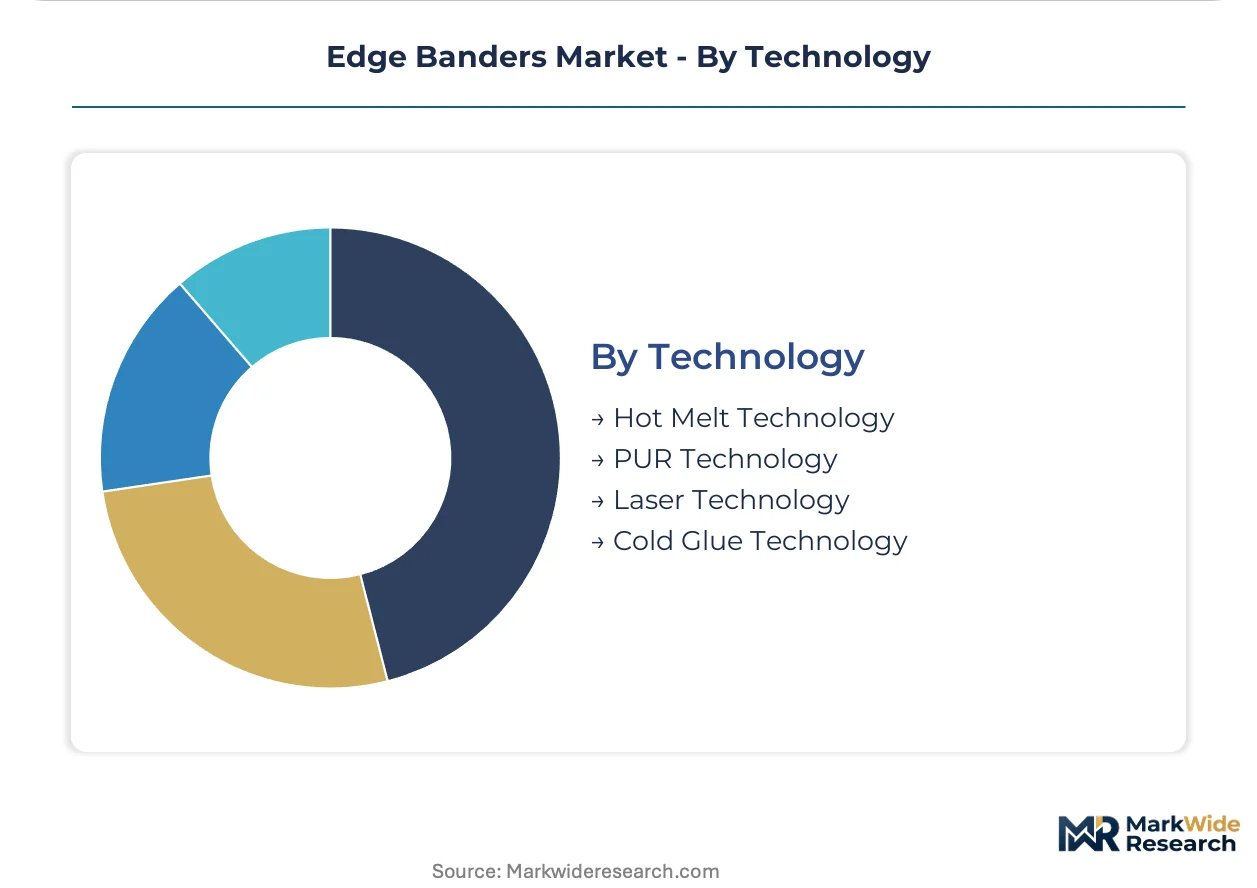
Adhesive bonding methods are bifurcating around regulatory emission thresholds and joint performance specifications.
- PUR Technology:Polyurethane reactive adhesives cure to thermoset bonds resistant to moisture, heat, and solvent exposure. EU REACH substance restrictions are accelerating factory retrofits toward PUR delivery systems that eliminate solvent handling infrastructure.
- Laser Technology:Infrared-activated polymer bonding eliminates adhesive layers entirely, achieving zero-joint aesthetics required by Italian high-end furniture producers and German architectural millwork specialists.
- Hot Melt Technology:Conventional ethylene-vinyl acetate systems retain cost-sensitive applications where emission regulations permit and joint durability requirements are moderate.
- Cold Glue Technology:Water-based adhesive systems serve specialized veneer applications and temperature-sensitive substrates in restoration and heritage furniture workshops.
Hot Melt retains the largest installed equipment base; laser platforms are expanding most quickly as solvent-free bonding becomes mandatory across European manufacturing jurisdictions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Guangdong province's integrated cabinetry clusters concentrate the heaviest procurement volumes for precision edge-banding equipment serving export-grade flat-pack production destined for European and North American markets.
Germany
Furniture manufacturers in Baden-Württemberg and North Rhine-Westphalia are expanding automated finishing lines to maintain export certification under tightening EU F-Gas Regulation adhesive emission caps. The EU REACH framework constrains volatile compound thresholds, accelerating factory retrofits toward solvent-free PUR and laser bonding systems. Stuttgart's precision machinery corridor hosts concentrated demand for CNC-laser platforms with predictive maintenance integration.
China
Guangdong province's cabinetry clusters source precision edge-banding equipment to maintain tolerance standards for flat-pack furniture exports. The country's dual carbon goals reshape equipment energy ratings and supplier qualification criteria for factory automation investments. Dongguan and Foshan manufacturing zones concentrate procurement of fully automatic systems serving IKEA-tier production contracts.
United States
Contract furniture manufacturers in North Carolina and Michigan prioritize single-source accountability for throughput guarantees as procurement patterns consolidate around integrated solution providers. EPA workplace exposure limits and OSHA ventilation specifications affect equipment specifications and factory layout requirements for manufacturers retaining solvent-based systems. Grand Rapids' office furniture corridor drives concentrated demand for modular automation architectures.
Italy
High-end furniture producers in Lombardy and Veneto are adopting laser-activated polymer systems at accelerating rates to eliminate solvent handling and ventilation infrastructure. CE marking requirements and EU Green Deal embodied carbon rules reshape equipment qualification criteria for architectural millwork specialists. Brianza's luxury furniture district anchors demand for zero-joint seam performance in premium interior applications.
Vietnam
Mid-tier manufacturers in Binh Duong and Dong Nai provinces source semi-automatic platforms requiring operator loading but automating adhesive application functions. Technical service infrastructure gaps for precision alignment and thermal calibration constrain upgrade cycles beyond hot-melt configurations. Ho Chi Minh City's furniture export zones concentrate procurement serving IKEA and Target supply chain diversification strategies.
Edge Banders Market Competitive Landscape
Capital-heavy producers compete with asset-light designers as equipment architecture bifurcates around adhesive technology standards. The vendor base separates into three strategic archetypes: vertically integrated machinery conglomerates controlling high-frequency glue technology, modular automation specialists scaling across throughput tiers, and software-integrated platform developers compressing changeover times. Dominant competitive moves include backward integration into adhesive delivery systems and geographic expansion through distributor-to-direct sales model transitions.
Among European-based fabricators, Homag Group and Biesse Group exemplify contrasting automation philosophies, while SCM Group anchors the vertically integrated tier with captive control over bonding system supply chains. Nanxing Machinery occupies a position among Chinese equipment specialists serving Guangdong province's export-oriented cabinetry clusters. These named entities represent archetype diversity rather than exhaustive market coverage, with each exemplifying distinct strategic positioning around technology integration depth, geographic service density, or cost-structure optimization.
| Leading Market Players |
|---|
| SCM Group |
| Michael Weinig |
| Homag Group |
| Biesse Group |
| Felder Group |
| Nanxing Machinery |
| Virutex |
| Altendorf |
| CO-MATIC Machinery |
| Others |
Supply & Pricing Matrix
Furniture manufacturers in Germany's automated finishing lines concentrate procurement authority for CNC-laser platforms, anchoring value-based pricing that ties equipment cost to throughput guarantees and uptime performance rather than capital expenditure alone.
Pricing Analysis
Throughput-based pricing dominates as buyers negotiate total cost-of-ownership contracts linking payment to panel processing volume and yield rates. Price differentiation rests on CE marking tier and predictive maintenance bundling, with premium configurations commanding substantial uplifts for laser-activated polymer compatibility. Cost compression in mid-tier manual and semi-automatic segments is intensifying because Chinese equipment specialists are scaling export capacity. Small cabinet makers and vocational training facilities exhibit highest price sensitivity, while industrial furniture manufacturers prioritize performance guarantees over acquisition cost.
Supply Chain Analysis
CE marking and EPA workplace exposure certification gating restricts supplier qualification to OEMs with validated adhesive delivery and ventilation integration documentation. Manufacturing concentrates in Germany, Italy, and China, with precision machining and control systems drawing from specialized component ecosystems in Japan and Switzerland. High-frequency glue technology and laser-activated polymer feedstock dependencies create single-source vulnerability for bonding system subassemblies. Distribution runs through direct manufacturer relationships displacing traditional equipment distributors, particularly in North American contract furniture procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU F-Gas Regulation's adhesive emission caps have erected a compliance moat that favors incumbent OEMs with certified solvent-free PUR and laser platform portfolios, raising capital barriers for uncertified competitors.
For Market Incumbents: Anticipate margin pressure from Chinese equipment specialists scaling modular automation architectures by deepening captive control over high-frequency glue technology supply chains and expanding technical service infrastructure density in Vietnam and Poland. Prioritize certification investment for dual REACH and EPA compliance to extend approval cycle advantages over emerging entrants lacking regulatory affairs capacity. For New Entrants and Emerging Players: Launch via subscription-based service models targeting mid-tier cabinet makers in Vietnam and Indonesia where technical service infrastructure gaps constrain incumbent support density. White-space opportunity concentrates in portable edge banding equipment for on-site construction millwork and aftermarket retrofit kits for legacy hot-melt line conversion. Pursue partnership positioning with Guangdong cabinetry clusters seeking cost-optimized precision equipment for export-grade production. For Investors and Strategic Acquirers: The window for entry favors equipment OEMs with validated laser platform architectures and established adhesive chemistry partnerships. Long-term viability hinges on regulatory compliance capacity rather than manufacturing scale alone. Monitor EU Green Deal embodied carbon rule implementation timelines as the critical inflection signal for equipment energy rating requalification cycles and supplier consolidation triggers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Adhesive Delivery Systems | Captive PUR and laser-activated polymer supply secures margin control against chemical supplier concentration. |
| Modular Automation Architecture Development | Scalable configurations capture upgrade pathways from mid-tier to industrial throughput without full replacement. |
| Software-Integrated Edge Processing Platform | Digital workflow compression reduces changeover times for custom furniture runs and short-batch production. |
| Technical Service Infrastructure Expansion | Dense technician networks in secondary manufacturing regions overcome alignment and calibration capability scarcity. |
| Dual Certification Investment Program | Simultaneous EU REACH and US EPA compliance accelerates approval cycles and disqualifies undercapitalized competitors. |
Research Methodology
Document review covered customs and trade data, SEC filings from listed machinery OEMs, EU F-Gas Regulation enforcement documentation, and REACH substance restriction updates, complemented by interviews with plant engineers at German furniture manufacturers, procurement leads at Guangdong cabinetry clusters, aftermarket service heads at Italian equipment distributors, and technical R&D directors at adhesive system suppliers. Bottom-up equipment shipment tracking and top-down manufacturing value-added estimates were triangulated against secondary validation from industry association production surveys and machinery export statistics.
Historical capacity utilization and replacement cycle patterns were cross-referenced against panel input from OEM order backlogs and flat-pack furniture export forecasts across the analysis window. Segmentation modeling incorporated automation tier, adhesive technology type, panel substrate material, and end-user scale dimensions. CAGRs were derived from regression analysis of equipment placement volumes against regulatory enforcement timelines and factory automation investment cycles, with specific inputs from EU Green Deal embodied carbon rule progression and China's dual carbon goal implementation pace.
Regulatory enforcement delays, adhesive feedstock supply disruptions, and vocational training pipeline shortfalls for laser alignment technicians are the dominant revision risks to equipment demand forecasts. Forecasts reflect documented assumptions regarding emission standard harmonization and factory retrofit completion rates. A model refresh is warranted upon material change in EU F-Gas Regulation adhesive emission cap enforcement timelines or major shifts in Guangdong export order volumes.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Ultra Hard Material Cutting Machines Market
Tools
Masonry Cleaners Market
Tools
Global Zero Point Clamping System Market
Tools
Pruning Saw Market
Tools
Handheld Engraving Machine Market
Tools
Cold and Hot Tool Steel Market
Tools
Portable Heat Press Machine Market
Tools
Portable Milling Machine Market
Tools
Global Cordless Power Tools Market
Tools
Machine Bench Vices Market
Tools
Pneumatic Tools Market
Tools
Adoption of Benelux Power Tools Market
Tools
Mechanical Hand Tools Market
Tools
Gear Honing Machines Market
Tools
Log Splitters Market
Tools
Impact Sockets Market