
 Power Press Machines Market | 2026-2036
Power Press Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Power Press Machines Market Analysis
Automotive electrification is recalibrating press capacity requirements across major manufacturing bases. Amada leverages its servo-electric technology leadership to capture EV battery housing and motor lamination contracts. Schuler sustains dominant position in large transfer press systems for legacy automaker retooling programs. AIDA Engineering specializes in high-speed precision presses that serve tier-one electronics suppliers migrating production to Southeast Asia.
Power press machines apply controlled mechanical force through reciprocating rams to deform, cut, or shape sheet metal and forgings, with modern units achieving positional accuracy within 0.01 mm through closed-loop servo control. The equipment serves as primary production assets in mass manufacturing of stamped automotive body panels, appliance enclosures, and precision electronic lead frames. C-frame configurations occupy the largest installed base due to lower capital outlay and operational flexibility in small-to-medium batch production. H-frame systems command premium positioning in heavy-gauge forming applications where structural rigidity determines part consistency. Mechanical technology retains volume leadership in high-speed stamping while hydraulic systems gain share in complex forming sequences requiring programmable force profiles.
OSHA machine guarding standards and EU Machinery Directive 2006/42/EC mandate two-hand controls, light curtains, and brake monitoring systems that elevate safety system costs but reduce liability exposure for fleet operators. China's GB standards on forging and pressing machinery safety, administered by SAMR, require domestic and imported equipment to undergo conformity assessment before facility commissioning. Stakeholders must monitor divergence between regional certification requirements when configuring export-ready product platforms.
Market Dynamics
Servo-electric press technology is displacing mechanical systems as the dominant force reshaping capital allocation decisions across automotive and electronics manufacturing clusters.
Growth Catalysts
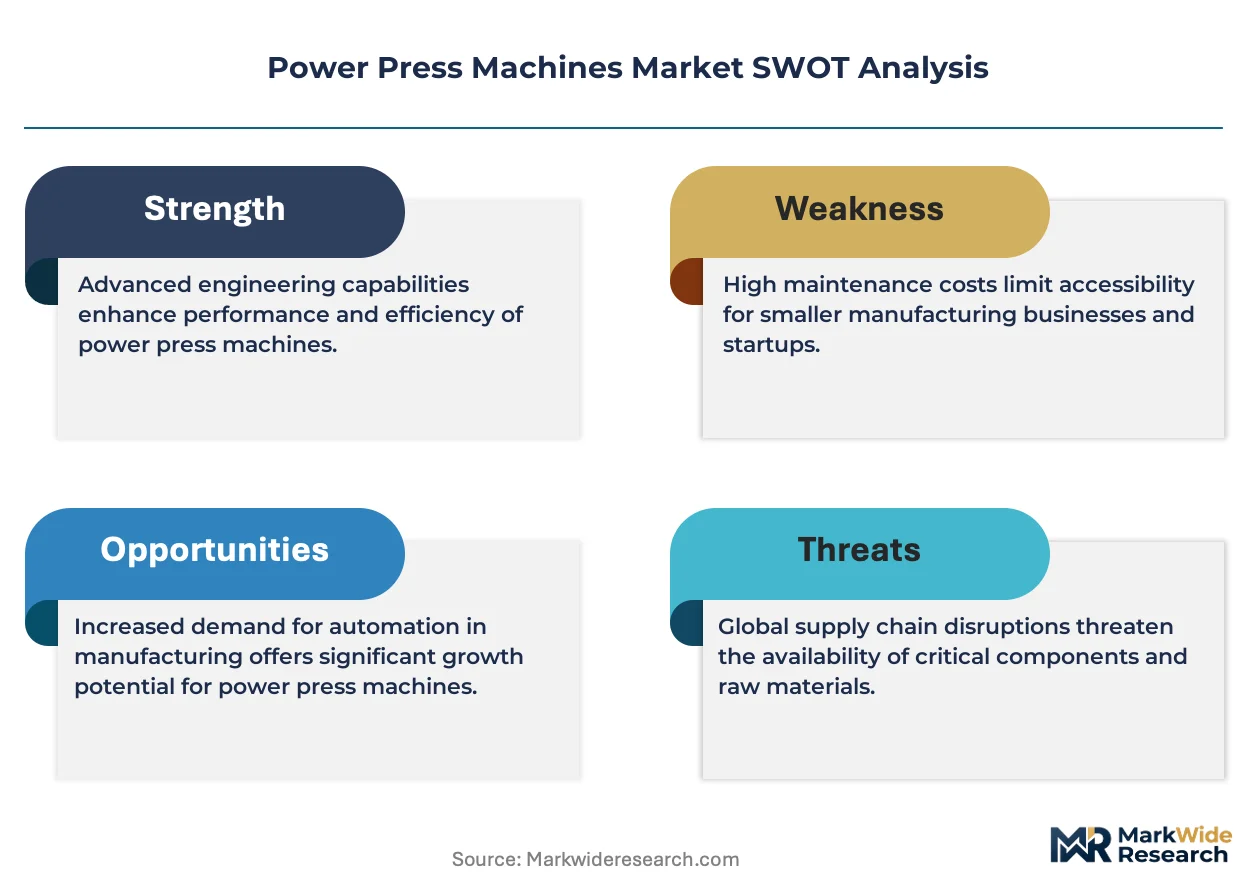
- EU Ecodesign efficiency mandates:German automotive OEMs retrofit stamping lines to meet 2024 energy performance requirements, triggering replacement cycles for hydraulic equipment.
- EV battery housing demand:Precision forming requirements for aluminum-intensive EV architectures pull high-tonnage servo presses into Korean and Chinese battery plant expansions.
- Japan METI factory energy standards:Tier-one electronics suppliers accelerate press modernization to capture government efficiency subsidies and carbon reduction credits.
Market Restraints
- Copper and rare-earth magnet cost volatility:Servo motor supply chains concentrate in Chinese processing facilities, exposing OEMs to input price swings that compress equipment margins.
- Technical limitation in thick-gauge forming:Mechanical presses retain cost advantages above 800-ton capacity for heavy truck chassis stampings, slowing full electrification of the installed base.
- REACH substance restrictions:Hydraulic fluid formulations face compliance redesign costs that extend European equipment commissioning timelines by 4-6 months.
Strategic Opportunities
- India PLI scheme for auto component manufacturing:Domestic press fabricators qualify for production-linked incentives when supplying stampers in Tamil Nadu and Gujarat industrial corridors.
- Southeast Asia electronics migration:Vietnamese and Indonesian metalworking clusters lack precision press density, creating first-mover advantages for servo-electric system suppliers.
- Digital twin convergence with predictive maintenance:Real-time ram position monitoring and AI-driven wear prediction enable outcome-based service pricing for fleet operators.
Industry Challenges
- Servo control programming expertise gap:Mechanical press technicians require 12-18 month retraining cycles to operate closed-loop CNC systems, constraining workforce scalability.
- Legacy mechanical press integration complexity:Brownfield facilities face production downtime risks when retrofitting safety-rated light curtains and brake monitoring to pre-2010 equipment.
- Multi-jurisdiction certification timelines:Exporters must sequence OSHA, CE marking, and China GB conformity assessments, extending product launch windows by 8-10 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Power Press Machines Market |
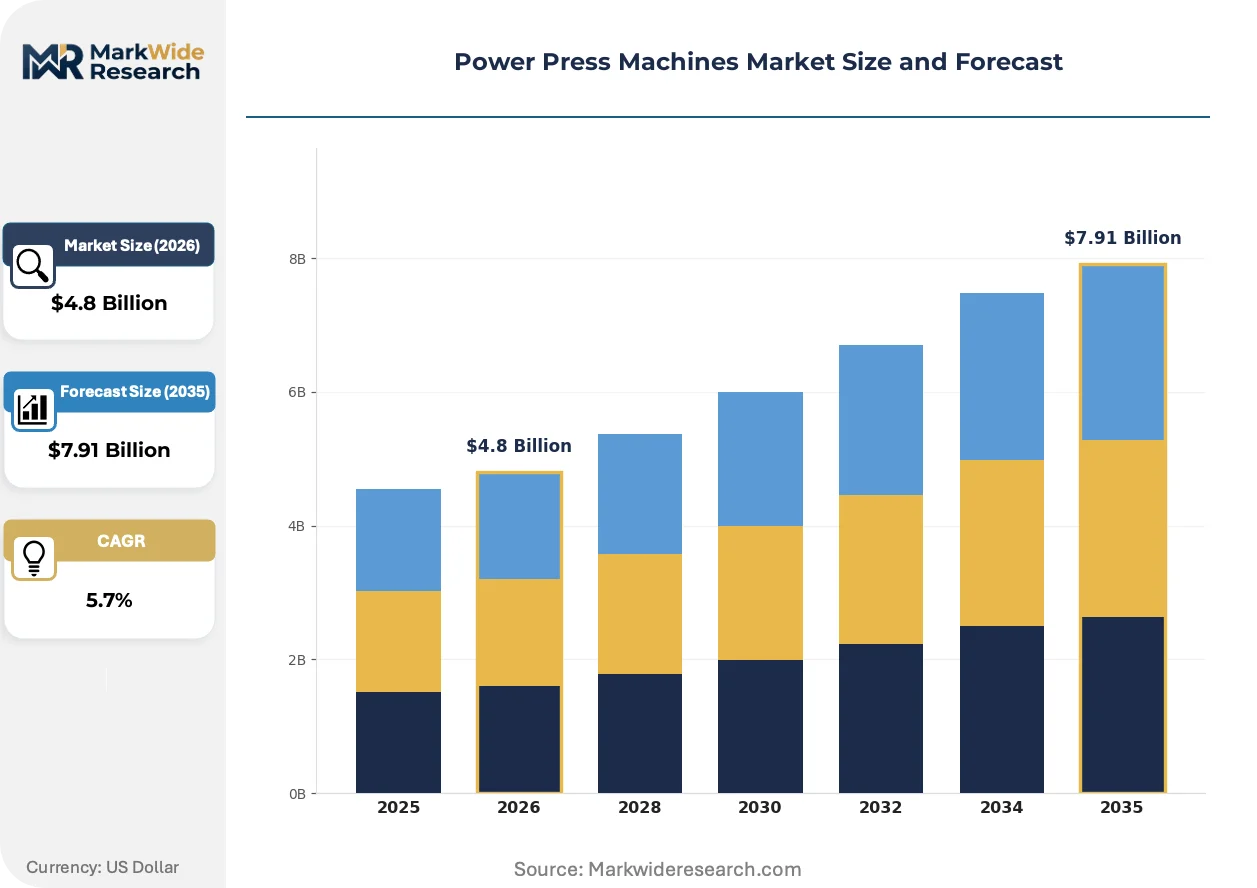
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: C-Frame, H-Frame, Pillar, Toggle End User: Automotive, Aerospace, Electronics, Metalworking Technology: Hydraulic, Mechanical, Pneumatic, Electrical Application: Stamping, Forming, Cutting, Bending |
| Companies Covered | Amada, AIDA Engineering, Zhejiang Bolun Precision Machinery Co., Ltd., Yangzhou Metalforming Machine Tool Co., Ltd., SIMPAC, Macrodyne Technologies Inc., Schuler, Shijiazhuang Lishen Forging Machine Tool Co., Ltd., JDM Jingda Machine (Ningbo) Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Power Press Machines Market Emerging Trajectories
Digital thread integration across press design, commissioning, and operational phases is compressing total cost of ownership calculations for fleet buyers.
Servo-electric drive architecture is decentralizing power distribution in high-speed stamping cells. Individual servo motors replace centralized flywheel systems, enabling programmable slide motion profiles that reduce die wear. Automotive tier-one suppliers in Germany and Japan adopt these systems for motor lamination and transmission component runs. The technology is decentralizing maintenance scheduling by allowing module-level replacement rather than full line shutdowns.
EU Machinery Directive 2006/42/EC amendments tighten functional safety requirements for collaborative press operations. Manufacturers must integrate safety PLCs with Category 3 performance levels for light curtain and two-hand control systems. European metalforming OEMs absorb 15-20% safety system cost premiums to maintain CE market access. Chinese exporters targeting EU markets accelerate in-house safety engineering capabilities to avoid third-party certification dependencies.
Buyer consolidation among automotive stampers shifts procurement toward full-line integration contracts rather than standalone press purchases. Tier-one suppliers now specify die-handling automation, coil feeding systems, and quality inspection modules as bundled requirements. Equipment vendors respond with expanded systems engineering divisions. This pattern concentrates most visibly in China's Yangtze River Delta, where state-owned vehicle groups consolidate supplier bases to reduce commissioning complexity.
Power Press Machines Market Segmentation
Power press machine procurement decisions hinge on force capacity, precision requirements, and energy efficiency mandates that vary sharply across end-use sectors. Segmentation reveals how automotive electrification and electronics miniaturization are reallocating capacity investments toward programmable servo systems and rigid-frame architectures.
Product Type:
Customization intensity spans from standardized C-frame units for job shops to engineered H-frame systems for dedicated automotive lines.
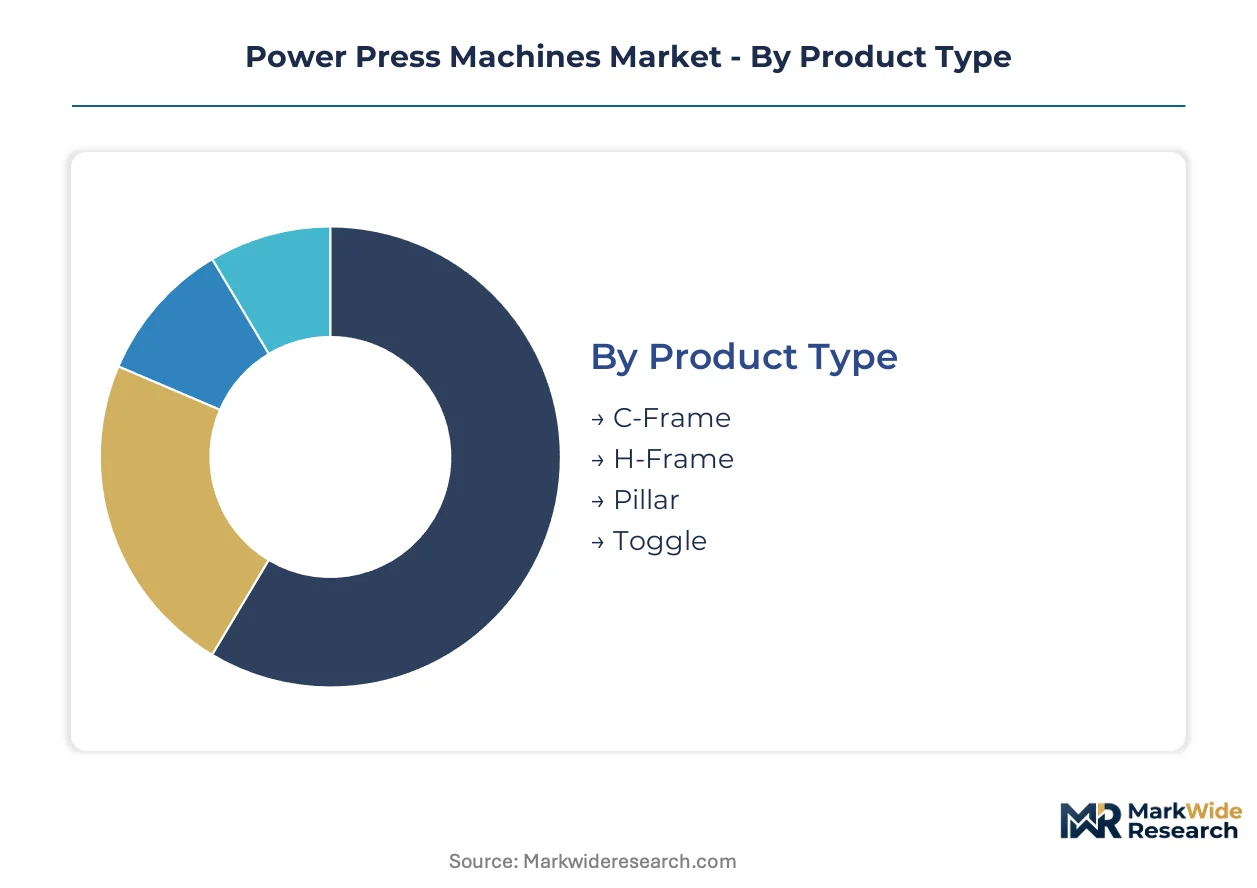
- C-Frame:Open-front configuration permits side access for die loading and part extraction, suiting short-run fabrication workflows. China's Yangtze River Delta metalworking clusters deploy these for appliance component batches where setup flexibility outweighs absolute rigidity.
- H-Frame:Four-column structure distributes forming loads symmetrically, maintaining parallelism under 1000+ ton forces. German automotive OEMs specify these for aluminum-intensive EV body panel stampings where dimensional repeatability determines assembly fit.
- Pillar:Vertical column design suits heavy-gauge forging applications with substantial bed areas.
- Toggle:Linkage mechanism amplifies force at bottom dead center for coining and embossing precision work.
Most installed capacity flows through C-Frame configurations. Expansion is steepest in H-Frame as EV architectures drive heavy-gauge aluminum forming demand.
End User:
Volume concentration and margin structure diverge between cyclical automotive procurement and electronics sector capital planning cycles.
- Automotive:Stamping lines operate at 600-1200 strokes per minute for high-volume body-in-white production. Tier-one suppliers in Germany and Japan modernize servo-electric capacity to meet EU Ecodesign and METI efficiency standards.
- Electronics:High-speed precision presses form motor laminations and battery interconnects at micron-level tolerances. Korean battery manufacturers pull 300+ ton servo systems into new plant constructions for EV cell housing production.
- Aerospace:Titanium and superalloy forming demands heat-assisted hydraulic systems with extended dwell capabilities.
- Metalworking:General fabrication shops prioritize equipment versatility across mixed material thicknesses.
Automotive commands the largest equipment fleet. Electronics represents the fastest-growing trajectory as electrification reshapes component demand.
Technology:
Energy accounting and programmable motion control separate legacy mechanical investments from next-generation servo architectures.
- Hydraulic:Variable force profiles enable deep-draw forming sequences with dwell control at pressure peaks. REACH substance restrictions on hydraulic fluids extend European commissioning timelines, slowing replacement cycles.
- Mechanical:Flywheel energy storage delivers cost-efficient high-speed stamping above 800-ton capacity. Technical limitations in programmable slide motion constrain adoption for complex forming sequences.
- Pneumatic:Compressed air systems serve light-gauge cutting and blanking in low-tonnage applications.
- Electrical:Servo motor arrays eliminate mechanical linkages, enabling programmable ram motion that reduces die wear. Copper and rare-earth magnet cost volatility compress OEM margins on these systems.
Hydraulic systems retain the broadest installed base. Electrical technology is gaining share fastest where energy efficiency mandates drive replacement decisions.
Application:
Process physics and tooling economics determine whether buyers prioritize speed, force precision, or motion programmability.
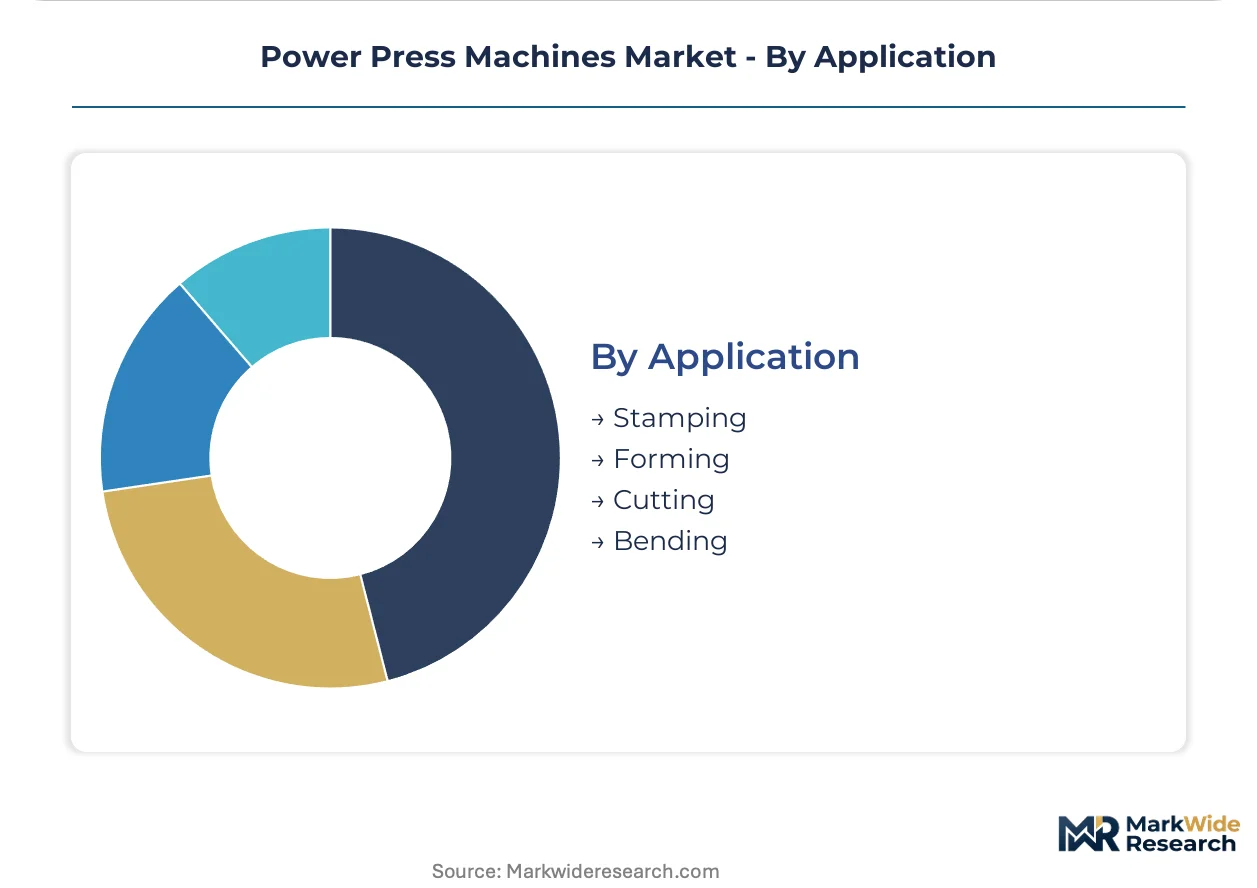
- Stamping:High-speed blanking and piercing operations dominate automotive volume production. Mechanical and servo-electric systems compete on stroke rate and energy recovery metrics.
- Forming:Stretch-draw and deep-draw sequences require controlled pressure profiles. Hydraulic and servo-electric architectures enable programmable force curves that protect die surfaces.
- Cutting:Shearing and slitting applications favor rigid frame structures with minimal deflection.
- Bending:Angle-forming and flanging operations span manual press brake to automated CNC systems.
Stamping absorbs the majority of press capacity. Forming applications are expanding most quickly as complex EV component geometries proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redistributing power press capacity toward jurisdictions with weaker energy efficiency mandates and lower safety compliance costs. Manufacturers are relocating assembly and sourcing operations to exploit gaps between EU Ecodesign requirements and emerging market enforcement timelines.
Germany
Automotive OEMs in Bavaria and Baden-Württemberg retrofit stamping lines to meet EU Ecodesign Directive energy performance thresholds. The country's national industrial regulator enforces Machinery Directive 2006/42/EC functional safety standards. Stuttgart's automotive cluster drives demand for H-frame servo-electric systems in aluminum-intensive EV body panel production.
China
Domestic fabricators in the Yangtze River Delta upgrade from mechanical to CNC-hydraulic presses for precision component output. SAMR administers GB standards conformity assessments before facility commissioning. Shanghai and Suzhou metalworking clusters concentrate capacity investments for appliance and electronics enclosure manufacturing.
Japan
Tier-one electronics suppliers accelerate press modernization to capture METI factory energy efficiency subsidies. The Ministry of Economy, Trade and Industry sets carbon reduction credit thresholds for capital equipment replacement. Nagoya's Chubu region hosts concentrated motor lamination and transmission component stamping operations.
United States
Automotive stampers in Michigan and Ohio face OSHA machine guarding standard compliance costs for legacy equipment retrofits. The Department of Labor mandates two-hand controls and brake monitoring systems that elevate safety system expenditures. Detroit's manufacturing corridor sustains demand for high-tonnage mechanical presses in heavy truck chassis production.
India
Domestic press fabricators qualify for PLI scheme production-linked incentives when supplying stampers in Tamil Nadu and Gujarat. The Ministry of Heavy Industries administers eligibility criteria for auto component manufacturing equipment. Chennai and Ahmedabad industrial corridors attract first-mover servo-electric system suppliers serving electronics migration from China.
Power Press Machines Market Vendor Landscape
Capacity expansion dominates the current landscape as equipment vendors build regional assembly facilities to shorten commissioning timelines and circumvent multi-jurisdiction certification delays. The vendor base stratifies across three tiers: integrated systems houses with full-line automation capabilities, mid-scale specialists in servo-electric architectures, and regional job-shop fabricators serving replacement part demand. Strategic archetypes include technology licensors monetizing servo control IP, vertically integrated firms capturing margin on rare-earth magnet supply chains, and service-intensive operators bundling predictive maintenance contracts. Geographic expansion and portfolio diversification represent the dominant competitive moves, with players adding die-handling automation and quality inspection modules to press offerings.
Within the integrated systems tier, Schuler and Amada exemplify full-line automation positioning. German-origin Schuler occupies a position in large transfer press systems for legacy automaker retooling programs. Japanese-headquartered Amada represents servo-electric technology leadership in EV battery housing and motor lamination contracts. Among precision specialists, AIDA Engineering anchors high-speed press supply for tier-one electronics suppliers migrating production to Southeast Asia. Zhejiang Bolun Precision Machinery Co., Ltd. sits within the Chinese regional fabricator archetype serving Yangtze River Delta upgrade cycles.
| Leading Market Players |
|---|
| Amada |
| AIDA Engineering |
| Zhejiang Bolun Precision Machinery Co., Ltd. |
| Yangzhou Metalforming Machine Tool Co., Ltd. |
| SIMPAC |
| Macrodyne Technologies Inc. |
| Schuler |
| Shijiazhuang Lishen Forging Machine Tool Co., Ltd. |
| JDM Jingda Machine (Ningbo) Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
Certified servo control engineers concentrated in Stuttgart and Nagoya command wage premiums that widen pricing spreads between premium servo-electric systems and standard hydraulic units. Labor-cost differentials between these specialized workforce pools and general mechanical press technician markets directly shape three-tier equipment pricing structures.
Pricing Analysis
Distributor margins of 12-18% separate factory gate pricing from end-user acquisition costs, with direct-to-OEM volume contracts commanding 8-12% discounts. Three-tier pricing structure across premium, standard, and economy levels reflects CE marking tier, servo motor brand tier, and after-sales service bundling intensity. Cost compression in economy-tier mechanical presses is intensifying because Chinese regional fabricators absorb margin to capture Yangtze River Delta upgrade cycles. Job-shop metalworkers in India's Gujarat corridor exhibit highest price sensitivity, while German automotive OEMs prioritize energy efficiency specifications over capital outlay minimization.
Supply Chain Analysis
Dual-sourcing requirements for rare-earth magnet arrays and copper winding assemblies force OEMs to qualify suppliers in both China and Japan. Servo motor production concentrates in China, Japan, and Germany, with CNC control systems sourcing from Taiwan and South Korea. Rare-earth magnet, high-grade steel forging, and precision ball screw dependencies expose assemblers to commodity price volatility. Tariff exposure on Chinese-processed rare-earth elements constitutes the dominant structural supply risk. Distribution runs through authorized regional distributors with factory-trained service capabilities rather than open-channel trading.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Power press equipment procurement has shifted into a late-cycle quality phase where EU Ecodesign efficiency mandates and METI factory energy standards pull buyers toward premium servo-electric specifications regardless of replacement cycle timing.
For Market Incumbents: Acquire servo control programming expertise pools to address the 12-18 month technician retraining bottleneck constraining workforce scalability. Consolidate aftermarket service networks in Southeast Asia to defend installed base relationships against emerging regional fabricators. Servo-electric technology displacement from mechanical systems threatens legacy revenue streams, requiring backward integration into rare-earth magnet supply chains to protect margin compression from Chinese processing concentration. For New Entrants and Emerging Players: Capture Vietnamese and Indonesian electronics metalworking clusters where precision press density remains underdeveloped and first-mover positioning in servo-electric systems is achievable. Target India's Tamil Nadu and Gujarat industrial corridors under PLI scheme qualification pathways. Partner with European safety engineering consultancies to accelerate CE marking timelines and circumvent 8-10 month multi-jurisdiction certification delays that disadvantage pure regional players. For Investors and Strategic Acquirers: Industrial automation conglomerates with automotive sector exposure represent the most active acquirer in this space, seeking servo-electric technology capabilities to complement existing robotics portfolios. Five-to-ten year viability hinges on digital twin integration and predictive maintenance contract attach rates rather than standalone equipment margins. Monitor divergence between OSHA, CE marking, and China GB conformity assessment timeline harmonization as the critical inflection signal for export-ready platform scalability.| Strategic Initiative | Industry Significance |
|---|---|
| Servo-Electric Technology Acquisition | Amada's motor lamination contracts demonstrate premium positioning in EV battery housing demand. |
| Southeast Asia Manufacturing Footprint | Vietnamese electronics migration lacks precision press density, creating first-mover supply advantages. |
| Digital Twin Platform Development | Real-time ram position monitoring enables AI-driven wear prediction and outcome-based service pricing. |
| Multi-Jurisdiction Certification Investment | In-house safety engineering capabilities at Chinese exporters reduce third-party CE marking dependencies. |
| Rare-Earth Magnet Supply Agreement | Copper and magnet cost volatility compress OEM margins, favoring upstream control over Chinese processing. |
Methodological Framework
Bottom-up automotive and electronics end-use modeling reconciled against top-down servo motor and control system supply-side tracking forms the analytical core. Primary interviews with maintenance directors at German automotive OEMs, plant engineers in China's Yangtze River Delta, OEM procurement teams at Korean battery manufacturers, and aftermarket service heads at Japanese electronics suppliers combined with secondary validation from SEC filings of listed equipment vendors, EU Ecodesign Directive implementation reports, METI factory energy standard subsidy disclosures, and SAMR GB standards conformity assessment databases. Triangulation between installed base surveys and replacement cycle intention studies anchors volume projections.
Input-output matrices map servo motor capacity, rare-earth magnet availability, and certified technician labor pools against EV battery housing demand, motor lamination requirements, and appliance enclosure production schedules across the projection horizon. Segmentation dimensions include force capacity tier, frame architecture type, technology category, end-use sector, and regional regulatory cluster. CAGRs derive from equipment replacement intention surveys and energy efficiency mandate compliance timelines. Industry-specific forecast inputs incorporate EU Ecodesign Directive enforcement phases and Japan METI carbon reduction credit thresholds.
Rare-earth magnet price volatility, REACH substance restriction redesign costs, and workforce retraining cycle duration are the dominant revision risks. Deviation in Chinese rare-earth export policy would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Turning Tools Market
Tools
United States Machine Tools Market
Tools
Rivet Gun Market
Tools
Cutting Pipe and Perforating Pipe Drilling Tools Market
Tools
Grabber Pole Market
Tools
US Chalk Reel and Line Market
Tools
End Milling Machine Market
Tools
Cutting Tool Inserts Market
Tools
Adjustable Gripping Hand Tools Market
Tools
Pneumatic Bolting Tools Market
Tools
Gear Honing Machines Market
Tools
Drill Bit Market
Tools
Tension Tester Market
Tools
Friction Washer Market
Tools
Tape Measure Market
Tools
Mechanical Springs Market