
 Tension Tester Market | 2026-2036
Tension Tester Market Size, Share, and Industry Trends Forecast 2026-2036
Tension Tester Market Outlook
Asset-light leasing and pay-per-test service models is fragmenting competitive dynamics in the tension tester landscape, enabling smaller construction firms and regional automotive suppliers to access calibrated validation without capital expenditure. Instron Corporation leverages its vertical integration into load frame manufacturing and software analytics to sustain premium positioning across laboratory deployments. ZwickRoell anchors European demand through its specialization in automated testing workflows for automotive and aerospace compliance programs. Shimadzu Corporation competes in Asia-Pacific through its control of precision sensor supply chains and localized calibration networks.
A tension tester measures mechanical stress, elongation, and breaking strength in materials under controlled axial loading, typically employing strain-gauge load cells with resolution down to 0.5% of full scale to validate structural integrity in wire ropes, cables, and composite assemblies. Digital tension meters occupy the largest revenue pool due to their integration with Industry 4.0 data architectures and real-time pass-fail automation in manufacturing lines. Portable tension testers represent the fastest-expanding category, driven by on-site wire rope testing mandates in offshore energy and bridge infrastructure inspection protocols where laboratory access proves impractical.
ASTM International and ISO govern material validation protocols in the United States and European Union respectively, while China's GB standards and NMPA calibration requirements shape product certification for equipment sold into domestic manufacturing facilities. OSHA workplace safety directives and FAA airworthiness regulations in the United States compel documented tension verification in lifting operations and control cable installations, creating recurring replacement demand for certified testing equipment. Stakeholders must monitor how evolving building codes and renewable energy installation standards redefine the performance thresholds that tension testers must demonstrate to maintain market access.
Market Dynamics
Equipment leasing and pay-per-test service models are fragmenting competitive dynamics in the tension tester landscape, enabling smaller construction firms and regional automotive suppliers to access calibrated validation without capital expenditure.
Growth Catalysts
- OSHA workplace safety directives:Documented tension verification mandates in US lifting operations create recurring replacement demand for certified testing equipment across industrial facilities.
- Offshore energy infrastructure:On-site wire rope testing protocols for subsea cables and platform rigging drive portable tension tester adoption where laboratory access proves impractical.
- Precision sensor miniaturization:Strain-gauge load cells achieving 0.5% resolution enable continuous in-line tension monitoring for quality certification in automotive assembly lines.
Market Restraints
- Calibration infrastructure concentration:Accredited calibration laboratories cluster in Germany, Japan, and the United States, creating service access barriers for equipment operators in emerging manufacturing regions.
- High-purity alloy input costs:Load cell manufacturing depends on specialty steel and aluminum alloys subject to commodity price volatility and export restriction regimes.
- Inter-standard incompatibility:ASTM E8 and ISO 6892 testing protocols generate specification conflicts for multinational manufacturers seeking unified procurement frameworks.
Strategic Opportunities
- India's PLI scheme for precision engineering:Domestic manufacturing incentives attract tension tester assembly operations targeting automotive and aerospace component suppliers in Pune and Chennai corridors.
- Renewable energy installation standards:Evolving wind turbine blade and solar tracking system certification requirements create demand for field-deployable tension validation equipment.
- Blockchain-integrated calibration records:Immutable test documentation addresses insurance and liability requirements in bridge infrastructure and elevator safety inspection markets.
Industry Challenges
- Metrology technician scarcity:Specialized calibration and repair skills concentrate in aging workforce demographics across European and North American service networks.
- Legacy system integration friction:Digital tension meters with Industry 4.0 data architectures face protocol mismatches with existing manufacturing execution systems in mature industrial facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tension Tester Market |
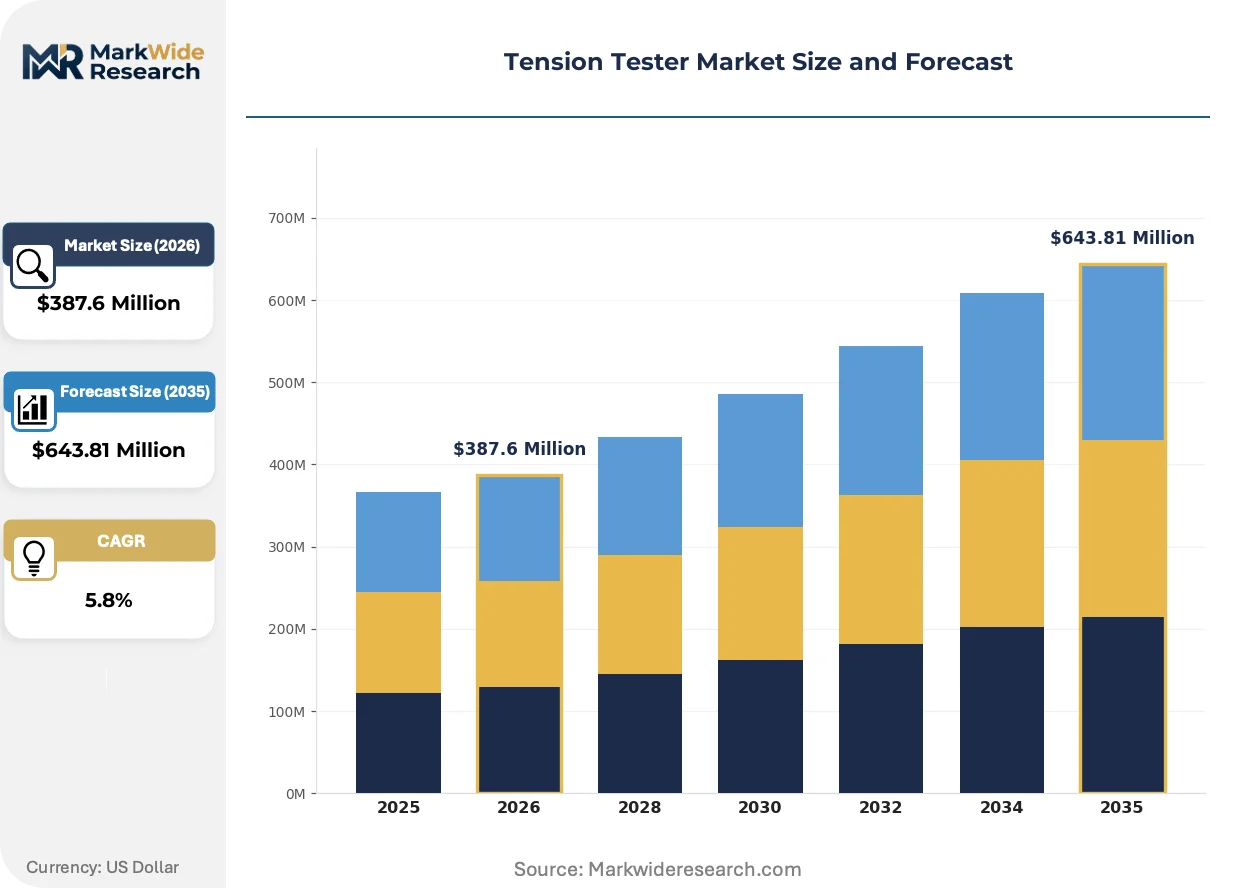
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $643.81 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital Tension Meters, Mechanical Tension Gauges, Optical Tension Sensors, Portable Tension Testers End User: Aerospace, Construction, Automotive, Manufacturing Deployment: On-site Testing, Laboratory Testing, Remote Monitoring, Integrated Testing Solutions Application: Wire Rope Testing, Cable Inspection, Load Testing, Structural Analysis |
| Companies Covered | Instron Corporation, Illinois Tool Works Inc., ZwickRoell, Shimadzu Corporation, Ametek, Tinius Olsen, Montalvo Corporation, Maxcess International, Erhardt + Leimer, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tension Tester Market Strategic Shifts
Digitalization of material validation workflows is compressing test cycle times and expanding real-time quality control deployment across manufacturing lines previously dependent on batch sampling protocols.
Wireless load cell networks with edge computing capabilities are hybridizing tension monitoring architectures. Offshore wind farm operators in the North Sea adopt these systems for continuous mooring line surveillance. Real-time alerts replace periodic manual inspection schedules, compressing maintenance response windows from weeks to hours.
REACH substance restrictions on heavy metals in electronic components are forcing load cell manufacturers to reformulate solder and coating chemistries. European suppliers face compliance verification costs that Asian competitors exporting into the EU must equally absorb. Component traceability documentation now extends through three-tier supply chains.
Service unbundling is separating hardware ownership from calibration and software maintenance obligations. Construction contractors in Germany's precision engineering corridor increasingly lease certified equipment with embedded recalibration scheduling. This shifts capital allocation toward project execution rather than asset ownership.
Tension Tester Market Segmentation
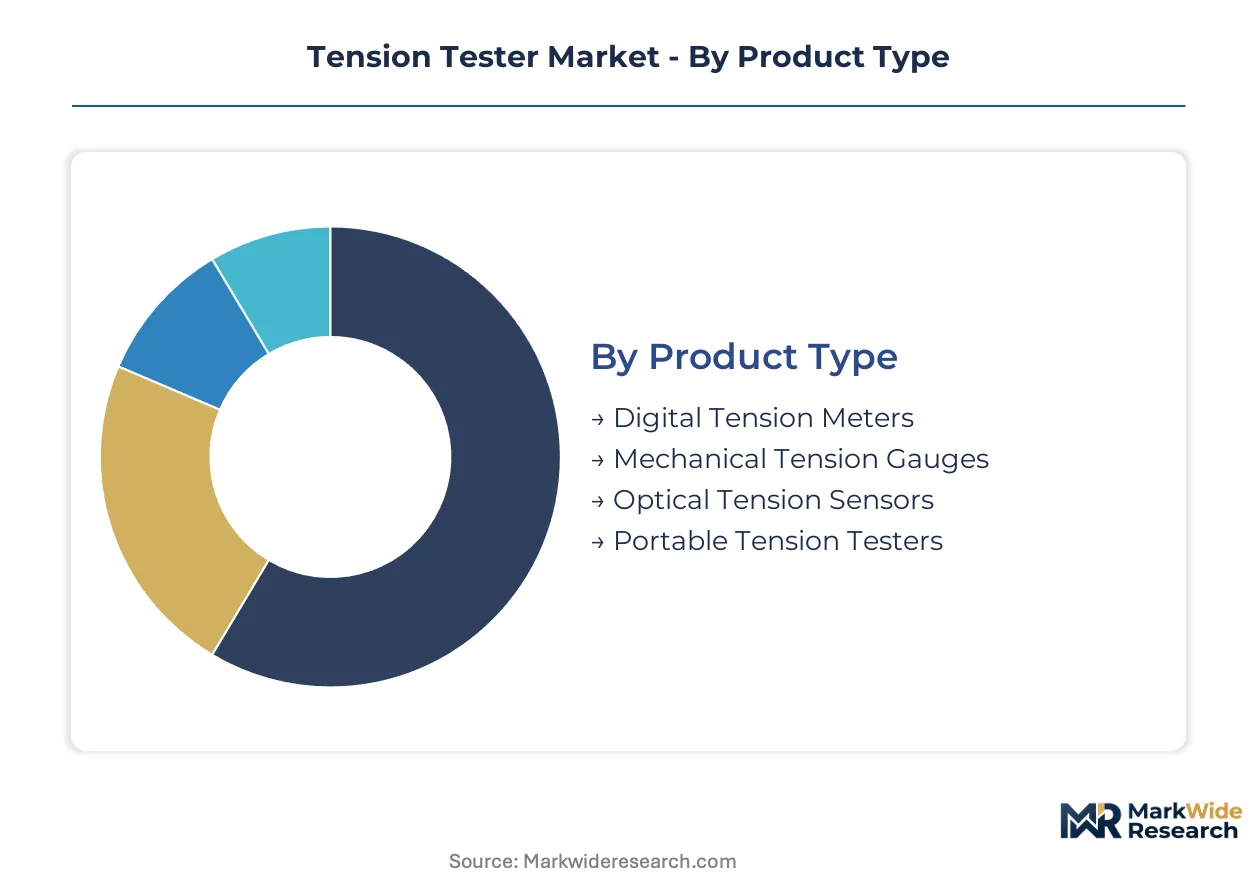
Tension tester procurement follows distinct technical and operational logics across product architectures, end-use environments, and deployment modalities. Segmentation reveals where capital expenditure concentrates versus where service-based models capture emerging demand.
Product Type:
Mature electromechanical designs coexist with emerging sensor architectures that embed wireless connectivity and edge computing capabilities.
- Digital Tension Meters:These units integrate strain-gauge load cells with microprocessor-controlled data acquisition, achieving 0.5% full-scale resolution. Automotive OEMs in Germany's precision engineering corridor deploy them for continuous in-line quality certification. Their Industry 4.0 compatibility drives replacement cycles in automated assembly environments.
- Portable Tension Testers:Battery-powered designs with wireless readouts enable on-site validation where laboratory access proves impractical. Offshore wind operators in the North Sea and bridge inspection crews across US interstate corridors represent concentrated demand. OSHA workplace safety directives mandating documented wire rope verification accelerate procurement.
- Mechanical Tension Gauges:Spring-and-dial analog instruments persist in budget-constrained construction subcontractor fleets.
- Optical Tension Sensors:Laser-based non-contact measurement systems serve applications where physical load cell attachment risks material damage.
Digital tension meters handle the majority of throughput; portable tension testers are the fastest mover on share.
End User:
Cost tier stratification separates capital-intensive certification programs from compliance-driven spot-testing requirements.
- Automotive:Tier-1 suppliers and OEMs require ASTM E8 and ISO 6892 compliant validation for every structural cable batch. Continuous in-line monitoring systems dominate capital allocation here.
- Construction:General contractors and specialty rigging firms access equipment through leasing models that bundle calibration scheduling. OSHA compliance documentation creates recurring service revenue.
- Aerospace:FAA airworthiness regulations demand traceable calibration chains with NIST-traceable certificates for control cable installations.
- Manufacturing:Diverse industrial facilities span from precision engineering workshops to heavy machinery assembly plants with heterogeneous testing protocols.
Automotive commands the largest equipment investment; construction is climbing the fastest as leasing penetration deepens.
Deployment:
Volume concentration reflects the shift from centralized metrology laboratories toward distributed testing architectures.
- Laboratory Testing:Fixed installations with climate-controlled environments deliver the highest accuracy for R&D and certification-grade validation. ZwickRoell and Instron anchor this segment with automated workflow integration.
- On-site Testing:Mobile units with rapid-deployment tripods and battery power address infrastructure inspection mandates. Bridge authorities and offshore platform operators drive replacement demand.
- Remote Monitoring:Wireless load cell networks with cloud dashboards enable continuous mooring line surveillance without manual inspection rounds.
- Integrated Testing Solutions:Embedded sensors within manufacturing execution systems automate pass-fail decisions at production line speeds.
Laboratory testing retains the deepest revenue base; on-site testing is gaining share fastest as field validation protocols expand.
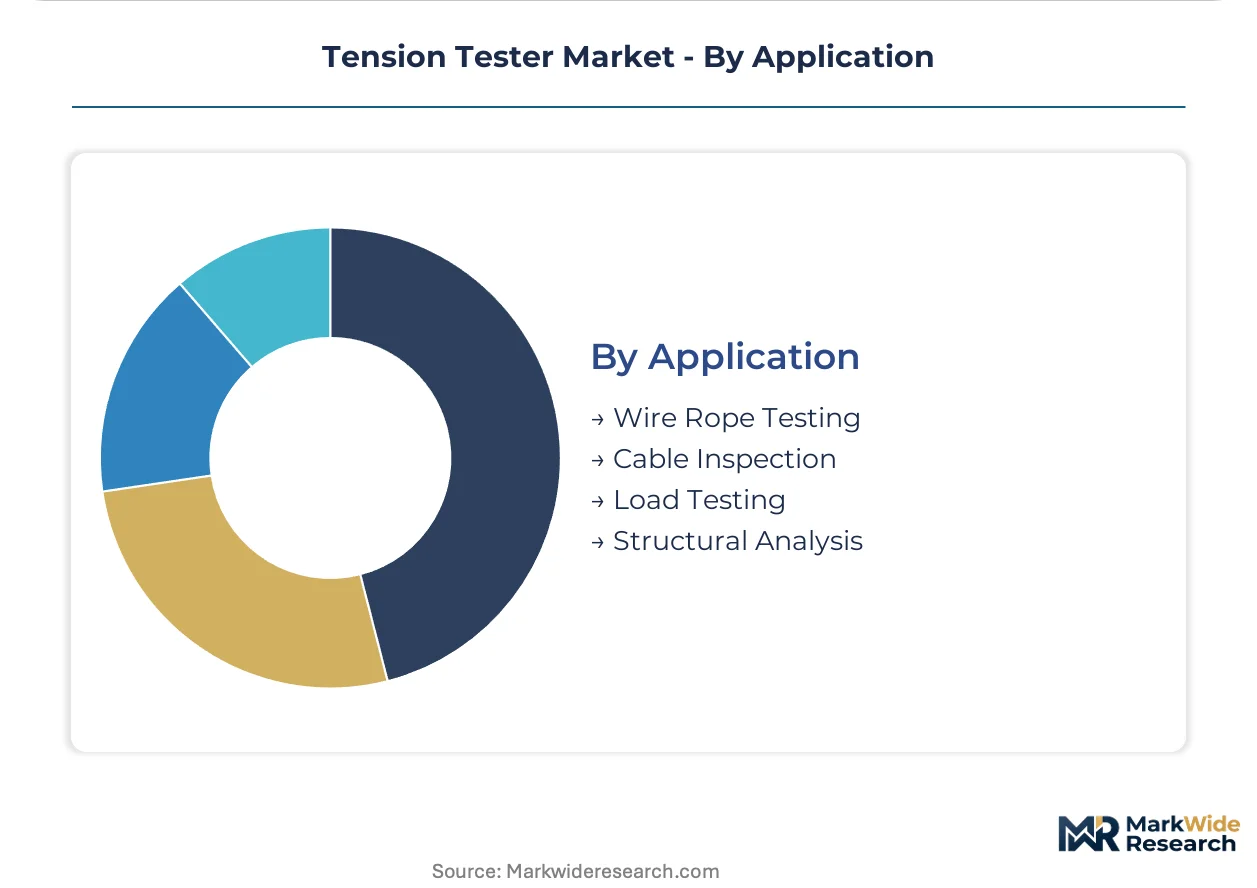
Application:
Customer type differentiation separates scheduled preventive inspection from reactive failure-analysis investigations.
- Wire Rope Testing:Destructive and non-destructive validation of crane cables, elevator hoist ropes, and mining haulage lines. Mandated inspection intervals under OSHA and FAA regulations create predictable replacement cycles.
- Cable Inspection:Electrical transmission lines and telecommunications infrastructure require tension verification for sag calculations and load capacity certification.
- Load Testing:Proof loading of lifting equipment and temporary structures validates rated capacity before operational deployment.
- Structural Analysis:Post-tensioned concrete and cable-stayed bridge engineering demands long-term creep monitoring and stress redistribution measurement.
Wire rope testing absorbs the greatest equipment volume; structural analysis is expanding most quickly as aging infrastructure inspection mandates proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany maintains a structural export surplus in precision tension testing equipment, while the United States and China absorb the largest import volumes for infrastructure and manufacturing deployment. Trade flows concentrate through specialized calibration service corridors that link equipment origin to end-use certification requirements.
United States
OSHA workplace safety directives mandate documented tension verification across lifting operations and elevator installations, generating recurring equipment replacement cycles. FAA airworthiness regulations compel traceable calibration chains for control cable validation in commercial aviation maintenance. Industrial clusters in Houston and the Gulf Coast concentrate demand for offshore rigging inspection protocols.
Germany
Automotive OEMs and cable system integrators in Stuttgart and Munich require continuous in-line tension monitoring for ISO 6892 quality certification. REACH substance restrictions on heavy metals in electronic components force load cell manufacturers to reformulate solder and coating chemistries. The precision engineering corridor between Bavaria and Baden-Württemberg anchors European R&D investment in automated testing workflows.
China
GB standards and NMPA calibration requirements shape domestic product certification for equipment sold into manufacturing facilities. Domestic production incentives under the 14th Five-Year Plan attract assembly operations targeting automotive component suppliers. Yangtze River Delta industrial zones concentrate demand for wire rope testing in port infrastructure and shipbuilding applications.
Japan
METI industrial standards govern precision sensor specifications for automotive and aerospace component validation. JIS certification requirements create barriers to entry for foreign equipment suppliers without localized calibration networks. Nagoya and Toyota City manufacturing clusters drive adoption of embedded tension monitoring in automated assembly environments.
India
PLI scheme incentives for precision engineering attract tension tester assembly operations targeting automotive and aerospace suppliers. BIS certification requirements for imported testing equipment create compliance complexity for multinational suppliers. Pune and Chennai industrial corridors concentrate demand from construction contractors accessing equipment through emerging leasing models.
Tension Tester Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in sensor and load cell fabrication. The vendor base separates into three functional layers: full-system providers with software-analytics integration, mid-tier equipment assemblers sourcing calibrated subsystems, and pure-play sensor manufacturers supplying OEM channels. Consolidation pressure concentrates at the system tier where automation capabilities determine procurement decisions. Competitive moves center on backward integration into precision sensor supply chains and geographic expansion of accredited calibration service networks.
Among North American platform integrators, Instron Corporation and Illinois Tool Works Inc. occupy positions emphasizing laboratory-grade system deployment. ZwickRoell anchors European demand through its specialization in automated compliance workflows. Shimadzu Corporation represents the Asia-Pacific archetype of sensor supply chain control combined with localized service infrastructure. These three exemplify how regional equipment certification requirements shape competitive positioning across distinct geographic markets.
| Leading Market Players |
|---|
| Instron Corporation |
| Illinois Tool Works Inc. |
| ZwickRoell |
| Shimadzu Corporation |
| Ametek |
| Tinius Olsen |
| Montalvo Corporation |
| Maxcess International |
| Erhardt + Leimer |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in Japanese precision sensor foundries tightens supply availability for strain-gauge load cells, forcing equipment manufacturers to pre-commit volumes and accept less favorable payment terms while passing input cost exposure downstream to automotive OEM procurement teams.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Premium tier equipment commands certification-grade positioning through NIST-traceable calibration chains and embedded software analytics, while economy tiers serve construction subcontractors with stripped-down mechanical gauges. Price differentiation rests on calibration documentation depth and after-sales service bundling. Cost compression in the standard tier intensifies because Chinese assemblers are capturing mid-market share with GB-certified alternatives. Construction leasing customers exhibit highest price sensitivity; aerospace compliance programs show lowest.
Supply Chain Analysis
Extended payment terms from German automotive OEMs cascade upstream, squeezing working capital for load cell manufacturers who must finance specialty alloy inventory through supply-chain finance facilities. Component fabrication concentrates in Germany, Japan, and the United States, with final assembly migrating to China and India under PLI incentives. Raw material sourcing draws from Swedish specialty steel, Australian aluminum, and Taiwanese semiconductor substrates. Single-source vulnerability sits with precision strain-gauge suppliers in Nagoya. Distribution runs through accredited calibration laboratories that bundle equipment with certification services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Equipment leasing and pay-per-test unbundling fragments demand into serviceable niches, creating entry points for specialized regional players outside the integrated system tier.
For Market Incumbents: Harden calibration network density in emerging manufacturing corridors before local accreditation regimes mature. Deepen backward integration into precision sensor supply chains to offset alloy cost volatility. Instron Corporation's captive load cell production illustrates defensive positioning against substitute pressure from wireless sensor entrants.
For New Entrants and Emerging Players: Pursue on-site portable testing contracts with North Sea offshore wind operators where laboratory access constraints create immediate procurement friction. India's PLI corridors offer white-space assembly opportunity with domestic content requirements favoring local entities. Blockchain-integrated calibration documentation provides differentiated go-to-market positioning for bridge infrastructure inspection markets.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because automation capabilities and calibration accreditation constitute scarce, defensible assets that compound with scale. Target mid-tier equipment assemblers with established BIS or NMPA certification pathways but limited geographic reach. Watch leasing penetration rates in German construction markets as inflection signal for service-model viability elsewhere.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sensor Supply Chains | Captive strain-gauge production insulates margin from specialty alloy price volatility and export restrictions. |
| Calibration Network Geographic Expansion | Accredited service presence in India and China addresses emerging-market equipment deployment without laboratory access. |
| Blockchain-Integrated Test Documentation | Immutable calibration records satisfy FAA airworthiness and OSHA liability requirements in infrastructure inspection markets. |
| Leasing Model Service Unbundling | Embedded recalibration scheduling shifts capital allocation for construction contractors toward project execution. |
| Wireless Load Cell Platform Development | Edge computing architectures enable continuous mooring line surveillance for North Sea offshore wind operators. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of regulatory filings, customs trade data, and equipment certification databases. Conversations with maintenance directors at automotive OEMs, plant engineers at construction contractors, aftermarket service heads at rental equipment firms, and procurement leads at cable system integrators informed demand-side validation. Secondary sources include OSHA enforcement records, FAA airworthiness directives, ISO 6892 protocol documentation, and NMPA calibration requirements. Bottom-up equipment shipment analysis triangulates against top-down manufacturing value-add estimates.
Forecast inputs span product architecture, end-use industry, deployment modality, and regional regulatory cluster across the analysis window. Modeled segmentation captures digital versus portable versus mechanical equipment types; automotive, construction, aerospace, and manufacturing end users; laboratory, on-site, remote, and integrated deployment formats. CAGRs derive from equipment replacement cycle analysis, regulatory mandate expansion trajectories, and leasing penetration elasticity. Industry-specific inputs include ASTM E8 and ISO 6892 compliance requirement evolution and REACH substance restriction implementation timelines.
Sensitivities concentrate around alloy commodity price spikes, calibration laboratory accreditation bottlenecks, and inter-standard protocol harmonization failures. Forecasts reflect documented assumptions regarding regulatory enforcement continuity and infrastructure inspection mandate expansion. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Global Table Saws Market
Tools
Turning Centers Market
Tools
US Chalk Reel and Line Market
Tools
Global DC Torque Tool Market
Tools
Water Pump Pliers Market
Tools
Floor Pads Market
Tools
Horizontal Milling Machine Market
Tools
Indexable Tool Inserts Market
Tools
Foldable Ladder Market
Tools
Assembly Fastening Tool Market
Tools
Forging Press Market
Tools
Diamond Core Drilling Market
Tools
Cordless Power Drill Market
Tools
Automotive Torque Tools Market
Tools
Dumpy Level Market
Tools
Boring-Milling Machines Market