
 GCC Polyethylene (PE) Pipes Market | 2026-2036
GCC Polyethylene (PE) Pipes Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Polyethylene (PE) Pipes Market Intelligence
Saudi Vision 2030 sustainability targets are broadening specifications for corrosion-resistant water infrastructure across the Kingdom. Borouge Pte Ltd leverages its Abu Dhabi petrochemical integration to supply certified PE100 resin grades to regional pipe extruders. Cosmoplast Industrial Company LLC anchors distribution across the UAE's emirate-level contracting landscape. Saudi Arabian Amiantit Co dominates large-diameter orders tied to Saudi Arabia's gigaproject pipeline networks.
Polyethylene pipes are thermoplastic conduits manufactured through extrusion of ethylene-based polymers, with density grades determining pressure ratings from PN6 to PN25 bar and operating temperatures typically spanning -40°C to 60°C. These pipes transport fluids and gases across buried and exposed installations where flexibility, chemical resistance, and fusion-welded joint integrity outperform metallic alternatives. High-Density Polyethylene leads volume due to its dominance in water supply and gas distribution pressure applications, while Cross-Linked Polyethylene commands premium positioning in hot-water and industrial chemical service where elevated temperature tolerance justifies material cost. Trenchless installation methods are expanding fastest among installation categories, driven by urban density constraints in Dubai and Doha that prohibit open-cut excavation on congested utility corridors.
SASO (Saudi Standards, Metrology and Quality Organization) and ESMA (Emirates Authority for Standardization and Metrology) enforce polyethylene pipe compliance with ISO 4427 and EN 12201 dimensional and performance benchmarks, while Gulf Standardization Organization harmonization reduces cross-border certification burdens. MOHAP and Saudi Arabia's National Water Company procurement rules increasingly specify PE over ductile iron for potable distribution renewals, redirecting material specifications across public tender pipelines. Stakeholders must monitor gigaproject completion schedules and desalination capacity additions to anticipate demand surges for large-diameter HDPE trunk lines.
Market Dynamics
Saudi Vision 2030 utility diversification mandates are redirecting public procurement toward corrosion-resistant polymer distribution networks, compressing traditional ductile iron specifications across municipal water tenders.
Growth Catalysts
- SASO compliance mandates:Saudi Standards, Metrology and Quality Organization specifications for ISO 4427-certified PE pipes are hardening material requirements across potable water renewals.
- Desalination trunk line expansion:Saudi Arabia's central province corridor is aggregating demand for large-diameter HDPE pressure pipes serving gigaproject water networks.
- Trenchless installation methods:Horizontal directional drilling adoption is accelerating in Dubai and Doha where urban density prohibits open-cut excavation on congested utility corridors.
Market Restraints
- Ethylene feedstock volatility:Crude oil price swings transmit directly to PE resin costs, squeezing extruder margins on fixed-price municipal contracts.
- Abu Dhabi petrochemical concentration:Borouge Pte Ltd's regional PE100 resin dominance creates single-source vulnerability for certified pipe grades.
- Temperature ceiling limitations:Standard HDPE operating ranges of -40°C to 60°C exclude high-temperature industrial process applications where metallic pipes retain specification.
Strategic Opportunities
- Qatar's infrastructure pipeline:FIFA legacy utility upgrades and Lusail City expansion are generating under-tendered demand for PE gas distribution and drainage systems.
- Cross-Linked Polyethylene hot-water service:PEX penetration in district cooling and solar thermal distribution offers premium positioning beyond commodity water supply.
- Gulf Standardization Organization harmonization:Unified certification protocols are reducing cross-border testing burdens for multi-emirate contractors.
Industry Challenges
- Fusion welding technician scarcity:Butt and electrofusion joint certification requirements are outpacing vocational training capacity in Saudi Arabia's Eastern Province.
- ESMA compliance timelines:Emirates Authority for Standardization and Metrology approval cycles for new pipe dimensions are extending project mobilization schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Polyethylene (PE) Pipes Market |
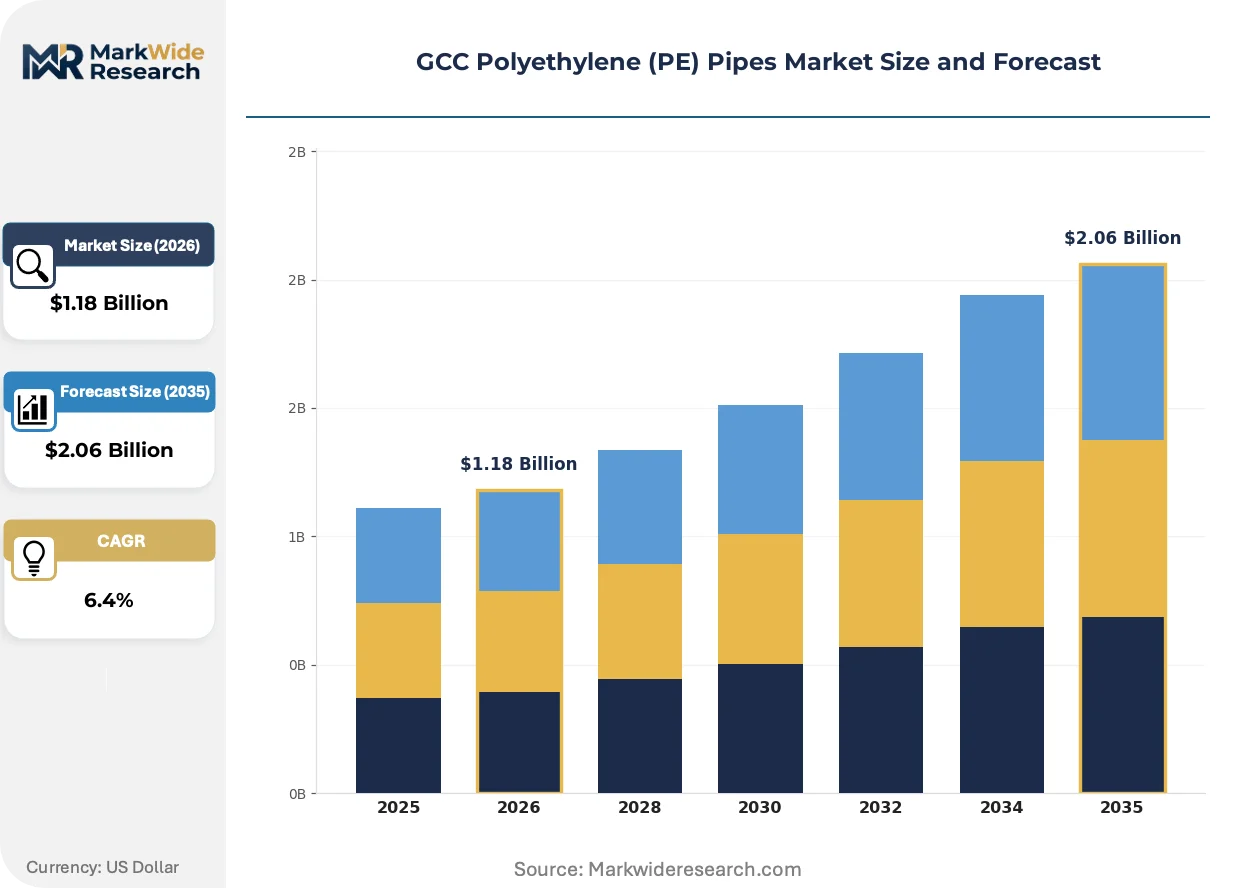
| Market Size in 2026 | $1.18 Billion |
| Market Size in 2035 | $2.06 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High-Density Polyethylene, Low-Density Polyethylene, Medium-Density Polyethylene, Cross-Linked Polyethylene Application: Water Supply, Gas Distribution, Sewage Treatment, Industrial Applications End User: Construction, Agriculture, Municipalities, Infrastructure Installation: Below Ground, Above Ground, Subsurface, Trenchless |
| Companies Covered | Cosmoplast Industrial Company LLC, Flying W Plastics Inc, Borouge Pte Ltd, Pipelife International GmbH, Wavin B.V., Union Pipes Industry, Al-Rowad Complex, AGRU, Saudi Arabian Amiantit Co, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Polyethylene (PE) Pipes Market Strategic Shifts & Innovations
Material science advances and installation methodology shifts are compressing project delivery timelines while elevating performance specifications across Gulf water infrastructure.
PE100-RC (resistant to cracks) resin grades are integrating into Saudi gigaproject specifications where pipe integrity under point loading is non-negotiable. National Water Company procurement teams are mandating these enhanced materials for trenchless installations beneath transportation corridors. This integration is displacing conventional PE80 grades from large-diameter trunk line tenders.
MOHAP and Saudi Arabia's National Water Company procurement rules are hardening PE-over-ductile-iron mandates for potable distribution renewals. These directives are compressing metallic pipe incumbent positions in municipal maintenance budgets. Desalination facility operators in Jubail and Yanbu are responding fastest, specifying HDPE for brine discharge and product water transmission.
Consolidated tendering by Saudi gigaproject developers is compressing supplier bases and elevating volume-scale requirements. Single-source accountability for multi-kilometer pipe runs is displacing fragmented emirate-level contracting. This concentration is most visible in NEOM and Red Sea Project water network packages where integrated EPC firms are bundling material procurement under billion-riyal awards.
GCC Polyethylene (PE) Pipes Market Segmentation
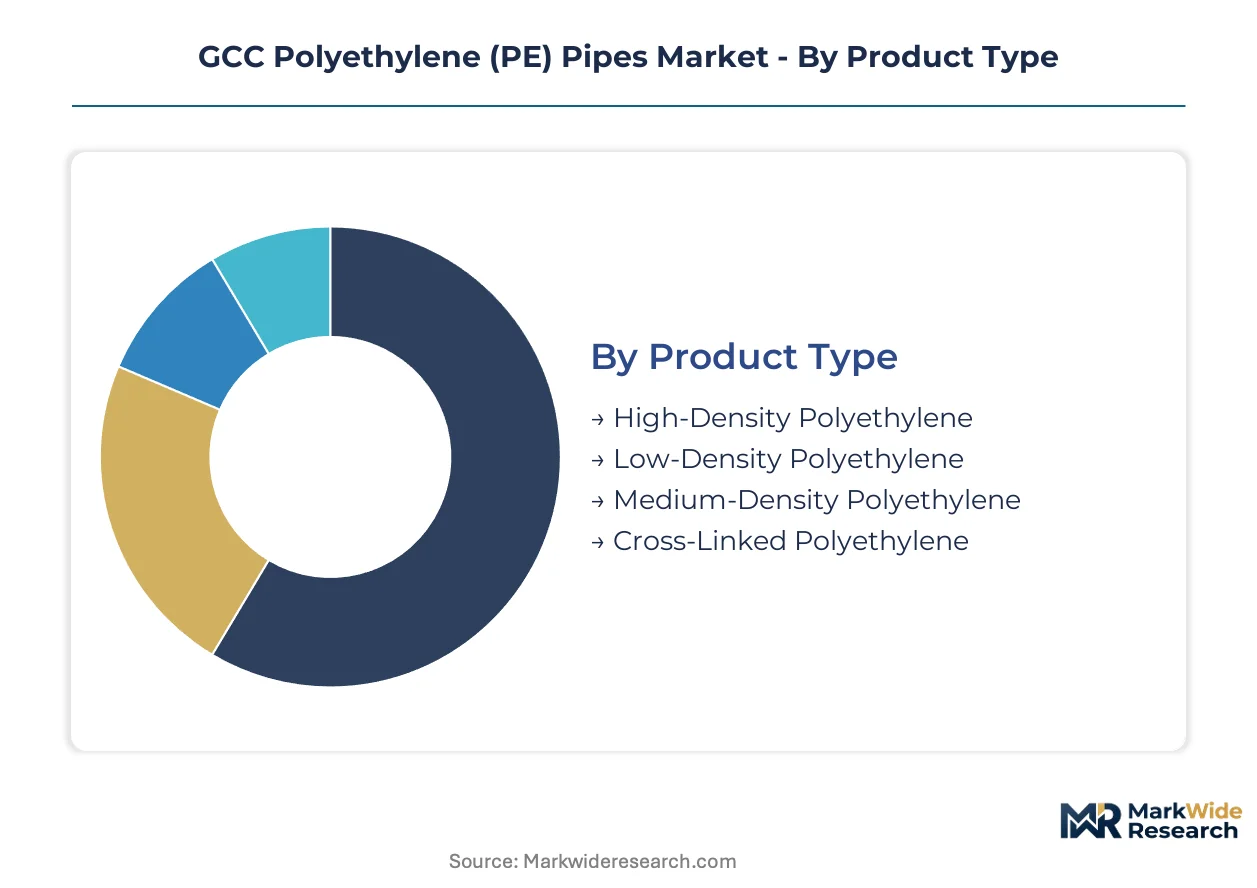
Density grades determine pressure ratings and thermal tolerance across GCC infrastructure applications, while installation methodology selection increasingly hinges on urban density constraints in Dubai and Doha. Specification divergence between commodity water supply and premium industrial service creates distinct procurement channels.
Product Type:
Density specifications govern pressure ratings from PN6 to PN25 bar and operating temperatures spanning -40°C to 60°C, with material selection driven by end-use thermal and mechanical demands.
- High-Density Polyethylene:Manufactured through extrusion of ethylene-based polymers with density above 0.941 g/cm³, delivering superior tensile strength and chemical resistance. Demand concentrates in Saudi Arabia's central province corridor where gigaproject water networks and desalination trunk lines specify HDPE for buried pressure applications. PE100-RC grades are displacing conventional PE80 from large-diameter tenders beneath transportation corridors.
- Cross-Linked Polyethylene:Produced through peroxide or silane cross-linking processes that create three-dimensional molecular networks, elevating thermal tolerance beyond standard polyethylene limits. Penetration accelerates in district cooling and solar thermal distribution across Qatar's Lusail City expansion where hot-water service specifications justify material premiums over commodity grades.
- Low-Density Polyethylene:Lower density formulations (0.910-0.925 g/cm³) provide enhanced flexibility for non-pressure drainage and irrigation lateral lines.
- Medium-Density Polyethylene:Intermediate density grades balance flexibility and strength for gas distribution networks requiring moderate pressure containment.
High-Density Polyethylene leads on scale; Cross-Linked Polyethylene leads on momentum.
Application:
End-use specifications diverge sharply between potable water infrastructure mandates and industrial process requirements, with regulatory procurement rules redirecting material selection.
- Water Supply:Potable distribution networks specify corrosion-resistant polymer conduits for buried installations where fusion-welded joint integrity outperforms metallic alternatives. SASO compliance mandates for ISO 4427-certified pipes are hardening material requirements across Saudi Arabia's municipal renewals, with National Water Company procurement rules compressing ductile iron incumbent positions.
- Gas Distribution:Pressure-rated PE systems transport natural gas across urban utility corridors where leak-tight fusion joints reduce safety risks versus mechanical connections. Qatar's FIFA legacy utility upgrades and Lusail City expansion are generating under-tendered demand for PE gas distribution specifications.
- Sewage Treatment:Chemical-resistant piping handles aggressive effluent streams in municipal wastewater infrastructure.
- Industrial Applications:Process piping specifications exclude standard HDPE where temperature ceilings exceed 60°C operational limits.
Water Supply commands procurement volume; Gas Distribution is climbing the fastest on infrastructure replacement cycles.
End User:
Procurement concentration patterns reflect public investment flows and gigaproject developer consolidation across the Gulf.
- Municipalities:Public water authorities specify PE over ductile iron for distribution renewals, with MOHAP and Saudi Arabia's National Water Company procurement rules redirecting material specifications across tender pipelines. Desalination facility operators in Jubail and Yanbu specify HDPE for brine discharge and product water transmission.
- Infrastructure:Integrated EPC firms bundle multi-kilometer pipe procurement under billion-riyal awards for NEOM and Red Sea Project water networks, compressing supplier bases and elevating volume-scale requirements.
- Construction:Private developers source certified grades for building service connections and on-site utilities.
- Agriculture:Irrigation networks specify lower-pressure LDPE formulations for lateral distribution systems.
Municipalities anchor procurement scale; Infrastructure is gaining share fastest on gigaproject consolidation.
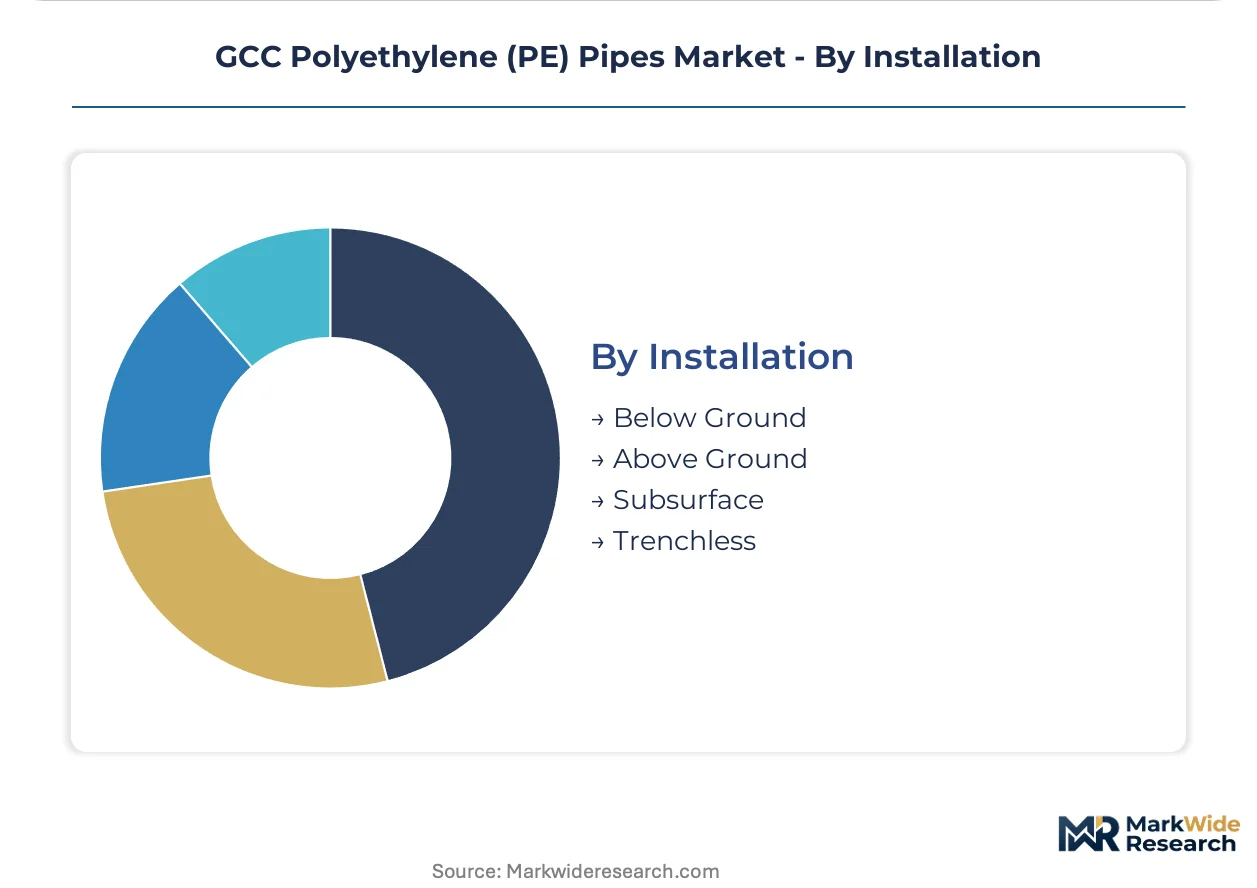
Installation:
Urban density constraints are compressing open-cut excavation viability across congested utility corridors.
- Trenchless:Horizontal directional drilling and pipe bursting methods eliminate surface disruption in Dubai and Doha where congested utility corridors prohibit open-cut excavation. National Water Company procurement teams mandate PE100-RC grades for these installations where pipe integrity under point loading is non-negotiable.
- Below Ground:Buried installations dominate water supply and gas distribution specifications across Saudi Arabia's gigaproject pipeline networks.
- Above Ground:Exposed applications concentrate in industrial process piping and temporary construction utilities.
- Subsurface:Shallow buried configurations serve building service connections and lateral distribution.
Below Ground maintains volume dominance; Trenchless shows steepest expansion trajectory on urban density constraints.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized fusion welding technicians concentrate in Saudi Arabia's Eastern Province and the UAE's industrial zones, anchoring regional installation capacity for large-diameter polyethylene infrastructure projects.
Saudi Arabia
Saudi Vision 2030 utility mandates are redirecting public procurement toward corrosion-resistant polymer networks across municipal water tenders. SASO specifications for ISO 4427-certified PE pipes are hardening material requirements for potable distribution renewals. The central province corridor is aggregating demand for large-diameter HDPE trunk lines serving gigaproject water networks and desalination expansion.
United Arab Emirates
Urban density constraints in Dubai are accelerating trenchless installation adoption where horizontal directional drilling eliminates surface disruption on congested utility corridors. ESMA approval cycles for new pipe dimensions are extending project mobilization schedules across emirate-level contracting. Abu Dhabi's petrochemical integration supplies certified PE100 resin grades to regional pipe extruders.
Qatar
FIFA legacy utility upgrades and Lusail City expansion are generating demand for PE gas distribution and drainage systems. District cooling and solar thermal distribution specifications are elevating cross-linked polyethylene penetration for hot-water service applications. Doha's urban density prohibits open-cut excavation, mandating trenchless methods for infrastructure renewal.
Kuwait
Municipal water authority procurement is specifying corrosion-resistant polymer conduits for buried installations where fusion-welded joint integrity outperforms metallic alternatives. The country's national standardization body is harmonizing certification protocols with Gulf Standardization Organization benchmarks. Industrial zones are specifying HDPE for chemical-resistant process piping in petrochemical adjacent facilities.
Oman
Desalination facility operators are specifying HDPE for brine discharge and product water transmission in coastal infrastructure zones. Public tender pipelines are redirecting material specifications toward PE over ductile iron for distribution renewals. Port and logistics corridor development is concentrating demand for large-diameter pressure pipes in Muscat and Sohar industrial zones.
GCC Polyethylene (PE) Pipes Market Key Industry Players
Capital-heavy resin producers compete with asset-light pipe extruders across the GCC polyethylene pipe value chain, creating a tiered structure where feedstock integration determines margin resilience. The market consolidates around petrochemical-backed suppliers and specialized extrusion fabricators serving distinct procurement channels. Three archetypes dominate: integrated petrochemical-resin-pipe conglomerates, independent extrusion specialists, and project-centric EPC-integrated procurement entities. Capacity expansion and strategic partnerships represent the dominant competitive moves as players secure resin supply security and installation certification capabilities.
Within the integrated petrochemical tier, Borouge Pte Ltd exemplifies feedstock-backed supply chain positioning through its Abu Dhabi petrochemical integration. Among Saudi-based fabricators, Saudi Arabian Amiantit Co occupies a position serving large-diameter infrastructure specifications tied to gigaproject networks. Cosmoplast Industrial Company LLC represents the UAE-focused distribution archetype, anchoring emirate-level contracting relationships across the federation's municipal procurement landscape.
| Leading Market Players |
|---|
| Cosmoplast Industrial Company LLC |
| Flying W Plastics Inc |
| Borouge Pte Ltd |
| Pipelife International GmbH |
| Wavin B.V. |
| Union Pipes Industry |
| Al-Rowad Complex |
| AGRU |
| Saudi Arabian Amiantit Co |
| Others |
Cost & Logistics Intelligence
Ethylene feedstock costs transmit directly from Abu Dhabi's petrochemical complexes through resin grades to extruder margins and municipal contract pricing tiers. PE100-RC certified pipes command substantial premiums over commodity PE80 grades as Saudi gigaproject developers bundle material procurement under consolidated EPC awards.
Pricing Analysis
Bundled EPC procurement dominates large-diameter trunk line awards while unbundled spot purchasing persists for emirate-level municipal maintenance contracts. Three-tier pricing structure across premium, standard, and economy levels separates PE100-RC certified grades from conventional PE100 and PE80 commodity pipes. Pricing pressure stems from crude oil volatility squeezing extruder margins on fixed-price Saudi municipal contracts. Municipal water authorities show highest price sensitivity on routine renewals; integrated gigaproject developers demonstrate lowest sensitivity due to lifecycle cost prioritization.
Supply Chain Analysis
Regional distribution centers in Jebel Ali and Dammam anchor hub-and-spoke patterns serving pipe extruders across Saudi Arabia, the UAE, and Qatar. Geographic supply concentrates in Abu Dhabi for PE100 resin, Saudi Arabia's Eastern Province for large-diameter extrusion, and the UAE for emirate-level distribution. Raw material dependencies include ethylene feedstock, peroxide cross-linking agents for PEX grades, and carbon black masterbatch for UV stabilization. Single-source vulnerability runs through Borouge's regional PE100 resin dominance. Distribution runs through project-centric EPC procurement channels for gigaprojects and fragmented contractor networks for municipal maintenance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as Saudi Vision 2030 procurement mandates displace ductile iron with corrosion-resistant polymer specifications across municipal water renewals.
For Market Incumbents: Lock in resin supply security through long-term offtake agreements with Abu Dhabi petrochemical producers before feedstock volatility intensifies. Defend position by expanding PE100-RC certification capabilities to capture trenchless installation specifications where National Water Company procurement teams mandate enhanced crack resistance. Prioritize fusion welding technician training capacity in Saudi Arabia's Eastern Province to alleviate installation bottlenecks threatening project delivery timelines. For New Entrants and Emerging Players: The price-point gap between premium PE100-RC certified grades and economy PE80 commodity pipes creates entry space for mid-tier PE100 specialists. Target Qatar's under-tendered gas distribution and drainage systems where FIFA legacy utility upgrades outpace established supplier capacity. Pursue district cooling and solar thermal distribution specifications for cross-linked polyethylene penetration where hot-water service premiums justify material cost differentials. For Investors and Strategic Acquirers: Consolidation pressure builds where fragmented emirate-level contracting yields to integrated EPC procurement under billion-riyal gigaproject awards. Long-term viability favors pipe extruders with backward integration into resin supply or captive access to certified PE100 grades. Monitor NEOM and Red Sea Project completion schedules as inflection indicators for demand surges in large-diameter HDPE trunk lines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Supply | Captive PE100 feedstock secures margin resilience against crude oil volatility. |
| PE100-RC Certification Investment | Enhanced crack resistance qualifies extruders for National Water Company trenchless mandates. |
| Fusion Welding Training Expansion | Technician scarcity in Saudi Arabia's Eastern Province threatens installation capacity. |
| Qatar Market Entry | FIFA legacy upgrades and Lusail City expansion generate under-served demand. |
| Gulf Standardization Organization Alignment | Unified certification protocols reduce cross-border testing burdens for multi-emirate contractors. |
Research Approach
Direct dialogue with pipe extrusion plant managers, EPC procurement directors, municipal water authority engineers, and fusion welding certification trainers grounded qualitative findings in operational reality. Secondary validation drew from SASO and ESMA regulatory filings, Gulf Standardization Organization harmonization protocols, National Water Company tender documentation, and customs trade data on PE resin imports. Bottom-up project pipeline enumeration triangulated against top-down petrochemical capacity assessments.
Segment-level outputs across density grades, application categories, end-user archetypes, and installation methodologies informed the analytical framework over the projection horizon. CAGRs derived from regression against desalination capacity additions, gigaproject award timelines, and municipal renewal cycles. Industry-specific inputs included PE100-RC grade penetration assumptions and trenchless installation adoption curves in Dubai and Doha.
The model assumes a particular technology adoption path for PE100-RC resin grades; alternative pathways for conventional PE80 retention would alter the outlook for extruder capacity utilization. Forecasts reflect assumptions on Saudi Vision 2030 procurement enforcement, ethylene feedstock price trajectories, and fusion welding technician training pipeline expansion. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pipes and Tubes
Cryogenic Pipes Market
Pipes and Tubes
Global Copper Pipes and Tubes Market
Pipes and Tubes
Cold Drawn Seamless (CDS) Steel Pipes Market
Pipes and Tubes
PVDF Pipes Market
Pipes and Tubes
Pipe Market
Pipes and Tubes
Heat Shrink Tubing Market
Pipes and Tubes
PVC Pipes Market
Pipes and Tubes
Tapping Sleeves Market
Pipes and Tubes
Industrial Blast Hoses Market
Pipes and Tubes
Pipeline Processing and Pipeline Services Market
Pipes and Tubes
Welded Pipes Market
Pipes and Tubes
Global Polypropylene Pipes Market
Pipes and Tubes
China Industrial Hoses Market
Pipes and Tubes
Acid Resistant Pipe Market
Pipes and Tubes
Hydrogen Tube Skids Market
Pipes and Tubes
Global Tracer Wires Market