
 Fttx Pipes Market | 2026-2036
Fttx Pipes Market Size, Share, and Industry Trends Forecast 2026-2036
Fttx Pipes Market Analysis
The skilled fiber-optic construction workforce is collapsing across multiple markets, constraining deployment timelines and forcing pipe suppliers to prioritize pre-connectorized and push-fit duct solutions. Orbia leverages its vertical integration in polymer compounds to secure resin supply for HDPE duct production. Furukawa Electric Co., Ltd. anchors its position through advanced multi-lumen microduct designs that reduce installation labor hours. Apollo Pipes competes on cost-optimized PVC offerings for secondary distribution networks in price-sensitive regions.
FTTx pipes are specialized conduits—typically HDPE, PVC, or composite constructions with inner diameters ranging from 7mm to 40mm—engineered to protect fiber-optic cables from moisture, crush loads, and thermal expansion during underground or aerial deployment. HDPE dominates product type demand due to its flexibility, chemical resistance, and suitability for trenchless installation methods that minimize civil works disruption. Ducted and direct buried installation methods represent the largest volume pools, while trenchless techniques capture the fastest expansion as municipalities restrict open-cut permits in urban cores. Among end users, telecom operators and internet service providers command the premium segment through specifications demanding decades-long service life certification.
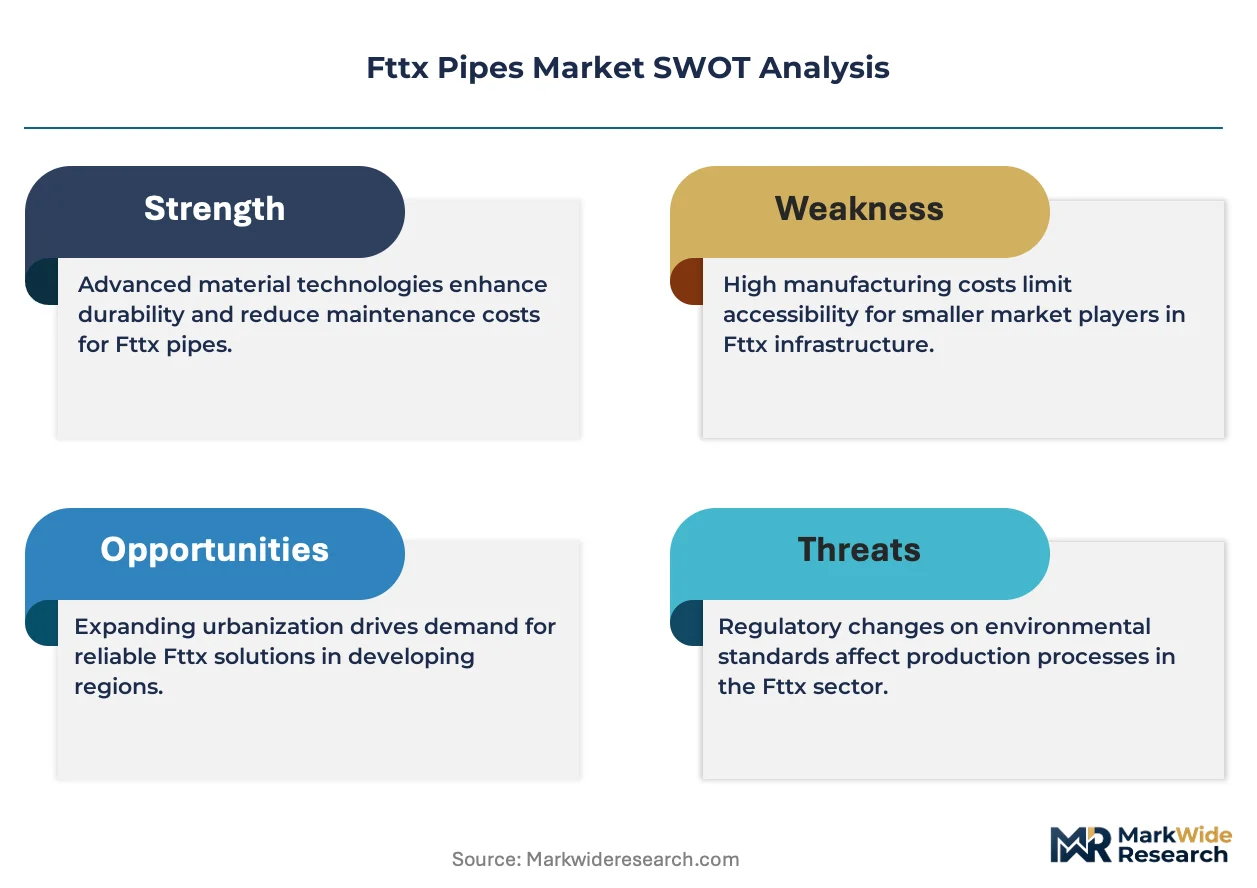
Regulatory frameworks including the FCC's broadband equity programs in the United States, India's BIS standards for telecom ducts, and the EU Green Deal's circular economy requirements for polymer recyclability collectively shape product compliance and market access conditions. These standards push manufacturers toward post-consumer recycled content verification and carbon footprint disclosure. Stakeholders must monitor how permitting velocity and labor availability interact to determine which installation method and material combination wins in each metropolitan deployment cycle.
Market Dynamics
The skilled fiber-optic construction workforce is collapsing across multiple markets, constraining deployment timelines and forcing pipe suppliers to prioritize pre-connectorized and push-fit duct solutions that compress installation labor hours.
Growth Catalysts
- FCC Broadband Equity Programs:The United States federal funding mandates accelerate fiber-to-the-home infrastructure buildouts, creating sustained demand for HDPE and composite duct systems in underserved census tracts.
- India's BIS Telecom Duct Standards:Mandatory certification requirements for polymer duct quality and dimensional consistency are formalizing procurement specifications among state-owned telecom operators and private ISPs.
- Trenchless Horizontal Directional Drilling:Municipal permitting restrictions on open-cut excavation in urban cores are redirecting installation method preferences toward microduct and multi-lumen configurations that minimize civil works disruption.
Market Restraints
- Polymer Resin Price Volatility:Ethylene and propylene feedstock cost fluctuations transmit directly to HDPE and PVC duct manufacturing margins, compressing profitability for non-integrated producers.
- Single-Source Silica Supply Concentration:Optical fiber preform manufacturing concentrates in a limited geography, creating upstream bottleneck risk that constrains downstream duct demand visibility.
- Copper Network Inertia:Legacy DSL infrastructure in aging suburban developments delays fiber overbuild economics, extending payback periods for greenfield FTTx pipe deployment.
Strategic Opportunities
- EU Green Deal Circular Economy Mandates:Post-consumer recycled content verification requirements for polymer products are creating first-mover advantage for duct manufacturers with certified closed-loop recycling capabilities.
- 5G Fronthaul Microduct Bundles:Dense urban small cell deployments require fiber-dense cable assemblies that integrate multiple microducts within a single outer sheath, expanding addressable product scope.
- Direct-to-Contractor Digital Distribution:E-procurement platforms serving fiber construction contractors are disintermediating traditional distributor networks, enabling margin capture and demand data access for pipe manufacturers.
Industry Challenges
- Fiber Splicing Technician Shortage:The specialized skill required for fusion splicing and optical testing is contracting faster than training program output, extending project commissioning timelines and inflating labor cost structures.
- Multi-Jurisdictional Permitting Complexity:FTTx deployments spanning municipal, county, and state boundaries encounter inconsistent right-of-way regulations and utility coordination requirements that stall construction velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fttx Pipes Market |
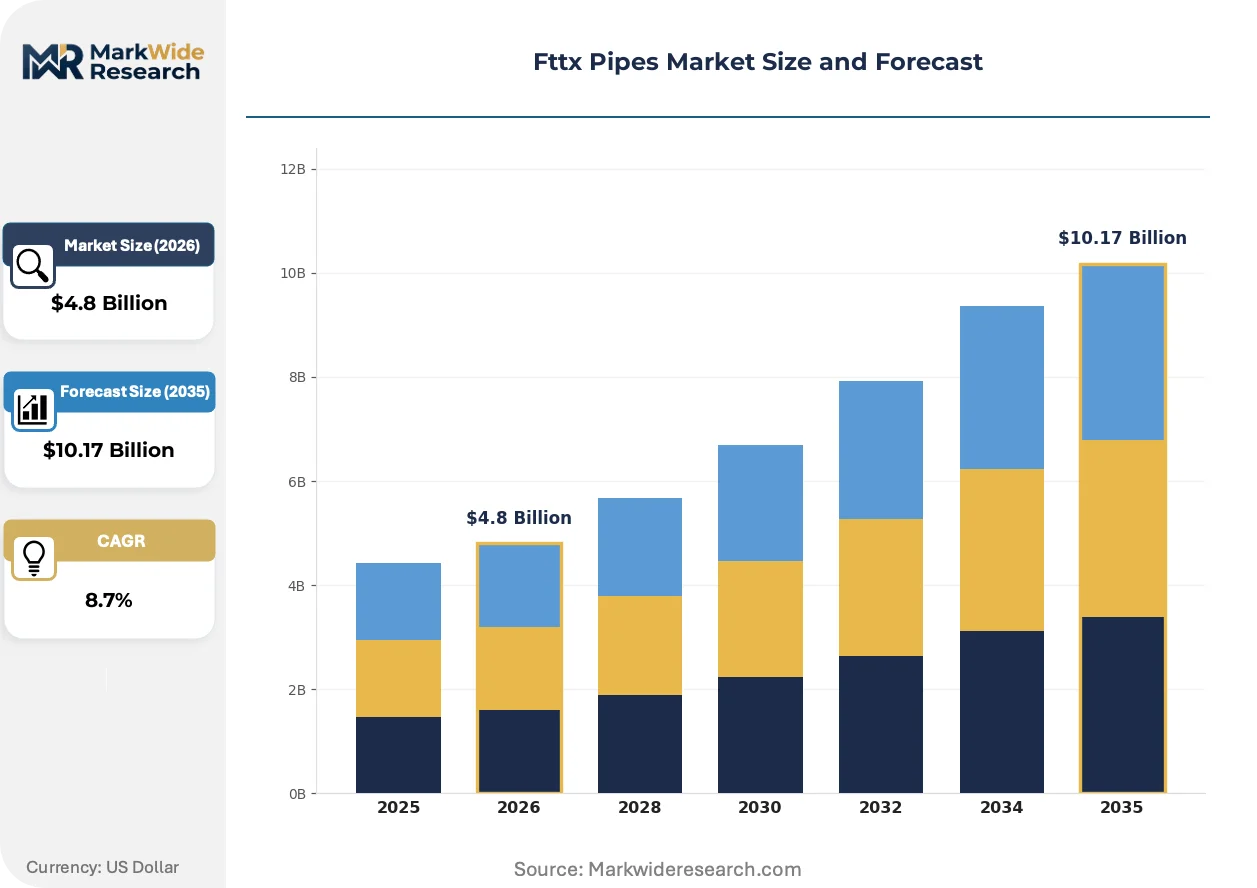
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: HDPE, PVC, Steel, Concrete Installation Method: Direct Buried, Aerial, Ducted, Trenchless End User: Telecom Operators, Internet Service Providers, Municipalities, Contractors Application: Broadband Networks, Fiber Optic Networks, Data Centers, Residential Areas |
| Companies Covered | Apollo Pipes, Orbia, Furukawa Electric Co., Ltd., Craley Group Limited, Evopipes, GM Plast, Gabo Systemtechnik GmbH, Himachal Futuristic Communications Limited, KNET Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fttx Pipes Market Emerging Trajectories
Material science advances and installation method evolution are compressing deployment economics while regulatory pressure on polymer recyclability is reshaping manufacturer investment priorities across the value chain.
Multi-lumen microduct architectures are displacing traditional single-bore HDPE pipes in dense urban deployments. Tier-1 telecom operators in Japan and South Korea specify these configurations to maximize fiber count per trench while minimizing restoration costs. The technology is displacing conventional duct specifications in metropolitan cores where civil works dominate total project cost.
The EU Green Deal's circular economy requirements for polymer recyclability are mandating post-consumer recycled content verification and carbon footprint disclosure across construction material supply chains. Manufacturers must redesign formulations to maintain mechanical performance with recycled HDPE feedstocks. Duct products destined for European public infrastructure tenders face the most stringent compliance timelines.
Consolidated procurement by national broadband program administrators is compressing supplier negotiation cycles and unbundling after-sales technical support. State-level aggregators in India and municipal purchasing cooperatives in the United States are replacing fragmented contractor-level ordering. This concentration is most visible in India's BHARAT NET phase implementation, where centralized tendering favors manufacturers with scale-certified quality systems.
Fttx Pipes Market Segmentation
FTTx pipe procurement patterns diverge sharply across material grades, installation techniques, and customer archetypes. Understanding these fault lines reveals which specifications command premium pricing versus which segments compete on pure cost efficiency.
Product Type:
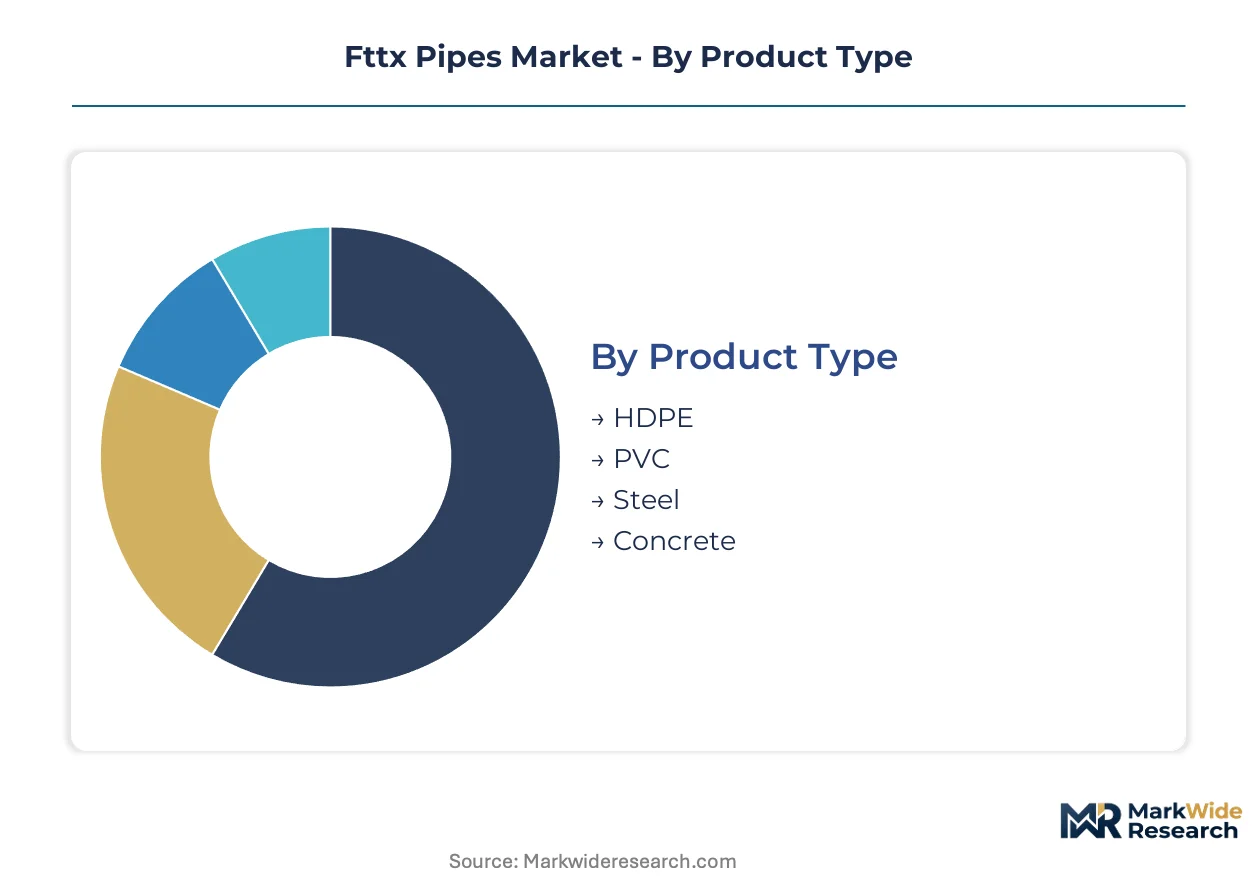
HDPE and PVC formulations dominate domestic consumption in India, China, and the United States, while steel and concrete variants serve export-led infrastructure projects in Middle Eastern and African markets where trenching conditions are most severe.
- HDPE:High-density polyethylene formulations deliver flexibility, chemical resistance, and suitability for horizontal directional drilling. Demand concentrates among United States telecom operators deploying fiber-to-the-home under FCC broadband equity mandates, where trenchless methods minimize civil works disruption in urban cores.
- PVC:Rigid polyvinyl chloride constructions offer cost-optimized protection for secondary distribution networks. India's state-owned operators under BHARAT NET procurement specifications favor PVC for rural trunk routes where installation labor costs outweigh material performance premiums.
- Steel:Galvanized or stainless steel pipes provide crush resistance in heavy-load environments such as railway crossings and industrial zones.
- Concrete:Reinforced concrete ducting serves specialized applications requiring maximum mechanical protection in extreme soil conditions or flood-prone geographies.
HDPE holds the largest share; momentum sits with PVC as India's national broadband program accelerates rural trunk deployment.
Installation Method:
Cost tier stratification separates premium trenchless techniques from economy-grade direct burial, with aerial methods occupying a mid-tier position for rapid suburban overbuilds.
- Direct Buried:Cables laid directly in excavated trenches without protective conduit represent the lowest-cost deployment path. Municipalities in India's tier-2 and tier-3 cities specify direct burial for BHARAT NET phase implementation where capital constraints override lifecycle durability concerns.
- Trenchless:Horizontal directional drilling and microtunneling eliminate surface disruption in dense urban cores. United States operators in metropolitan markets face municipal permitting restrictions on open-cut excavation, redirecting preference toward microduct configurations that compress restoration timelines.
- Aerial:Pole-mounted deployment leverages existing utility infrastructure for rapid suburban and semi-urban coverage extension.
- Ducted:Conduit-based systems enable future fiber pulls and cable upgrades without additional excavation.
Direct buried claims the greatest volume; trenchless methods are climbing the fastest as urban permitting tightens across multiple jurisdictions.
End User:
Customer type determines specification rigor, with telecom operators demanding decades-long service certification while contractors prioritize installation speed and material handling efficiency.
- Telecom Operators:Tier-1 carriers and national incumbents specify HDPE multi-lumen microducts with verified mechanical performance under IEC standards. Japan and South Korea operators drive specification evolution for dense urban small cell fronthaul requiring maximum fiber count per trench.
- Contractors:Fiber construction firms prioritize pre-connectorized and push-fit duct solutions that compress installation labor hours amid skilled technician shortages. Digital procurement platforms serving this segment are disintermediating traditional distributor networks.
- Internet Service Providers:Regional and competitive local exchange carriers balance performance requirements against capital constraints in overbuild scenarios.
- Municipalities:City governments and utility authorities specify duct systems for smart city infrastructure and traffic management fiber networks.
Telecom operators command the premium tier; contractors represent the steepest expansion trajectory as workforce constraints reshape procurement priorities.
Application:
Volume concentration sits with broadband access networks, while data center interconnects and residential fiber drops represent emerging specification battlegrounds.
- Broadband Networks:Fiber-to-the-home and fiber-to-the-building deployments constitute the foundational demand pool. India's BIS telecom duct standards formalize procurement specifications for state-owned operators rolling out national broadband infrastructure.
- Fiber Optic Networks:Backbone and metro fiber routes require high-capacity duct systems with future-proofing for cable upgrades. United States rural broadband programs under federal funding mandates sustain demand for HDPE and composite duct systems in underserved census tracts.
- Data Centers:Hyperscale facility interconnects and campus networks demand specialized high-density microduct bundles.
- Residential Areas:Last-mile distribution to individual premises requires cost-efficient single-bore or dual-bore configurations.
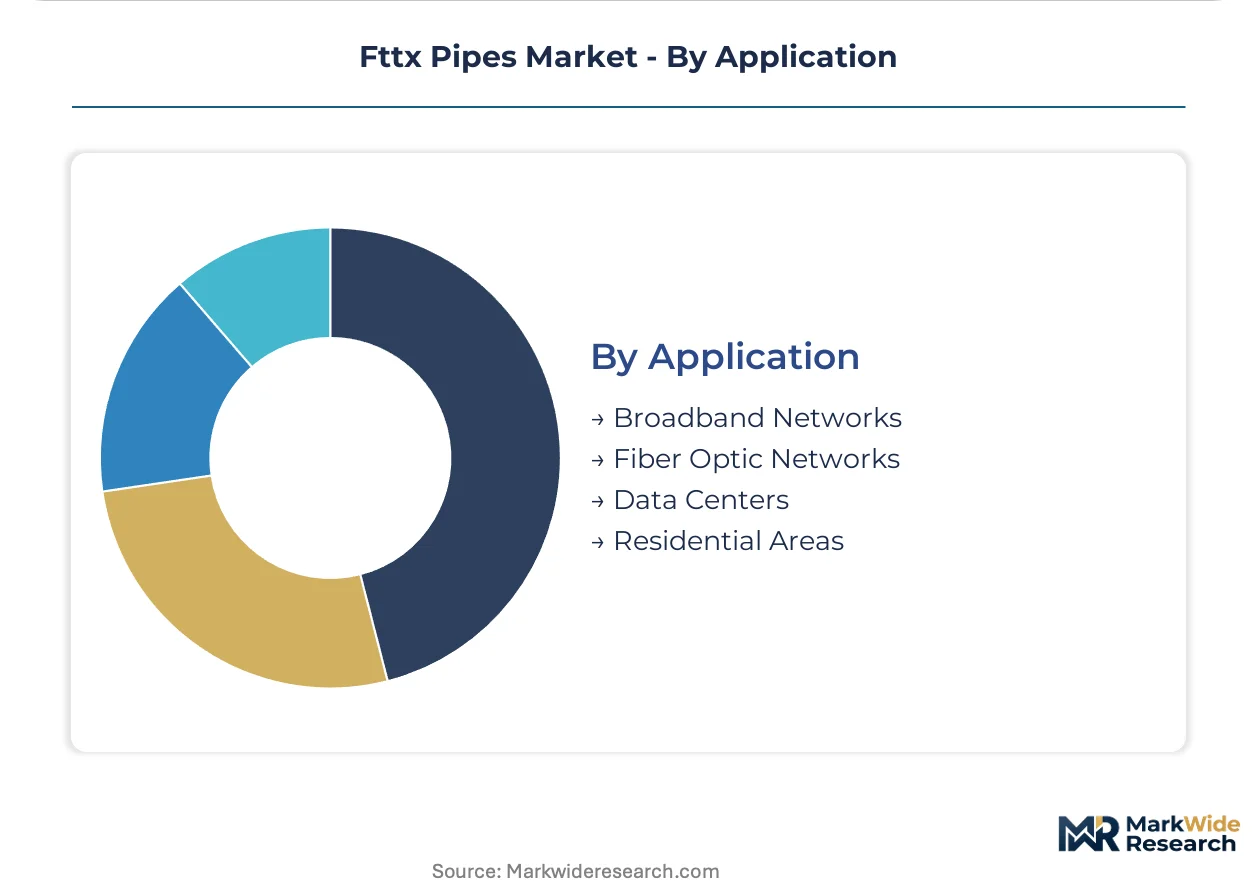
Broadband networks anchor volume; data center applications are gaining share fastest as cloud infrastructure investment accelerates inter-facility connectivity requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across major markets. United States operators prioritize trenchless HDPE microducts for urban fiber builds, while India favors cost-optimized PVC for rural trunk routes under national broadband mandates.
United States
FCC broadband equity programs sustain fiber-to-the-home deployment velocity across underserved census tracts. Municipal permitting restrictions in metropolitan cores redirect installation preferences toward horizontal directional drilling methods. Texas and California anchor deployment volume, with Dallas-Fort Worth and Los Angeles metro areas driving multi-lumen microduct procurement.
India
BHARAT NET phase implementation accelerates rural trunk network construction for state-owned telecom operators. BIS telecom duct standards formalize polymer quality and dimensional certification requirements. Maharashtra and Gujarat concentrate manufacturing capacity, with Pune and Ahmedabad industrial corridors supplying PVC and HDPE duct systems for nationwide distribution.
China
Dual carbon goals and MIIT fiber infrastructure targets shape polymer procurement specifications for 5G backhaul and residential broadband expansion. Yangtze River Delta manufacturing clusters in Jiangsu and Zhejiang provinces dominate domestic HDPE duct production. Shanghai and Suzhou anchor R&D activity for composite duct formulations.
Germany
EU Green Deal circular economy mandates enforce post-consumer recycled content verification for polymer construction materials. REACH compliance and carbon footprint disclosure requirements reshape manufacturer investment priorities. North Rhine-Westphalia and Bavaria concentrate duct fabrication, with Düsseldorf and Munich serving as specification-setting hubs for European telecom infrastructure.
Japan
METI digital infrastructure programs and JIS standards drive premium multi-lumen microduct adoption for dense urban small cell deployments. Tier-1 operators specify decades-long service life certification for fiber-dense cable assemblies. Kanto and Kansai regions anchor demand, with Tokyo and Osaka metropolitan areas leading specification evolution for 5G fronthaul infrastructure.
Fttx Pipes Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in the FTTx pipes market. Consolidated polymer compounders with captive resin supply compete against regional fabricators focused on cost-optimized formulations. Three archetypes define positioning: vertically integrated material-science leaders, installation-method specialists, and price-focused commodity suppliers. Capacity expansion in South Asia and strategic partnerships for recycled content certification represent the dominant competitive vectors.
Among integrated material-science leaders, Orbia leverages polymer compound expertise to secure resin supply chains for HDPE duct production. Furukawa Electric Co., Ltd. anchors the specialist tier through advanced microduct architectures that reduce installation labor requirements. Apollo Pipes occupies a position within the cost-optimized segment, serving secondary distribution networks in price-sensitive regional markets.
| Leading Market Players |
|---|
| Apollo Pipes |
| Orbia |
| Furukawa Electric Co., Ltd. |
| Craley Group Limited |
| Evopipes |
| GM Plast |
| Gabo Systemtechnik GmbH |
| Himachal Futuristic Communications Limited |
| KNET Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
Recycled HDPE feedstock substitution for virgin resin is redrawing procurement geography toward European recyclers with EU Green Deal certification, simultaneously compressing material cost differentials and elevating compliance premiums for non-certified producers.
Pricing Analysis
Long-term offtake contracts dominate procurement between tier-1 telecom operators and integrated compounders, insulating buyers from ethylene spot volatility while locking suppliers into fixed-margin structures. Price differentiation rests on IEC certification tier and volume scale, with BHARAT NET aggregators commanding steepest discounts against premium multi-lumen specifications. Cost compression in standard-grade PVC is intensifying because Apollo Pipes and regional competitors expand Indian manufacturing capacity. Municipal contractors exhibit highest price sensitivity, while Japan's METI-funded operators accept material premiums for decades-long service warranties.
Supply Chain Analysis
Inventory cycles stretch to 8-12 weeks for specialized microduct configurations as resin qualification protocols extend lead times for recycled-content formulations. Manufacturing gravity centers on India, China, and the United States, with Maharashtra and Jiangsu provinces feeding domestic broadband programs. Feedstock supply draws from ethylene crackers in the US Gulf Coast and naphtha-based complexes in East Asia, exposing margins to crude-oil linkage volatility. Single-source vulnerability concentrates in optical fiber preform supply, constraining downstream duct demand visibility. Distribution runs through national broadband program administrators and emerging e-procurement platforms serving fiber construction contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The FTTx pipes market sits at an inflection where FCC broadband equity mandates and EU circular economy requirements simultaneously expand addressable demand and reshape compliance economics for material sourcing.
For Market Incumbents: Fortify resin supply security through backward integration or captive offtake agreements with Gulf Coast ethylene producers, insulating margins from feedstock volatility that erodes non-integrated competitors. Accelerate post-consumer recycled content certification to meet EU Green Deal tender requirements before compliance windows close, converting regulatory burden into procurement preference.
For New Entrants and Emerging Players: Anchor in India's tier-2 city contractor segment, where BHARAT NET phase implementation outruns established supplier capacity and price-sensitive procurement favors agile local fabricators. Pursue digital distribution partnerships with e-procurement platforms serving fiber construction firms, bypassing traditional distributor markups while capturing demand data.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional pipe fabricators in South Asia lacking recycled-content certification but holding established BIS compliance and state-level tender relationships. Monitor EU public infrastructure tender award patterns as the inflection signal—first-mover certification advantages will concentrate procurement share before compliance mandates fully phase in.
| Strategic Initiative | Industry Significance |
|---|---|
| Recycled Content Certification Investment | EU Green Deal compliance unlocks premium public infrastructure tender access across Germany and France. |
| Backward Integration into Resin Supply | Gulf Coast ethylene offtake agreements insulate HDPE margins from propylene feedstock volatility. |
| Multi-Lumen Microduct Capacity Expansion | Tokyo and Osaka 5G fronthaul specifications drive specification migration toward fiber-dense configurations. |
| E-Procurement Platform Partnership | Direct contractor channel access disintermediates distributor networks and captures real-time demand signals. |
| BIS Quality System Certification | Centralized BHARAT NET tendering favors scale-certified manufacturers over fragmented regional suppliers. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with polymer procurement directors at telecom operators, fiber construction contractor operations heads, and HDPE compounding plant managers; and secondary validation through FCC broadband program disbursement records, BIS certification registries, EU tender award databases, and SEC filings from listed pipe manufacturers. Triangulation across bottom-up project pipeline assessments and top-down national broadband program budget allocations anchored volume estimates.
Across the projection horizon, the analytical framework modeled demand by material grade, installation method, end-user archetype, and regional regulatory cluster. CAGRs derived from deployment velocity assumptions tied to named national broadband mandates, with sensitivity testing against resin price scenarios and labor availability constraints. Forecast inputs incorporated municipal permitting velocity indices and recycled-content compliance phase-in schedules.
Decision-makers should treat outputs as directional under sustained federal funding commitment and resin supply stability assumptions; material deviation in either would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pipes and Tubes
Chlorinated Polyvinyl Chloride (Cpvc) Pipes Market
Pipes and Tubes
China Industrial Hoses Market
Pipes and Tubes
Steel Roll-On Tube Market
Pipes and Tubes
Hot Dip Galvanized Steel Pipe Market
Pipes and Tubes
Global Polyolefin Pipes Market
Pipes and Tubes
Global Polyethylene Pipes and Fittings Market
Pipes and Tubes
Steel Pipes and Tubes Market
Pipes and Tubes
Pneumatic Fittings Market
Pipes and Tubes
Copper Tube Market
Pipes and Tubes
Glass Reinforced Epoxy (GRE) Pipes Market
Pipes and Tubes
Global Tracer Wires Market
Pipes and Tubes
Welded Pipes Market
Pipes and Tubes
HDPE Pipes Market
Pipes and Tubes
Global Lance Tubes Market
Pipes and Tubes
United States Copper Pipes and Tubes Market
Pipes and Tubes
GCC CPVC Pipes Market