
 Saudi Arabia Copper Pipes and Tubes Market | 2026-2036
Saudi Arabia Copper Pipes and Tubes Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Copper Pipes and Tubes Market Outlook
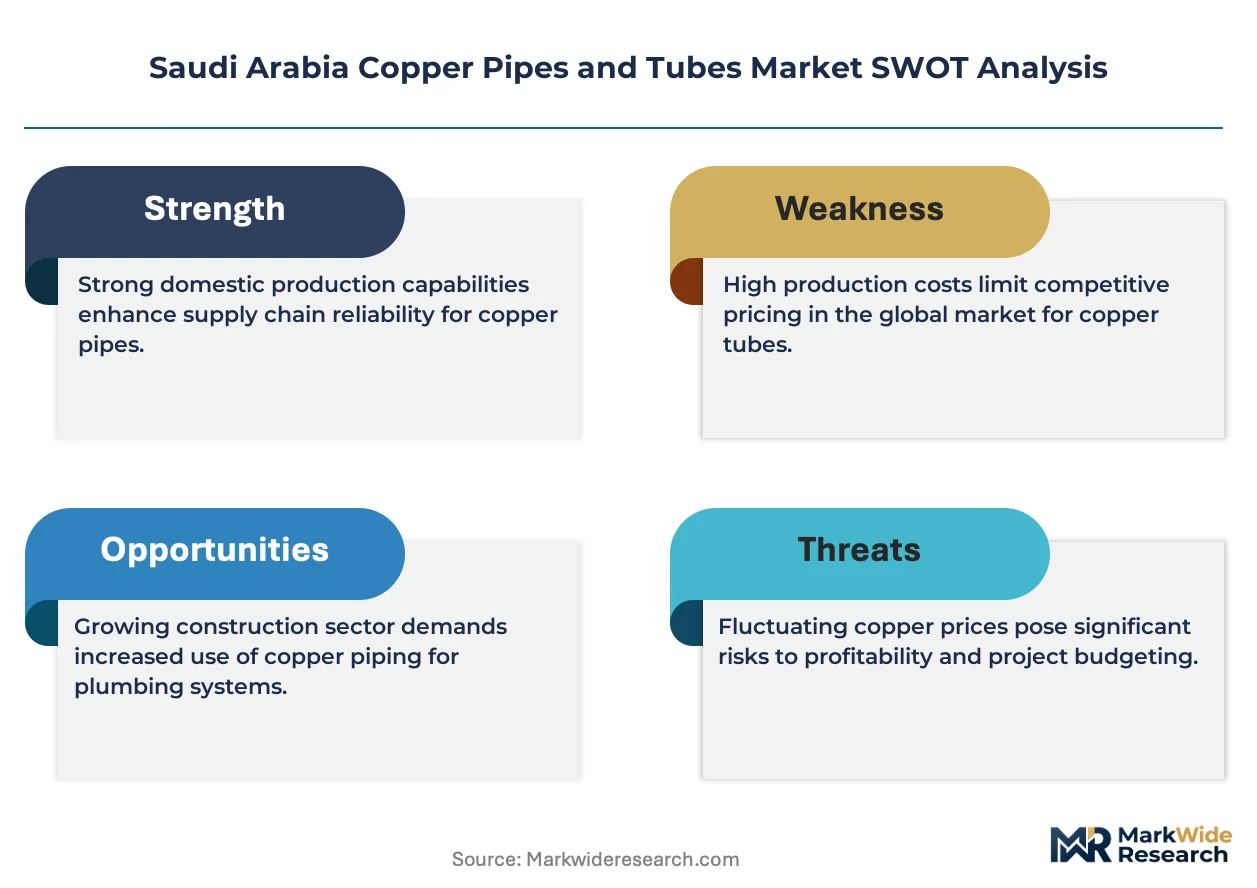
Saudi Vision 2030 green building targets is broadening copper tube specification across megaproject developments. Aurubis AG leverages its European smelting base to supply high-purity feedstock for Saudi fabricators. Mueller Industries anchors North American technical standards in its Middle East distribution strategy. Cool Plus Trading Est. competes through specialized HVAC inventory held in Jeddah and Dammam warehouses.
Copper pipes and tubes are hollow cylindrical conductors fabricated from copper alloys, typically containing 99.9% pure copper with trace phosphorus or deoxidized grades, manufactured through extrusion, drawing, or welding processes to achieve precise wall thickness and diameter tolerances for fluid transport and heat exchange. Seamless tubes dominate high-pressure applications where burst resistance and leak integrity justify premium pricing, while coiled pipes capture growing share in residential plumbing for reduced joint count and faster installation. Welded tubes occupy the cost-sensitive volume tier, particularly in commercial HVAC trunk lines where operating pressures remain moderate.
SFDA and SASO standards govern material composition and pressure ratings for potable water and building services applications, with SASO certification mandatory for all imported copper products entering the Kingdom. The Saudi Building Code, enforced by municipal authorities in Riyadh, Jeddah, and Dammam, mandates minimum thermal performance thresholds that elevate copper over polymer alternatives in climate system specifications. Stakeholders must monitor gigaproject procurement calendars and localization requirements under the National Industrial Development Center to align capacity investments with demand timing.
Market Dynamics
Saudi gigaproject procurement calendars are compressing order windows for copper tube suppliers, forcing fabricators to pre-position inventory ahead of construction mobilization phases that now run on 18-month cycles rather than traditional 36-month timelines.
Growth Catalysts
- Saudi Building Code thermal mandates:Municipal enforcement in Riyadh, Jeddah, and Dammam now requires minimum conductivity thresholds that exclude polymer alternatives from climate system specifications.
- District cooling network expansion:HVAC contractors in the Central Region are scaling copper tube procurement for chilled water distribution systems serving NEOM and Red Sea Project zones.
- SFDA potable water certification:Mandatory SASO marking for imported copper products creates preference for pre-certified feedstock that accelerates customs clearance and project commissioning.
Market Restraints
- Copper cathode price volatility:LME pricing fluctuations transmit directly to tube fabrication costs, squeezing margin buffers for distributors serving fixed-price construction contracts.
- European smelter concentration:High-purity feedstock dependence on Aurubis and limited alternative sources exposes Saudi fabricators to shipment delays through Suez Canal routing constraints.
- Cross-linked polyethylene substitution:PEX tubing captures residential plumbing share where pressure ratings permit, particularly in villa developments outside municipal district cooling zones.
Strategic Opportunities
- Eastern Province industrial localization:Ras Al-Khair and Jubail manufacturing zones offer tariff advantages for tube fabrication facilities serving Aramco and SABIC process cooling demand.
- Desalination plant retrofits:Existing thermal desalination facilities require copper alloy tubing replacements that match original seawater corrosion specifications.
- Smart building BMS integration:Copper tube specification now bundles with sensor-ready infrastructure for gigaproject developments targeting LEED-equivalent certification.
Industry Challenges
- Pressure vessel welder certification:SASO-authorized testing facilities in Dammam and Riyadh face backlogs that delay qualified workforce deployment to fabrication sites.
- Legacy plumbing contractor conversion:Traditional galvanized iron installers require retraining on copper brazing techniques and oxygen-acetylene safety protocols before gigaproject site access.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Copper Pipes and Tubes Market |
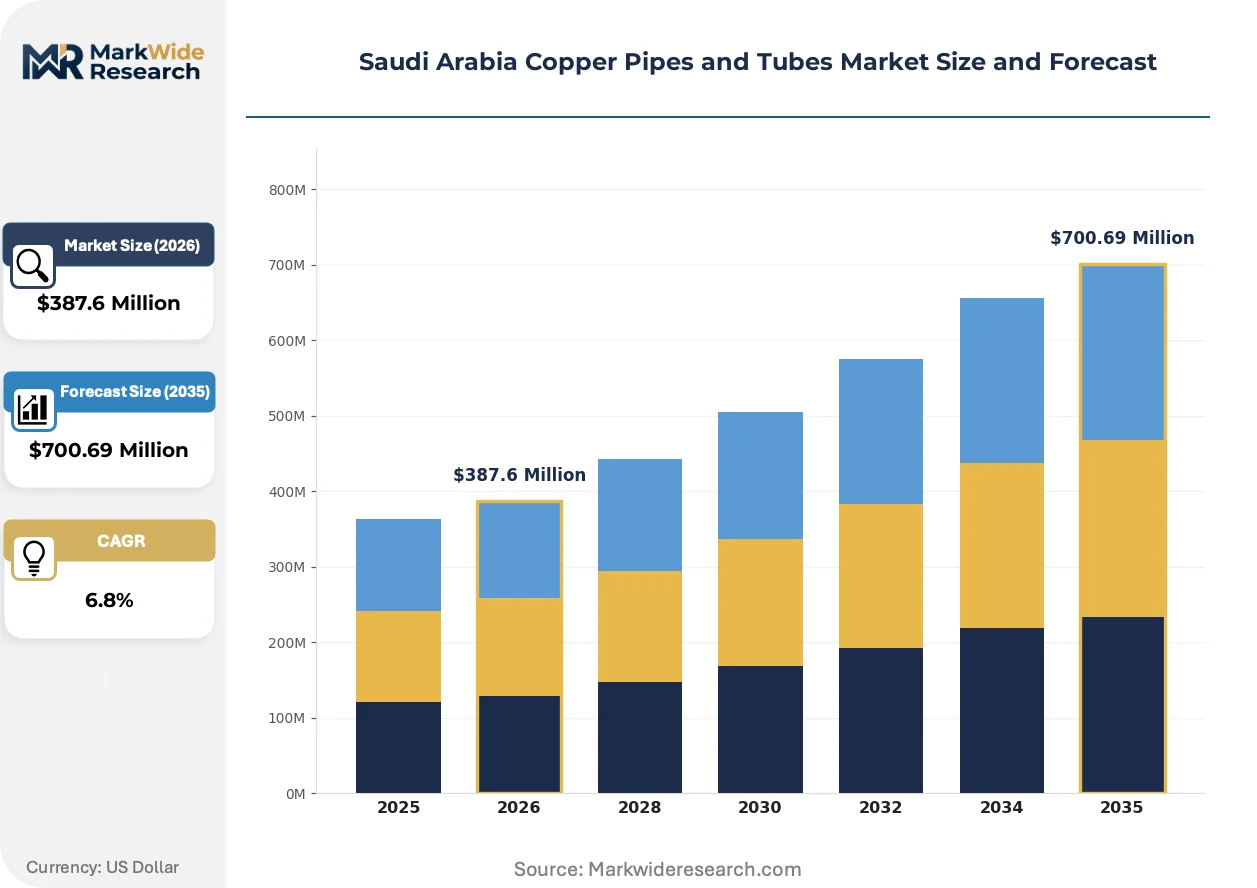
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $700.69 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Seamless Tubes, Welded Tubes, Coiled Pipes, Straight Pipes Application: Plumbing, HVAC, Electrical, Construction End User: Residential, Commercial, Industrial, Utilities Size: Small Diameter, Medium Diameter, Large Diameter, Custom Size |
| Companies Covered | MM Kembla, Cool Plus Trading Est., Aurubis AG, Sawaed International Trading Est., Cannelle Holdings FZCO, Mueller Industries, Techno Cool Co., C-Flo Copper, Mehta Tubes Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Copper Pipes and Tubes Market Strategic Shifts
Automation of tube fabrication and inspection processes is compressing lead times while regulatory pressure on thermal performance is locking in material specifications ahead of construction mobilization.
Laser-guided orbital welding systems are automating joint formation in high-purity copper tube assemblies for semiconductor-grade cooling loops. Medical device and data center contractors in Riyadh are specifying these systems for leak-critical installations. The technology is automating quality assurance steps that previously required manual dye-penetrant inspection, reducing fabrication labor hours by half.
SASO has tightened traceability requirements for copper alloy composition in potable water applications, mandating mill test reports for every heat lot entering the Kingdom. Fabricators must now maintain batch records linking raw cathode to finished tube for ten-year retention periods. Large HVAC contractors are responding by qualifying only suppliers with integrated smelter-to-tube documentation chains.
Consolidated procurement desks at Saudi Real Estate Infrastructure Company and similar gigaproject developers are displacing fragmented contractor purchasing. These centralized buying functions negotiate annual frame agreements that lock in volume commitments and price bands. The shift is most visible in Riyadh, where Qiddiya and Diriyah Gate developments now route all copper tube orders through single-source supply agreements rather than distributed subcontractor procurement.
Saudi Arabia Copper Pipes and Tubes Market Segmentation
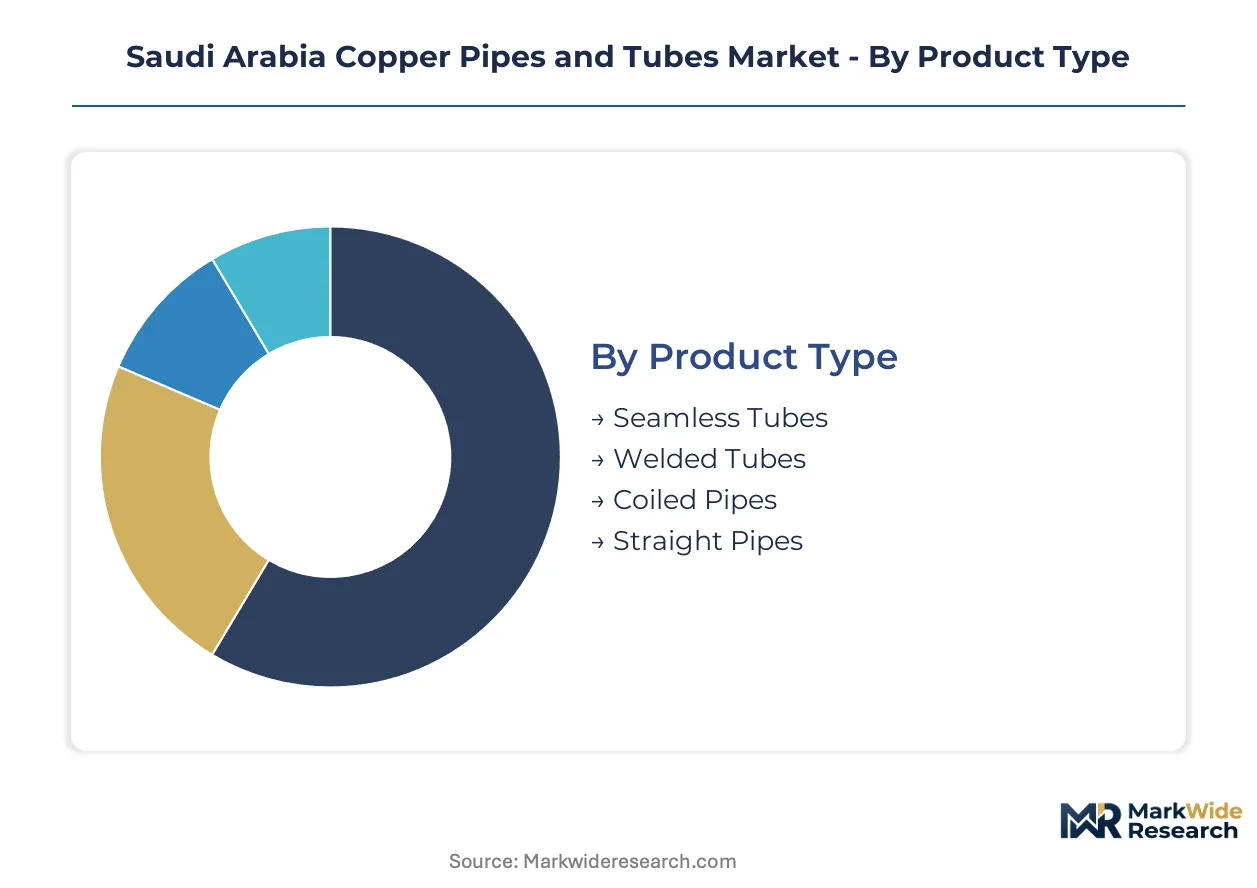
Copper pipe and tube specifications in Saudi Arabia diverge sharply across installation contexts. Product form, diameter class, and end-use environment each impose distinct technical requirements that shape procurement patterns among Riyadh gigaproject developers and Jeddah HVAC contractors.
Product Type:
Upgrade cycles in Saudi district cooling networks favor tube geometries that minimize joint count and accelerate field installation. Fabricators serving NEOM and Red Sea Project zones pre-position inventory based on anticipated replacement schedules for chiller plant piping.
- Seamless Tubes:Extruded from solid copper billet without longitudinal weld seams, these tubes withstand burst pressures exceeding 300 bar in high-rise plumbing risers. Riyadh's Qiddiya development specifies seamless construction for potable water distribution where leak integrity overrides cost considerations.
- Welded Tubes:Formed from copper strip stock with electric resistance or TIG welding along the longitudinal seam, offering wall thickness consistency for commercial HVAC trunk lines. Jeddah district cooling contractors specify welded construction for chilled water mains where operating pressures remain below 16 bar.
- Coiled Pipes:Continuous-length annealed copper supplied on reels up to 100 meters, eliminating intermediate joints in residential plumbing retrofits. Villa developers in Dammam's suburban corridors specify coiled product for faster installation timelines.
- Straight Pipes:Rigid six-meter lengths for commercial and industrial headers requiring precise alignment. Aramco process cooling specifications mandate straight pipe for heat exchanger bundles at Ras Tanura refinery.
Volume placements concentrate in Welded Tubes; the faster expansion belongs to Coiled Pipes.
Application:
Cost tier differentiation separates commodity plumbing from engineered climate systems. Specification authority rests with distinct stakeholder groups—municipal building codes for plumbing, MEP consultants for HVAC—that impose divergent material standards.
- Plumbing:Potable water distribution systems in residential and commercial buildings, governed by SFDA leaching limits and SASO pressure ratings. Riyadh municipal authorities enforce copper-only specifications for high-rise domestic hot water recirculation loops.
- HVAC:Chilled water, refrigerant, and condensate lines for climate control systems. NEOM's linear city design specifies copper tube for all district cooling lateral connections to minimize thermal losses across the 170-kilometer development.
- Electrical:Grounding conductors and busbar enclosures for power distribution infrastructure. SABIC industrial sites specify heavy-wall copper tube for substation grounding grids in Jubail.
- Construction:Structural and architectural applications including column cladding and decorative elements. Diriyah Gate heritage district specifications require oxidized copper tube for traditional aesthetic matching.
Specification density runs highest in HVAC; plumbing specifications are climbing fastest under revised Saudi Building Code thermal mandates.
End User:
Customer type determines volume scale and contract structure. Gigaproject developers consolidate procurement through annual frame agreements, while residential contractors purchase through distributor spot markets.
- Residential:Single-family villas and low-rise apartment plumbing systems. PEX substitution pressures concentrate here, though SASO certification requirements slow polymer adoption in Riyadh and Jeddah municipal zones.
- Commercial:Office towers, retail complexes, and hospitality developments. Red Sea Project hospitality clusters specify copper tube for all potable and HVAC systems to meet LEED-equivalent certification targets.
- Industrial:Process cooling, heat exchangers, and specialized fluid handling for manufacturing and petrochemical operations. Aramco and SABIC maintenance schedules drive replacement demand for corrosion-resistant alloy tubing.
- Utilities:District cooling plant infrastructure and municipal water distribution networks. Saudi Real Estate Infrastructure Company procurement desks specify copper for primary distribution headers in Riyadh's expanding district cooling zones.
Contract value concentrates in Commercial; Industrial end-use is expanding most quickly under Eastern Province manufacturing localization.
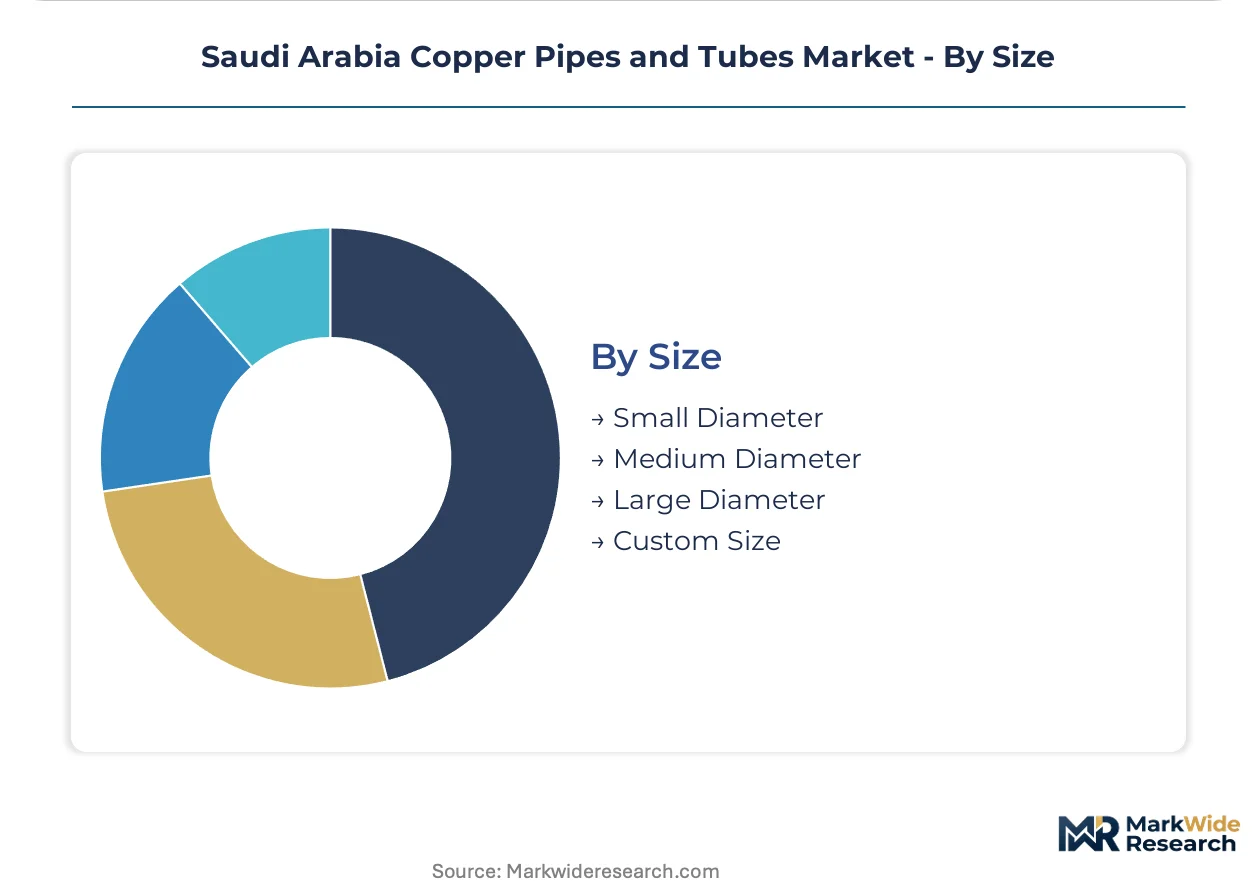
Size:
Supply concentration in medium diameters reflects standardization pressures from HVAC and plumbing contractors. Custom fabrication capacity remains limited to specialized desalination and semiconductor cooling applications.
- Small Diameter:Tube OD below 15mm for residential plumbing fixtures, medical gas lines, and precision instrumentation. Jeddah hospital construction specifies small-diameter copper for medical air and vacuum systems.
- Medium Diameter:Tube OD 15-50mm for standard HVAC and commercial plumbing applications. This diameter class captures bulk procurement volumes from gigaproject MEP contractors in Riyadh.
- Large Diameter:Tube OD above 50mm for district cooling mains, desalination plant condensers, and industrial process headers. Ras Al-Khair desalination facility retrofits specify large-diameter copper-nickel alloy for seawater corrosion resistance.
- Custom Size:Non-standard diameters and wall thicknesses for specialized heat exchanger and pressure vessel applications. Semiconductor-grade cooling loops in Riyadh data centers require custom orbital-welded assemblies.
Fabrication throughput centers on Medium Diameter; specification growth is steepest for Custom Size in high-purity industrial applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia consumes far more copper tube than it fabricates, importing high-purity cathode from European smelters while domestic extrusion capacity concentrates in Eastern Province industrial zones. Riyadh and Jeddah contractors drive demand through gigaproject procurement, with regional distribution networks pre-positioning inventory ahead of construction mobilization.
Central Region
Qiddiya and Diriyah Gate developments specify seamless copper tube for high-rise potable water risers where leak integrity is non-negotiable. SFDA potable water certification mandates SASO marking for all imported products, accelerating customs clearance for pre-certified feedstock. Riyadh municipal authorities enforce copper-only specifications for domestic hot water recirculation loops in buildings exceeding 12 stories.
Eastern Province
Aramco process cooling maintenance schedules drive replacement demand for corrosion-resistant alloy tubing at Ras Tanura refinery. The National Industrial Development Center offers tariff advantages for tube fabrication facilities serving SABIC petrochemical complexes. Jubail manufacturing zones attract backward-integrated smelter-to-tube investments targeting captive industrial demand.
Western Region
Jeddah district cooling contractors specify welded construction for chilled water mains where operating pressures remain below 16 bar. Red Sea Project hospitality clusters require copper tube for all potable and HVAC systems to meet LEED-equivalent certification targets. Cool Plus Trading Est. maintains specialized HVAC inventory in Jeddah and Dammam warehouses for rapid contractor fulfillment.
NEOM Northwest
The linear city design specifies copper tube for all district cooling lateral connections to minimize thermal losses across the 170-kilometer development. Consolidated procurement desks negotiate annual frame agreements that lock in volume commitments and price bands. NEOM's compressed 18-month construction cycles force fabricators to pre-position inventory ahead of mobilization phases.
Saudi Arabia Copper Pipes and Tubes Market Competitive Environment
The competitive structure tilts toward European feedstock suppliers and regional distributors rather than integrated domestic fabricators. Two strategic archetypes dominate: European smelters supplying high-purity cathode to Saudi extruders, and specialized HVAC distributors holding localized inventory for contractor spot purchasing. Competitive moves center on securing SASO pre-certification chains and locking annual frame agreements with gigaproject procurement desks.
Among European-anchored suppliers, Aurubis AG represents the feedstock concentration archetype, while Mueller Industries exemplifies technical standards transfer from North American parent operations. Cool Plus Trading Est. occupies the regional distribution specialist position. These three entities illustrate the tripartite structure: upstream cathode control, technical specification authority, and last-mile inventory positioning.
| Leading Market Players |
|---|
| MM Kembla |
| Cool Plus Trading Est. |
| Aurubis AG |
| Sawaed International Trading Est. |
| Cannelle Holdings FZCO |
| Mueller Industries |
| Techno Cool Co. |
| C-Flo Copper |
| Mehta Tubes Ltd. |
| Others |
Value Chain & Pricing Dynamics
LME copper cathode pricing cascades through Saudi fabrication tiers, compressing margin buffers for distributors serving fixed-price construction contracts while elevating procurement leverage for gigaproject developers with annual volume commitments.
Pricing Analysis
Yield-based pricing anchors premium tiers, where seamless tube specifications for high-rise potable water risers command markups tied to leak-integrity guarantees rather than commodity metal content. Three-tier pricing structure across premium, standard, and economy levels separates SASO-certified seamless construction from welded HVAC trunk lines and coiled residential plumbing. Cost compression in the standard tier intensifies as PEX substitution pressures residential villa developments outside municipal district cooling zones. Gigaproject procurement desks exhibit lowest price sensitivity due to consolidated annual frame agreements, while spot-market contractors face highest exposure to LME volatility.
Supply Chain Analysis
High-purity cathode supply rests on European smelting concentration, with German and Belgian feedstock sources feeding Saudi extrusion capacity. Copper cathode, phosphorus deoxidized grades, and precision drawing lubricants constitute the critical input trinity. Single-source vulnerability through Suez Canal routing exposes Saudi fabricators to shipment delays when canal transit restrictions emerge. Distribution runs through Jeddah and Dammam warehouse hubs serving HVAC contractor spot purchasing, with Riyadh gigaproject procurement increasingly bypassing distributor tiers for direct mill relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race, with players pursuing backward control over European smelter relationships to secure SASO-traceable feedstock chains ahead of procurement desk consolidation.
For Market Incumbents: Lock in annual frame agreements with Saudi Real Estate Infrastructure Company and NEOM procurement desks before 18-month construction cycles compress further. Secure exclusive cathode supply relationships with Aurubis or alternative European smelters to defend against feedstock diversion to Eastern Province localization projects. Invest in Dammam and Riyadh SASO-authorized testing facility partnerships to accelerate pressure vessel welder certification throughput. For New Entrants and Emerging Players: Enter via specialized HVAC inventory positioning in Jeddah and Dammam corridors, where Cool Plus Trading Est. demonstrates the regional distributor archetype. Target Eastern Province industrial localization zones, where Ras Al-Khair and Jubail manufacturing incentives attract backward-integrated fabrication investments. Pursue Aramco and SABIC process cooling maintenance schedules as the most penetrable industrial entry point, leveraging corrosion-resistant alloy expertise. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap fabricators with dormant SASO certification pipelines in the Eastern Province, where tariff advantages and captive industrial demand create defensive positioning. Long-term viability hinges on smelter-to-tube documentation chain completeness under tightening SASO traceability mandates. Watch for LME price volatility spikes as the inflection indicator triggering consolidation among margin-constrained distributors serving fixed-price construction contracts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into European Smelter Relationships | Secures SASO-traceable feedstock chains for gigaproject procurement compliance. |
| Eastern Province Manufacturing Localization | Captures National Industrial Development Center tariff advantages for Aramco and SABIC supply. |
| SASO-Authorized Testing Facility Investment | Alleviates Dammam and Riyadh welder certification backlogs delaying qualified workforce deployment. |
| Annual Frame Agreement Negotiation | Locks volume commitments with Saudi Real Estate Infrastructure Company ahead of procurement desk consolidation. |
| Corrosion-Resistant Alloy Capacity Expansion | Targets Ras Al-Khair desalination retrofit demand and seawater process cooling specifications. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with HVAC procurement managers, MEP consultants, district cooling plant engineers, SASO certification officers, and copper tube fabrication plant managers. SASO technical regulations, SFDA potable water standards, Saudi Building Code enforcement documents, and LME pricing archives furnished validation benchmarks. Bottom-up project pipeline tracking across Qiddiya, Diriyah Gate, NEOM, and Red Sea Project zones combined with top-down cathode import volume analysis.
Data-stream reconciliation across product type, application, end user, diameter class, and regional demand cluster dimensions shaped the analytical framework. CAGRs emerged from segmented volume trajectory modeling against gigaproject procurement calendar phasing. District cooling network expansion timelines, desalination plant retrofit schedules, and municipal thermal mandate enforcement intensity informed industry-specific forecast inputs throughout the projection horizon.
Forecast precision tightens around the base case; tail outcomes carry wider variance under copper cathode price volatility spikes or Suez Canal logistics disruptions. Assumptions reflect documented gigaproject mobilization timelines, SASO traceability mandate implementation schedules, and PEX substitution elasticity in residential plumbing segments. LME pricing regime shifts, European smelter supply disruptions, and gigaproject timeline accelerations warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pipes and Tubes
Metal Pipe Market
Pipes and Tubes
Stainless Steel Plumbing Pipes Market
Pipes and Tubes
FRP Pipe Market
Pipes and Tubes
Stainless Steel Welded Pipes Market
Pipes and Tubes
Global Copper Pipes and Tubes Market
Pipes and Tubes
GCC CPVC Pipes Market
Pipes and Tubes
Global Tracer Wires Market
Pipes and Tubes
Global CPVC Pipes and Fittings Market
Pipes and Tubes
Industrial Blast Hoses Market
Pipes and Tubes
Global PEX (Cross-Linked Polyethylene) Market
Pipes and Tubes
Saudi Arabia PVC Pipes Market
Pipes and Tubes
Multibore Tubes Market
Pipes and Tubes
Portugal PVC Pipes Market
Pipes and Tubes
OCTG Pipe Market
Pipes and Tubes
Steel Pipes and Tubes Market
Pipes and Tubes
Galvanized Iron Pipes Market