
 Global PEX (Cross-Linked Polyethylene) Market | 2026-2036
Global PEX (Cross-Linked Polyethylene) Market Size, Share, and Industry Trends Forecast 2026-2036
Global PEX (Cross-Linked Polyethylene) Market Foresight
Silane grafting technology is tilting PEX manufacturing toward more uniform cross-linking densities and faster production cycles. Dow leverages its integrated polyethylene feedstock position to sustain cost leadership in PEX B resin supply. REHAU anchors European demand through captive pipe extrusion and pre-insulated system bundling. Uponor dominates North American plumbing specification through direct contractor training programs and code-body relationships.
Cross-linked polyethylene is a thermoset polymer produced by creating covalent bonds between linear polyethylene chains through peroxide, silane, or electron-beam methods, yielding operating temperatures up to 95°C and burst resistance exceeding 800 psi at elevated temperatures. PEX A leads plumbing applications due to its kink recovery and expansion fitting compatibility, while PEX Al Pex captures premium share in radiant heating for its oxygen diffusion resistance and dimensional stability. Infrastructure end users represent the fastest-growing demand pool as municipalities specify PEX for buried district heating networks.
REACH compliance in Europe restricts certain peroxide initiators, pushing producers toward silane-cross-linking platforms with lower volatile organic compound profiles. The EPA's lead and copper rule revisions in the United States accelerate copper replacement timelines, directly expanding PEX plumbing retrofit eligibility. China's GB standards for plastic piping in building applications now incorporate long-term hydrostatic pressure testing protocols that favor established cross-linking technologies. Stakeholders must monitor code adoption velocity in India's emerging smart cities and assess backward integration opportunities into metallocene polyethylene feedstocks.
Market Dynamics
Silane grafting technology is consolidating PEX manufacturing around faster production cycles and tighter cross-linking uniformity, compressing the competitive advantage of legacy peroxide-based systems. This structural shift is redrawing cost curves and regional supply positions.
Growth Catalysts
- Plumbing retrofit mandates:The EPA's lead and copper rule revisions in the United States compress copper replacement timelines, expanding PEX eligibility in residential repipe projects.
- Underfloor heating codes:Germany's KBA building standards now mandate oxygen-barrier PEX for new multifamily construction, locking in material specification at the design phase.
- District heating infrastructure:Municipalities across Scandinavia and Central Europe are specifying PEX for buried network applications, creating a new demand pool outside traditional building construction.
Market Restraints
- Feedstock concentration:Metallocene polyethylene supply concentrates among integrated petrochemical majors, creating vulnerability for non-backward-integrated PEX compounders.
- REACH chemical restrictions:ECHA limitations on peroxide initiators force costly process conversions toward silane platforms, raising compliance burdens for European producers.
- Metal composite substitution:PEX-Al-PEX multilayer pipe captures premium radiant heating share through superior oxygen diffusion resistance, capping pure PEX pricing power.
Strategic Opportunities
- India smart city buildout:Code adoption velocity in emerging Indian urban clusters offers first-mover positioning for piping system suppliers ahead of specification lock-in.
- Pre-insulated system bundling:European contractors are shifting toward packaged solutions combining PEX pipe, insulation, and controls, opening margin expansion for integrated providers.
- Electron-beam cross-linking:Convergence of EB technology with high-speed extrusion lines enables on-demand customization without batch curing delays, serving project-specific geometries.
Industry Challenges
- Installer certification bottlenecks:Expansion fitting systems for PEX A require trained contractor networks, and training capacity lags demand growth in retrofit-heavy markets.
- GB standard compliance timelines:China's long-term hydrostatic pressure testing protocols favor established cross-linking technologies, extending product qualification cycles for new entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global PEX (Cross-Linked Polyethylene) Market |
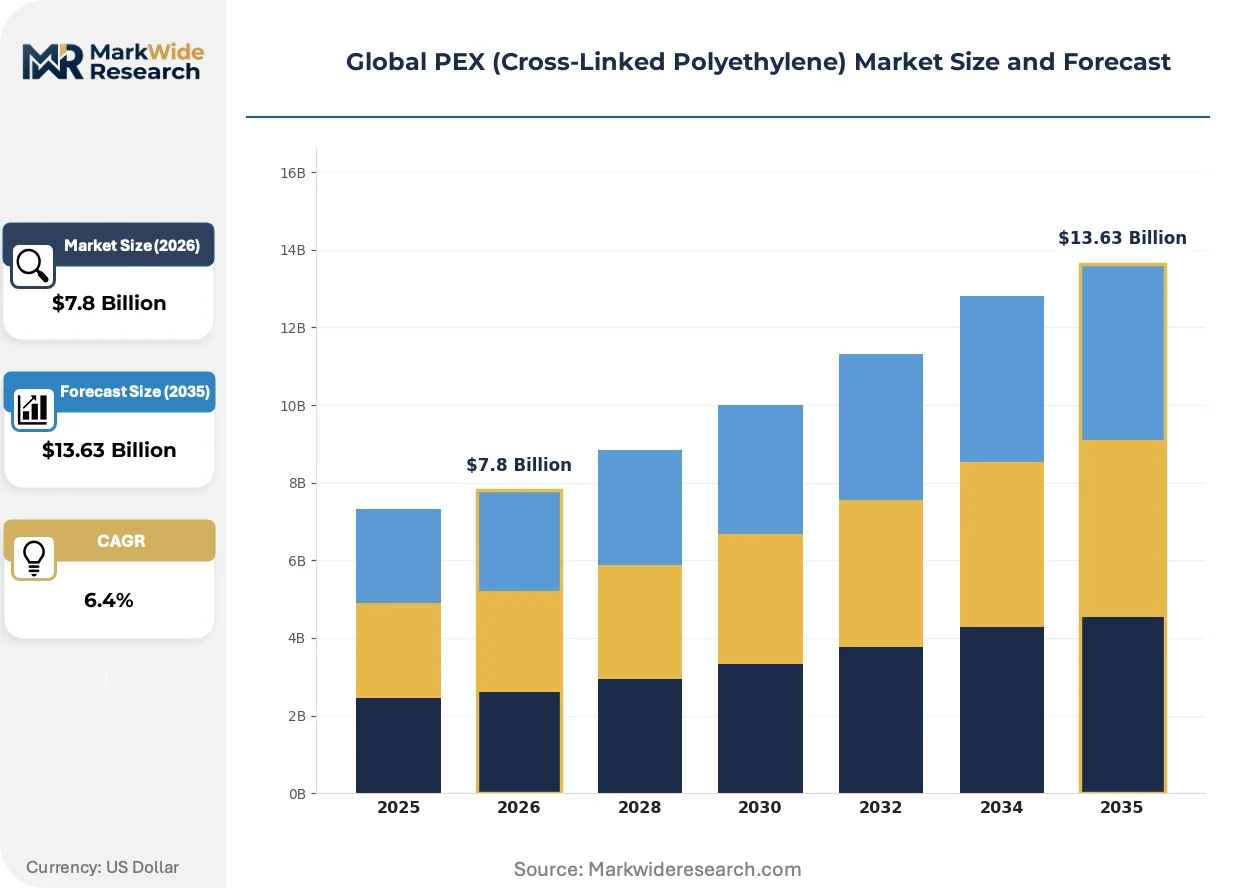
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $13.63 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pex A, Pex B, Pex C, Pex Al-Pex Application: Plumbing, Radiant Heating, Fire Protection, Snow Melting End User: Residential, Commercial, Industrial, Infrastructure Installation Type: New Construction, Renovation, Retrofits, Upgrades |
| Companies Covered | Dow, Borealis AG, LyondellBasell Industries Holdings B.V., Exxon Mobil Corporation, Avient Corporation, Uponor, REHAU, Viega, Solvay, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global PEX (Cross-Linked Polyethylene) Market Shifts & Advancements
Process digitization and regulatory chemistry shifts are converging to redefine how PEX is manufactured, specified, and deployed across heating and plumbing networks. These forces are compressing legacy competitive advantages.
Real-time cross-linking density monitoring is digitizing quality assurance in silane-grafting operations. European compounders are adopting inline spectroscopic sensors that replace offline batch testing, cutting release times from hours to minutes. This compression of verification cycles is enabling just-in-time compounding for project-specific orders.
REACH chemical safety frameworks are forcing substitution of volatile organic compound-heavy peroxide initiators across European production lines. The industrial consequence is accelerated capital redeployment toward silane and electron-beam platforms. German and Austrian producers are responding by consolidating compounding operations to capture scale economies in the transition.
Specification authority is migrating from distributors to direct contractor relationships in North American plumbing. Uponor and REHAU have built captive training networks that bypass traditional wholesale channels, capturing decision-making at the installation crew level. This channel compression is most visible in Texas and Florida residential markets where repipe volumes concentrate.
Global PEX (Cross-Linked Polyethylene) Market Segmentation
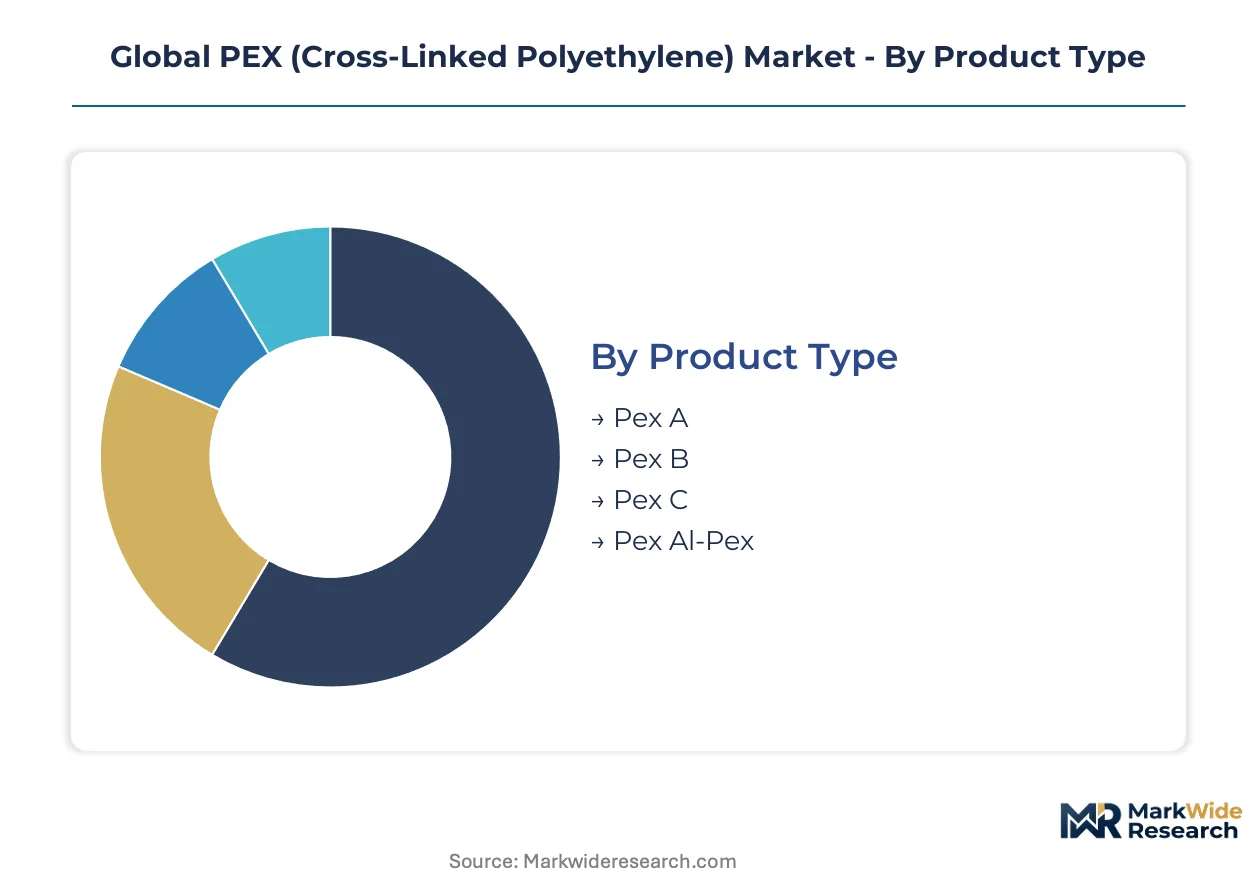
PEX market segmentation reveals how cross-linking chemistry, application thermal requirements, and installation constraints fragment demand into distinct competitive arenas. Each dimension carries different margin profiles and specification authority structures that shape supplier positioning.
Product Type:
Mature silane and peroxide platforms dominate current throughput, while emerging electron-beam systems are gaining traction in specialized geometries.
- PEX A:Peroxide cross-linking yields uniform three-dimensional molecular networks with exceptional kink recovery and shape memory. Plumbing contractors in the United States specify PEX A for residential repipe projects where expansion fitting systems accelerate installation timelines.
- PEX B:Silane grafting produces slightly lower cross-link density at reduced manufacturing cost, capturing volume share in cost-sensitive plumbing specifications. Dow leverages integrated polyethylene feedstock positions to sustain resin supply leadership for this segment.
- PEX C:Electron-beam radiation cross-linking enables post-extrusion customization without batch curing delays, serving project-specific geometries in industrial applications.
- PEX Al-Pex:Multilayer construction with aluminum oxygen barrier delivers dimensional stability and diffusion resistance for underfloor heating networks in Germany and Austria.
PEX B handles the majority of throughput; PEX Al-Pex is expanding most quickly in premium radiant heating specifications.
Application:
Cost tier differentiation separates commodity plumbing from engineered thermal management systems with specialized performance requirements.
- Plumbing:Potable water distribution systems leverage PEX flexibility and corrosion resistance to displace copper in residential and commercial buildings. EPA lead and copper rule revisions in the United States compress replacement timelines and expand retrofit eligibility.
- Radiant Heating:Hydronic floor warming systems demand oxygen-barrier specifications to prevent ferrous component corrosion in closed-loop circuits. Germany's KBA building codes mandate barrier-grade PEX for new multifamily construction, locking in material specification at design phase.
- Fire Protection:Sprinkler system applications exploit PEX freeze resistance and installation speed in residential and light commercial construction.
- Snow Melting:Hydronic surface heating for driveways and walkways requires robust burst resistance at sub-zero operating conditions in Scandinavian and Alpine climates.
Plumbing commands the largest installed base; radiant heating is climbing the fastest on specification intensity and code mandates.
End User:
Volume concentration sits with established residential and commercial construction, while margin expansion follows infrastructure-scale district heating deployments.
- Residential:Single-family and multifamily housing drives baseline demand through plumbing rough-in and radiant floor specifications. Uponor's direct contractor training programs in Texas and Florida capture specification authority at installation crew level.
- Commercial:Office, retail, and hospitality construction specifies PEX for domestic hot water distribution and hydronic climate control.
- Industrial:Process cooling and chemical transport applications exploit PEX chemical resistance and temperature tolerance in manufacturing facilities.
- Infrastructure:Municipal district heating networks in Scandinavia and Central Europe specify pre-insulated PEX for buried distribution lines, creating a demand pool outside traditional building construction with multi-decade replacement cycles.
Residential absorbs the highest absolute volume; infrastructure is gaining share fastest on project scale and specification durability.
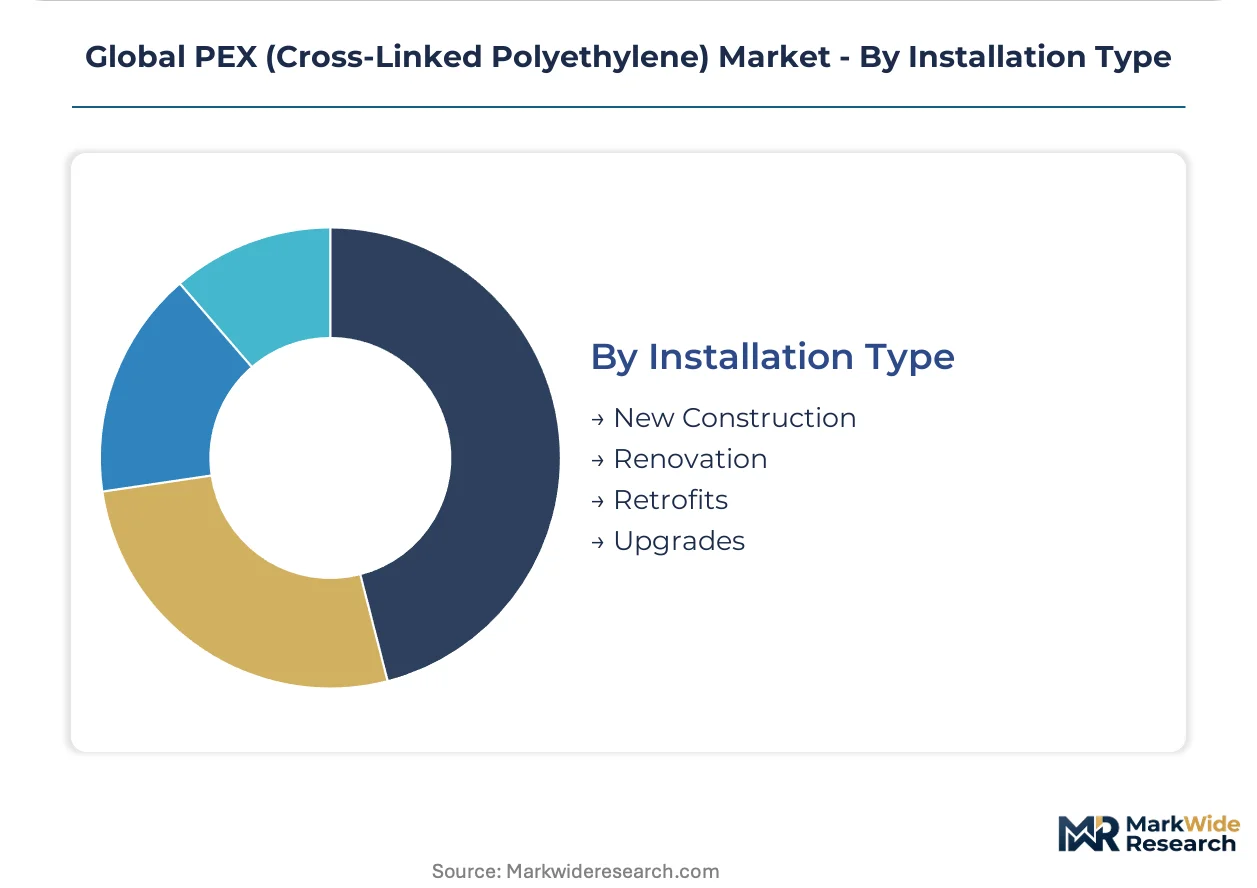
Installation Type:
Customer type segmentation distinguishes new construction specification patterns from renovation decision-making timelines and retrofit urgency drivers.
- New Construction:Greenfield projects enable integrated system design with PEX specified at architectural phase. China's tier-one cities concentrate demand where REHAU and Uponor operate localized compounding facilities.
- Renovation:Building modernization projects replace legacy piping during structural upgrades, with specification influenced by existing infrastructure constraints.
- Retrofits:Urgent pipe replacement driven by failure, contamination, or regulatory compliance compresses decision timelines and favors contractor-preferred materials. EPA lead and copper rule enforcement accelerates copper displacement in United States residential retrofits.
- Upgrades:Elective system improvements for efficiency or comfort enhancement support premium product positioning in established buildings.
New construction maintains the steadiest flow; retrofits are expanding most quickly on regulatory pressure and aging infrastructure replacement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports pre-insulated PEX piping systems to Scandinavian district heating utilities, while China ships compounded resin to Southeast Asian extrusion facilities. Trade corridors concentrate value-added fabrication in Northern Europe and feedstock conversion in East Asia.
United States
Residential repipe contractors in Texas and Florida specify PEX A tubing for copper replacement at accelerating rates. EPA lead and copper rule revisions compress compliance timelines for municipal water systems. Uponor operates direct training networks in Houston and Miami that bypass traditional wholesale channels.
Germany
KBA building codes mandate oxygen-barrier PEX for underfloor heating in new multifamily construction across Berlin and Munich. REACH restrictions on peroxide initiators force producers toward silane-cross-linking platforms. REHAU anchors European demand through captive pipe extrusion in Bavaria.
China
GB standards for plastic piping now incorporate long-term hydrostatic pressure testing that favors established cross-linking technologies. Tier-one cities concentrate demand where REHAU and Uponor operate localized compounding operations. Shanghai and Beijing municipal projects specify PEX for buried district heating networks.
India
Smart city buildouts in emerging urban clusters create first-mover positioning opportunities ahead of specification lock-in. BIS certification requirements for plastic piping extend product qualification cycles for new entrants. Maharashtra and Gujarat housing authorities pilot PEX plumbing in affordable residential developments.
Global PEX (Cross-Linked Polyethylene) Market Competitive Landscape
Channel-controlling players compete with product-specialist players across specification-driven segments. The vendor base fragments between integrated petrochemical majors supplying resin and downstream fabricators extruding finished pipe. Three archetypes dominate: backward-integrated polyethylene producers, system-bundling European manufacturers, and regional extrusion specialists. Competitive moves concentrate on captive training network expansion and pre-insulated system bundling.
Within the integrated-resin tier, Dow and Borealis AG represent feedstock-to-compound positioning. Among system-bundling fabricators, Uponor and REHAU occupy positions defined by direct contractor relationships and code-body engagement. These named entities exemplify how specification authority migrates from distributors to installation-level decision makers in North American and European markets respectively.
| Leading Market Players |
|---|
| Dow |
| Borealis AG |
| LyondellBasell Industries Holdings B.V. |
| Exxon Mobil Corporation |
| Avient Corporation |
| Uponor |
| REHAU |
| Viega |
| Solvay |
| Others |
Supply & Pricing Matrix
Rotterdam-Antwerp barge freight corridors transmit polyethylene feedstock cost volatility into PEX compounder margins, compressing price differentiation between silane-grafting specialists and peroxide-based legacy producers while amplifying regional arbitrage opportunities for integrated resin suppliers.
Pricing Analysis
Peroxide-based PEX A commands premium positioning over silane-graft PEX B and electron-beam PEX C across contractor-specified plumbing segments. Three-tier pricing structure across oxygen-barrier radiant systems, standard potable grades, and commodity plumbing resin reflects certification intensity and backward integration depth. Cost compression in PEX B resin supply is intensifying because Dow's integrated polyethylene position sustains volume leadership. Municipal infrastructure buyers exhibit lowest price sensitivity due to multi-decade lifecycle accounting, while residential retrofit contractors face acute margin pressure from copper displacement urgency.
Supply Chain Analysis
REACH chemical restrictions on peroxide initiators limit technology transfer and equipment procurement flows into European compounding operations. Metallocene polyethylene feedstock concentrates in integrated petrochemical complexes across the United States, Germany, and Saudi Arabia. PEX compounding draws from specialized silane grafting agents, high-density polyethylene resin, and antioxidant stabilizer packages. Single-source vulnerability sits with metallocene catalyst technology controlled by select licensors. Distribution runs through direct contractor training networks in North America and captive extrusion-to-system-bundling channels in Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Silane grafting technology disruption compresses legacy peroxide process returns while EPA lead rule enforcement accelerates copper replacement velocity, creating a high-growth inflection for specification-captive suppliers.
For Market Incumbents: Entrench specification authority through captive installer certification networks that bypass distributor channels, mirroring Uponor's Houston and Miami training hubs. Expand backward integration into metallocene polyethylene feedstocks to defend margin position against Dow's resin cost leadership. Prioritize pre-insulated system bundling in European district heating corridors where REHAU's Bavarian extrusion complexes anchor value capture.
For New Entrants and Emerging Players: Build out electron-beam cross-linking capacity to serve project-specific industrial geometries without batch curing delays. Target India's Maharashtra and Gujarat affordable housing pilots ahead of BIS certification lock-in. Pursue joint venture structures with established European compounders to shortcut China's extended GB standard qualification timelines.
For Investors and Strategic Acquirers: Carve-out targets emerge from petrochemical majors seeking to monetize non-core PEX compounding assets amid REACH compliance capital redeployment. Long-term viability hinges on positioning ahead of India's smart city specification waves and Scandinavia's district heating infrastructure buildouts. Monitor code adoption velocity in emerging Indian urban clusters as the primary demand inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Metallocene Feedstock | Dow's polyethylene position demonstrates cost leadership sustainability across PEX B resin supply. |
| Captive Installer Certification Network Expansion | Uponor's direct contractor relationships in Texas and Florida bypass wholesale channel margin extraction. |
| Pre-insulated System Bundling | REHAU's European district heating packages capture margin through integrated pipe, insulation, and controls. |
| Electron-beam Cross-linking Capacity Addition | Post-extrusion customization serves industrial project geometries without batch curing delays. |
| Joint Venture for GB Standard Compliance | China's hydrostatic pressure testing protocols favor established cross-linking technology partnerships. |
Research Methodology
The analysis maps silane-grafting, peroxide, and electron-beam cross-linking platforms, each validated through interviews with plant operations managers, plumbing contractor training directors, municipal district heating procurement officers, and regulatory compliance leads. Primary fieldwork combined with secondary validation from customs trade data, KBA building code filings, EPA lead rule dockets, and SEC petrochemical segment disclosures. Bottom-up resin throughput estimates triangulated against top-down construction spending allocations across residential, commercial, and infrastructure end uses.
Assumptions held fixed include REACH chemical restriction timelines and EPA enforcement velocity, while variables included India's smart city code adoption speed and China's GB standard implementation rigor. Segmentation modeling spanned cross-linking chemistry, application thermal requirements, installation type, and end-user scale across the projection horizon. CAGRs derived from construction output correlations and infrastructure replacement cycle analysis, with specific inputs from radiant heating code mandate penetration and copper pipe failure rate trajectories.
Sensitivities concentrate around ECHA peroxide initiator restriction expansion, India's BIS certification timeline compression, and municipal district heating budget allocation shifts. Forecasts reflect these documented assumptions. Material shifts in China GB standard enforcement rigor or EPA lead rule compliance deadline acceleration would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pipes and Tubes
HDPE Corrugated Pipe Market
Pipes and Tubes
Saudi Arabia PVC Pipes Market
Pipes and Tubes
India Process Piping Market
Pipes and Tubes
Steel Pipes and Tubes Market
Pipes and Tubes
Pipes and Fittings Market
Pipes and Tubes
Thermoplastic Pipe Market
Pipes and Tubes
Global CPVC Pipes and Fittings Market
Pipes and Tubes
Pneumatic Fittings Market
Pipes and Tubes
Gas Pipe Fittings Market
Pipes and Tubes
HPLC Fused Silica Tube Market
Pipes and Tubes
US Cold Drawn Seamless Steel Pipes Market
Pipes and Tubes
Global Butt Weld Fittings Market
Pipes and Tubes
Copper Tube Market
Pipes and Tubes
Global Flexible Pipes Market
Pipes and Tubes
Global Fiberglass Pipe Market
Pipes and Tubes
Steel Tubes Market