
 North America Hydraulic Fluid Connectors Market | 2026-2036
North America Hydraulic Fluid Connectors Market Size, Share, and Industry Trends Forecast 2026-2036
North America Hydraulic Fluid Connectors Market Analytics
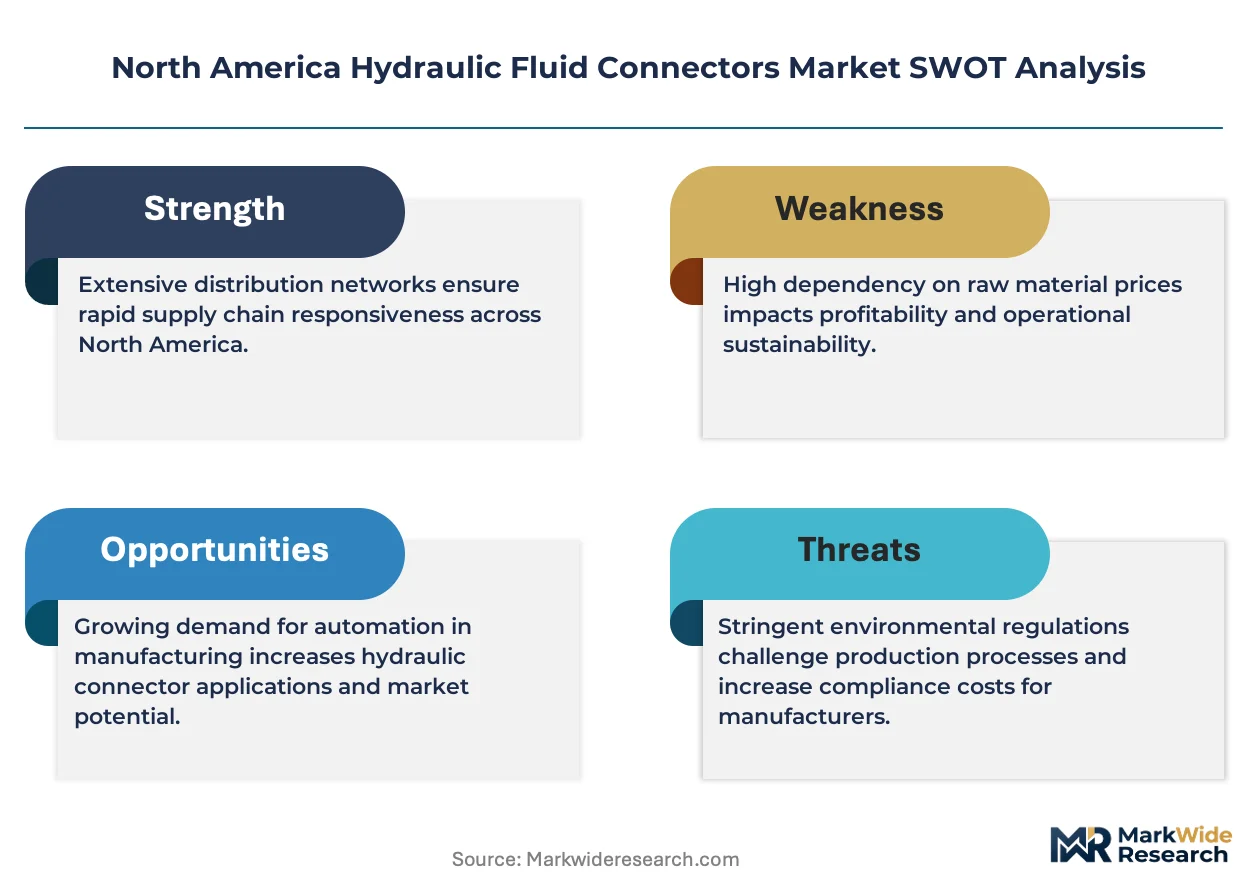
The EPA Tier 4 Final and emerging Stage V alignment for off-road equipment is recalibrating the cost-of-entry calculus for hydraulic fluid connector suppliers serving diesel-powered machinery. Parker Hannifin Corporation leverages its integrated motion and control portfolio to dominate specification-driven procurement channels across North American OEMs. Eaton Corporation Plc. sustains competitive positioning through captive manufacturing of advanced sealing technologies that reduce fugitive emissions in high-pressure circuits. Gates Corporation anchors its market presence with specialized thermoplastic hose and coupling systems engineered for mobile hydraulic applications.
North America hydraulic fluid connectors are precision-engineered mechanical interfaces that join hoses, tubes, and components within pressurized fluid power systems, typically rated for operating pressures from 3,000 to 6,000 psi and constructed with elastomeric seals, metal ferrules, and threaded or snap-lock geometries to prevent leakage under dynamic load cycles. Their primary industrial purpose is to transmit hydraulic energy reliably across mobile equipment, stationary machinery, and process automation infrastructure. Quick disconnects command substantial volume share in maintenance-intensive sectors where tool changeover speed directly impacts equipment uptime. Stainless steel variants capture premium margin pools in aerospace and corrosive-process applications where material certification and traceability requirements exceed standard industrial grades. Removable installation types are gaining structural share in aftermarket service channels as fleet operators prioritize field-repairable architectures over permanent crimp solutions.
The US Department of Transportation's PHMSA pipeline safety regulations and OSHA hydraulic press safety standards collectively shape product design mandates, pressure-rating certifications, and material traceability requirements across the North American supply base. Canada's CSA Group standards for fluid power components create parallel compliance obligations for cross-border suppliers serving integrated North American OEM supply chains. Stakeholders must monitor evolving EPA methane and VOC fugitive emissions rules, as these frameworks are likely to tighten seal-performance specifications and accelerate demand for zero-leak connector architectures in environmentally sensitive operating environments.
Market Dynamics
EPA Tier 4 Final and emerging Stage V emissions alignment for off-road diesel equipment is recalibrating procurement specifications toward lighter, leak-resistant connector architectures across North American OEM supply chains.
Growth Catalysts
- Emissions Compliance Pressure:The EPA's evolving standards for off-road diesel equipment are pushing manufacturers toward zero-leak connector designs that reduce fugitive methane and VOC emissions in environmentally sensitive operating environments.
- Construction Equipment Expansion:OEMs for hydraulic excavators and loaders are expanding connector procurement volumes to support fleet modernization and infrastructure investment cycles across the US Gulf Coast petrochemical corridor.
- Quick Disconnect Adoption:Maintenance-intensive sectors are standardizing quick disconnect geometries to compress tool changeover cycles and maximize equipment uptime in field-service applications.
Market Restraints
- Specialty Steel Input Volatility:Stainless steel variants for aerospace and corrosive-process applications face margin pressure from nickel and chromium price swings that complicate long-term contract pricing.
- Cross-Border Certification Friction:Canada's CSA Group standards for fluid power components create parallel compliance obligations that extend product development timelines for US-based suppliers serving integrated North American OEM chains.
- Thermoplastic Substitution Threat:Specialized thermoplastic hose systems are capturing share in mobile hydraulic applications where weight reduction and corrosion resistance outweigh traditional metal-ferrule performance.
Strategic Opportunities
- Great Lakes Manufacturing Belt Concentration:Demand clustering around automotive and heavy machinery production hubs in Michigan, Ohio, and Ontario creates localized procurement density for specialized connector distributors.
- Removable Installation Architectures:Aftermarket service channels are prioritizing field-repairable connector designs over permanent crimp solutions, opening white space for modular product lines.
- OSHA Hydraulic Press Safety Alignment:Tightening workplace safety standards are accelerating specification upgrades toward higher pressure-rating certifications and enhanced material traceability systems.
Industry Challenges
- Seal Performance Certification Timelines:Zero-leak architecture validation under dynamic load cycles requires extended testing protocols that compress product launch windows.
- Legacy System Integration Complexity:Fleet operators running mixed-vintage equipment face interoperability constraints when upgrading to newer quick-disconnect geometries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Hydraulic Fluid Connectors Market |
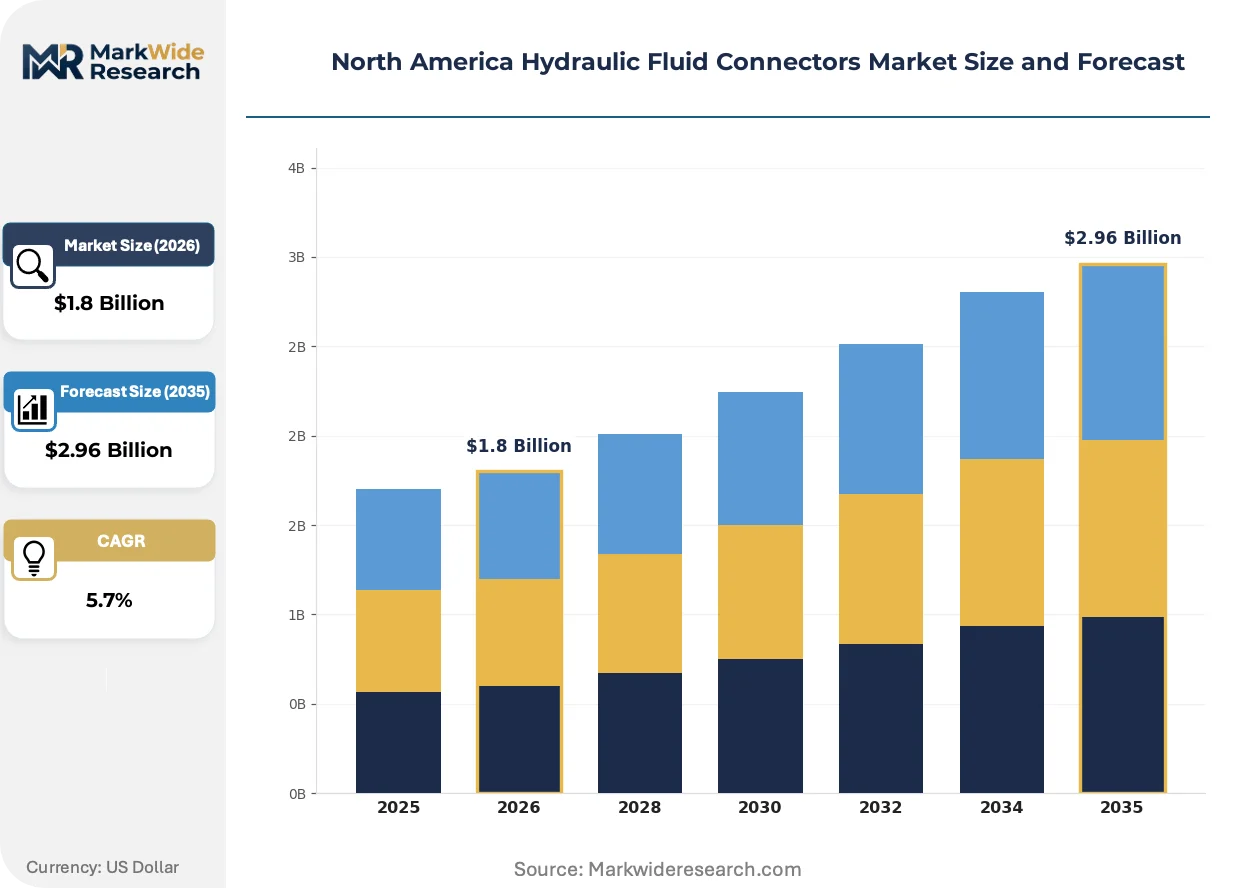
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Quick Disconnects, Hose Couplings, Adaptors, Valves Material: Stainless Steel, Brass, Aluminum, Plastic End User: Aerospace, Construction, Agriculture, Manufacturing Installation Type: Permanent, Removable, Direct, Remote |
| Companies Covered | Parker Hannifin Corporation, Eaton Corporation Plc., Gates Corporation, Cameron International Corporation, Manuli Hydraulics, Kurt Hydraulics, RYCO Hydraulics Pty. Ltd., Swagelok Company, Danfoss Power Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Hydraulic Fluid Connectors Market Evolving Landscape
Active reshaping in this market centers on material substitution, regulatory-driven design mandates, and procurement model compression across maintenance-intensive verticals.
Advanced elastomeric seal compounds with embedded fiber reinforcement are consolidating specification dominance in high-pressure circuits rated above 4,500 psi. Mobile equipment OEMs serving construction and agriculture are adopting these formulations at accelerated pace to meet extended service-interval requirements. The technology is consolidating supplier tiers by compressing qualification timelines for second-source ferrule geometries.
PHMSA pipeline safety regulations and OSHA hydraulic press standards are tightening pressure-rating certification and material traceability mandates across the North American supply base. These frameworks are forcing design-stage documentation upgrades and third-party testing investments. Off-road diesel equipment manufacturers face the steepest compliance burden as dual-agency oversight converges on fugitive emissions performance.
Specification-driven procurement is compressing distributor influence in favor of direct OEM-supplier relationships anchored by long-term performance contracts. Independent distributors serving the aftermarket are losing share to captive service networks operated by major equipment manufacturers. This channel consolidation is most visible in the US Gulf Coast petrochemical corridor where integrated operators prioritize single-source accountability over multi-vendor sourcing flexibility.
North America Hydraulic Fluid Connectors Market Segmentation
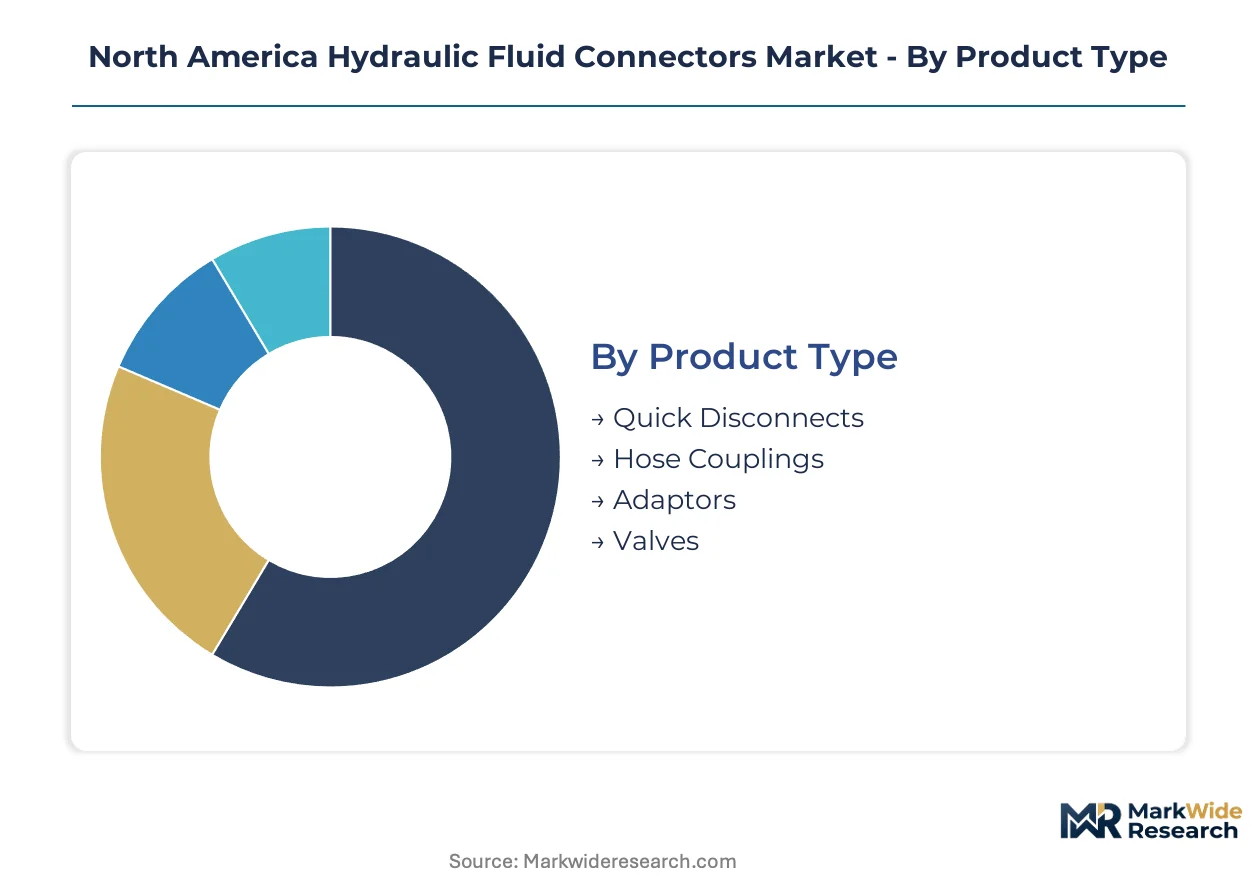
Segmentation in North American hydraulic fluid connectors reveals distinct procurement patterns across pressure ratings, material certifications, and maintenance architectures. OEM specification teams weight end-use environmental exposure against field-service requirements when sourcing connector portfolios.
Product Type:
Volume concentrates in standardized geometries serving high-frequency maintenance cycles, while premium positioning accrues to specialized architectures with integrated valving or rapid-disconnect functionality.
- Quick Disconnects:These self-sealing interfaces incorporate poppet valves that isolate fluid flow during uncoupling, eliminating spillage in tool-change scenarios. Maintenance-intensive sectors across the Great Lakes manufacturing belt specify these geometries to compress equipment downtime during scheduled service intervals.
- Hose Couplings:Metal-ferrule assemblies crimped onto reinforced elastomeric hose stock form the backbone of mobile hydraulic circuits rated to 6,000 psi. Construction equipment OEMs serving the US Gulf Coast petrochemical corridor specify these in high volumes for excavator and loader hydraulic systems.
- Adaptors:Threaded transition fittings bridge incompatible port geometries and pressure ratings across mixed-vintage fleet equipment.
- Valves:Integrated connector-valve combinations consolidate circuit protection and connection functions in space-constrained aerospace and mobile equipment layouts.
Mature deployment sits with hose couplings. Newer deployment is concentrated in quick disconnects.
Material:
Cost tiering separates corrosion-resistant aerospace grades from commodity industrial specifications, with mid-range alloys capturing mobile equipment standardization.
- Stainless Steel:Austenitic grades with full material certification and lot traceability satisfy aerospace and corrosive-process requirements where failure costs exceed component price by orders of magnitude. These variants command premium positioning in specification-driven procurement channels.
- Brass:Copper-zinc alloys offer machinability and moderate corrosion resistance for general industrial applications below 3,000 psi operating pressure.
- Aluminum:Lightweight extrusions and forgings reduce mass in mobile equipment where every pound affects fuel efficiency compliance.
- Plastic:Engineered thermoplastics displace metal in low-pressure pneumatic and fluid handling circuits where chemical compatibility outweighs mechanical strength requirements.
Established specification dominance resides with stainless steel. Accelerated substitution is occurring in plastic.
End User:
Customer-type segmentation aligns connector performance requirements with regulatory exposure and uptime economics across distinct operational environments.
- Aerospace:FAA-certified assemblies with complete material traceability and NDT documentation support flight control and landing gear hydraulic systems. These applications demand zero-failure tolerance under cyclic loading and extreme temperature swings.
- Construction:Mobile equipment fleets operating in abrasive, high-vibration environments specify robust ferrule geometries with extended service intervals to minimize field failures.
- Agriculture:Seasonal equipment utilization patterns favor cost-optimized connector specifications with readily available aftermarket replacement inventory.
- Manufacturing:Stationary hydraulic presses and automation systems prioritize OSHA-compliant pressure ratings and documented maintenance protocols over extreme environmental sealing.
Specification complexity peaks in aerospace. Procurement volume concentrates in construction.
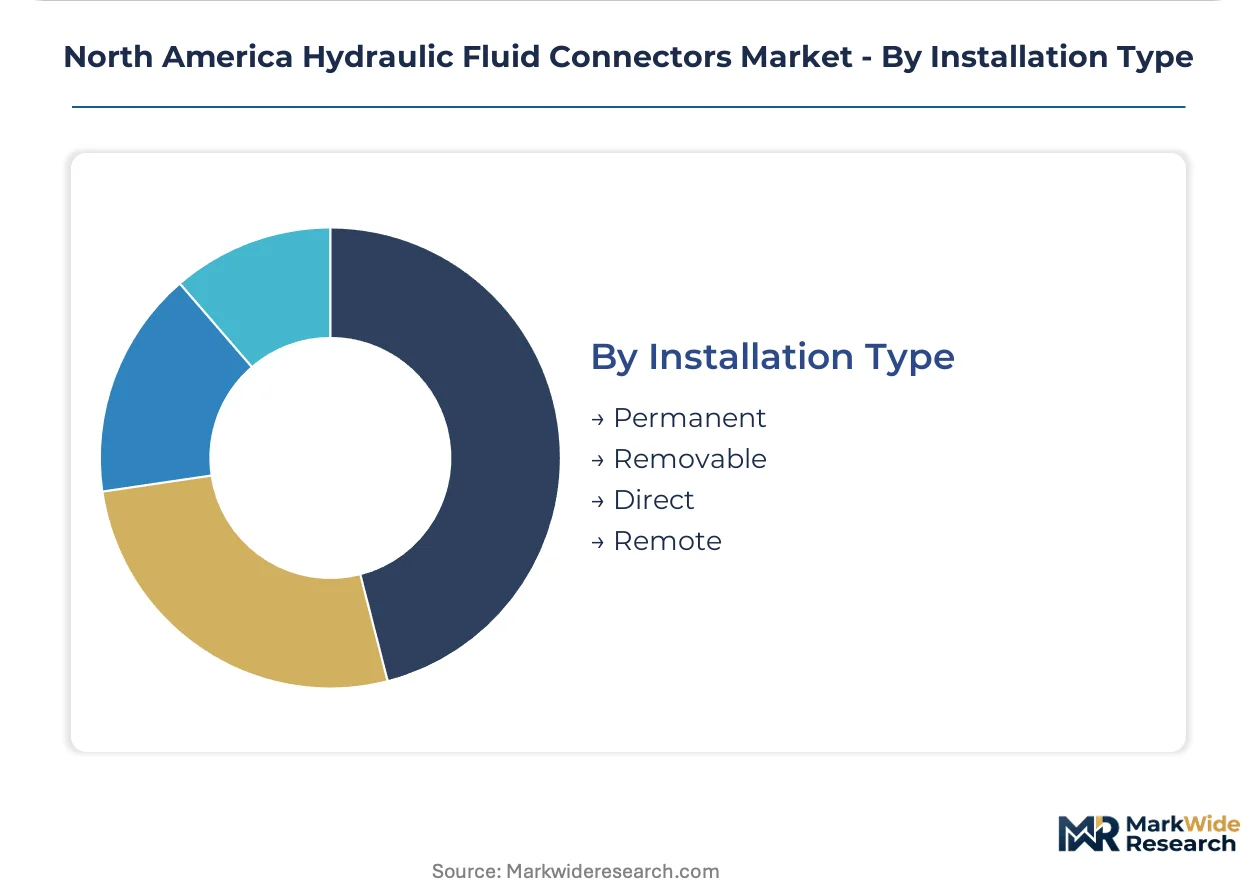
Installation Type:
Margin structure diverges between permanent crimp architectures with single-source ferrule dependence and field-serviceable alternatives that enable aftermarket parts competition.
- Permanent:Crimped ferrule systems deliver maximum pressure rating and leak resistance through controlled assembly processes requiring specialized tooling. OEM production lines and certified service depots dominate this architecture.
- Removable:Threaded, clamp, or snap-lock geometries enable field repair without dedicated crimp equipment, opening specification opportunities for independent distributors and fleet maintenance operations.
- Direct:Bulkhead-mounted connectors eliminate intermediate plumbing runs in compact equipment layouts.
- Remote:Extended stem or hose-tailed configurations position connection points away from heat sources or mechanical interference zones.
Production-line standardization favors permanent installation. Aftermarket channel expansion is driving removable adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US Gulf Coast petrochemical corridor and Great Lakes manufacturing belt concentrate procurement through specialized economic zones that reward localized supplier density with accelerated logistics and technical service response.
United States
Hydraulic excavator and loader OEMs in Michigan and Ohio are expanding connector procurement volumes to support infrastructure modernization cycles. EPA Tier 4 Final emissions standards push manufacturers toward zero-leak architectures that reduce fugitive methane and VOC releases. The Great Lakes manufacturing belt anchors specification-driven procurement channels where automotive and heavy machinery production hubs cluster.
Canada
Cross-border OEM supply chains serving integrated North American production networks drive steady demand for CSA-certified fluid power components. CSA Group standards for fluid power components create parallel compliance obligations that extend product development timelines for US-based suppliers. Ontario's manufacturing corridor concentrates aftermarket service channels as fleet operators prioritize field-repairable connector designs.
Mexico
Maquiladora operations along the northern border states absorb connector volumes for mobile equipment assembly serving export markets. The country's national industrial standards body aligns pressure-rating certifications with North American trade integration frameworks. Nuevo León's heavy machinery production cluster is expanding specification-driven procurement for hydraulic systems in construction equipment.
North America Hydraulic Fluid Connectors Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across a moderately consolidated vendor landscape where specification-driven procurement favors established certification portfolios. Three to five integrated motion-control conglomerates anchor OEM supply relationships through long-term performance contracts. Mid-tier distributors serving aftermarket channels face margin compression as captive service networks expand. Competitive moves concentrate on backward integration into advanced sealing technologies and geographic expansion toward the US Gulf Coast petrochemical corridor.
Among diversified industrial conglomerates, Parker Hannifin Corporation and Eaton Corporation Plc. exemplify integrated motion and control portfolio strategies that dominate specification-driven procurement channels. Gates Corporation occupies a position within the specialized hose and coupling tier, representing focused investment in thermoplastic systems for mobile hydraulic applications. These three anchors demonstrate how certification depth and geographic proximity to demand clusters determine competitive positioning in this market.
| Leading Market Players |
|---|
| Parker Hannifin Corporation |
| Eaton Corporation Plc. |
| Gates Corporation |
| Cameron International Corporation |
| Manuli Hydraulics |
| Kurt Hydraulics |
| RYCO Hydraulics Pty. Ltd. |
| Swagelok Company |
| Danfoss Power Solutions |
| Others |
Value Network & Pricing Analysis
EPA Tier 4 Final and emerging Stage V emissions alignment gates qualified supply access and premium-tier pricing power for zero-leak connector architectures serving North American off-road diesel equipment manufacturers. Suppliers demonstrating validated seal performance under dynamic load cycles command pricing premiums while uncertified competitors face exclusion from specification-driven OEM procurement channels.
Pricing Analysis
Short lead-time premiums separate expedited delivery contracts from spot inventory discounts across the Great Lakes manufacturing belt and US Gulf Coast petrochemical corridor. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and volume scale commitments from construction equipment OEMs. Cost compression in stainless steel variants intensifies because nickel and chromium price volatility complicates long-term contract pricing. Fleet operators running mixed-vintage equipment show highest price sensitivity, while aerospace specification teams demonstrate lowest sensitivity given failure-cost multiples.
Supply Chain Analysis
Workforce availability constraints in Michigan, Ohio, and Ontario metalworking clusters limit ferrule machining capacity for high-pressure connector assemblies. Supply concentration centers on the United States, Canada, and Mexico for integrated North American OEM production networks. Raw material dependencies draw from specialty steel mills, advanced elastomeric compounders, and precision seal manufacturers. Single-source vulnerability runs through captive sealing technology suppliers controlled by dominant motion-control conglomerates. Distribution runs through direct OEM-supplier long-term performance contracts and specialized industrial distributors serving aftermarket maintenance channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America hydraulic fluid connectors market sits in a material-transition phase as engineered thermoplastics displace traditional metal-ferrule geometries in mobile hydraulic weight-reduction applications.
For Market Incumbents: Acquire advanced sealing technology portfolios to defend specification-driven procurement relationships against thermoplastic substitution threats. Backward integration into fiber-reinforced elastomeric compound production secures supply continuity for high-pressure circuits rated above 4,500 psi. Expand captive service network density across the US Gulf Coast petrochemical corridor to compress independent distributor influence. For New Entrants and Emerging Players: Independent distributors serving aftermarket channels represent the most penetrable entry point for field-repairable removable installation architectures. Target Ontario's manufacturing corridor where fleet operators prioritize modular connector designs over permanent crimp solutions. Pursue CSA Group certification pathways early to unlock cross-border supply relationships with integrated North American OEM chains. For Investors and Strategic Acquirers: EPA methane and VOC fugitive emissions rule tightening is the leading indicator that zero-leak architecture validation capabilities will consolidate supplier tiers. Long-term viability favors targets with demonstrated PHMSA pipeline safety and OSHA hydraulic press standard compliance portfolios. Watch for CSA Group standard harmonization announcements as inflection signals for cross-border procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sealing Technologies | Captive control over advanced elastomeric compounds compresses second-source qualification timelines for OEMs. |
| CSA Group Certification Investment | Parallel compliance capability unlocks specification-driven procurement across integrated US-Canada OEM supply chains. |
| Quick Disconnect Product Line Expansion | Maintenance-intensive sectors in the Great Lakes manufacturing belt prioritize tool changeover speed. |
| Direct OEM Performance Contracts | Long-term agreements with construction equipment manufacturers displace multi-vendor distributor relationships. |
| Thermoplastic Hose System Development | Lightweight corrosion-resistant architectures capture share in mobile fuel efficiency compliance applications. |
Research Methodology
Independent corroboration across OEM procurement executives, aftermarket service directors, fluid power engineers, and industrial distribution managers underwrites the qualitative findings in this study. Primary fieldwork combined structured interviews with secondary validation drawing from EPA regulatory filings, OSHA safety standard updates, CSA Group technical bulletins, and SEC 10-K disclosures from listed motion-control conglomerates. Bottom-up connector volume estimates triangulated against top-down OEM production forecasts across the analysis window.
Comparable-period anchoring to historical infrastructure investment cycles and emissions compliance phase-ins structured the projection horizon for market expansion modeling. Segmentation dimensions encompassed product type, material certification grade, end-use industry, and installation architecture across the modeling period. CAGRs derived from pressure-rating tier growth differentials and regional procurement density clustering. Forecast inputs incorporated EPA enforcement trajectory assumptions and construction equipment fleet modernization patterns.
Caveats apply where nickel and chromium commodity volatility, CSA Group standard revision timelines, or thermoplastic material substitution acceleration could materially shift the outlook. Forecasts reflect documented assumptions regarding emissions compliance alignment and OEM specification consolidation. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pipes and Tubes
Hydrogen Tube Skids Market
Pipes and Tubes
Duplex Stainless Steel Pipe Market
Pipes and Tubes
Stainless Steel Plumbing Pipes and Fittings Market
Pipes and Tubes
Saudi Arabia PPR Pipes Market
Pipes and Tubes
Reinforced Thermoplastic Pipes Market
Pipes and Tubes
Water and Wastewater Pipe Market
Pipes and Tubes
Spain PVC Pipes Market
Pipes and Tubes
Perfusion Tubing Systems Market
Pipes and Tubes
Carbon Steel Pipe Fittings Market
Pipes and Tubes
Glass Reinforced Plastic (GRP) Piping Market
Pipes and Tubes
Welded Pipes Market
Pipes and Tubes
HDPE Corrugated Pipe Market
Pipes and Tubes
Global Butt Weld Fittings Market
Pipes and Tubes
Polyethylene Pipes Market
Pipes and Tubes
Saudi Arabia PE Pipes Market
Pipes and Tubes
Steel Pipes and Tubes Market