

Aluminum Pipe Market Size, Share, and Industry Trends Forecast 2026-2036
Aluminum Pipe Market Insights
Modular piping configurations is restructuring buyer procurement patterns across industrial infrastructure projects. Norsk Hydro leverages integrated bauxite-to-pipe operations across Nordic and Brazilian supply nodes. Kaiser Aluminum sustains defense and aerospace certification depth that competitors struggle to replicate. Chalco anchors cost positioning through captive alumina refining and government-backed capacity expansion.
Aluminum pipe comprises hollow cylindrical extrusions or drawn sections of aluminum alloys, typically series 6061, 6063, or 5083, manufactured to precise wall-thickness tolerances for fluid conveyance and structural load-bearing. Its primary purpose spans thermal-fluid transport, lightweight framework assembly, and corrosion-resistant conduit protection across marine, aerospace, and building systems. Seamless pipes command premium positioning in pressure-critical aerospace and shipbuilding applications where weld-integrity risk disqualifies joined alternatives. Welded pipes dominate volume in construction and HVAC Systems where cost efficiency outweighs absolute performance thresholds. Extruded pipes are capturing share in electrical infrastructure as Utility Providers prioritize rapid-install, corrosion-immune conduit solutions.
EPA emissions rules and OSHA workplace exposure limits shape North American smelter operating economics and downstream pipe pricing. China's MEE enforces dual carbon compliance that constrains primary aluminum output and redirects investment toward recycled feedstock pipe production. The EU's F-Gas Regulation and REACH chemical restrictions limit certain alloy additives and surface treatments used in European-sold products. Stakeholders must monitor regulatory divergence between carbon-accounting methodologies as this determines competitive sourcing advantage across export markets.
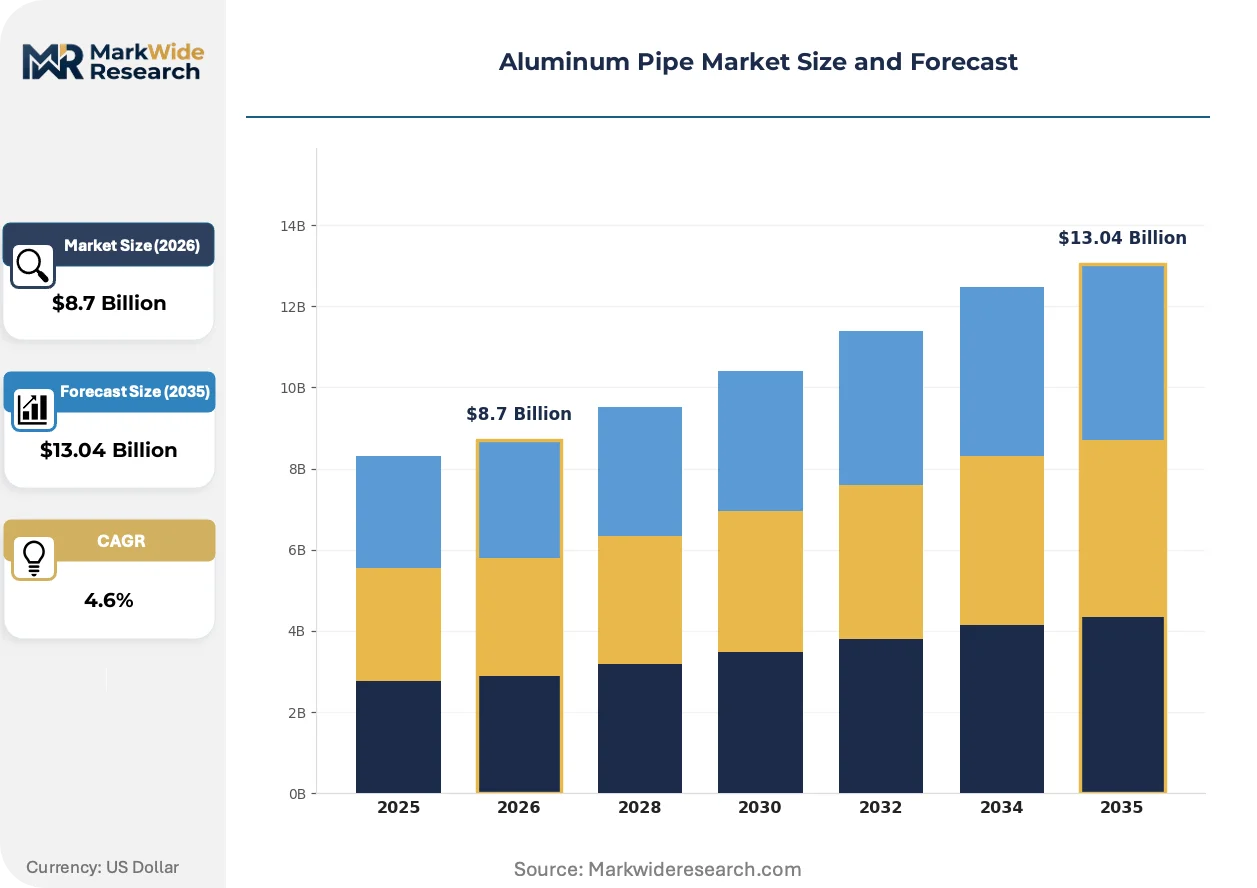
Market Dynamics
Primary aluminum smelting curtailments under China's MEE dual carbon enforcement are compressing feedstock availability and forcing pipe producers toward scrap-based remelt strategies.
Growth Catalysts
- Aerospace lightweighting mandates:FAA certification pathways for 6061-T6 seamless pipe in airframe structures are accelerating qualification timelines at tier-1 suppliers.
- EU F-Gas phasedown:HVAC contractors across Germany and France are specifying aluminum pipe for heat pump refrigerant lines to replace copper-intensive legacy systems.
- Scrap-sorting advances:Laser-induced breakdown spectroscopy is enabling closed-loop alloy recovery at remelt facilities, tightening specification control for secondary pipe production.
Market Restraints
- Alumina cost volatility:Bauxite refining energy intensity exposes pipe producers to natural gas price swings in Gulf Coast smelter corridors.
- Smelter concentration risk:Primary aluminum output restrictions in Yunnan and Guangxi provinces are constraining 6063 billet supply for extruded pipe manufacturers.
- Composite substitution:Carbon fiber-reinforced polymer pressure piping is displacing aluminum in offshore riser applications above 150-meter water depths.
Strategic Opportunities
- Vietnam industrial corridor:Manufacturing relocation from coastal China is creating demand for corrosion-resistant conduit in Hai Phong and Da Nang processing zones.
- Hydrogen transport infrastructure:5083-H112 seamless pipe specifications for 700-bar hydrogen refueling stations are opening certification-driven procurement channels.
- Digital twin integration:Real-time wall-thickness monitoring via embedded fiber optics is enabling predictive maintenance contracts with pipeline operators.
Industry Challenges
- ASME Section IX welder scarcity:Qualified orbital welding technicians for aerospace pipe fabrication command premium labor rates that compress contract margins.
- REACH substance notification:Chromium conversion coating alternatives for marine-grade pipe require 18-month ECHA authorization cycles that delay product launches.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aluminum Pipe Market Trends and Innovations
Extrusion press control systems and alloy development pipelines are converging to produce thinner-wall, higher-strength pipe configurations that challenge traditional material specifications.
Friction stir welding for longitudinal seam pipe is automating joint formation in 6082-T6 structural applications. Shipbuilders in South Korea are adopting the process for deck piping systems that previously required seamless stock. The technology is automating quality assurance through real-time force-feedback control that eliminates radiographic inspection bottlenecks.
China's GB 39726 emissions standard for aluminum smelting is tightening particulate and fluoride discharge limits that raise operating costs for primary metal suppliers. Downstream pipe producers are responding by qualifying Indian and Middle Eastern billet sources to diversify supply risk. The regulation is accelerating investment in inert anode pilot programs that promise zero-carbon smelting by decade's end.
Utility-scale solar developers are unbundling conduit procurement from EPC contracts and sourcing aluminum pipe directly through digital platforms. This disintermediation compresses distributor margins while rewarding producers with API certification and mill-direct logistics capabilities. The shift is most pronounced in Texas and Arizona utility corridors where project timelines have compressed to 14-month completion cycles.
Aluminum Pipe Market Segmentation
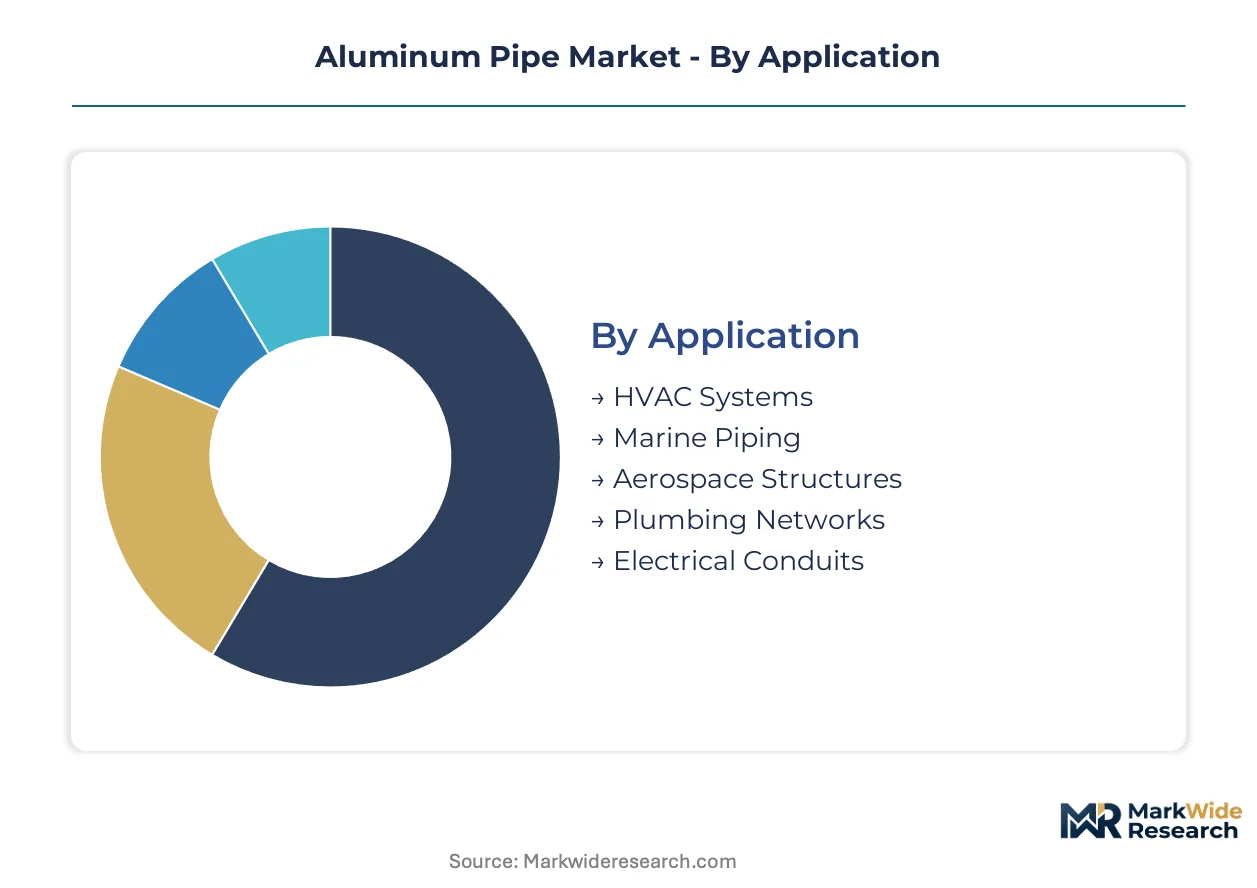
Aluminum pipe procurement decisions hinge on pressure ratings, corrosion exposure, and installation labor economics. Specification engineers weight alloy series, wall tolerance, and seam integrity against total lifecycle cost rather than unit price alone.
Application:
End-use environments dictate alloy selection and certification requirements above all other variables.
- HVAC Systems:6061-T6 and 6063-T5 alloys dominate refrigerant line applications where thermal conductivity and formability balance cost. German and French contractors are specifying aluminum for heat pump retrofits under EU F-Gas phasedown mandates.
- Marine Piping:5083-H116 seamless configurations resist saltwater corrosion in ballast and fire suppression systems. South Korean shipbuilders at DSME and Hyundai Heavy Industries are qualifying friction-stir welded longitudinal seam pipe to reduce seamless stock dependence.
- Aerospace Structures:6061-T6 seamless pipe meets AS9100 and FAA certification for fuel and hydraulic lines.
- Plumbing Networks:Extruded 6063 pipe serves potable water distribution in mid-rise residential construction.
- Electrical Conduits:Thin-wall extruded pipe replaces galvanized steel in solar farm collector systems across Texas and Arizona.
Volume sits with HVAC Systems; growth tilts toward Aerospace Structures.
Product Type:
Manufacturing method determines pressure tolerance, surface finish, and unit economics in buyer specifications.
- Seamless Pipes:Rotary piercing or extrusion-mandrel processes produce homogeneous grain structures for pressure-critical applications. Aircraft Manufacturers at Boeing and Airbus tier-1 suppliers command premium positioning for 6061-T6 seamless stock in landing gear and fuel system integration.
- Welded Pipes:Longitudinal or spiral seam construction from coiled strip enables diameter flexibility at lower cost per meter. Construction Firms in Vietnam's Hai Phong industrial corridor are procuring welded 6063 pipe for corrosion-resistant building framework.
- Extruded Pipes:Direct or indirect extrusion of solid billets creates complex cross-sections with tight tolerance control.
- Drawn Pipes:Cold-drawing over mandrels improves dimensional precision and surface finish for instrumentation tubing.
- Decorative Pipes:Anodized 6063 extrusions serve architectural handrail and fixture applications.
Shipbuilders and Aircraft Manufacturers drive seamless premiumization; Utility Providers and Construction Firms expand welded and extruded volume.
Technology:
Process selection traces back to billet quality, diameter range, and downstream forming requirements.
- Extrusion:Direct extrusion through shaped dies produces the majority of architectural and electrical conduit pipe. Hydro's Nordic smelters supply 6063 billets to extrusion presses serving European solar farm developers.
- Rolling:Pilger or roll-forming mills reduce wall thickness in seamless pipe production for high-pressure aerospace specifications.
- Drawing:Cold-drawing sequences achieve tight OD/ID tolerances for hydraulic and instrumentation applications.
- Casting:Continuous or centrifugal casting generates hollow starting stock for subsequent processing.
- Hydroforming:Fluid pressure expansion creates complex geometries from preformed tube blanks.
Extrusion anchors current capacity; hydroforming gains traction in structural automotive prototyping.
End User Industry:
Customer scale and certification depth fragment procurement patterns across the value chain.
- Construction Firms:Project-based procurement through distributor networks prioritizes availability over mill-direct relationships. Southeast Asian contractors in Da Nang and Hai Phong are sourcing 6063 extruded pipe for industrial facility frameworks.
- Shipbuilders:Long-term alloy qualification programs and Lloyd's Register certification create supplier stickiness. South Korean yards are adopting friction-stir welded pipe to bypass seamless supply constraints.
- Aircraft Manufacturers:AS9100 and NADCAP accreditation requirements limit qualified supplier pools. Boeing and Airbus tier-1 suppliers maintain dedicated seamless pipe inventory positions.
- Utility Providers:Unbundled procurement from EPC contracts is accelerating direct mill relationships.
- Electrical Installers:Regional contractor networks prioritize lightweight conduit for commercial retrofit speed.
Construction Firms and Utility Providers generate base volume; Aircraft Manufacturers and Shipbuilders concentrate margin capture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China dominates primary aluminum smelting while consuming the largest pipe volumes, yet manufacturing demand is dispersing toward Southeast Asian industrial zones and North American aerospace corridors. This production-consumption asymmetry is reshaping billet trade flows and regional procurement strategies.
China
Yunnan and Guangxi smelter curtailments under MEE dual carbon enforcement are constraining 6063 billet supply for extruded pipe manufacturers. GB 39726 emissions standards tighten particulate discharge limits that raise operating costs for primary metal suppliers. Manufacturers in Shandong Province are qualifying Indian and Middle Eastern billet sources to diversify feedstock risk.
United States
EPA emissions rules and OSHA workplace exposure limits shape smelter operating economics and downstream pipe pricing across Gulf Coast corridors. FAA certification pathways for 6061-T6 seamless pipe accelerate qualification timelines at tier-1 aerospace suppliers. Utility-scale solar developers in Texas and Arizona unbundle conduit procurement from EPC contracts and source aluminum pipe directly through digital platforms.
Germany
EU F-Gas Regulation phasedown drives HVAC contractors across Germany and France to specify aluminum pipe for heat pump refrigerant lines replacing copper-intensive legacy systems. REACH chemical restrictions limit certain alloy additives and surface treatments used in European-sold products. Industrial fabricators in the Ruhr Valley adapt procurement to carbon-accounting methodologies that determine competitive sourcing advantage.
South Korea
DSME and Hyundai Heavy Industries shipbuilders qualify friction-stir welded longitudinal seam pipe to reduce seamless stock dependence in deck piping systems. KOSHA workplace safety standards govern fabrication facility compliance. Busan-Ulsan shipyard clusters adopt automated quality assurance through real-time force-feedback control that eliminates radiographic inspection bottlenecks.
Vietnam
Manufacturing relocation from coastal China creates demand for corrosion-resistant conduit in Hai Phong and Da Nang processing zones. Construction firms procure welded 6063 pipe for industrial facility frameworks. The country's national industrial development incentives attract extrusion press investment serving regional solar and HVAC infrastructure.
Aluminum Pipe Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the aluminum pipe value chain. Consolidated upstream players with captive smelting and refining assets command cost positioning advantages in commodity-grade extruded pipe. Three archetypes dominate: integrated bauxite-to-pipe operators leveraging Nordic and Brazilian supply nodes; defense-aerospace certified specialists sustaining qualification depth; and government-backed national champions with captive alumina refining. Capacity expansion and strategic partnerships represent the dominant competitive moves as producers secure billet supply and qualify for hydrogen transport infrastructure certifications.
Within the integrated upstream tier, Norsk Hydro and Chalco exemplify divergent geographic and ownership models. Norsk Hydro ASA operates as a Norwegian public limited company with Nordic and Brazilian supply node integration. Chalco represents the state-backed national champion archetype with government-supported capacity positioning. Kaiser Aluminum Corporation anchors the specialty-certified segment as a Delaware-incorporated aerospace and defense supplier. These three occupy positions that illustrate how regulatory compliance depth, geographic supply node control, and end-use certification requirements stratify competitive positioning across seamless, welded, and extruded pipe categories.
| Leading Market Players |
|---|
| Norsk Hydro |
| Alcoa Corporation |
| Constellium |
| Chalco |
| Kaiser Aluminum |
| UACJ |
| JFE Steel |
| Hydro Extrusion |
| Arconic |
| Others |
Pricing and Supply Chain Analysis
Aircraft Manufacturers and Utility Providers concentrate procurement volume, forcing Three-tier pricing structure across premium, standard, and economy levels that stratifies by certification depth and mill-direct access.
Pricing Analysis
Margin tightening in seamless aerospace grades reflects AS9100 qualification scarcity and billet supply constraints from Yunnan smelter curtailments. Pricing stratifies across premium, standard, and economy tiers where FAA-certified seamless pipe commands substantial premiums over welded construction alternatives. Cost-down pressure on extruded conduit accelerates because Utility Providers unbundle procurement from EPC contracts and source direct through digital platforms. Shipbuilders demonstrate lowest price sensitivity due to Lloyd's Register certification stickiness, while Southeast Asian Construction Firms drive aggressive standard-tier negotiation.
Supply Chain Analysis
Mill-direct channels handle hyperscale Utility Provider demand, while distributor networks serve fragmented Construction Firm procurement. Primary aluminum production concentrates in China, Norway, and Brazil, with extrusion capacity expanding in Vietnam and India. Downstream pipe manufacturing draws from bauxite refining, primary smelting, and scrap remelt feedstocks. Single-source vulnerability concentrates in Chinese 6063 billet supply for extruded pipe producers. Distribution runs through regional metal service centers that maintain alloy-specific inventory positions for qualified buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Friction stir welding automation is displacing legacy seamless pipe dependence in marine applications, compressing qualification timelines and restructuring supplier tier relationships.
For Market Incumbents: Anchor defense through captive billet supply from Nordic or Brazilian nodes and accelerated AS9100 recertification to block emerging alloy qualification programs. Carbon fiber-reinforced polymer substitution in offshore risers above 150-meter depths threatens seamless premium positioning. Vertical integration into scrap-sorting LIBS technology tightens secondary pipe specification control. For New Entrants and Emerging Players: Launch via digital platform mill-direct relationships targeting Texas and Arizona utility-scale solar corridors where procurement unbundling creates white-space. Vietnam's Hai Phong industrial zone offers penetrable welded pipe demand from manufacturing relocation. Hydrogen transport infrastructure certification for 700-bar 5083-H112 specifications provides asymmetric entry angle. For Investors and Strategic Acquirers: The window for entry favors defense-aerospace certified specialists with NADCAP depth and government-backed national champions with captive alumina refining. Long-term viability hinges on dual carbon compliance positioning and inert anode technology access. Watch FAA qualification timeline compression at tier-1 suppliers as inflection indicator for seamless pipe demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bauxite Refining | Chalco's captive alumina supply anchors cost positioning against Nordic competitors. |
| Friction Stir Welding Certification | Hyundai Heavy Industries adoption validates automated seam quality for Lloyd's Register. |
| Scrap-Based Remelt Capacity Expansion | Laser-induced breakdown spectroscopy enables closed-loop 6063 recovery under China's MEE enforcement. |
| Hydrogen Infrastructure Qualification | 5083-H112 seamless specifications for 700-bar stations open premium procurement channels. |
| Digital Platform Mill-Direct Launch | Texas solar developers bypass distributors through API-certified logistics capabilities. |
Research Methodology
SEC 10-K filings, customs and trade databases, and aluminum industry association reports formed the secondary backbone for production and trade flow validation. Primary interviews with extrusion plant managers, aerospace tier-1 procurement leads, shipyard technical directors, and utility EPC contractors combined with secondary sources through bottom-up and top-down triangulation.
Historical trendline analysis of billet supply, extrusion press utilization, and end-use demand patterns informed the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, alloy series, application vertical, manufacturing technology, and end-user industry scale. CAGRs derived from regression analysis against primary aluminum output trajectories and scrap availability curves, with friction stir welding adoption rates and hydrogen infrastructure deployment as industry-specific forecast inputs.
Smelter curtailment enforcement, composite substitution acceleration, and welder certification scarcity are the dominant revision risks to pipe demand assumptions. Forecasts reflect documented assumptions on alloy qualification timelines and regional manufacturing relocation velocity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.