
 Absolute Ethanol Market | 2026-2036
Absolute Ethanol Market Size, Share, and Industry Trends Forecast 2026-2036
Absolute Ethanol Market Analysis
Buyer concentration in pharmaceutical solvent procurement is decoupling from traditional fuel-ethanol offtake patterns as biopharma manufacturers diversify supply sources. POET LLC leverages its corn-ethanol infrastructure to serve industrial chemical buyers. Valero Energy Corporation anchors fuel-additive demand through refinery integration. Cargill Inc competes on agricultural feedstock control and geographic reach across North American processing hubs.
Absolute ethanol denotes ethyl alcohol with water content below one percent by mass, typically produced through azeotropic distillation or molecular sieve dehydration to achieve purity exceeding 99.5 percent. Its primary industrial purpose centers on serving as a non-polar solvent for pharmaceutical extraction, chemical synthesis, and coatings formulation. Pharmaceutical Grade ethanol commands premium positioning due to USP and EP compliance burdens, while Industrial Grade occupies volume leadership in fuel-blending and chemical intermediate applications. Laboratory Grade maintains niche margins in analytical and research settings.
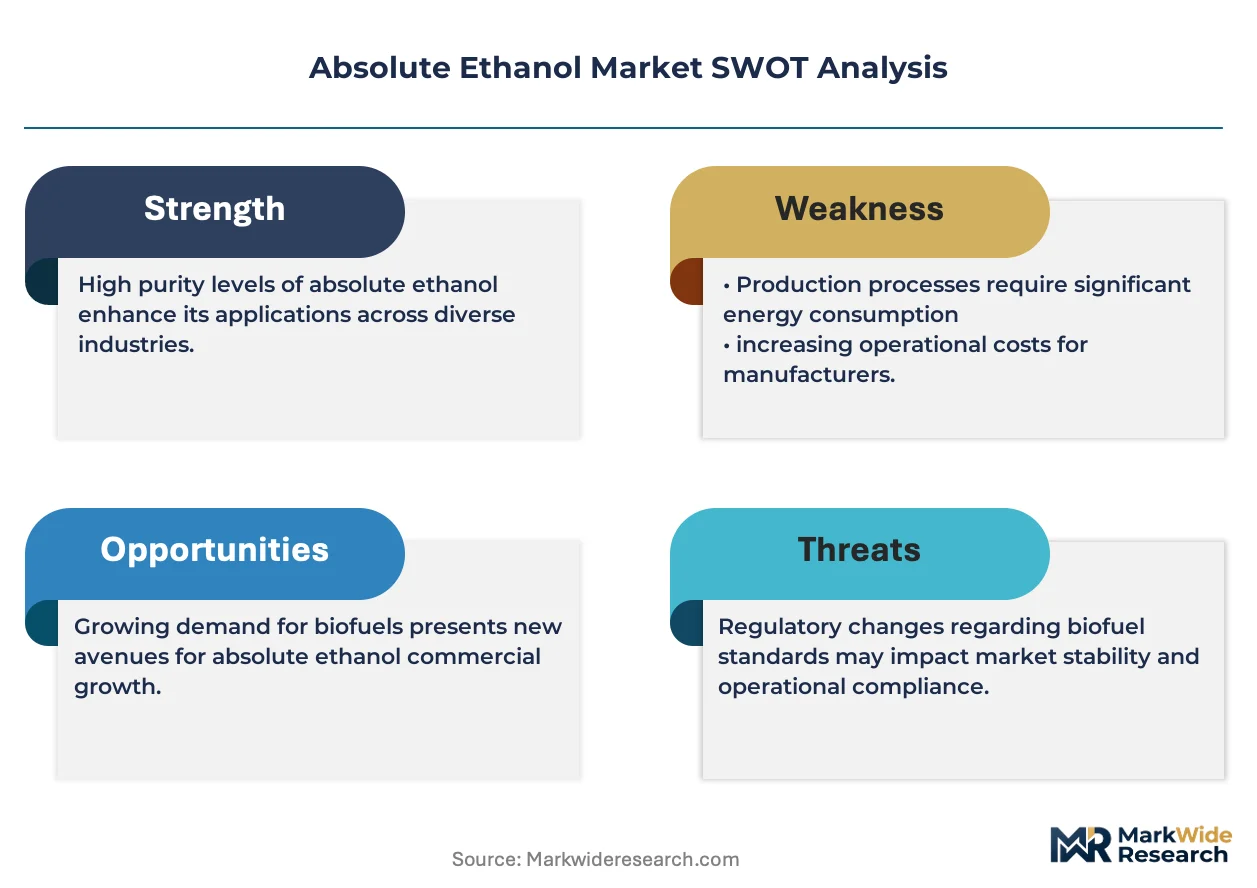
The US EPA enforces Renewable Fuel Standard blending mandates that shape fuel-grade ethanol demand volumes and compliance credit markets. EU REACH and ECHA classification protocols restrict residual impurity profiles for chemical intermediate and solvent applications. FDA and USP monographs govern Pharmaceutical Grade specifications for drug manufacturing. Stakeholders must monitor biofuel policy revisions and pharmaceutical purity standard harmonization between FDA and EMA frameworks.
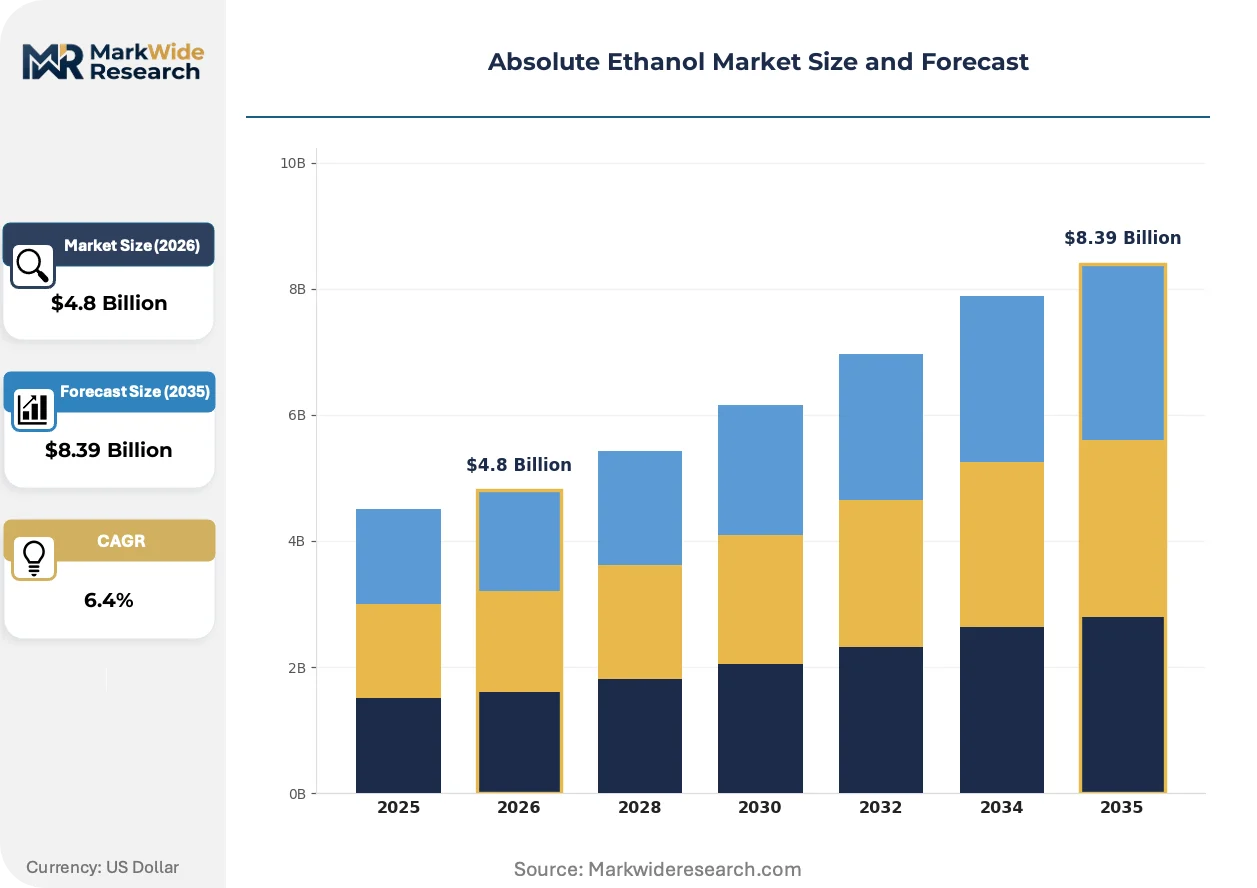
Market Dynamics
Pharmaceutical solvent procurement is decoupling from fuel-ethanol offtake as biopharma manufacturers diversify supply sources, while EPA Renewable Fuel Standard compliance tightens purity specifications across both industrial and fuel-grade streams.
Growth Catalysts
- EPA Renewable Fuel Standard:Blending mandates for fuel-grade ethanol sustain baseline demand volumes and compliance credit markets, anchoring refinery integration investments.
- Biopharma solvent diversification:Active ingredient synthesis operations are expanding absolute ethanol procurement outside traditional fuel-ethanol supply chains to secure pharmaceutical-grade purity.
- Ludwigshafen-Leverkusen corridor:Germany's chemical processing cluster concentrates demand for industrial-grade ethanol in coatings and chemical intermediate applications.
Market Restraints
- Corn feedstock volatility:Agricultural commodity price swings transmit directly into ethanol production economics, compressing margins for corn-based processors.
- EU REACH impurity restrictions:Residual contaminant limits for chemical intermediate applications raise purification costs and disqualify lower-grade supply.
- Cellulosic ethanol substitution:Second-generation biofuel technologies threaten to displace corn-ethanol capacity in long-dated fuel blending contracts.
Strategic Opportunities
- India pharmaceutical manufacturing:CDSCO compliance requirements for drug-grade solvents are expanding as domestic API production scales under PLI scheme incentives.
- Molecular sieve dehydration:Advanced drying technology is converging with continuous processing to enable modular, lower-capex production units for regional supply.
- Direct pharmaceutical contracting:Long-term offtake agreements with biopharma manufacturers bypass commodity fuel-ethanol pricing volatility.
Industry Challenges
- USP-EP certification timelines:Pharmaceutical-grade qualification periods extend months, freezing working capital and delaying revenue recognition for new capacity.
- Azeotropic distillation energy intensity:Thermal dehydration processes face carbon accounting pressure under EU Green Deal emissions frameworks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Absolute Ethanol Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.39 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Grade, Pharmaceutical Grade, Food Grade, Laboratory Grade Application: Solvent, Fuel Additive, Antiseptic, Chemical Intermediate End User: Pharmaceuticals, Food & Beverage, Personal Care, Paints & Coatings Distribution Channel: Direct Sales, Online Retail, Wholesalers, Distributors |
| Companies Covered | Archer Daniels Midland Company, Green Plains Inc, Valero Energy Corporation, POET LLC, Cargill Inc, Celanese Corporation, Lyondell Basell Industries N.V., AGRANA Beteiligungs-AG, Cremer Oleo GmbH Co.KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Absolute Ethanol Market Emerging Trajectories
Dehydration technology advancement and regulatory purity convergence are compressing grade distinctions while biopharma procurement models bypass traditional fuel-ethanol distribution channels.
Membrane-based pervaporation is converging with molecular sieve systems to reduce energy consumption in high-purity ethanol production. Pharmaceutical manufacturers in Switzerland and Germany are piloting hybrid dehydration trains. This technology convergence is enabling smaller-scale, distributed production closer to chemical processing clusters.
EU REACH and ECHA classification protocols are tightening residual impurity profiles for solvent-grade ethanol used in chemical synthesis. Industrial buyers must now document contaminant thresholds previously required only for pharmaceutical applications. Chemical intermediate producers in the Netherlands and Belgium are retrofitting purification trains to meet the elevated specifications.
Biopharma procurement teams are consolidating solvent suppliers through direct long-term contracts rather than spot market purchases. This bypasses traditional fuel-ethanol distributors and locks in pharmaceutical-grade supply security. The shift is most visible among mid-sized API manufacturers in Germany's Rhine-Neckar metropolitan region.
Absolute Ethanol Market Segmentation
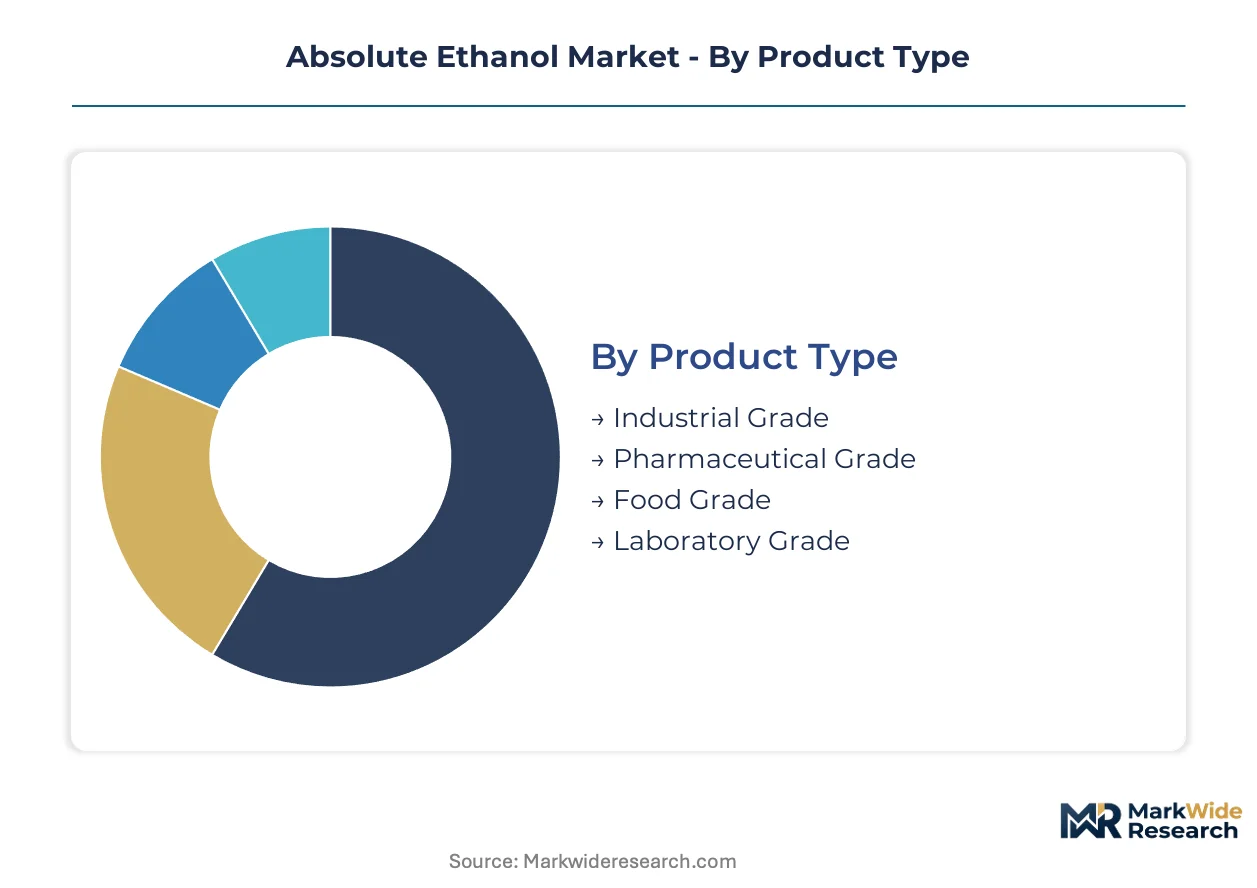
Absolute ethanol markets fragment across purity thresholds that determine regulatory burden and pricing power. Buyers in pharmaceutical synthesis, fuel blending, and chemical processing each demand distinct certification levels that reshape procurement economics and supplier qualification timelines.
Product Type:
Purity specifications differentiate buyers by compliance intensity and margin tolerance.
- Pharmaceutical Grade:USP and EP monographs govern residual solvent limits below 0.5% for API manufacturing. FDA and EMA inspection protocols extend qualification periods, freezing working capital for new entrants. Demand concentrates among contract manufacturers in Germany's Rhine-Neckar region serving European biopharma.
- Industrial Grade:Purity ranges from 95% to 99.5% for fuel blending and chemical synthesis applications. EPA Renewable Fuel Standard compliance drives volume procurement through refinery-integrated channels. Ludwigshafen chemical processors anchor demand for coatings and intermediate production.
- Food Grade:FCC and FSSAI standards govern beverage and extraction applications with lower purity thresholds than pharmaceutical tiers.
- Laboratory Grade:ACS and ISO 17025 specifications serve analytical and research settings with niche volume but premium pricing.
Volume sits with Industrial Grade; growth tilts toward Pharmaceutical Grade.
Application:
Functional use determines supply chain configuration and purity investment.
- Solvent:Non-polar extraction properties drive demand across pharmaceutical API synthesis and natural product processing. EU REACH impurity restrictions are elevating purification costs for chemical intermediate producers in Belgium and the Netherlands.
- Fuel Additive:Blending mandates under EPA Renewable Fuel Standard sustain baseline demand through corn-ethanol infrastructure. Valero Energy and POET LLC anchor procurement through captive refinery and processing networks.
- Antiseptic:Hospital and pharmaceutical formulation applications require pharmaceutical-grade certification with documented batch consistency.
- Chemical Intermediate:Ethylene and acetic acid derivative production consumes industrial-grade supply from German chemical corridor processors.
Solvent applications command margin premiums; fuel additive volumes dominate tonnage.
End User:
Industry verticals separate buyers by certification sophistication and contract structure.
- Pharmaceuticals:CDSCO compliance requirements in India and USP-EP harmonization pressures are expanding pharmaceutical-grade procurement outside traditional North American supply chains. Direct long-term contracting is displacing spot market purchases.
- Paints & Coatings:Industrial-grade consumption clusters in Germany's chemical processing corridor around Leverkusen, where coatings formulators demand consistent dehydration specifications.
- Food & Beverage:Extraction and flavoring applications require food-grade certification with lower purity investment than pharmaceutical tiers.
- Personal Care:Cosmetic formulation demand concentrates in Swiss and German manufacturing hubs with REACH-compliant solvent specifications.
Pharmaceutical buyers lead margin capture; coatings processors anchor industrial volume.
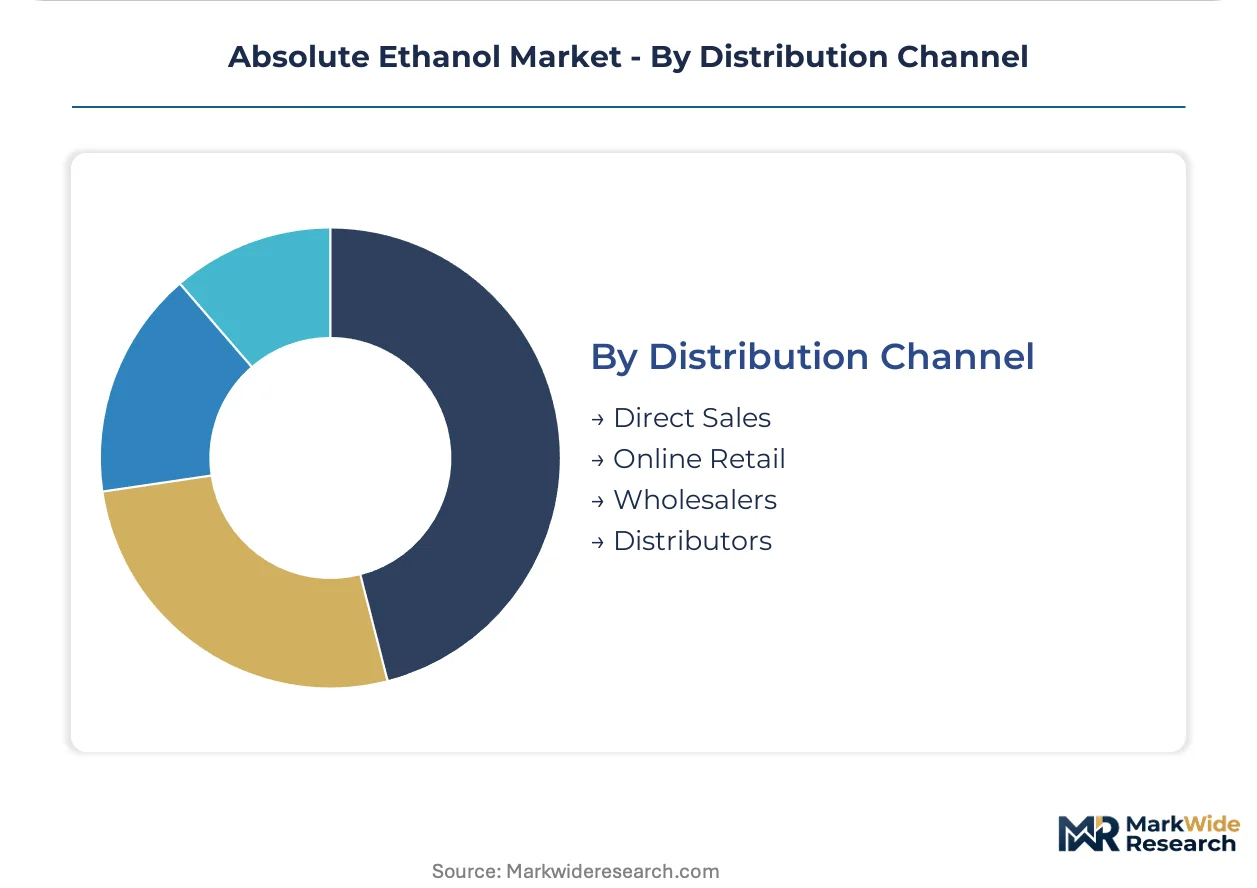
Distribution Channel:
Channel selection reflects buyer scale and certification handling requirements.
- Direct Sales:Pharmaceutical manufacturers bypass distributors to secure batch documentation and lock in pharmaceutical-grade supply security. German API producers in the Rhine-Neckar region are consolidating procurement through direct long-term agreements.
- Distributors:Industrial-grade and fuel-additive volumes flow through regional chemical distributors serving fragmented coatings and chemical synthesis buyers.
- Wholesalers:Laboratory-grade and small-volume industrial supply moves through specialty chemical wholesalers with certification handling capabilities.
- Online Retail:Research-grade and small-batch pharmaceutical supply serves academic and analytical laboratories with documented chain-of-custody.
Direct sales expand fastest among pharmaceutical buyers; distributors retain industrial-grade dominance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical solvent procurement concentrates in Germany's chemical processing corridor, while fuel-grade demand anchors in the United States corn belt. Industrial buyers in Belgium and the Netherlands face tightening EU REACH impurity restrictions. India's CDSCO compliance requirements are expanding as domestic API production scales.
United States
EPA Renewable Fuel Standard blending mandates sustain baseline demand volumes through corn-ethanol infrastructure. Refinery-integrated processors anchor fuel-additive procurement networks across the Midwest. POET LLC leverages its Iowa and South Dakota processing hubs to serve industrial chemical buyers seeking supply security.
Germany
Ludwigshafen and Leverkusen concentrate demand for industrial-grade ethanol in coatings and chemical intermediate applications. ECHA classification protocols restrict residual impurity profiles for solvent-grade supply. Rhine-Neckar metropolitan region API manufacturers are consolidating procurement through direct long-term contracts.
India
CDSCO compliance requirements for drug-grade solvents are expanding under PLI scheme incentives for domestic API production. Pharmaceutical manufacturers in Maharashtra and Gujarat are diversifying supply sources outside traditional fuel-ethanol channels. Hyderabad and Mumbai clusters anchor contract manufacturing demand for pharmaceutical-grade certification.
Belgium
Chemical intermediate producers face EU REACH contaminant thresholds previously required only for pharmaceutical applications. Antwerp and Ghent processing hubs are retrofitting purification trains to meet elevated specifications. Industrial buyers must now document residual solvent limits across coatings and synthesis operations.
Netherlands
Rotterdam chemical processors consume industrial-grade supply for ethylene and acetic acid derivative production. EU Green Deal emissions frameworks pressure thermal dehydration processes. Pernis and Moerdijk industrial clusters are piloting hybrid membrane-molecular sieve systems to reduce carbon intensity.
Absolute Ethanol Market Vendor Landscape
North American producers anchor the fuel-grade tier; European specialists hold pharmaceutical-grade positioning. The vendor base separates into corn-ethanol processors with refinery integration, chemical conglomerates with backward integration into feedstock control, and regional specialists with certification depth. Three archetypes dominate: agricultural processors leveraging grain supply chains, energy majors with downstream blending infrastructure, and chemical intermediaries with purity technology. Capacity expansion and direct pharmaceutical contracting represent the dominant competitive vectors.
Among agricultural processors, Archer Daniels Midland Company and Green Plains Inc exemplify the scale-driven archetype with grain supply chain control. Valero Energy Corporation anchors the energy-integrated tier through refinery blending operations. Cargill Inc occupies a position spanning agricultural feedstock dominance with geographic reach across North American processing hubs. These three represent the structural split between fuel-grade volume leadership and industrial chemical diversification.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| Green Plains Inc |
| Valero Energy Corporation |
| POET LLC |
| Cargill Inc |
| Celanese Corporation |
| Lyondell Basell Industries N.V. |
| AGRANA Beteiligungs-AG |
| Cremer Oleo GmbH Co.KG |
| Others |
Supply Flow & Price Mechanics
Corn futures volatility at Chicago Board of Trade cascades through ethanol production economics, compressing margins for fuel-grade processors while pharmaceutical-grade premiums widen against industrial benchmarks. This feedstock-cost transmission shapes a bifurcated pricing architecture where certification burden separates margin capture from volume commoditization.
Pricing Analysis
Volume concentrates in Industrial Grade fuel-additive contracts, while Pharmaceutical Grade commands margin premiums through USP-EP certification moats. Price differentiation hinges on purity thresholds and regulatory compliance intensity, with fuel-grade spot markets absorbing corn-price volatility and pharmaceutical long-term offtakes locking in supply security. Pricing pressure intensifies in industrial tiers as EU REACH purification mandates elevate processing costs without corresponding price recovery. Fuel-blend buyers exhibit highest price sensitivity; biopharma manufacturers demonstrate lowest sensitivity due to qualification switching costs.
Supply Chain Analysis
Regional distribution centers in Iowa, South Dakota, and Nebraska anchor hub-and-spoke patterns for corn-ethanol origination, with molecular sieve dehydration modules positioned proximate to Ludwigshafen and Leverkusen chemical clusters. Supply concentrates in the United States, Germany, and India for distinct grade tiers. Raw material dependencies include corn feedstock, molecular sieve desiccants, and natural gas for thermal dehydration. Single-source vulnerability permeates pharmaceutical-grade supply where USP-EP certification timelines freeze working capital. Distribution runs through direct sales channels for pharmaceutical buyers and regional chemical distributors for industrial offtake.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a cost-of-compliance story where EU REACH and FDA USP monographs erect barrier-to-entry moats that reward incumbent certification investments and punish undercapitalized challengers.
For Market Incumbents: Cement pharmaceutical-grade positioning through molecular sieve dehydration capacity additions in Germany's Rhine-Neckar corridor, locking in long-term API manufacturer contracts before cellulosic ethanol substitution threatens corn-ethanol fuel contracts. Prioritize backward integration into corn supply chains to buffer Chicago Board of Trade volatility. For New Entrants and Emerging Players: Begin with CDSCO-compliant pharmaceutical-grade supply to Maharashtra and Gujarat API clusters under India's PLI scheme, where domestic production incentives outpace established import channels. Deploy modular pervaporation-molecular sieve hybrid units for distributed production with lower capital intensity than azeotropic distillation legacy assets. For Investors and Strategic Acquirers: The window for entry favors pharmaceutical-grade specialists with USP-EP certification depth over fuel-grade commodity processors facing cellulosic displacement. Monitor EPA Renewable Fuel Standard blending mandate revisions as inflection signal for corn-ethanol infrastructure stranded asset risk.| Strategic Initiative | Industry Significance |
|---|---|
| Molecular Sieve Capacity Expansion | Enables modular pharmaceutical-grade production closer to Ludwigshafen-Leverkusen demand clusters. |
| Backward Integration into Corn Supply | Locks in feedstock cost visibility against Chicago Board of Trade volatility for Iowa processors. |
| Direct Pharmaceutical Contracting | Bypasses fuel-ethanol distribution channels for Rhine-Neckar API manufacturers seeking supply security. |
| Hybrid Dehydration Technology Licensing | Reduces carbon intensity for Netherlands processors facing EU Green Deal emissions accounting pressure. |
| CDSCO Compliance Investment | Captures Maharashtra and Gujarat API demand scaling under India's PLI scheme incentives. |
Methodological Framework
Multi-period observation of EPA Renewable Fuel Standard credit markets, EU REACH regulatory amendments, and pharmaceutical-grade spot premiums anchored the trend analysis, supplemented by interviews with ethanol plant managers, biopharma procurement directors, chemical intermediate buyers, and molecular sieve technology suppliers. Secondary validation drew from EIA fuel-ethanol production data, ECHA substance registration databases, FDA USP monograph revisions, and SEC 10-K disclosures from agricultural processors. Bottom-up capacity assessments triangulated against top-down demand modeling across grade tiers and application segments.
Segment-weighting applied purity-grade stratification, end-use industry concentration, and regional regulatory cluster differentiation across the projection horizon. CAGRs derived from regression analysis of historical price-volume relationships and forward-looking capacity expansion announcements. Forecast inputs incorporated corn feedstock price trajectories, EPA mandate compliance credit dynamics, and pharmaceutical-grade qualification timeline assumptions.
Underlying measurement precision varies by segment; Pharmaceutical Grade carries tighter precision due to documented contract structures, while Laboratory Grade exhibits wider variance from fragmented academic purchasing. Forecasts reflect stated assumptions regarding regulatory continuity and feedstock supply stability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Organic Chemicals
Phenolic Board Market
Organic Chemicals
Organic Coating Market
Organic Chemicals
Synthetic and Bio-Based Aniline Market
Organic Chemicals
Dimethylformamide (DMF) Market
Organic Chemicals
Organocatalyst Market
Organic Chemicals
Acetylacetone Market
Organic Chemicals
Diethyl Ketone Market
Organic Chemicals
Alanine Market
Organic Chemicals
1,3-Dichloroacetone Market
Organic Chemicals
Oryzenin Market
Organic Chemicals
Cyclopentanone Market
Organic Chemicals
N-Hexyl Chloride Market
Organic Chemicals
Synthetic Antioxidants Market
Organic Chemicals
Ethylamine Market
Organic Chemicals
2-Iodophenol Market
Organic Chemicals
Chloro -Dimethylsilane (CAS 1066-35-9) Market