
 Wood Repair Epoxy Market | 2026-2036
Wood Repair Epoxy Market Size, Share, and Industry Trends Forecast 2026-2036
Wood Repair Epoxy Market Insights
Specialty retail and pro-dealer channels for wood repair epoxy is fragmenting as direct-to-contractor platforms capture specification influence. Sika AG leverages its construction chemicals footprint to anchor specification relationships with European carpentry workshops. Gorilla Glue Inc. competes through mass-market shelf presence and consumer brand recognition. Abatron Inc. specializes in heritage-grade formulations that meet stringent restoration standards.
Wood repair epoxy comprises two-part thermosetting systems based on bisphenol-A or bisphenol-F resins cured with amine hardeners, achieving compressive strengths exceeding 10,000 psi and bonding dissimilar substrates including oak, teak, and mahogany. Paste epoxy leads application volumes in structural timber repair due to its gap-filling viscosity and sag resistance on vertical surfaces. Liquid epoxy represents the fastest-expanding product category as marine woodwork applications demand deep-penetrating consolidation treatments for water-damaged hull frames. Artisan studios drive premium pricing for putty epoxy packaged in mini jars, where color-matching precision commands margin premiums over bulk formats.
EPA guidelines on volatile organic compound emissions shape formulation chemistry for US-manufactured wood repair epoxies, while REACH restrictions on aromatic amine hardeners redirect European product development toward aliphatic alternatives. The EU Green Deal's embodied carbon thresholds for construction materials extend compliance burdens to imported repair compounds. Stakeholders must monitor evolving chemical substance restrictions and certification requirements for heritage restoration projects.
Market Dynamics
Heritage timber restoration mandates across European regulatory frameworks are concentrating specification power in paste epoxy formulations, while marine consolidation treatments in German and Italian shipyards reshape procurement volumes toward liquid systems.
Growth Catalysts
- EU Green Deal embodied carbon thresholds:Construction material compliance burdens extend to imported repair compounds, redirecting formulation development toward low-carbon aliphatic hardener alternatives.
- Historic preservation agencies:Reversible repair protocol mandates for heritage timber structures accelerate demand for paste epoxy with gap-filling viscosity and sag resistance.
- Marine woodwork modernization:German and Italian shipyards are concentrating procurement volumes as aging fleet refurbishment drives deep-penetrating liquid epoxy consolidation treatments.
Market Restraints
- REACH aromatic amine restrictions:European product development faces formulation redirection costs toward aliphatic hardener alternatives, compressing margin structures for heritage-grade compounds.
- Bisphenol-A resin input volatility:Petrochemical feedstock price swings directly transmit to two-part thermosetting system cost structures, constraining small-batch artisan studio pricing flexibility.
- Epoxy-putty substitution by traditional wood fillers:Cost-sensitive consumer segments in mass retail channels retain preference for lower-performance cellulose and vinyl-based alternatives.
Strategic Opportunities
- Direct-to-contractor platform expansion:Specialty retail and pro-dealer channel fragmentation creates specification influence capture opportunities for digital procurement platforms serving European carpentry workshops.
- Heritage-grade color-matching precision:Artisan studio demand for mini-jar putty epoxy with substrate-specific tinting commands premium positioning above bulk format commoditization.
- EPA VOC emission guideline alignment:US-manufactured formulation chemistry adapted for volatile organic compound compliance enables cross-Atlantic product standardization economies.
Industry Challenges
- Amine hardener certification timelines:REACH-compliant aliphatic alternative qualification for heritage restoration projects extends product development cycles beyond traditional 18-month windows.
- Dissimilar substrate bonding expertise:Oak, teak, and mahogany consolidation treatments require specialized application training that concentrates skilled technician availability in German and Italian maritime clusters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wood Repair Epoxy Market |
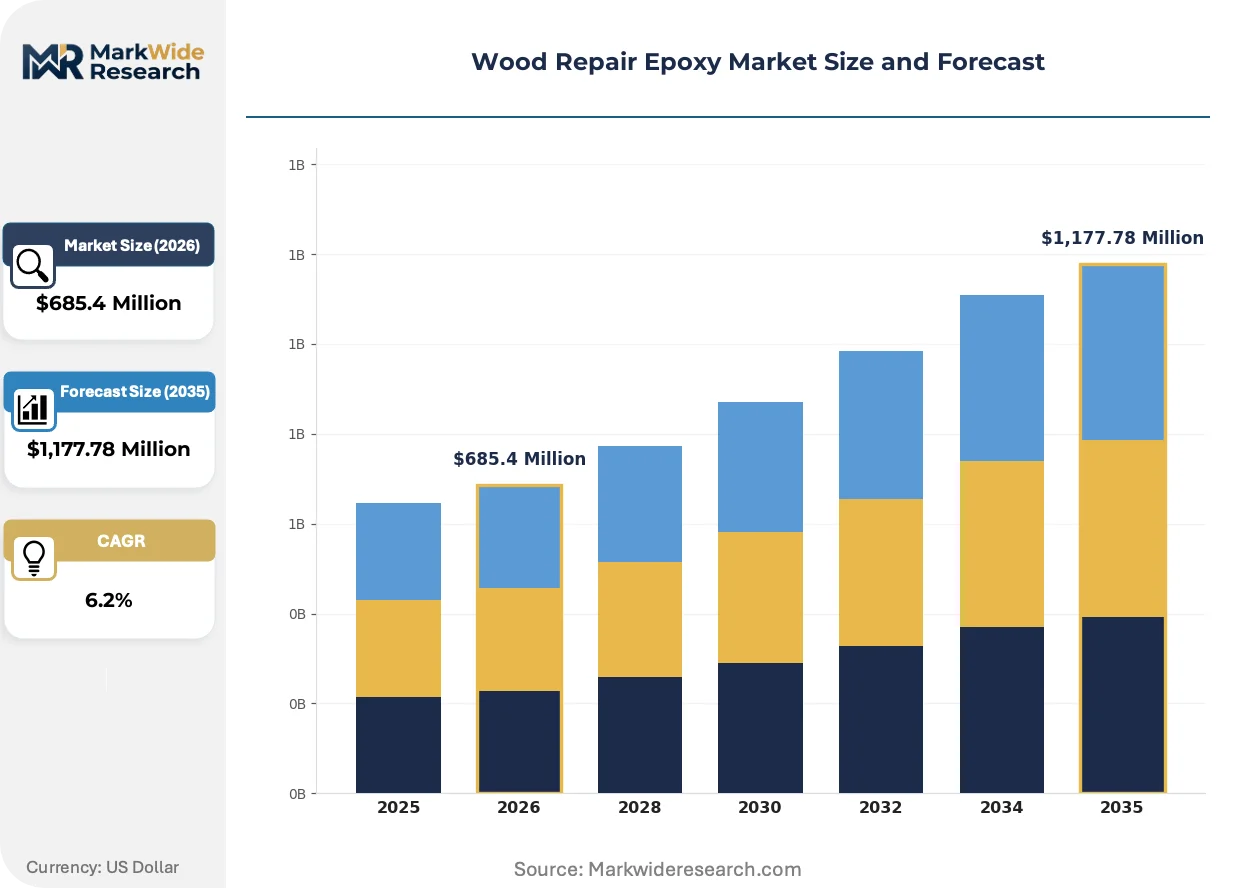
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,177.78 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Epoxy, Paste Epoxy, Putty Epoxy, Wood Filler Epoxy Application: Furniture Restoration, Marine Woodwork, Structural Repair, Decorative Artworks End User: Carpentry Workshops, Shipyards, Construction Firms, Artisan Studios Packaging Type: Twin-Tube, Syringe, Bulk Containers, Mini Jars |
| Companies Covered | 3M, Sika AG, Henkel AG & Co. KGaA, Mapei, Parker Hannifin Corporation, Gorilla Glue Inc., Abatron Inc, J-B Weld Company, System Three Resins, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wood Repair Epoxy Market Trends and Innovations
Formulation chemistry is pivoting toward regulatory-compliant hardener alternatives while digital procurement platforms restructure traditional distribution hierarchies in construction chemicals.
Deep-penetrating liquid epoxy consolidation technology is virtualizing traditional surface-repair approaches in marine woodwork applications. German and Italian shipyards adopting these systems for water-damaged hull frame restoration are compressing treatment timelines from multi-week drying protocols to single-application cures. This capability is virtualizing the competitive boundary between repair and replacement economics in aging fleet refurbishment.
REACH restrictions on aromatic amine hardeners are redirecting European product development toward aliphatic alternatives with equivalent compressive strength profiles. Industrial consequence includes extended formulation qualification periods for heritage-grade paste epoxies seeking restoration-standard certification. Heritage timber contractors in France and Italy are responding by consolidating supplier relationships with firms demonstrating pre-qualified aliphatic compound portfolios.
Specification influence is migrating from pro-dealer shelf presence toward direct-to-contractor digital platforms with embedded technical documentation. Specialty retail channels serving European carpentry workshops face disintermediation pressure as these platforms capture project-level material decisions. This behavioral shift is most visible in German-speaking markets where workshop procurement centralization favors integrated specification-to-fulfillment workflows.
Wood Repair Epoxy Market Segmentation
Wood repair epoxy formulations diverge sharply across viscosity grades and cure profiles, with each segment serving distinct substrate conditions and application constraints. Procurement patterns cluster around performance specifications rather than brand loyalty, creating segmentation-driven supplier strategies.
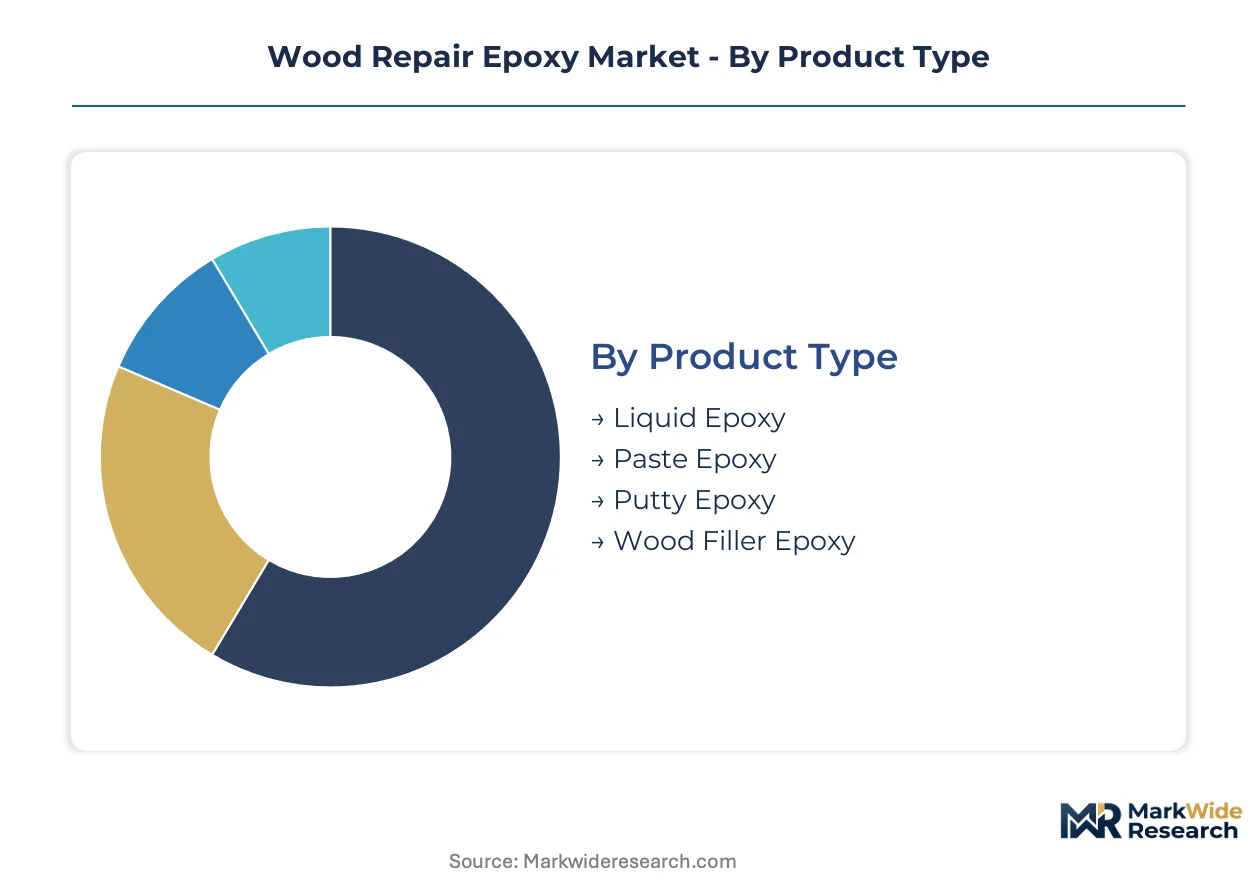
Product Type:
Cost tiers separate these formulations by raw material intensity and processing complexity.
- Paste Epoxy:Thixotropic bisphenol-A or bisphenol-F formulations with gap-filling viscosity above 50,000 cPs achieve sag resistance on vertical timber surfaces. Historic preservation agencies in France and Italy mandate paste systems for reversible heritage repairs, concentrating specification power with aliphatic hardener suppliers.
- Liquid Epoxy:Low-viscosity penetrating systems below 5,000 cPs consolidate water-damaged cellular structures through capillary action. German and Italian shipyards drive procurement volumes for hull frame restoration, compressing treatment timelines from multi-week drying to single-application cures.
- Putty Epoxy:Highly filled compounds with color-matching precision for surface finishing applications.
- Wood Filler Epoxy:Economy-grade cellulose-blended alternatives for non-structural cosmetic repairs.
Paste epoxy holds installed capacity. Liquid epoxy is rotating up the share rankings.
Application:
End-use environments dictate cure speed requirements and regulatory compliance burdens.
- Marine Woodwork:Saltwater immersion demands hydrolytic stability and moisture-tolerant curing chemistry. Deep-penetrating consolidation treatments for teak and mahogany hull frames in Mediterranean shipyards represent the steepest expansion trajectory as fleet refurbishment accelerates.
- Structural Repair:Load-bearing timber restoration requires compressive strength exceeding 10,000 psi and dissimilar substrate bonding. Oak framing in historic European buildings drives paste epoxy specification for gap-filling structural integrity.
- Furniture Restoration:Surface-level cosmetic repair with emphasis on stain compatibility and sandability.
- Decorative Artworks:Miniature-scale precision applications requiring extended working times and color stability.
Structural repair dominates current volumes. Marine woodwork is climbing the fastest.
End User:
Customer type determines procurement channel preference and technical support requirements.
- Shipyards:Industrial-scale buyers with centralized procurement and specification-to-fulfillment workflow integration. German and Italian maritime clusters concentrate skilled technician availability for specialized substrate bonding expertise.
- Carpentry Workshops:Fragmented European base migrating from pro-dealer channels toward direct-to-contractor digital platforms with embedded technical documentation.
- Construction Firms:Volume purchasers prioritizing bulk format economics and jobsite delivery reliability.
- Artisan Studios:Premium segment demanding mini-jar packaging with substrate-specific tinting for color-matching precision.
Shipyards anchor procurement scale. Artisan studios are gaining margin contribution fastest.
Packaging Type:
Volume and margin structure split across format scalability and application precision.
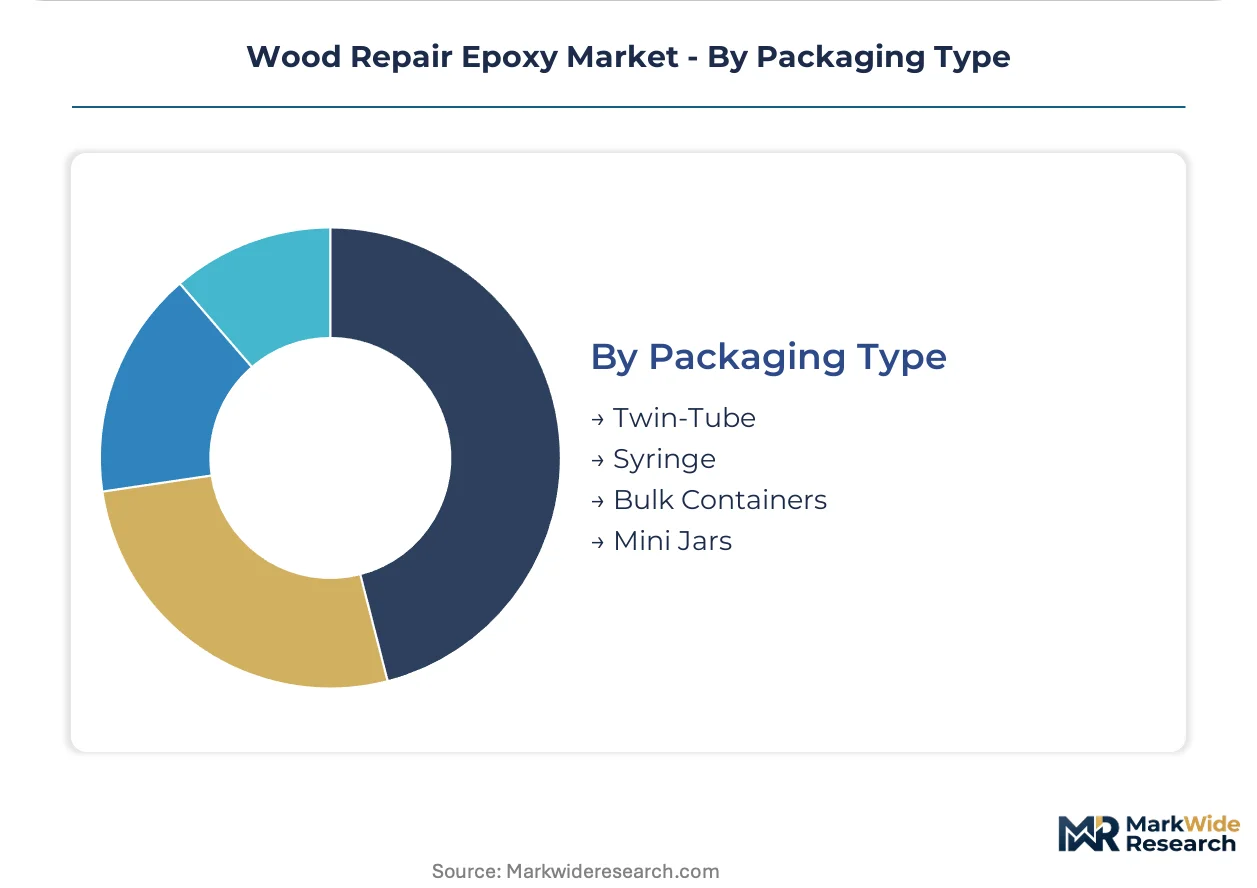
- Mini Jars:Artisan-grade portioning for heritage restoration color-matching commands premium positioning. French and Italian heritage timber contractors consolidate supplier relationships around pre-qualified aliphatic compound portfolios in this format.
- Bulk Containers:Industrial drum and pail formats for shipyard and construction firm volume procurement.
- Twin-Tube:Consumer-accessible side-by-side cartridges for controlled mixing ratios.
- Syringe:Precision-delivery systems for decorative artwork and detailed furniture restoration.
Bulk containers hold volume leadership. Mini jars are expanding share in value terms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German shipyards command premium pricing for marine-grade liquid epoxy systems, while Italian heritage restoration contractors absorb margin compression from REACH-compliant aliphatic hardener reformulation costs.
Germany
Marine woodwork modernization in Hamburg and Bremen shipyards concentrates procurement volumes for deep-penetrating hull frame consolidation treatments. KBA maritime safety standards mandate hydrolytic stability certification for saltwater immersion applications. The North Sea and Baltic maritime clusters anchor skilled technician availability for specialized teak and mahogany bonding expertise.
Italy
Historic preservation agencies in Rome and Florence enforce reversible repair protocols for Renaissance-era timber structures, accelerating paste epoxy specification. ECHA REACH restrictions on aromatic amines redirect formulation development toward aliphatic alternatives with equivalent compressive profiles. Venetian lagoon shipyards combine heritage restoration mandates with pleasure craft fleet refurbishment demand.
France
Artisan studios in Paris and Lyon drive premium positioning for mini-jar putty epoxy with substrate-specific color-matching precision. ANSM heritage material compliance extends qualification timelines for restoration-standard certification. The Île-de-France carpentry workshop base migrates toward direct-to-contractor digital procurement platforms with embedded technical documentation.
United States
EPA VOC emission guidelines shape formulation chemistry for bisphenol-A and bisphenol-F resin systems manufactured domestically. New England historic districts and Pacific Northwest timber framing markets concentrate demand for gap-filling paste viscosity above 50,000 cPs. Massachusetts and California regulatory stringency creates cross-state product standardization pressure.
United Kingdom
Heritage England conservation officers mandate reversible repair approaches for listed building timber structures, concentrating specification power with pre-qualified aliphatic compound portfolios. London and Edinburgh carpentry workshops fragment procurement across specialty retail and emerging direct-to-contractor channels. The Construction Products Regulation alignment post-Brexit maintains CE marking equivalence for epoxy repair compounds.
Wood Repair Epoxy Market Competitive Landscape
Construction chemical conglomerates and specialty adhesive specialists split the market along specification-influence versus mass-market accessibility vectors. Tier-one players anchor relationships with European carpentry workshops through embedded technical service capabilities. Three archetypes dominate: diversified construction chemical groups with heritage restoration certification portfolios; mass-market consumer brands with retail shelf dominance; and artisan-grade specialists with color-matching precision capabilities. Competitive dynamics center on aliphatic hardener pre-qualification speed and direct-to-contractor platform capture.
Among diversified construction chemical groups, Sika AG and Henkel AG & Co. KGaA exemplify the specification-relationship archetype through their European workshop anchoring strategies. Gorilla Glue Inc. occupies the mass-market accessibility position with consumer brand recognition driving retail channel presence. Abatron Inc. represents the heritage-grade specialist tier, where restoration-standard certification and substrate-specific formulation capabilities command premium positioning above commoditized bulk formats.
| Leading Market Players |
|---|
| 3M |
| Sika AG |
| Henkel AG & Co. KGaA |
| Mapei |
| Parker Hannifin Corporation |
| Gorilla Glue Inc. |
| Abatron Inc |
| J-B Weld Company |
| System Three Resins, Inc. |
| Others |
Pricing and Supply Chain Analysis
Rotterdam-Antwerp barge freight corridors for bisphenol-A resin feedstock concentrate supply-side leverage among German and Dutch chemical processors, transmitting petrochemical volatility directly into paste epoxy pricing tiers while compressing margin structures for small-batch heritage-grade suppliers.
Pricing Analysis
The customization-premium spread between artisan-grade mini-jar putty epoxy and bulk liquid systems for shipyard procurement runs from 3x to 8x on a per-kilogram basis. Three-tier pricing structure across heritage-certified, industrial-grade, and economy cellulose-blended levels separates specification-driven buyers from cost-sensitive retail consumers. Pricing pressure stems from REACH-compliant aliphatic hardener reformulation costs absorbing margin in European heritage restoration channels. Artisan studios demonstrate lowest price sensitivity due to substrate-specific color-matching requirements, while mass-market retail channels exhibit highest elasticity to cellulose filler substitution.
Supply Chain Analysis
Tariff exposure between US Gulf Coast petrochemical hubs and EU formulation plants dominates supply chain risk calculus for bisphenol-F resin alternatives. Raw material concentration centers on Germany, Netherlands, and Belgium for epoxy resin precursors, with amine hardener specialty chemicals anchored in Swiss and German pharmaceutical-chemical clusters. Formulation chemistry draws from petrochemical feedstocks, aliphatic amine intermediates, and mineral filler additives. Single-source vulnerability persists for REACH-compliant aliphatic hardener qualification timelines extending beyond traditional product development windows. Distribution runs through direct-to-contractor digital platforms disintermediating traditional pro-dealer networks in German-speaking markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized substrate bonding expertise for oak-teak-mahogany consolidation treatments concentrates in maritime clusters, creating capability scarcity that rewards firms with pre-qualified aliphatic compound portfolios and embedded technical service capacity.
For Market Incumbents: Harden specification relationships with European heritage timber contractors through accelerated aliphatic hardener certification investments, defending against emerging digital procurement platforms capturing project-level material decisions. Prioritize backward integration into amine hardener intermediates to compress reformulation cost absorption from REACH aromatic amine restrictions. Anchor capacity in German and Italian maritime clusters where skilled technician availability creates natural barriers to competitor replication. For New Entrants and Emerging Players: Artisan studios in France and Italy represent the most penetrable entry point for heritage-grade color-matching precision capabilities underserved by bulk-format incumbents. Marine woodwork consolidation treatments for Mediterranean pleasure craft fleets offer secondary white-space expansion as fleet refurbishment accelerates. Go-to-market execution should embed substrate-specific technical documentation within direct-to-contractor digital platforms capturing specification influence from fragmented carpentry workshop procurement. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors heritage-grade specialists with pre-qualified aliphatic compound portfolios and restoration-standard certification moats. Long-term viability across the analysis window rests on regulatory compliance speed rather than manufacturing scale. Acquisition target archetype: mid-cap formulation houses with embedded technical service relationships in French and Italian heritage restoration markets. Signal to monitor: ECHA substance restriction expansion timelines compressing qualification windows for non-compliant competitors.| Strategic Initiative | Industry Significance |
|---|---|
| Aliphatic Hardener Certification Investment | REACH-compliant qualification accelerates specification capture in heritage restoration channels. |
| Direct-to-Contractor Platform Development | Digital procurement integration captures project-level decisions from fragmented carpentry workshops. |
| Backward Integration into Amine Intermediates | Captive supply of hardener precursors compresses margin erosion from petrochemical volatility. |
| Heritage-Grade Color-Matching Precision Expansion | Artisan studio mini-jar positioning commands premium pricing above bulk commoditization. |
| Maritime Cluster Technical Service Capacity | Embedded expertise in teak-mahogany bonding creates defensible specification relationships. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of ECHA substance restriction databases, customs trade data for epoxy resin imports, and construction chemical industry association reports. Primary interviews engaged formulation chemists at heritage restoration compound suppliers, procurement directors at German and Italian shipyards, technical directors at European carpentry workshop associations, and regulatory affairs leads navigating REACH compliance pathways. Secondary validation drew from EU Green Deal construction material guidelines, EPA VOC emission technical documents, and national historic preservation agency procurement specifications. Bottom-up demand modeling triangulated against top-down chemical industry production capacity assessments.
Forecast inputs include viscosity-grade segmentation dynamics, end-use application growth differentials, and regulatory compliance timeline impacts across the projection horizon. Segmentation dimensions encompass product type tiers, application environments, end-user procurement channel preferences, and packaging format scalability. CAGRs derived from regression analysis of historical volume trajectories adjusted for regulatory inflection points and fleet refurbishment cycle timing. Industry-specific inputs incorporate aliphatic hardener substitution elasticity and digital platform penetration rates in workshop procurement.
Macroeconomic conditions sit as an overlay; deviation in petrochemical feedstock pricing, maritime construction investment cycles, or heritage restoration funding allocation would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory implementation timelines and substitution technology readiness. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Europe Flock Adhesives Market
Adhesives & Sealants
Brazil Sealants Market
Adhesives & Sealants
Tissue Adhesives Market
Adhesives & Sealants
Wood to Metal Glue Market
Adhesives & Sealants
Bio-Based Adhesive and Sealant Market
Adhesives & Sealants
Industrial Wood Adhesives Market
Adhesives & Sealants
South America Epoxy Adhesives Market
Adhesives & Sealants
Acrylates Copolymer Market
Adhesives & Sealants
Global Anti-Tack Agents Market
Adhesives & Sealants
Aqueous Acrylic Binders Market
Adhesives & Sealants
South America Electronics Adhesives Market
Adhesives & Sealants
Adhesive Dispensing Systems Market
Adhesives & Sealants
Asia-Pacific Bone Glue Market
Adhesives & Sealants
Moisture Curing Adhesives Market
Adhesives & Sealants
Active Metal Brazing (AMB) Paste Market
Adhesives & Sealants
North America Human Fibrin Glue Market