
 Si-C Anode Material Market | 2026-2036
Si-C Anode Material Market Size, Share, and Industry Trends Forecast 2026-2036
Si-C Anode Material Market Insights
Performance-based coating service contracts are decoupling material supply from cell validation outcomes, shifting risk to anode producers. BTR New Material Group leverages its integrated precursor-to-coating pipeline to capture recurring revenue streams. Shin-Etsu Chemical anchors its position through captive polysilicon supply that insulates against raw material volatility. Sila Nanotechnologies differentiates by embedding nano-composite engineering into long-term supply agreements with automotive cell makers.
Silicon-carbon anode material combines porous silicon structures with carbonaceous matrices to achieve specific capacities exceeding 2,000 mAh/g while mitigating volumetric expansion during lithiation. Manufacturers employ chemical vapor deposition coating techniques to encapsulate silicon nanoparticles within conductive carbon shells, creating composites that retain structural integrity across thousands of charge cycles. Composite materials command premium positioning as cell makers prioritize energy density thresholds for electric vehicle platforms. Consumer electronics applications sustain steady volume through thinner form-factor demands, though electric vehicles represent the dominant margin pool as OEMs qualify next-generation cell architectures.
China's NMPA and GB standards enforce rigorous battery safety testing that shapes Si-C composite qualification protocols for domestic cell manufacturers. South Korea's MFDS and KATS frameworks coordinate with METI in Japan on cross-border material certification, creating aligned but distinct compliance pathways. The EU Battery Regulation and REACH chemical restrictions are extending due diligence requirements to anode precursor supply chains. Stakeholders must monitor how solid-state battery development timelines intersect with Si-C capacity buildout decisions.
Market Dynamics
Cell manufacturers are decoupling material qualification from volume procurement, forcing anode suppliers to absorb validation risk before securing long-term offtake agreements.
Growth Catalysts
- China's dual carbon goals:Beijing's 2030 carbon peak mandate accelerates domestic qualification timelines for next-generation anode materials in electric vehicle battery supply chains.
- Energy density thresholds:OEMs now specify minimum 300 Wh/kg cell targets, pulling silicon-carbon composites into platform designs previously reserved for graphite-only architectures.
- South Korean cell cluster expansion:Dedicated production lines in Gwangyang and Ochang are scaling to supply Hyundai and Samsung SDI qualification programs.
Market Restraints
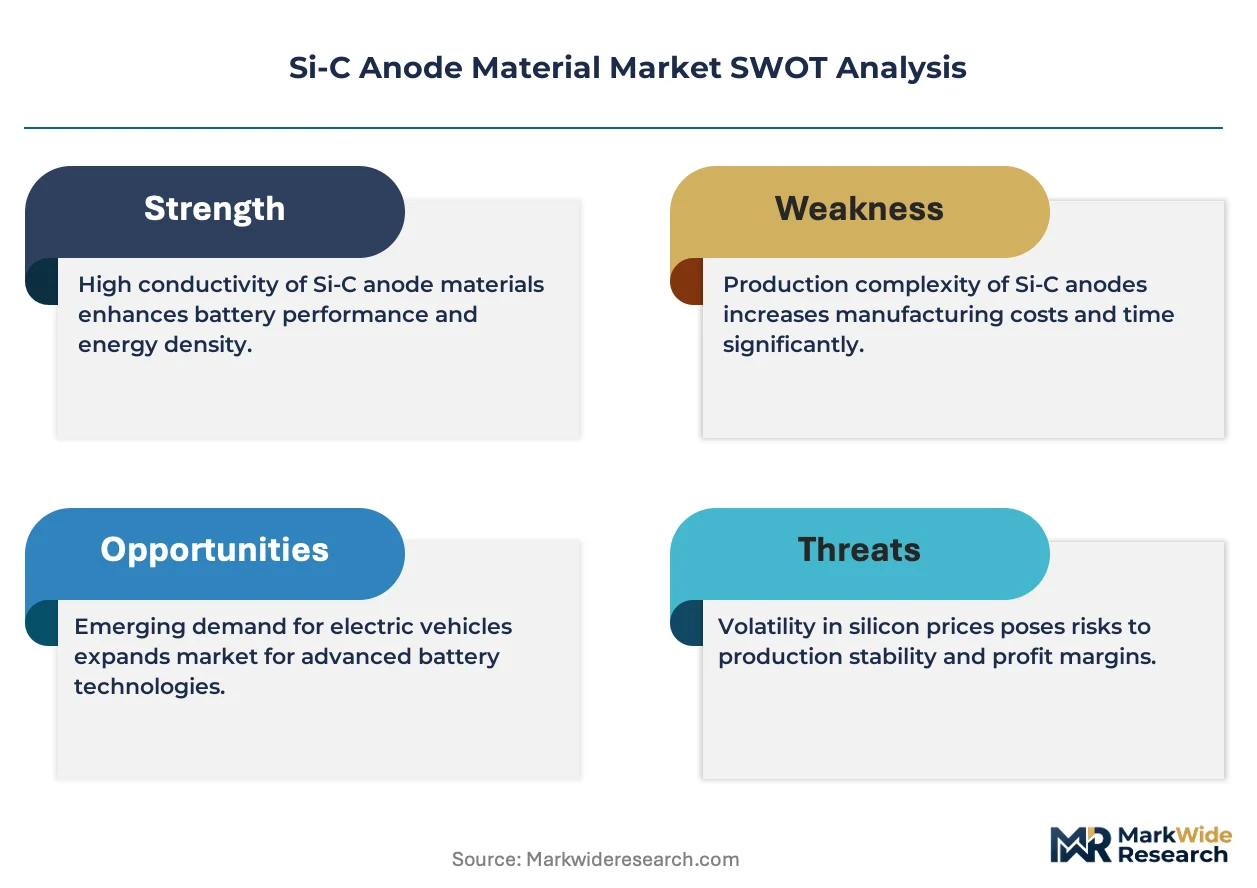
- Polysilicon cost volatility:Metallurgical-grade silicon prices swing with solar panel demand cycles, compressing anode producer margins during upstream tightness.
- Single-source precursor dependence:High-purity silane gas concentrates among semiconductor chemical suppliers, creating supply vulnerability for CVD coating operations.
- Solid-state battery substitution:Lithium-metal anode development in Toyota and QuantumScape roadmaps threatens Si-C addressable market if commercialization accelerates.
Strategic Opportunities
- India's PLI scheme for cell manufacturing:Reliance Industries and Ola Electric are qualifying anode suppliers for domestic gigafactory ramp-ups.
- Consumer electronics form-factor demands:Wearable device manufacturers are specifying sub-3 mm cell thicknesses that silicon-carbon's volumetric advantage enables.
- EU Battery Regulation due diligence:Carbon footprint disclosure mandates are favoring European-located anode coating facilities against Asian imports.
Industry Challenges
- Electrode slurry formulation expertise:Cell makers report 18-month qualification cycles to optimize binder systems for silicon's 300% volume expansion.
- Dry electrode coating capex:Maxwell-style solvent-free processes require $200 million-plus equipment commitments before volume production.
- Cross-border certification fragmentation:China's GB standards, South Korea's KATS frameworks, and EU REACH restrictions create divergent testing protocols for identical material grades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Si-C Anode Material Market |
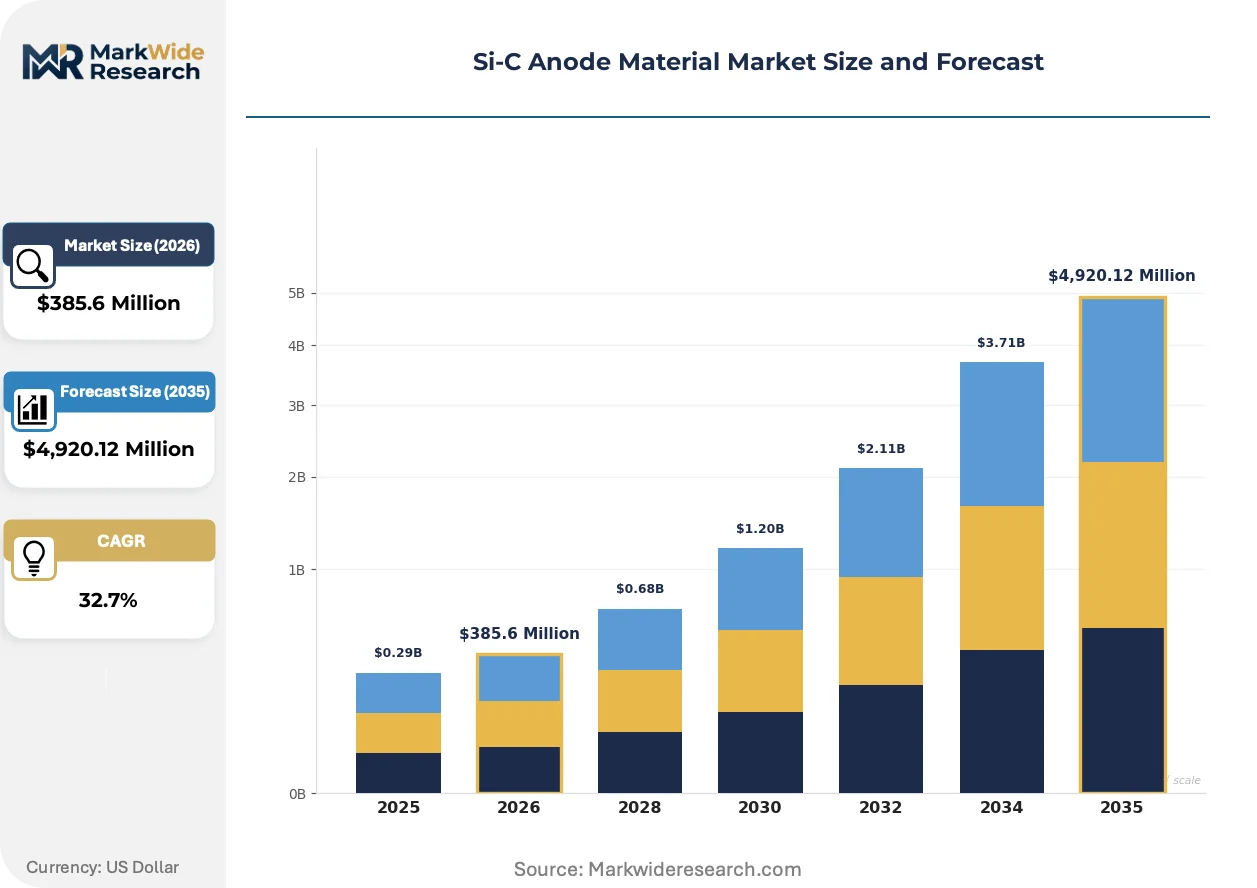
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $4,920.12 Million |
| CAGR (2026 – 2036) | 32.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Graphite, Synthetic Graphite, Silicon, Composite Materials Application: Consumer Electronics, Electric Vehicles, Energy Storage, Industrial Equipment End User: Automotive, Electronics Manufacturers, Energy Providers, Research Institutions Technology: Coating Techniques, Synthesis Methods, Battery Design, Electrode Fabrication |
| Companies Covered | BTR New Material Group, Shin-Etsu Chemical, Ningbo Shanshan, Resonac Holdings Corporation, POSCO Future M, Mitsubishi Chemical Group, Group14 Technologies, Sila Nanotechnologies, Nexeon, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Si-C Anode Material Market Trends and Innovations
Manufacturing process intensification is compressing the boundary between precursor synthesis and final coating, collapsing traditional multi-step supply chains into integrated production nodes.
Pre-lithiated silicon-carbon composites are electrifying cell formation economics by eliminating first-cycle capacity loss that previously required 15-20% excess cathode material. Korean cell makers are adopting these materials for 2025 platform launches. The technology is electrifying competitive positioning among anode suppliers capable of delivering stabilized capacities above 2,000 mAh/g.
REACH chemical restrictions are extending due diligence requirements to anode precursor supply chains, forcing importers to document carbon intensity and conflict mineral status. ECHA's 2024 SVHC candidate list now encompasses several silicon processing reagents. European cell manufacturers are responding by qualifying domestic coating facilities ahead of 2027 compliance deadlines.
Performance-based contracting is displacing traditional tonnage-based procurement as automotive OEMs transfer cycle-life risk to material suppliers. Cell makers now withhold 30-40% of contract value until validation milestones are met. This shift is most visible in South Korea, where Hyundai's E-GMP platform suppliers have restructured agreements around driving-range guarantees rather than material specifications.
Si-C Anode Material Market Segmentation
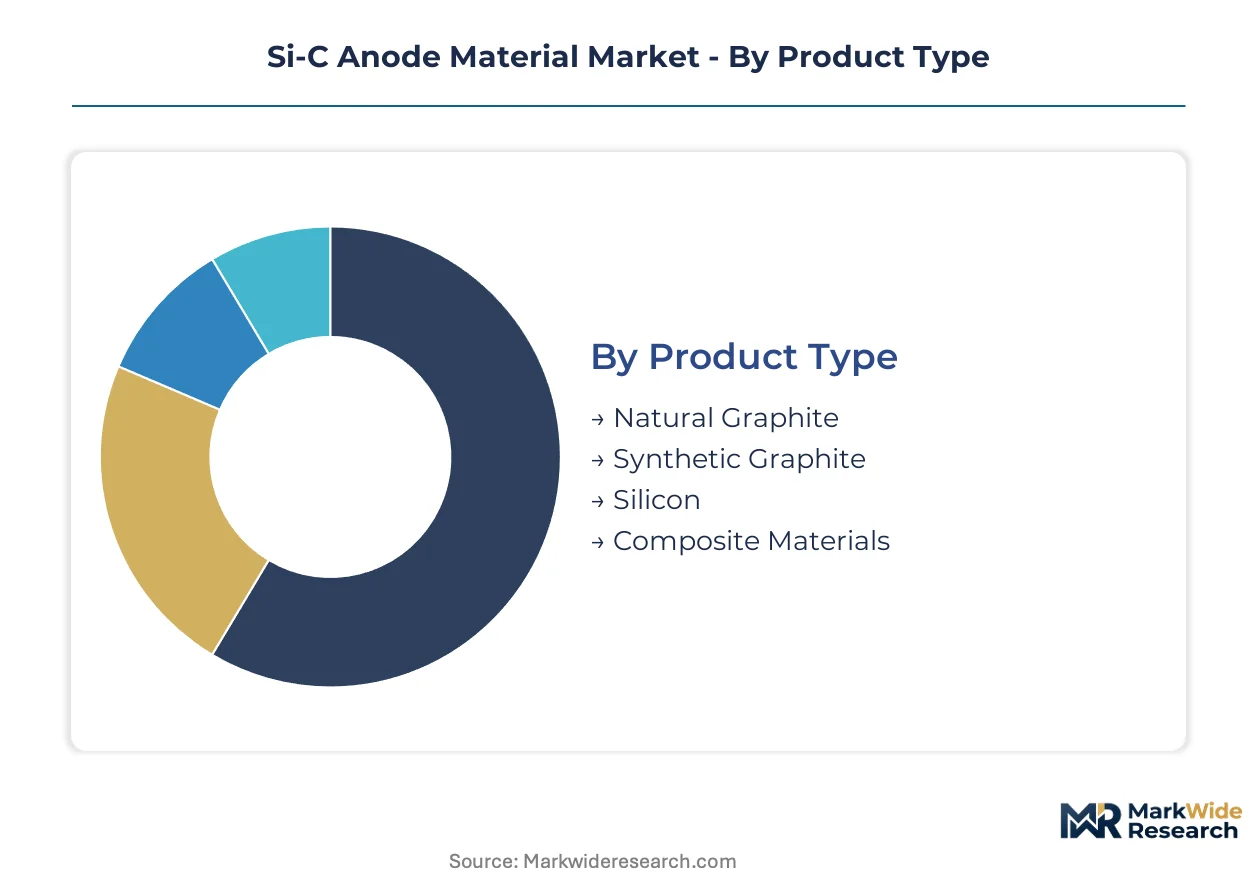
Si-C anode material procurement patterns diverge sharply across end-use applications, with electric vehicle battery makers prioritizing energy density thresholds while consumer electronics OEMs optimize for volumetric efficiency. Understanding these segment-specific qualification protocols and volume trajectories enables suppliers to align capacity investments with margin-accretive demand pools.
Product Type:
Buyers in this category differentiate primarily by performance tier and cost sensitivity, with automotive cell makers absorbing premiums for advanced composites while industrial applications remain anchored to graphite economics.
- Composite Materials:Silicon-carbon composites integrate porous silicon structures within conductive carbon matrices to deliver specific capacities exceeding 2,000 mAh/g. Korean cell manufacturers at Hyundai and Samsung SDI are concentrating procurement for 2025 platform launches where energy density thresholds mandate graphite alternatives. Chemical vapor deposition coating techniques dominate production, though polysilicon cost volatility compresses margins during upstream tightness.
- Silicon:Nano-structured silicon anodes achieve the highest theoretical capacity among commercial options but require sophisticated binder systems to manage 300% volumetric expansion during lithiation. Research institutions and specialty electronics manufacturers sustain niche demand while electrode slurry formulation expertise limits broader qualification.
- Natural Graphite:Lower-cost feedstock for blended anode formulations where silicon loading remains below 10% by mass.
- Synthetic Graphite:Higher-purity alternative with controlled particle morphology for premium cell architectures.
Composite materials lead volumes today; silicon is gaining share fastest among next-generation qualification programs.
Application:
Volume concentration in this category tracks directly to cell manufacturing scale, with automotive platforms generating tenfold material throughput per gigawatt-hour against consumer electronics.
- Electric Vehicles:OEMs now specify minimum 300 Wh/kg cell targets that pull silicon-carbon composites into platform designs previously reserved for graphite-only architectures. China's dual carbon goals accelerate domestic qualification timelines for next-generation anode materials across BYD, CATL, and CALB supply chains. South Korean cell cluster expansion at Gwangyang and Ochang scales dedicated production lines to supply Hyundai E-GMP and Samsung SDI programs.
- Consumer Electronics:Wearable device manufacturers specify sub-3 mm cell thicknesses that silicon-carbon's volumetric advantage enables. Apple's supply chain and Samsung Electronics sustain steady volume through thinner form-factor demands, though margins compress against automotive contracts.
- Energy Storage:Grid-scale battery projects prioritize cycle life over energy density, limiting silicon adoption to demonstration installations.
- Industrial Equipment:Forklift and material handling applications maintain graphite dominance due to cost sensitivity and moderate performance requirements.
Electric vehicles anchor revenue concentration; consumer electronics delivers the steadiest volume trajectory.
End User:
Procurement sophistication separates this category, with automotive OEMs imposing performance-based contracting while research institutions tolerate material variability for experimental programs.
- Automotive:Cell manufacturers are decoupling material qualification from volume procurement, forcing anode suppliers to absorb validation risk before securing long-term offtake agreements. Hyundai's E-GMP platform suppliers have restructured agreements around driving-range guarantees rather than material specifications, withholding 30-40% of contract value until validation milestones are met.
- Electronics Manufacturers:Consumer-facing OEMs prioritize supply security and form-factor flexibility over absolute energy density, creating stable demand for mid-tier composite grades.
- Energy Providers:Utility-scale storage developers emphasize total cost of ownership calculations that disadvantage premium silicon-carbon materials.
- Research Institutions:Academic and national laboratory demand concentrates on experimental silicon architectures and pre-lithiated formulations for publication and patent generation.
Automotive end users command the largest contract values; electronics manufacturers offer the most predictable procurement cadence.
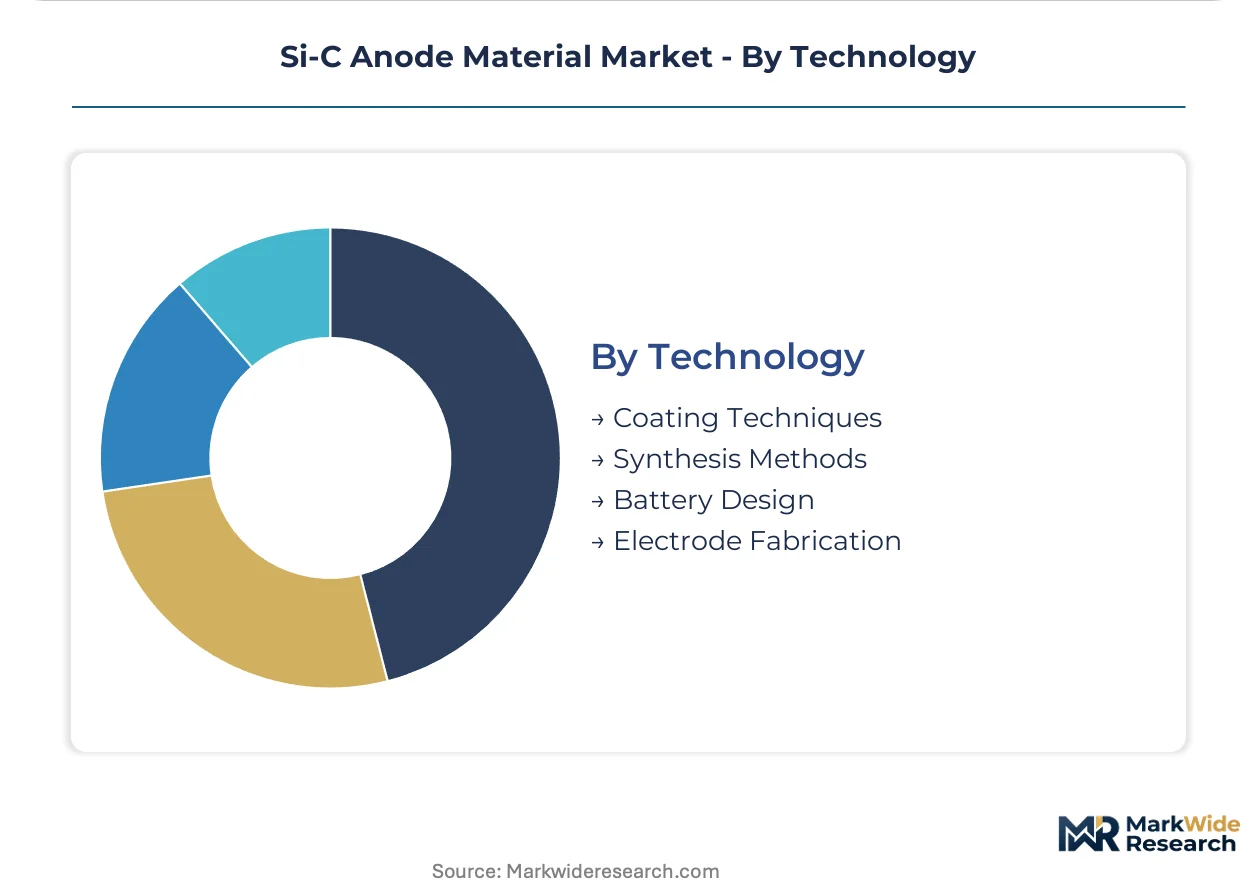
Technology:
Capital intensity and intellectual property concentration define buyer differentiation here, with coating technique specialists capturing recurring revenue while synthesis method innovators struggle to scale.
- Coating Techniques:Chemical vapor deposition encapsulates silicon nanoparticles within conductive carbon shells, creating composites that retain structural integrity across thousands of charge cycles. BTR New Material Group leverages its integrated precursor-to-coating pipeline to capture recurring revenue streams from cell makers seeking to outsource capital-intensive processing steps.
- Synthesis Methods:Pre-lithiated silicon-carbon composites electrify cell formation economics by eliminating first-cycle capacity loss that previously required 15-20% excess cathode material. Korean cell makers are adopting these materials for imminent platform launches, electrifying competitive positioning among suppliers capable of delivering stabilized capacities above 2,000 mAh/g.
- Battery Design:Cell architecture decisions determine silicon loading limits and electrode thickness constraints that cascade back to material specifications.
- Electrode Fabrication:Dry electrode coating processes require $200 million-plus equipment commitments before volume production, concentrating procurement among capital-rich tier-one cell makers.
Coating techniques dominate installed capacity; synthesis methods are climbing the fastest as pre-lithiation gains commercial traction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's silicon-carbon qualification timelines outpace South Korea's cell cluster buildout, while Japan's METI coordination and Germany's EU Battery Regulation compliance create divergent pathways for anode material certification.
China
BYD, CATL, and CALB are expanding procurement of silicon-carbon composites to meet Beijing's dual carbon goals for 2030. NMPA and GB standards enforce rigorous battery safety testing that accelerates domestic qualification protocols. The Yangtze River Delta concentrates precursor synthesis and CVD coating operations serving these cell manufacturers.
South Korea
Hyundai and Samsung SDI are qualifying next-generation anode materials for E-GMP platform launches targeting 300 Wh/kg cell thresholds. MFDS and KATS frameworks coordinate material certification with automotive OEM validation cycles. Gwangyang and Ochang host dedicated Si-C production lines scaling to supply these qualification programs.
Japan
Toyota's lithium-metal anode development and Panasonic's cell manufacturing sustain demand for advanced anode research despite solid-state substitution risks. METI coordinates cross-border material certification with South Korean regulators through aligned testing protocols. Chubu and Kansai industrial corridors concentrate silicon processing expertise and chemical supplier networks.
Germany
BMW and Volkswagen are qualifying European-located anode coating facilities to meet EU Battery Regulation carbon footprint disclosure mandates. ECHA's 2024 SVHC candidate list extension to silicon processing reagents forces supply chain due diligence documentation. Bavaria and North Rhine-Westphalia host emerging coating facilities positioning ahead of 2027 compliance deadlines.
United States
Detroit-based OEMs and California EV startups are negotiating performance-based contracts that transfer cycle-life risk to material suppliers. EPA and NHTSA frameworks intersect with state-level zero-emission vehicle mandates in shaping procurement specifications. The Pacific Northwest and Texas host pilot-scale operations targeting automotive qualification programs.
Si-C Anode Material Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated precursor-to-coating pipelines commanding premium positioning against toll-coating service providers. The vendor base concentrates among chemical conglomerates with captive polysilicon supply, nanotechnology specialists with embedded composite engineering, and diversified material groups with backward integration into silicon sourcing. Three archetypes dominate: upstream-integrated chemical producers, nano-engineering technology licensors, and battery-focused material suppliers with dedicated anode divisions. Capacity expansion and strategic partnerships constitute the dominant competitive moves, as players secure offtake agreements before committing capital to CVD coating lines.
Within the upstream-integrated tier, Shin-Etsu Chemical and POSCO Future M exemplify archetypes leveraging captive raw material supply to insulate margin positions against polysilicon volatility. Among nanotechnology specialists, Sila Nanotechnologies occupies a position representing embedded composite engineering capabilities that differentiate supply agreements with automotive cell makers. These three companies anchor the competitive structure while the broader field includes diversified material groups and emerging technology developers.
| Leading Market Players |
|---|
| BTR New Material Group |
| Shin-Etsu Chemical |
| Ningbo Shanshan |
| Resonac Holdings Corporation |
| POSCO Future M |
| Mitsubishi Chemical Group |
| Group14 Technologies |
| Sila Nanotechnologies |
| Nexeon |
| Others |
Pricing and Supply Chain Analysis
Metallurgical-grade silicon feedstock moves from solar panel demand cycles through polysilicon refinement into three-tier pricing structure across premium, standard, and economy levels for anode coating operations. Chinese Yangtze River Delta producers capture margin premiums against South Korean toll-coating service providers as GB standards and MFDS frameworks impose divergent qualification cost burdens.
Pricing Analysis
Capacity additions in South Korea are reshaping price floors for CVD-coated composites as Gwangyang and Ochang facilities reach operational scale. Contract-based long-term offtake agreements dominate automotive procurement, with certification grade and volume scale as primary price differentiation drivers. Cost compression in standard-tier materials is intensifying because polysilicon volatility transfers upstream risk to coating operators. Consumer electronics manufacturers exhibit highest price sensitivity, while automotive cell makers absorb premiums for pre-lithiated formulations.
Supply Chain Analysis
Freight costs for high-purity silane gas concentrate supply chain leverage among semiconductor chemical suppliers serving CVD operations across China, South Korea, and Japan. Raw material sourcing draws from metallurgical-grade silicon refineries, carbon precursor manufacturers, and lithium stabilization reagent producers. Single-source vulnerability for silane gas creates structural risk if semiconductor demand cycles tighten availability. Distribution runs through integrated precursor-to-coating pipelines and toll-coating service providers to cell manufacturing clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Si-C anode material market functions as a regulatory compounder where EU Battery Regulation carbon footprint disclosure mandates and China's dual carbon goals accelerate qualification timelines and reshape procurement specifications.
For Market Incumbents: Anchor market position through captive polysilicon supply that insulates margin structures against solar panel demand volatility. Prioritize backward integration into high-purity silane gas production to eliminate single-source precursor vulnerability. Invest in pre-lithiation synthesis capabilities as Korean cell makers adopt stabilized capacity formulations for platform launches.
For New Entrants and Emerging Players: Digital qualification platforms offer entry pathways into automotive supply chains where cell manufacturers seek to decouple material validation from volume procurement. Target India's PLI scheme for cell manufacturing as Reliance Industries and Ola Electric qualify domestic anode suppliers for gigafactory ramp-ups. Pursue toll-coating service contracts that transfer capital equipment risk while capturing recurring revenue from cell makers outsourcing CVD processing.
For Investors and Strategic Acquirers: Consolidation pressure builds where dry electrode coating capex requirements exceed $200 million equipment commitments and concentrate procurement among capital-rich tier-one cell makers. Five-to-ten year viability favors nano-engineering specialists with embedded composite engineering capabilities and integrated precursor pipelines. Monitor solid-state battery development timelines at Toyota and QuantumScape as inflection indicators threatening Si-C addressable market expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silane Gas Production | Eliminates single-source precursor vulnerability for CVD coating operations serving Korean cell clusters. |
| Pre-Lithiation Synthesis Scale-Up | Captures Korean cell maker adoption of stabilized capacity materials for E-GMP platform specifications. |
| EU Coating Facility Qualification | Positions suppliers ahead of ECHA 2024 SVHC compliance deadlines for European automotive OEM procurement. |
| Performance-Based Contract Restructuring | Transfers cycle-life risk to material suppliers as Hyundai withholds contract value until validation milestones. |
| India PLI Scheme Supplier Qualification | Secures offtake agreements with Reliance Industries and Ola Electric domestic gigafactory programs. |
Research Methodology
Coverage spans China, South Korea, Japan, Germany, and the United States, with primary inputs from each region combining interviews with cell manufacturer procurement directors, anode coating plant managers, polysilicon supplier sales leads, and automotive OEM platform engineers. Secondary validation draws from NMPA GB standard filings, ECHA SVHC candidate list updates, METI coordination protocols, customs trade data for silicon precursor flows, and SEC disclosures from listed material groups. Bottom-up capacity assessments and top-down demand projections triangulate volume estimates.
Rate-of-change decomposition separates volume growth from price trajectory across product type, application, end user, and technology segmentation dimensions. Modeled variables include silicon loading percentages in composite formulations, coating yield rates, and qualification timeline compression under regulatory acceleration. CAGRs derive from segment-specific adoption curves and automotive platform launch schedules throughout the forecast period.
The model assumes a particular technology adoption path; alternative pathways for lithium-metal anode solid-state architectures would alter the outlook if Toyota and QuantumScape commercialization accelerates. Forecasts reflect assumptions regarding polysilicon cost stability, cross-border certification alignment, and dry electrode coating adoption rates. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advanced Materials
Bioactive Glass Market
Advanced Materials
Densified Silica Fume Market
Advanced Materials
Cathode Materials Market
Advanced Materials
High Nickel Cathode Materials Market
Advanced Materials
Global Advanced Phase Change Materials Market
Advanced Materials
Inorganic Non-Metallic Materials Market
Advanced Materials
Global Aluminum Honeycomb Market
Advanced Materials
Europe Next Generation Anode Materials Market
Advanced Materials
Thermal Spray Market
Advanced Materials
Glass Reinforced Vinyl Ester (GRV) Market
Advanced Materials
Europe Blanket Aerogel Market
Advanced Materials
Thermal Conductive Material Market
Advanced Materials
Silica Aerogel Market
Advanced Materials
Global Next Generation Anode Materials Market
Advanced Materials
North America Advanced Phase Change Materials Market
Advanced Materials
Graphite Materials Market