
 Saudi Arabia Plastic Bottles Market | 2026-2036
Saudi Arabia Plastic Bottles Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Plastic Bottles Market Insights
A capital-intensity divergence between blow-molding scale leaders and regional converters is redrawing competitive tiers in the Saudi Arabia plastic bottles landscape. Alpla Group leverages its integrated preform-to-bottle infrastructure across European-origin technology lines to sustain margin discipline in high-volume beverage contracts. National Plastic Factory anchors its position through geographic dominance in the Eastern Province industrial zone, while 3P Gulf Plastic Packaging Factory differentiates via specialized pharmaceutical-grade cleanroom bottle output.
Plastic bottles in the Saudi Arabian context denote hollow thermoplastic containers produced through extrusion blow molding, injection stretch blow molding, or injection blow molding, typically featuring barrier-enhanced PET or HDPE compositions with neck-finish precision measured in millimeters to ensure closure compatibility. These vessels serve primarily as primary packaging for liquids, semi-solids, and granular products across consumer and industrial supply chains. PET bottles command the largest volume share given their dominance in beverage and mineral water applications, while pharmaceutical-grade HDPE bottles capture concentrated margin pools due to SFDA compliance overhead and batch-traceability requirements. The 500ml to 1L capacity band exhibits the steepest growth trajectory, reflecting single-serve consumption patterns and on-the-go portability trends in the Kingdom's urban centers.
SFDA governs food-contact and pharmaceutical packaging standards through migration testing protocols and material safety certifications, while SASO enforces technical regulations on plastic product quality and labeling conformity. The Saudi Green Initiative and circular economy policy signals are pressuring converters toward recycled content integration and rPET qualification pathways. Stakeholders must monitor regulatory timeline announcements for mandatory recycled content thresholds and assess preform sourcing strategies against evolving domestic collection infrastructure capabilities.
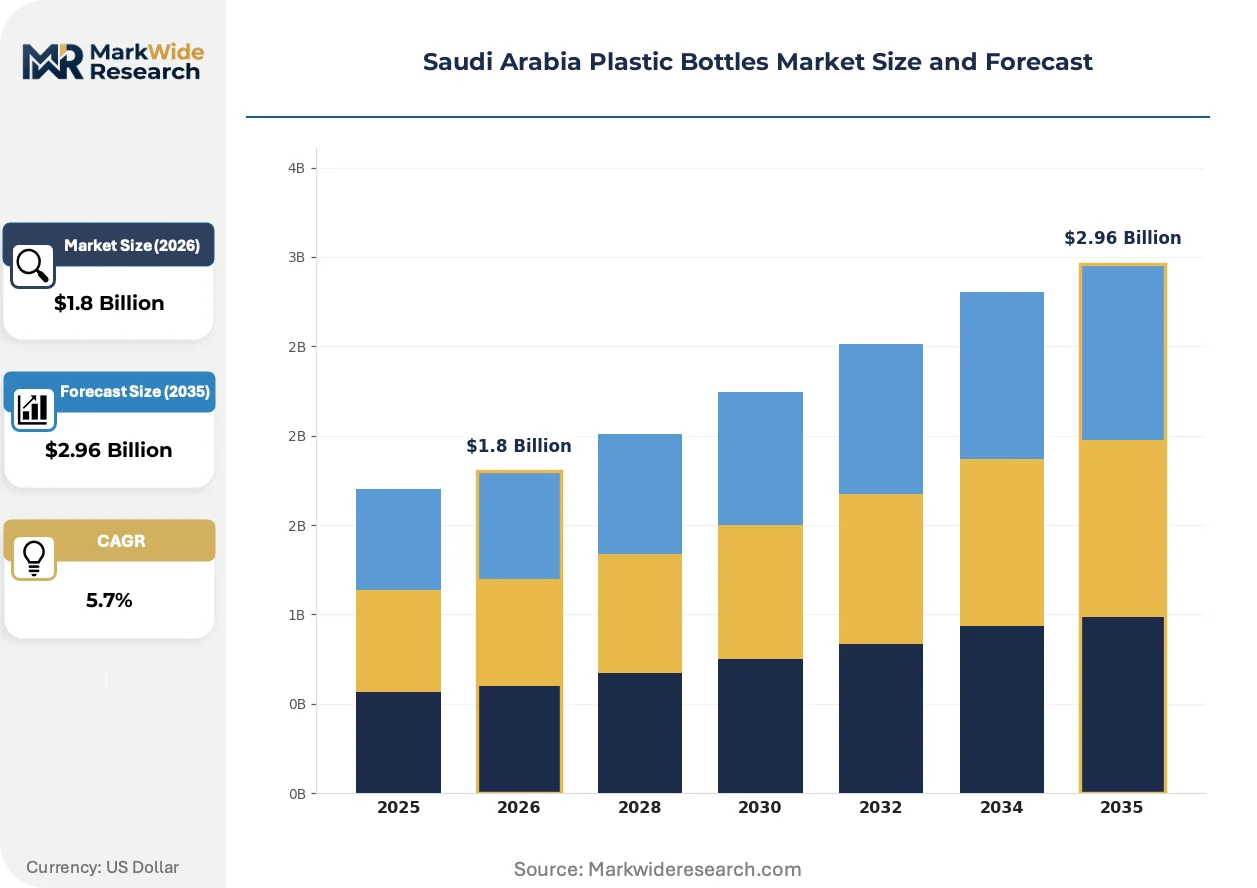
Market Dynamics
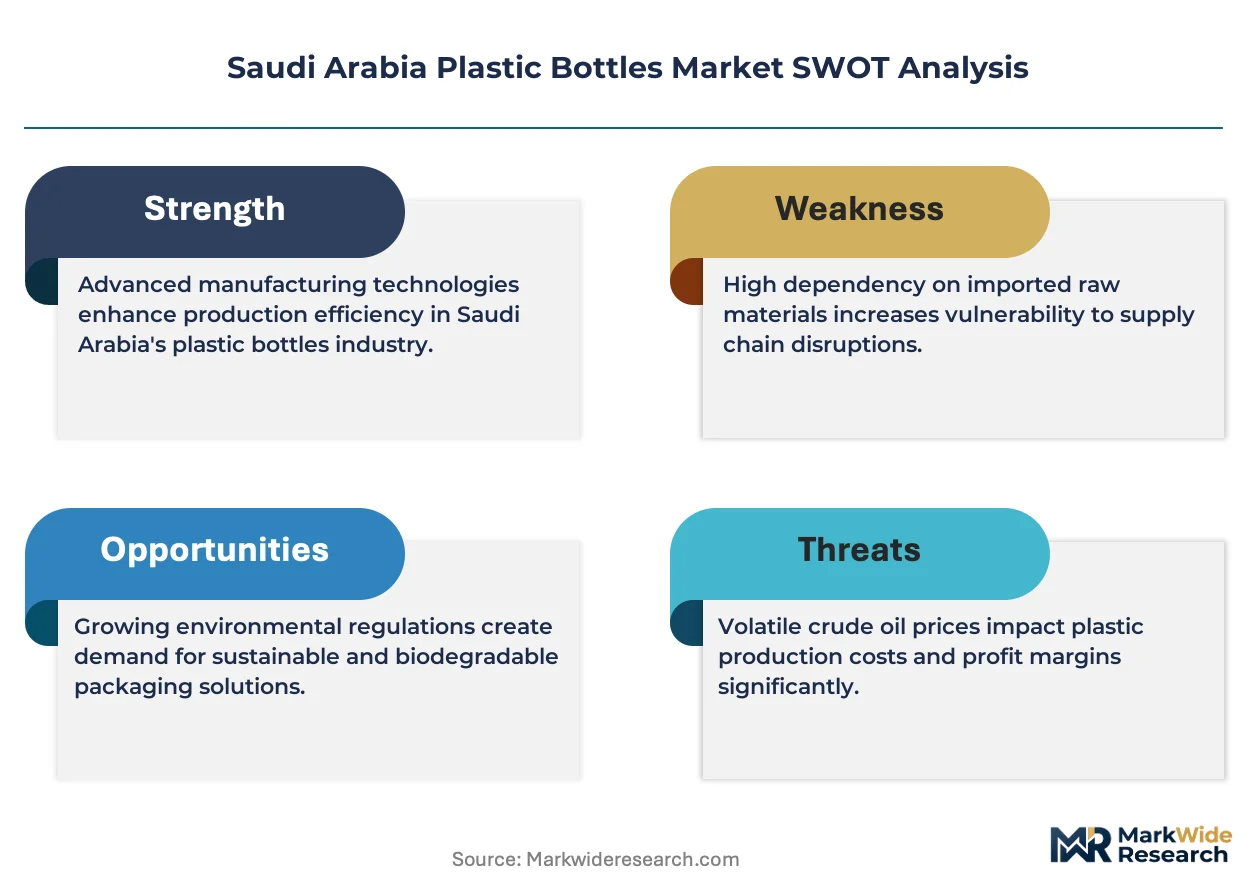
SFDA's tightened migration limits for food-contact materials are forcing converters to retool testing protocols and preform sourcing strategies, compressing margins for non-compliant regional suppliers while rewarding integrated blow-molding operators with captive laboratory capabilities.
Growth Catalysts
- SFDA Compliance Investments:The regulator's updated food-contact material standards are accelerating capital deployment into barrier-enhanced PET lines and migration testing infrastructure among Riyadh-Jeddah corridor converters.
- Beverage Bottling Expansion:Mega-beverage clusters across the Kingdom are commissioning dedicated PET packaging lines for mineral water and carbonated drinks, pulling preform demand toward high-cavitation injection stretch blow molding systems.
- Single-Serve Consumption:Urban portability trends in Riyadh and Jeddah are concentrating volume growth in the 500ml to 1L capacity band, favoring lightweighting investments and neck-finish standardization.
Market Restraints
- rPET Feedstock Scarcity:Domestic collection infrastructure for post-consumer PET remains underdeveloped, forcing converters to absorb premium pricing for imported flake or delay recycled content roadmaps.
- Eastern Province Supply Concentration:National Plastic Factory's geographic lock on the industrial zone creates single-source vulnerability for pharmaceutical-grade HDPE bottles, amplifying disruption risk from logistics bottlenecks.
- Pharmaceutical Compliance Overhead:SFDA batch-traceability requirements and cleanroom certification timelines extend qualification periods for new entrants, freezing price competition in high-margin therapeutic packaging.
Strategic Opportunities
- Central Region Dairy Processors:Untapped demand from ultrahigh-temperature milk and laban bottlers in Riyadh's food manufacturing belt offers white space for HDPE barrier bottle specialists with aseptic filling compatibility.
- Saudi Green Initiative Tailwinds:Circular economy policy signals are pressuring brand owners toward rPET qualification pathways, rewarding early movers with integrated collection partnerships and chemical recycling offtake agreements.
- E-Commerce Channel Penetration:Direct-to-consumer beverage subscriptions and pharmaceutical delivery platforms are fragmenting traditional distributor networks, creating demand for customized bottle formats with tamper-evident closures.
Industry Challenges
- Cleanroom Technician Scarcity:Pharmaceutical-grade bottle production requires operators trained in ISO 14644 particulate control and aseptic handling, a skill set concentrated among European and Asian expatriate workforces with limited local pipeline depth.
- Legacy Preform Inventory Reconciliation:Converters maintaining dual stockpiles of virgin and rPET preforms face working capital strain and batch segregation complexity during SFDA audit cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Plastic Bottles Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PET, HDPE, LDPE, PVC End User: Beverage, Cosmetics, Pharmaceuticals, Household Products Capacity: Less than 500ml, 500ml to 1L, 1L to 2L, More than 2L Closure Type: Screw Cap, Flip Top, Pump, Others |
| Companies Covered | Alpla Group, National Plastic Factory, 3P Gulf Plastic Packaging Factory, Arabian Plastic Industrial Co. (APICO), Saudi Plastic Packaging Systems, Zamil Plastic Industries Co., Saudi Modern Packaging Factory Co. Ltd. (Printopack), Takween Advanced Industries Co., Al-Sharq Plastics Industries, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Plastic Bottles Market Trends and Innovations
Barrier-enhanced packaging architectures and circular material flows are restructuring competitive advantage among Saudi converters, separating capital-intensive technology leaders from commodity blow-molding operators.
Multilayer co-injection PET with passive oxygen scavenger functionality is supplanting monolayer structures in sensitive beverage applications. Premium juice and functional drink bottlers in Jeddah's free zone are specifying these constructions for 12-month shelf life extension. The technology is compressing acceptable quality thresholds for regional converters lacking co-injection capability, concentrating high-margin contracts among European-technology licensees.
SASO technical regulations on plastic product labeling conformity are tightening traceability requirements for resin grade and manufacturing origin. Converters must now embed QR-linked batch data on bottle sidewalls, extending label application lines and validating digital printing investments. Pharmaceutical and infant nutrition segments are absorbing the highest compliance costs, passing specifications upstream to preform suppliers.
Direct procurement relationships between Riyadh-headquartered beverage multinationals and blow-molding operators are displacing traditional distributor intermediaries. Volume commitments now flow through annual tender platforms with technical scorecards weighting rPET roadmap credibility and energy consumption metrics. This disintermediation is most visible in the carbonated soft drink vertical, where three bottlers account for the majority of PET bottle offtake.
Saudi Arabia Plastic Bottles Market Segmentation
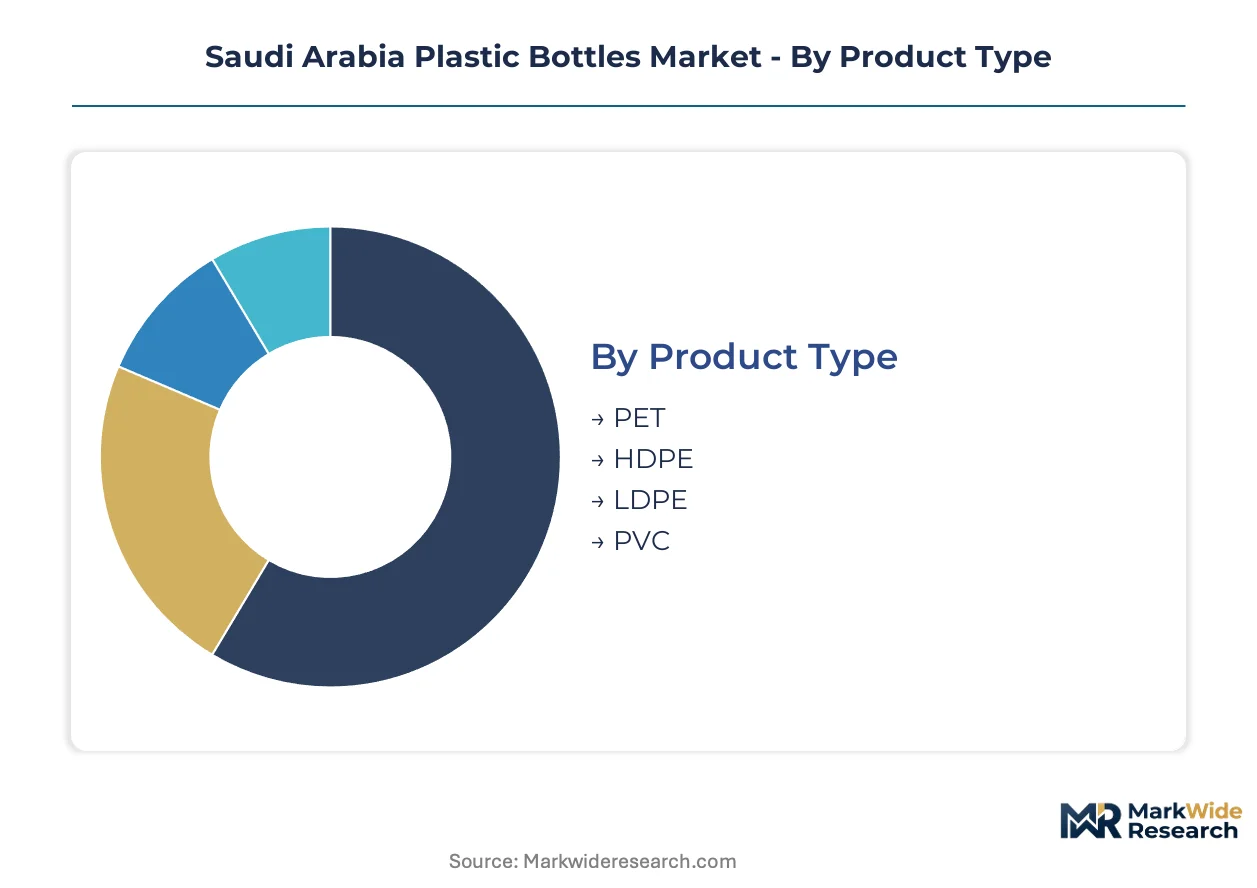
Segmentation in the Saudi Arabia plastic bottles market reveals how SFDA migration limits and beverage bottler procurement patterns concentrate margin pools across material grades and capacity bands. Converters must align production footprints with the Riyadh-Jeddah corridor's demand geography while navigating substitution threats from glass and aluminum packaging.
Product Type:
Substitution pressure from aluminum cans and glass bottles weighs most heavily on commodity resin grades lacking barrier functionality or recycled content credentials.
- PET:Injection stretch blow-molded polyethylene terephthalate dominates beverage applications with biaxial orientation delivering clarity and carbonation retention. Mega-bottlers in Jeddah's industrial zone specify virgin and rPET blends for mineral water and carbonated drinks, though imported flake scarcity constrains recycled content roadmaps.
- HDPE:Extrusion blow-molded high-density polyethylene serves pharmaceutical and dairy segments where chemical resistance and moisture barriers outweigh clarity requirements. SFDA batch-traceability mandates and cleanroom certification overhead protect margin pools for Eastern Province converters with captive laboratory infrastructure.
- LDPE:Low-density polyethylene squeezes into squeeze-tube and flexible bottle niches where softness and puncture resistance matter more than rigidity.
- PVC:Polyvinyl chloride clings to specialty chemical and household product lines despite environmental headwinds, with SASO labeling conformity adding compliance burden.
PET retains volume leadership; HDPE holds the steepest expansion curve.
End User:
Cost tier stratification separates commodity beverage contracts from pharmaceutical-grade cleanroom production with tenfold margin differentials.
- Beverage:Carbonated soft drinks and mineral water bottlers drive preform demand toward high-cavitation systems, with direct procurement relationships displacing distributor intermediaries in annual tender platforms.
- Pharmaceuticals:SFDA-regulated therapeutic packaging demands ISO 14644 cleanroom environments, particulate control, and batch-linked QR traceability—qualification timelines freeze price competition.
- Cosmetics:Premium skin-care and fragrance brands in Riyadh's retail corridors specify custom neck finishes and decorative labeling, fragmenting order sizes.
- Household Products:Detergent and cleaning chemical bottlers absorb HDPE and PVC volumes with less stringent migration testing than food-contact applications.
Beverage commands absolute volume; pharmaceuticals capture concentrated margin premiums.
Capacity:
Volume concentration in single-serve formats reflects urban portability trends and on-the-go consumption patterns across Saudi urban centers.
- 500ml to 1L:The dominant consumption band for mineral water and carbonated drinks, with lightweighting investments reducing gram weight per bottle while maintaining top-load strength for palletized distribution.
- Less than 500ml:Travel-size cosmetics and pharmaceutical sample bottles, plus premium juice shots in Jeddah's free zone, where unit economics favor higher price points.
- 1L to 2L:Family-size dairy and juice applications, with aseptic filling compatibility requirements narrowing supplier pools.
- More than 2L:Bulk household cleaners and institutional beverage formats, with lower per-unit margins compensated by production line efficiency.
The 500ml to 1L band anchors procurement volumes; sub-500ml formats climb fastest on premium positioning.
Closure Type:
Application-specific functionality determines closure specification, with tamper-evidence and dispensing convenience driving differentiation.
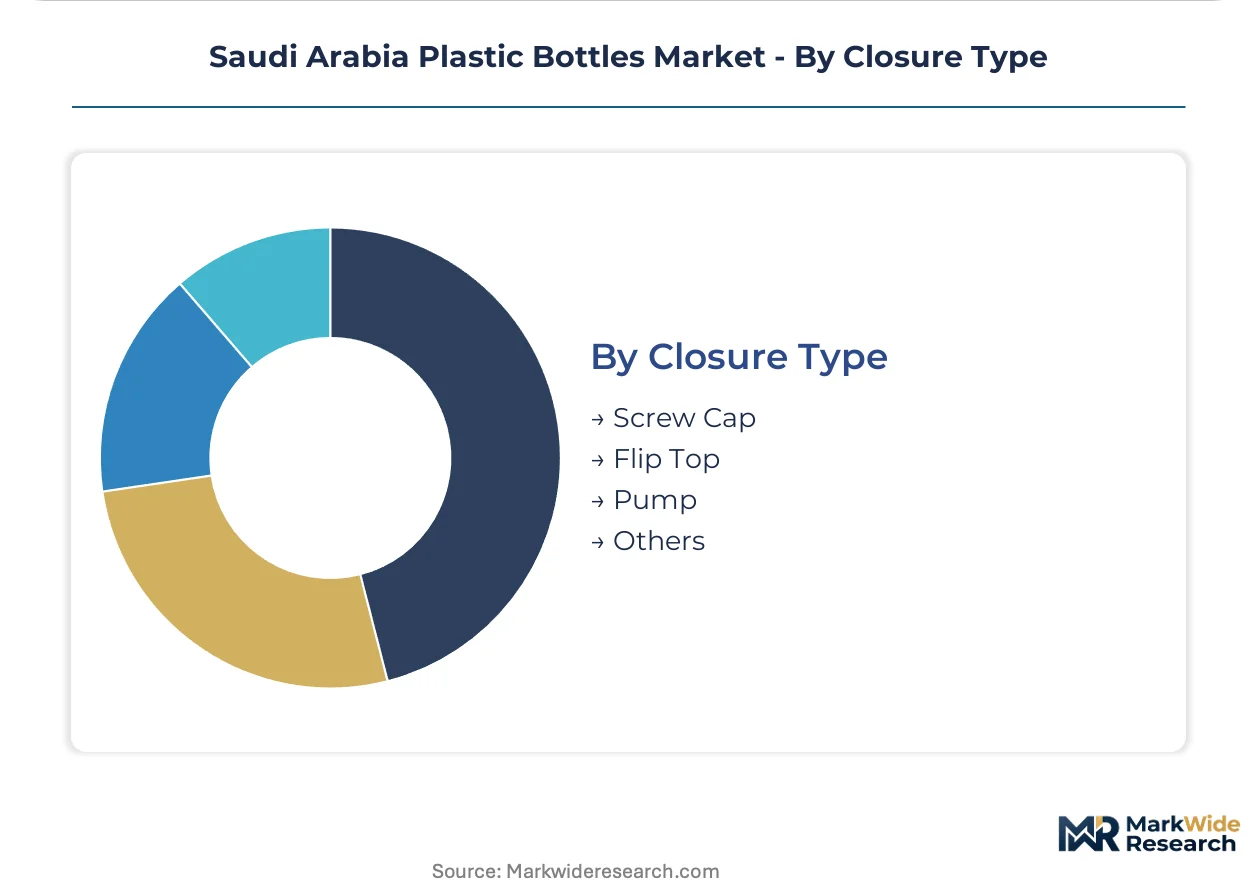
- Screw Cap:Universal standard across beverage and pharmaceutical segments, with neck-finish precision measured in millimeters ensuring capping line compatibility.
- Flip Top:One-handed operation for sports drinks and on-the-go consumption, popular in Riyadh's fitness-oriented demographic segments.
- Pump:Dispensing precision for cosmetics and viscous household products, with actuator quality determining repeat purchase rates.
- Others:Trigger sprayers, disc tops, and child-resistant closures for niche chemical and pharmaceutical applications.
Screw cap retains universal adoption; pump mechanisms expand fastest on cosmetics premiumization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity across Saudi Arabia's plastic bottles market varies sharply by geography. Riyadh-Jeddah corridor buyers absorb premium pricing for barrier-enhanced formats, while Eastern Province procurement prioritizes volume scale over material sophistication.
Riyadh
Central Region dairy processors and beverage multinationals anchor procurement volumes for HDPE barrier bottles and PET single-serve formats. SFDA's migration testing protocols concentrate compliance investments among Riyadh-headquartered converters with captive laboratory infrastructure. King Abdullah Economic City food manufacturing belt is pulling aseptic-compatible bottle demand from specialized suppliers.
Eastern Province
Industrial zone concentration around Dammam and Jubail creates geographic lock-in for pharmaceutical-grade HDPE production. Saudi Aramco's downstream petrochemical complexes supply virgin resin feedstock at cost-advantaged pricing to regional converters. National Plastic Factory's infrastructure dominance amplifies single-source vulnerability for therapeutic packaging procurement.
Western Region
Jeddah's free zone beverage bottlers specify multilayer co-injection PET with oxygen scavenger functionality for premium juice applications. Red Sea coastal logistics corridors enable imported preform sourcing from Asian suppliers. Makkah corridor pilgrimage-driven consumption concentrates seasonal demand spikes in 500ml mineral water formats.
NEOM Northwest
Giga-project construction is generating institutional-scale beverage procurement for worker accommodation camps. Circular economy mandates within NEOM's sustainability framework are pressuring rPET qualification timelines ahead of domestic collection infrastructure maturity. Regional planners are evaluating chemical recycling offtake agreements to bypass feedstock scarcity constraints.
Saudi Arabia Plastic Bottles Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in Saudi Arabia's plastic bottles market. Scale leaders command high-cavitation blow-molding infrastructure and direct procurement relationships with Riyadh-Jeddah beverage multinationals. Specialist operators differentiate through pharmaceutical-grade cleanroom certification and barrier-enhanced material architectures. Competitive dynamics center on vertical integration into preform production and migration testing capability deployment ahead of SFDA enforcement timelines.
Within the integrated multinational tier, Alpla Group occupies a position exemplifying European-technology licensing and captive preform-to-bottle infrastructure. National Plastic Factory anchors the domestic scale leader archetype through Eastern Province geographic concentration. 3P Gulf Plastic Packaging Factory represents the specialized cleanroom operator segment with pharmaceutical-grade output positioning.
| Leading Market Players |
|---|
| Alpla Group |
| National Plastic Factory |
| 3P Gulf Plastic Packaging Factory |
| Arabian Plastic Industrial Co. (APICO) |
| Saudi Plastic Packaging Systems |
| Zamil Plastic Industries Co. |
| Saudi Modern Packaging Factory Co. Ltd. (Printopack) |
| Takween Advanced Industries Co. |
| Al-Sharq Plastics Industries |
| Others |
Pricing and Supply Chain Analysis
High-cavitation blow-molding capacity utilization above 85 percent across the Riyadh-Jeddah corridor anchors price floors for commodity PET bottles while compressing margins for regional converters lacking scale. SFDA migration testing investments and rPET feedstock premiums are widening spreads between integrated operators and batch-converter tiers, forcing procurement decisions toward direct annual tenders with technical scorecards.
Pricing Analysis
After-sales service bundling around migration testing support and batch-traceability documentation drives lifetime value for pharmaceutical-grade contracts. Three-tier pricing structure across premium barrier-enhanced, standard virgin PET, and economy non-compliant tiers stratifies by SFDA certification status and cleanroom capability. Cost compression in the economy tier is intensifying as Eastern Province volume leaders absorb logistics premiums to defend share. Beverage multinationals exhibit lowest price sensitivity given direct procurement scale, while household chemical bottlers face acute margin pressure from aluminum can substitution.
Supply Chain Analysis
Strait of Hormuz transit underwrites resin feedstock security for Saudi converters drawing from Qatari and Kuwaiti petrochemical complexes. Virgin PET resin and pharmaceutical-grade HDPE pellets feed from Saudi Aramco downstream operations and imported Asian flake, with preform sourcing tethered to European technology licensors. Single-source vulnerability concentrates in Eastern Province pharmaceutical-grade HDPE production. Distribution runs through direct annual tender platforms for beverage bottlers and specialized distributor networks for pharmaceutical cleanroom supply.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
SFDA's tightened migration limits constitute a regulatory inflection accelerating capital deployment into barrier-enhanced PET lines and captive laboratory infrastructure, compressing timelines for competitive repositioning.
For Market Incumbents: Secure backward integration into preform production to defend margin pools against rPET feedstock volatility and imported flake pricing premiums. Expand high-cavitation capacity in the Riyadh corridor to capture direct procurement relationships displacing distributor intermediaries. SFDA audit cycle investments in batch segregation systems protect pharmaceutical-grade positioning against cleanroom-certified challengers. For New Entrants and Emerging Players: Anchor in Central Region dairy processor demand for aseptic-compatible HDPE barrier bottles, where ultrahigh-temperature milk and laban bottlers remain undersupplied relative to beverage vertical concentration. Target NEOM institutional procurement for worker accommodation camps ahead of circular economy mandate enforcement. Partner with chemical recycling offtake providers to bypass domestic collection infrastructure gaps. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors converters with European-technology licensing and integrated preform-to-bottle infrastructure over commodity blow-molding operators facing margin compression. Long-term viability across the projection horizon rests on rPET roadmap credibility and SFDA compliance investment depth. Monitor SFDA enforcement timeline announcements as the primary inflection signal for mandatory recycled content threshold acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Preform Production | Captive resin processing insulates margins from imported PET flake volatility and SFDA migration testing premiums. |
| High-Cavitation Blow-Molding Capacity Expansion | Riyadh-Jeddah corridor beverage multinationals prioritize suppliers with direct annual tender scale and technical scorecard compliance. |
| Pharmaceutical Cleanroom Certification Investment | ISO 14644 particulate control and batch-traceability infrastructure capture tenfold margin premiums over commodity tiers. |
| Chemical Recycling Offtake Partnership | NEOM circular economy mandates and domestic collection infrastructure gaps reward early movers with alternative rPET feedstock pathways. |
| Barrier-Enhanced Co-Injection Technology Licensing | Multilayer PET with oxygen scavenger functionality concentrates premium juice and functional drink contracts in Jeddah's free zone. |
Research Methodology
The analysis maps PET beverage packaging, pharmaceutical-grade HDPE, and barrier-enhanced co-injection sub-sectors, each validated through blow-molding operations directors, SFDA regulatory affairs consultants, and beverage procurement managers. Primary interviews with preform suppliers, dairy processor technical leads, and pharmaceutical cleanroom operators combined with secondary validation from SASO technical regulations, SFDA food-contact material guidelines, and customs trade data. Bottom-up capacity utilization estimates and top-down demand aggregation triangulated across the modeling period.
Consistency checks against external benchmarks validated volume and value outputs across material grade, end-use vertical, capacity band, and regional production cluster segmentation dimensions. CAGRs derived from installed capacity expansion announcements, beverage bottler tender pipelines, and pharmaceutical packaging procurement trends. Forecast inputs incorporated SFDA enforcement timeline probabilities and rPET feedstock availability scenarios without year-specific assumptions.
Decision-makers should treat outputs as directional under stable regulatory enforcement and resin feedstock pricing assumptions; material deviation would warrant model refresh. Practitioners should keep alternative scenarios live as SFDA recycled content mandates and circular economy policy signals evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plastic Packaging
Clear Plastic Boxes Market
Plastic Packaging
CPET Trays Market
Plastic Packaging
Sugarcane Based PET Bottles Market
Plastic Packaging
Recycled Plastic Envelope Market
Plastic Packaging
United States Plastic Bottles Market
Plastic Packaging
Philippines Plastics Market
Plastic Packaging
PET Clamshell Market
Plastic Packaging
Global Molded Plastic Packaging Market
Plastic Packaging
Plastic Keg Market
Plastic Packaging
Plastic Caulk Tube Market
Plastic Packaging
FFS Rigid Films Market
Plastic Packaging
Australia Plastic Packaging Market
Plastic Packaging
Europe Polyethylene Terephthalate (PET) Market
Plastic Packaging
Advanced-Recycled Polyethylene for E-Commerce Packaging Market
Plastic Packaging
North America PET Bottle Market
Plastic Packaging
Poland Plastic Bottles Market