
 HDPE Bottles Market | 2026-2036
HDPE Bottles Market Size, Share, and Industry Trends Forecast 2026-2036
HDPE Bottles Market Outlook
A shift from single-source resin procurement to multi-source contracting is realigning supply strategies across HDPE bottle converters. Berry Global Inc. leverages backward integration into resin compounding to buffer against ethylene price swings. ALPLA Group anchors its competitive stance through captive preform manufacturing in Central European plants. Graham Packaging Company differentiates via blow-molding automation that cuts cycle times for high-volume personal care contracts.
HDPE bottles are hollow containers blow-molded from high-density polyethylene resin with typical density ranging from 0.941 to 0.965 g/cm³, valued for chemical resistance, moisture barrier properties, and compatibility with fluorination treatments for solvent containment. Standard bottles dominate volume across food packaging and cleaning products, while trigger sprayers command margin premiums in industrial and household chemical segments. Screw caps remain the default closure across mass-market applications, though child-resistant caps are gaining share in pharmaceutical and cannabis-adjacent packaging as safety regulations stiffen.
FDA maintains food-contact notification requirements for HDPE resins, while EPA rules on recycled content thresholds shape post-consumer feedstock availability for bottle production. EU REACH restricts certain additive chemistries in polyethylene formulations, pushing converters toward certified virgin-recycled blends. Stakeholders must monitor how EFSA evolves its stance on chemical migration from recycled HDPE into food-contact applications.
Market Dynamics
Multi-source resin contracting is displacing single-source procurement as ethylene price volatility forces converters to hedge feedstock exposure across regional suppliers.
Growth Catalysts
- EU REACH compliance mandates:Material purity standards for food-contact applications are tightening additive chemistries, pushing certified virgin-recycled blend adoption among German and French converters.
- Personal care packaging expansion:Shampoo and lotion brands are specifying fluorination-treated HDPE for solvent containment, widening bottle applications beyond traditional food and chemical segments.
- Brazil manufacturing cluster deepening:São Paulo-based blow-molding operations are scaling trigger sprayer production for industrial chemical contracts, anchoring South American supply.
Market Restraints
- Ethylene feedstock volatility:Crude-linked naphtha cracking economics expose converters to margin compression when oil benchmarks swing abruptly.
- Post-consumer feedstock scarcity:EPA recycled content thresholds limit rHDPE availability for food-contact bottles, constraining circular production targets.
- Polypropylene substitution in pharmaceutical closures:PP resins with superior clarity are displacing HDPE in child-resistant cap applications where aesthetic differentiation commands premium positioning.
Strategic Opportunities
- Indian pharmaceutical packaging underpenetration:CDSCO serialization mandates for track-and-trace compliance are creating demand for HDPE bottles with integrated tamper-evident features in Mumbai and Hyderabad manufacturing zones.
- US cannabis-adjacent packaging regulatory tailwind:State-level child-resistant packaging laws are mandating CPSC-certified closures, opening specialized HDPE bottle segments outside traditional FDA oversight.
- Digital printing-blow molding convergence:Direct-to-container inkjet systems are enabling SKU proliferation without label inventory, compressing minimum order quantities for niche personal care brands.
Industry Challenges
- Fluorination technician scarcity:Barrier treatment operations require specialized handling of fluorine gas systems, limiting converter expansion into solvent containment grades.
- EFSA migration study timelines:Pending scientific opinions on chemical transfer from recycled HDPE into food-contact applications are freezing rHDPE adoption decisions among risk-averse brand owners.
- Legacy blow-molding asset retrofit costs:Converters face capital intensity upgrading hydraulic machines to all-electric systems for energy efficiency and cycle time compression.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | HDPE Bottles Market |
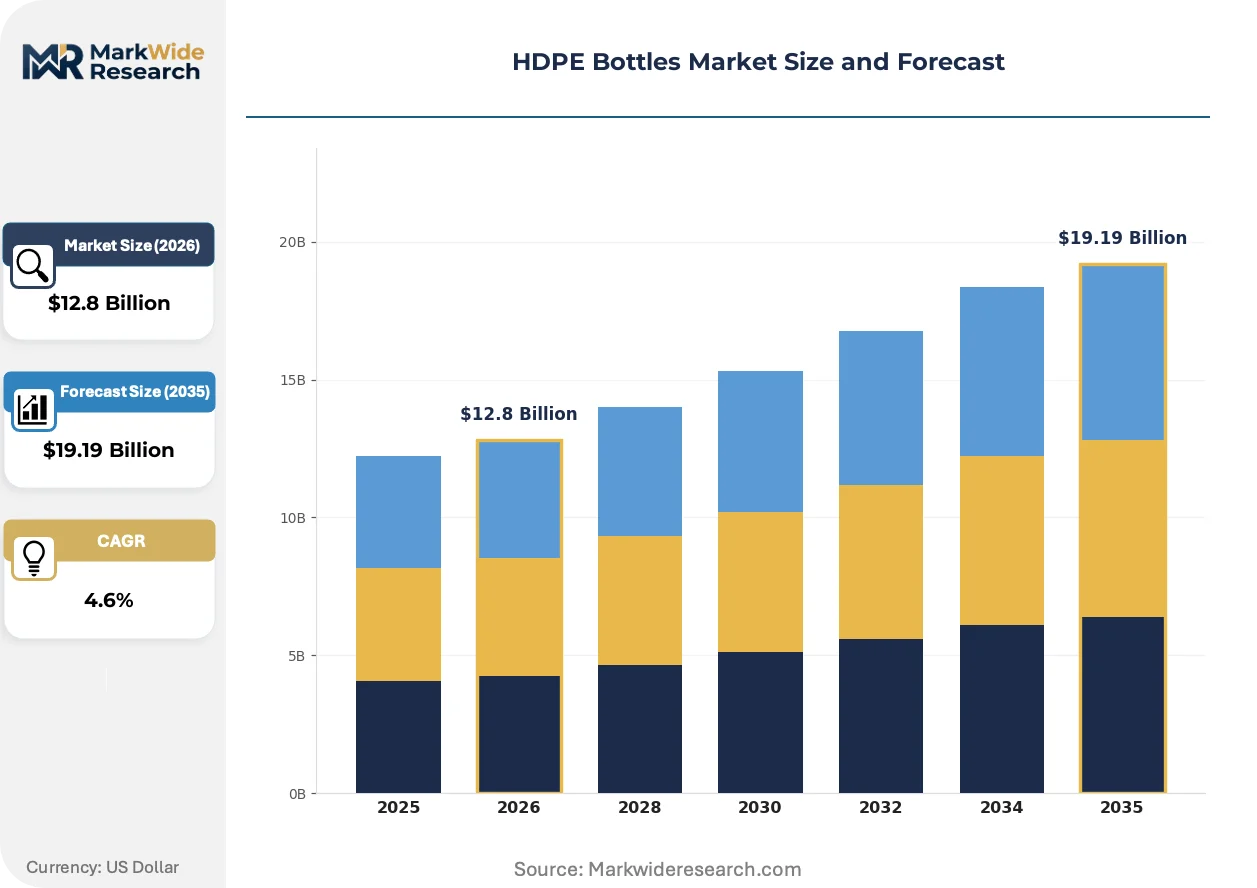
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $19.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Bottles, Trigger Sprayers, Pails, Jars Application: Personal Care, Cleaning Products, Food Packaging, Pharmaceutical Closure Type: Child-Resistant Caps, Screw Caps, Spout Caps, Press-on Lids Size: 500ml, 1L, 2L, 5L |
| Companies Covered | Amcor plc, Berry Global Inc., Graham Packaging Company, ALPLA Group, Plastipak Holdings, Inc, Silgan Holdings Inc., Canyon Plastics Inc., Indorama Ventures Public Company Limited, Dahl-Tech, Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
HDPE Bottles Market Strategic Shifts
Automation and material science advances are compressing production economics while regulatory science evolves around circular feedstock safety. Three developments are restructuring competitive positioning.
Fluorination surface treatment is expanding into high-performance solvent containment applications. Industrial chemical distributors are specifying fluorinated HDPE for agrochemical and automotive fluid packaging previously served by metal or fluoropolymer containers. This technology is expanding into personal care as brands seek moisture barrier properties without aluminum laminate costs.
EFSA is accelerating chemical migration assessment protocols for recycled polyethylene. The regulator's evolving stance on post-consumer feedstock safety is forcing European converters to segregate rHDPE streams by prior use category. Food-contact bottle producers are responding with dual-track virgin and certified recycled production lines pending formal opinion publication.
Brand owners are consolidating blow-molded bottle suppliers to reduce qualification overhead. Personal care multinationals are shrinking approved vendor lists from regional fragmentation to continental hub arrangements. This concentration is most visible in Germany, where centralized procurement teams now mandate ISO 15378 pharmaceutical-grade certification even for cosmetic applications.
HDPE Bottles Market Segmentation
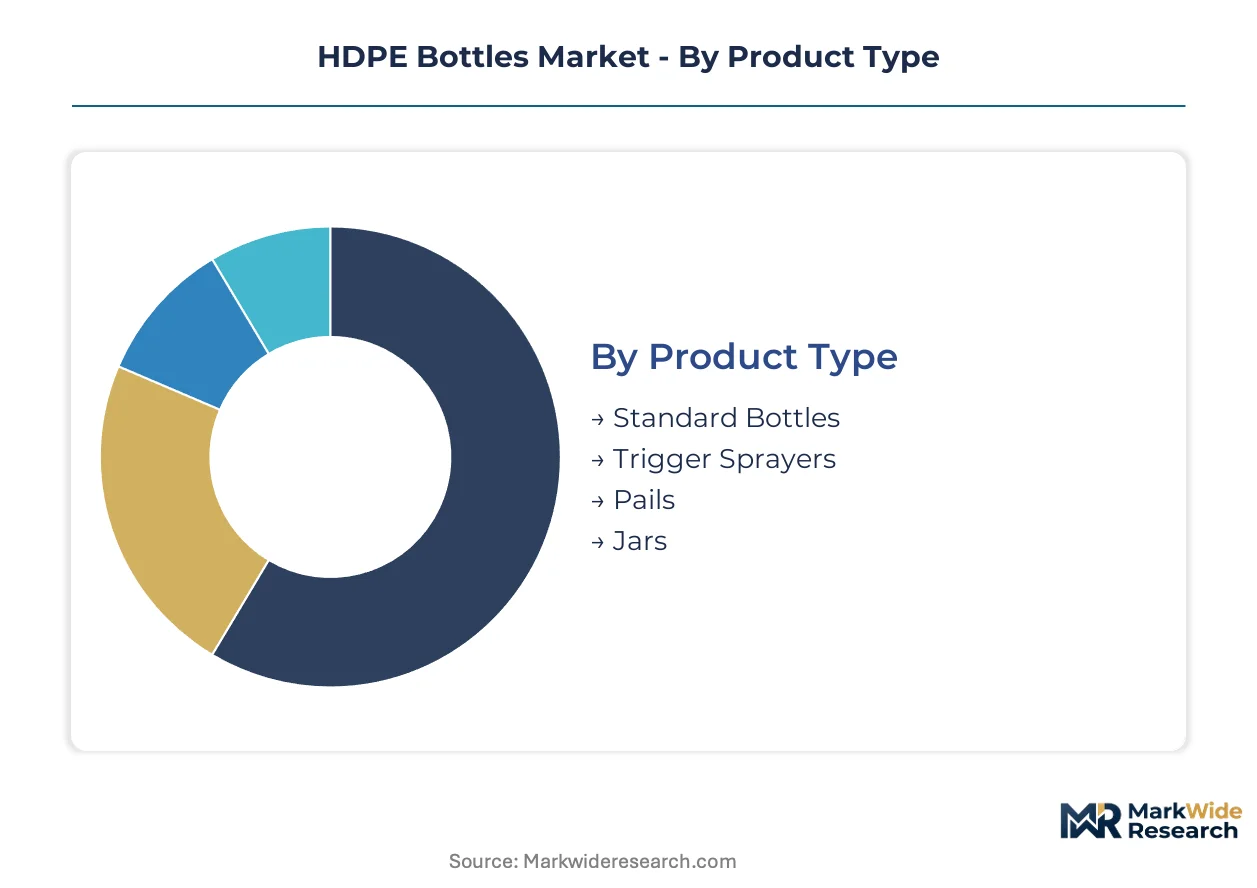
HDPE bottle converters configure production assets around four distinct segmentation axes. Product type determines blow-molding equipment specifications, while application dictates regulatory compliance pathways and barrier treatment requirements.
Product Type:
Standalone packaging formats dominate procurement volumes, whereas embedded dispensing systems require co-molded or assembled components that alter converter economics.
- Standard Bottles:Hollow containers extrusion blow-molded in 0.941-0.965 g/cm³ density resin, serving as the default format for food packaging and cleaning products across German and Indian manufacturing clusters. Demand concentrates in 1L and 2L capacities for edible oil and household chemical distributors seeking cost-optimized logistics.
- Trigger Sprayers:Integrated dispensing systems combining HDPE bottle bodies with mechanical pump mechanisms, commanding margin premiums in industrial and household chemical segments. São Paulo-based operations are scaling production for agrochemical contracts requiring fluorination-treated solvent containment.
- Pails:Rigid containers typically 5L capacity serving institutional cleaning and food service bulk packaging, with screw-on lids replacing traditional metal handles for reduced material cost.
- Jars:Wide-mouth configurations with press-on or screw closures, finding placement in personal care creams and pharmaceutical ointments where access geometry outweighs pour control.
Volume placements concentrate in Standard Bottles; the faster expansion belongs to Trigger Sprayers.
Application:
End-use sectors separate by regulatory intensity, with pharmaceutical and food packaging demanding certified virgin-recycled blends while personal care tolerates broader feedstock flexibility.
- Personal Care:Shampoo and lotion brands specify fluorination-treated HDPE for moisture barrier properties, with Mumbai and Hyderabad manufacturing zones deepening production for domestic and export contracts.
- Cleaning Products:Household and industrial chemical distributors drive standard bottle and trigger sprayer demand, with EPA recycled content thresholds constraining post-consumer feedstock availability for US-facing production.
- Food Packaging:Edible oil and condiment bottlers require FDA food-contact notification compliance, with EU REACH additive restrictions pushing German converters toward certified virgin-recycled segregation protocols.
- Pharmaceutical:CDSCO serialization mandates in India and state-level cannabis packaging laws in the US create demand for HDPE bottles with integrated tamper-evident and child-resistant features.
Food Packaging captures the largest shipment volumes; Pharmaceutical applications are climbing the fastest on regulatory tailwinds.
Closure Type:
Closure selection determines capping equipment investment and safety certification requirements, with child-resistant mechanisms requiring specialized torque testing infrastructure.
- Child-Resistant Caps:Push-and-turn or squeeze-and-turn mechanisms mandated by CPSC certification for pharmaceutical and cannabis-adjacent packaging, with polypropylene substitution threatening HDPE closure share where clarity commands premium positioning.
- Screw Caps:Threaded closures remaining the default across mass-market food and cleaning applications, with standard torque specifications enabling high-speed capping line compatibility.
- Spout Caps:Directional pour controls specified for industrial chemical and automotive fluid packaging, reducing spillage risk in solvent containment applications.
- Press-on Lids:Snap-fit closures for jar configurations in personal care and food service, sacrificing reseal security for manufacturing simplicity and cost minimization.
Screw Caps dominate unit placements; Child-Resistant Caps are gaining share fastest on safety regulation expansion.
Size:
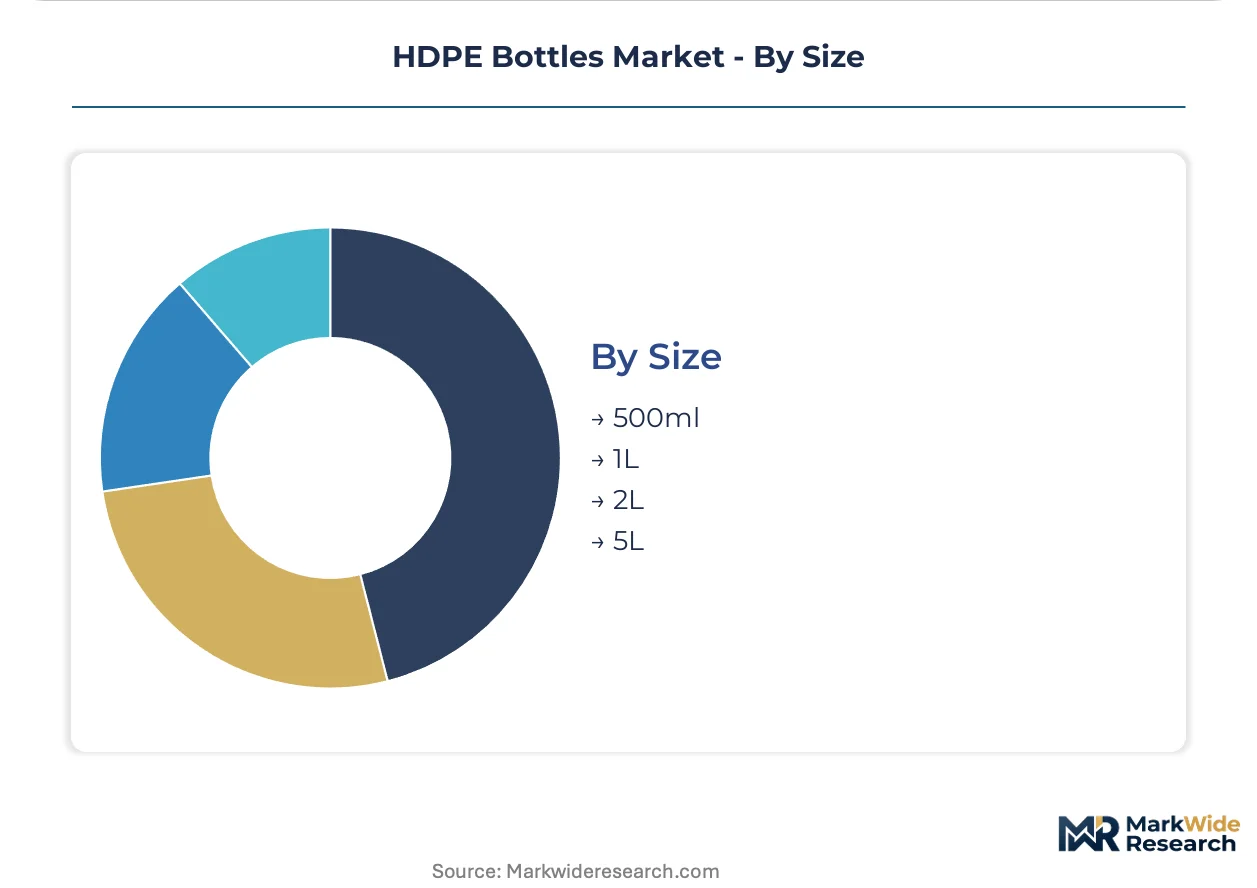
Capacity selection maps to distribution channel economics, with retail-facing formats clustering below 2L and institutional bulk packaging anchoring 5L demand.
- 500ml:Travel-size and sample formats for personal care and pharmaceutical sampling programs, with digital printing enabling SKU proliferation for niche brand launches.
- 1L:Standard retail capacity for edible oils and household cleaners, optimizing shelf space efficiency and consumer handling ergonomics across German and Brazilian supermarket channels.
- 2L:Family-size and value-tier positioning for cleaning products and food commodities, with blow-molding automation investments targeting cycle time compression at this capacity sweet spot.
- 5L:Institutional and food service bulk packaging, with pail and large bottle configurations requiring reinforced wall thickness for stacking strength in logistics.
1L and 2L sizes anchor volume placements; 500ml formats are expanding most quickly on personal care sampling and travel retail recovery.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ethylene feedstock availability from Gulf Coast petrochemical complexes anchors United States converter economics, while naphtha-derived resin economics shape European and Asian production costs differently.
United States
Shale-advantaged ethane cracking supplies low-cost HDPE resin to domestic blow-molders serving personal care and cleaning product brands. EPA recycled content thresholds constrain post-consumer feedstock flows into food-contact applications. Houston-Galveston corridor plants are expanding fluorination treatment capacity for agrochemical packaging contracts.
Germany
REACH additive restrictions are pushing converters toward certified virgin-recycled blend segregation protocols for food-contact bottles. EU EFSA migration study timelines are freezing rHDPE adoption decisions among risk-averse brand owners. North Rhine-Westphalia manufacturing clusters are consolidating supplier qualification lists to reduce procurement overhead.
India
CDSCO serialization mandates for pharmaceutical track-and-trace compliance are creating demand for HDPE bottles with integrated tamper-evident features. FSSAI food-contact regulations are tightening material purity standards for edible oil packaging. Mumbai and Hyderabad manufacturing zones are deepening production for domestic and export personal care contracts.
Brazil
São Paulo-based blow-molding operations are scaling trigger sprayer production for industrial chemical distribution contracts. ANVISA pharmaceutical packaging regulations are aligning with international standards for child-resistant closure certification. Southeast Asian export demand is pulling Brazilian converter capacity toward fluorination-treated solvent containment grades.
China
Dual carbon policy targets are pressuring converters to source certified recycled feedstock despite inconsistent post-consumer collection infrastructure. SAMR food-contact notification requirements mirror FDA protocols for resin purity certification. Yangtze River Delta manufacturing hubs are retrofitting hydraulic blow-molding assets to all-electric systems for energy efficiency compliance.
HDPE Bottles Market Competitive Environment
Backward integration into resin compounding dominates the current landscape as converters seek insulation from ethylene price volatility. The vendor base spans multinational packaging conglomerates with captive resin supply, regional specialists focused on barrier treatment technologies, and emerging Asian fabricators scaling automated blow-molding lines. Three archetypes define competitive positioning: vertically integrated resin-to-bottle producers, fluorination treatment specialists, and automation-heavy scale operators. M&A activity concentrates on regional bottle converters in pharmaceutical corridors, while capacity expansion targets Indian and Brazilian manufacturing clusters.
Within the integrated-resin tier, Berry Global Inc. and Indorama Ventures Public Company Limited exemplify upstream control strategies that buffer margin compression during feedstock price swings. Among North American fabricators, Graham Packaging Company occupies a position emphasizing blow-molding automation for cycle time compression. European specialists including ALPLA Group and Amcor plc anchor competitive stance through captive preform manufacturing and continental hub arrangements that reduce brand owner qualification overhead.
| Leading Market Players |
|---|
| Amcor plc |
| Berry Global Inc. |
| Graham Packaging Company |
| ALPLA Group |
| Plastipak Holdings, Inc |
| Silgan Holdings Inc. |
| Canyon Plastics Inc. |
| Indorama Ventures Public Company Limited |
| Dahl-Tech, Inc |
| Others |
Value Chain & Pricing Dynamics
Personal care multinationals with consolidated continental procurement teams command contract structures that stratify HDPE bottle pricing across certification tiers rather than volume brackets alone. Their vendor consolidation from regional fragmentation to hub arrangements concentrates buyer leverage, compressing margin premiums for converters lacking ISO 15378 pharmaceutical-grade certification or fluorination treatment capabilities.
Pricing Analysis
After-sales technical support and barrier treatment warranties are unbundled from base resin pricing, with fluorination-treated bottles commanding separate service fees for solvent containment certification. Pricing stratifies across pharmaceutical-grade, food-contact certified, and industrial-standard tiers, with FDA food-contact notification compliance and EU REACH additive restrictions as primary differentiation drivers. Cost compression in standard bottle segments is intensifying as Brazilian and Indian converters scale automated blow-molding capacity for export contracts. Household chemical distributors exhibit highest price sensitivity due to commoditized specifications, while pharmaceutical brands tolerate premium positioning for child-resistant closure integration and serialization-ready formats.
Supply Chain Analysis
ISO 15378 pharmaceutical-grade certification and FDA food-contact notification status function as non-negotiable gating criteria for supplier qualification lists, with dual-track virgin and certified recycled production lines becoming mandatory for European food-contact bottle producers. Resin supply concentrates in United States Gulf Coast petrochemical complexes, German North Rhine-Westphalia chemical corridors, and Indian Mumbai manufacturing zones. Converter operations draw from ethane-derived HDPE resin, fluorination treatment chemicals, and mechanical pump assemblies for trigger sprayer configurations. Single-source vulnerability in fluorination technician availability limits converter expansion into solvent containment grades. Distribution runs through brand owner centralized procurement hubs rather than regional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
HDPE bottle production is transitioning from hydraulic blow-molding assets to all-electric systems for energy efficiency compliance, with digital printing-blow molding convergence replacing legacy label-based SKU management. This technology displacement is compressing minimum order quantities and enabling niche personal care brand proliferation.
For Market Incumbents: To counter margin compression from Brazilian and Indian automation-heavy scale operators, Berry Global Inc. and ALPLA Group should deepen backward integration into resin compounding to buffer ethylene price volatility. Captive preform manufacturing in Central European plants and fluorination treatment capacity expansion in Houston-Galveston corridor facilities represent critical defensive levers against regional converter encroachment.
For New Entrants and Emerging Players: The price-point gap between pharmaceutical-grade certified bottles and economy-tier industrial standard formats offers entry positioning for mid-cap specialists targeting Indian pharmaceutical packaging underpenetration. CDSCO serialization mandates in Mumbai and Hyderabad manufacturing zones create demand for HDPE bottles with integrated tamper-evident features. A go-to-market angle anchored on digital printing-blow molding convergence enables SKU proliferation without label inventory investment.
For Investors and Strategic Acquirers: Distressed-cycle entries favor fluorination treatment specialists with existing technician capabilities in São Paulo-based operations or German North Rhine-Westphalia clusters, where EFSA migration study timelines have frozen rHDPE adoption decisions and compressed valuations. Long-term viability over a 5-10 year window rests on converters with dual-track virgin and certified recycled production line infrastructure. The signal to watch is EFSA publication of formal opinions on chemical transfer from recycled HDPE into food-contact applications.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Berry Global Inc. buffers margin compression through captive ethylene supply control. |
| Fluorination Treatment Capacity Expansion | Houston-Galveston corridor plants capture agrochemical packaging contract migration from metal containers. |
| Digital Printing-Blow Molding Convergence | Direct-to-container inkjet systems compress minimum order quantities for niche personal care launches. |
| Pharmaceutical-Grade Certification Investment | ISO 15378 compliance enables access to consolidated continental procurement hub arrangements. |
| All-Electric Blow-Molding Retrofit | Yangtze River Delta hubs meet dual carbon policy targets through energy efficiency compliance. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, with primary interviews conducted among blow-molding plant managers, personal care brand procurement leads, pharmaceutical packaging regulatory affairs directors, and fluorination treatment technicians. Secondary validation drew from FDA food-contact notification databases, EU EFSA scientific opinion filings, EPA recycled content threshold documentation, and CDSCO serialization mandate circulars. Bottom-up capacity assessments across German, Indian, and Brazilian manufacturing clusters were triangulated against top-down demand estimates from end-use sector consumption patterns.
Reconciliation of resin production data, converter capacity utilization surveys, and brand owner procurement disclosures informed the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, application, closure mechanism, capacity tier, and regional regulatory cluster. CAGRs were derived from trend extrapolation of ethylene feedstock economics, automation adoption curves, and regulatory compliance cost trajectories. Forecast inputs incorporated EFSA migration study timeline scenarios and CDSCO serialization mandate implementation pace.
Inputs from regulatory agencies and trade associations were available through the study window; gaps in real-time converter capacity utilization data introduce uncertainty bands around near-term supply estimates. Forecasts reflect assumptions regarding EFSA opinion publication timing, ethylene price volatility persistence, and fluorination technician training pipeline expansion. A model refresh is warranted upon material change in EFSA regulatory stance on recycled HDPE food-contact safety.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Containers
Cubitainer Market
Containers
Stainless Steel Cask Market
Containers
Feeder Containers Market
Containers
USA and Canada Packer Bottle Market
Containers
Container Mouth Inner Seal Market
Containers
Canisters Market
Containers
Car Lube Container Market
Containers
Pinch Grip Jars Market
Containers
Global Flexitanks Market
Containers
Safety Bottle Tote Carriers Packaging Market
Containers
Packaging Bins Market
Containers
HDPE Crates Market
Containers
Takeaway Containers Market
Containers
Thermoformed Shallow Trays Market
Containers
Soup Containers Market
Containers
Lever Lid Tinplate Containers Market