
 Plastic Keg Market | 2026-2036
Plastic Keg Market Size, Share, and Industry Trends Forecast 2026-2036
Plastic Keg Market Insights
Aftermarket service revenue is fragmenting as keg fleet operators unbundle cleaning, tracking, and logistics from core container sales. Petainer UK Holdings Ltd leverages its blow-molding expertise to anchor refillable PET keg programs across British retail channels. Lightweight Containers BV sustains competitive positioning through geographic dominance in Benelux brewing cooperatives. MicroStar / Kegstar differentiates via technology leadership in RFID-enabled keg tracking systems that reduce loss rates for North American craft brewers.
A plastic keg is a cylindrical beverage container manufactured through injection or blow-molding processes using polyethylene, polypropylene, or multi-layer PET with oxygen barrier coatings, designed to hold carbonated or still liquids under pressure for draft dispensing. Quarter Barrel configurations lead current volume owing to their compatibility with existing tap systems and reduced weight for manual handling, while Custom Size variants represent the fastest-growing category as microbreweries seek branded, event-specific formats. Polyethylene dominates material selection for cost-sensitive applications, though Polypropylene is gaining share in hot-fill and extended-shelf-life segments where thermal resistance commands premium positioning.
Food-contact material regulations from the FDA and EU's REACH framework govern migration limits and additive compositions for plastic kegs entering beverage service, while Germany's KBA and France's ANSM enforce transport safety standards for pressurized container logistics. The EU Green Deal's packaging waste targets are reshaping demand toward mono-material, fully recyclable designs that simplify end-of-life processing. Stakeholders must monitor evolving extended producer responsibility schemes and decide whether to invest in deposit-return infrastructure or partner with existing pooling networks.
Market Dynamics
Polymer barrier engineering is compressing the cost-performance gap between refillable PET kegs and traditional stainless steel, forcing container economics to recenter around logistics efficiency rather than asset longevity.
Growth Catalysts
- EU Single-Use Plastics Directive:The framework mandates reduction targets for disposable beverage packaging, pushing brewers toward reusable polymer formats that qualify for regulatory relief.
- RFID-enabled tracking systems:Fleet operators are embedding wireless identification to cut keg loss rates and optimize rotation cycles across distributed pub networks.
- Benelux brewing cooperatives:Dense cluster procurement is normalizing lightweight container acceptance, creating reference demand that radiates into neighboring supply chains.
Market Restraints
- Stainless steel residual value:Established metal keg pools retain decades of depreciation runway, delaying replacement cycles for capital-constrained operators.
- Barrier coating supply concentration:Oxygen-scavenging additive production centers on specialized chemical processors in Germany and the Netherlands, creating input vulnerability.
- Hot-fill thermal limits:Standard polyethylene formulations deform above pasteurization temperatures, excluding polymer kegs from certain sterilization-dependent beverage categories.
Strategic Opportunities
- United Kingdom pub distribution networks:Cask ale and craft lager channels show container standardization gaps that favor branded custom-format penetration.
- EU Green Deal packaging targets:Extended producer responsibility schemes reward mono-material designs with simplified end-of-life processing and reduced compliance fees.
- Event-specific format convergence:Microbreweries are commissioning limited-run keg geometries tied to seasonal releases, merging packaging with marketing spend.
Industry Challenges
- Blow-molding technician scarcity:Multi-layer PET fabrication requires specialized machine operation skills that outpace vocational training pipeline output in manufacturing regions.
- REACH migration testing timelines:New barrier additive approvals face extended ECHA evaluation periods that stall product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plastic Keg Market |
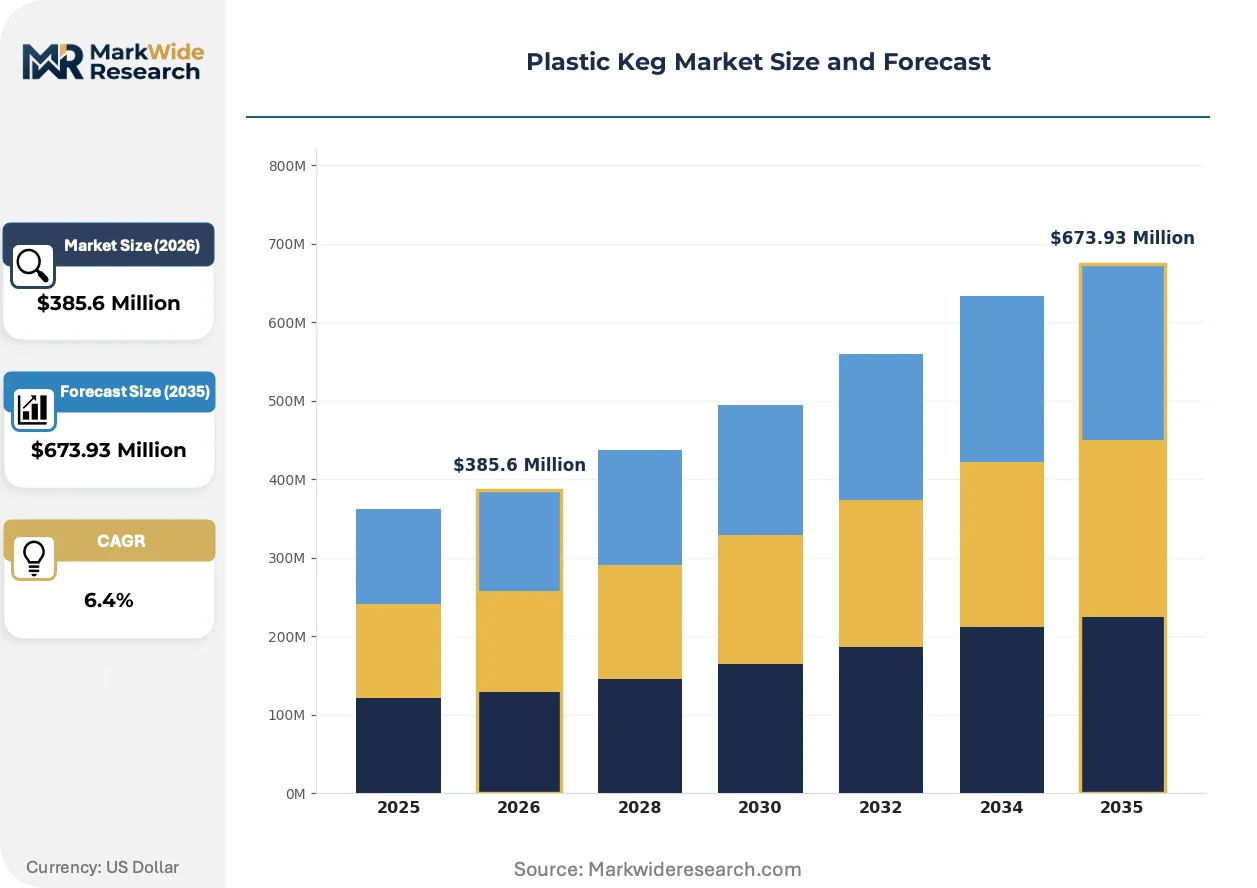
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $673.93 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Quarter Barrel, Half Barrel, Full Barrel, Custom Size End User: Beverage Industry, Food Service, Event Management, Packaging Material: Polyethylene, Polypropylene, PVC, Others Distribution Channel: Online Retail, Direct Sales, Distributors, Wholesale |
| Companies Covered | Lightweight Containers BV, Petainer UK Holdings Ltd, Dolium BV, MicroStar / Kegstar, i-Keg, KegPlast, Konvoy, PolyKeg S.r.l., Ningbo BestFriends Beverage Containers Co. Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plastic Keg Market Trends and Innovations
Container intelligence and material science are converging to redefine keg economics, shifting competitive advantage from manufacturing scale toward fleet management sophistication and circular design compliance.
Multi-layer PET with oxygen barrier coatings is migrating from niche craft applications toward mainstream lager distribution. Mid-sized German breweries are adopting these formats for export shipments to reduce return-logistics burden. The technology is migrating from premium positioning into volume segments as coating costs fall and blow-molding throughput rises.
REACH framework migration limits are tightening acceptable additive portfolios for food-contact polymers. ECHA evaluations now demand extensive extraction testing for new barrier chemistries, extending qualification timelines. German KBA transport safety certifications for pressurized polymer containers face renewed scrutiny, compressing design iteration cycles for innovators.
Brewery procurement departments are unbundling keg cleaning, tracking, and logistics from core container acquisition. Third-party pooling operators are capturing service revenue that equipment vendors previously monopolized. This restructuring is most visible in North American craft brewing, where capital-light fleet access models displace ownership-heavy asset strategies.
Plastic Keg Market Segmentation
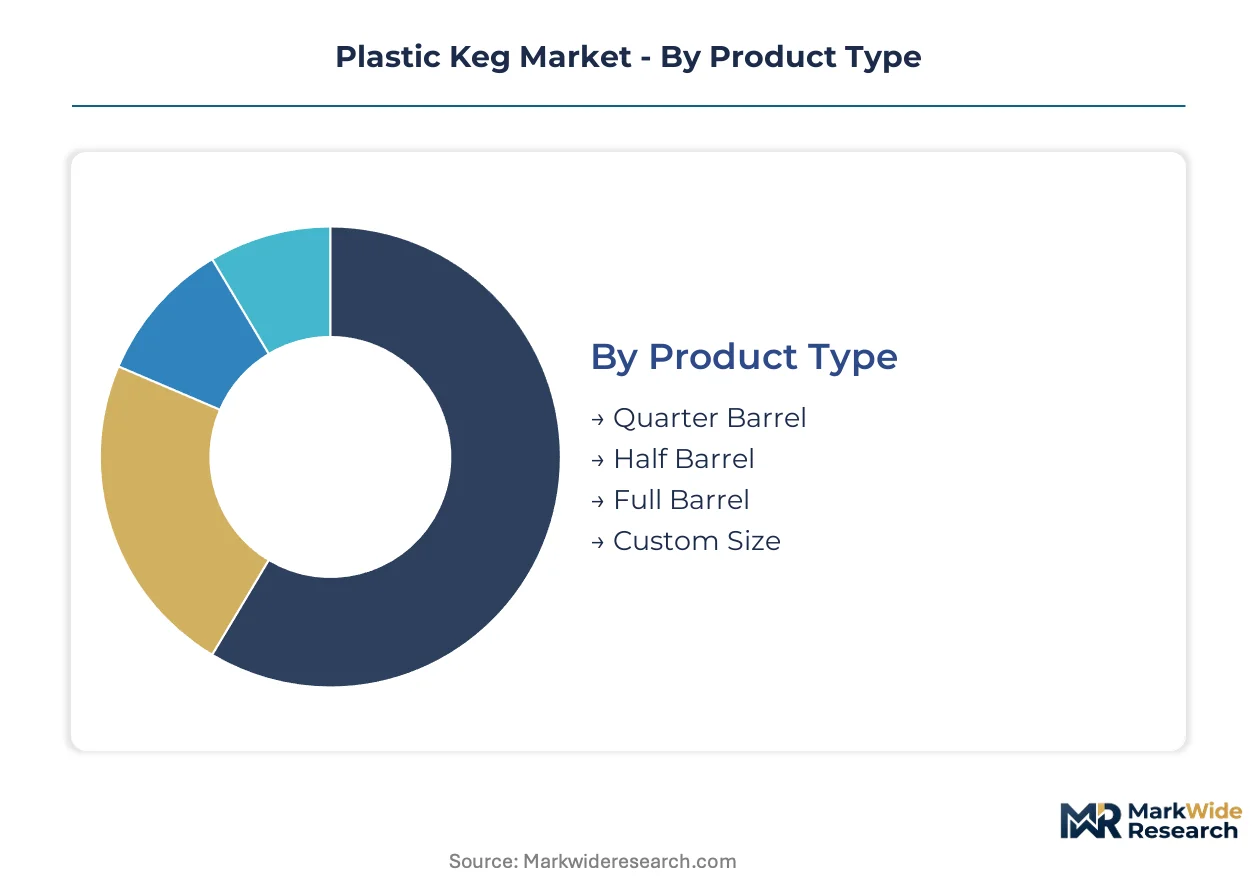
Plastic keg segmentation reveals how container economics fragment across handling requirements, thermal constraints, and procurement channel preferences. Each dimension carries distinct margin profiles and regulatory exposure that reshape vendor positioning.
Product Type:
Volume tier determines handling economics and tap-system compatibility across draft beverage service.
- Quarter Barrel:7.75-gallon capacity suits manual handling in high-turnover pub environments. Germany's craft brewing corridor favors this format for reduced warehouse labor costs and compatibility with existing cellar infrastructure.
- Half Barrel:Standard 15.5-gallon specification dominates North American draft distribution. The format balances transport density against single-person maneuverability in commercial kitchens.
- Full Barrel:31-gallon volume serves high-throughput stadium and festival deployment with forklift-dependent logistics.
- Custom Size:Event-specific geometries merge branded marketing with container function. Microbreweries commission limited-run formats for seasonal releases.
Quarter Barrel holds installed capacity. Custom Size is rotating up the share rankings.
End User:
Application context dictates barrier specifications, cleaning protocols, and rotation velocity requirements.
- Beverage Industry:Breweries and soft-drink manufacturers constitute core demand, with carbonation pressure requirements driving multi-layer PET adoption. United Kingdom pub distribution networks show particular concentration for cask ale and craft lager channels.
- Food Service:Restaurants and catering operations prioritize lightweight handling and rapid turnover. The segment accepts higher per-use costs in exchange for reduced injury liability and faster cellar operations.
- Event Management:Temporary dispensing installations favor single-use or short-lifecycle containers to eliminate return logistics.
- Packaging:Contract packagers and co-manufacturers source containers for brand-owner filling operations with customized labeling specifications.
Beverage Industry commands current volume concentration. Food Service is climbing the fastest as labor costs reshape handling preferences.
Material:
Polymer selection trades cost position against thermal resistance and oxygen barrier performance.
- Polyethylene:Low-density formulations dominate cost-sensitive applications with cold-fill requirements. The material's deformation threshold below pasteurization temperatures excludes hot-fill beverage categories.
- Polypropylene:Higher thermal resistance enables hot-fill and extended-shelf-life segments where steam sterilization protocols apply. Premium positioning commands margin recovery for the material cost differential.
- PVC:Specialized applications leverage clarity and printability for branded visual presentation.
- Others:Niche biopolymers and recycled-content formulations serve sustainability-mandated procurement specifications.
Polyethylene maintains production scale dominance. Polypropylene is gaining share fastest as thermal performance premiums expand addressable applications.
Distribution Channel:
Channel structure determines service bundling, fleet management responsibility, and working capital allocation.
- Direct Sales:Large brewery groups negotiate volume contracts with embedded cleaning and tracking services. The channel captures full lifecycle revenue that third-party pooling operators now contest.
- Distributors:Regional beverage distributors bundle container provision with route logistics and tap maintenance. Benelux brewing cooperatives concentrate procurement through this channel.
- Wholesale:General industrial packaging wholesalers serve fragmented small-batch brewers with spot purchasing flexibility.
- Online Retail:Direct-to-brewer e-commerce enables rapid specification comparison for custom-format inquiries and replacement orders.
Direct Sales anchors existing revenue concentration. Distributors are rotating up the share rankings as fleet outsourcing accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany's craft brewing corridor show the least price sensitivity to per-unit container costs, prioritizing logistics efficiency and regulatory compliance. British pub networks operate at the opposite elasticity extreme, where lightweight handling savings must offset material premiums within single-rotation economics. The United States craft segment sits between these poles, balancing capital-light fleet access against ownership depreciation preferences.
Germany
Mid-sized Bavarian breweries are converting export shipments to multi-layer PET formats to eliminate return-logistics burdens from distant markets. The KBA maintains stringent transport safety certifications for pressurized polymer containers, compressing design iteration cycles for domestic blow-molders. The Baden-Württemberg brewing corridor concentrates procurement decisions for southern German cooperatives.
United Kingdom
Cask ale and craft lager distribution networks favor Quarter Barrel configurations for reduced warehouse labor costs and cellar infrastructure compatibility. The Environment Agency enforces packaging waste targets that reward mono-material, fully recyclable keg designs with simplified compliance pathways. Greater Manchester's pub distribution hubs are normalizing RFID-enabled fleet tracking to cut rotation cycle losses.
United States
North American craft brewers are displacing ownership-heavy asset strategies with capital-light fleet access models from third-party pooling operators. FDA food-contact material regulations govern migration limits for polyethylene and polypropylene formulations entering interstate beverage commerce. The Pacific Northwest brewing cluster—Portland to Seattle—drives custom-format inquiries for seasonal release branding.
Netherlands
Benelux brewing cooperatives concentrate procurement through regional distributors bundling container provision with route logistics. REACH framework migration limits from ECHA tighten acceptable additive portfolios for barrier coatings, extending qualification timelines for new chemistries. The Eindhoven blow-molding corridor anchors multi-layer PET fabrication capacity for northwestern European export.
Belgium
Dense cooperative procurement networks normalize lightweight container acceptance, creating reference demand that radiates into French and German supply chains. The EU Single-Use Plastics Directive mandates reduction targets that push brewers toward reusable polymer formats qualifying for regulatory relief. Flanders' brewing associations coordinate fleet standardization across shared pooling infrastructure.
Plastic Keg Market Competitive Landscape
Capability concentration sits with specialized blow-molding technicians and barrier coating formulators; scale advantage sits with pooling operators commanding distributed fleet networks. The vendor base organizes around three strategic archetypes: captive fabricators serving single brewery groups, independent specialists selling containers to fragmented brewers, and third-party fleet managers unbundling logistics from manufacturing. Dominant competitive moves include geographic expansion into adjacent national brewing corridors and technology licensing for RFID-enabled tracking systems.
Within the European specialist tier, Petainer UK Holdings Ltd and Lightweight Containers BV exemplify divergent geographic anchoring strategies—British retail channel penetration versus Benelux cooperative dominance. MicroStar / Kegstar occupies a position at the technology-vector end, representing the fleet-management archetype that unbundles logistics from core container sales. These three named entities illustrate how competitive positioning fragments across manufacturing expertise, regional procurement relationships, and circular-economy service bundling.
| Leading Market Players |
|---|
| Lightweight Containers BV |
| Petainer UK Holdings Ltd |
| Dolium BV |
| MicroStar / Kegstar |
| i-Keg |
| KegPlast |
| Konvoy |
| PolyKeg S.r.l. |
| Ningbo BestFriends Beverage Containers Co. Ltd |
| Others |
Pricing and Supply Chain Analysis
The Eindhoven blow-molding corridor anchors multi-layer PET fabrication capacity for northwestern European export, concentrating polymer barrier technology expertise that feeds downstream pricing power toward container specialists serving German and British brewery procurement offices.
Pricing Analysis
Long-term offtake contracts dominate procurement relationships between large brewery groups and captive fabricators, locking in volume commitments that insulate blow-molders from spot resin volatility. Three-tier pricing structure across premium, standard, and economy levels separates multi-layer PET with oxygen barrier coatings from basic polyethylene formulations and recycled-content alternatives. Price differentiation hinges on thermal resistance certification and embedded RFID tracking capability. Pricing pressure stems from unbundling of fleet management services that previously subsidized container margins. British pub distribution networks exhibit highest price sensitivity, while German craft brewing corridors prioritize logistics efficiency over per-unit cost.
Supply Chain Analysis
Upstream feedstock for barrier coatings concentrates among specialized chemical processors in Germany and the Netherlands, creating input vulnerability for multi-layer PET fabrication. Polyethylene and polypropylene resin supply draws from petrochemical complexes in Belgium, the Netherlands, and Germany. Oxygen-scavenging additive production rests on single-source relationships with ECHA-registered formulators. Supply chain risk centers on REACH migration testing timelines that stall new chemistry qualifications. Distribution runs through regional beverage distributors bundling container provision with route logistics, particularly in Benelux cooperative networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized blow-molding technician scarcity constrains capacity expansion across the Eindhoven corridor and German manufacturing regions, compressing design iteration cycles for innovators seeking KBA transport safety certifications.
For Market Incumbents: Insulate core fabrication margins by securing captive supply of oxygen-scavenging additives through backward integration into barrier coating formulators, and deepen geographic entrenchment in the Baden-Württemberg brewing corridor before pooling operators unbundle logistics revenue entirely. For New Entrants and Emerging Players: Build out event-specific format capabilities targeting Pacific Northwest microbreweries commissioning seasonal release branding, and anchor initial production in Greater Manchester pub distribution hubs where RFID-enabled fleet tracking standardization gaps favor technology-vector positioning over manufacturing scale. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified packaging conglomerates with underutilized blow-molding assets and dormant food-contact polymer certifications; long-term viability hinges on circular-economy service bundling rather than container manufacturing alone, with ECHA evaluation period compression for new barrier chemistries serving as the critical inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Barrier Coating Backward Integration | Captive supply of oxygen-scavenging additives from German chemical processors reduces REACH-driven input vulnerability. |
| RFID Fleet Tracking Partnership | Technology licensing to North American craft brewers displaces ownership-heavy asset strategies with service revenue. |
| Benelux Cooperative Expansion | Regional distributor relationships in Flanders normalize lightweight container acceptance radiating into French supply chains. |
| Mono-Material Design Certification | EU Green Deal packaging waste compliance rewards simplified end-of-life processing with reduced extended producer responsibility fees. |
| Custom Format Manufacturing Scale-Up | Limited-run keg geometries for seasonal releases merge packaging function with microbrewery marketing spend capture. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with brewery procurement directors, blow-molding plant managers, beverage distributor logistics heads, ECHA regulatory affairs specialists, and fleet pooling operations executives. Secondary validation drew from KBA transport safety certification databases, REACH registration dossiers, EU Single-Use Plastics Directive implementation reports, Benelux brewing cooperative procurement disclosures, and FDA food-contact material compliance filings. Bottom-up container shipment estimates were triangulated against top-down beverage industry draft volume allocations.
Calibration against historical polymer keg adoption curves and stainless steel displacement patterns anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product volume tier, material thermal resistance grade, end-use application context, and distribution channel structure. CAGRs were derived from logistic diffusion curves fitted to cooperative procurement normalization patterns and export logistics burden reduction incentives. Forecast inputs incorporated ECHA evaluation period assumptions and RFID fleet tracking penetration trajectories.
Stress conditions across barrier coating supply concentration, REACH migration testing timeline extension, and brewery capital expenditure cyclicality were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory relief qualification for reusable polymer formats and cooperative procurement network density thresholds. Cross-checking against German KBA pressurized container certification issuance rates and British Environment Agency packaging waste compliance filings is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plastic Packaging
Indonesia Plastic Packaging Market
Plastic Packaging
Plastic Battery Containers Market
Plastic Packaging
Packaging Industry in South Africa Market
Plastic Packaging
Polyethylene Mailers Market
Plastic Packaging
Poland Plastic Bottles Market
Plastic Packaging
Canada Plastic Bottles Market
Plastic Packaging
North America Single-Use Plastic Packaging Market
Plastic Packaging
Africa BOPP Films Market
Plastic Packaging
Global Molded Plastic Packaging Market
Plastic Packaging
Plastic T-Shirt Bags Market
Plastic Packaging
Global Plastic Bottle Recycling Market
Plastic Packaging
Plastic Cans Market
Plastic Packaging
United Arab Emirates Plastic Packaging Market
Plastic Packaging
Shrink Plastic Films Market
Plastic Packaging
Plastic Tumblers Market
Plastic Packaging
Thermoformed Plastic Trays Market