
 Sugarcane Based PET Bottles Market | 2026-2036
Sugarcane Based PET Bottles Market Size, Share, and Industry Trends Forecast 2026-2036
Sugarcane Based PET Bottles Market Analytics
The beverage industry is pivoting toward plant-derived packaging as carbon accounting becomes embedded in procurement criteria. Braskem anchors South American supply through its bio-ethylene platform in Triunfo. Indorama Ventures Public Company Limited extends its PET resin leadership into bio-based feedstock partnerships across Asian manufacturing zones. Coca-Cola leverages its scale to negotiate long-term offtake agreements for sugarcane-derived MEG, locking in volume commitments that competitors struggle to match.
Sugarcane based PET bottles substitute fossil-derived ethylene glycol with bio-ethylene glycol refined from fermented sucrose, yielding resin with identical mechanical properties and recyclability to conventional PET while reducing cradle-to-gate carbon intensity. The material serves primarily as a drop-in replacement for brands seeking verified Scope 3 emissions reductions without compromising bottle clarity, barrier performance, or existing reheat-stretch blow molding equipment. Bottles within the product type category dominate current volume, though containers are gaining traction in food packaging applications requiring wider mouth geometries. The disposable form segment leads absolute shipments, yet reusable formats command margin premiums through deposit-return system compatibility and extended-use durability specifications.
The EPA's bio-preferred program and the EU Green Deal packaging regulations create divergent compliance pathways that manufacturers must navigate simultaneously. Brazil's national biofuel policy framework and ANVISA food-contact material standards shape production economics and export eligibility for regional converters. Stakeholders must monitor feedstock cost volatility relative to Brazilian ethanol pricing and track certification scheme harmonization between Bonsucro and ISCC PLUS to avoid market access friction.
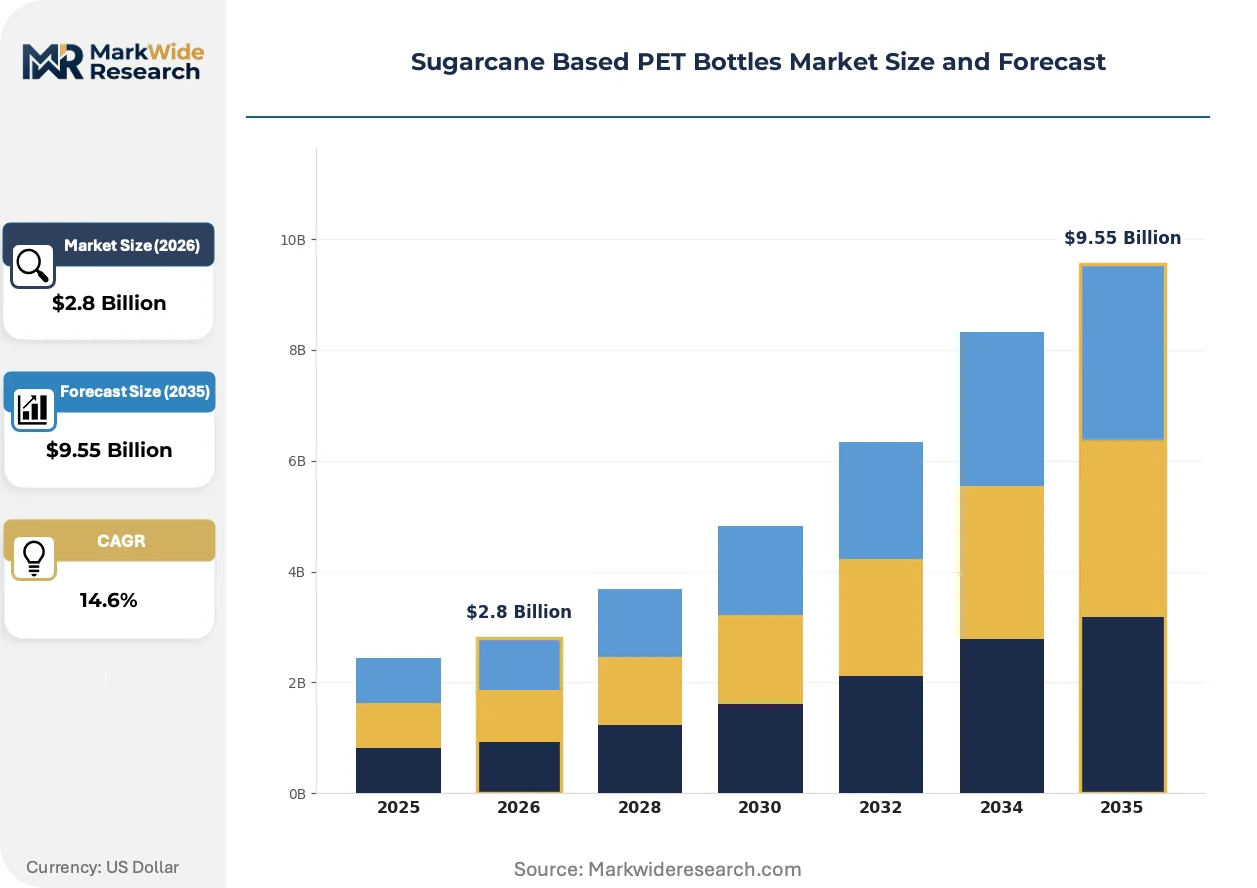
Market Dynamics
Beverage brand carbon accounting mandates are compressing procurement cycles for bio-based packaging, forcing converters to certify cradle-to-gate emissions reductions through audited supply chains rather than conventional resin purchasing.
Growth Catalysts
- EU Green Deal packaging directives:Mandatory recycled and bio-based content thresholds in beverage containers create compliance-driven demand for certified sugarcane-derived PET.
- Brazilian ethanol-to-ethylene infrastructure:Integrated biorefinery complexes in São Paulo and Triunfo deliver cost-competitive bio-ethylene glycol at scale unmatched by emerging producers.
- Deposit-return system expansion:Extended producer responsibility frameworks across Scandinavia and Germany reward mono-material bio-PET compatibility with existing sorting infrastructure.
Market Restraints
- Feedstock cost volatility:Brazilian ethanol pricing fluctuates with sugar commodity markets and federal fuel-blending mandates, compressing resin margins unpredictably.
- Supply concentration risk:Triunfo petrochemical cluster hosts the majority of commercial bio-ethylene capacity, creating single-point vulnerability for global bio-PET feedstock.
- Technical limitation:Current fermentation pathways cannot economically convert lignocellulosic bagasse to MEG, leaving sucrose dependence intact.
Strategic Opportunities
- ISCC PLUS certification harmonization:Convergence between European and Brazilian mass-balance accounting standards would unlock cross-border bio-content claims for converters.
- Food packaging mouth geometries:Wider-neck containers for sauces and condiments represent underpenetrated formats where bio-PET clarity advantages command specification premiums.
- Reusable format durability specifications:Deposit-return systems in Germany and Denmark are testing extended-wash-cycle bio-PET formulations that tolerate 25+ reuse iterations.
Industry Challenges
- Mass-balance auditor scarcity:ISCC PLUS and Bonsucro certification bodies face 6-9 month backlogs for facility audits, delaying product launches.
- Legacy blow molding reheat calibration:Bio-PET's slightly altered crystallization kinetics require furnace temperature adjustments that line engineers resist without technical support.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sugarcane Based PET Bottles Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $9.55 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottles, Containers, Jars, Carafes End User: Beverage Industry, Food Packaging, Personal Care, Household Products Form: Reusable, Disposable, Single-Use, Multi-Layer Capacity: 500ml, 1L, 2L, 5L |
| Companies Covered | Amcor Limited, Indorama Ventures Public Company Limited, Plastipak Holdings, Inc., Braskem, Avantium, ALPLA, Berry Global Inc., Coca-Cola, Danone, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sugarcane Based PET Bottles Market Evolving Landscape
Carbon accounting software integration is embedding emissions verification directly into procurement workflows, eliminating retrospective certification and compressing supplier qualification timelines.
Enzymatic PET depolymerization paired with bio-based virgin resin is rewriting circularity economics for beverage brands. Coca-Cola and PepsiCo pilot facilities in California and São Paulo are testing closed-loop systems where sugarcane-derived MEG re-enters the same bottle format. This convergence is compressing reliance on mechanical recycling infrastructure and enabling food-contact-approved circular claims that mechanical routes cannot match.
The EPA's bio-preferred program and EU Green Deal packaging waste regulations are diverging on bio-content calculation methodologies. US federal procurement favors minimum renewable content percentages while Brussels mandates mass-balance chain of custody. Converters supplying both markets must maintain dual certification systems, with European requirements generally proving more stringent and audit-intensive.
Brand sustainability officers are consolidating supplier rosters around vertically integrated resin-to-bottle partners capable of single-source carbon footprint reporting. This procurement compression favors converters with captive bio-ethylene supply or long-term offtake agreements, squeezing merchant resin buyers into secondary specification tiers. The shift is most visible in North American beverage contracts where Scope 3 disclosure deadlines have accelerated from annual to quarterly reporting cycles.
Sugarcane Based PET Bottles Market Segmentation
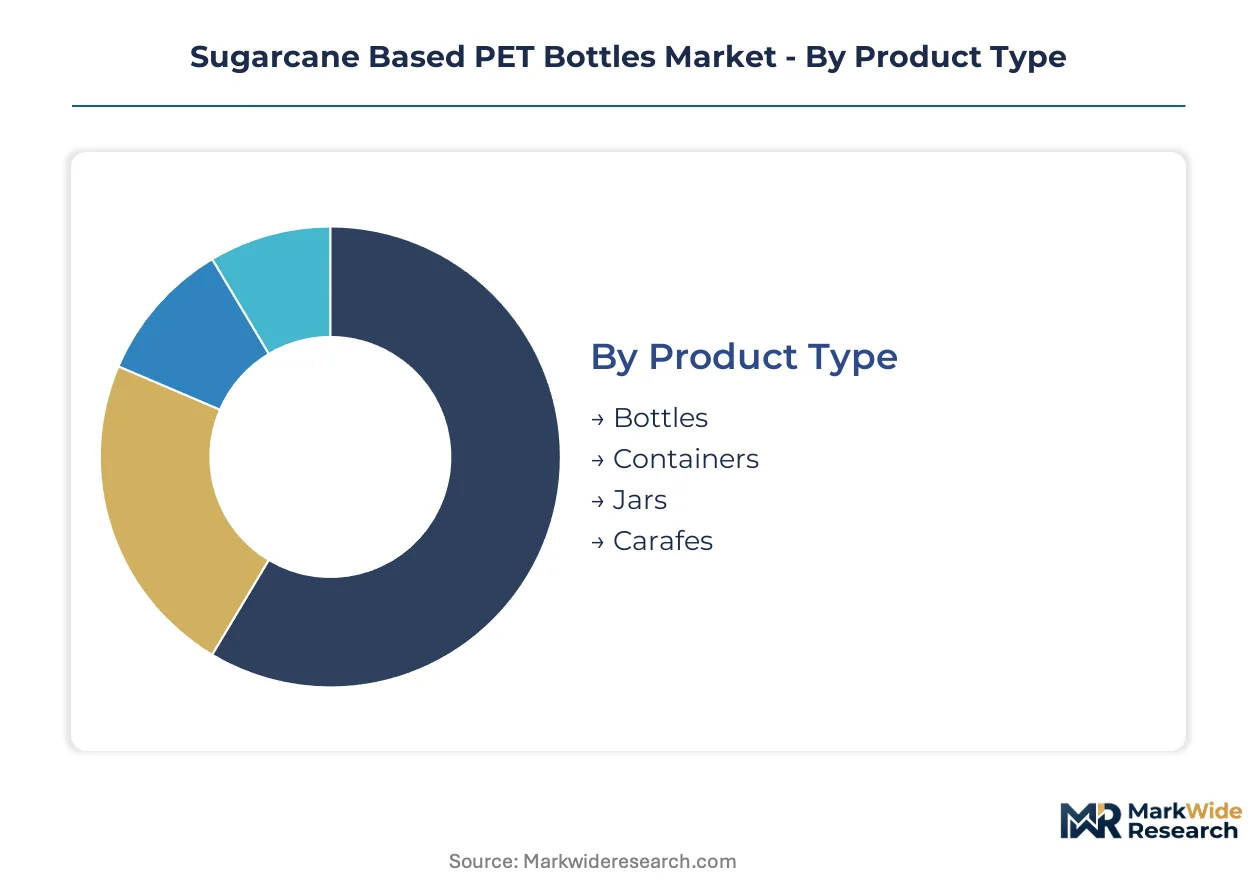
Sugarcane-based PET bottles command premium positioning across distinct product categories, with certification requirements varying sharply by end-use exposure and food-contact stringency. Procurement teams segment purchases around ISCC PLUS chain-of-custody thresholds, Bonsucro feedstock provenance, and ANVISA or FDA food-contact approvals.
Product Type:
Bottles carry the heaviest certification burden, requiring full FDA food-contact notification and EU 10/2011 compliance for beverage applications. Containers face intermediate scrutiny for dry goods, while jars and carafes navigate varying national standards for cosmetics and household chemical compatibility.
- Bottles:Standard neck finishes dominate beverage filling lines, with 28mm PCO and 38mm 3-start threads capturing the majority of carbonated and still water volumes. Demand concentrates in Brazil's integrated ethanol corridor and Germany's deposit-return infrastructure, where mono-material clarity supports mechanical sorting compatibility.
- Containers:Wide-mouth geometries suit sauces, condiments, and prepared foods requiring spoon access. Food packaging specifications in the EU and US drive ISCC PLUS mass-balance certification for bio-content claims above 30%.
- Jars:Cosmetic and personal care applications emphasize wall thickness and UV barrier properties. ANVISA cosmetic packaging standards govern Brazilian export eligibility.
- Carafes:Premium tableware and hospitality formats prioritize optical clarity and dishwasher durability. European hospitality procurement favors reusable formats with verified wash-cycle tolerance.
Leading the category by volume: Bottles. Growing fastest: Containers.
End User:
Cost tiers separate segments by resin grade tolerance and certification investment recovery. Beverage brands absorb premium bio-PET pricing for carbon accounting visibility, while household products accept lower bio-content blends.
- Beverage Industry:Carbonated soft drinks, bottled water, and juices require highest-purity MEG with <0.1% acetaldehyde content to protect taste profiles. Coca-Cola and PepsiCo offtake agreements anchor volume commitments.
- Food Packaging:Sauces, edible oils, and ready-meal containers demand oxygen barrier performance and migration testing under FDA and EFSA frameworks. Extended shelf-life specifications favor multi-layer structures with bio-PET outer skins.
- Personal Care:Shampoos, lotions, and cosmetics prioritize aesthetic clarity and chemical resistance. Fragrance compatibility testing adds 4-6 months to qualification timelines.
- Household Products:Cleaners and detergents tolerate higher bio-content variance and recycled PET blends. Price sensitivity limits bio-PET penetration to premium eco-label positioning.
Volume leadership: Beverage Industry. Steepest expansion trajectory: Food Packaging.
Form:
Application durability requirements dictate material formulation and reheat-stretch blow molding parameters. Reusable formats demand enhanced IV stability through extended wash cycles.
- Reusable:Deposit-return systems in Germany, Denmark, and Sweden specify 25+ wash-cycle tolerance. IV drop must remain below 0.05 dL/g per cycle to maintain mechanical integrity.
- Disposable:Single-trip beverage and food service applications prioritize cost minimization and existing recycling stream compatibility. Mechanical recycling infrastructure in Western Europe and North America accepts bio-PET without sorting separation.
- Single-Use:Event catering and travel retail formats emphasize lightweighting down to 8-10 gram preforms for 500ml water bottles. Carbon accounting disclosures drive specification above conventional PET pricing.
- Multi-Layer:Oxygen-scavenging interlayers and UV barrier coatings complicate end-of-life recycling. Mass-balance certification applies only to bio-PET structural layers, diluting overall bio-content claims.
Dominant by shipments: Disposable. Gaining share fastest: Reusable.
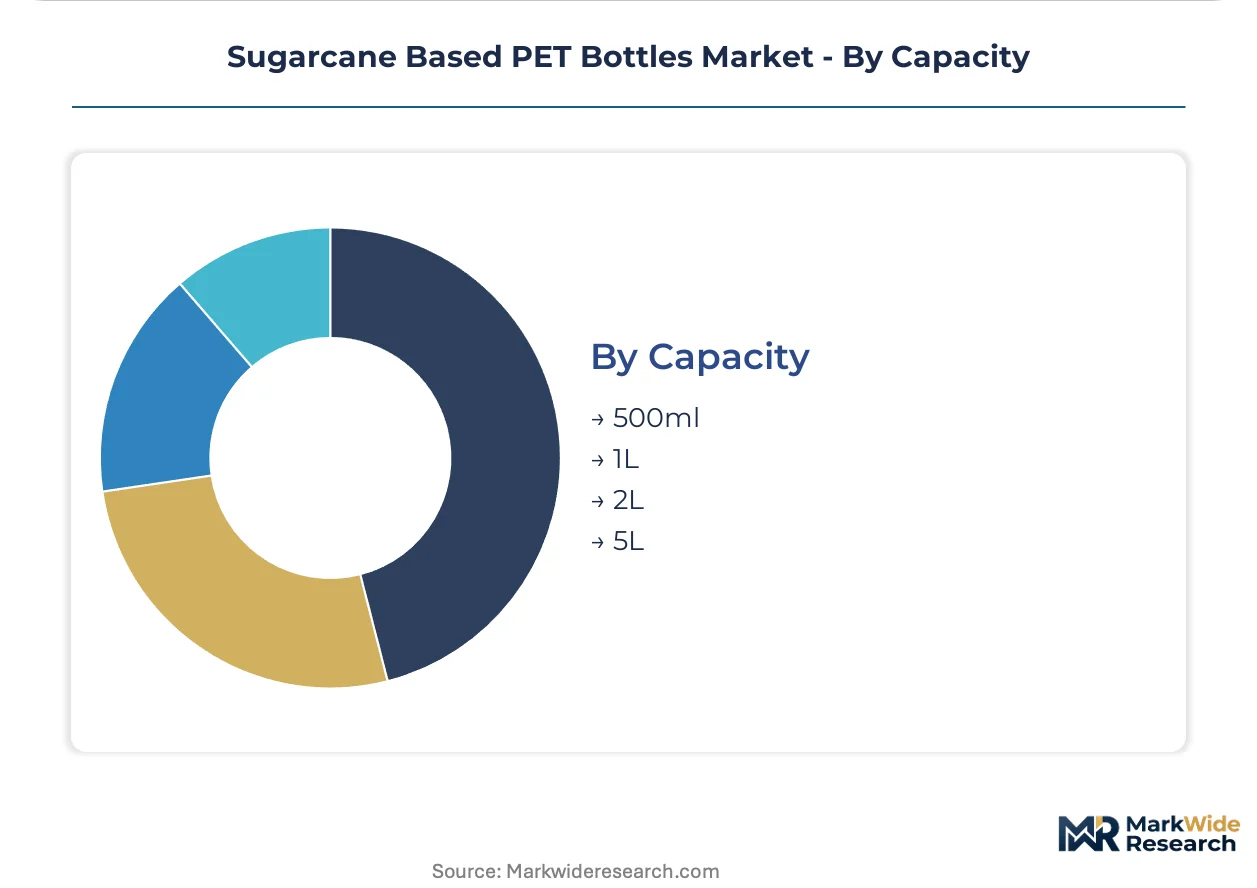
Capacity:
Customer type segmentation separates institutional buyers with long-term offtake contracts from spot-market purchasers. Volume scale determines converter willingness to absorb certification and tooling costs.
- 500ml:Personal hydration and single-serve beverage standard. Preform standardization across 14-16 gram weights enables high-speed filling line compatibility.
- 1L:Family-size beverages and condiment formats balance shelf presence with handling ergonomics. European retail private label penetration is strongest in this tier.
- 2L:Carbonated soft drink and edible oil bulk formats. Pressure resistance specifications exceed 4 bar internal pressure for CSD applications.
- 5L:Water cooler refills and institutional food service. Reusable formats with handle integration dominate, requiring specialized blow molding tooling.
Highest absolute volume: 500ml. Expanding most quickly: 1L.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
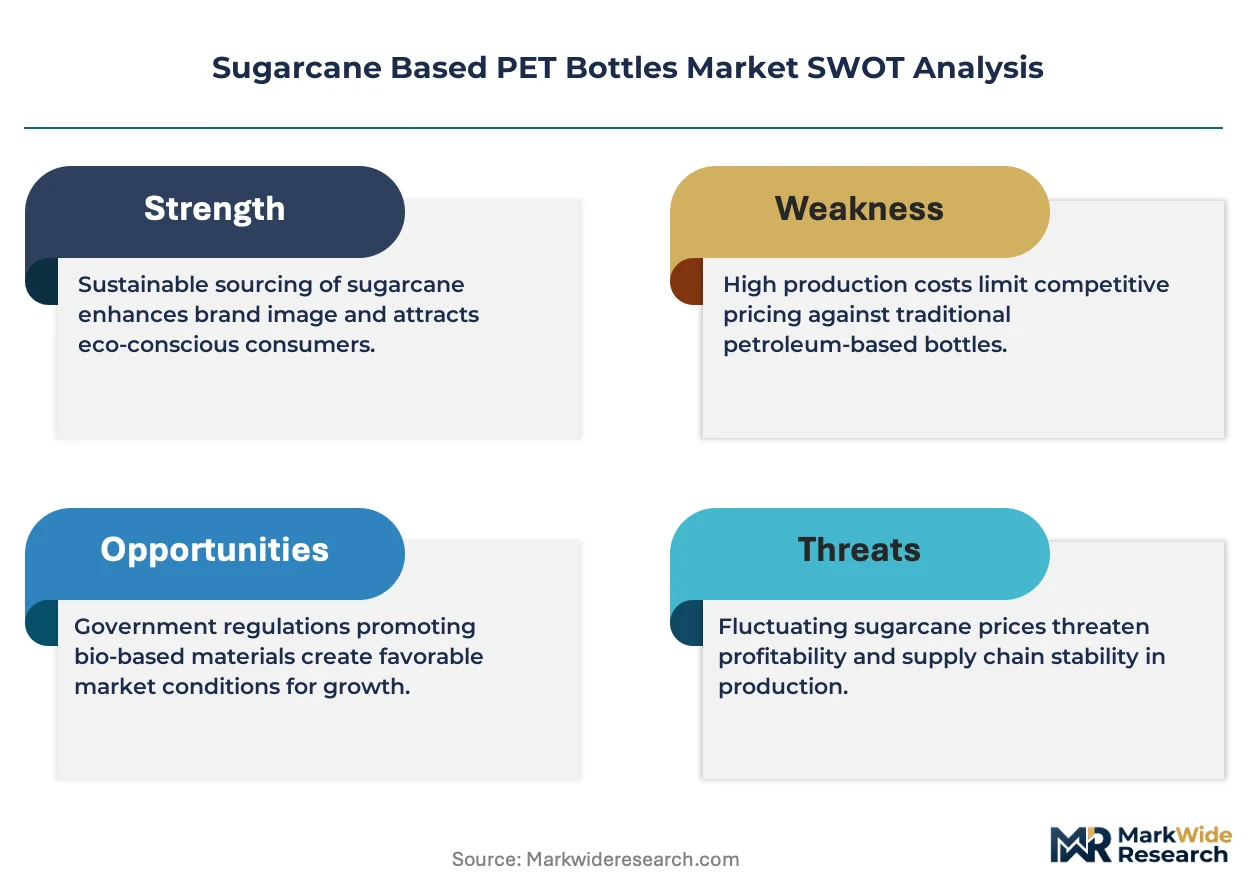
Brazil's Triunfo Petrochemical Complex anchors global bio-ethylene capacity through Braskem's integrated ethanol-to-ethylene corridor, creating a tax-advantaged export platform that feeds converters across three continents.
United States
Beverage brand carbon accounting mandates from Coca-Cola and PepsiCo drive procurement of ISCC PLUS-certified bio-PET for domestic filling lines. The EPA's bio-preferred program establishes minimum renewable content thresholds for federal procurement eligibility. California's SB 54 extended producer responsibility law requires post-consumer recycled and bio-based content in single-use packaging, concentrating converter investment in the Central Valley and Los Angeles basin.
Germany
Deposit-return system expansion rewards mono-material bio-PET compatibility with existing sorting infrastructure across 16 federal states. The EU Green Deal packaging waste directive mandates bio-based content thresholds for beverage containers sold in German retail. The Ruhr industrial corridor hosts pilot facilities testing 25-wash-cycle reusable bio-PET formulations for extended-use durability.
Brazil
Federal fuel-blending mandates and ANVISA food-contact standards shape production economics for sugarcane-derived MEG exports. The national biofuel policy framework guarantees ethanol supply security for Triunfo's petrochemical cluster. São Paulo state's integrated ethanol-to-bottle converter network delivers cost-competitive resin at scale unmatched by emerging producers.
Netherlands
Rotterdam's port infrastructure handles bulk bio-ethylene glycol imports for European converter networks seeking mass-balance certification. The Dutch government's circular plastics agenda accelerates procurement of bio-based packaging by institutional buyers. Eindhoven's polymer research institutes pilot enzymatic depolymerization systems paired with sugarcane-derived virgin resin.
Japan
METI's green growth strategy targets bio-based plastics substitution in food and beverage packaging supply chains. Japanese beverage conglomerates negotiate long-term offtake agreements for certified sugarcane-derived PET to meet Scope 3 disclosure requirements. The Kansai industrial region hosts specialty converters developing multi-layer oxygen barrier structures with bio-PET outer skins.
Sugarcane Based PET Bottles Market Competitive Landscape
Top-tier vendors anchor resin supply and long-term offtake negotiations, while mid-scale converters compete on certification speed and regional logistics. The market exhibits dual-layer concentration around captive bio-ethylene producers and vertically integrated bottle fabricators. Three archetypes dominate: integrated petrochemical-resin-to-bottle conglomerates, specialized bio-based packaging converters with ISCC PLUS certification, and beverage brand captive manufacturing divisions securing supply chain control. Capacity expansion and strategic partnerships represent the dominant competitive moves, with players racing to lock in Brazilian ethanol supply through multi-year agreements.
Among integrated petrochemical operators, Braskem anchors South American supply through its bio-ethylene platform, while Indorama Ventures Public Company Limited extends PET resin leadership into bio-based feedstock partnerships across Asian manufacturing zones. Amcor Limited occupies a position within the specialized converter tier, representing the packaging fabricator archetype that bridges resin procurement and brand qualification timelines.
| Leading Market Players |
|---|
| Amcor Limited |
| Indorama Ventures Public Company Limited |
| Plastipak Holdings, Inc. |
| Braskem |
| Avantium |
| ALPLA |
| Berry Global Inc. |
| Coca-Cola |
| Danone |
| Others |
Value Network & Pricing Analysis
Captive integration into Brazilian ethanol-to-ethylene corridors anchors both supply security and pricing power for converters serving multinational beverage brands. This upstream control over bio-ethylene glycol feedstock insulates integrated operators from spot market volatility while forcing merchant resin buyers into price-taker positions.
Pricing Analysis
Short lead-time premiums for ISCC PLUS-certified resin run 15-25% above contract baselines, while spot inventory liquidation creates temporary buying opportunities for smaller converters. Three-tier pricing structure across premium certified, standard mass-balance, and economy conventional PET tiers reflects certification investment recovery timelines. Pricing pressure stems from Brazilian ethanol cost volatility tied to sugar commodity swings and federal fuel-blending policy adjustments. Beverage brands with Scope 3 disclosure mandates show least price sensitivity, while household products converters resist bio-PET premiums beyond 10% of conventional resin.
Supply Chain Analysis
Dual-sourcing requirements from Coca-Cola and PepsiCo procurement teams mandate qualification of at least two ISCC PLUS-certified resin suppliers per geography, compressing single-source dependence despite Triunfo's concentration. Supply draws from Brazil, Thailand, and India for bio-ethylene glycol, with European converters adding Rotterdam bulk import terminals. Raw material dependencies center on sugarcane ethanol, bio-ethylene, and purified terephthalic acid. Single-source vulnerability concentrates in Braskem's Triunfo petrochemical cluster. Distribution runs through converter-owned blow molding facilities co-located with beverage filling lines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race. Players are pursuing captive bio-ethylene supply to lock in margin capture and certification speed.
For Market Incumbents: Deploy long-term ethanol offtake agreements to secure feedstock priority ahead of new converter entrants. Braskem's integrated position in Triunfo demonstrates how backward integration into Brazilian ethanol corridors neutralizes margin compression from sugar price volatility. Incumbents must accelerate ISCC PLUS audit capacity expansion to reduce 6-9 month certification backlogs that delay product launches.
For New Entrants and Emerging Players: Enzymatic depolymerization technology paired with bio-based virgin resin offers a technology-first wedge against mechanical recycling incumbents. Food packaging mouth geometries for sauces and condiments represent underpenetrated white space where bio-PET clarity advantages command specification premiums. Target European private label converters with faster qualification timelines than multinational beverage direct contracts.
For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by integrated petrochemical conglomerates seeking bio-based packaging capabilities. Long-term viability hinges on certification scheme harmonization between Bonsucro and ISCC PLUS standards. Watch Brazilian federal fuel-blending mandate adjustments as the inflection signal for ethanol supply security and pricing stability.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ethanol Supply | Captive Brazilian ethanol sourcing insulates converters from ANVISA export eligibility disruptions. |
| ISCC PLUS Certification Acceleration | Reduced audit timelines unlock German deposit-return system procurement before competitors qualify. |
| Reusable Format Durability Investment | 25-wash-cycle bio-PET formulations capture margin premiums in Scandinavian extended-use systems. |
| Enzymatic Depolymerization Pilot Scale-Up | Closed-loop MEG recovery enables food-contact circular claims beyond mechanical recycling limits. |
| Food Packaging Geometry Expansion | Wide-mouth container tooling accesses EU sauce and condiment specifications with bio-content thresholds. |
Research Methodology
Independent corroboration across regulatory filings, trade customs data, and certification body disclosures underwrites the qualitative findings. Primary interviews with bio-ethylene plant managers, beverage procurement directors, ISCC PLUS auditors, and blow molding line engineers combined with secondary validation from ANVISA food-contact notifications, Bonsucro chain-of-custody records, and Brazilian ethanol production statistics. Bottom-up resin capacity modeling and top-down beverage packaging demand estimation provided triangulation checks.
Rate-of-change decomposition across the analysis window separated volume growth drivers by product type, end-use industry, form durability specification, and regional regulatory cluster. Segmentation dimensions modeled include bottle geometry, beverage versus food packaging application, disposable versus reusable format, and converter capacity tier. CAGRs derived from logistic diffusion curves fitted to bio-based content penetration patterns, with ethanol pricing elasticity and certification adoption rates as key forecast inputs.
Several conditions sit outside the modeled scope, including breakthrough lignocellulosic MEG conversion technologies and EU-US regulatory convergence on mass-balance methodologies. Deviation in Brazilian federal fuel-blending policy would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plastic Packaging
Plastic-Free Packs Market
Plastic Packaging
Thailand Plastic Bottles Market
Plastic Packaging
Compostable Plastic Packaging Material Market
Plastic Packaging
United Kingdom Plastic Bottles Market
Plastic Packaging
South Africa Plastic Packaging Market
Plastic Packaging
MENA Thermoform Plastic Packaging Market
Plastic Packaging
Plastic Bottles and Containers Market
Plastic Packaging
Australia and New Zealand Plastic Bottles Market
Plastic Packaging
Germany Plastic Packaging Market
Plastic Packaging
Global Plastic Bottle Recycling Market
Plastic Packaging
North America Single-Use Plastic Packaging Market
Plastic Packaging
Asia Pacific Plastic Bottles Market
Plastic Packaging
Australia Plastic Packaging Market
Plastic Packaging
Injection Molded Plastics Market
Plastic Packaging
South Africa Flexible Plastic Packaging Market
Plastic Packaging
BOPP Tobacco Films Market