
 Australia Plastic Packaging Market | 2026-2036
Australia Plastic Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Plastic Packaging Market Outlook
APCO's 2025 packaging recycling targets is rotating competitive eligibility toward producers with verified closed-loop systems. Amcor plc leverages its global R&D network to sustain technology leadership in barrier films for protein packaging. Visy Industries Australia Pty Ltd anchors its position through backward integration into recycled resin production. Pact Group Holdings Ltd differentiates via geographic dominance across Australasian rigid packaging infrastructure.
Australia plastic packaging encompasses thermoformed, extruded, and molded polymer structures engineered to contain, protect, and preserve goods through distribution and retail channels, with specifications typically spanning 10-200 micron thickness for films and 0.5-5 liter capacities for rigid containers. Its primary commercial purpose centers on extending shelf stability while minimizing transport weight versus glass or metal alternatives. Polyethylene maintains volume leadership across bags and stretch film applications, while polypropylene gains share in injection-molded food containers where heat resistance commands premium positioning. Blow molding dominates bottle production for beverages and personal care, though thermoforming grows fastest in ready-meal tray formats aligned with convenience retail expansion.
TGA guidelines on pharmaceutical primary packaging, the National Plastics Plan recovery targets, and state EPA waste reduction policies collectively reshape material specifications and producer responsibility obligations across the value chain. These frameworks elevate demand for food-contact-compliant recycled content and accelerate compliance costs for importers lacking local recycling partnerships. Stakeholders must weigh capital allocation between virgin resin efficiency and recycled-content certification infrastructure as regulatory thresholds tighten without grandfathering provisions.
Market Dynamics
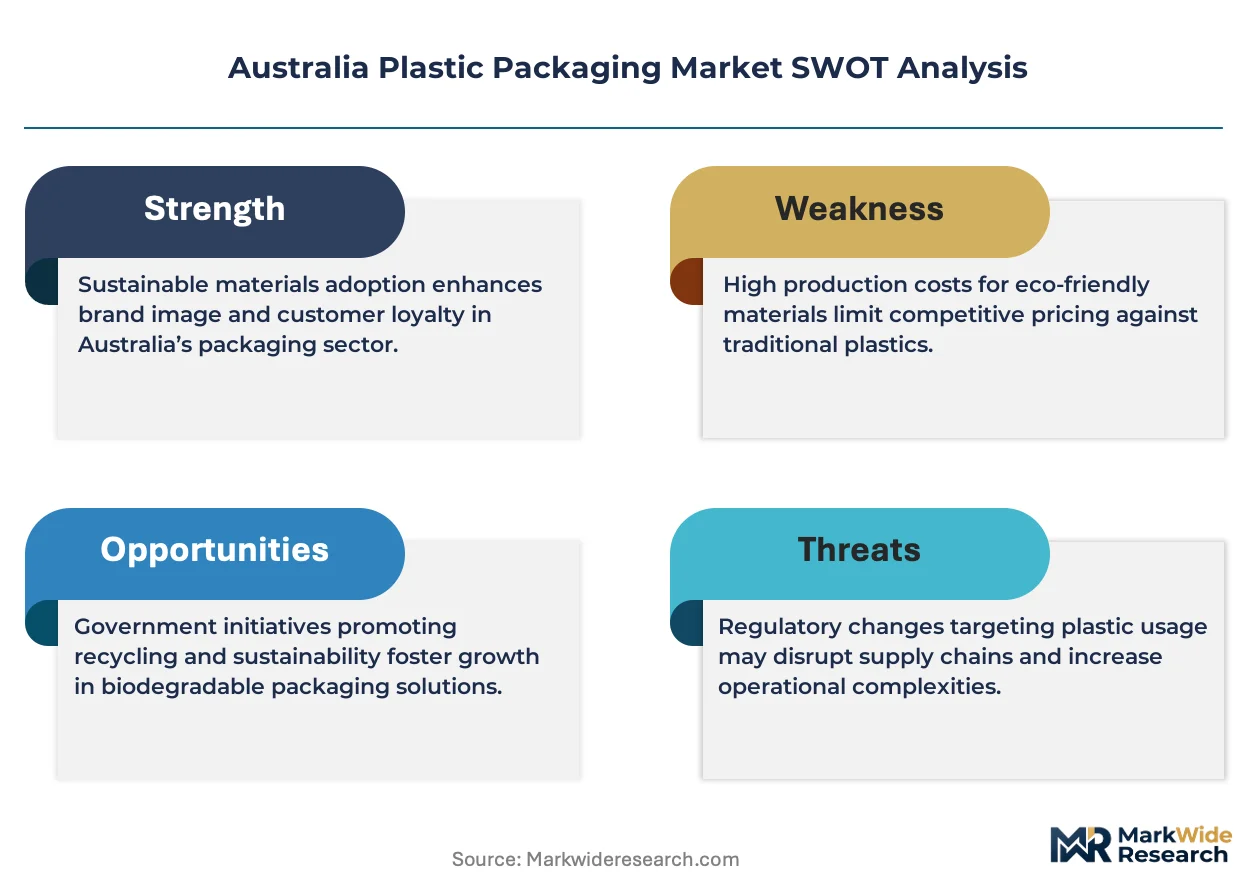
Australia's National Plastics Plan recovery targets and state-level container deposit schemes are compressing virgin resin demand while forcing capital reallocation toward closed-loop infrastructure. This regulatory tightening is the dominant structural force reshaping producer obligations across the value chain.
Growth Catalysts
- Container deposit scheme expansion:Victoria and New South Wales deposit-return obligations are accelerating collection infrastructure investment. Producers with verified recycling partnerships gain preferential shelf access.
- Protein packaging barrier innovation:Extended shelf-life films for fresh meat and dairy are displacing modified atmosphere formats. Retailers are consolidating SKUs around longer-dated stock.
- Queensland manufacturing cluster formation:Southeast Queensland's food processing corridor is concentrating flexible packaging demand. Logistics proximity to Port of Brisbane reduces inbound resin costs.
Market Restraints
- Recycled resin supply scarcity:Local rPET and rHDPE capacity lags APCO 2025 targets by approximately 40%. Import dependency exposes producers to shipping volatility.
- Natural gas feedstock cost pass-through:Polyethylene and polypropylene production remains tethered to east coast gas pricing. Energy-intensive blow molding operations face margin compression.
- Glass and fiber substitution in premium segments:Craft beverage and organic personal care brands are reverting to refillable glass. This retreat compresses high-margin bottle volumes.
Strategic Opportunities
- Tasmanian underpenetration:Island state's food export sector relies heavily on imported packaging. Local thermoforming capacity would capture premium seafood and dairy logistics.
- Chemically recycled content certification:Pyrolysis-derived feedstock offers food-contact compliance pathway unavailable to mechanical recycling. Early certifiers will secure brand partnerships.
- Direct-to-processor digital platforms:Bypassing distributor markup through B2B marketplaces is gaining traction among mid-sized food manufacturers. Platform economics favor scale aggregators.
Industry Challenges
- Polymer chemist talent scarcity:Formulation expertise for recycled-content compatibility is concentrated among retiring cohorts. Technical succession planning is underdeveloped.
- Multi-site certification synchronization:Achieving APCO verification across distributed manufacturing footprints requires harmonized audit timelines. Coordination costs escalate with facility count.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Plastic Packaging Market |
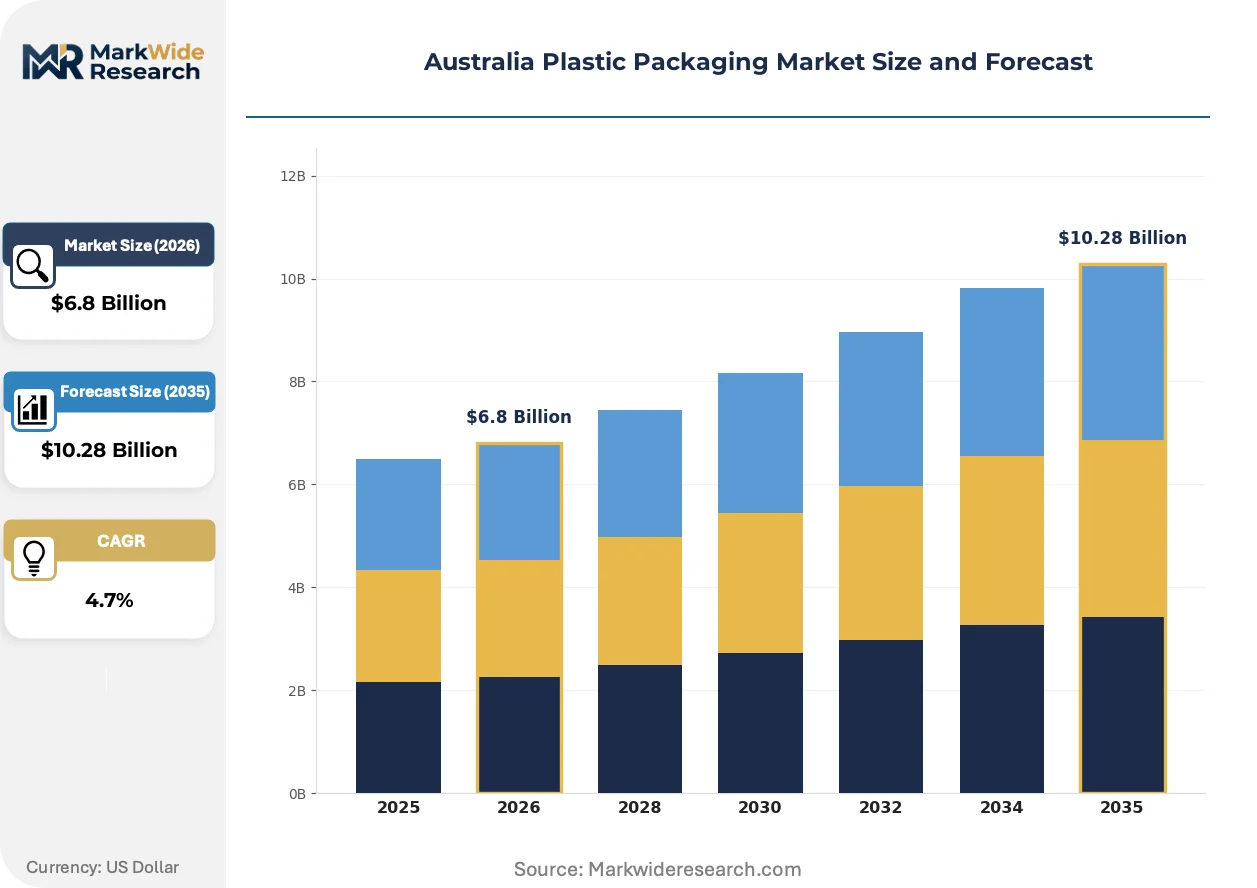
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.28 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Polyethylene, Polypropylene, Polyvinyl Chloride, Polystyrene Packaging Form: Bags, Bottles, Trays, Containers End Use: Food & Beverage, Household Products, Personal Care, Pharmaceuticals Technology: Blow Molding, Injection Molding, Thermoforming, Stretch Film |
| Companies Covered | Pact Group Holdings Ltd, Filton Packaging Pty Ltd, Amcor plc, Circular Plastics Australia Pty Ltd, Synergy Packaging Pty Ltd, Visy Industries Australia Pty Ltd, Pro-Pac Packaging Ltd, Flexible Packaging Solutions Pty Ltd, Orora Packaging Australia Pty Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Plastic Packaging Market Strategic Shifts
Active and intelligent packaging formats are penetrating Australian food retail, while regulatory compliance infrastructure becomes a competitive differentiator rather than cost center. Material science and digital traceability are converging to reshape producer value propositions.
Mono-material polyethylene structures are supplanting multi-layer barrier films in frozen food and snack applications. Coles and Woolworths private-label suppliers are converting tray specifications to simplify mechanical recycling streams. This simplification is compressing demand for ethylene vinyl alcohol coextrusion and adhesive lamination equipment.
TGA guidelines on pharmaceutical primary packaging are tightening extractables and leachables testing protocols for polymer containers. Compliance documentation burdens are shifting toward importers lacking local analytical capabilities. Generic drug contract manufacturers in Victoria and New South Wales are consolidating supplier panels to reduce audit duplication.
Retailer-led packaging reduction mandates are compressing traditional specification cycles. Woolworths' sustainable packaging targets are forcing suppliers to present lightweighted formats within 90-day windows. Protein and ready-meal categories are experiencing the most rapid iteration pressure as shelf-ready display requirements clash with material minimization goals.
Australia Plastic Packaging Market Segmentation
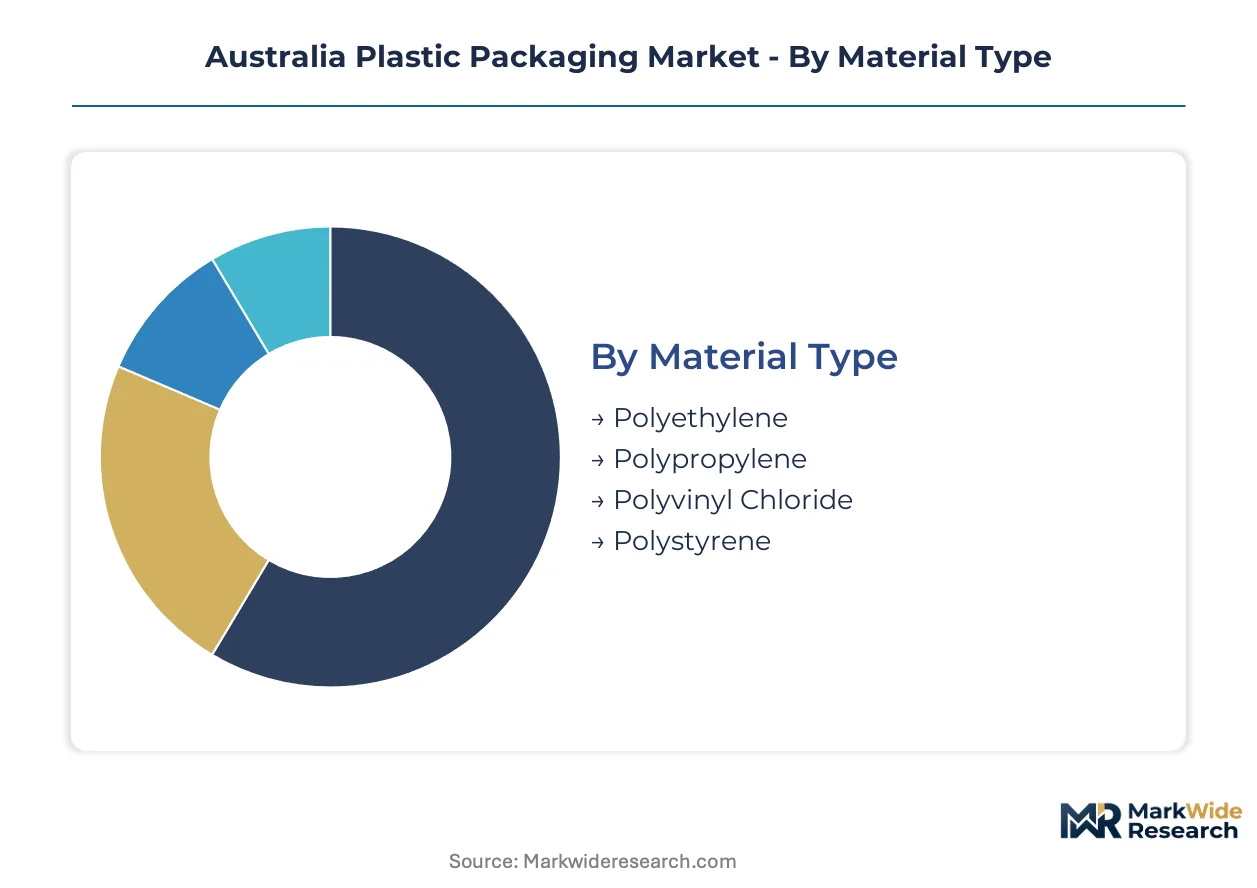
Australian plastic packaging procurement channels diverge sharply by material specification and shelf-life requirements. Food and beverage processors dominate volume flows, while pharmaceutical and personal care segments command premium positioning through TGA compliance infrastructure.
Material Type:
Polyethylene and polypropylene concentrate through supermarket private-label supply chains, while PVC and polystyrene serve specialized industrial and food service channels with distinct certification burdens.
- Polyethylene:Linear low-density formulations dominate stretch film and carrier bag applications across Victorian and New South Wales retail distribution centers. Woolworths and Coles have consolidated specifications around mono-material PE structures to satisfy APCO recycling targets.
- Polypropylene:Injection-molded containers for ready-meal and dairy applications are displacing polystyrene in Queensland's food processing corridor. Heat resistance specifications above 120°C enable hot-fill and microwaveable formats that polyethylene cannot match.
- Polyvinyl Chloride:Cling film and blister pack applications persist in pharmaceutical and fresh produce wrapping despite APCO pressure to eliminate problematic plastics.
- Polystyrene:Expanded formats retain niche presence in seafood export packaging and protective cushioning for Tasmanian aquaculture logistics.
By volume, polyethylene leads. By growth pace, polypropylene is climbing the fastest.
Packaging Form:
Cost tiers separate commodity formats from precision-engineered structures, with bags and stretch film anchoring economy positioning while trays and specialized containers capture margin through technical differentiation.
- Bags:T-shirt and wicketed formats flow through high-volume grocery channels with minimal specification variance. Lightweighting to sub-15 micron thicknesses has reached technical limits without compromising load integrity.
- Bottles:Blow-molded HDPE and PET containers for beverages and personal care face substitution pressure from refillable glass in premium craft segments. Container deposit scheme compliance adds recovery infrastructure costs that compress margin at economy price points.
- Trays:Thermoformed ready-meal and protein formats are expanding fastest in Southeast Queensland manufacturing clusters. Mono-material specifications simplify mechanical recycling streams versus legacy multi-layer barriers.
- Containers:Injection-molded rigid formats for dairy and spreads concentrate APCO compliance investment around verified recycled content certification.
By shipment frequency, bags dominate. By value per kilogram, containers command the steepest premium trajectory.
End Use:
Application requirements dictate material selection, with shelf-life extension driving barrier innovation in food while pharmaceutical extractables testing elevates documentation burdens.
- Food & Beverage:Protein packaging and ready-meal formats absorb the majority of flexible film innovation investment. Extended shelf-life specifications are displacing modified atmosphere packaging through active barrier layers.
- Household Products:Concentrated detergent and cleaning chemical containers prioritize chemical resistance and child-safety closures over recycled content percentages.
- Personal Care:Organic and premium brands in this segment are reverting to refillable glass and aluminum, compressing plastic bottle volumes in high-margin applications.
- Pharmaceuticals:TGA extractables and leachables protocols for polymer primary packaging are consolidating supplier panels among Victorian and New South Wales generic drug manufacturers.
By tonnage, food and beverage leads. By regulatory compliance cost per unit, pharmaceuticals sit at the apex.
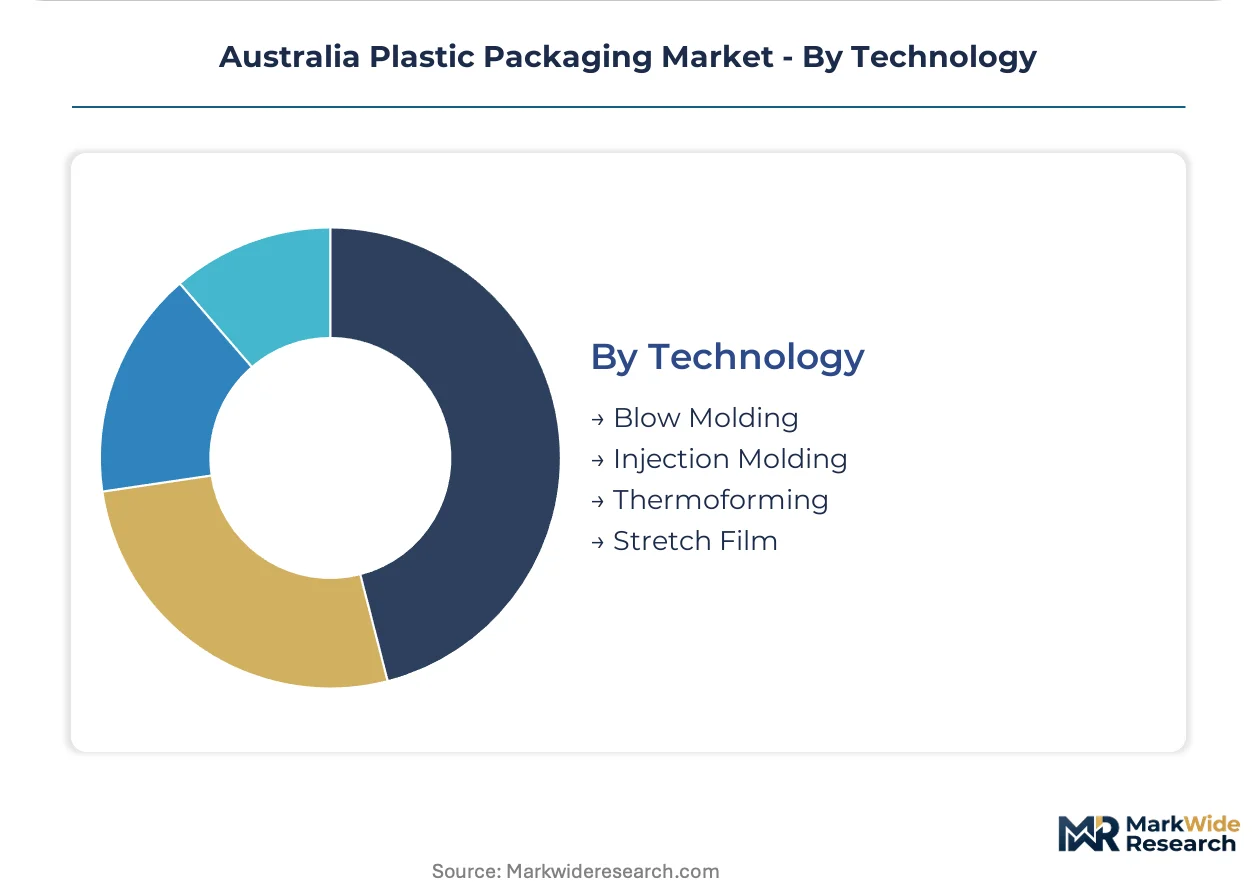
Technology:
Customer type separates commodity processors from specialized converters, with blow and injection molding serving high-volume brand owners while thermoforming and stretch film equipment address flexible, shorter-run requirements.
- Blow Molding:Extrusion and injection-stretch processes for beverage and personal care bottles remain tethered to east coast natural gas pricing. Energy-intensive operations face margin compression from feedstock volatility.
- Injection Molding:High-speed thin-wall production for dairy containers and closures concentrates in Pact Group's Australasian network. Cycle time optimization and hot-runner efficiency separate competitive cost positions.
- Thermoforming:Roll-fed and cut-sheet processes for ready-meal trays are gaining share fastest in Queensland's food processing corridor. Tooling flexibility enables rapid specification changes demanded by retailer reduction mandates.
- Stretch Film:Cast and blown processes for pallet wrapping and agricultural silage dominate polyethylene consumption volumes with minimal value-added differentiation.
By installed capacity, blow molding leads. By capital investment intensity per output dollar, thermoforming is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Melbourne anchors Australia's plastic packaging distribution network, handling the majority of resin imports and finished goods exports that flow through southeastern manufacturing corridors.
New South Wales
Sydney's food processing belt drives flexible film demand for protein packaging and ready-meal formats. The state's EPA waste reduction policies enforce APCO compliance timelines on producers operating within Greater Sydney. Manufacturing clusters in Western Sydney and the Central Coast concentrate thermoforming capacity for retail tray applications.
Victoria
Melbourne's dairy and beverage processing sector sustains high-volume rigid container consumption across the northern suburbs industrial zone. Container deposit scheme obligations under state legislation compel investment in collection infrastructure and verified recycling partnerships. Geelong's emerging advanced manufacturing precinct is attracting chemical recycling pilot facilities.
Queensland
Southeast Queensland's food processing corridor generates concentrated demand for flexible packaging serving meat and seafood exports. The state's container deposit scheme expansion is accelerating collection network buildout across Brisbane and the Gold Coast. Port of Brisbane proximity reduces inbound resin logistics costs for converters operating in the Bremer River industrial zone.
Western Australia
Perth's isolation from eastern manufacturing centers sustains localized blow molding capacity for beverage and household chemical containers. State-level waste recovery targets lag APCO national timelines, creating compliance complexity for national distributors. Kwinana's industrial strip hosts polymer compounding operations supplying regional packaging converters.
South Australia
Adelaide's container deposit scheme, operational since 1977, provides the most mature recovery infrastructure template nationally. Wine export logistics generate specialized demand for protective packaging formats serving Barossa Valley and McLaren Vale producers. The state's advanced manufacturing precincts are piloting mono-material specifications for simplified mechanical recycling streams.
Australia Plastic Packaging Market Competitive Environment
Listed leaders compete with private specialists across capital access and operational flexibility dimensions. The market structure tilts toward consolidation at the top tier, with three to four major players commanding scale advantages in resin procurement and national distribution networks. Strategic archetypes separate integrated resin-to-package operators, geographic-focused rigid specialists, and technology-led barrier film innovators. Dominant competitive moves center on backward integration into recycled resin production and APCO certification infrastructure buildout.
Within the integrated operator tier, Amcor plc and Visy Industries Australia Pty Ltd occupy positions that exemplify divergent scale strategies. Amcor leverages its global research network to anchor technology leadership in specialized barrier applications. Visy represents the backward-integrated archetype through captive recycled resin production. Pact Group Holdings Ltd sits within the geographic dominance category, with facility networks concentrated across Australasian rigid packaging infrastructure.
| Leading Market Players |
|---|
| Pact Group Holdings Ltd |
| Filton Packaging Pty Ltd |
| Amcor plc |
| Circular Plastics Australia Pty Ltd |
| Synergy Packaging Pty Ltd |
| Visy Industries Australia Pty Ltd |
| Pro-Pac Packaging Ltd |
| Flexible Packaging Solutions Pty Ltd |
| Orora Packaging Australia Pty Ltd |
| Others |
Value Chain & Pricing Dynamics
Mono-material polyethylene substitution for multi-layer barrier films is redrawing procurement geography toward Victorian and New South Wales converters while compressing ethylene vinyl alcohol coextrusion premiums. This material pivot simultaneously concentrates volume buying power among Woolworths and Coles private-label suppliers and erodes legacy adhesive lamination margins.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates contract negotiations. Price differentiation hinges on APCO certification grade and volume scale, with verified closed-loop systems commanding shelf-access premiums. Cost compression in economy-tier blow molding is intensifying because east coast natural gas feedstock volatility passes directly through polyethylene production. Mid-sized food manufacturers exhibit highest price sensitivity, while pharmaceutical contract manufacturers absorb compliance premiums without volume pushback.
Supply Chain Analysis
Strategic stockpiling of recycled resin dominates inventory strategy as local rPET and rHDPE capacity lags APCO targets. Supply concentrates in Thailand, South Korea, and China for virgin resin imports, while mechanical recycling feedstock draws from Victorian and New South Wales collection infrastructure. Single-source vulnerability permeates pyrolysis-derived food-contact feedstock, where early certifiers lock brand partnerships. Distribution runs through Port of Melbourne for southeastern manufacturing clusters, with Port of Brisbane serving Queensland food processing corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Australia's plastic packaging market functions as a service-attach opportunity where APCO compliance certification and recycling partnership verification expand faster than base resin conversion economics. Recurring revenue from audit synchronization and closed-loop infrastructure management outpaces commodity margin growth.
For Market Incumbents: Fortify backward integration into recycled resin production before import dependency exposes margin compression. Amcor plc and Visy Industries Australia Pty Ltd anchor positions through captive rPET supply and chemical recycling pilot capacity. Pact Group Holdings Ltd defends geographic dominance across Australasian rigid infrastructure by harmonizing multi-site APCO verification timelines. Threat of glass substitution in premium craft beverage segments demands barrier film innovation investment to retain high-margin bottle volumes. For New Entrants and Emerging Players: Differentiate on Tasmanian thermoforming capacity for seafood and dairy export logistics, where island state reliance on imported packaging sustains premium positioning. Southeast Queensland's food processing corridor offers white-space entry through mono-material tray specifications aligned with retailer reduction mandates. Direct-to-processor digital platforms bypass distributor markup among mid-sized Victorian meat processors seeking verified recycling partnerships. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed rigid packaging specialists lacking chemical recycling certification pathways. Five-to-ten year viability hinges on pyrolysis-derived food-contact compliance infrastructure that mechanical recycling cannot match. Signal to watch: APCO threshold tightening without grandfathering provisions triggering forced seller dynamics among import-dependent converters.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recycled Resin | Captive rPET supply insulates Visy Industries from shipping volatility and APCO compliance gaps. |
| Chemical Recycling Certification | Pyrolysis-derived feedstock unlocks food-contact pathways unavailable to mechanical recycling operators. |
| Multi-Site APCO Synchronization | Harmonized audit timelines reduce coordination costs for Pact Group's distributed manufacturing footprint. |
| Direct-to-Processor Digital Platform | B2B marketplace aggregation captures mid-sized food manufacturers bypassing traditional distribution markup. |
| Mono-Material Specification Conversion | Coles and Woolworths private-label compliance simplifies mechanical recycling streams and displaces EVOH barriers. |
Study Parameters
A spread of perspectives from resin procurement managers, thermoforming plant engineers, supermarket category buyers, and APCO compliance officers converged on the working assumptions. Primary fieldwork across Melbourne, Sydney, and Brisbane manufacturing clusters combined with secondary validation from Australian Bureau of Statistics trade data, state EPA waste reduction policy filings, and TGA pharmaceutical packaging guidelines. Bottom-up capacity assessments at converter facilities triangulated against top-down resin import flow analysis.
Segmentation dimensions modeled span material type, packaging form, end-use application, and manufacturing technology across the projection horizon. CAGRs derive from resin consumption tonnage trajectories, container deposit scheme expansion schedules, and protein packaging barrier innovation adoption curves. Forecast inputs incorporate east coast natural gas pricing volatility, recycled resin import dependency ratios, and retailer-led specification reduction mandate velocity.
Material uncertainties — regulatory threshold acceleration, chemical recycling feedstock commercialization delays, and glass substitution pace in premium segments — sit outside the modeled envelope. Forecasts reflect assumptions around APCO target continuity and state-level scheme harmonization without federal preemption. Revision becomes warranted when recycled resin supply scarcity crosses 50% of target shortfall thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plastic Packaging
Europe Personal Care Plastic Tube Packaging Market
Plastic Packaging
Plastic Cans Market
Plastic Packaging
Australia and New Zealand Plastic Bottles Market
Plastic Packaging
UVI Stretch Films Market
Plastic Packaging
Saudi Arabia Plastic Packaging Market
Plastic Packaging
Europe Single-Use Plastic Packaging Market
Plastic Packaging
E-Commerce Plastic Packaging Market
Plastic Packaging
Global Plastic Pails Market
Plastic Packaging
GCC PET Packaging Market
Plastic Packaging
PET Jars Market
Plastic Packaging
Plastic Bottles and Containers Market
Plastic Packaging
United Arab Emirates Plastic Bottles Market
Plastic Packaging
Injection Molded Plastics Market
Plastic Packaging
Italy Plastic Bottles Market
Plastic Packaging
North America Plastic Bottles Market
Plastic Packaging
Egypt Plastic Bottles Market