
 Europe Polyethylene Terephthalate (PET) Market | 2026-2036
Europe Polyethylene Terephthalate (PET) Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Polyethylene Terephthalate (PET) Market Insights
Food-grade rPET certification is redrawing competitive boundaries across European resin supply. Indorama Ventures Public Company Limited leverages its integrated flake-to-resin footprint to dominate recycled feedstock access in Western Europe. Novapet anchors its position through specialized copolyester production for premium cosmetic and pharmaceutical packaging. Selenis Portugal differentiates via pharmaceutical-grade PETG manufacturing serving regulated medical device markets.
Polyethylene terephthalate is a thermoplastic polyester polymerized from purified terephthalic acid and monoethylene glycol, typically exhibiting intrinsic viscosity between 0.70 and 0.84 dL/g depending on solid-state polymerization conditions; it functions primarily as a barrier packaging material for carbonated beverages, food containers, and industrial films requiring clarity, mechanical strength, and chemical resistance. Virgin PET retains volume leadership in carbonated soft drink bottling where optical clarity and batch consistency command premium positioning, while recycled PET captures accelerated growth in non-food contact sheet and fiber applications constrained by EFSA authorization timelines for direct food contact. Copolyester variants occupy margin-rich niches in medical blister packs and high-end cosmetic dispensers where modified glycol content enhances thermoformability and impact resistance.
The EU Green Deal packaging and packaging waste regulation, REACH chemical compliance frameworks, and EFSA food contact material authorizations collectively shape resin specifications, recycling content mandates, and market access conditions across the twenty-seven member states. Germany's national packaging ordinance and France's extended producer responsibility schemes impose differentiated collection and recycled content obligations that fragment procurement strategies. Stakeholders must monitor EFSA novel recycling process approvals and national deposit-return scheme expansions to calibrate capacity investments between virgin and recycled resin streams.
Market Dynamics
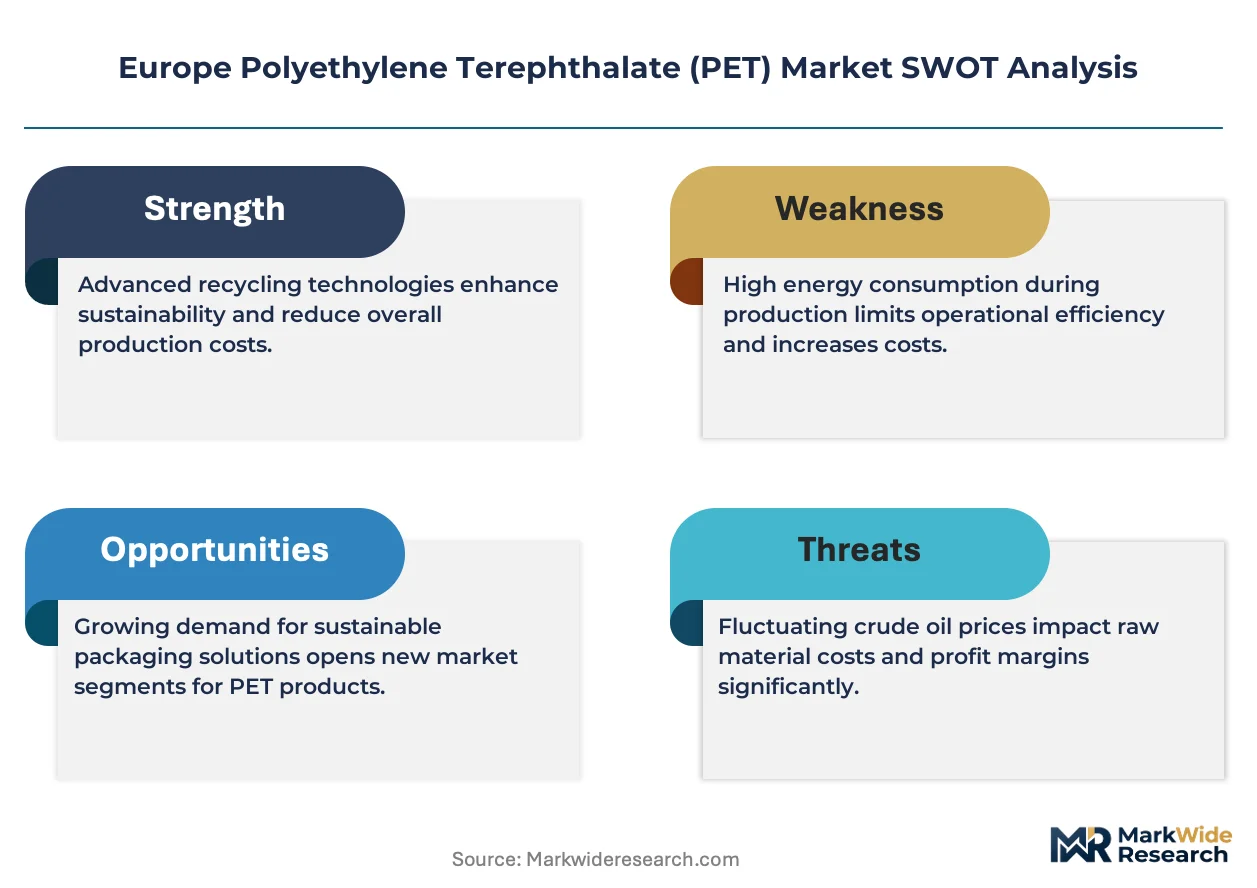
The EU Green Deal's packaging waste directives are forcing resin converters to reallocate capacity between virgin and recycled feedstock streams, compressing legacy asset valuations while rewarding EFSA-authorized recycling investments.
Growth Catalysts
- Deposit-return scheme expansion:Germany's national packaging ordinance and France's extended producer responsibility frameworks are mechanically boosting post-consumer PET collection rates, tightening bale supply for authorized recyclers.
- EFSA novel process approvals:Accelerated food-grade rPET authorizations are unlocking direct food contact applications previously reserved for virgin resin, redirecting brand procurement specifications.
- Beverage bottler consolidation:Major bottlers across Western Europe are standardizing on rPET-blend specifications, aggregating demand sufficient to justify dedicated recycling line investments.
Market Restraints
- Monoethylene glycol feedstock volatility:Crude oil and paraxylene price swings transmit directly to virgin PET resin economics, eroding margin predictability for non-integrated converters.
- Recycling capacity concentration:Western European flake-to-resin infrastructure clusters in Germany, France and Italy, creating geographic supply bottlenecks for peripheral markets.
- Intrinsic viscosity degradation:Mechanical recycling processes impose molecular weight loss constraints that disqualify rPET from carbonated beverage applications requiring high-pressure resistance.
Strategic Opportunities
- Central and Eastern European greenfield sites:Poland, Romania and Hungary offer lower-cost labor pools and proximity to underexploited post-consumer bale flows from expanding deposit schemes.
- Pharmaceutical-grade PETG copolyester:Modified glycol formulations for medical blister packs command substantial premiums over commodity resin, rewarding specialized polymerization expertise.
- Chemical recycling integration:Pyrolysis and glycolysis technologies promise food-grade output without EFSA batch-by-batch authorization delays, attracting strategic capital deployment.
Industry Challenges
- Polymer chemist scarcity:Specialized expertise in solid-state polymerization and IV control is concentrating at established Western European producers, constraining new entrant technical capabilities.
- Legacy extrusion line retrofit costs:Converting sheet and fiber equipment to handle higher rPET contamination tolerance requires substantial capital outlays with uncertain payback periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Polyethylene Terephthalate (PET) Market |
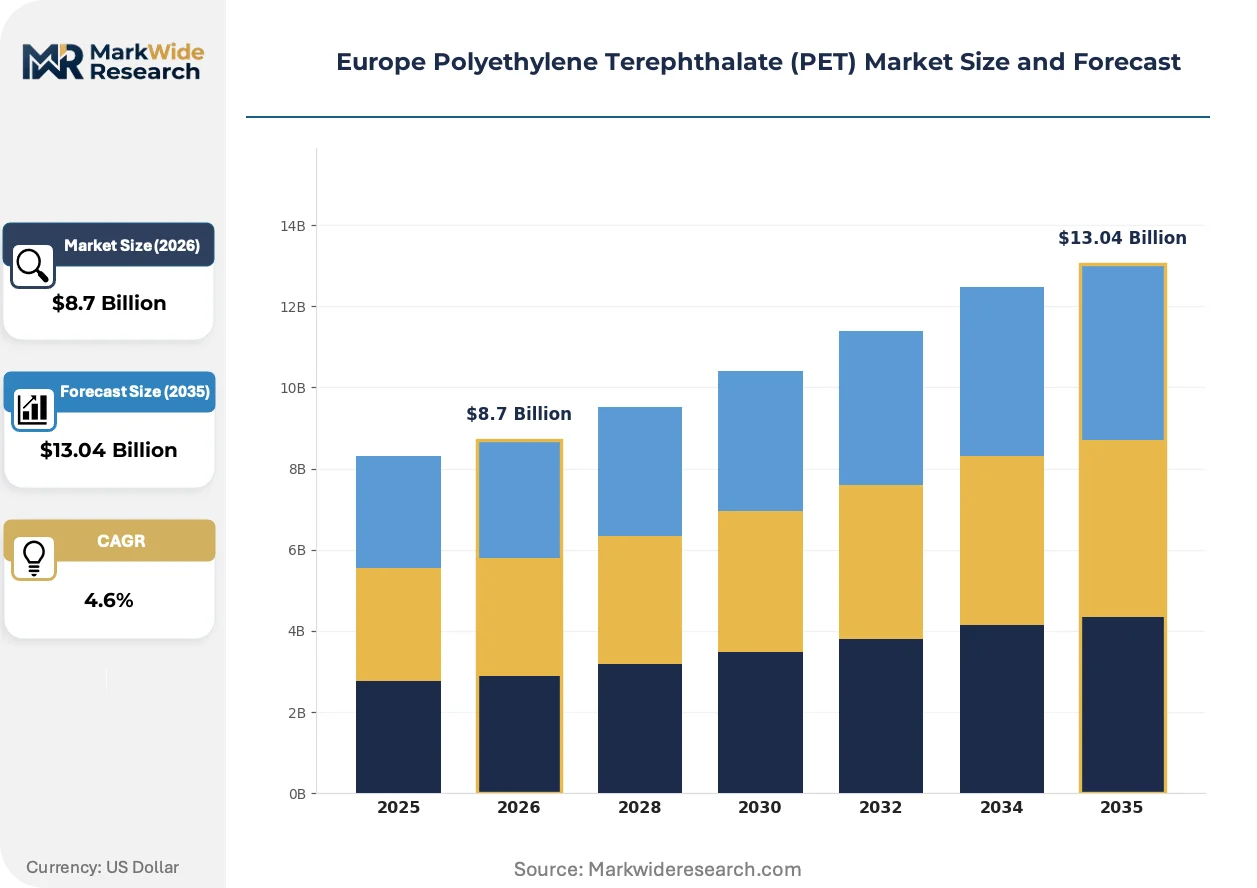
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Virgin PET, Recycled PET, Blended PET, Copolyester Application: Bottles, Films, Fiber, Packaging End User: Consumer Goods, Automotive, Electronics, Textiles Distribution Channel: Online Retail, Direct Sales, Distributors, Wholesalers |
| Companies Covered | Indorama Ventures Public Company Limited, Alpek S.A.B. de C.V., Plastipak Holdings, ALPLA Group, Equipolymers, LyondellBasell Industries, BASF SE, Novapet, Selenis Portugal, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Polyethylene Terephthalate (PET) Market Trends and Innovations
Advanced recycling technologies are decomposing the technical barriers between post-consumer waste and food-grade resin quality, restructuring competitive advantage around molecular purification capabilities rather than mechanical sorting scale.
Enzymatic depolymerization is decomposing PET at the molecular level into purified terephthalic acid and monoethylene glycol monomers, enabling infinite recyclability without viscosity loss. Beverage bottlers in France and the Netherlands are piloting offtake agreements for enzymatically recycled output. This technology is decomposing the historical trade-off between recycled content targets and performance specifications in carbonated soft drink applications.
REACH chemical compliance frameworks are tightening registration requirements for recycled feedstock contaminants, compelling recyclers to invest in advanced purification and analytical testing infrastructure. The industrial consequence is accelerated consolidation among small-scale mechanical recyclers unable to absorb compliance costs. Pharmaceutical and cosmetic packaging segments are most affected, with brands demanding batch-level contaminant documentation previously unnecessary for industrial applications.
Brand-led procurement coalitions are aggregating volume commitments to underwrite dedicated rPET supply contracts, bypassing spot market volatility. Major European retailers are displacing traditional resin distributors with direct converter relationships backed by multi-year offtake guarantees. This pattern is most visible in Germany, where supermarket private-label beverage volumes provide sufficient scale to justify integrated recycling investments.
Europe Polyethylene Terephthalate (PET) Market Segmentation
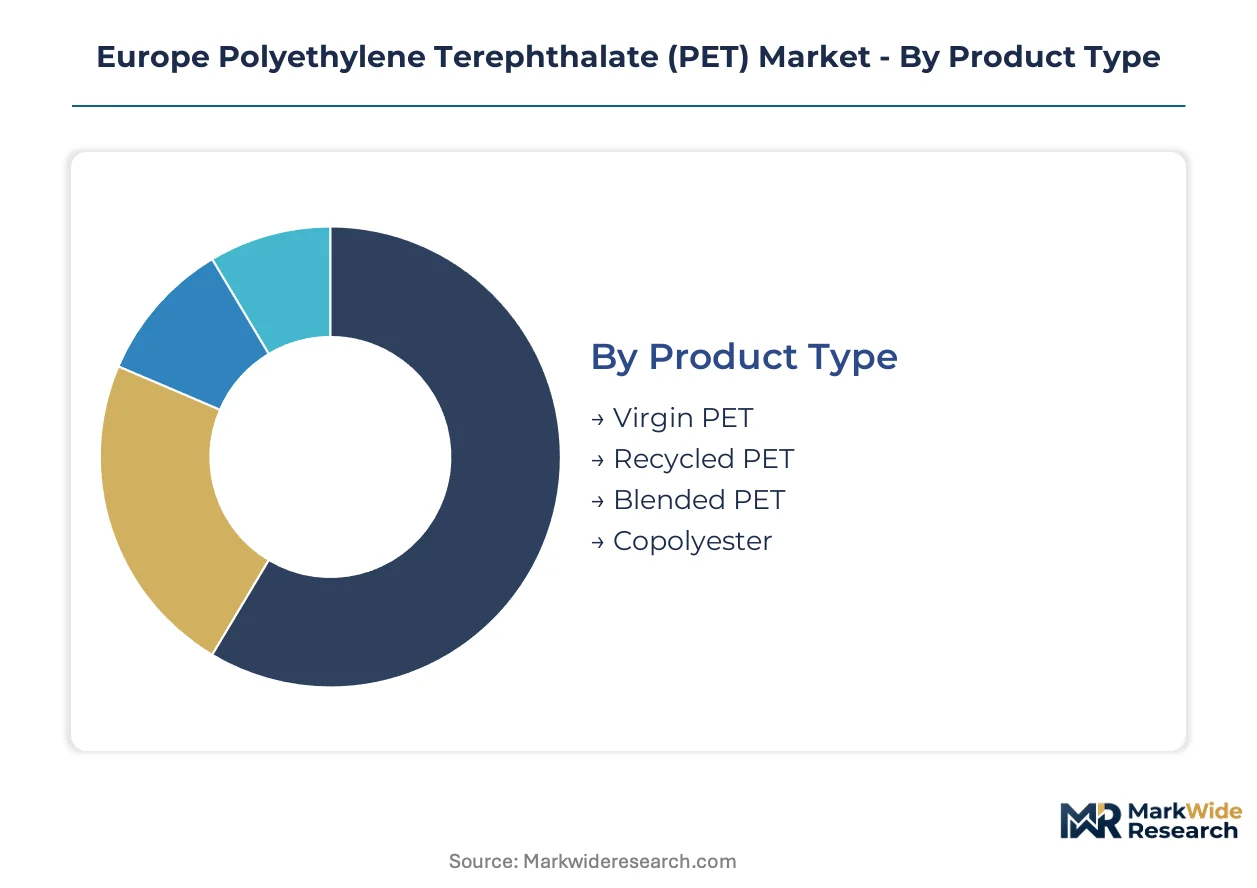
Segmentation across the Europe PET market reveals how regulatory pressure and end-use specifications are fragmenting procurement strategies. Each dimension exposes different competitive advantages, from EFSA authorization requirements in food-contact grades to specialized copolyester formulations for medical applications.
Product Type:
Domestic demand concentrates in virgin and recycled grades serving beverage bottlers across Germany, France, and Italy, while copolyester exports target premium pharmaceutical and cosmetic packaging in Switzerland and the Nordic markets.
- Virgin PET:Polymerized from purified terephthalic acid and monoethylene glycol through solid-state polymerization, achieving intrinsic viscosity between 0.72 and 0.82 dL/g. Carbonated soft drink bottlers in Germany and France specify virgin resin for optical clarity and batch consistency under high-pressure filling conditions. This grade commands premium positioning where performance specifications override sustainability targets.
- Recycled PET:Derived from post-consumer flake through mechanical or chemical reprocessing, with food-grade variants requiring EFSA novel process authorization. Beverage bottlers in the Netherlands and Belgium are standardizing rPET-blend specifications, aggregating demand sufficient to justify dedicated recycling line investments. REACH compliance frameworks and intrinsic viscosity degradation constraints limit penetration in pressure-sensitive applications.
- Blended PET:Combines virgin and recycled feedstock at ratios calibrated to application requirements and brand sustainability commitments. Sheet extruders across Spain and Portugal utilize blends to balance cost and environmental credentials without full food-contact authorization.
- Copolyester:Modified glycol formulations including PETG and PCTG variants with enhanced thermoformability and impact resistance. Pharmaceutical blister pack manufacturers in Switzerland and high-end cosmetic dispensers in France specify these grades for regulatory compliance and aesthetic performance.
Virgin PET holds the largest share; momentum sits with recycled PET as EFSA approvals accelerate.
Application:
Cost tier differentiation separates commodity bottle resin from margin-rich specialty films and fiber grades, with packaging applications commanding the widest specification spread.
- Bottles:Carbonated beverage, water, and edible oil containers represent the dominant volume application, with specifications varying by pressure resistance and clarity requirements. German and French bottlers are driving rPET integration through deposit-return scheme expansions and extended producer responsibility mandates.
- Films:Biaxially oriented PET films for food packaging, industrial lamination, and electrical insulation require precise thickness control and surface treatment. Italian converters specialize in thin-gauge films for flexible packaging exports to North African markets.
- Fiber:Textile-grade PET for polyester staple fiber and filament yarn serves automotive interiors and technical textiles. Non-food contact fiber applications absorb significant rPET volumes constrained by EFSA authorization timelines for direct food contact alternatives.
- Packaging:Thermoformed trays, clamshells, and blister packs span food, pharmaceutical, and consumer goods segments. Medical-grade packaging in Switzerland and premium cosmetic applications in France specify copolyester variants with superior barrier properties and thermoformability.
Bottles dominate volume; packaging represents the steepest expansion trajectory as pharmaceutical and cosmetic specifications tighten.
End User:
Customer type fragmentation separates high-volume beverage procurement from specialized automotive and electronics specifications with diverging technical requirements and contract structures.
- Consumer Goods:Beverage, food, personal care, and household product packaging constitutes the primary demand center. Major European retailers are displacing traditional resin distributors with direct converter relationships backed by multi-year offtake guarantees for rPET-blend specifications.
- Automotive:Interior trim, under-hood components, and electrical connectors utilize glass-filled and impact-modified PET grades. Tier suppliers in Germany and the Czech Republic specify recycled content for sustainability reporting without food-contact purity constraints.
- Electronics:Connectors, switches, and LED housings require flame-retardant and high-heat formulations. Italian and German compounders serve this segment with specialized additive packages and color-matching capabilities.
- Textiles:Polyester fiber for apparel, home furnishings, and technical applications draws heavily on non-food-grade rPET streams. Turkish and Moroccan textile mills source European flake for downstream processing, creating export demand for collected bales.
Consumer goods commands the largest share; automotive is gaining share fastest as sustainability reporting mandates expand.
Distribution Channel:
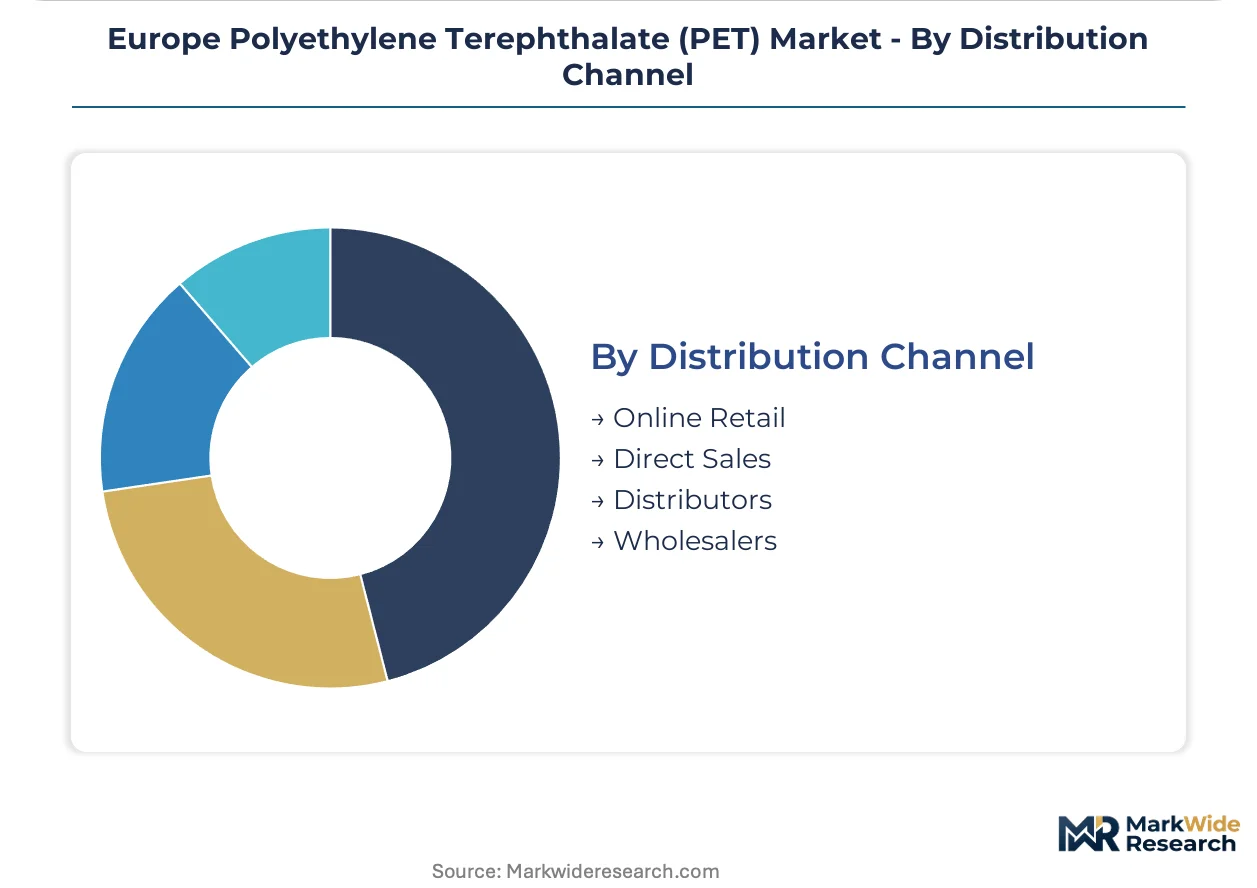
Supply concentration varies by channel, with direct sales dominating large beverage accounts and distributors serving fragmented sheet and fiber converters across peripheral markets.
- Online Retail:Emerging platform for specialty grades and small-lot procurement, particularly for pilot-scale chemical recycling output and experimental copolyester formulations. Limited current penetration in bulk virgin resin transactions.
- Direct Sales:Integrated producers including Indorama Ventures and Novapet maintain direct relationships with major beverage bottlers and pharmaceutical packaging converters. Multi-year offtake agreements with price-volume mechanisms displace spot market exposure.
- Distributors:Regional stockists serve mid-scale sheet extruders, fiber producers, and compounders across Spain, Portugal, and Eastern Europe. Inventory positioning and technical support differentiate distributor value propositions.
- Wholesalers:Bulk resin traders aggregate spot volumes and manage inter-regional arbitrage, particularly for non-integrated converters in Poland, Romania, and Hungary seeking alternative to direct mill relationships.
Direct sales holds the largest share; momentum sits with distributors as mid-scale converter fragmentation persists in peripheral markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Western European resin production exceeds internal consumption, generating substantial export volumes to North African textile mills and Eastern European converters. Peripheral markets import specialized copolyester grades from Swiss and German producers. Intra-regional trade flows concentrate through Rotterdam and Hamburg port complexes.
Germany
Beverage bottlers in Bavaria and North Rhine-Westphalia drive rPET procurement through the national packaging ordinance's deposit-return infrastructure. The country's central bank monitors industrial polymer feedstock costs as part of broader manufacturing inflation indices. Hamburg anchors flake-to-resin conversion capacity serving Scandinavian and Baltic export markets.
France
Extended producer responsibility frameworks mechanically boost post-consumer collection rates around Paris and Lyon metropolitan clusters. EFSA novel process approvals for food-grade recycling concentrate among converters in the Île-de-France industrial belt. Cosmetic packaging specialists in Provence-Alpes-Côte d'Azur specify premium copolyester grades for export to Swiss pharmaceutical customers.
Italy
Thin-gauge film extruders in Lombardy and Emilia-Romagna export flexible packaging to North African markets. The country's national packaging regulator enforces differentiated recycled content obligations across northern and southern regions. Venice-Porto Marghera hosts specialized PETG production serving medical device manufacturers.
Netherlands
Rotterdam's petrochemical complex integrates purified terephthalic acid production with downstream resin polymerization. Dutch beverage bottlers pilot enzymatic recycling offtake agreements with technology developers. The port city's warehousing infrastructure enables just-in-time delivery to German and Belgian converters.
Spain
Sheet extruders in Catalonia and Valencia utilize blended PET grades to balance cost and environmental credentials without full food-contact authorization. The country's national waste management agency coordinates bale collection from expanding municipal deposit schemes. Barcelona's converter cluster serves Portuguese and Moroccan packaging markets.
Europe Polyethylene Terephthalate (PET) Market Competitive Landscape
Listed leaders compete with private specialists across flake-to-resin integration depth, creating tiered supply access. The vendor base concentrates around integrated petrochemical groups and specialized recycling operators. Three archetypes dominate: multinational resin producers with backward integration into purified terephthalic acid, standalone mechanical recyclers seeking EFSA food-grade authorization, and copolyester specialists serving pharmaceutical niches. Capacity expansion and strategic partnerships constitute the dominant competitive moves.
Within the integrated multinational tier, Indorama Ventures Public Company Limited and Alpek S.A.B. de C.V. occupy positions defined by scale and feedstock control. Novapet represents the specialized copolyester archetype, while Selenis Portugal exemplifies pharmaceutical-grade PETG manufacturing expertise. These three entities anchor distinct competitive vectors without overlapping strategic positioning.
| Leading Market Players |
|---|
| Indorama Ventures Public Company Limited |
| Alpek S.A.B. de C.V. |
| Plastipak Holdings |
| ALPLA Group |
| Equipolymers |
| LyondellBasell Industries |
| BASF SE |
| Novapet |
| Selenis Portugal |
| Others |
Pricing and Supply Chain Analysis
EFSA food-grade rPET authorization gates both supply qualification and price differentiation across European resin markets. The certification regime bifurcates converters into authorized premium suppliers and non-authorized commodity sellers, with beverage bottlers paying substantial premiums for direct food-contact grades while sheet extruders absorb lower-cost alternatives.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across the European PET market. Price differentiation separates EFSA-authorized food-grade resin from industrial sheet and fiber grades, with virgin PET commanding premiums for optical clarity in carbonated beverage applications. Cost compression in mechanical recycling is intensifying because intrinsic viscosity degradation constrains high-pressure bottle specifications. Mid-scale converters in Spain and Portugal exhibit highest price sensitivity, while pharmaceutical packaging specialists in Switzerland demonstrate lowest sensitivity due to regulatory compliance requirements.
Supply Chain Analysis
Germany, France and Italy anchor flake-to-resin conversion capacity serving Western European beverage bottlers. Purified terephthalic acid, monoethylene glycol and post-consumer bale collections constitute critical input dependencies. Single-source vulnerability concentrates in EFSA-authorized recycling infrastructure clustered around Hamburg, Paris and Milan metropolitan belts. Distribution runs through Rotterdam and Hamburg port complexes with just-in-time delivery to German and Belgian converters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized polymerization expertise scarcity defines competitive boundaries, with solid-state polymerization and intrinsic viscosity control capabilities concentrating at established Western European producers. This capability gap constrains new entrant technical qualification and sustains incumbent margin structures.
For Market Incumbents: Fortify EFSA authorization portfolios through dedicated recycling line investments in Germany and France to preempt emerging chemical recycling entrants. Deepen captive supply of purified terephthalic acid to insulate margin structures from paraxylene volatility. Prioritize pharmaceutical-grade PETG capacity expansion in Switzerland to capture medical device packaging premiums.
For New Entrants and Emerging Players: Chemical recycling purification services represent the most penetrable white-space target, with pyrolysis and glycolysis technologies bypassing EFSA batch-by-batch authorization delays. Poland, Romania and Hungary offer underexploited post-consumer bale flows from expanding deposit schemes with lower-cost labor pools. Pursue direct offtake agreements with Dutch beverage bottlers piloting enzymatic depolymerization output.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed mechanical recyclers seeking EFSA food-grade authorization to compete with integrated petrochemical groups. Long-term viability favors molecular purification technology developers over mechanical sorting scale operators. Monitor EFSA novel recycling process approval timelines as inflection indicator for authorized capacity valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| EFSA Food-Grade Authorization Investment | Unlocks direct beverage bottler procurement previously reserved for virgin resin specifications. |
| Chemical Recycling Technology Deployment | Enables infinite recyclability without viscosity loss constraints plaguing mechanical reprocessing. |
| Central and Eastern European Greenfield Expansion | Captures underexploited bale flows from Poland, Romania and Hungary deposit scheme growth. |
| Pharmaceutical-Grade PETG Capacity Addition | Commands substantial premiums from Swiss medical device and French cosmetic packaging customers. |
| Backward Integration into Purified Terephthalic Acid | Insulates margin structures from paraxylene price volatility transmitted through non-integrated converters. |
Research Methodology
Initial hypotheses were tested against primary input from resin plant managers, beverage bottler procurement leads, recycling technology developers and EFSA regulatory affairs specialists and refined through secondary validation. Customs and trade data, Cefic industry reports, SEC 10-K filings from listed petrochemical groups, and national packaging ordinance implementation records provided foundational benchmarks. Bottom-up capacity assessments triangulated against top-down demand modeling across beverage, pharmaceutical and textile end-uses.
Variance decomposition across product type, application grade, end-use industry and regional production hub dimensions structured the analytical framework. CAGRs were derived from segmented volume trajectories calibrated to EFSA authorization timelines and deposit-return scheme expansion schedules. Monoethylene glycol feedstock cost curves and post-consumer bale collection rate assumptions informed price elasticity modeling throughout the projection horizon.
Forecasts assume regulatory continuity in EU Green Deal packaging waste directives and REACH chemical compliance frameworks; material policy shifts would require re-modeling. Recalibration cycles align with EFSA novel recycling process approvals and national deposit-return scheme implementation milestones.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plastic Packaging
Poland Plastic Packaging Tubes Market
Plastic Packaging
Plastic Bottles and Containers Market
Plastic Packaging
Banding Stretch Film Market
Plastic Packaging
Advanced-Recycled Polyethylene for E-Commerce Packaging Market
Plastic Packaging
PCR Bottles Market
Plastic Packaging
Vacuum Forming Plastic Market
Plastic Packaging
Low Density Polyethylene (LDPE) Packaging Market
Plastic Packaging
South Africa Plastic Bottles Market
Plastic Packaging
Plastic Films Market
Plastic Packaging
Global Plastic Container Market
Plastic Packaging
United Arab Emirates Plastic Bottles Market
Plastic Packaging
Global Molded Plastic Packaging Market
Plastic Packaging
UVI Stretch Films Market
Plastic Packaging
Middle East and Africa Single-Use Plastic Packaging Market
Plastic Packaging
Europe BPA Free Plastic Market
Plastic Packaging
Japan Plastic Bottles Market