
 United States Plastic Bottles Market | 2026-2036
United States Plastic Bottles Market Size, Share, and Industry Trends Forecast 2026-2036
United States Plastic Bottles Market Insights
Domestic blow-molding capacity in the Ohio River Valley is realigning toward food-grade recycled PET output. Graham Packaging Co Inc. leverages vertical integration across preform and bottle manufacturing to secure supply chain control for beverage clients. Plastipak Holdings Inc. anchors its position through proprietary barrier coating technology that extends shelf life for sensitive contents. Berry Global Inc. competes by sustaining one of the broadest geographic manufacturing footprints among North American rigid packaging producers.
Plastic bottles are hollow containers formed through extrusion or injection blow-molding of thermoplastic resins, typically ranging from 10ml to 20L in capacity, with wall thickness calibrated to internal pressure and barrier requirements. Their primary purpose is to store, protect, and dispense liquid, semi-solid, or granular products across consumer and industrial supply chains. Polyethylene Terephthalate dominates beverage applications due to its clarity, recyclability, and oxygen barrier properties, while High-Density Polyethylene leads in household and industrial chemical containment where chemical resistance outweighs aesthetic demands. The 500ml-1L capacity bracket captures the largest volume share as single-serve beverage formats and personal care SKUs consolidate around this standard.
The FDA governs food-contact and pharmaceutical packaging materials through 21 CFR standards that dictate resin purity and additive migration limits, while the EPA administers recycled content and waste management rules under the National Recycling Strategy and emerging state-level extended producer responsibility laws. OSHA workplace exposure limits for volatile organic compounds during resin processing shape plant ventilation and automation investments. Stakeholders must monitor how California's recycled content mandates and pending federal packaging legislation will alter resin qualification protocols and capital allocation timelines.
Market Dynamics
Extended producer responsibility mandates in California and New Jersey are compressing virgin resin demand while redirecting capital toward food-grade recycling infrastructure. State-level recycled content floors are forcing blow-molders to requalify supply chains under tighter FDA migration limits.
Growth Catalysts
- California SB 54 mandates:Beverage bottlers must source 50% recycled content by 2030, pulling post-consumer PET supply chains into compliance readiness.
- Pharmaceutical serialization:Blow-molders serving sterile drug delivery in North Carolina are retrofitting lines for track-and-trace compliance under FDA 21 CFR.
- Lightweighting technology:Preform design software and barrier coatings are cutting resin intensity per bottle without sacrificing shelf-life performance.
Market Restraints
- Recycled PET supply scarcity:Collection infrastructure gaps in the Ohio River Valley limit food-grade flake availability for beverage requalification.
- Propylene feedstock volatility:HDPE resin pricing tracks natural gas liquid differentials, compressing margin predictability for household chemical bottlers.
- Multi-layer barrier complexity:Oxygen-scavenging coextrusions complicate mechanical recycling streams, creating regulatory friction under EPA sorting guidelines.
Strategic Opportunities
- Texas chemical recycling clusters:Pyrolysis partnerships near Houston offer molecular recycling pathways for contaminated PET waste streams.
- Direct-to-consumer refill formats:Concentrate and tablet packaging in sub-100ml bottles bypasses traditional retail distribution economics.
- Biopharma cold-chain expansion:Blow-molders with validated sterile barrier expertise can capture vaccine vial and diagnostic reagent demand.
Industry Challenges
- Food-contact requalification timelines:FDA Letters of No Objection for novel recycled content sources stretch 18-24 months, freezing procurement decisions.
- Automation retrofit costs:Vision inspection and robotic handling upgrades for thin-wall lightweight bottles demand capital commitments that mid-tier molders struggle to finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Plastic Bottles Market |
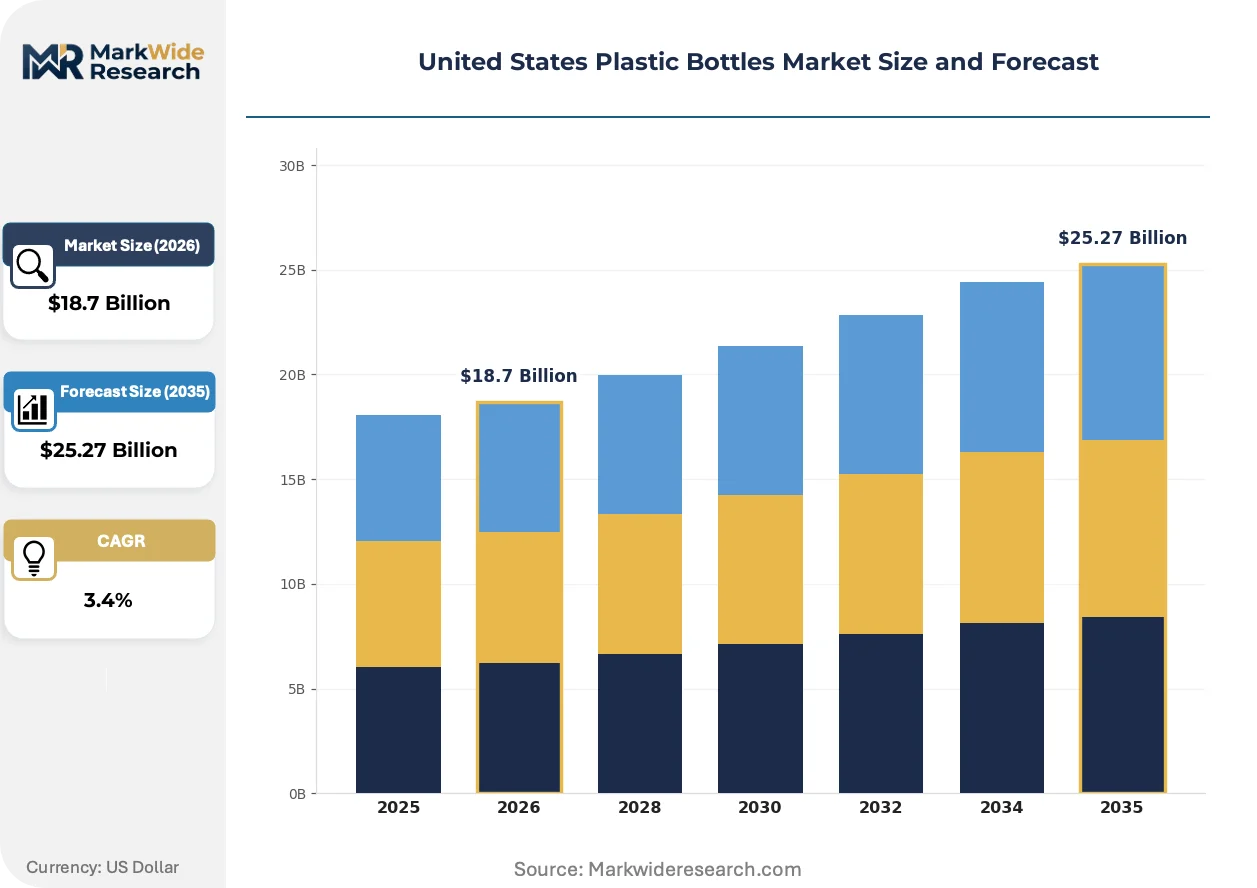
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $25.27 Billion |
| CAGR (2026 – 2036) | 3.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Polyethylene Terephthalate, High-Density Polyethylene, Polypropylene, Others Application: Food & Beverage, Personal Care, Household Products, Pharmaceuticals Capacity: Below 250ml, 250ml-500ml, 500ml-1L, Above 1L Closure Type: Screw Cap, Flip Top, Pump Dispenser, Others |
| Companies Covered | Graham Packaging Co Inc., Plastipak Holdings Inc., Berry Global Inc., Amcor Group GmbH, ALPLA Group, Comar LLC, Loews Corp, Silgan Plastics, Alpha Packaging Holdings Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Plastic Bottles Market Trends and Innovations
Digital printing and smart labeling are collapsing minimum order quantities while enabling SKU proliferation. These technologies are compressing the traditional trade-off between customization economics and production scale.
Digital sleeve labeling with full-body shrink coverage is overtaking pressure-sensitive adhesive labels in premium beverage segments. Craft distillers and functional water brands are adopting this technology at 20-30% annual clip. The shift is overtaking conventional label converters' regional monopoly on short-run decoration, fragmenting supplier power.
EPA's National Recycling Strategy and pending federal packaging legislation are tightening resin traceability requirements. Blow-molders must now document chain-of-custody from bale to pellet for food-contact applications. Pharmaceutical packaging corridors in New Jersey are responding fastest, deploying blockchain-enabled batch records ahead of enforcement timelines.
Retailers are consolidating private-label bottled water procurement through direct supplier agreements, bypassing traditional beverage distributor networks. Walmart and Target are negotiating multi-year volume commitments with blow-molders in Texas and California. This concentration is most visible in the 500ml-1L single-serve bracket, where shelf-space velocity determines contract allocation.
United States Plastic Bottles Market Segmentation
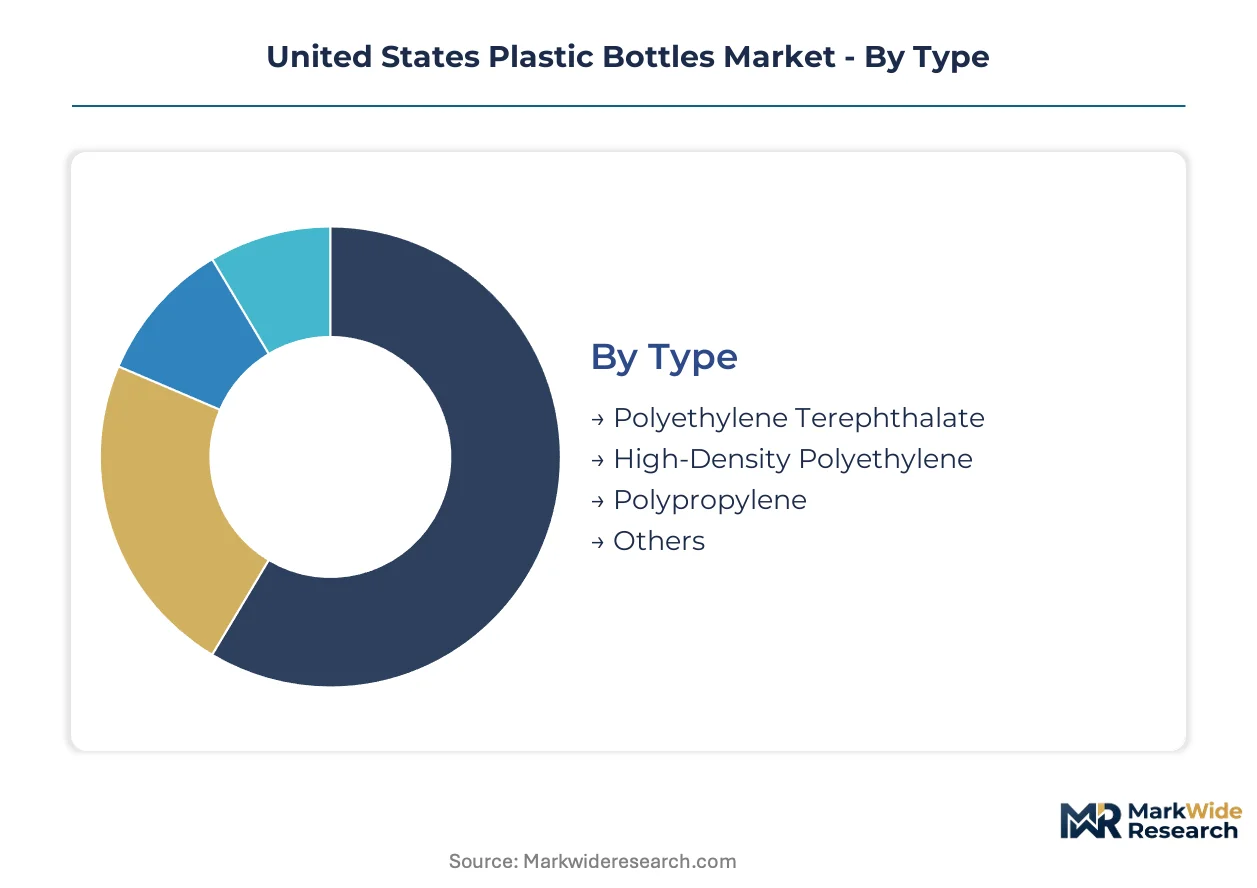
Resin selection and capacity calibration in the United States plastic bottles market determine barrier performance, regulatory compliance, and manufacturing economics. Blow-molders configure production lines around specific polymer-process combinations that align with end-use sterilization requirements and state-level recycled content mandates.
Type:
Polymer crystallinity and barrier architecture separate resin grades across food-contact, pharmaceutical, and industrial chemical applications.
- Polyethylene Terephthalate:Amorphous-to-crystalline ratio engineered for clarity and oxygen barrier delivers shelf-stable beverage packaging. California bottlers under SB 54 mandates are requalifying supply chains for 50% recycled content thresholds, pulling post-consumer flake through FDA Letters of No Objection protocols.
- High-Density Polyethylene:Linear polymer structure with high tensile strength resists chemical permeation in household cleaner and industrial containment. Ohio River Valley blow-molders serving Midwest chemical formulators face propylene feedstock volatility tied to natural gas liquid differentials.
- Polypropylene:Semi-crystalline thermoplastic with elevated heat deflection temperature suits hot-fill and retort applications. FDA migration limits constrain additive packages for food-contact grades.
- Others:Polycarbonate and bio-based alternatives address niche pharmaceutical and premium cosmetic segments where impact resistance or sustainability credentials command specification premiums.
Polyethylene Terephthalate leads on scale; Polypropylene leads on momentum as hot-fill dairy and ready-to-drink coffee applications expand.
Application:
End-use sterilization standards and distribution channel velocity dictate wall thickness, barrier layering, and closure integration.
- Food & Beverage:Oxygen-scavenging coextrusions and UV barriers protect shelf-stable juices and functional waters. Texas bottlers are consolidating procurement through direct retailer agreements with Walmart and Target, bypassing traditional distributor networks.
- Personal Care:Visual clarity and tactile surface finishes drive differentiation in shampoo and lotion packaging. Digital sleeve labeling enables 20-30% annual SKU proliferation for craft and premium brands.
- Household Products:Chemical resistance and child-resistant closure compatibility dominate specification sheets. HDPE resin intensity per bottle is declining through lightweighting preform design.
- Pharmaceuticals:Sterile barrier validation and track-and-trace serialization under FDA 21 CFR govern blow-molding protocols. North Carolina and New Jersey corridors are retrofitting lines for biopharma cold-chain expansion.
Food & Beverage commands volume concentration; Pharmaceuticals is climbing the fastest on per-unit value and regulatory compliance premiums.
Capacity:
Fill-line throughput and retail shelf-space economics calibrate optimal bottle volume brackets.
- Below 250ml:Concentrate, tablet, and travel-size formats for direct-to-consumer subscription channels. Sub-100ml blow-molding bypasses traditional retail distribution economics through e-commerce fulfillment.
- 250ml-500ml:Trial-size personal care and pharmaceutical unit-dose applications. New Jersey sterile drug delivery bottlers favor this bracket for diagnostic reagent packaging.
- 500ml-1L:Single-serve beverage standard and personal care family-size consolidation. This bracket captures shelf-space velocity determinants at Walmart and Target private-label negotiations.
- Above 1L:Economy-size household chemical and bulk beverage formats. Lightweighting technology reduces resin intensity most aggressively in this bracket where wall thickness tolerances widen.
500ml-1L dominates contract allocation; Below 250ml is gaining share fastest through e-commerce subscription model adoption.
Closure Type:
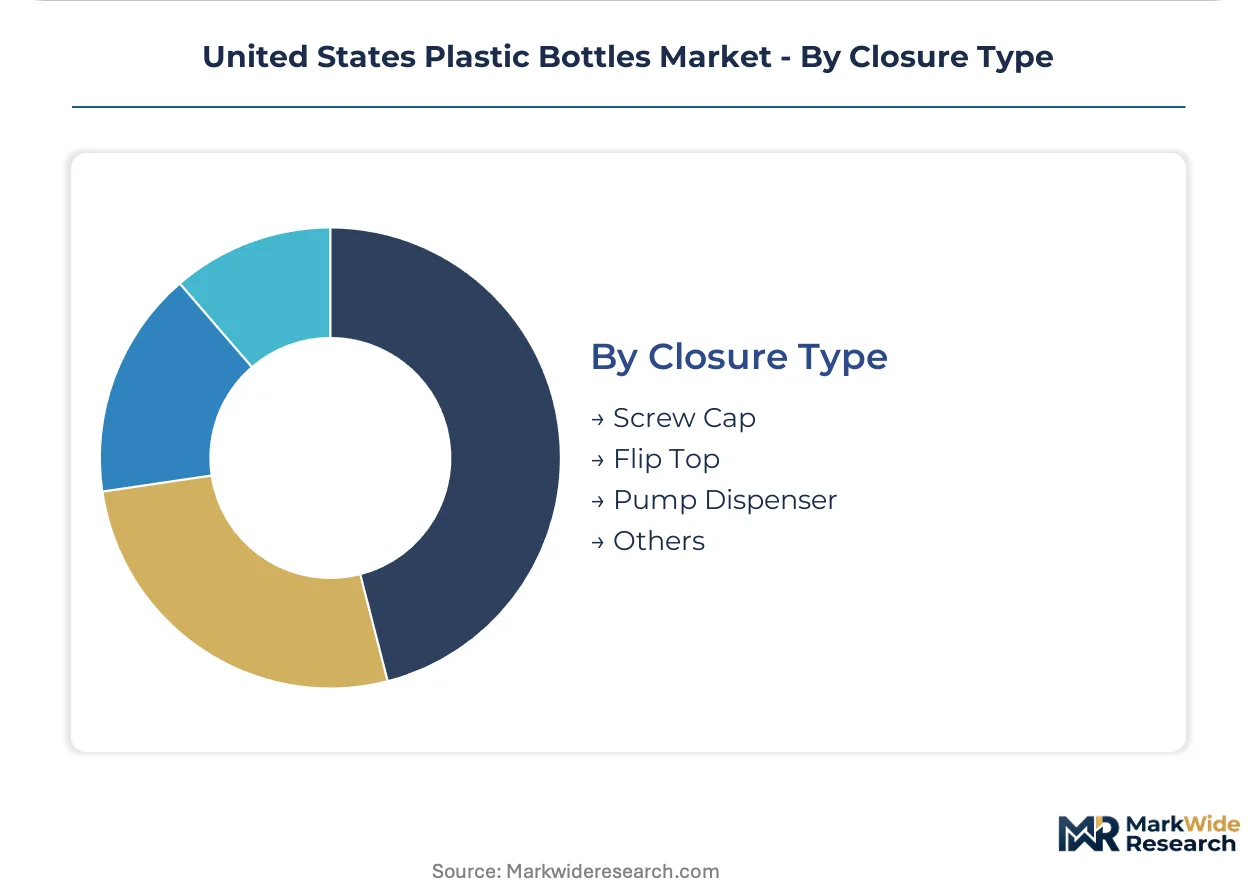
Dispensing mechanism selection aligns with product viscosity, usage occasion, and child-safety requirements.
- Screw Cap:Threaded polyethylene or polypropylene closure for carbonated beverage pressure retention and resealability. California bottlers are integrating tethered cap designs to meet emerging extended producer responsibility sorting guidelines.
- Flip Top:Hinged polypropylene lid for single-hand dispensing in on-the-go beverage and condiment applications. Sports nutrition and functional water brands are specifying this format at elevated rates.
- Pump Dispenser:Dip tube and piston mechanism for viscous lotion, soap, and sanitizer products. Personal care brands in the 250ml-500ml bracket favor pump integration for premium positioning.
- Others:Trigger sprayers, disc tops, and custom dispensing systems for industrial and specialty chemical containment. OSHA workplace exposure limits shape ventilation requirements during closure assembly automation.
Screw Cap maintains installed base dominance; Pump Dispenser shows steepest expansion trajectory through personal care premiumization and hygiene product demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California bottlers operate under stricter recycled content mandates than Texas producers, yet both states anchor the national supply chain for beverage-grade PET. Ohio River Valley molders face distinct feedstock pressures compared to Southeast pharmaceutical corridors.
California
Beverage bottlers under SB 54 mandates must source 50% recycled content by 2030, compressing virgin resin procurement timelines. EPA recycled content rules intersect with state sorting guidelines to requalify supply chains. Los Angeles and Central Valley blow-molding clusters are retrofitting lines for food-grade flake processing.
Texas
Pyrolysis partnerships near Houston offer molecular recycling pathways for contaminated PET waste streams. State environmental regulators coordinate with federal EPA frameworks on chemical recycling permitting. Gulf Coast resin producers supply blow-molders serving Walmart and Target direct procurement agreements.
Ohio River Valley
Domestic blow-molding capacity realigns toward food-grade recycled PET output as collection infrastructure gaps limit flake availability. OSHA workplace exposure limits shape automation investments across Kentucky and Ohio plants. Cincinnati and Louisville corridors serve Midwest household chemical formulators with HDPE containment solutions.
New Jersey
Pharmaceutical serialization requirements under FDA 21 CFR drive track-and-trace compliance retrofits for sterile drug delivery. State-level extended producer responsibility laws compress packaging waste timelines. Northern New Jersey blow-molders deploy blockchain-enabled batch records ahead of enforcement dates.
North Carolina
Biopharma cold-chain expansion creates demand for validated sterile barrier expertise in vaccine vial and diagnostic reagent packaging. FDA migration limits constrain additive packages for food-contact adjacent production. Research Triangle Park and Charlotte corridors attract blow-molders retrofitting lines for pharmaceutical-grade output.
United States Plastic Bottles Market Competitive Landscape
Ohio River Valley producers anchor one tier; Gulf Coast specialists hold differentiated positions through chemical recycling proximity. The vendor base splits between integrated resin-to-bottle operators and independent molders sourcing flake from third-party reclaimers. Three archetypes dominate: vertically integrated packaging conglomerates, regional specialists with barrier coating expertise, and mid-tier molders serving private-label retail contracts. Capacity expansion and supply chain requalification for recycled content compliance represent the dominant competitive moves.
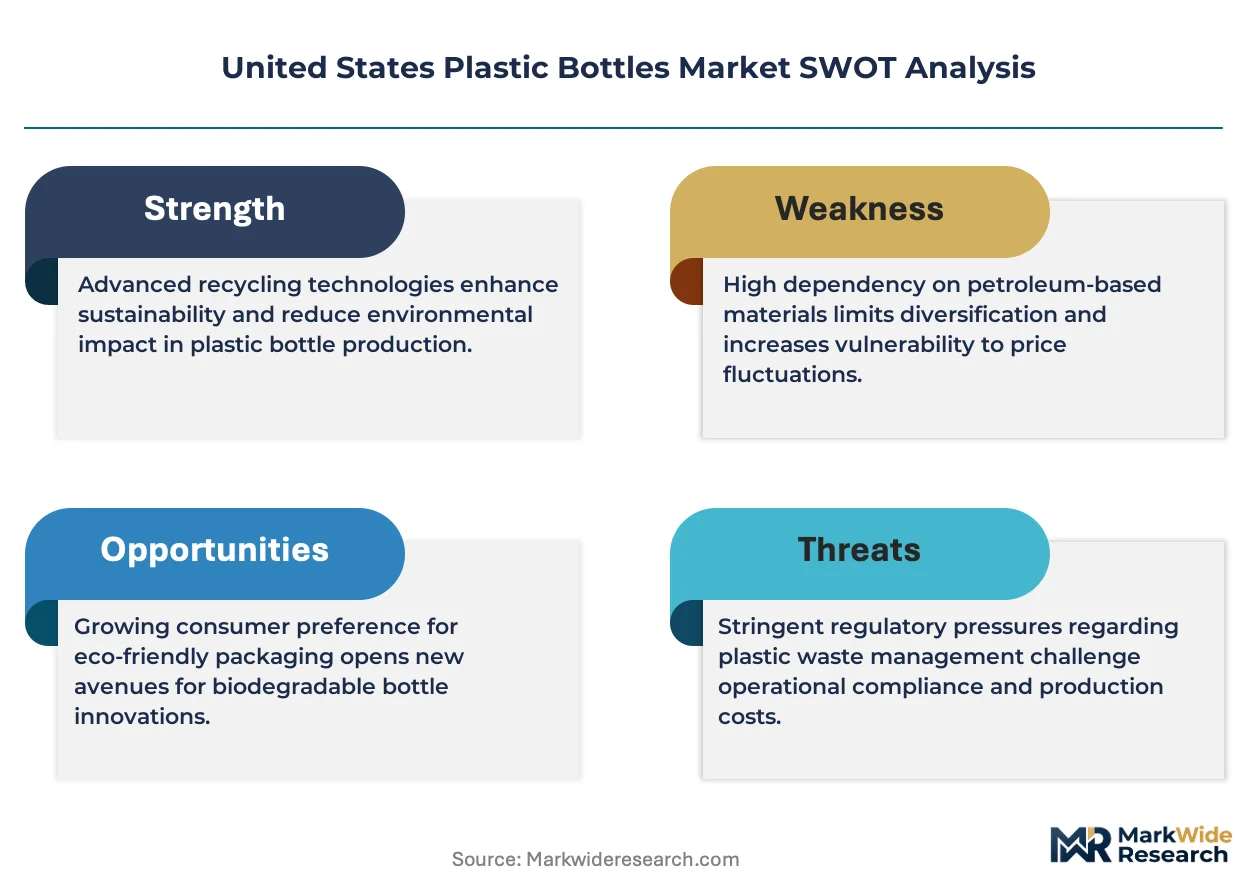
Among North American packaging conglomerates, Graham Packaging Co Inc., Plastipak Holdings Inc., and Berry Global Inc. exemplify distinct strategic positions. Graham Packaging occupies a position within vertically integrated preform-to-bottle manufacturing. Plastipak Holdings represents specialists with proprietary technology positions. Berry Global exemplifies geographic scale advantages across dispersed manufacturing footprints. These three entities anchor the competitive structure through which state-level mandates and retailer procurement consolidation flow.
| Leading Market Players |
|---|
| Graham Packaging Co Inc. |
| Plastipak Holdings Inc. |
| Berry Global Inc. |
| Amcor Group GmbH |
| ALPLA Group |
| Comar LLC |
| Loews Corp |
| Silgan Plastics |
| Alpha Packaging Holdings Inc. |
| Others |
Pricing and Supply Chain Analysis
Resin price indices for PET and HDPE cascade through blow-molding supply chains into three distinct pricing tiers calibrated by recycled content certification and barrier performance specifications. California's SB 54 mandates compress virgin resin premiums while elevating food-grade recycled flake valuations, redirecting procurement economics toward circular supply chains.
Pricing Analysis
Distributor margin compression in traditional beverage supply chains is accelerating direct-to-retailer contract negotiations. Three-tier pricing structure across premium, standard, and economy levels separates pharmaceutical-grade sterile barriers from commodity beverage containers and private-label household chemical formats. Cost compression in standard-tier beverage packaging is intensifying because Walmart and Target procurement consolidation extracts volume discounts. Private-label retail buyers exhibit highest price sensitivity; pharmaceutical serialization compliance commands lowest sensitivity due to FDA validation requirements.
Supply Chain Analysis
Regional distribution centers in Texas, California, and Ohio anchor hub-and-spoke patterns serving beverage bottlers and household chemical formulators. Resin supply draws from Gulf Coast petrochemical clusters, Midwest recycling reclaimers, and Southeast pharmaceutical-grade compounders. Single-source vulnerability concentrates in food-grade recycled PET flake where Ohio River Valley collection gaps limit qualified supply. Distribution runs through direct retailer agreements bypassing traditional beverage distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States plastic bottles market represents a late-cycle quality story as pharmaceutical serialization and cold-chain validation shift demand toward premium sterile barrier specifications.
For Market Incumbents: Deepen backward integration into preform manufacturing and food-grade recycling infrastructure to defend margin position against resin price volatility and California recycled content mandates. Secure FDA Letters of No Objection for novel flake sources before procurement freezes tighten qualified supplier pools. Prioritize automation retrofits for lightweight bottle inspection to offset labor cost pressure in Ohio River Valley plants. For New Entrants and Emerging Players: The gap between premium pharmaceutical-grade barriers and economy private-label beverage containers offers white-space entry through mid-tier personal care and functional water segments. Target direct-to-consumer concentrate formats in sub-100ml bottles where e-commerce subscription economics bypass retail shelf-space competition. Pursue barrier coating technology licensing as the fastest qualification pathway against incumbent proprietary positions. For Investors and Strategic Acquirers: Asymmetric upside sits with regional specialists possessing validated sterile barrier expertise and pharmaceutical serialization capabilities. Five-to-ten year viability favors molders retrofitting lines for biopharma cold-chain expansion over commodity beverage exposure. Monitor FDA migration limit enforcement timelines as the critical inflection signal for recycled content requalification capital deployment.| Strategic Initiative | Industry Significance |
|---|---|
| Food-Grade Recycling Infrastructure Investment | California SB 54 compliance secures beverage bottler contracts under 50% recycled content mandates. |
| Pharmaceutical Serialization Line Retrofit | FDA 21 CFR track-and-trace validation captures sterile drug delivery demand in North Carolina corridors. |
| Barrier Coating Technology Licensing | Proprietary oxygen-scavenging formulations extend shelf life for sensitive functional water brands. |
| Direct-to-Consumer Format Development | Sub-100ml concentrate bottles bypass traditional retail distribution economics through e-commerce channels. |
| Chemical Recycling Partnership Formation | Pyrolysis alliances near Houston unlock molecular recycling pathways for contaminated PET waste streams. |
Research Methodology
Bottom-up beverage and pharmaceutical packaging modeling reconciled against top-down resin production and recycling capacity tracking forms the analytical core of this study. Primary interviews with blow-molding plant managers, beverage procurement executives, pharmaceutical packaging engineers, and FDA regulatory consultants combined with secondary validation from EPA National Recycling Strategy filings, state extended producer responsibility legislation, ACC resin production data, and SEC 10-K disclosures from listed packaging conglomerates. Triangulation across supply-side capacity announcements and demand-side contract awards calibrated volume estimates.
Historical trendline analysis of PET and HDPE resin pricing, blow-molding capacity utilization, and recycled content qualification timelines anchored projection frameworks across the analysis window. Segmentation dimensions modeled include resin type, application end-use, capacity bracket, closure mechanism, and regional regulatory cluster. CAGRs derived from weighted average of capacity expansion announcements, recycled content mandate phase-in schedules, and pharmaceutical serialization compliance deadlines. Industry-specific inputs encompassed FDA Letter of No Objection processing timelines and retailer private-label procurement consolidation patterns.
Caveats apply where recycled PET collection infrastructure buildout delays, pharmaceutical serialization enforcement timeline shifts, or pyrolysis permitting accelerations could materially shift the outlook. Forecasts reflect documented assumptions about resin price volatility, regulatory phase-in compliance rates, and automation retrofit capital availability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plastic Packaging
Global Plastic Tarpaulin Market
Plastic Packaging
United States PET Packaging Market
Plastic Packaging
Plastic Bottles Market
Plastic Packaging
UVI Stretch Films Market
Plastic Packaging
Plastic Carboy Market
Plastic Packaging
PET Preforms Market
Plastic Packaging
Canada Plastic Packaging Market
Plastic Packaging
Plastic T-Shirt Bags Market
Plastic Packaging
Plastic Tumblers Market
Plastic Packaging
PCR Bottles Market
Plastic Packaging
South Africa Plastic Packaging Films Market
Plastic Packaging
Corrugated Plastic Trays Market
Plastic Packaging
Blow Moulded Plastic Packaging Market
Plastic Packaging
Spain Plastic Bottles Market
Plastic Packaging
Plant-Based Plastic Packaging Market
Plastic Packaging
Brazil Plastic Packaging Market