
 Global Molded Plastic Packaging Market | 2026-2036
Global Molded Plastic Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Global Molded Plastic Packaging Market Foresight
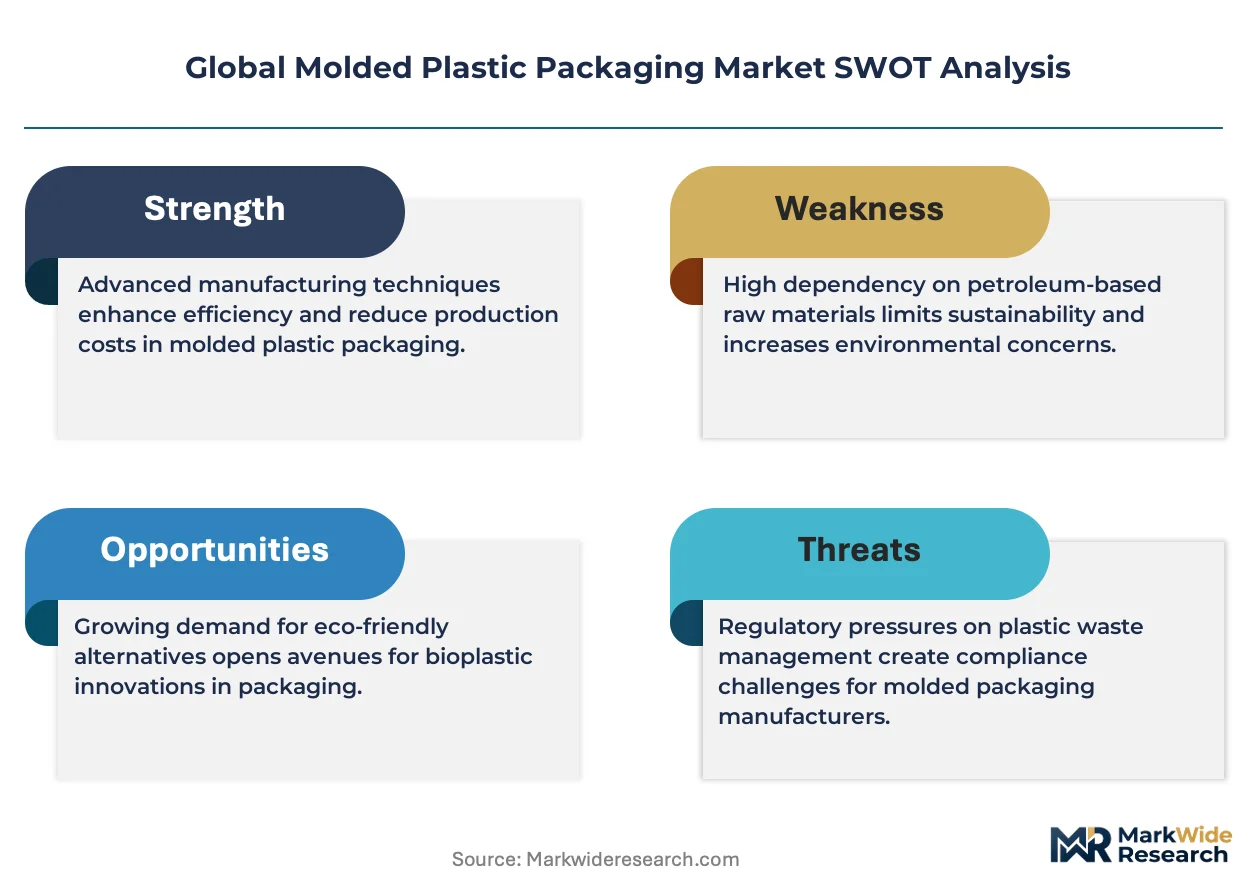
Asset-light leasing models for injection and blow-molding equipment is rewriting capital requirements for mid-scale entrants, eroding the historical scale advantage of fully owned plant networks. Amcor leverages its global preform library to sustain rapid format turnover for pharmaceutical clients. Berry Global anchors North American food tray supply through backward integration into recycled polyethylene flake processing. Greiner Packaging differentiates via in-house tooling design that compresses prototype-to-production cycles for custom clamshell programs.
Molded plastic packaging comprises thermoformed or injection-molded polymer structures engineered to precise dimensional tolerances, typically wall-thickness ranges of 0.25–2.0 mm, serving containment, protection, and unit-dose dispensing functions across supply chains. Polypropylene formats lead rigid container volumes due to chemical resistance and microwave compatibility, while polylactic acid represents the fastest-expanding material category as brand owners convert catalogues to bio-based feedstocks under retailer sustainability scorecards. Blister packs command concentrated margin pools in pharmaceutical applications where child-resistance certification and barrier-layer coextrusion create qualification barriers for new suppliers.
The FDA enforces strict extractables and leachables testing for pharmaceutical contact materials, while the EU Green Deal's packaging and packaging waste regulation mandates minimum recycled content thresholds that reshape virgin resin procurement strategies. India's BIS certification requirements for food-contact plastics add a secondary compliance layer for exporters targeting its domestic retail modernization. Stakeholders must monitor how rapidly evolving extended producer responsibility frameworks in the European Union and diverging state-level recycling infrastructure investments across the United States reshape the cost structure of post-consumer resin qualification.
Market Dynamics
Pharmaceutical cold-chain logistics is compressing qualification timelines for high-barrier molded formats, forcing converters to synchronize material validation with temperature-sensitive distribution networks. EU Green Deal mandates and FDA extractables testing are simultaneously tightening compliance windows, reshaping how resin suppliers and molders coordinate specification lock.
Growth Catalysts
- EU Green Deal packaging waste regulation:Minimum recycled content thresholds are pulling post-consumer polyethylene and polypropylene into food-contact grades, expanding qualified supply pools for tray and container producers.
- India pharmaceutical exports:BIS-certified molded vials and closures are capturing share in generic drug cold-chain shipments to Africa and Southeast Asia, driving domestic blow-molding capacity expansion.
- Barrier-layer coextrusion:EVOH and nylon interlayers in pharmaceutical blisters are extending product shelf life, creating specification premiums that offset raw material cost volatility.
Market Restraints
- Post-consumer resin qualification costs:FDA extractables and leachables testing for recycled-content pharmaceutical contact materials adds validation cycles that stretch 18-24 months.
- Tooling concentration in China and Germany:High-cavity injection mold fabrication relies on a narrow supplier base, creating lead time vulnerability for custom clamshell and tray programs.
- Polylactic acid performance ceiling:PLA's moisture sensitivity and narrow processing window limit its penetration in hot-fill and retort applications despite brand owner sustainability commitments.
Strategic Opportunities
- Asset-light equipment leasing:Mid-scale entrants are accessing blow-molding and thermoforming capacity without plant ownership, eroding historical scale advantages of integrated resin-to-package producers.
- Indonesia domestic FMCG modernization:Modern trade expansion in Jakarta and Surabaya is creating demand for unit-dose blister and strip packs previously supplied by informal recycling networks.
- Digital watermark sorting integration:Invisible marker technologies are converging with mechanical recycling infrastructure to enable food-grade polypropylene recovery at scale.
Industry Challenges
- Multi-layer delamination in mechanical recycling:Barrier coextrusions containing EVOH, tie layers, and incompatible polymers complicate flake purification, forcing investment in solvent-based or chemical recycling pathways.
- Tooling engineer scarcity:Design-for-recyclability mandates require mold flow simulation expertise that outpaces vocational training pipeline output in North American and European manufacturing clusters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Molded Plastic Packaging Market |
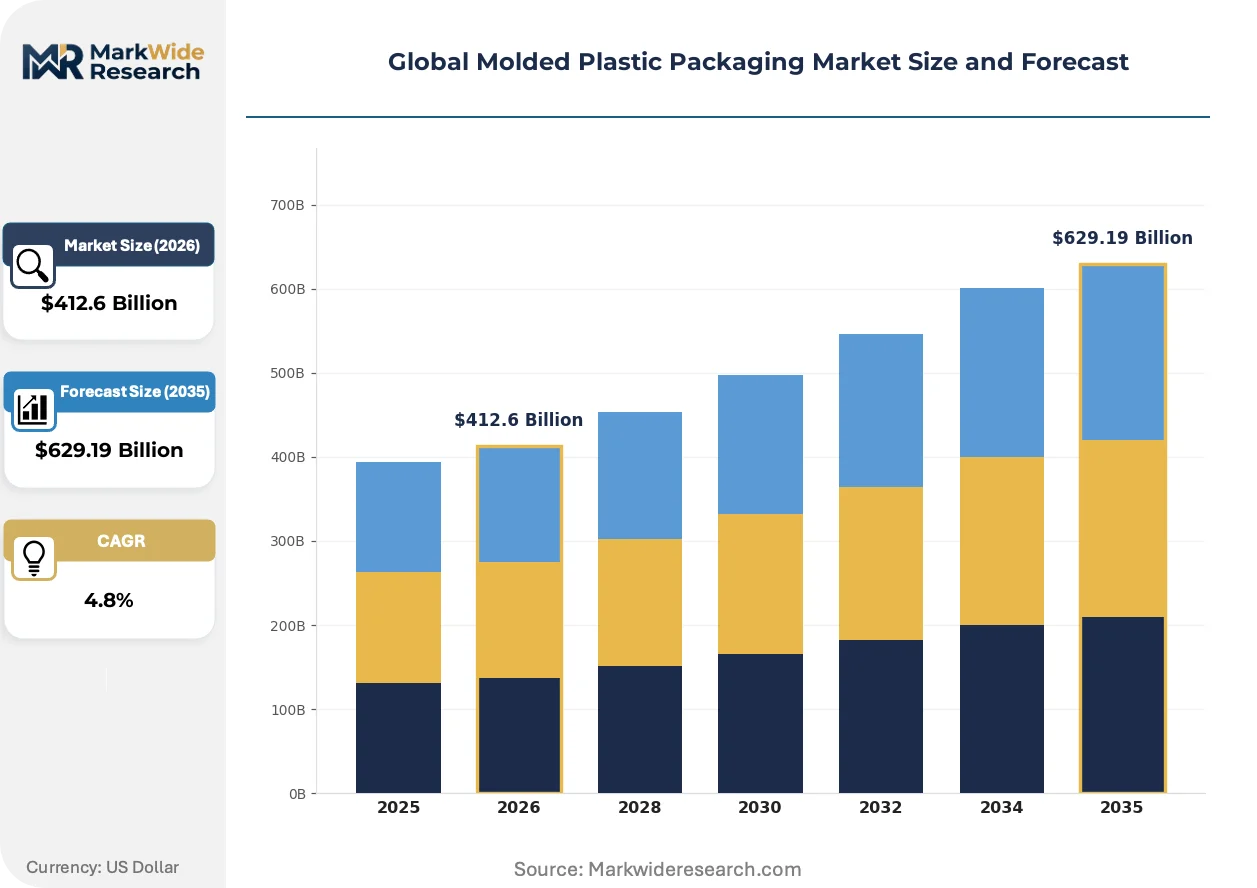
| Market Size in 2026 | $412.6 Billion |
| Market Size in 2035 | $629.19 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blister Packs, Clamshells, Trays, Containers, Bottles, Caps Material: Polyethylene Terephthalate, Polypropylene, High-Density Polyethylene, Polystyrene, Polyvinyl Chloride, Polylactic Acid Application: Food & Beverage, Personal Care, Household Chemicals, Pharmaceuticals, Electronics, Agriculture Distribution Channel: Direct Sales, Retail Chains, E-Commerce Platforms, Wholesalers, Distributors, Institutional Buyers |
| Companies Covered | Amcor, Berry Global, Sealed Air, Sonoco Products, Mondi Group, Plastipak, Greiner Packaging, ALPLA, Constantia Flexibles, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Molded Plastic Packaging Market Shifts & Advancements
Material science and regulatory compliance are fusing into a single competitive axis where bio-based feedstocks, digital traceability, and circular infrastructure investments determine supplier viability. Converters are repositioning around closed-loop collection partnerships rather than virgin resin procurement scale.
Barrier film integration is hybridizing conventional injection-molded containers with in-mold labeling and internal laminate sleeves. Pharmaceutical contract packagers in Switzerland and Singapore are qualifying these hybrid structures for moisture-sensitive solid dose products. The technology is compressing the traditional separation between primary container and secondary blister functions.
REACH SVHC disclosure requirements and the EU Green Deal's packaging waste regulation are forcing resin suppliers to document full polymer chain of custody. Compounders serving food-contact applications are investing in mass balance certification infrastructure to access premium pricing in German and French retail channels. The compliance burden is concentrating procurement relationships around suppliers with established recycling partnerships.
Brand owner sustainability scorecards are rotating procurement criteria toward verified recycled content and carbon footprint data. European and North American consumer health companies are unbundling packaging specification from historical resin supplier relationships, creating entry points for regional recyclers with FDA food-contact letters of no objection. The shift is most visible in personal care and nutritional supplement segments where packaging differentiation commands shelf price premiums.
Global Molded Plastic Packaging Market Segmentation
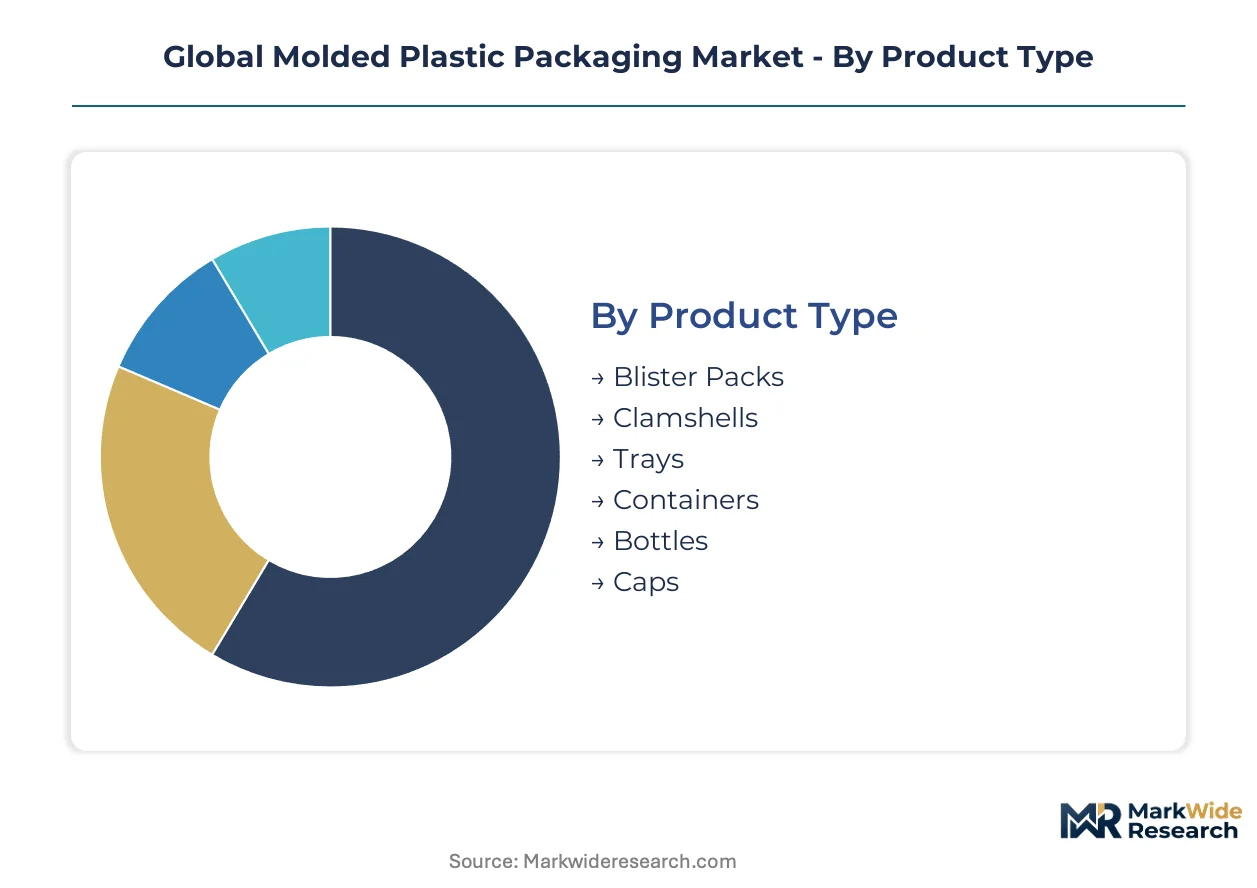
Segmentation in molded plastic packaging reveals how specification requirements fragment across temperature sensitivity, barrier performance, and regulatory compliance tiers. Material selection and format geometry diverge sharply between pharmaceutical cold-chain applications and ambient food retail, creating distinct margin architectures within each slice.
Product Type:
Volume concentration tracks directly to barrier complexity and tooling amortization cycles across pharmaceutical and food-contact applications.
- Blister Packs:Thermoformed or cold-formed cavities with lidding foil heat-sealed to form unit-dose enclosures. Pharmaceutical serialization mandates in the European Union and FDA track-and-trace requirements are compressing qualification timelines for high-barrier formats with EVOH interlayers.
- Clamshells:Hinged two-piece structures thermoformed from clear PET or RPET, engineered for retail theft deterrence and shelf visibility. Demand clusters around fresh produce and consumer electronics retail in Germany and the United States where tamper-evident features command specification premiums.
- Trays:Shallow thermoformed platforms for food service and medical kit organization.
- Containers:Injection-molded or thermoformed vessels with defined rim geometries for lidding compatibility.
- Bottles:Blow-molded or injection-stretch-blown hollow bodies for liquid containment across personal care and pharmaceutical segments.
- Caps:Threaded or snap-fit closures with induction seal liners, child-resistance mechanisms, or dispensing features.
Blister packs command the established base. The steepest expansion runs through clamshells as retail theft deterrence specifications tighten across European and North American mass merchandisers.
Material:
Cost tier and performance ceiling split procurement decisions between commodity resins, engineering polymers, and emerging bio-based feedstocks.
- Polyethylene Terephthalate:Clear, oriented, or amorphous polyester with excellent barrier to oxygen and carbon dioxide. Cold-chain pharmaceutical vials and beverage bottles in Switzerland and Singapore leverage its clarity and FDA food-contact approval density.
- Polypropylene:Semi-crystalline olefin with broad chemical resistance and microwave stability. Food tray and container demand in India and Indonesia concentrates here due to heat tolerance and competitive resin pricing.
- High-Density Polyethylene:Stiff, opaque polyethylene for dairy bottles and industrial pails.
- Polystyrene:Clear or expanded styrenic for low-cost trays and protective packaging.
- Polyvinyl Chloride:Plasticized or rigid vinyl for blister lidding and medical tubing applications.
- Polylactic Acid:Bio-based aliphatic polyester derived from corn starch or sugarcane. Moisture sensitivity constraints limit hot-fill deployment, though compostable food service applications in France and Italy are climbing fastest as retailer sustainability scorecards harden.
Polypropylene anchors volume share across food-contact applications. Polylactic acid is gaining share fastest where composting infrastructure and brand owner carbon commitments align.
Application:
End-use specification intensity determines margin tier, with pharmaceutical and electronics applications demanding dimensional precision and extractables documentation that commodity food formats do not require.
- Food & Beverage:Tray, container, and bottle formats for fresh, frozen, and shelf-stable goods. India's retail modernization and cold-chain infrastructure buildout are pulling molded PP and PET into dairy and ready-meal segments previously served by informal packaging networks.
- Personal Care:Dispensing bottles, jars, and tubes for cosmetics and hygiene products. Premium positioning in German and French retail channels is forcing mass balance certification and post-consumer recycled content verification.
- Household Chemicals:Trigger-spray bottles and pails for cleaning and automotive products.
- Pharmaceuticals:Blister packs, vials, and closures with child-resistance and barrier-layer specifications. FDA extractables testing and EU MDR compliance are consolidating supply relationships around converters with validated cleanroom capacity.
- Electronics:Antistatic trays and clamshells for component protection.
- Agriculture:Nursery pots, seedling trays, and pesticide containers.
Food and beverage captures the volume base. Pharmaceuticals is expanding most quickly as temperature-sensitive biologics proliferation multiplies barrier-format qualification programs.
Distribution Channel:
Customer scale and specification authority fragment procurement patterns, with institutional buyers and direct pharmaceutical contracts operating on qualification timelines wholly distinct from spot wholesale purchasing.
- Direct Sales:Converter-to-brand-owner relationships with locked specifications and volume commitments. Pharmaceutical and personal care multinationals in Switzerland and the United States leverage direct channels to synchronize packaging validation with product launch timelines.
- Retail Chains:Centralized procurement for private-label food and household products. German and French supermarket sustainability scorecards are forcing recycled content documentation and digital watermark traceability into molded tray specifications.
- E-Commerce Platforms:Direct-to-consumer fulfillment requiring damage-resistant formats.
- Wholesalers:Inventory aggregation for small-format retailers and food service.
- Distributors:Regional stock-and-resell operations for industrial and agricultural packaging.
- Institutional Buyers:Hospital systems, contract packagers, and government procurement with mandated compliance documentation.
Direct sales retains the specification-intensive base. E-commerce platforms are climbing fastest as last-mile damage rates force structural redesign of bottle and container geometries.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in Germany and Switzerland runs 15-20% above Indian export benchmarks, reflecting qualification intensity for pharmaceutical-grade formats. This asymmetry fragments procurement relationships between premium cold-chain corridors and volume-driven generic supply.
United States
FDA extractables testing mandates and pharmaceutical serialization requirements drive specification premiums for barrier-layer blister formats. The EPA's evolving framework for chemical recycling pathways shapes post-consumer resin qualification timelines. New Jersey and North Carolina clusters concentrate blow-molding capacity serving contract packagers for temperature-sensitive biologics.
Germany
EU Green Deal recycled content thresholds pull mass balance-certified polyethylene into food tray applications previously dominated by virgin resin. ECHA REACH SVHC disclosure requirements force compounders to document full polymer chain of custody. The Baden-Württemberg tooling corridor anchors high-cavity mold fabrication for pharmaceutical clamshell programs.
India
BIS certification for food-contact plastics and CDSCO pharmaceutical packaging standards compress qualification windows for export-oriented converters. Domestic FMCG retail modernization in Mumbai and Delhi accelerates polypropylene container uptake for dairy and ready-meal segments. Gujarat blow-molding clusters expand capacity to serve generic drug cold-chain shipments to Africa.
China
SAMR food-contact material safety standards and NMPA pharmaceutical packaging regulations tighten compliance documentation for export-oriented molders. Dual carbon goals pressure resin suppliers to verify recycled content claims through third-party audit infrastructure. The Yangtze River Delta concentrates injection-molding capacity serving electronics antistatic tray demand.
Switzerland
Swissmedic pharmaceutical packaging regulations and retailer sustainability scorecards converge to demand verified bio-based content in unit-dose formats. Precision tooling capabilities in the Basel region support rapid prototype-to-production cycles for custom blister geometries. The country's contract packaging sector qualifies hybrid barrier structures for moisture-sensitive solid dose products.
Global Molded Plastic Packaging Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream of specification lock-in, creating a bifurcated structure where global preform libraries compete against regional recyclers with FDA food-contact letters. The vendor base clusters around three archetypes: resin-to-package integrators with captive recycling infrastructure, format-focused converters with in-house tooling design, and asset-light operators leasing molding capacity. Consolidation pressure runs highest among mid-scale European tray producers facing EU Green Deal compliance investments. Dominant competitive moves include backward integration into recycled flake processing and digital watermark traceability partnerships with retail chains.
Within the integrated tier, Amcor exemplifies global preform library scale, while Berry Global anchors North American recycled polyethylene infrastructure. Greiner Packaging occupies a position emphasizing in-house tooling design capabilities for custom clamshell programs. These three represent distinct strategic postures: specification breadth, upstream recycling control, and rapid format iteration respectively.
| Leading Market Players |
|---|
| Amcor |
| Berry Global |
| Sealed Air |
| Sonoco Products |
| Mondi Group |
| Plastipak |
| Greiner Packaging |
| ALPLA |
| Constantia Flexibles |
| Others |
Supply & Pricing Matrix
High-cavity injection mold fabrication concentrates in Germany and China, anchoring margin capture downstream in pharmaceutical blister formats where EVOH coextrusion and child-resistance certification create specification premiums. This upstream tooling bottleneck funnels pricing power toward converters with validated cleanroom capacity and established FDA food-contact letters.
Pricing Analysis
Configured-to-order pricing for custom clamshell and tray programs commands spreads of 40-60% above standard catalog formats. Three-tier pricing structure across premium, standard, and economy levels reflects barrier-layer complexity, with pharmaceutical-grade EVOH interlayers and mass balance-certified bio-based feedstocks anchoring the top tier. Cost compression in commodity food-contact polypropylene is intensifying because Indian and Indonesian converters are expanding blow-molding capacity for domestic FMCG modernization. Brand owners in personal care and nutritional supplements demonstrate lowest price sensitivity, while generic food tray buyers in wholesale channels exhibit highest elasticity.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculus for electronics antistatic tray programs serving Yangtze River Delta injection-molding clusters. Virgin resin procurement draws from Saudi Arabian and US Gulf Coast petrochemical complexes, while post-consumer polyethylene and polypropylene flake processing concentrates in North American and European recycling infrastructure. Single-source vulnerability in high-cavity mold steel and hot-runner systems creates lead time fragility for custom pharmaceutical formats. Distribution runs through direct converter-to-brand-owner relationships for specification-intensive applications, with retail chain centralized procurement handling volume food-contact segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among pharmaceutical multinationals and German retail chains, with sustainability scorecards and serialized compliance requirements consolidating procurement relationships around fewer qualified suppliers.
For Market Incumbents: Harden barrier-layer coextrusion capabilities and cleanroom validation assets against asset-light leasing entrants eroding historical scale advantages. Prioritize backward integration into recycled polyethylene flake processing to secure mass balance certification access for EU Green Deal compliance. Lock in digital watermark traceability partnerships with French and German retail chains before qualification windows close. For New Entrants and Emerging Players: Build out asset-light leasing models for blow-molding and thermoforming capacity serving mid-scale pharmaceutical contract packagers in India and Southeast Asia. Indonesia's domestic FMCG modernization presents the most penetrable geography, with unit-dose blister and strip pack demand outpacing local supply. Lead with rapid prototype-to-production cycles enabled by outsourced tooling partnerships rather than captive mold fabrication. For Investors and Strategic Acquirers: Capital is best deployed toward regional recyclers with FDA food-contact letters of no objection and established retail chain partnerships, as brand owners unbundle packaging specification from historical resin supplier relationships. Long-term viability hinges on circular infrastructure positioning rather than virgin resin procurement scale. Watch for inflection signals in chemical recycling pathway commercialization that could resolve multi-layer delamination constraints in barrier coextrusions.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recycled Flake Processing | Berry Global's captive RPET infrastructure secures mass balance certification for EU retail compliance. |
| Digital Watermark Traceability Partnership | Invisible marker convergence with mechanical recycling enables food-grade polypropylene recovery at German supermarket scale. |
| Asset-Light Equipment Leasing Model | Mid-scale entrants access blow-molding capacity without plant ownership, eroding integrated producer scale advantages. |
| Hybrid Barrier Structure Qualification | Swiss contract packagers validate in-mold labeled containers with internal laminate sleeves for moisture-sensitive solid dose products. |
| Tooling Design Capability Investment | Greiner Packaging's in-house mold flow simulation compresses prototype-to-production cycles for custom clamshell programs. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with pharmaceutical packaging engineers, food-contact regulatory affairs leads, retail chain sustainability procurement managers, and blow-molding plant operations directors. Secondary validation drew from FDA extractables guidance documents, ECHA REACH SVHC disclosure databases, EU Green Deal packaging waste regulation drafts, and Indian BIS certification registries. Bottom-up capacity and demand modeling triangulated against top-down trade flow and resin consumption data.
Calibration anchored volume and value outputs to operating metrics disclosed across the analysis window, with segmentation modeling spanning product type, material grade tier, application intensity, and regional regulatory cluster. CAGRs were derived from slope-intercept trajectory fitting against historical resin price elasticity and converter capacity utilization patterns. Forecast inputs incorporated pharmaceutical cold-chain logistics expansion rates and EU recycled content threshold implementation timelines.
Practitioners should monitor chemical recycling pathway cost curves and extended producer responsibility framework evolution for early signals of post-consumer resin qualification disruption. Forecasts embed assumptions regarding BIS certification harmonization and FDA food-contact letter processing velocity that operating reality may revise. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plastic Packaging
E-Commerce Plastic Packaging Market
Plastic Packaging
Poland Plastic Bottles Market
Plastic Packaging
Philippines Plastics Market
Plastic Packaging
Disposable Straw Market
Plastic Packaging
UVI Stretch Films Market
Plastic Packaging
Plant-Based Plastic Packaging Market
Plastic Packaging
PCR Films Market
Plastic Packaging
Plastic Sterilization Trays Market
Plastic Packaging
Europe Blow Molded Plastic Market
Plastic Packaging
Brazil Plastic Bottles Market
Plastic Packaging
Asia Pacific Plastic Packaging Market
Plastic Packaging
Corrugated Plastic Trays Market
Plastic Packaging
BOPP Tobacco Films Market
Plastic Packaging
Europe Personal Care Plastic Tube Packaging Market
Plastic Packaging
Cast Stretch Films Market
Plastic Packaging
Plastic Medicine Bottles Market