
 Saudi Arabia Plastic Caps and Closures Market | 2026-2036
Saudi Arabia Plastic Caps and Closures Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Plastic Caps and Closures Market Insights
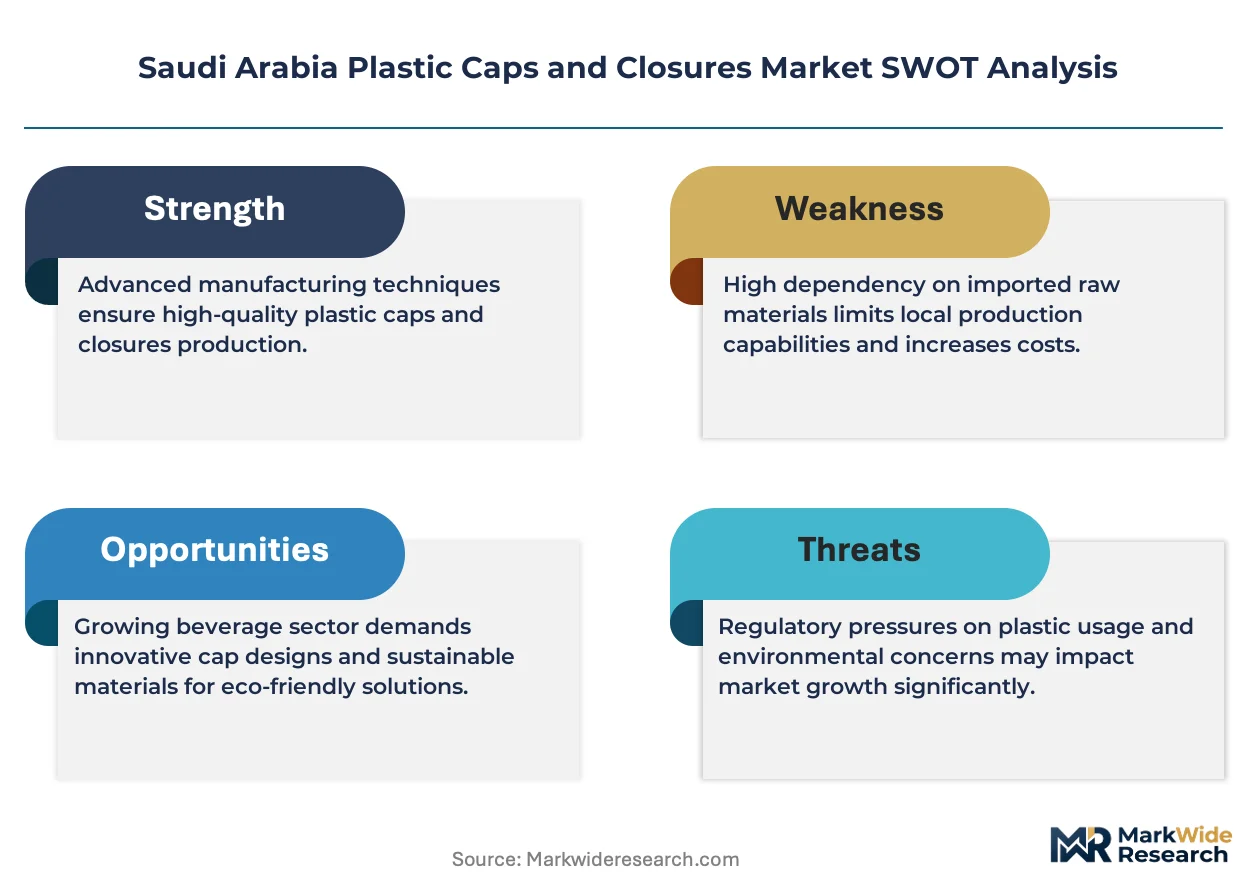
Modular closure configurations with integrated tamper-evident bands and dispensing features is expanding buyer choice across beverage and personal care segments. APICO leverages its domestic manufacturing footprint to sustain cost-competitive supply to regional bottlers. Takween Advanced Industries anchors its position through specialized polymer compounding capabilities that serve closure-specific performance requirements. SABIC competes by controlling upstream polyethylene and polypropylene resin supply, giving it raw material cost advantages over import-dependent rivals.
Plastic caps and closures are injection-molded or compression-molded thermoplastic components, typically manufactured from polyethylene or polypropylene with specified thread dimensions and torque-release profiles, designed to seal containers against contamination, leakage, and oxidation while enabling controlled consumer access. Screw caps dominate volume demand due to their resealability and compatibility with carbonated beverages, while flip top configurations capture premium positioning in personal care and household applications where one-handed dispensing drives purchase preference. Polypropylene leads material selection for hot-fill and chemical-resistant applications, whereas polyethylene sustains cost-sensitive beverage segment share.
SFDA, SASO, and the Saudi Food and Drug Authority's packaging material guidelines shape compliance obligations for pharmaceutical and food-contact closures, mandating migration testing and additive disclosure that elevates entry barriers for non-certified suppliers. The Saudi Standards, Metrology and Quality Organization enforces technical regulations on plastic product safety that influence resin grade selection and manufacturing process validation. Stakeholders must monitor evolving extended producer responsibility frameworks and recyclability mandates that will reshape material specifications and closure lightweighting investments.
Market Dynamics
SFDA's tightening material traceability mandates for pharmaceutical-grade closures are forcing resin grade upgrades and manufacturing process revalidations across domestic production facilities.
Growth Catalysts
- Beverage Bottling Expansion:Bottled water and soft drink producers in Riyadh and Jeddah are scaling output to match convenience packaging shifts, anchoring volume demand for screw-cap configurations.
- SFDA Compliance Upgrades:Pharmaceutical packaging material guidelines mandate migration testing and additive disclosure, creating certified-supplier premiums that elevate domestic compounders with validated quality systems.
- Polypropylene Substitution:Hot-fill compatibility and chemical resistance specifications are displacing polyethylene in personal care and household applications where one-handed dispensing features command price premiums.
Market Restraints
- Resin Import Dependency:Non-integrated processors face polyethylene and polypropylene cost volatility tied to SABIC's upstream pricing power and global feedstock fluctuations.
- Concentrated Demand Geography:Riyadh and Jeddah bottling clusters absorb disproportionate supply volume, leaving peripheral regions underserved by cost-competitive logistics networks.
- SFDA Certification Timelines:Extended validation periods for pharmaceutical-grade closure materials compress working capital cycles and delay revenue recognition for new product introductions.
Strategic Opportunities
- Eastern Province Manufacturing:Jubail industrial corridor offers petrochemical proximity for backward-integrated compounders seeking captive resin supply and export access to Bahrain and Kuwait.
- Extended Producer Responsibility:Anticipated recyclability mandates will reshape material specifications, rewarding early investments in closure lightweighting and mono-material designs compatible with existing Saudi recycling infrastructure.
- Smart Closure Integration:Convergence of tamper-evident bands with QR-enabled authentication features opens premium positioning in pharmaceutical and high-value personal care segments.
Industry Challenges
- Tooling Retrofit Costs:Compression molding migration from injection systems demands capital-intensive equipment swaps that strain mid-tier processors with limited balance sheet capacity.
- Polymer Compounding Expertise Gap:Specialized formulation knowledge for hot-fill and chemical-resistant specifications concentrates at Takween Advanced Industries and select technical institutes, constraining workforce scalability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Plastic Caps and Closures Market |
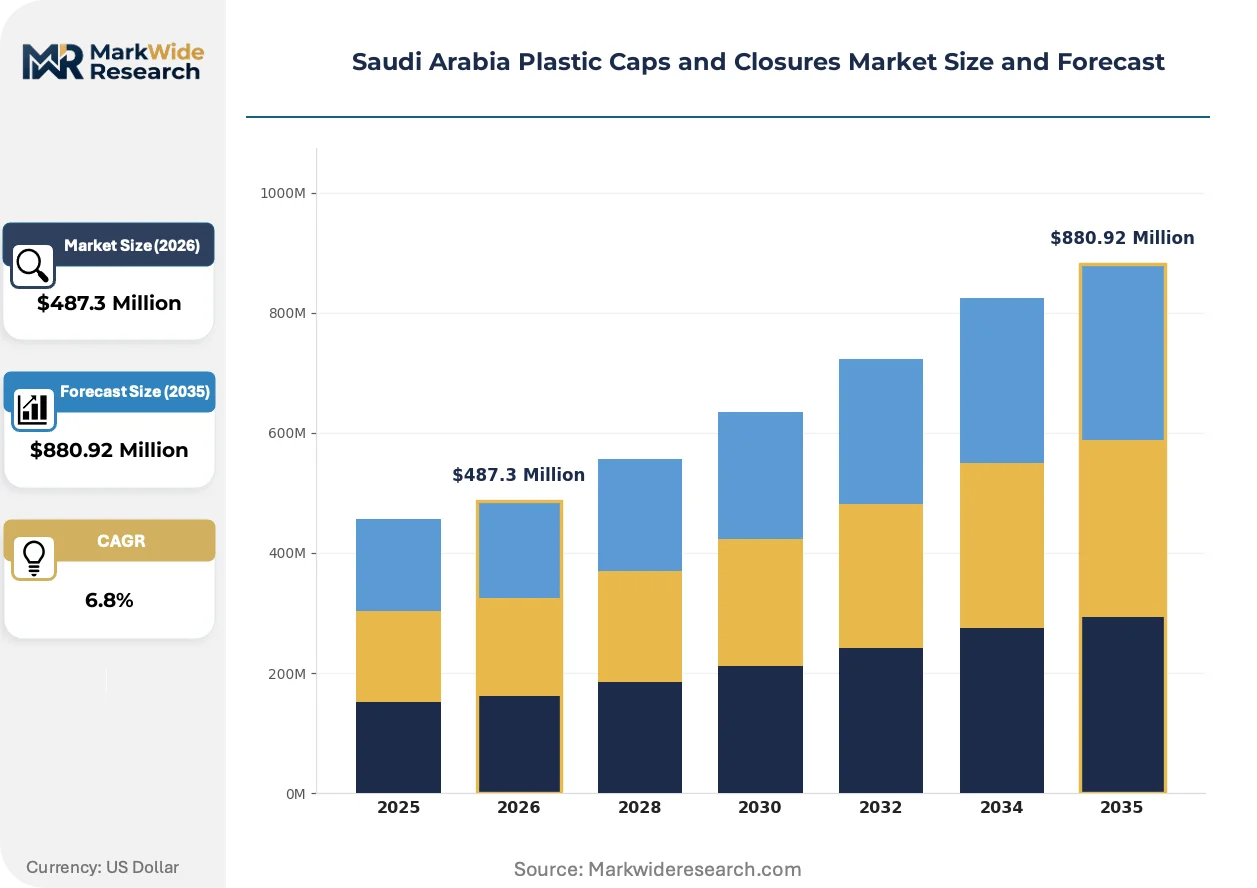
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flip Top, Screw Cap, Snap-on, Valve Cap Material: Polyethylene, Polypropylene, Polystyrene, PVC Application: Beverages, Pharmaceuticals, Personal Care, Household End User: Food Manufacturers, Cosmetic Companies, Healthcare Providers, Retailers |
| Companies Covered | Tetra Pak Global, Arabian Plastic Industrial Company Limited (APICO), Takween Advanced Industries, AptarGroup, Inc., Saudi Plastic Factory Co., ALPLA Group, 3P Gulf Group, Saudi Basic Industries Corporation (SABIC), Al-Amoudi Closures Manufacturing Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Plastic Caps and Closures Market Trends and Innovations
Closure design is converging with digital authentication and sustainability mandates, compressing development cycles while expanding functional requirements beyond basic sealing performance.
All-electric injection molding systems with integrated vision inspection are automating defect detection and torque consistency verification in high-volume beverage applications. Major bottlers in Riyadh are adopting these platforms to reduce manual quality checkpoints. The technology is automating workforce reallocation toward process engineering roles while compressing acceptable defect thresholds.
SASO technical regulations on plastic product safety are tightening additive disclosure requirements for food-contact closures. Manufacturers must now document migration test results across batch records, elevating documentation burdens. Pharmaceutical and infant nutrition segments are responding by consolidating supplier bases toward compounders with pre-validated resin grades.
Direct procurement relationships between bottlers and specialized compounders are displacing distributor-mediated resin sourcing in Jeddah's personal care manufacturing cluster. Brand owners now specify torque-release profiles and thread dimensions in supply agreements rather than accepting standard catalog offerings. This pattern concentrates most visibly in premium shampoo and conditioner brands where dispensing ergonomics drive repeat purchase decisions.
Saudi Arabia Plastic Caps and Closures Market Segmentation
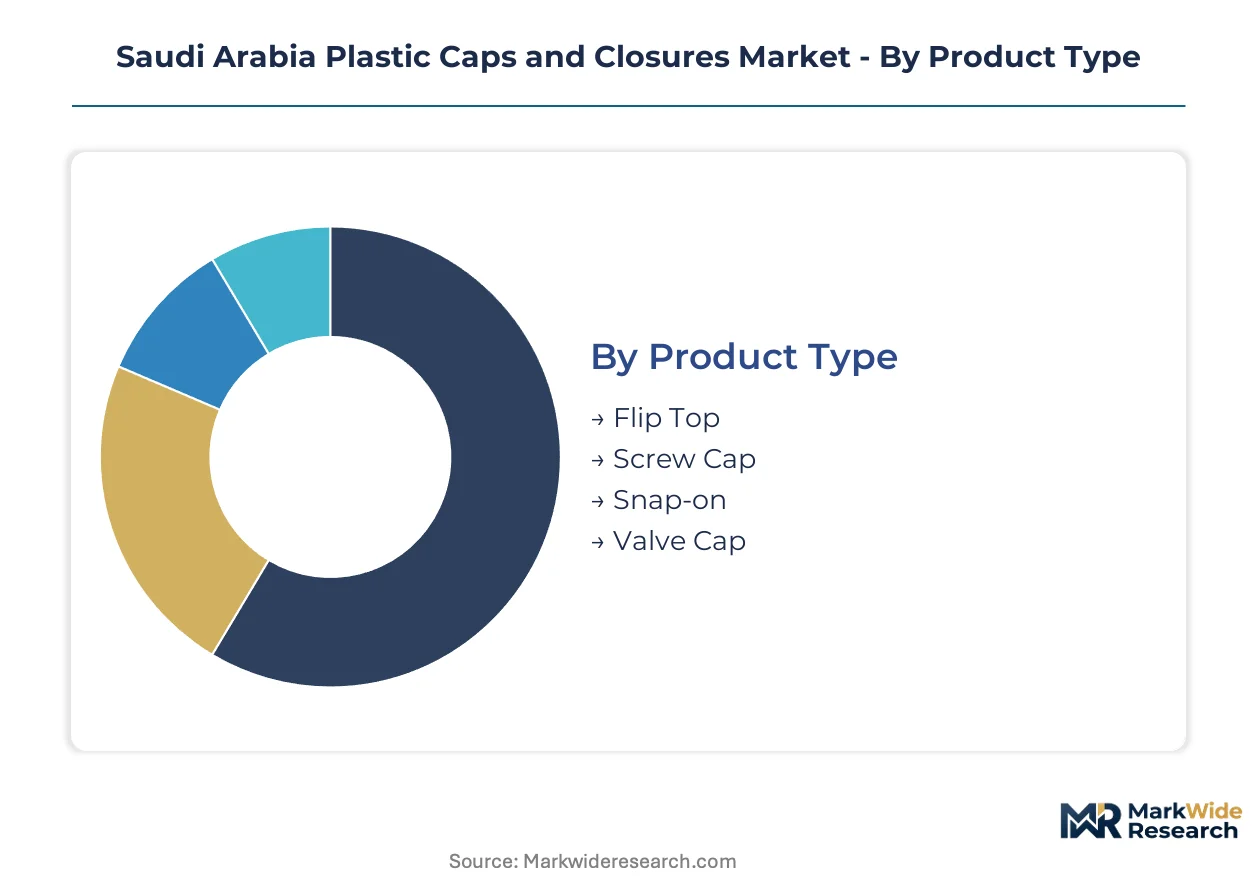
Closure specifications diverge sharply across Saudi Arabia's beverage bottling corridors and pharmaceutical packaging zones, with thread dimensions and torque-release profiles calibrated to distinct contamination-risk tolerances. Material selection and dispensing mechanism choices determine compliance pathways against SFDA migration testing mandates and SASO technical regulations.
Product Type:
Equipment replacement cycles at Riyadh and Jeddah bottling facilities favor configurations that integrate tamper-evidence with consumer convenience features without retooling entire production lines.
- Screw Cap:Injection-molded or compression-molded thermoplastic components with specified thread dimensions and resealability profiles. Riyadh bottled water and soft drink producers anchor volume demand for this configuration due to carbonated beverage compatibility and established capping line infrastructure.
- Flip Top:Hinged-lid designs enabling one-handed dispensing through integrated living hinges. Personal care manufacturers in Jeddah command price premiums for shampoo and conditioner applications where dispensing ergonomics drive repeat purchase decisions.
- Snap-on:Press-fit closures without threading for single-use beverage and dairy applications. Food manufacturers specify these for portion-controlled products requiring minimal opening force.
- Valve Cap:Silicone or thermoplastic elastomer valves controlling directional flow. Household cleaning product lines utilize these for controlled dispensing of viscous liquids.
Volume placements concentrate in Screw Cap; the faster expansion belongs to Flip Top.
Material:
Resin grade selection separates cost-sensitive beverage contracts from pharmaceutical-grade premiums validated through SFDA batch documentation requirements.
- Polypropylene:Semi-crystalline thermoplastic selected for hot-fill compatibility and chemical resistance specifications. Personal care and household applications displace polyethylene where one-handed dispensing features command price premiums.
- Polyethylene:Lower-density option sustaining cost-sensitive beverage segment share through SABIC's upstream supply control. Riyadh bottlers specify LDPE and HDPE grades for carbonated soft drink closures where migration thresholds are less stringent.
- Polystyrene:Amorphous polymer for rigid, transparent closure applications. Cosmetic companies specify crystal grades for premium visual presentation in skincare packaging.
- PVC:Chlorinated polymer retained for specific chemical barrier requirements. Limited pharmaceutical applications persist where alternative materials fail compatibility testing.
Polyethylene dominates unit placements; polypropylene gains share fastest in premium personal care conversions.
Application:
Regulatory intensity tiers separate pharmaceutical compliance investments from commodity beverage tooling.
- Beverages:Bottled water and soft drink producers in Riyadh and Jeddah scaling output to match convenience packaging shifts. Screw-cap configurations anchor this segment through established capping line infrastructure.
- Pharmaceuticals:SFDA packaging material guidelines mandate migration testing and additive disclosure. Certified-supplier premiums elevate domestic compounders with validated quality systems serving healthcare providers.
- Personal Care:Shampoo, conditioner, and skincare brands where dispensing ergonomics drive specification. Jeddah manufacturers consolidate supplier bases toward compounders with pre-validated resin grades.
- Household:Cleaning products and maintenance chemicals requiring chemical-resistant closure specifications. Hot-fill compatibility demands push polypropylene substitution in this segment.
Beverage applications absorb the highest unit volumes; pharmaceutical specifications carry the steepest margin premiums.
End User:
Procurement authority concentration distinguishes direct bottler-compounder relationships from distributor-mediated sourcing.
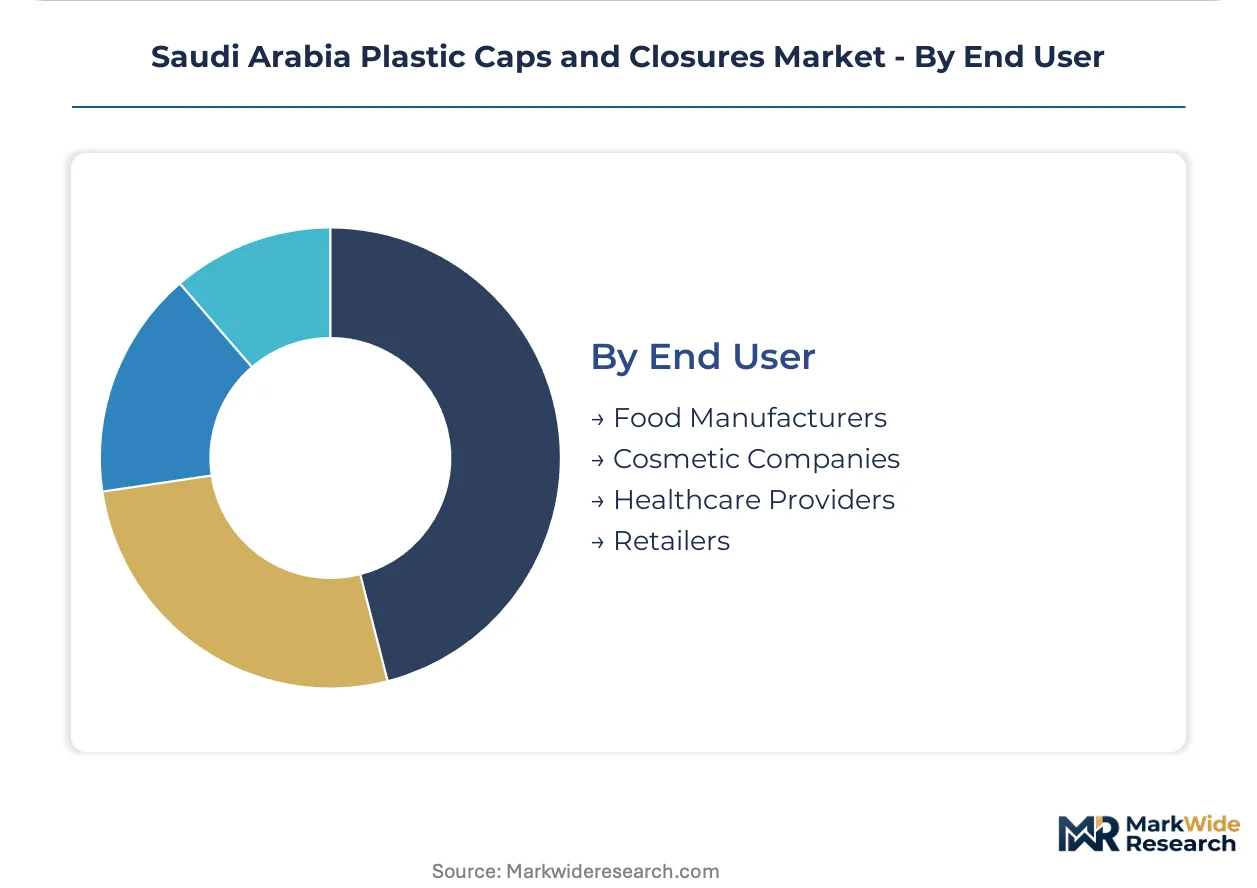
- Food Manufacturers:Bottled water, dairy, and condiment producers specifying torque-release profiles in supply agreements. Riyadh clusters drive standardization toward screw-cap and snap-on configurations.
- Cosmetic Companies:Premium shampoo and conditioner brands in Jeddah's manufacturing corridor. Direct procurement relationships displace distributor-mediated resin sourcing as brand owners specify thread dimensions.
- Healthcare Providers:Hospital systems and pharmaceutical packaging contractors facing SFDA certification timelines. Extended validation periods compress working capital cycles for new product introductions.
- Retailers:Private-label bottlers and contract packagers serving peripheral regions beyond Riyadh-Jeddah concentration. Logistics cost disadvantages limit cost-competitive supply reach.
Food manufacturers place the largest unit orders; cosmetic companies drive the fastest specification upgrading.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia's plastic caps and closures production concentrates in the Central and Western regions, while consumption spreads across urban bottling corridors. This geographic mismatch shapes logistics networks and supplier consolidation patterns.
Riyadh
Bottled water and soft drink bottlers anchor demand through high-volume screw-cap placements. SFDA compliance requirements for food-contact closures mandate migration testing documentation from compounders. The Riyadh industrial zone hosts injection-molding facilities serving carbonated beverage producers with validated resin grades.
Eastern Province
Jubail's petrochemical corridor offers backward-integrated compounders captive polyethylene and polypropylene supply. The region's resin production proximity reduces import dependency for closure manufacturers. Export-oriented processors leverage port access to serve Bahrain and Kuwait bottling operations.
Jeddah
Personal care manufacturers drive premium flip-top specifications for shampoo and conditioner applications. Direct procurement relationships displace distributor-mediated sourcing as brand owners mandate torque-release profiles. The city's manufacturing cluster concentrates dispensing-ergonomics innovation for repeat-purchase-driven categories.
Western Region
Pharmaceutical packaging contractors face extended SFDA certification timelines for closure material validation. Healthcare providers consolidate supplier bases toward compounders with pre-documented quality systems. Taif and surrounding areas host specialized converters serving infant nutrition segments.
Saudi Arabia Plastic Caps and Closures Market Competitive Landscape
The competitive structure tilts toward resin-integrated compounders with validated quality systems. Domestic processors with SABIC supply relationships command cost advantages over import-dependent rivals. Three archetypes dominate: upstream-integrated resin suppliers, specialized polymer compounders, and regional fabrication specialists. Capacity expansion and strategic partnerships represent the primary competitive vectors as bottlers consolidate supplier bases.
Among resin-integrated players, Saudi Basic Industries Corporation anchors upstream supply control. Takween Advanced Industries occupies the specialized compounding tier with formulation expertise for hot-fill applications. Arabian Plastic Industrial Company represents regional fabrication scale serving Riyadh and Jeddah bottling corridors.
| Leading Market Players |
|---|
| Tetra Pak Global |
| Arabian Plastic Industrial Company Limited (APICO) |
| Takween Advanced Industries |
| AptarGroup, Inc. |
| Saudi Plastic Factory Co. |
| ALPLA Group |
| 3P Gulf Group |
| Saudi Basic Industries Corporation (SABIC) |
| Al-Amoudi Closures Manufacturing Company |
| Others |
Pricing and Supply Chain Analysis
Compression molding migration from injection systems is compressing unit economics for mid-tier processors while concentrating supply relationships around SABIC-integrated compounders with captive resin access. This equipment transition simultaneously elevates capital barriers and rewards backward-integrated players who control polyethylene and polypropylene feedstock costs.
Pricing Analysis
Cost-down pressure on pharmaceutical-grade closures accelerates because SFDA certification timelines compress working capital cycles and elevate documentation burdens. Three-tier pricing structure across certified-premium, validated-standard, and commodity-economy levels separates domestic compounders with batch-validated systems from import-dependent rivals. Price differentiation hinges on migration test documentation depth and torque-release profile customization. Beverage bottlers in Riyadh exhibit highest price sensitivity due to volume scale and screw-cap standardization, while Jeddah personal care manufacturers absorb premiums for flip-top dispensing ergonomics.
Supply Chain Analysis
Post-consumer closure collection and regrind flows remain underdeveloped across Saudi Arabia, constraining circular feedstock availability for mono-material redesigns. Resin supply concentrates in Jubail's Eastern Province petrochemical corridor, with polyethylene and polypropylene production anchoring domestic compounder cost positions. Raw material dependencies rest on SABIC's upstream supply control, global propylene feedstock markets, and specialized thermoplastic elastomer imports for valve applications. Single-source vulnerability around SFDA-certified resin grades creates supply chain risk for pharmaceutical packaging contractors. Distribution runs through direct bottler-compounder relationships in Riyadh and Jeddah clusters, with distributor mediation persisting in peripheral regions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
SFDA's tightening material traceability mandates construct a compliance moat that rewards certified domestic compounders while elevating entry costs for non-validated suppliers. This regulatory barrier-to-entry dynamic favors incumbents with pre-established quality systems.
For Market Incumbents: Extend certification coverage into infant nutrition and high-value personal care segments before regulatory scope expansion. SFDA validation investments compound competitive advantage as import-dependent rivals face extended approval timelines. Backward integration into captive resin compounding at Jubail anchors cost positions against polyethylene price volatility. Channel control through direct bottler relationships in Riyadh bottling corridors limits distributor disintermediation risk. For New Entrants and Emerging Players: Smart closure integration with QR-enabled authentication features offers technology-first wedge into pharmaceutical and premium personal care white space. Eastern Province manufacturing at Jubail leverages petrochemical proximity for export access to Bahrain and Kuwait bottling operations. Peripheral region retailers beyond Riyadh-Jeddah concentration represent most penetrable demand geography due to logistics cost disadvantages facing incumbent suppliers. Go-to-market positioning should emphasize mono-material designs compatible with anticipated extended producer responsibility mandates. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to regional packaging conglomerates seeking Saudi manufacturing footprint. Long-term viability favors compounders with validated quality systems serving healthcare and infant nutrition segments where regulatory intensity sustains margin premiums. Acquisition target archetype: mid-scale processors with SFDA pre-certification and compression molding equipment capable of hot-fill polypropylene specifications. Monitor SFDA scope expansion announcements for inflection signals on compliance investment requirements.| Strategic Initiative | Industry Significance |
|---|---|
| SFDA Certification Investment | Validates quality systems for pharmaceutical-grade closure supply, creating supplier consolidation pressure. |
| Compression Molding Migration | Automates defect detection and torque consistency verification for Riyadh beverage bottlers. |
| Jubail Manufacturing Footprint | Captures petrochemical proximity for backward-integrated resin supply and Gulf export access. |
| Mono-Material Design Transition | Aligns closure specifications with Saudi recycling infrastructure and anticipated EPR mandates. |
| Direct Bottler Procurement Relationships | Displaces distributor mediation in Jeddah personal care clusters through specification control. |
Research Methodology
Independent corroboration across plant managers at Riyadh injection-molding facilities, procurement leads at Jeddah personal care manufacturers, SFDA regulatory affairs specialists, and distribution channel partners underwrites the qualitative findings. Secondary validation draws from SASO technical regulation filings, SFDA packaging material guidelines, customs trade data on polyethylene and polypropylene imports, and SEC disclosures from listed packaging conglomerates. Bottom-up demand estimates from bottler capacity expansions triangulate against top-down resin consumption patterns.
Comparable historical periods anchored the forecast window to pre-pandemic baseline demand and post-regulatory implementation trajectories across the analysis window. Segmentation modeling spans product type, material grade, application intensity, and end-user procurement authority. CAGRs derive from unit placement trends by closure configuration and value-per-unit escalation from premium material substitutions. Industry-specific inputs include SFDA certification timeline data and SABIC resin pricing disclosure patterns.
Several conditions sit outside the modeled scope, including abrupt SFDA regulatory scope expansions, SABIC supply disruptions, and Gulf political trade realignments. Forecasts reflect documented assumptions on certification timeline stability and resin price volatility bands. Practitioners should monitor SFDA guidance releases, extended producer responsibility mandate announcements, and Jubail petrochemical capacity expansion schedules for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Caps and Closures
Elastomeric Closures Market
Caps and Closures
Global Die Cut Lids Market
Caps and Closures
South Africa Plastic Caps and Closures Market
Caps and Closures
Polypropylene Screw Caps Market
Caps and Closures
Twist Dispensing Closures Market
Caps and Closures
Tear Tab Cap Market
Caps and Closures
End Cap Market
Caps and Closures
Ribbed Closures Market
Caps and Closures
Molded Fiber End Caps Market
Caps and Closures
China Plastic Caps and Closures Market
Caps and Closures
Dauber Caps Market
Caps and Closures
Steel Ring Pull Caps Market
Caps and Closures
Handheld Induction Cap Sealers Market
Caps and Closures
IBC Caps Market
Caps and Closures
Resealable Closures and Spouts Packaging Market
Caps and Closures
Molded Fiber Pulp Cap Market