
 Advanced-Recycled Polyethylene for E-Commerce Packaging Market | 2026-2036
Advanced-Recycled Polyethylene for E-Commerce Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Advanced-Recycled Polyethylene for E-Commerce Packaging Market Insights
Project finance tied to circular-economy infrastructure is fragmenting competitive access in advanced-recycled polyethylene. Amcor leverages its integrated recycling network across European polymer hubs to secure feedstock certainty. Sealed Air anchors its position through proprietary film formulations that meet postal durability standards while raising recycled content ratios. Pregis competes by specializing in void-fill systems tailored to electronics and cosmetics shippers.
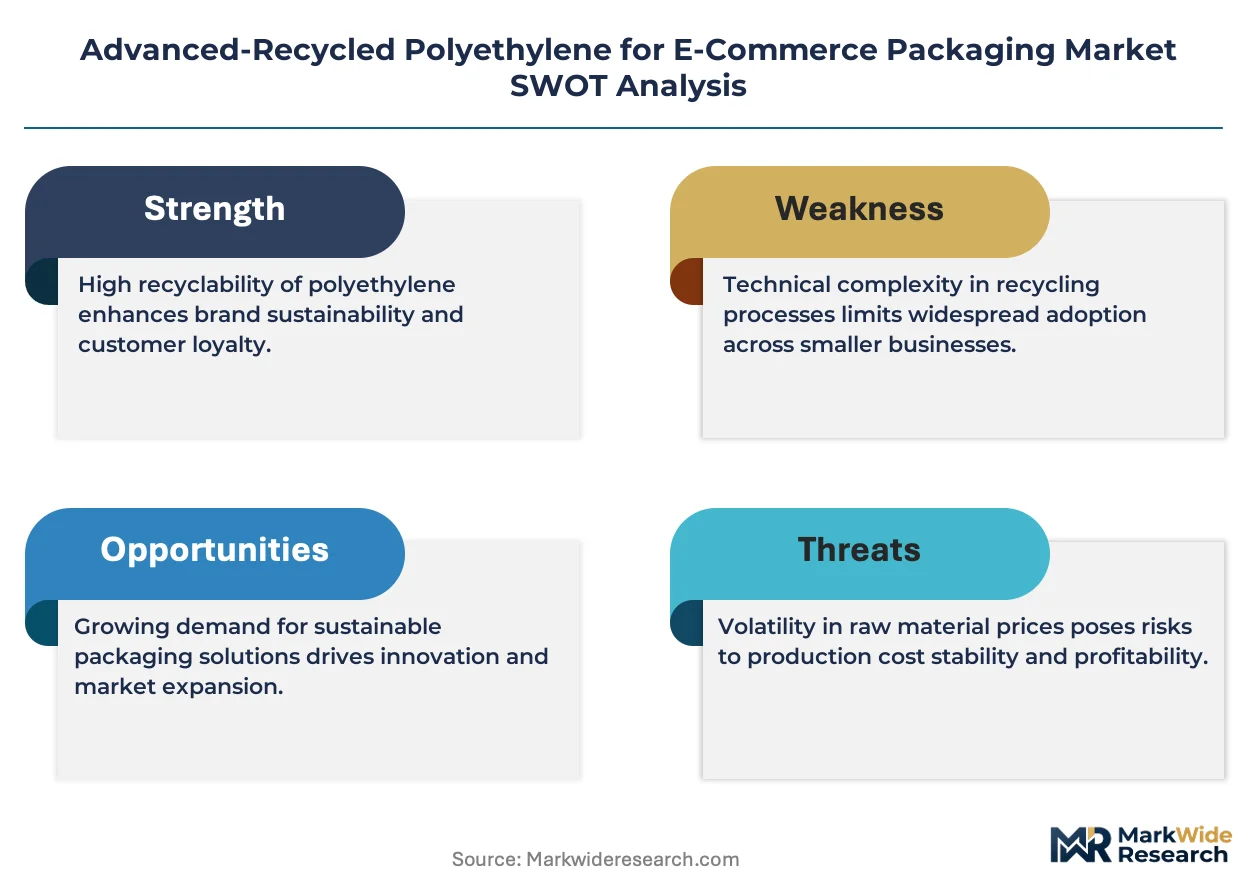
Advanced-recycled polyethylene denotes polymer recovered via chemical or mechanical purification from post-consumer and post-industrial streams, reprocessed to achieve melt-flow indices between 0.3 and 150 g/10 min for film extrusion and injection molding. Its primary commercial purpose is substituting virgin resin in protective and flexible e-commerce formats without sacrificing seal strength or puncture resistance. Low-density polyethylene occupies the dominant share in mailer envelopes due to existing blown-film infrastructure and softness requirements, while linear low-density polyethylene captures expanding demand in shrink films where dart-impact performance matters. Flexible pouches represent the fastest-growing application segment as direct-to-consumer brands replace rigid containers with lightweight formats.
The EPA oversees post-consumer resin certification under recycled-content procurement guidelines, while the EU Green Deal and REACH constrain permissible additives and mandate extended producer responsibility across packaging categories. These frameworks compel converters to document chain-of-custody from collection through reprocessing, effectively raising compliance costs for smaller compounders. Stakeholders must monitor how state-level recycled-content thresholds in California and New York diverge from federal benchmarks, as this fragmentation will determine where capacity investments yield viable offtake.
Market Dynamics
The EU Packaging and Packaging Waste Regulation is compressing virgin resin demand across European fulfillment networks. Chemical recycling capacity expansions in the Netherlands and Germany are redrawing feedstock access maps for flexible film converters.
Growth Catalysts
- Post-consumer resin mandates:The EU Green Deal establishes binding recycled content thresholds for e-commerce mailers. German fulfillment centers now face contractual sustainability requirements from platform operators.
- Blown-film line retrofits:Mechanical recycling purification upgrades allow 30% recycled polyethylene incorporation without seal-strength degradation. Film extruders in Belgium and France are reconfiguring die geometries.
- Cosmetics and electronics shippers:Direct-to-consumer brands in these verticals specify flexible pouches with certified chain-of-custody documentation. Premium positioning justifies material cost premiums.
Market Restraints
- Feedstock volatility:Post-consumer bale quality inconsistency from municipal collection systems generates reprocessing yield losses of 15-25%. Chemical recycling input costs track naphtha spreads.
- Antwerp-Rotterdam polymer hub concentration:Advanced recycling capacity clusters in this corridor create single-point-of-failure risk for European flexible packaging supply.
- REACH additive constraints:Legacy colorants and slip agents in post-consumer streams face authorization sunset dates. Reformulation timelines extend 18-24 months.
Strategic Opportunities
- Spanish and Italian fulfillment expansion:Southern European e-commerce penetration lags Northern benchmarks by 40%. Greenfield distribution centers offer clean-sheet recycled packaging specifications.
- Shrink-film format conversion:Linear low-density polyethylene with enhanced dart-impact properties is capturing pallet-wrapping applications from polypropylene strapping.
- Extended producer responsibility incentives:France's Citeo modulation fees reward high-recycled-content packaging with reduced compliance contributions. Brand owners optimize eco-modulation scores.
Industry Challenges
- Polymer chemist scarcity:Formulation expertise for recycled-content melt-flow index management concentrates at legacy petrochemical R&D centers. Converter hiring pipelines lack specialized training pathways.
- ISCC PLUS certification timelines:Mass-balance documentation for chemically recycled polyethylene requires 12-18 month audit cycles. Smaller compounders face consultant cost barriers.
- Legacy ERP integration:Batch-level chain-of-custody tracking demands real-time inventory system overhauls. Mid-tier converters defer digital investments due to payback uncertainty.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Advanced-Recycled Polyethylene for E-Commerce Packaging Market |
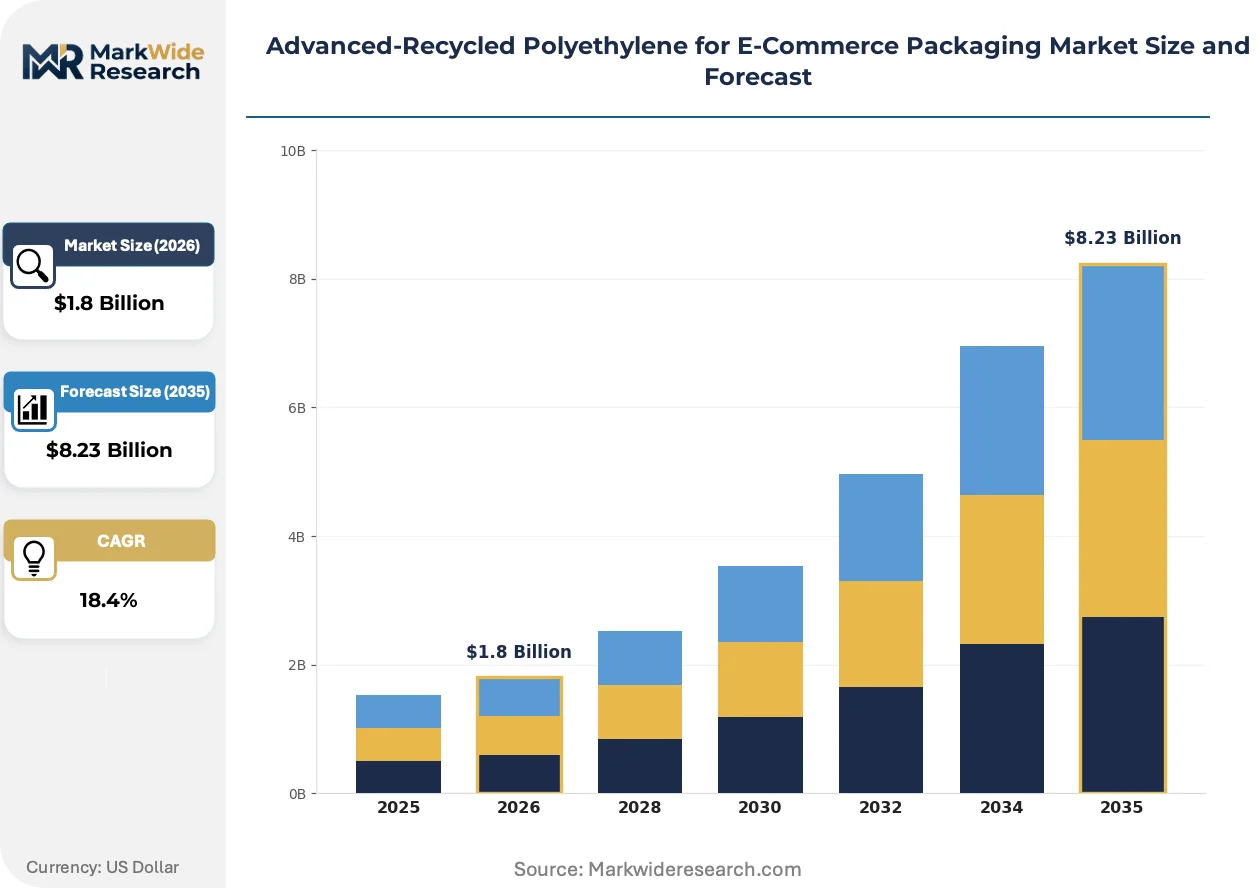
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.23 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High-Density Polyethylene, Low-Density Polyethylene, Linear Low-Density Polyethylene, Cross-Linked Polyethylene, Ultra-High Molecular Weight Polyethylene Application: Flexible Pouches, Mailer Envelopes, Bubble Wrap, Void Fill, Shrink Films, Tape End User: Online Retailers, Third-Party Logistics Providers, Direct-to-Consumer Brands, Subscription Box Services, Fulfillment Centers Packaging Type: Zip Lock Bags, Poly Bags, Stand-Up Pouches, Gusseted Bags, Mailing Sacks, Protective Sleeves |
| Companies Covered | Amcor, Sealed Air, Pregis, Mondi, Berry Global, Sonoco Products Company, Storopack Hans Reichenecker, International Paper, Smurfit Westrock, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Advanced-Recycled Polyethylene for E-Commerce Packaging Market Trends and Innovations
Chemical recycling pyrolysis output is achieving polymer-grade parity with virgin resin specifications. This breakthrough is collapsing traditional quality-tier distinctions between mechanical and advanced recycling pathways.
Pyrolysis-based polyethylene regeneration is collapsing the performance gap that previously confined recycled resin to lower-tier applications. Electronics and cosmetics brand owners in Germany and the Netherlands are specifying 50% chemically recycled content for premium unboxing experiences. The technology is collapsing virgin resin premium pricing power in mailer envelope segments.
REACH authorization requirements for legacy plastic additives are forcing systematic reformulation across European compounder networks. The regulation's sunset clause timeline is compressing R&D cycles for slip agents and UV stabilizers. Flexible pouch converters serving French and German markets are accelerating alternative additive qualification.
Direct-to-consumer brands are consolidating packaging specifications around certified circular formats. Electronics shippers are displacing rigid box-void-fill combinations with all-flexible pouch systems. This preference compression is most visible in German urban fulfillment zones where last-mile density supports lightweight format economics.
Advanced-Recycled Polyethylene for E-Commerce Packaging Market Segmentation
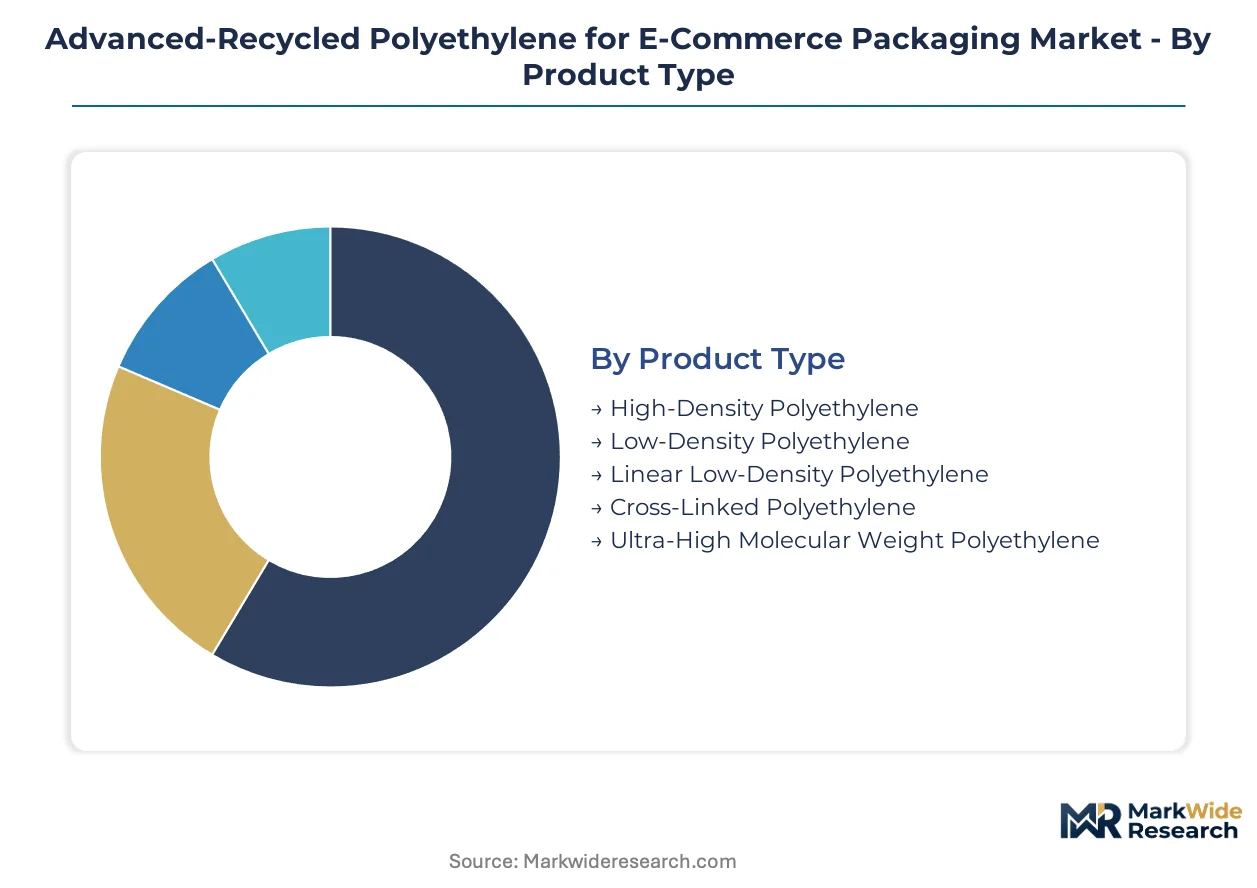
Segmentation in advanced-recycled polyethylene reflects divergent performance requirements across e-commerce formats. Material specifications, application durability, and end-user compliance obligations each create distinct procurement patterns that reshape converter priorities.
Product Type:
Cost tiers separate commodity-grade mechanical recyclate from premium chemically purified resin streams.
- Low-Density Polyethylene:Blown-film extrusion favors this grade for mailer envelope softness and existing European infrastructure. German fulfillment networks specify LDPE for platform-mandated sustainability targets.
- Linear Low-Density Polyethylene:Enhanced dart-impact properties suit shrink-film applications displacing polypropylene strapping. Belgian converters are retrofitting die geometries to raise recycled incorporation rates.
- High-Density Polyethylene:Stiffer profiles serve protective sleeve segments where puncture resistance outweighs flexibility.
- Cross-Linked Polyethylene:Specialized electronics packaging demands thermal stability beyond standard melt-flow ranges.
- Ultra-High Molecular Weight Polyethylene:Premium unboxing experiences in cosmetics verticals absorb material cost premiums.
LDPE holds installed capacity. LLDPE is rotating up the share rankings.
Application:
Volume concentration tracks last-mile density and format weight economics across fulfillment networks.
- Flexible Pouches:Lightweight formats displace rigid containers in direct-to-consumer cosmetics and electronics. Dutch brand owners specify 50% chemically recycled content for certified circular positioning.
- Mailer Envelopes:Platform operator contracts in Germany mandate minimum recycled thresholds. Chemical recycling pyrolysis output is collapsing virgin resin premium pricing in this segment.
- Shrink Films:Pallet-wrapping applications favor LLDPE with enhanced mechanical properties.
- Bubble Wrap:Void-fill systems for fragile electronics require consistent seal-strength performance.
- Void Fill:Pregis specializes in formats tailored to electronics and cosmetics shippers.
- Tape:Adhesive compatibility constraints limit recycled content ratios in closure systems.
Flexible pouches are gaining share fastest. Mailer envelopes defend volume leadership.
End User:
Customer type determines chain-of-custody documentation intensity and sustainability target bindingness.
- Online Retailers:Platform-level mandates in Germany and France compress procurement flexibility. Citeo modulation fees reward high-recycled-content specifications.
- Direct-to-Consumer Brands:Premium positioning justifies certified circular format cost premiums in cosmetics and electronics.
- Fulfillment Centers:Southern European greenfield facilities offer clean-sheet recycled packaging specifications.
- Third-Party Logistics Providers:Multi-tenant operations standardize across lowest-common-denominator compliance thresholds.
- Subscription Box Services:Unboxing experience requirements drive format consolidation around flexible pouch systems.
Online retailers anchor procurement volume. Direct-to-consumer brands are climbing the priority ladder.
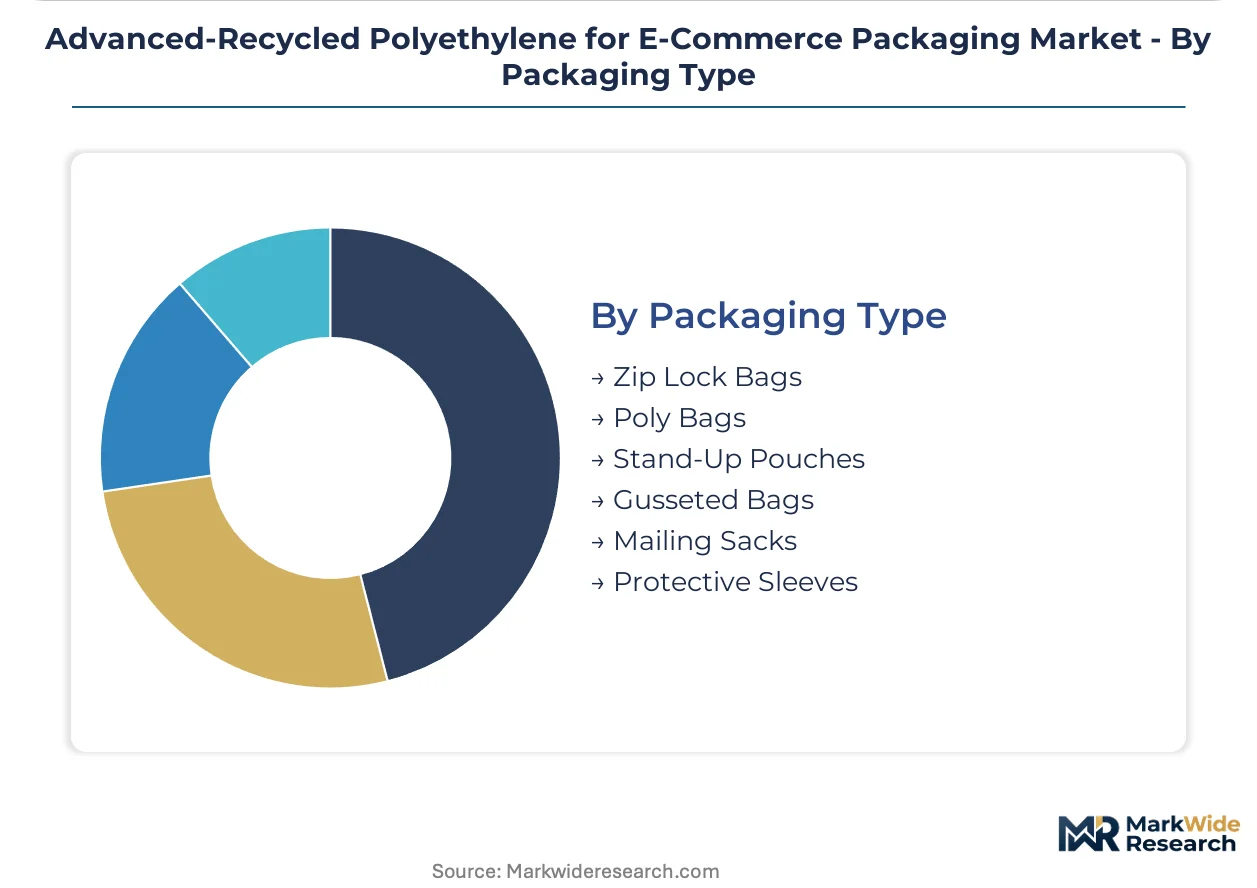
Packaging Type:
Maturity gradients separate established formats with installed recycling infrastructure from emerging specifications.
- Poly Bags:Commodity-grade formats dominate high-volume apparel shipping with mechanical recyclate compatibility.
- Stand-Up Pouches:Premium cosmetics and electronics unboxing experiences specify chemically recycled content tiers.
- Zip Lock Bags:Reclosure functionality demands precise seal-layer formulation.
- Gusseted Bags:Bulk fulfillment applications favor dimensional stability.
- Mailing Sacks:Heavy-duty variants serve industrial e-commerce with puncture resistance priorities.
- Protective Sleeves:Electronics-specific formats absorb UHMWPE cost premiums.
Poly bags dominate installed base. Stand-up pouches show steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German fulfillment networks command premium pricing for certified circular packaging, while Spanish greenfield distribution centers operate on thinner margins with clean-sheet specifications. This asymmetry is compressing converter margins in Southern Europe while rewarding early compliance investments in the North.
Germany
Platform operator contracts mandate minimum recycled thresholds for mailer envelopes across fulfillment networks. The EU Packaging and Packaging Waste Regulation binds producers to extended producer responsibility schemes with escalating targets. The Rhine-Ruhr polymer corridor hosts chemical recycling retrofits serving e-commerce film extruders.
Netherlands
Dutch brand owners specify 50% chemically recycled content for premium unboxing experiences in cosmetics and electronics. REACH authorization timelines for legacy additives are forcing 18-24 month reformulation cycles. The Antwerp-Rotterdam hub concentrates pyrolysis capacity that redraws feedstock access maps.
France
Citeo modulation fees reward high-recycled-content packaging with reduced compliance contributions, incentivizing specification upgrades. The EU Green Deal establishes binding recycled content thresholds that tighten through 2030. The Paris Basin fulfillment zone anchors procurement volume for flexible pouch converters.
Spain
Southern European e-commerce penetration lags Northern benchmarks by 40%, creating greenfield specification opportunities. National transposition of EU packaging waste rules is accelerating municipal collection system upgrades. Barcelona and Madrid distribution corridors attract capacity investments targeting clean-sheet recycled packaging contracts.
United States
State-level recycled-content thresholds in California and New York diverge from federal EPA benchmarks, fragmenting compliance landscapes. The EPA oversees post-consumer resin certification under procurement guidelines that vary by agency. The Southeast fulfillment corridor is absorbing blown-film line retrofits for mechanical recycling integration.
Advanced-Recycled Polyethylene for E-Commerce Packaging Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in feedstock and formulation layers. The market structure concentrates around integrated converters with captive recycling networks and specialized film compounders with proprietary additive packages. Three archetypes dominate: multinational packaging platforms with vertical recycling assets, regional flexible film specialists with formulation expertise, and chemical recycling technology licensors with mass-balance certification capabilities. Competitive moves center on blown-film line retrofits for higher recycled incorporation and ISCC PLUS audit investments to secure brand owner contracts.
Within the integrated platform tier, Amcor leverages its European polymer hub network to anchor feedstock certainty for fulfillment network contracts. Sealed Air occupies a position exemplifying proprietary film formulation specialization, while Pregis represents the void-fill systems niche tailored to electronics and cosmetics verticals. These three entities illustrate how competitive positioning fragments across recycling integration depth, formulation IP, and application-specific engineering rather than converging on a single dominant model.
| Leading Market Players |
|---|
| Amcor |
| Sealed Air |
| Pregis |
| Mondi |
| Berry Global |
| Sonoco Products Company |
| Storopack Hans Reichenecker |
| International Paper |
| Smurfit Westrock |
| Others |
Pricing and Supply Chain Analysis
Antwerp-Rotterdam hub overcapacity in pyrolysis capacity is compressing chemical recycling feedstock premiums while simultaneously tightening mechanical recyclate spreads. This utilization asymmetry is redrawing converter procurement calendars and forcing tiered sourcing strategies across European film extruders.
Pricing Analysis
The customization-premium spread between ISCC PLUS-certified chemically recycled polyethylene and commodity mechanical recyclate now spans three performance tiers. Pricing stratifies across premium chemically purified resin, standard mass-balance certified grades, and economy mechanical recyclate with limited chain-of-custody documentation. Cost compression in the economy tier is intensifying because municipal bale quality inconsistency generates 15-25% reprocessing yield losses. Direct-to-consumer cosmetics brands absorb premium-tier pricing with minimal sensitivity, while third-party logistics providers standardize around lowest-common-denominator compliance thresholds.
Supply Chain Analysis
Contract manufacturing concentration for blown-film extrusion sits with integrated packaging platforms operating captive recycling networks across Germany, the Netherlands, and Belgium. Feedstock sourcing draws from post-consumer bale aggregators in France, municipal collection upgrades in Spain, and pyrolysis output from the Rhine-Ruhr corridor. Single-source vulnerability concentrates in the Antwerp-Rotterdam polymer hub where chemical recycling capacity clusters create chokepoint exposure. Distribution runs through platform operator procurement systems that mandate minimum recycled thresholds for fulfillment network contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment via ISCC PLUS certification timelines creates switching costs that lock brand owners into qualified supplier relationships.
For Market Incumbents: Pre-empt feedstock security gaps by anchoring long-term offtake agreements with pyrolysis operators in the Netherlands and Germany before capacity absorption tightens. Chemical recycling technology licensors represent an emerging entrant archetype threatening to disintermediate traditional converter margins; backward integration into post-consumer bale aggregation in Southern Europe offers defensive positioning against this threat. For New Entrants and Emerging Players: Spanish and Italian fulfillment center greenfield specifications offer the most penetrable geographic entry point, with e-commerce penetration lagging Northern benchmarks by 40% and clean-sheet procurement protocols absent legacy supplier entrenchment. Target void-fill systems for electronics shippers as the anchor application, then leverage Citeo modulation fee optimization as the go-to-market angle for French market expansion. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across chemical recycling pyrolysis capacity as mass-balance certification requirements extend audit cycles and consultant costs. Long-term viability favors integrated platforms with captive recycling networks over standalone compounders facing feedstock volatility. Watch for ISCC PLUS certification backlog clearance rates as the inflection signal indicating when qualified supply scarcity will compress converter margins.| Strategic Initiative | Industry Significance |
|---|---|
| Blown-Film Line Retrofit for Recycled Incorporation | Belgian and French extruders reconfigure die geometries to raise mechanical recyclate rates without seal-strength degradation. |
| ISCC PLUS Certification Investment | Mass-balance documentation capabilities unlock brand owner contracts specifying 50% chemically recycled content tiers. |
| Backward Integration into Bale Aggregation | Captive feedstock sourcing from Spanish municipal collection upgrades reduces yield loss exposure from quality inconsistency. |
| Proprietary Additive Package Development | REACH-compliant slip agent reformulation addresses sunset clause timelines compressing R&D cycles to 18-24 months. |
| Southern European Fulfillment Network Partnership | Greenfield distribution center specifications in Barcelona and Madrid corridors bypass incumbent supplier lock-in. |
Research Methodology
Operator-level perspectives from film extrusion plant managers, procurement leads at German fulfillment networks, chemical recycling technology licensors, and cosmetics brand sustainability directors anchored the qualitative base. Primary interview findings triangulated against secondary sources including EU Packaging and Packaging Waste Regulation implementation trackers, ECHA REACH authorization sunset databases, Citeo eco-modulation fee schedules, and customs data on post-consumer resin trade flows. Bottom-up capacity buildout assessments across pyrolysis retrofits in the Netherlands and Germany combined with top-down demand modeling from e-commerce fulfillment expansion projections.
Scenario-bracketing framed volume and value outputs across the analysis window, with segmentation dimensions spanning polyethylene grade tier, e-commerce application format, end-user procurement mandate bindingness, and regional regulatory cluster. CAGRs derived from installed capacity absorption rates, platform operator contract renewal calendars, and municipal collection system upgrade timelines. Industry-specific inputs included blown-film line retrofit lead times and ISCC PLUS certification audit cycle durations.
The forecast holds incumbent behavior within observed patterns; aggressive capacity additions by chemical recycling technology licensors or accelerated EU recycled content threshold tightening would shift outcomes beyond modeled bounds. Quarterly review of pyrolysis output quality parity announcements and REACH additive authorization withdrawal notices is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plastic Packaging
Blow Molded Plastics Market
Plastic Packaging
PCR Bottles Market
Plastic Packaging
Middle East and Africa Plastic Packaging Market
Plastic Packaging
South Africa Rigid Plastic Packaging Market
Plastic Packaging
Clear Plastic Boxes Market
Plastic Packaging
United Kingdom Plastic Bottles Market
Plastic Packaging
Plastic Bottles and Containers Market
Plastic Packaging
Plastic Liners Market
Plastic Packaging
Global Returnable Plastic Crates Market
Plastic Packaging
Thailand Rigid Plastic Packaging Market
Plastic Packaging
Plastic Ready Meal Trays Market
Plastic Packaging
Shrink Plastic Films Market
Plastic Packaging
Plastic Crates Market
Plastic Packaging
Plastic Canister Market
Plastic Packaging
Latin America Single-Use Plastic Packaging Market
Plastic Packaging
Post-Consumer Recycled Plastic Packaging Market