
 Clear Plastic Boxes Market | 2026-2036
Clear Plastic Boxes Market Size, Share, and Industry Trends Forecast 2026-2036
Clear Plastic Boxes Market Outlook
The EU Packaging and Packaging Waste Regulation is restructuring procurement criteria for transparent rigid packaging across European retail supply chains. Amcor leverages its integrated recycling infrastructure to supply post-consumer recycled content grades that meet these specifications. Placon sustains leadership in thermoformed PET clamshells for foodservice applications through proprietary tooling capabilities. Berry Global anchors North American supply with multi-site extrusion and thermoforming operations serving mass retail channels.
Clear plastic boxes are rigid transparent containers fabricated from polyethylene terephthalate, polystyrene, or polypropylene through injection molding, thermoforming, or extrusion processes, typically specified for dimensional tolerances of 0.1-0.5 millimeters to ensure stackability and optical clarity. These containers serve primary functions in product visibility, protection from contamination, and shelf-ready merchandising across retail and institutional settings. Storage Containers and Display Boxes command the largest share of product type revenue, with Display Boxes capturing premium margin pools in cosmetics and electronics sectors where visual presentation directly influences purchase decisions. The Food Packaging segment within product types and the Food Storage application are expanding fastest, propelled by deli, bakery, and ready-meal segments demanding crystal-clear oxygen barrier properties.
The FDA regulates food-contact clear plastic boxes under 21 CFR for migration limits and material safety, while EPA guidelines govern volatile organic compound emissions from solvent-based printing and adhesive operations in box decoration. In Europe, EFSA and REACH compliance requirements restrict certain phthalates and bisphenol derivatives in transparent packaging resins, compelling reformulation toward bio-based or recycled feedstocks. Stakeholders must monitor evolving extended producer responsibility frameworks and decide whether to invest in chemical recycling infrastructure or pivot toward fiber-based transparent alternatives before compliance deadlines harden.
Market Dynamics
The EU Packaging and Packaging Waste Regulation is forcing a supply-chain recalibration across rigid transparent packaging, compelling converters to certify recyclability credentials and retailers to requalify supplier bases ahead of enforcement deadlines.
Growth Catalysts
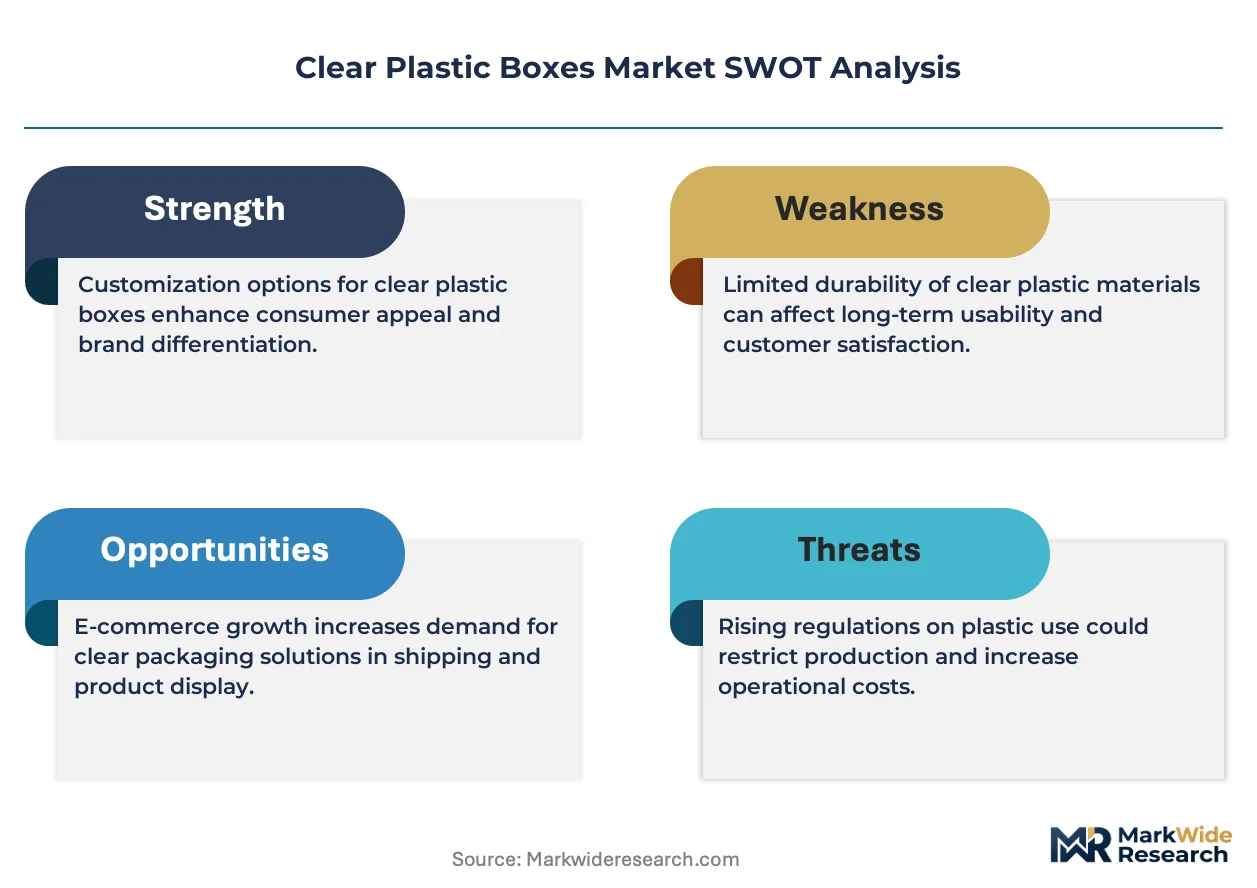
- REACH-compliant resin reformulation:ECHA restrictions on phthalates and bisphenol derivatives are accelerating bio-based PET and recycled-content PP adoption in food-contact applications across German and French retail channels.
- Electronics anti-static specifications:Semiconductor manufacturers in South Korea and Taiwan specify ionic-dissipative clear boxes for wafer transport, creating premium volume pools with 0.1-millimeter dimensional tolerances.
- Injection molding cluster density:China's Guangdong province concentrates tooling expertise and export logistics for consumer goods brands, reducing lead times for custom thermoformed display packaging.
Market Restraints
- Post-consumer recycled PET supply scarcity:Collection infrastructure gaps in Southern Europe limit food-grade rPET availability, forcing converters to absorb price volatility or downgrade clarity specifications.
- Monomer input cost exposure:Paraxylene and ethylene glycol prices track crude oil futures, compressing margins for extrusion-based box producers without long-term feedstock contracts.
- Fiber-based transparent substitution:Molded pulp with cellulose windows and coated paperboard alternatives capture shelf-ready produce applications where optical clarity requirements relax.
Strategic Opportunities
- India organized retail expansion:Reliance Retail and D-Mart are standardizing clear clamshell specifications for private-label electronics and cosmetics, creating first-mover advantages for converters with BIS-certified operations.
- Chemical recycling infrastructure partnerships:Pyrolysis-based PET purification enables food-contact circularity beyond mechanical recycling limits, aligning with EU Green Deal targets for 2030 packaging recyclability.
- Direct-to-consumer unboxing experience design:E-commerce beauty brands specify hinged clear boxes with tamper-evident closures, displacing folding cartons in premium subscription channels.
Industry Challenges
- Multi-jurisdiction compliance synchronization:Simultaneous FDA 21 CFR migration testing, EFSA dossier preparation, and China's GB standards alignment extend product launch timelines by 8-14 months for global food brands.
- Thermoforming tooling capex intensity:Custom aluminum molds for deep-draw clamshells require six-figure investments with 12-week fabrication lead times, freezing out mid-volume entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Clear Plastic Boxes Market |
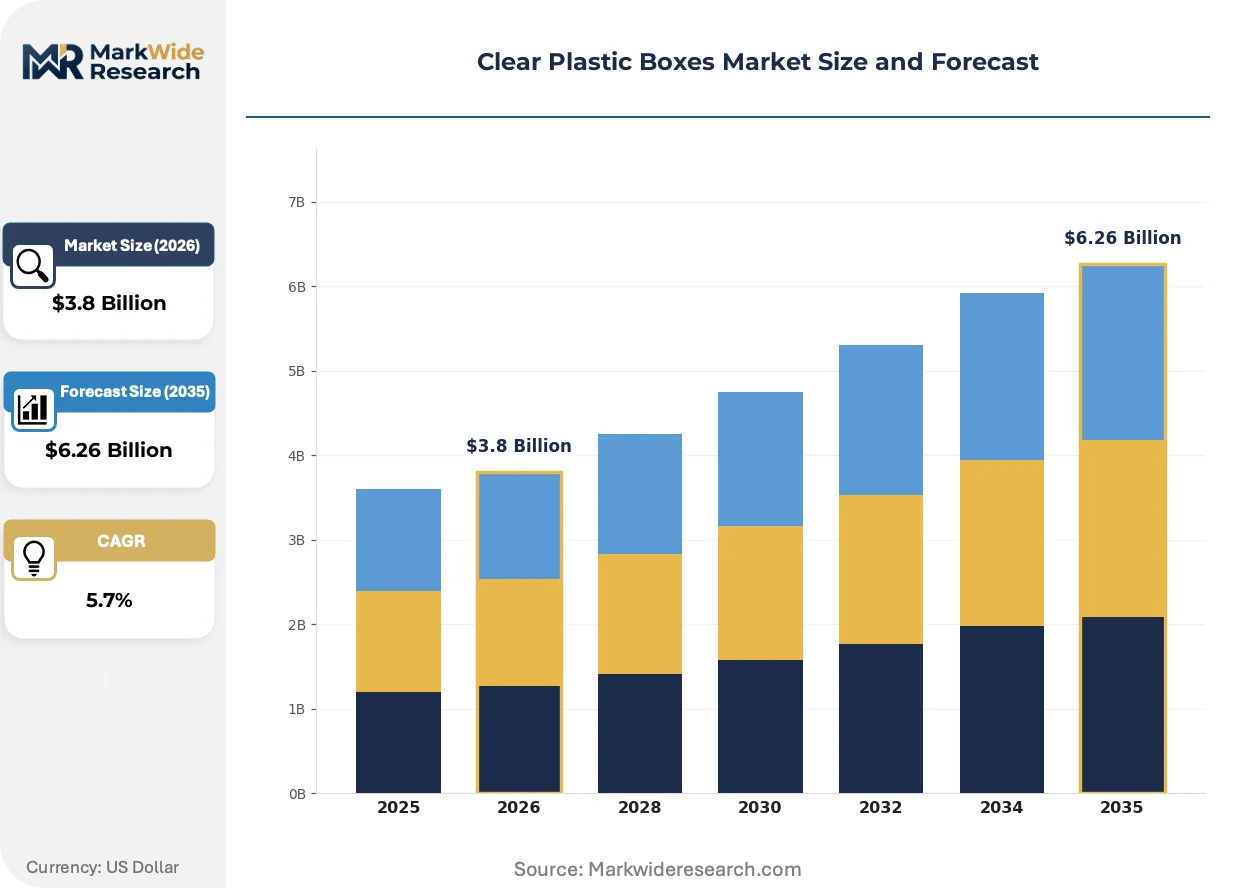
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Storage Containers, Display Boxes, Organizers, Food Packaging End User: Retail, Hospitality, Healthcare, Household Application: Food Storage, Product Display, Crafting, Medical Supplies Packaging Type: Recyclable, Biodegradable, Custom Printed, Standard |
| Companies Covered | Amcor, Smurfit Kappa, DS Smith, Placon, Uline, Transparent Packaging, Hip Lik Packaging, Berry Global, Gel-Pak, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Clear Plastic Boxes Market Strategic Shifts
Active materials science and regulatory chemistry are converging to redefine performance specifications for transparent rigid packaging, shifting competitive advantage from scale economies to formulation expertise and certification velocity.
Barrier-coated polyethylene terephthalate is consolidating oxygen transmission control in fresh protein and ready-meal segments. Retail deli counters in US and UK grocery chains specify sub-0.5 cc/m²/day OTR specifications. This material compression is eliminating multi-layer PP/EVOH structures from premium chilled applications.
REACH Annex XVII restrictions on intentionally added microplastics are triggering reformulation programs across European thermoforming operations. Compounders must certify biodegradability or demonstrate essential use exemptions for glitter and slip agents. Small-format cosmetic boxes face the steepest compliance cost escalation.
Brand-led packaging reduction mandates are compressing traditional box-to-product volume ratios. Unilever and L'Oréal specify right-sized clear containers with 15-20% material reduction versus legacy formats. This specification tightening is most visible in Western European mass-market cosmetics launches.
Clear Plastic Boxes Market Segmentation
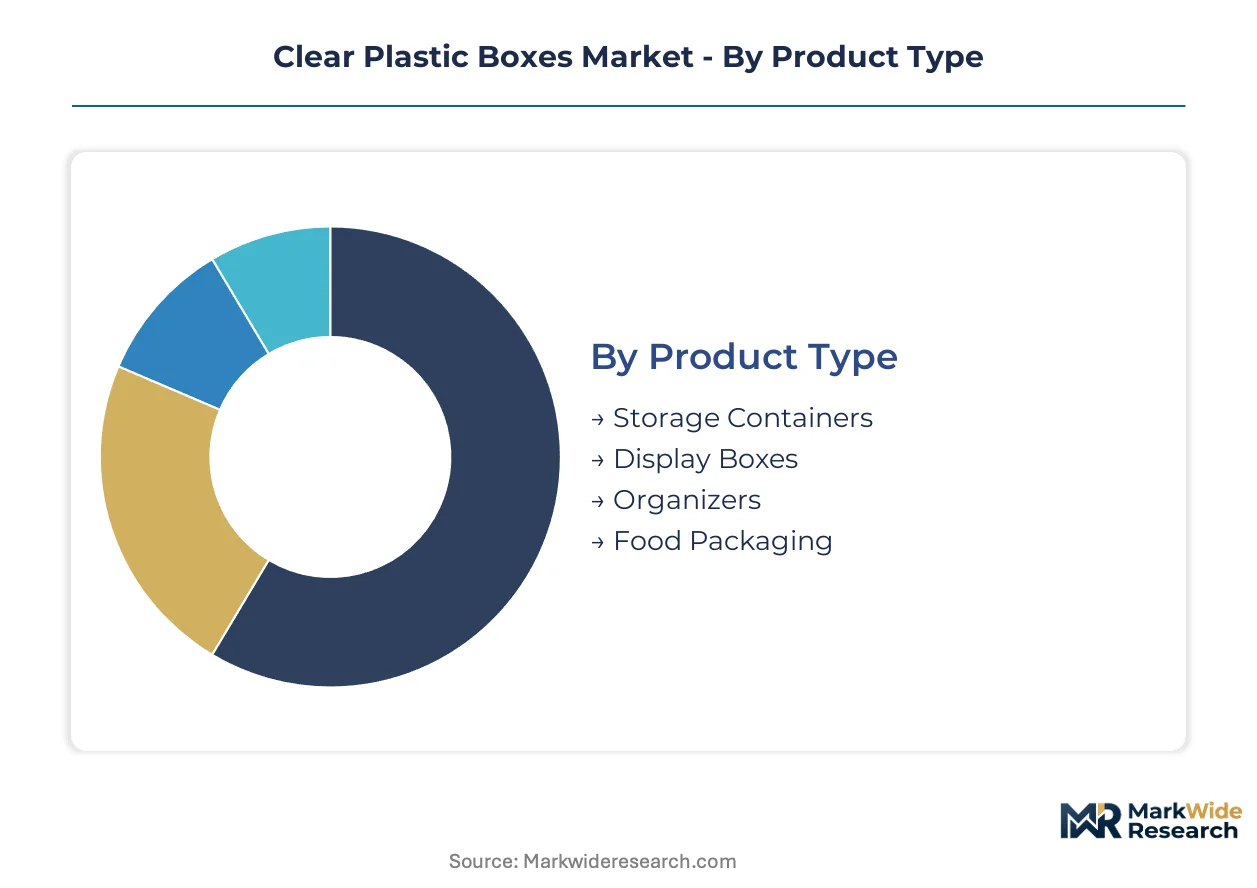
Segmentation in the Clear Plastic Boxes Market reveals divergent margin structures across visibility-driven versus protection-driven applications. Material specifications, regulatory compliance tiers, and end-use durability requirements create distinct procurement patterns that suppliers must navigate simultaneously.
Product Type:
Volume concentration sits with commodity storage functions, while premium capture attaches to merchandising visibility and specialized barrier properties.
- Storage Containers:Injection-molded PET and PP formulations dominate this segment, specified for 0.3-0.5 millimeter wall thicknesses in warehouse and household inventory management. Demand concentrates in China's Guangdong injection molding clusters serving export-oriented consumer goods brands with compressed lead times for high-volume orders.
- Display Boxes:Thermoformed PET clamshells and hinged containers deliver optical clarity above 90% light transmission for cosmetics and electronics retail presentation. German and French luxury brands specify these formats for point-of-sale conversion optimization, absorbing premium pricing for crystal-grade material and custom tooling.
- Organizers:Multi-compartment PP units serve craft, hardware, and small parts sorting with modular stackability features.
- Food Packaging:Oxygen barrier-coated PET expands most quickly in ready-meal and deli applications across US and UK grocery chains demanding sub-0.5 cc/m²/day OTR specifications.
Mature deployment sits with Storage Containers. Newer deployment is concentrated in Food Packaging.
End User:
Procurement scale separates institutional buyers with specification teams from household purchasers responding to shelf presence.
- Retail:Mass merchandisers and specialty chains drive standardization of clamshell dimensions for supply chain efficiency. Walmart and Target specify anti-theft features and tamper-evident closures that elevate unit costs against unprotected alternatives.
- Hospitality:Hotels and foodservice operators prioritize stackability and dishwasher durability in back-of-house storage applications.
- Healthcare:FDA 21 CFR compliance for sterilization compatibility and particulate control governs procurement for surgical kit and pharmaceutical logistics in US hospital networks.
- Household:Price-sensitive demand through big-box retail and e-commerce channels favors lighter-gauge PP over PET for closet and garage organization.
Specification intensity peaks with Healthcare. Volume scale concentrates in Retail.
Application:
Functional requirements span passive containment to active shelf-life extension, with material science differentiation determining supplier selection.
- Food Storage:Barrier-coated PET and emerging bio-based PP formulations address oxygen and moisture sensitivity in fresh protein and bakery segments. EFSA migration limits and REACH-compliant resin certification gate European market access for converters.
- Product Display:Electronics and cosmetics brands specify ionic-dissipative and UV-resistant grades for semiconductor wafer transport and luxury goods presentation in South Korean and Taiwanese manufacturing corridors.
- Crafting:Compartmentalized organizers with removable dividers serve hobbyist and educational supply chains with lower regulatory burden than food-contact applications.
- Medical Supplies:Sterile barrier packaging for surgical instruments and diagnostic components demands validated sealing processes and lot traceability systems.
Regulatory complexity clusters in Medical Supplies. Steepest expansion trajectory appears in Food Storage.
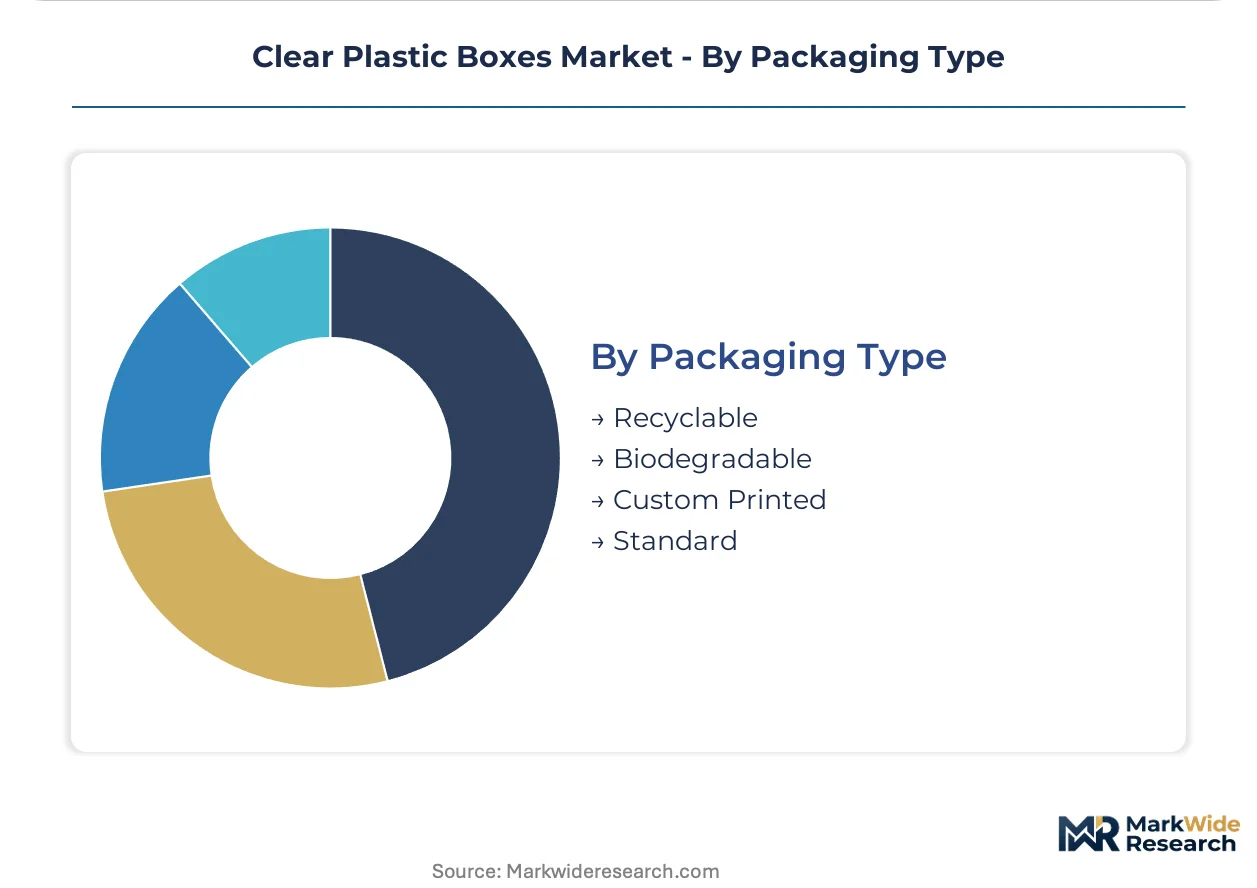
Packaging Type:
Sustainability certification tiers are restructuring supplier qualification criteria across European and North American procurement functions.
- Recyclable:Post-consumer recycled PET content grades certified under EU Packaging and Packaging Waste Regulation requirements command price premiums in French and German retail supply chains. Collection infrastructure gaps in Southern Europe constrain food-grade rPET availability.
- Biodegradable:PLA and PHA-based transparent formulations respond to REACH Annex XVII microplastic restrictions, though industrial composting infrastructure limitations temper volume scaling.
- Custom Printed:Solvent-free UV and water-based decoration systems reduce VOC emissions per EPA guidelines while enabling brand differentiation.
- Standard:Virgin PET and PS grades maintain cost competitiveness in price-sensitive channels without sustainability premiums.
Compliance investment concentrates in Recyclable. Emerging specification growth attaches to Biodegradable.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates injection molding capacity while the United States and Germany absorb premium branded volumes. Regulatory divergence between FDA migration limits and REACH-compliant resin certification fragments supplier qualification criteria across Atlantic trade lanes.
China
Guangdong province anchors export-oriented production for consumer goods packaging with compressed lead times. GB standards alignment with FDA 21 CFR migration testing gates North American food-contact market access. Shenzhen and Dongguan clusters specialize in anti-static clear boxes for semiconductor logistics serving South Korean and Taiwanese electronics manufacturers.
United States
Walmart and Target procurement teams standardize clamshell dimensions with tamper-evident closure specifications. EPA guidelines on VOC emissions from solvent-based printing operations constrain decoration processes in Midwest converting facilities. Chicago and Dallas distribution hubs consolidate mass retail channel supply with multi-site extrusion networks.
Germany
Luxury cosmetics brands in Hamburg and Düsseldorf specify crystal-grade PET display boxes with 90% plus light transmission. ECHA restrictions on phthalates under REACH Annex XVII accelerate bio-based PET reformulation across Bavarian thermoforming operations. Berlin-based retailers requalify supplier bases ahead of EU Packaging and Packaging Waste Regulation enforcement deadlines.
India
Reliance Retail and D-Mart private-label expansion drives standardization of clear clamshell specifications for electronics and cosmetics. BIS certification requirements for food-contact materials create compliance barriers for unorganized sector converters. Maharashtra and Gujarat injection molding corridors scale capacity for domestic organized retail penetration.
South Korea
Samsung and SK Hynix semiconductor fabrication facilities specify ionic-dissipative clear boxes with 0.1-millimeter dimensional tolerances for wafer transport. MFDS regulates food-contact migration limits parallel to FDA frameworks. Gyeonggi-do province clusters serve display packaging demand from Seoul-based beauty brand headquarters.
Clear Plastic Boxes Market Competitive Environment
The competitive structure tilts toward integrated resin-to-container converters with certified recycling infrastructure. Scale advantages concentrate among multi-site operators serving mass retail channels, while mid-volume specialists occupy premium niches demanding custom tooling velocity. Three archetypes dominate: integrated multinational converters with post-consumer recycled content pipelines, regional thermoforming specialists with proprietary mold capabilities, and Asia-Pacific export-oriented fabricators leveraging cluster density. Dominant competitive moves include chemical recycling infrastructure partnerships and backward integration into rPET flake purification.
Among integrated multinational converters, Amcor anchors post-consumer recycled content supply through European collection infrastructure, while Berry Global occupies a position across North American extrusion and thermoforming networks. Placon exemplifies the regional specialist archetype with proprietary tooling capabilities in foodservice clamshells. These three represent the spectrum from global scale to niche precision in transparent rigid packaging supply.
| Leading Market Players |
|---|
| Amcor |
| Smurfit Kappa |
| DS Smith |
| Placon |
| Uline |
| Transparent Packaging |
| Hip Lik Packaging |
| Berry Global |
| Gel-Pak |
| Others |
Value Chain & Pricing Dynamics
Mass retail procurement teams at Walmart and Target anchor North American demand for clear plastic boxes, imposing contract-based long-term offtake pricing that compresses margin flexibility for converters without scale. This buyer concentration forces tiered pricing stratification across premium crystal-grade PET, standard virgin formulations, and economy recycled-content tiers.
Pricing Analysis
Cost compression in standard-grade virgin PET intensifies as paraxylene and ethylene glycol prices track crude oil futures, squeezing extrusion-based producers lacking feedstock hedges. Three-tier pricing separates FDA-certified food-contact grades from industrial storage tiers and uncertified commodity boxes. Price differentiation hinges on EFSA migration certification and post-consumer recycled content percentages. Price sensitivity peaks among household purchasers through big-box channels, while healthcare and semiconductor logistics buyers absorb premiums for dimensional precision.
Supply Chain Analysis
Resin supply rests on petrochemical complexes in China, South Korea, and Saudi Arabia, with Guangdong injection molding clusters converting pellets to finished boxes for export markets. Raw material dependencies span paraxylene, ethylene glycol, and specialty ionic-dissipative additives for electronics applications. Single-source vulnerability concentrates in Southern European rPET collection infrastructure gaps. Distribution runs through mass retail consolidation centers in Chicago and Dallas, with direct-to-consumer e-commerce channels gaining share in cosmetics subscription boxes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Clear Plastic Boxes Market sits at a materials transition inflection, with barrier-coated PET and bio-based formulations displacing multi-layer PP/EVOH structures in fresh protein packaging.
For Market Incumbents: Cement leadership in post-consumer recycled content pipelines through European collection infrastructure partnerships before EU Packaging and Packaging Waste Regulation enforcement hardens. Prioritize chemical recycling offtake agreements to secure food-grade circularity beyond mechanical limits. Defend against fiber-based transparent substitution by emphasizing oxygen barrier performance in ready-meal segments. For New Entrants and Emerging Players: REACH Annex XVII restrictions on intentionally added microplastics in Europe open a window for PLA and PHA-based biodegradable formulations in small-format cosmetic boxes. Target India's organized retail expansion through BIS-certified operations serving Reliance Retail and D-Mart private-label specifications. Lead with direct-to-consumer unboxing experience design for e-commerce beauty brands demanding hinged clear boxes with tamper-evident closures. For Investors and Strategic Acquirers: The window for entry favors regional thermoforming specialists with proprietary aluminum mold capabilities and certified food-contact operations in undersupplied geographies. Long-term viability hinges on backward integration into rPET flake purification or pyrolysis-based chemical recycling infrastructure. Watch EU Green Deal packaging recyclability target acceleration as the signal for valuation inflection in circularity-enabling assets.| Strategic Initiative | Industry Significance |
|---|---|
| Chemical Recycling Infrastructure Partnership | Pyrolysis-based PET purification enables food-contact circularity beyond mechanical recycling limits, aligning with EU Green Deal targets. |
| Barrier-Coated PET Capacity Expansion | Sub-0.5 cc/m²/day OTR specifications capture ready-meal and deli segments in US and UK grocery chains. |
| Proprietary Thermoforming Tooling Investment | Custom aluminum molds with 12-week fabrication velocity secure premium cosmetics and electronics display contracts. |
| Post-Consumer Recycled Content Pipeline | European collection infrastructure integration commands price premiums under EU Packaging and Packaging Waste Regulation. |
| Direct-to-Consumer Channel Development | E-commerce beauty brand specifications for unboxing experience displace folding cartons in premium subscription channels. |
Study Parameters
Independent corroboration across injection molding plant managers, retail category buyers, resin procurement leads, and thermoforming R&D directors underwrites the qualitative findings. Secondary validation draws from customs trade data, SEC filings of packaging converters, ECHA restriction dossiers, and FDA 21 CFR migration testing records. Bottom-up demand modeling across end-use applications triangulates against top-down resin consumption estimates from petrochemical industry associations.
Rate-of-change decomposition separates volume growth from price realization effects across the projection horizon. Segmentation dimensions span product type, end user, application, packaging type, and regional regulatory cluster. CAGRs derive from curve-fitting historical shipment data against identified catalyst trajectories. Forecast inputs incorporate injection molding cluster capacity utilization, rPET collection infrastructure buildout timelines, and REACH-compliant resin reformulation adoption curves.
The model assumes a particular technology adoption path; alternative pathways for chemical recycling scale-up would alter the outlook for mechanical recycling incumbents. Forecasts reflect assumptions on EU enforcement timelines, crude oil price corridors, and fiber-based substitution elasticity. A small set of triggers—MFDS migration limit tightening, BIS certification acceleration, and anti-static specification proliferation in semiconductor logistics—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plastic Packaging
MENA Thermoform Plastic Packaging Market
Plastic Packaging
United States PET Packaging Market
Plastic Packaging
Mushroom Plastics Market
Plastic Packaging
Plastic Cans Market
Plastic Packaging
Europe Plastic Packaging Market
Plastic Packaging
Egypt Plastic Packaging Market
Plastic Packaging
Plastic Cutlery Market
Plastic Packaging
United States Plastic Bottles Market
Plastic Packaging
Blow Moulded Plastic Packaging Market
Plastic Packaging
Canada Plastic Packaging Market
Plastic Packaging
Folding Plastic Crates Market
Plastic Packaging
Global Stretch Films Market
Plastic Packaging
Plastic Bottles and Containers Market
Plastic Packaging
Plastic Ready Meal Trays Market
Plastic Packaging
PET Preforms Market
Plastic Packaging
South America Polyethylene Terephthalate (PET) Market