
 CPET Trays Market | 2026-2036
CPET Trays Market Size, Share, and Industry Trends Forecast 2026-2036
CPET Trays Market Outlook
China is reconfiguring its thermoforming capacity through automated CPET tray lines serving export-oriented food processors. Sealed Air Corporation leverages its Cryovac technology heritage to dominate high-barrier CPET applications for protein packaging. Huhtamaki Oyj anchors European supply through its Faerch subsidiary, which specializes in closed-loop rPET tray production. Genpak, LLC competes in North American foodservice channels with standardized compartment designs for institutional buyers.
Crystallized polyethylene terephthalate (CPET) trays combine amorphous PET clarity with crystallized heat resistance up to 220°C, enabling direct oven-to-table functionality for prepared foods and laboratory sterilization cycles. Multi-compartment configurations capture premium positioning in ready-meal packaging where sauce-pasta-protein separation commands shelf price advantages. Food manufacturers represent the dominant end-user channel, though pharmaceutical companies are expanding CPET adoption for temperature-stable clinical sample storage. Material-grade segmentation shows rCPET gaining share against virgin resin as EFSA clearance for food-contact recycled content broadens supplier qualification pools.
The EU F-Gas Regulation and REACH chemical restrictions constrain fluorinated barrier coatings, pushing converters toward plasma-enhanced SiOx or AlOx deposition technologies. FDA food-contact substance notifications govern US market entry for novel CPET additives, while China's GB standards mandate heavy-metal thresholds for export-bound trays. Stakeholders must monitor polymer feedstock volatility and evolving extended-producer-responsibility schemes that will reshape tray economics and collection infrastructure requirements.
Market Dynamics
EU Packaging and Packaging Waste Regulation mandates are compressing acceptable material inputs for single-use food containers, forcing converters to requalify barrier coatings and accelerate closed-loop collection infrastructure investments.
Growth Catalysts
- EFSA rPET Clearance:Expanded food-contact approvals for recycled polyethylene terephthalate are broadening supplier qualification pools and reducing virgin resin dependency for tray manufacturers.
- Germany:Centralized retail distribution networks favor standardized multi-compartment tray formats, creating volume pull for CPET ready-meal packaging across European supermarket chains.
- Plasma-Enhanced Deposition:SiOx and AlOx barrier technologies are displacing fluorinated coatings constrained by REACH chemical restrictions, opening new compliance pathways for high-barrier applications.
Market Restraints
- Polymer Feedstock Volatility:Crude oil price fluctuations transmit directly to virgin PET resin costs, compressing converter margins and destabilizing long-term contract pricing.
- China Thermoforming Concentration:Automated CPET line capacity clusters in export-oriented manufacturing zones, creating geographic supply risk and freight cost exposure for distant buyers.
- Aluminum Substitution:Foil trays retain cost advantages in price-sensitive institutional foodservice channels, limiting CPET penetration in cafeteria and hospital segments.
Strategic Opportunities
- Pharmaceutical Cold Chain:Temperature-stable clinical sample storage applications represent an underpenetrated end-use vertical with premium pricing tolerance and regulatory barrier entry.
- Extended Producer Responsibility:EU-wide EPR scheme implementation is mandating tray collection infrastructure investment, creating first-mover advantages for vertically integrated rPET producers.
- Dual-Oven Compatibility:Conventional microwaveable trays face displacement as CPET crystallization processes enable simultaneous microwave and conventional oven performance without material degradation.
Industry Challenges
- Barrier Coating Requalification:FDA food-contact substance notification timelines for novel SiOx additives extend 18-24 months, delaying product launches and freezing R&D roadmaps.
- Multi-Compartment Tooling:Complex thermoform molds for sauce-pasta-protein separation require capital-intensive precision engineering, elevating break-even volumes for new product introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | CPET Trays Market |
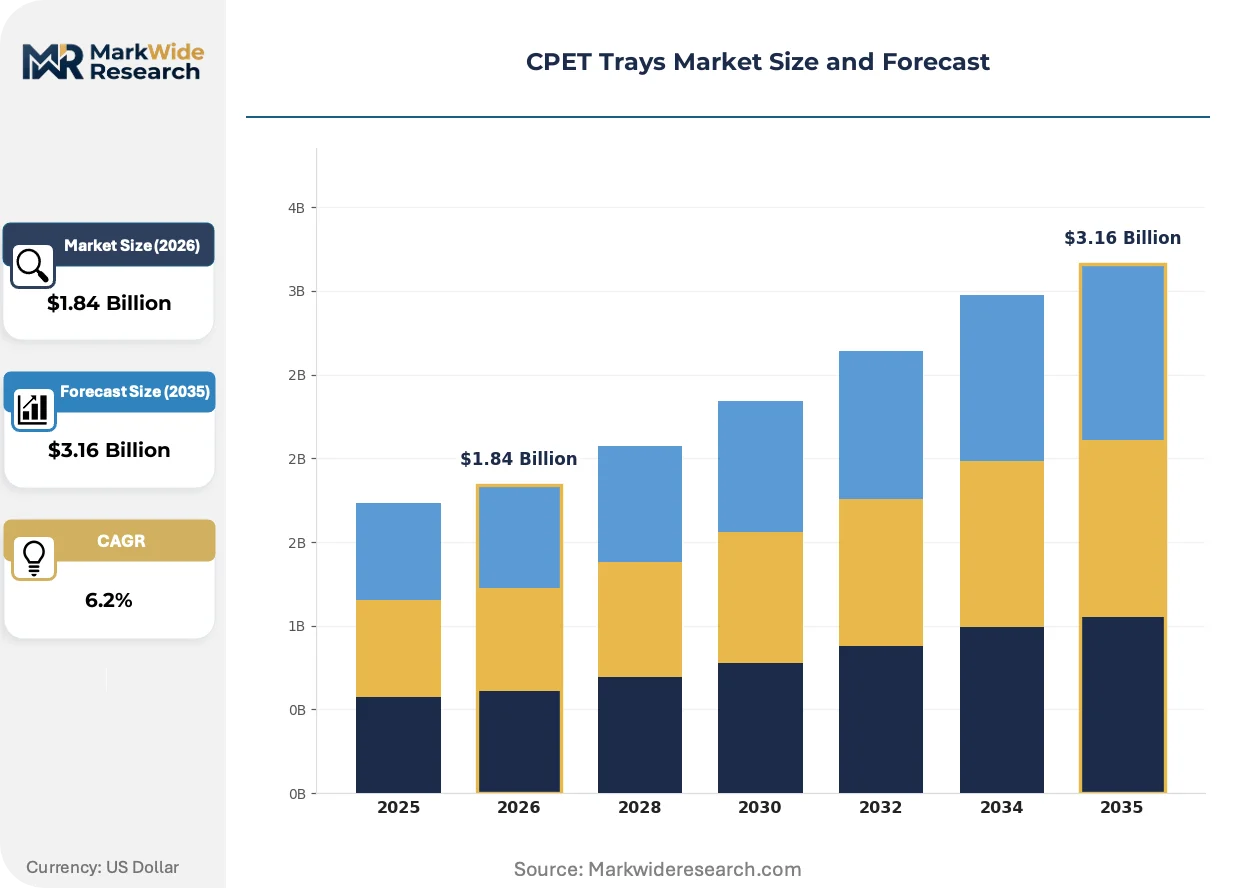
| Market Size in 2026 | $1.84 Billion |
| Market Size in 2035 | $3.16 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Compartment, Multi-Compartment, Microbiological, Customizable End User: Food Manufacturers, Pharmaceutical Companies, Research Laboratories, Retailers Application: Food Packaging, Sample Storage, Laboratory Testing, Medical Waste Management Material: CPET, PET, Polypropylene, Bioplastic |
| Companies Covered | Sealed Air Corporation, Huhtamaki Oyj, Faerch A/S, Lacerta Group, Inc., Pactiv LLC, Bemis Company, Inc., Genpak, LLC, Coveris Holdings S.A., Sonoco Products Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
CPET Trays Market Strategic Shifts
Barrier coating chemistry and crystallization process control are converging to expand CPET functional range, while regulatory chemical restrictions and buyer sustainability mandates reshape competitive positioning.
Plasma-enhanced chemical vapor deposition is hybridizing barrier performance with fluorine-free compliance. Food manufacturers in protein packaging segments are adopting SiOx-coated trays at accelerating rates as EFSA and FDA clearance pathways mature. This deposition technology is compressing the addressable market for conventional high-barrier laminates while enabling oven-to-table functionality in extended shelf-life applications.
EU F-Gas Regulation phase-down schedules are eliminating perfluorinated compound use in food-contact barriers by 2030. Thermoforming converters face forced technology transition timelines, with AlOx deposition systems requiring 12-18 month installation and qualification cycles. Ready-meal packaging for German and French retail channels bears the highest compliance burden, driving early plasma equipment commitments from major European suppliers.
Retail procurement consolidation is compressing supplier qualification cycles and unbundling tray specification from full packaging system contracts. Centralized buying desks at pan-European supermarket groups now mandate rPET content minimums and mass-balance certification, displacing fragmented regional purchasing. This concentration is most visible in German discount retail, where standardized tray formats now dominate private-label ready-meal introductions.
CPET Trays Market Segmentation
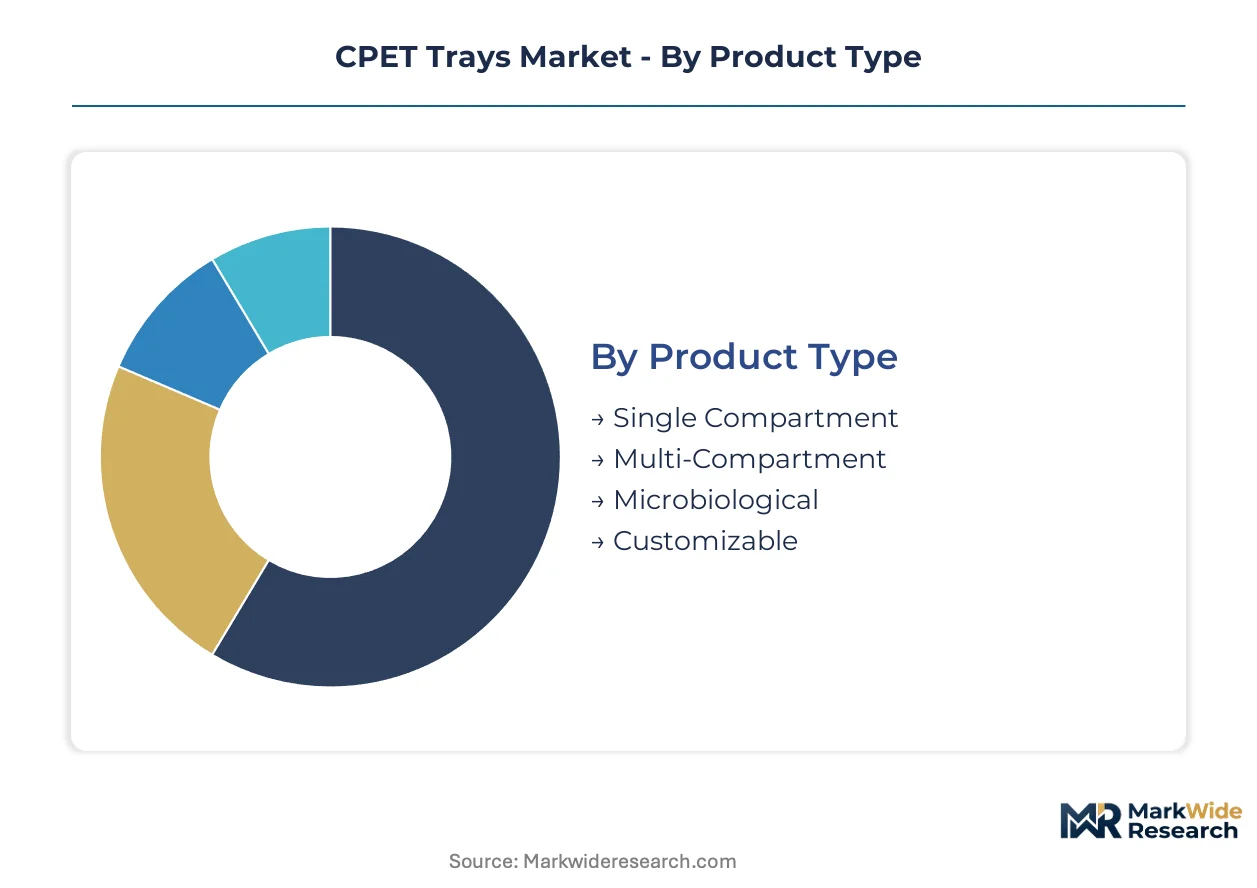
CPET tray specifications diverge sharply across end-use requirements, with crystallization grades, barrier coatings, and compartment geometries commanding distinct tooling investments and qualification timelines. Material-grade selection and regulatory clearance pathways segment supplier capabilities more than volume scale.
Product Type:
After-sales service intensity varies dramatically by compartment complexity, with multi-cavity molds requiring precision maintenance programs and rapid spare-part availability to minimize food processor downtime.
- Multi-Compartment:Sauce-pasta-protein separation configurations utilize precision-engineered thermoform molds with integrated crystallization zones. German supermarket chains specify these formats for private-label ready-meal lines where shelf price premiums justify tooling amortization across high-volume contracts.
- Single Compartment:Standardized formats dominate institutional foodservice procurement with lower unit economics and faster mold changeover cycles. Aluminum substitution pressure concentrates in this segment within North American hospital and cafeteria channels.
- Microbiological:Sterilization-grade trays for laboratory autoclave cycles feature enhanced crystallization density and dimensional stability protocols.
- Customizable:Tool-on-demand configurations serve regional food brands requiring rapid format iteration without capital-intensive dedicated molds.
By volume, Single Compartment leads. By growth pace, Multi-Compartment is expanding most quickly.
End User:
Customer procurement sophistication stratifies the vendor base, with pharmaceutical buyers demanding batch traceability and food manufacturers prioritizing line-speed compatibility.
- Food Manufacturers:Protein packagers and ready-meal processors specify high-barrier SiOx-coated trays for extended shelf-life applications. EFSA rPET clearance is broadening supplier qualification pools for these buyers across European centralized retail distribution networks.
- Pharmaceutical Companies:Temperature-stable clinical sample storage represents an underpenetrated vertical with premium pricing tolerance. FDA food-contact substance notification requirements for novel additives create 18-24 month entry barriers.
- Research Laboratories:Autoclave sterilization cycles demand CPET grades with crystallization thresholds above 200°C.
- Retailers:Pan-European supermarket buying desks now mandate rPET content minimums and mass-balance certification, consolidating supplier bases.
Food Manufacturers capture the largest revenue share. Pharmaceutical Companies are climbing the fastest as cold-chain applications mature.
Application:
Functional performance requirements determine barrier technology selection, with oxygen transmission rate specifications varying by shelf-life target and storage temperature.
- Food Packaging:Oven-to-table functionality drives crystallized PET adoption over conventional microwaveable alternatives. Plasma-enhanced SiOx deposition is displacing fluorinated coatings constrained by EU F-Gas Regulation phase-down schedules.
- Sample Storage:Clinical specimen integrity demands thermal stability across freeze-thaw cycles and chemical resistance to preservatives.
- Laboratory Testing:Sterilization compatibility and optical clarity for automated imaging systems define material specifications.
- Medical Waste Management:Puncture resistance and autoclave durability prioritize structural integrity over barrier performance.
Food Packaging dominates current volumes. Sample Storage shows the steepest expansion trajectory as biobank infrastructure investment accelerates.
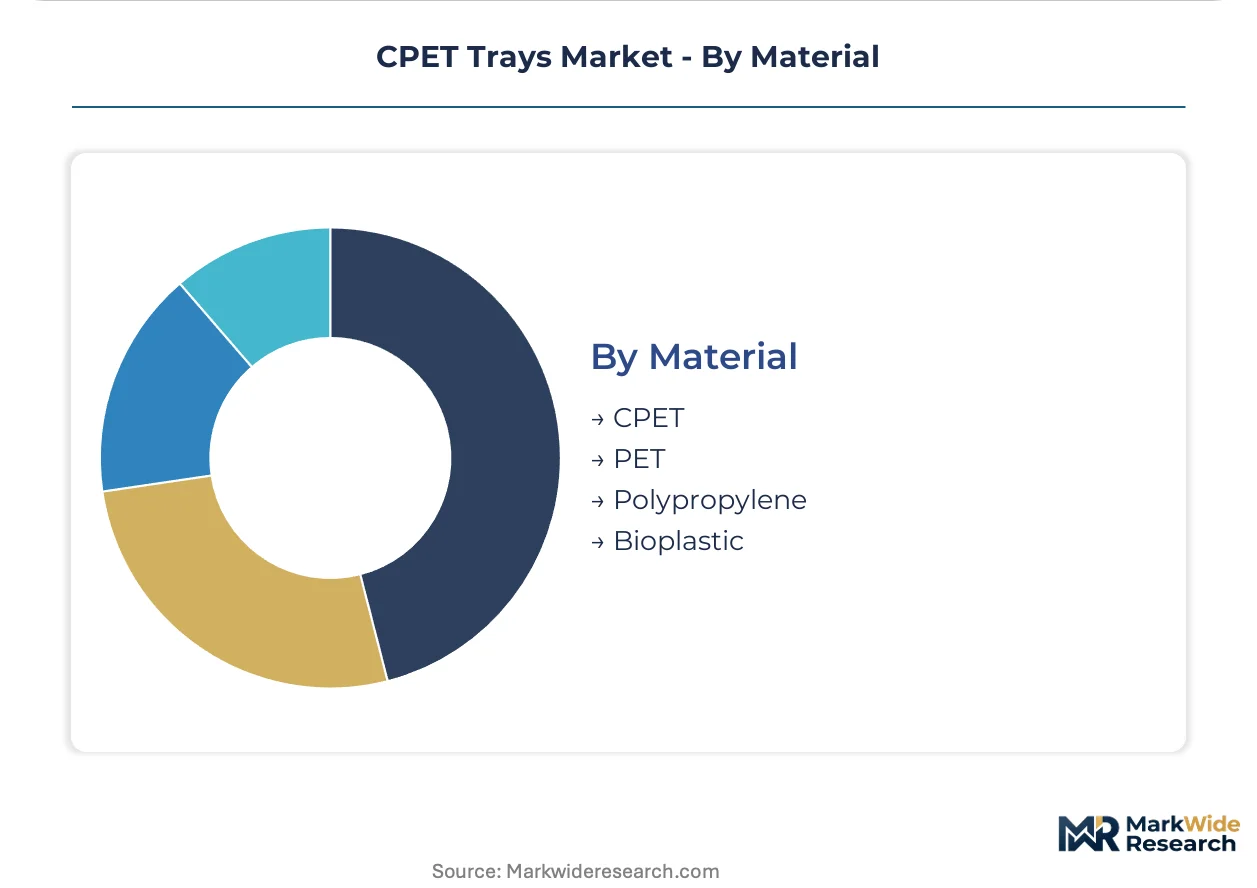
Material:
Feedstock volatility and circular economy mandates are reshaping material economics, with recycled content qualification becoming a competitive differentiator.
- rCPET:Post-consumer recycled polyethylene terephthalate with EFSA food-contact clearance reduces virgin resin dependency. Closed-loop collection infrastructure investments by vertically integrated producers are securing qualified feedstock streams ahead of EU Extended Producer Responsibility mandates.
- Virgin CPET:Controlled crystallization processes deliver consistent optical clarity and heat resistance for premium ready-meal applications where batch uniformity commands specification adherence.
- PET:Amorphous grades lack oven compatibility but serve cost-sensitive microwave-only segments.
- Polypropylene:Lower barrier performance limits penetration in protein packaging despite processing advantages.
- Bioplastic:PLA and starch-based alternatives face heat resistance ceilings below CPET crystallization thresholds.
Virgin CPET leads by current shipment volume. rCPET is gaining share fastest as EFSA clearance broadens and collection infrastructure matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany consumes multi-compartment CPET trays for centralized retail ready-meals, while China deploys identical material grades for export-oriented protein packaging bound for distant markets. This consumption-mix differential shapes divergent supply chain configurations and regulatory compliance burdens across manufacturing geographies.
Germany
Discount retail chains specify standardized multi-compartment formats for private-label ready-meal introductions. The EU Packaging and Packaging Waste Regulation mandates closed-loop collection infrastructure investments by 2030. Thermoforming converters in North Rhine-Westphalia cluster near centralized distribution hubs serving pan-European supermarket buying desks.
China
Export-oriented food processors drive automated CPET line capacity expansion for protein packaging bound for North American and European buyers. GB standards enforce heavy-metal thresholds for export-bound trays. Manufacturing gravity concentrates in Yangtze River Delta thermoforming zones serving international brand owners.
United States
Institutional foodservice channels favor standardized single-compartment formats for hospital and cafeteria procurement. FDA food-contact substance notifications govern novel additive introductions, extending qualification timelines. Midwestern converters supply protein packagers with high-barrier specifications for extended shelf-life applications.
France
Ready-meal processors adopt SiOx-coated trays as EFSA clearance pathways mature for plasma-enhanced deposition. The EU F-Gas Regulation phase-down eliminates perfluorinated compound use in food-contact barriers by 2030. Industrial clusters in Île-de-France accelerate AlOx equipment installation ahead of compliance deadlines.
India
Domestic food manufacturers pilot CPET adoption for premium ready-meal segments targeting urban retail modernization. FSSAI food-contact regulations govern imported packaging material qualifications. Maharashtra-based converters evaluate rPET feedstock streams as EFSA clearance precedents inform local regulatory expectations.
CPET Trays Market Competitive Environment
Capability concentration sits with specialized barrier-coating developers; scale advantage sits with diversified packaging conglomerates. The vendor base stratifies across three tiers: integrated rPET producers controlling closed-loop collection, high-barrier technology licensors, and regional thermoforming specialists serving fragmented foodservice accounts. Dominant competitive moves include backward integration into rPET flake production and strategic partnerships with plasma deposition equipment suppliers.
Within the diversified packaging tier, Sealed Air Corporation and Huhtamaki Oyj occupy positions reflecting distinct geographic anchoring and technology heritage. Sealed Air represents North American high-barrier capability, while Huhtamaki exemplifies European closed-loop rPET integration through its Faerch subsidiary structure. Genpak, LLC sits within the North American foodservice specialist archetype, competing on standardized compartment designs for institutional procurement channels.
| Leading Market Players |
|---|
| Sealed Air Corporation |
| Huhtamaki Oyj |
| Faerch A/S |
| Lacerta Group, Inc. |
| Pactiv LLC |
| Bemis Company, Inc. |
| Genpak, LLC |
| Coveris Holdings S.A. |
| Sonoco Products Company |
| Others |
Value Chain & Pricing Dynamics
Yangtze River Delta port congestion transmits freight cost volatility directly to European food manufacturers, compressing converter margins while amplifying price differentiation between virgin CPET and rCPET grades. This logistics corridor's cost dynamics concentrate pricing power among vertically integrated rPET producers with captive flake supply, leaving spot-market dependent converters exposed to polymer feedstock swings.
Pricing Analysis
Long-term offtake agreements dominate procurement between major European retailers and tier-one thermoforming converters, locking volume commitments across multi-year horizons while spot transactions serve fragmented foodservice accounts. Three-tier pricing structure across premium, standard, and economy levels separates SiOx-coated multi-compartment trays from single-cavity microwave-only formats and aluminum-substitute institutional grades. Cost compression in the single-compartment tier intensifies because aluminum foil retains cost advantages in price-sensitive hospital and cafeteria channels. Institutional buyers exhibit highest price sensitivity; pharmaceutical cold-chain adopters demonstrate lowest.
Supply Chain Analysis
Extended payment terms from pan-European supermarket buying desks now stretch 90-120 days, forcing mid-tier converters toward supply-chain finance facilities anchored by receivables from Faerch and Sealed Air. Manufacturing gravity concentrates in China, Germany, and the United States, with Yangtze River Delta thermoforming zones feeding export-oriented protein packaging. Feedstock streams draw from virgin PET resin, post-consumer rPET flake, and plasma deposition precursor chemicals. Single-source vulnerability concentrates in fluorinated barrier coating supply chains facing REACH phase-out deadlines. Distribution runs through centralized retail distribution hubs in North Rhine-Westphalia serving German discount chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Plasma-enhanced barrier deposition represents a high-growth disruption as EU F-Gas Regulation deadlines force technology transition across ready-meal packaging by 2030.
For Market Incumbents: Entrench closed-loop rPET collection infrastructure ahead of Extended Producer Responsibility mandates, securing qualified feedstock streams that lock out spot-market competitors. Accelerate AlOx equipment installation cycles in Île-de-France and North Rhine-Westphalia clusters to capture compliance-driven demand from French and German retail channels. Aluminum substitution in institutional foodservice poses margin pressure requiring defensive cost engineering.
For New Entrants and Emerging Players: Establish a beachhead in pharmaceutical cold-chain sample storage, where temperature-stable clinical applications carry premium pricing tolerance and FDA notification barriers deter incumbent expansion. Target microbiological sterilization-grade trays for laboratory autoclave cycles, a niche with enhanced crystallization density requirements and limited qualified supply. Pursue partnership licensing with plasma deposition equipment suppliers rather than capital-intensive in-house barrier development.
For Investors and Strategic Acquirers: Specialized barrier-coating developers with EFSA-cleared SiOx processes command scarcity premia as fluorinated coating phase-outs accelerate. Long-term viability hinges on backward integration into rPET flake production securing feedstock independence from virgin resin volatility. Watch EFSA clearance expansion timelines for post-consumer recycled content as the inflection signal for supplier qualification pool broadening.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into rPET Flake Production | Captive feedstock supply insulates margin compression from oil-linked virgin resin volatility. |
| Plasma Deposition Equipment Partnership | AlOx and SiOx barrier licensing accelerates compliance pathways ahead of EU F-Gas deadlines. |
| Multi-Compartment Mold Precision Engineering | Sauce-pasta-protein separation tooling commands shelf price premiums in German retail. |
| Pharmaceutical Cold-Chain Certification Investment | FDA food-contact substance notification unlocks temperature-stable clinical sample storage vertical. |
| Extended Producer Responsibility Infrastructure Buildout | Closed-loop collection mandates by EU Packaging and Packaging Waste Regulation create first-mover advantage. |
Study Parameters
Cross-validation between primary interviews and secondary regulatory filings anchors the qualitative findings on barrier coating transition timelines. Conversations with thermoforming plant managers, supermarket category buyers, pharmaceutical packaging engineers, and EFSA regulatory affairs specialists informed supply-side capacity and demand-side specification evolution. Secondary sources include EU Packaging and Packaging Waste Regulation implementation texts, EFSA scientific opinions on rPET food-contact clearance, FDA food-contact substance notification databases, and Yangtze River Delta customs export records. Bottom-up tray shipment data from converter disclosures triangulates against top-down ready-meal packaging demand estimates.
Calibration against historical crystallization process adoption curves and barrier technology substitution patterns shapes the projection framework across the analysis window. Segmentation dimensions model material grade, compartment geometry, barrier coating chemistry, end-use vertical, and geographic regulatory cluster. CAGRs derive from fitted growth curves adjusted for EPR mandate implementation phasing and plasma equipment installation cycle durations. Feedstock volatility scenarios and EFSA clearance expansion timelines constitute industry-specific forecast inputs.
Sensitivities concentrate around EU F-Gas Regulation enforcement intensity, EFSA rPET clearance breadth, and polymer feedstock price trajectories. Forecasts reflect documented assumptions on technology transition timelines and collection infrastructure buildout rates. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plastic Packaging
FFS Rigid Films Market
Plastic Packaging
Blow Molded Plastics Market
Plastic Packaging
Global Stretch Films Market
Plastic Packaging
Asia-Pacific Plastic Bottles and Containers Market
Plastic Packaging
United Kingdom Plastic Packaging Market
Plastic Packaging
China Plastic Packaging Market
Plastic Packaging
United Kingdom Plastic Bottles Market
Plastic Packaging
Vietnam Plastic Bottles Market
Plastic Packaging
Plastic Sterilization Trays Market
Plastic Packaging
Europe Plastic Packaging Market
Plastic Packaging
Malaysia and Thailand Thermoformed Plastic Market
Plastic Packaging
North America PET Bottle Market
Plastic Packaging
Asia Pacific Single-Use Plastic Packaging Market
Plastic Packaging
Canada Plastic Bottles Market
Plastic Packaging
South Africa Flexible Plastic Packaging Market
Plastic Packaging
Egypt Plastic Bottles Market