
 Philippines Plastics Market | 2026-2036
Philippines Plastics Market Size, Share, and Industry Trends Forecast 2026-2036
Philippines Plastics Market Analytics
Buyer concentration among large-format packaging converters is hardening across the Philippines, squeezing mid-tier resin distributors on volume terms and payment cycles. JG Summit Petrochemicals Group leverages its Bataan refinery integration to supply captive polyethylene streams to affiliated downstream operations. D&L Industries anchors the specialty compounds segment through its Batangas blending facilities serving multinational food brands. NPC Alliance Corporation competes on recycled-content formulations, positioning its Calabarzon plants to capture EPR-driven procurement mandates.
Philippines plastics comprise synthetic or semi-synthetic organic polymers formulated from petrochemical feedstocks or biomass-derived monomers, typically processed through extrusion, injection molding, or blow molding into shapes with specified melt flow indices and tensile properties. These materials serve as lightweight, corrosion-resistant substitutes for metal, glass, and wood across industrial and consumer applications. Polyethylene dominates resin consumption through its dominance in flexible packaging films and sachet laminates for the archipelago's fragmented retail economy. Polypropylene captures expanding share in rigid containers and automotive interior components as Thai and Japanese OEMs localize parts sourcing. Construction-grade polyvinyl chloride maintains steady offtake for piping systems amid government irrigation and housing programs.
The Philippines' Department of Environment and Natural Resources enforces Extended Producer Responsibility regulations compelling brand owners to recover plastic packaging waste, while the Bureau of Product Standards mandates compliance with PNS ISO 9001 for imported resin grades. The central bank's sustainable finance framework channels credit toward recycling infrastructure, tightening market access for virgin-only suppliers. Stakeholders must monitor enforcement timelines for recycled-content minimums and calibrate feedstock sourcing between naphtha-derived and chemically recycled streams.
Market Dynamics
Extended Producer Responsibility mandates from the Department of Environment and Natural Resources are compressing virgin resin demand while chemically recycled feedstock capacity struggles to scale, forcing converters to renegotiate supply agreements mid-contract.
Growth Catalysts
- EPR Compliance Deadlines:The Philippines' Extended Producer Responsibility law obligates brand owners to recover plastic packaging waste, redirecting procurement budgets toward post-consumer resin suppliers with certified recycling streams.
- Food Processing Expansion:Luzon-based agribusiness clusters are expanding flexible packaging orders for polyethylene films to serve export-oriented seafood and fruit processing operations.
- Chemical Recycling Pilot Programs:Pyrolysis-based plastic-to-plastic conversion is attracting development capital from Japanese trading houses targeting Calabarzon industrial zones for feedstock supply security.
Market Restraints
- Naphtha Price Volatility:JG Summit Petrochemicals Group's Bataan refinery and regional spot markets expose converters to feedstock cost swings that compress margin buffers on fixed-price packaging contracts.
- Mechanical Recycling Contamination Rates:Domestic collection infrastructure yields post-consumer polyethylene with moisture and label residue levels that exceed specifications for food-contact applications without additional washing investment.
- Biopolymer Cost Premium:Polylactic acid and polyhydroxyalkanoate resins trade at multiples of conventional polyethylene, limiting penetration beyond premium cosmetic and pharmaceutical sachet segments.
Strategic Opportunities
- Mindanao Industrial Corridor:Davao City's emerging manufacturing belt lacks established resin distribution networks, creating first-mover positioning for compounders with regional blending capabilities.
- Automotive Localization:Thai and Japanese OEMs are qualifying polypropylene interior components from Philippine molders, opening specification-grade compound demand previously served by Thai imports.
- Digital Procurement Platforms:B2B marketplaces connecting Calabarzon converters directly to Singapore and Taiwan resin traders are compressing distributor margins and enabling spot-volume arbitrage.
Industry Challenges
- Polymer Processing Technician Shortage:Batangas and Cavite facilities report unfilled positions for extrusion line operators with melt flow index calibration and blown-film gauge control competencies.
- Recycled-Content Certification Timelines:Bureau of Product Standards PNS ISO 9001 compliance documentation for imported post-consumer resin batches delays customs clearance by three to six weeks.
- Legacy Sachet Lamination Equipment:Metro Manila converters face stranded asset risk as multilayer barrier structures fall out of favor under EPR recyclability scoring protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Philippines Plastics Market |
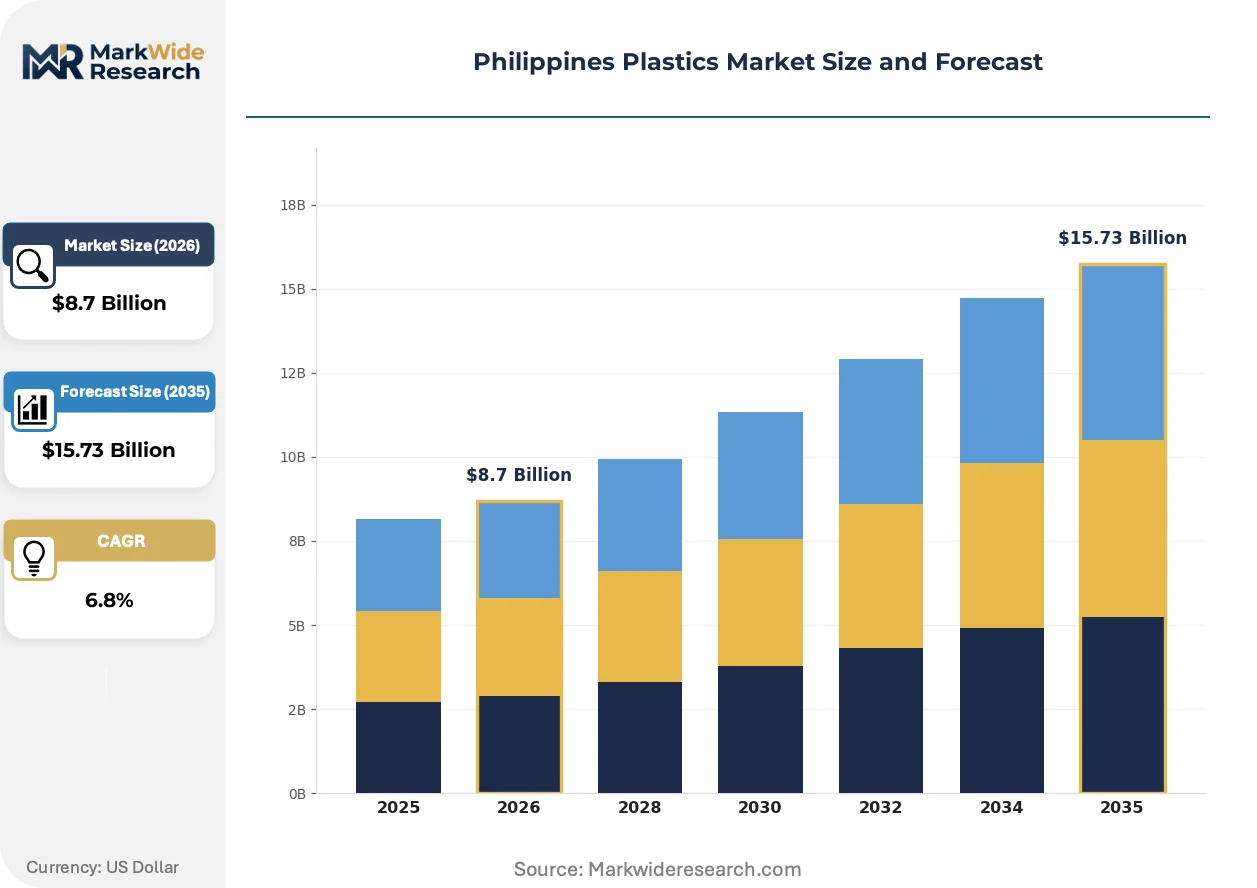
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene, Polypropylene, Polyvinyl Chloride, Polystyrene Application: Packaging, Construction, Automotive, Consumer Goods End User: Manufacturers, Retailers, Wholesalers, Exporters Distribution Channel: Direct Sales, Online Retail, Distributors, Dealers |
| Companies Covered | NPC Alliance Corporation, D&L Industries, JG Summit Petrochemicals Group, DuPont, Nan Ya Plastics, Chemrez Technologies, Philippine Resins Industries, LyondellBasell, Petron Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Philippines Plastics Market Evolving Landscape
Decentralized pyrolysis units and digital traceability platforms are fragmenting the traditional refinery-to-converter supply hierarchy, while EPR scoring methodologies rewrite material specification priorities across Philippine packaging procurement.
Small-scale chemical recycling using modular pyrolysis reactors is decentralizing feedstock recovery from centralized mechanical recycling plants. Food-grade polyethylene producers in Calabarzon are piloting 500-tonne annual units to process contaminated agricultural film on-site. This distributed model collapses collection logistics costs for remote farming cooperatives while bypassing Manila-centric baling infrastructure.
The Department of Environment and Natural Resources' EPR implementing rules and regulations are tightening recycled-content verification requirements. Brand owners must submit third-party audited recovery certificates to maintain product registration. Multinational FMCG distributors operating in Metro Manila are accelerating supplier audits to preempt enforcement actions anticipated during the 2026 compliance review cycle.
Buyer concentration among large-format retail chains is compressing payment terms for resin distributors. Puregold and SM Retail procurement teams now demand 90-day credit windows and volume rebates that squeeze mid-tier compounders without captive banking relationships. Cebu-based packaging converters report switching to direct import arrangements with Singapore traders to circumvent distributor financing markups.
Philippines Plastics Market Segmentation
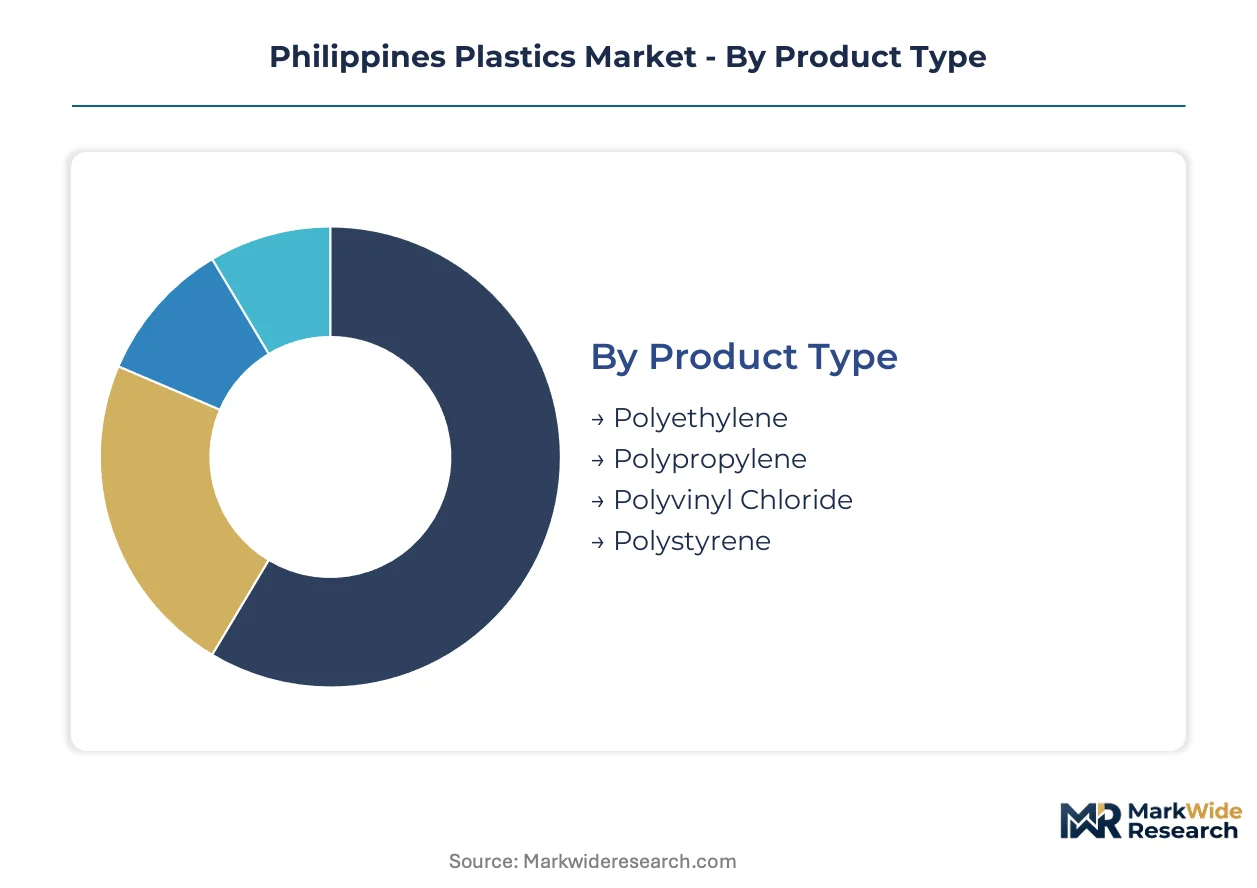
Philippine plastics procurement patterns diverge sharply between integrated petrochemical supply chains serving multinational food brands and fragmented distributor networks supplying provincial converters. Understanding these segment boundaries clarifies where EPR compliance costs concentrate and where chemical recycling pilots can achieve scale.
Product Type:
Polyethylene and polypropylene function as standalone commodity resins with established specification grades, while PVC and polystyrene embed more tightly into construction systems and appliance supply chains.
- Polyethylene:Linear low-density and high-density grades dominate flexible packaging specifications for Metro Manila food processors. Luzon-based agribusiness clusters drive film orders for seafood and fruit export operations.
- Polypropylene:Homopolymer and copolymer resins serve injection-molded rigid containers and automotive interior components. Thai and Japanese OEM localization programs in Calabarzon are qualifying Philippine-molded parts previously imported from Thailand.
- Polyvinyl Chloride:Construction-grade formulations supply government irrigation and housing programs through established piping system specifications.
- Polystyrene:Expandable and general-purpose grades anchor appliance housings and food service disposables with limited recycling pathway viability under current EPR scoring.
Volume placements concentrate in polyethylene; the faster expansion belongs to polypropylene.
Application:
Packaging applications absorb resin at commodity scale with thin margin profiles, while automotive and construction segments reward specification-grade compound capabilities with longer contract tenors.
- Packaging:Flexible films and multilayer sachet laminates serve the archipelago's fragmented retail economy. EPR recyclability mandates are forcing converters away from legacy barrier structures toward mono-material designs.
- Construction:PVC piping and polyethylene geomembranes align with public infrastructure spending cycles. Government irrigation programs sustain steady offtake regardless of consumer demand fluctuations.
- Automotive:Interior trim and under-hood components require melt-flow-calibrated polypropylene compounds with thermal stability certification.
- Consumer Goods:Housewares and appliance housings draw general-purpose resins through distributor channels with minimal technical service requirements.
Packaging commands the largest volume footprint; automotive applications are climbing the fastest as localization accelerates.
End User:
Manufacturers integrate resin procurement into production planning with direct refinery relationships, while retailers and wholesalers operate through distributor credit structures vulnerable to payment term compression.
- Manufacturers:Large-format packaging converters in Batangas and Cavite negotiate volume contracts with JG Summit Petrochemicals Group for captive polyethylene streams. These buyers harden terms on mid-tier distributors without refinery integration.
- Retailers:Puregold and SM Retail procurement teams demand 90-day credit windows and volume rebates that squeeze compounder margins. Direct import arrangements with Singapore traders are bypassing local distributor financing markups.
- Wholesalers:Provincial distributors serve Mindanao and Visayas converters with fragmented order patterns and higher logistics costs.
- Exporters:Food processing operations in Luzon agribusiness zones source food-contact-certified films for seafood and fruit shipments to East Asian markets.
Manufacturer offtake dominates current volume; exporter demand is gaining share fastest as agricultural processing expands.
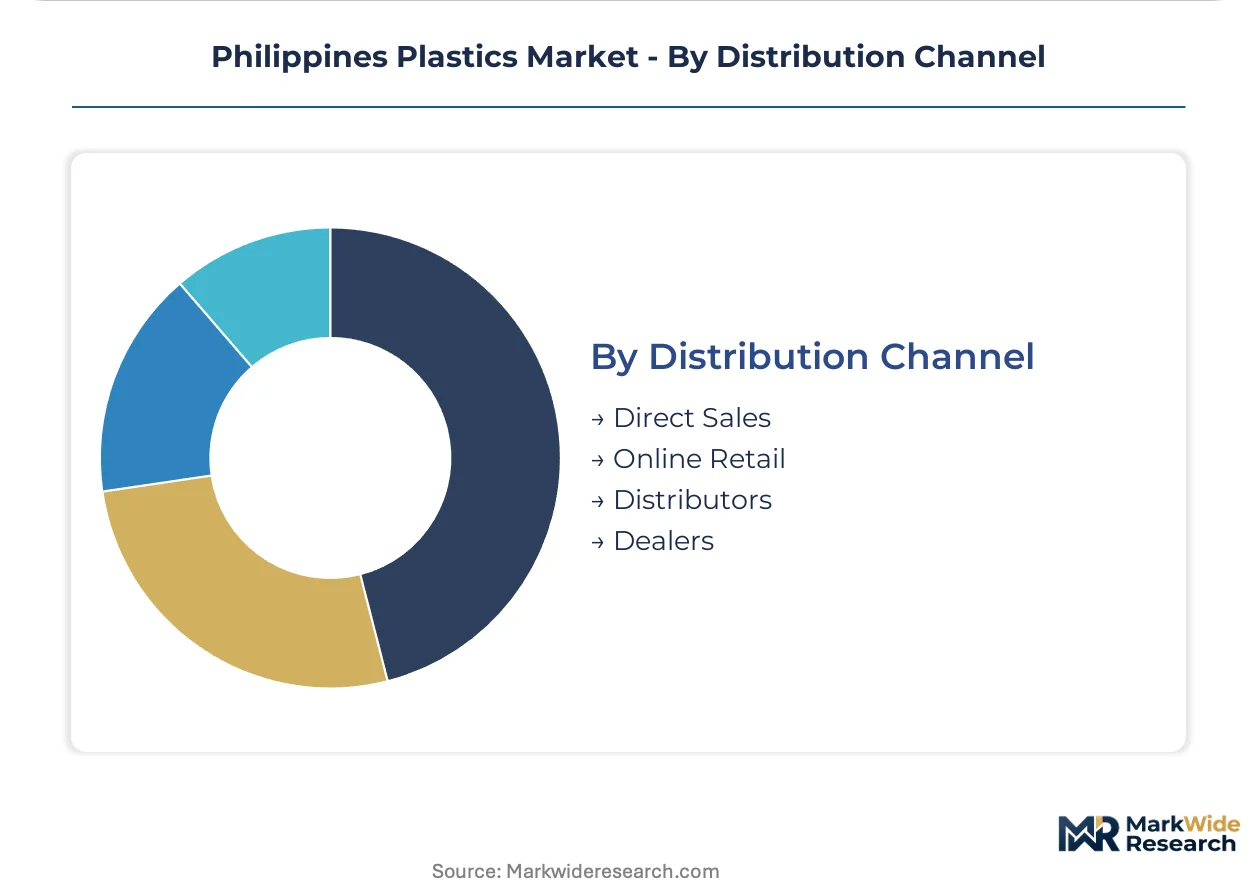
Distribution Channel:
Direct sales channels reward scale and banking relationships, while digital platforms are fragmenting traditional distributor hierarchies through spot-price transparency.
- Direct Sales:Refinery-integrated suppliers like JG Summit Petrochemicals Group serve affiliated downstream operations through captive supply arrangements. These relationships bypass distributor markups entirely.
- Distributors:Mid-tier compounders in Calabarzon maintain regional blending facilities with technical service capabilities. Payment term compression from large retail chains is eroding profitability.
- Online Retail:B2B marketplaces connecting Calabarzon converters directly to Singapore and Taiwan resin traders enable spot-volume arbitrage. Digital procurement is compressing traditional distributor margins.
- Dealers:Provincial agents serve small-format converters in Davao and Cebu with limited credit facilities and higher per-unit logistics costs.
Distributor networks handle the largest volume base; online retail channels are expanding most quickly as procurement digitization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Philippine resin demand concentrates in three industrial corridors where packaging converters cluster around food processing zones and government infrastructure programs sustain construction-grade offtake.
Metro Manila Industrial Corridor
Flexible packaging film orders from Luzon-based agribusiness clusters drive polyethylene consumption for seafood and fruit export operations. The Department of Environment and Natural Resources enforces Extended Producer Responsibility compliance timelines that redirect procurement toward post-consumer resin suppliers. Calabarzon compounders in Batangas and Cavite are qualifying food-contact-certified recycled streams to serve multinational FMCG distributors.
Central Visayas Manufacturing Belt
Cebu City's emerging automotive components sector is qualifying polypropylene interior parts for Thai and Japanese OEM localization programs. The Bureau of Product Standards mandates PNS ISO 9001 compliance for imported resin grades, extending customs clearance timelines for regional distributors. Mactan Economic Zone processors are negotiating direct import arrangements with Singapore traders to bypass local financing markups.
Davao Gulf Industrial Zone
Mindanao's fragmented converter base relies on provincial distributors with limited credit facilities and higher per-unit logistics costs. The central bank's sustainable finance framework channels credit toward recycling infrastructure, tightening market access for virgin-only suppliers in the southern corridor. Davao City lacks established resin distribution networks, creating positioning opportunities for compounders with regional blending capabilities.
Calabarzon Petrochemical Hub
Integrated refinery operations in Bataan supply captive polyethylene streams to affiliated downstream packaging operations. NPC Alliance Corporation positions its Calabarzon plants to capture EPR-driven procurement mandates with recycled-content formulations. Chemical recycling pilot programs using modular pyrolysis reactors are attracting Japanese trading house development capital for feedstock supply security.
Philippines Plastics Market Competitive Landscape
Bataan-integrated producers anchor one tier; Batangas specialty compounders hold specification-grade positions; Singapore-connected distributors capture spot-volume arbitrage. The market structures around refinery-captive supply, regional blending capabilities, and digital procurement platforms. Three archetypes dominate: integrated petrochemical groups, specialty compounders with technical service, and B2B marketplace intermediaries. Capacity expansion and backward integration into recycling streams represent the dominant competitive moves.
Within the integrated tier, JG Summit Petrochemicals Group occupies a position exemplifying refinery-captive supply advantages. D&L Industries and NPC Alliance Corporation represent contrasting archetypes—specialty compounding versus recycled-content positioning. These three anchors illustrate how Philippine plastic procurement splits between affiliated supply chains and independent compounders competing on EPR compliance capabilities.
| Leading Market Players |
|---|
| NPC Alliance Corporation |
| D&L Industries |
| JG Summit Petrochemicals Group |
| DuPont |
| Nan Ya Plastics |
| Chemrez Technologies |
| Philippine Resins Industries |
| LyondellBasell |
| Petron Corporation |
| Others |
Value Network & Pricing Analysis
Naphtha feedstock costs at JG Summit Petrochemicals Group's Bataan refinery cascade through three pricing tiers: captive supply arrangements for affiliated converters, contract-volume discounts for large-format packaging groups, and spot-market premiums for provincial distributors without banking relationships. Payment term compression from Puregold and SM Retail procurement teams forces mid-tier compounders toward direct Singapore import arrangements that bypass local financing markups.
Pricing Analysis
Volume-scale buyers capture margin through captive refinery relationships while smaller converters absorb spot-price volatility. Pricing stratifies across food-contact-certified premium grades, standard industrial polyethylene, and economy-tier recycled-content formulations with moisture contamination. Cost compression in the mid-tier distributor segment intensifies because 90-day credit windows from retail chains erode working capital buffers. Provincial converters in Mindanao exhibit highest price sensitivity; integrated petrochemical groups with captive supply show least.
Supply Chain Analysis
Polyethylene resin supply rests on naphtha cracking capacity concentrated in the Philippines, Singapore, and Taiwan. Feedstock streams draw from regional spot markets, Japanese trading house offtake agreements, and pyrolysis-based chemical recycling pilots. Single-source vulnerability concentrates around JG Summit Petrochemicals Group's Bataan refinery integration. Distribution runs through Calabarzon blending facilities, Singapore-connected B2B marketplaces, and provincial dealer networks serving Visayas and Mindanao.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Philippine plastics procurement has become a vertical-integration race where control over chemical recycling feedstock streams determines long-term contract viability. Players are pursuing backward integration into pyrolysis capacity to secure EPR-compliant resin supply.
For Market Incumbents: Acquire modular pyrolysis reactor assets in Calabarzon industrial zones to capture EPR-driven procurement mandates before enforcement timelines harden. Consolidate regional blending capabilities in Batangas to defend specification-grade compound positions against Singapore trader spot-volume arbitrage. Certification investment in Bureau of Product Standards PNS ISO 9001 compliance documentation accelerates customs clearance for post-consumer resin batches. For New Entrants and Emerging Players: The 40-50% price-point gap between premium food-contact-certified polyethylene and economy-tier contaminated recycled grades opens positioning room for mid-tier compounders with washing investment. White-space targets cluster in Davao City's emerging manufacturing belt lacking established resin distribution networks. Go-to-market leverage rests on digital procurement platform partnerships connecting Mindanao converters directly to Taiwan resin traders. For Investors and Strategic Acquirers: Distressed-cycle entries favor specialty compounders with technical service capabilities in Calabarzon over commodity distributors facing margin compression. Long-term viability across the five-to-ten year window hinges on recycled-content formulation expertise rather than virgin resin trading positions. Watch Bureau of Environment and Natural Resources enforcement timelines for recycled-content minimums as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pyrolysis Capacity | Captures EPR compliance premiums from multinational FMCG distributors in Metro Manila. |
| Regional Blending Facility Expansion | Positions compounders to serve Davao Gulf converters without established distribution networks. |
| Digital Procurement Platform Partnership | Enables spot-volume arbitrage that compresses traditional distributor financing markups. |
| Food-Contact Certification Investment | Accelerates Bureau of Product Standards PNS ISO 9001 customs clearance for recycled resin batches. |
| Automotive Interior Compound Qualification | Opens specification-grade polypropylene demand from Thai and Japanese OEM localization programs. |
Research Methodology
Independent corroboration across primary interviews with resin procurement managers, plant operations directors at Calabarzon converters, distribution channel partners, and Bureau of Product Standards compliance officers underwrites the qualitative findings. Secondary validation drew from Philippine customs trade data, Department of Environment and Natural Resources EPR implementation guidelines, central bank sustainable finance framework disclosures, and SEC filings from listed petrochemical groups. Bottom-up volume estimates from converter order patterns triangulate against top-down naphtha derivative consumption models.
Historical reference periods spanning pre-EPR regulatory baselines through current compliance-phase procurement shifts anchor the forecast window. Segmentation modeling incorporated resin grade tier, end-use application across packaging and automotive verticals, distribution channel structure, and regional industrial corridor concentration. CAGRs derive from weighted-average growth assumptions across these dimensions, with chemical recycling capacity buildout curves and automotive localization program timelines serving as key forecast inputs.
Inputs from converter procurement records and regulatory filing databases were available through the study window; gaps in real-time pyrolysis pilot operational data introduce uncertainty bands around recycled-content supply projections. Forecasts reflect documented assumptions regarding EPR enforcement intensity and naphtha price volatility. A small set of triggers—Bureau of Product Standards certification timeline shifts, central bank sustainable finance credit allocation changes, and Japanese trading house chemical recycling investment decisions—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plastic Packaging
Blow Molded Plastics Market
Plastic Packaging
Mexico Plastic Packaging Market
Plastic Packaging
Plastic Corrugated Sheets Market
Plastic Packaging
Plastic Films Market
Plastic Packaging
Cast Stretch Films Market
Plastic Packaging
Plastic Battery Containers Market
Plastic Packaging
Polyethylene Terephthalate (PET) Market
Plastic Packaging
Disposable Straw Market
Plastic Packaging
Conductive Plastic Boxes Market
Plastic Packaging
Europe BPA Free Plastic Market
Plastic Packaging
Transparent Plastic Packaging Market
Plastic Packaging
Australia and New Zealand Plastic Bottles Market
Plastic Packaging
Advanced-Recycled Polyethylene for E-Commerce Packaging Market
Plastic Packaging
South America Polyethylene Terephthalate (PET) Market
Plastic Packaging
Latin America Single-Use Plastic Packaging Market
Plastic Packaging
PET Jars Market